
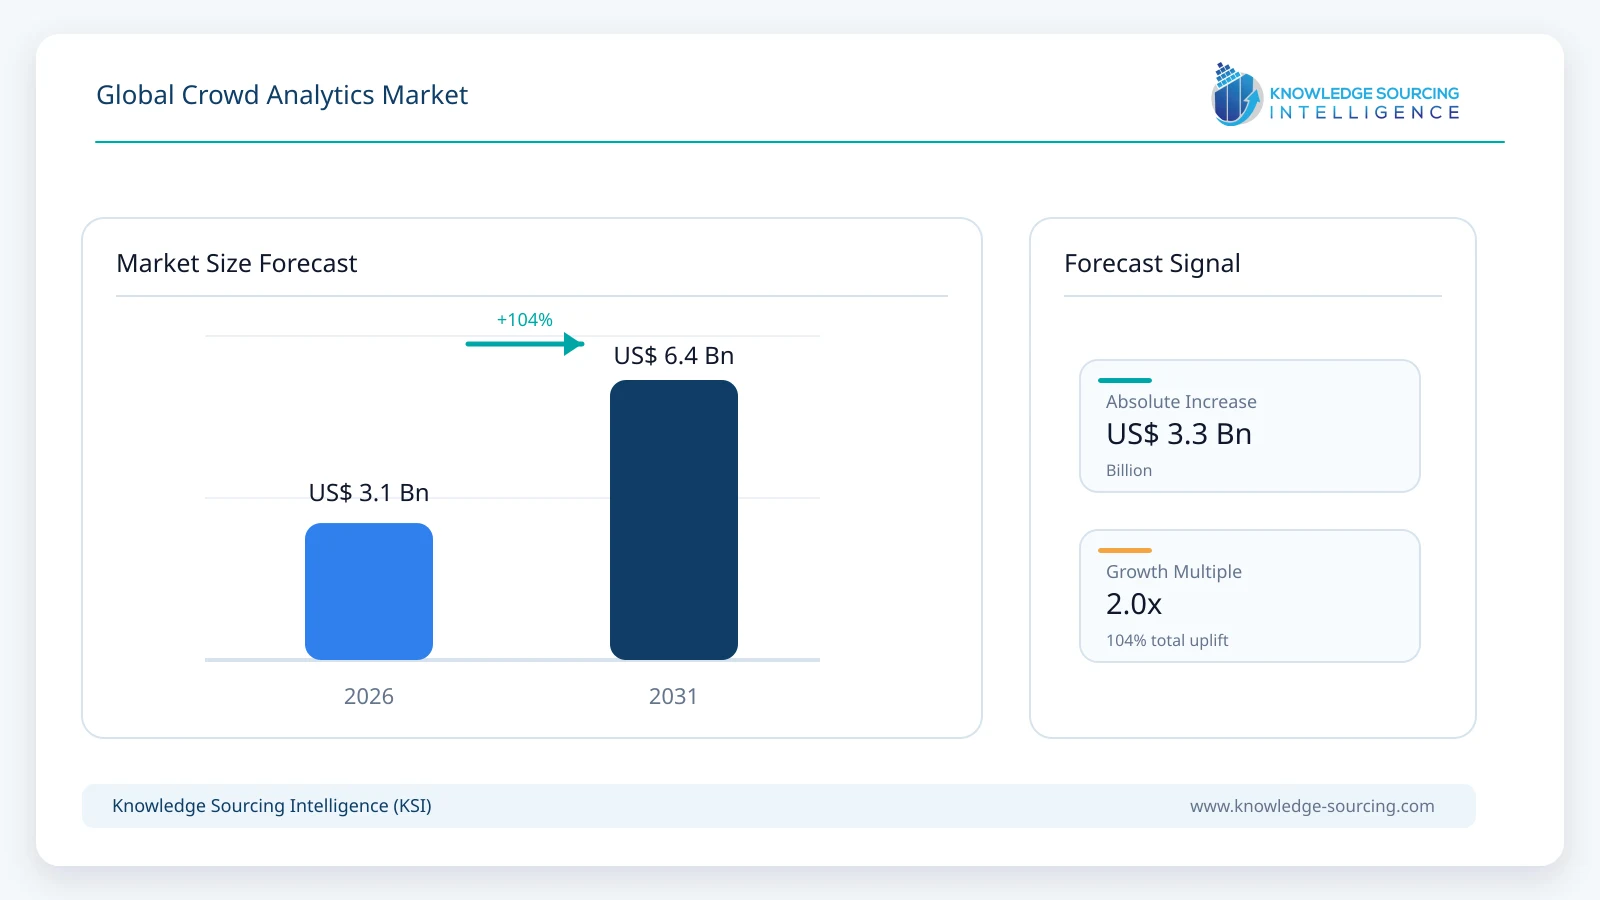
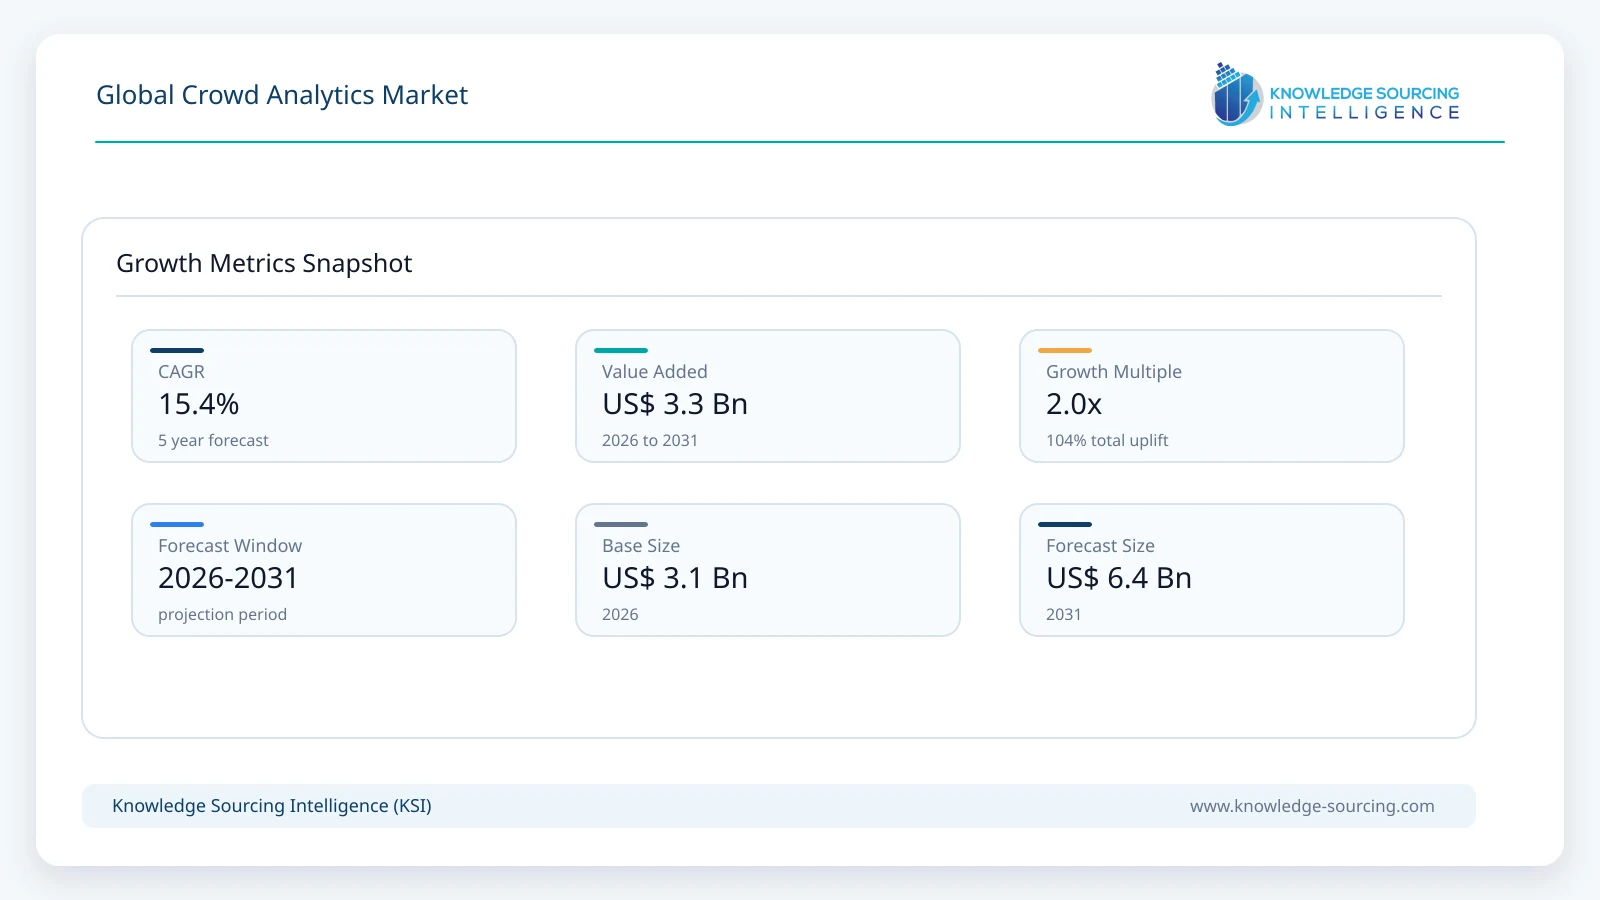
The Global Crowd Analytics Market is projected to grow at a CAGR of 15.4%, reaching USD 6.38 billion in 2031 from USD 3.12 billion in 2026.
Highlights:
- 1Software accounts for approximately 70% of market value in 2026, supported by analytics platforms, dashboards, alerts and integration tools.
- 2Services are projected to grow at approximately 16.7% annually through 2031, supported by system integration, calibration and implementation requirements.
- 3On-Premise deployment remains slightly larger in 2026, while Cloud deployment is projected to record approximately 19.5% CAGR.
- 4Computer Vision remains the largest technology category, while Artificial Intelligence and Machine Learning record the strongest forecast-period growth.
- 5Large Organizations account for approximately 72% of market value in 2026, although adoption among smaller organizations is expanding more rapidly.
- 6Transportation and Logistics remains the largest end-user segment, while Retail records one of the strongest growth rates as physical-store analytics becomes more operationally focused.
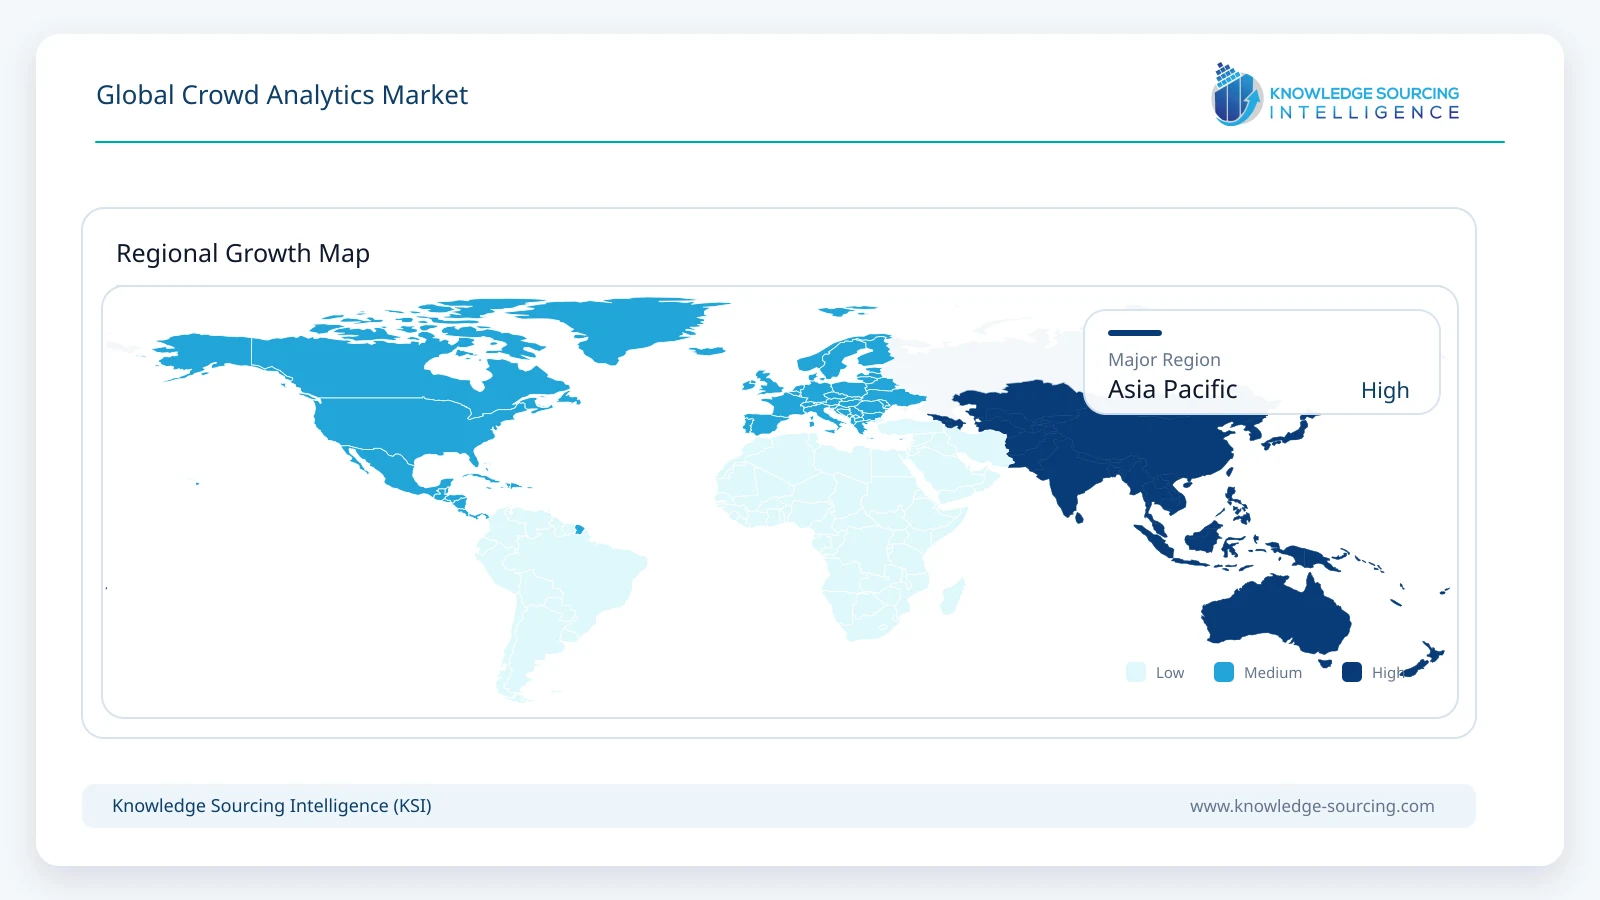
- 7North America remains the largest regional market in 2026, while Asia Pacific is projected to record the fastest growth.
Crowd analytics combines video, computer vision, artificial intelligence, LiDAR and other sensing technologies to measure people counts, occupancy, density, direction of movement, dwell time and unusual crowd behaviour across physical environments. The market is moving beyond conventional surveillance as airports, transportation authorities, retailers, event operators, municipalities and commercial facilities increasingly use pedestrian and occupancy data for capacity planning, queue management, staffing, safety and customer-experience improvement.
The demand environment is expanding alongside urbanisation and greater concentration of people in transport and commercial infrastructure. The United Nations estimates that cities housed around 45% of the world’s 8.2 billion people in 2025, while the number of megacities with populations above 10 million reached 33. Two-thirds of global population growth through 2050 is expected to occur in cities, increasing the scale and complexity of railway stations, airports, shopping districts, entertainment venues and public spaces where real-time understanding of pedestrian movement has operational value.
Passenger-intensive infrastructure represents one of the clearest commercial applications. Airports Council International reported approximately 9.8 billion airport passengers globally in 2025, with the world’s 20 busiest airports handling around 1.59 billion passengers. Airports and other transportation operators increasingly analyse queues, checkpoint congestion, terminal occupancy and movement between processing areas to allocate staff and infrastructure dynamically. Crowd analytics is therefore becoming connected to routine facility management rather than operating only as a security layer.
The technology is also moving closer to the sensing edge. Modern cameras can perform person detection, counting, occupancy analysis and queue measurement locally instead of continuously transmitting high-resolution video to central servers. This lowers bandwidth requirements, improves response times and can reduce the amount of identifiable footage that needs to leave the device. The combination of edge processing with centrally managed analytics platforms is widening the range of locations where crowd intelligence can be deployed economically.
Market Growth Drivers and Trends
Growing Urban Density Is Increasing the Need for Real-Time Crowd Intelligence
Urbanisation increases the operational complexity of transportation networks, commercial districts, entertainment facilities and public spaces. Large concentrations of people move simultaneously through constrained entrances, platforms, corridors and intersections, making static capacity assumptions less useful during peak periods or unexpected disruptions. Crowd analytics allows operators to assess occupancy and directional movement continuously and intervene before congestion becomes operationally disruptive or unsafe.
The United Nations’ World Urbanization Prospects 2025 estimates that cities contain around 45% of the global population and that the number of megacities has increased from eight in 1975 to 33 in 2025, with 19 located in Asia. This concentration supports demand for analytics across transport stations, civic infrastructure, major venues and retail environments. The commercial value comes not only from identifying overcrowding but from understanding recurring movement patterns that can influence facility design, staffing schedules, signage and longer-term capacity planning.
AI and Edge Computing Are Making Existing Video Infrastructure More Useful
A substantial surveillance-camera base already exists across transportation, retail, commercial buildings and public environments. Artificial intelligence allows this infrastructure to generate structured operational information rather than functioning primarily as a recording system. Modern video analytics can count visitors, estimate occupancy, identify queues, classify movement and detect developing congestion without requiring operators to review individual video feeds continuously.
Edge processing is particularly important because it allows much of the analytical work to occur on the camera or local device. Axis Object Analytics, for example, supports detection, classification, tracking and counting directly from compatible cameras, while Bosch, NEC and Hanwha Vision offer related analytical capabilities across commercial and public environments. Processing at the edge reduces the amount of continuous video that needs to be transferred and makes real-time analytics more practical across large sensor networks.
This architecture also supports more privacy-conscious deployments. A system can generate counts, movement metadata or threshold alerts locally while transferring only the analytical output required by the central platform. As processing capability continues to improve inside cameras and other sensors, the economics of deploying crowd analytics across existing surveillance networks become progressively more attractive.
Passenger Growth Is Increasing Demand Across Airports and Transportation Networks
Transportation facilities are natural environments for crowd analytics because passenger volumes fluctuate significantly by hour, route schedule, disruption and event timing. Airport terminals, railway stations, metro systems and bus terminals need to accommodate large flows through security points, ticketing areas, platforms and boarding zones without allowing congestion to reduce safety or service quality.
Global airport passenger traffic reached approximately 9.8 billion in 2025, according to Airports Council International, exceeding pre-pandemic levels. High-volume airports increasingly use passenger-flow information alongside operational systems to understand where queues are forming and how long passengers remain within individual processing areas. The same principles apply to railway and urban transit networks where changing crowd density can affect platform management, passenger routing and staff allocation.
The Transportation & Logistics segment therefore benefits from applications extending well beyond security. Crowd data can influence checkpoint staffing, cleaning schedules, signage, commercial-space planning and infrastructure investment, making it easier for operators to link analytical spending with measurable operational outcomes.
Retailers Are Turning Physical Footfall Into Operational Data
Retail crowd analytics is evolving from basic entrance counting toward a broader measurement of how people use physical stores. Retailers increasingly analyse visitor traffic, dwell time, queue length, occupancy and movement between zones to understand whether store layouts, staffing levels and merchandising decisions are supporting conversion.
Platforms from companies such as V-Count, Axis and RetailNext allow retailers to compare traffic with transactions, identify areas where customers spend more time and measure differences between locations using a common analytical framework. This is particularly useful to larger retail networks because sales data alone cannot distinguish between a store that attracts insufficient visitors and one that receives strong traffic but converts poorly.
Retail is consequently one of the faster-growing end-user applications, with growth estimated at approximately 17.7% annually through 2031. The expansion is being supported by cloud-managed analytics and edge-capable sensors that make it possible to apply a consistent measurement framework across multiple stores without building a separate analytics environment at every location.
LiDAR and Multisensor Analytics Expand Privacy-Conscious Applications
Camera-based analytics remains the largest technology foundation, but LiDAR and other sensors are increasingly used where depth accuracy, lighting independence or privacy considerations are important. LiDAR can map the movement of people and vehicles spatially without depending on conventional facial imagery, making it useful for transportation corridors, intersections, event environments and selected public spaces.
Ouster’s BlueCity platform combines 3D LiDAR with AI-based perception to analyse vehicle and pedestrian movement. During 2026, the company expanded deployments across intersections and transportation infrastructure in the United States, including installations around MetLife Stadium and a larger intersection programme in Utah. These deployments illustrate how crowd and pedestrian analytics are becoming part of broader traffic and mobility management rather than remaining confined to indoor camera systems.
The long-term market is therefore moving toward a mixed-sensor architecture in which cameras, LiDAR and other technologies are selected according to environment, required accuracy and privacy constraints. This makes the analytical software layer increasingly important because customers need to combine data from different sensing technologies into a common operational view.
Market Restraints
Privacy Regulation Limits Some Forms of Identification and Tracking
Crowd analytics becomes more sensitive when anonymous occupancy measurement progresses toward facial recognition, biometric identification or persistent tracking of individuals. Regulations increasingly distinguish between aggregated movement analysis and systems designed to identify specific people, particularly when technologies are deployed in publicly accessible locations.
The EU AI Act places significant restrictions on certain uses of real-time remote biometric identification and establishes additional obligations for high-risk biometric applications. These requirements do not prohibit ordinary visitor counting or anonymous occupancy analytics, but they make system architecture and data governance increasingly important to commercial deployment.
Vendors are therefore placing greater emphasis on edge processing, anonymisation and the collection of only the metadata required for a specific operational purpose. Systems capable of delivering useful crowd intelligence without unnecessary identification are better positioned for environments where privacy requirements are stringent.
Accuracy Declines in Complex Crowd Conditions
Analytical accuracy becomes more difficult to maintain as density rises and individuals overlap visually. Camera angle, lighting, shadows, weather conditions and obstructions can also affect conventional video analysis, requiring different algorithms and sensor placement for entrances, open plazas and densely occupied venues.
Modern computer-vision models have improved significantly, but large deployments still require site-specific calibration rather than simply applying identical settings across every camera. Hanwha Vision, for example, distinguishes general people counting from crowd counting in large open areas because the analytical problem changes materially when individuals cannot be clearly separated.
This requirement increases implementation effort but also supports demand for professional services. Vendors that can combine algorithms with sensor placement, calibration and ongoing validation are better positioned in complex public-space environments.
Integration With Legacy Infrastructure Can Increase Project Cost
Crowd analytics often needs to operate alongside existing CCTV, video management systems, access-control platforms, transportation control centres, point-of-sale systems, facility management software and digital signage. Large organizations frequently operate infrastructure from multiple vendors and technology generations, making integration a significant part of the project rather than a secondary technical task.
APIs and open architectures are reducing the barrier, but customers may still require custom integration, network upgrades and professional services before analytical data can influence operational workflows. This is one reason Services are projected to grow faster than the overall market even though Software remains the larger component.
The commercial value of crowd analytics improves when the system can trigger an operational response rather than merely display a dashboard. Integration capability therefore becomes a significant part of vendor differentiation.
High Initial Cost Can Delay Smaller Deployments
Major airports, transportation authorities and large retailers can distribute analytics investment across millions of passengers or thousands of daily visitors, making productivity and safety improvements easier to quantify. Smaller facilities have a more difficult investment case when dedicated sensors, subscriptions and system integration are required.
Edge AI and cloud-based platforms are gradually reducing this barrier by limiting the need for separate servers and allowing organizations to start with smaller deployments. Existing cameras can also sometimes support new analytics through software upgrades rather than complete infrastructure replacement.
This improves accessibility for smaller organizations, but adoption remains dependent on a clear operational benefit such as occupancy compliance, staffing efficiency, customer conversion or queue reduction.
Algorithmic Errors Can Create Operational Risk
Crowd analytics increasingly informs decisions involving staffing, passenger routing and public safety. False congestion alerts can waste staff resources, while missed events can reduce confidence in the system. The risk increases when analytics extends into behavioural interpretation or attempts to infer abnormal activity from movement patterns.
Customers therefore require clearly defined thresholds, ongoing model validation and human oversight for higher-risk decisions. Performance also needs to be measured in the environment where the system will operate rather than relying entirely on laboratory benchmarks.
These requirements slow adoption in some safety-critical applications but support established vendors with larger reference deployments and stronger implementation capability.
Crowd Analytics Market Segmentation Analysis
By Component
Software Remains the Largest Component
Software accounts for approximately 70% of market value in 2026, reflecting the increasing importance of analytical platforms rather than the sensing hardware itself. Modern crowd analytics software aggregates input from cameras and other sensors, generates occupancy and movement metrics, creates alerts and allows organizations to compare behaviour across locations and time periods.
The role of software is expanding as processing becomes distributed. Detection may occur on an edge camera, while a central or cloud platform combines metadata from multiple devices and turns it into dashboards, historical trends and operational alerts. The value therefore shifts from simply identifying a person in a video stream toward organising large volumes of movement information into a format that operators can use.
Software remains the principal revenue pool through the forecast period, while the increasing complexity of deployment creates faster growth in associated Services. Services are projected to expand at approximately 16.7% annually through 2031 as customers require greater support for integration, calibration, privacy configuration and maintenance across multisite environments.
By Deployment
On-Premise Remains the Larger Deployment Model, While Cloud Expands Faster
On-Premise deployment represents approximately 52% of the market in 2026, supported by airports, public-safety environments, transportation facilities and other organizations that require direct control over video infrastructure and data. Large surveillance deployments can already have substantial local processing and storage capacity, making the addition of crowd analytics to existing architecture commercially practical.
Cloud deployment is projected to grow at approximately 19.5% annually through 2031, supported particularly by retailers and other organizations managing geographically distributed locations. Cloud platforms simplify centralized dashboards, historical analysis, software updates and comparisons across sites, while reducing the need to build a complete analytical stack at each location.
The distinction between the two models is also becoming less rigid. Many deployments process video or detections locally and transmit only metadata to centrally managed cloud platforms. This hybrid architecture combines low-latency edge processing with easier multisite management and allows cloud participation to increase without requiring customers to transmit all raw video continuously.
By Technology
Computer Vision Provides the Largest Installed Technology Base
Computer Vision accounts for approximately 46% of market value in 2026, supported by the large installed base of surveillance and network cameras across commercial and public environments. Video remains the most accessible source of information about people movement because the same infrastructure can support security, operational monitoring and analytical applications.
Current computer-vision platforms can count visitors, estimate occupancy, identify queue formation and track directional movement without necessarily identifying individual people. This allows organizations to obtain operational intelligence from camera networks that were originally installed primarily for surveillance.
Artificial Intelligence & Machine Learning represents the fastest-growing technology category, with an estimated CAGR of approximately 19.4% through 2031. The distinction between AI and conventional computer vision is narrowing as newer platforms use machine-learning models to improve classification, recognise unusual movement patterns and generate predictive alerts. Over the forecast period, AI increasingly becomes an embedded analytical layer within camera and sensor platforms rather than a completely separate technology category.
By Organization Size
Large Organizations Dominate Spending, While Smaller Organizations Gain Access
Large Organizations account for approximately 72% of market value in 2026 because transportation operators, municipal agencies, large venues and major retail groups can deploy crowd analytics across extensive sensor networks and integrate the information with broader operational systems. They also face larger financial and safety consequences from poor crowd management, making investment easier to justify.
Smaller organizations historically faced higher barriers because crowd analytics required dedicated servers, specialized cameras and technical expertise. Cloud-based dashboards and edge processing are reducing these requirements by allowing organizations to deploy analytics with less local infrastructure.
Small & Medium Organizations are therefore projected to grow at approximately 19.3% annually through 2031. The opportunity is expanding across individual stores, gyms, libraries, offices and smaller venues where occupancy, visitor flow or queue measurement can produce a specific operational benefit without requiring enterprise-scale infrastructure.
By End-User
Transportation & Logistics Remains the Largest End-User
Transportation & Logistics represents approximately USD 904.8 million in 2026, making it the largest end-user segment. Airports, railways, metro stations and other transportation environments combine high pedestrian volumes with constrained infrastructure, making crowd movement directly relevant to service quality and safety.
Global airport traffic reached approximately 9.8 billion passengers in 2025, creating large-scale demand for queue management, terminal occupancy measurement and passenger-flow analysis. Similar requirements exist across railway and metro systems where platform congestion and passenger movement can change rapidly during service disruptions or peak periods.
Transportation operators increasingly use this information alongside staffing and facility systems rather than treating crowd monitoring as a standalone security application. This broad operational use supports the segment’s leading position through the forecast period.
Retail Records the Strongest Growth
Retail is projected to grow at approximately 17.7% annually through 2031, supported by increasing demand for measurable insight into how customers use physical stores. Retailers are moving beyond entrance counts and using analytics to understand movement between zones, dwell time, queue formation and how visitor traffic relates to staffing and sales performance.
This creates a more direct connection between crowd analytics and store economics. A retailer can distinguish between weak visitor acquisition and weak in-store conversion, evaluate whether labour schedules match traffic peaks and compare the effect of layout changes across multiple locations. V-Count, Axis, RetailNext and other providers increasingly position their platforms around these operational questions rather than simple footfall reporting.
Cloud-managed platforms strengthen the opportunity because retailers can apply common metrics across geographically distributed stores while keeping detection close to the edge. This allows physical-store analytics to become part of regular performance management without requiring a separate analytical infrastructure at every location.
Geographical Outlook
North America Remains the Largest Market
North America accounts for approximately 34% of global market value in 2026, supported by extensive camera infrastructure, established retail analytics, large transportation networks and investment in smart infrastructure. The United States provides the majority of regional demand across airports, retail, public safety, venues and transportation management.
Recent deployments illustrate the movement toward broader mobility intelligence. During 2026, Ouster’s BlueCity platform was deployed around MetLife Stadium and expanded across intersections in Utah, combining LiDAR-based detection with traffic and pedestrian analytics. These systems demonstrate how crowd analytics can become part of larger transportation-management architectures rather than remaining an isolated video application.
North America continues to grow strongly, but its share gradually moderates as deployment accelerates in Asian markets with larger pipelines of new urban infrastructure.
Asia Pacific Records the Fastest Regional Growth
Asia Pacific is projected to grow at approximately 17.8% annually through 2031, supported by rapid urban development, large public-transport systems and continued investment in smart-city infrastructure. The region contains 19 of the world’s 33 megacities, creating a particularly large base of airports, rail networks, commercial complexes and public spaces where crowd-management challenges are significant.
China, Japan and South Korea combine sophisticated surveillance and sensing infrastructure with established domestic technology suppliers, while India and Southeast Asia add a growing pipeline of transportation and urban-development projects. Companies including NEC, Hikvision, Dahua and Hanwha Vision also give the region a substantial technology supply base.
The regional growth opportunity therefore combines new infrastructure with upgrades to existing systems. As edge AI lowers processing and connectivity requirements, crowd analytics can be added to a wider range of commercial and public facilities without requiring entirely new centralized surveillance architecture.
Recent Developments
August 2026, Ouster and Econolite announced expansion of the BlueCity traffic-management system across an additional 160 intersections in Utah, combining LiDAR, AI-based detection and analytical data covering vehicles, cyclists and pedestrians.
June 2026, Ouster completed deployment of BlueCity at more than 40 highway locations around MetLife Stadium for the 2026 FIFA World Cup, supporting congestion monitoring and transportation management around high visitor volumes.
June 2026, Ouster introduced an upgraded BlueCity platform using Rev8 native-colour LiDAR with longer detection range and privacy-oriented edge functionality, with Stamford, Connecticut becoming the first deployment of the updated configuration.
April 2026, Hanwha Vision detailed an edge-AI crowd-counting architecture designed for large open environments including plazas, stadiums, shopping centres, airports and transport terminals.
April 2026, Axis Communications introduced additional AI-powered dome cameras with AXIS Object Analytics preinstalled, allowing person detection, tracking and counting directly at the edge.
Competitive Environment
The Crowd Analytics Market combines major video-surveillance companies, specialist people-counting providers, LiDAR suppliers and analytics-software vendors. Axis Communications, Bosch, NEC, Hikvision, Dahua and Hanwha Vision participate through camera-based AI and video analytics, while Motorola Solutions’ Avigilon and Canon’s BriefCam provide broader video-intelligence platforms.
Specialist suppliers compete through more focused operational analytics. V-Count, Xovis, FootfallCam, RetailNext and Density provide people counting, passenger movement, occupancy and retail-traffic analysis, while Beonic combines physical-space analytics with broader customer and movement intelligence. Irisity, Ipsotek and viisights focus more strongly on AI-based video interpretation and behavioural detection.
Ouster represents an alternative sensor architecture through LiDAR-based spatial analytics. Its recent transportation deployments illustrate how pedestrian and crowd information can be integrated with traffic-management systems without relying entirely on conventional camera imagery.
Competition through 2031 is likely to depend on analytical accuracy, edge-processing capability, privacy architecture, integration and the ability to convert raw sensor data into information that changes an operational decision. Customers increasingly value platforms that can work with existing infrastructure and deliver consistent analytics across multiple locations rather than isolated detection algorithms.
Analyst View
The Global Crowd Analytics Market is projected to grow as crowd intelligence becomes part of routine physical-space management. The market is moving away from a narrow surveillance proposition toward operational applications involving queues, staffing, congestion, store conversion and facility utilisation.
Video remains the largest sensing foundation because cameras are already widely installed, while AI increases the amount of useful information that can be extracted from those networks. Edge processing improves the economics further by allowing data to be analysed locally and reducing the need to move continuous high-resolution video across networks.
Transportation provides the largest current opportunity because passenger movement has direct operational and safety consequences, while Retail expands faster as physical stores seek more measurable understanding of customer behaviour. The same pattern is visible geographically, with North America maintaining the largest installed market while Asia Pacific benefits from a larger pipeline of urban and transportation infrastructure.
Privacy increasingly influences system architecture rather than eliminating demand. Solutions centred on aggregate counting, occupancy and anonymous movement analysis can provide significant operational value without identifying individuals, creating a stronger path to adoption as regulators and customers place greater emphasis on responsible use of physical-space data.
Crowd Analytics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.12 billion |
| Total Market Size in 2031 | USD 6.38 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Deployment, Technology, Organization Size, End-User, Geography |
| Companies |
|
Market Segmentation
By Component
Software
Services
By Deployment
Cloud
On-Premise
By Technology
Artificial Intelligence & Machine Learning
Computer Vision
Others
By Organization Size
Small & Medium Organizations
Large Organizations
By End-User
Travel & Tourism
Media & Entertainment
Retail
Transportation & Logistics
Healthcare
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Thailand
Taiwan
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL CROWD ANALYTICS MARKET BY COMPONENT
5.1. Introduction
5.2. Software
5.3. Services
6. GLOBAL CROWD ANALYTICS MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Cloud
6.3. On-Premise
7. GLOBAL CROWD ANALYTICS MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Artificial Intelligence & Machine Learning
7.3. Computer Vision
7.4. Others
8. GLOBAL CROWD ANALYTICS MARKET BY ORGANIZATION SIZE
8.1. Introduction
8.2. Small & Medium Organizations
8.3. Large Organizations
9. GLOBAL CROWD ANALYTICS MARKET BY END-USER
9.1. Introduction
9.2. Travel & Tourism
9.3. Media & Entertainment
9.4. Retail
9.5. Transportation & Logistics
9.6. Healthcare
9.7. Others
10. GLOBAL CROWD ANALYTICS MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. United Kingdom
10.4.2. Germany
10.4.3. France
10.4.4. Italy
10.4.5. Spain
10.4.6. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. Israel
10.5.4. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. Japan
10.6.3. India
10.6.4. South Korea
10.6.5. Thailand
10.6.6. Taiwan
10.6.7. Indonesia
10.6.8. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. NEC Corporation
12.2. Axis Communications AB
12.3. Bosch Security and Safety Systems
12.4. Motorola Solutions, Inc.
12.5. Canon Inc.
12.6. Hangzhou Hikvision Digital Technology Co., Ltd.
12.7. Zhejiang Dahua Technology Co., Ltd.
12.8. Hanwha Vision Co., Ltd.
12.9. Ouster, Inc.
12.10. V-Count
12.11. Xovis AG
12.12. FootfallCam
12.13. RetailNext, Inc.
12.14. Beonic
12.15. Density Inc.
12.16. Irisity AB
12.17. Ipsotek Ltd.
12.18. viisights
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











