
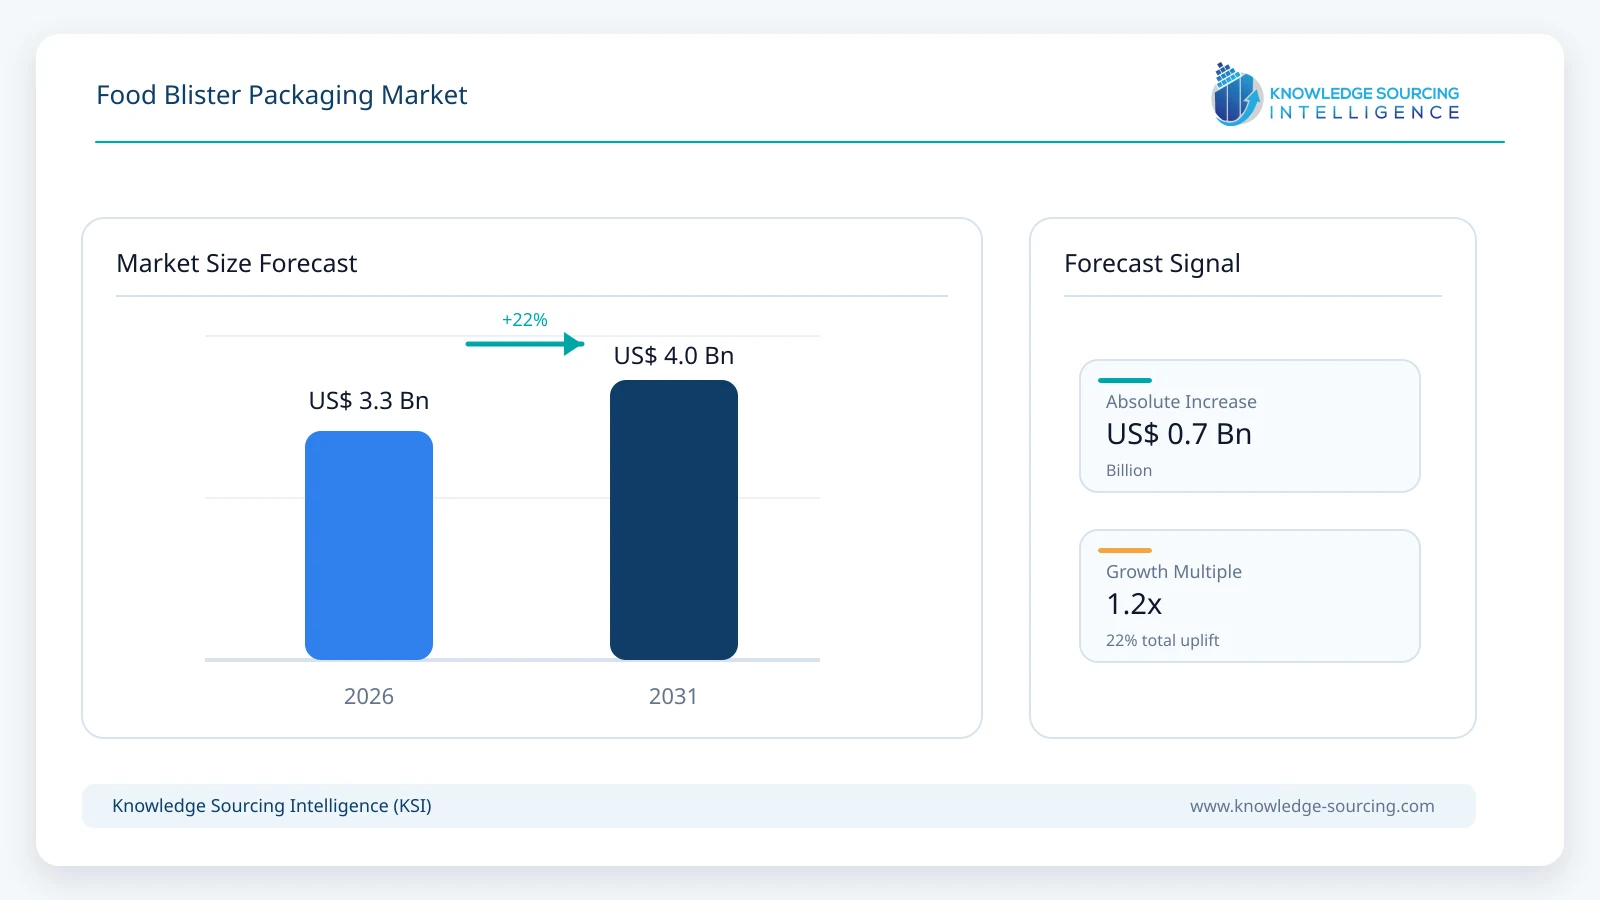
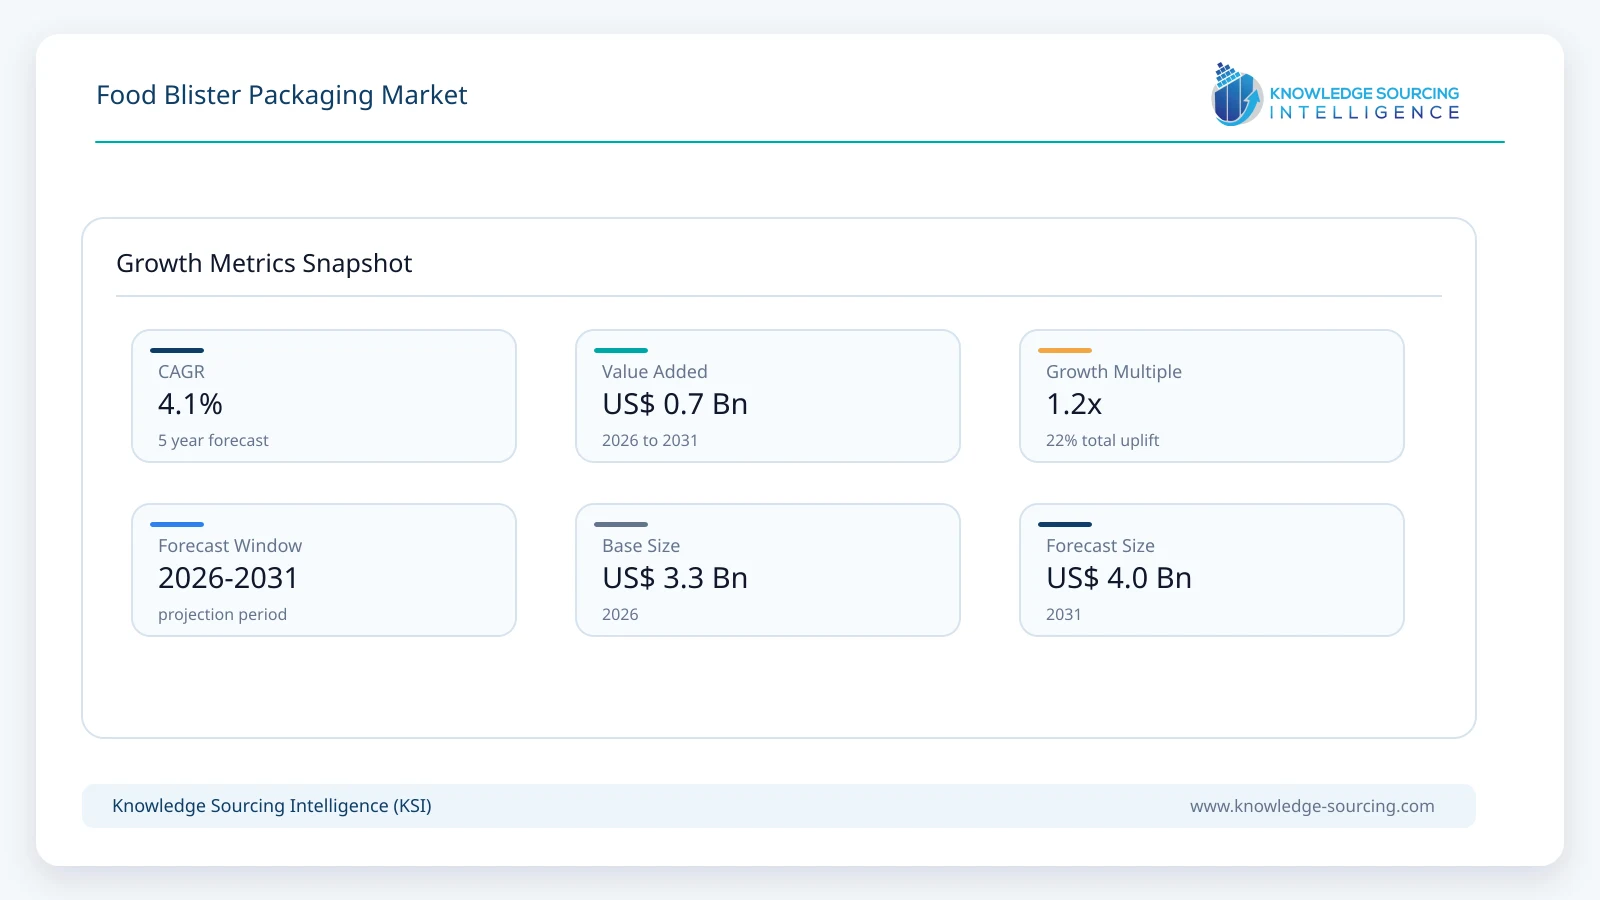
The global food blister packaging market is forecast to grow at a CAGR of 4.1%, reaching USD 4.01 billion in 2031 from USD 3.28 billion in 2026.
Highlights:
- 1Improving food protectionBarrier films and sealed blister cavities are helping protect food products against moisture, oxygen exposure, contamination, and physical damage.
- 2Expanding across Asia-PacificUrbanization, organized retail, packaged-food consumption, and digital commerce are creating opportunities for convenient, portion-controlled packaging formats.
- 3Advancing barrier technologiesImprovements in thermoforming, sealing, and multilayer film design are supporting product freshness and more consistent packaging performance.
- 4Increasing portion controlIndividual compartments are supporting single-serving snacks, confectionery, dried fruit, nuts, and selected ready-to-eat food applications.
- 5Automating packaging operationsModern forming, filling, sealing, inspection, and traceability systems are helping food manufacturers improve production consistency and packaging hygiene.
- 6Prioritizing sustainable materialsRecyclable mono-material structures, lightweight designs, and reduced-material packaging are gaining importance as brands respond to environmental regulations and customer expectations.
Food blister packaging is a specialized packaging format that uses a formed cavity to hold and protect an individual food product or a group of products. The cavity is generally produced from a plastic sheet or another formable material and sealed using a compatible film, foil, paperboard, or cardboard backing. Depending on the intended application, the package can be designed to provide product visibility, portion separation, tamper evidence, moisture resistance, and protection during storage and transportation.
The global food blister packaging market is supported by the expanding consumption of packaged snacks, confectionery, bakery products, processed foods, and selected fresh-food applications. Manufacturers use blister formats when individual product presentation, organized compartments, controlled access, and protection from external conditions are important. The packaging is also relevant to products sold through supermarkets, convenience stores, vending machines, foodservice channels, and online retail platforms.
Material selection is a central consideration in food blister packaging. Polyvinyl chloride (PVC), polypropylene (PP), and other formable polymers can be selected according to the required rigidity, clarity, forming performance, sealing compatibility, and barrier properties. Polyvinylidene chloride (PVDC) can be used as a barrier layer or coating in selected structures, while paperboard and other materials can provide support, printing surfaces, and additional structural strength. The suitability of each material depends on the food's composition, storage conditions, intended shelf life, and applicable food-contact requirements.
Demand is also being influenced by the need to balance food protection with packaging waste reduction. The Food and Agriculture Organization of the United Nations (FAO) reports that approximately 13.2% of food is lost in the supply chain between post-harvest stages and retail, while a further 19% is wasted at retail, foodservice, and household levels, according to the 2024 UNEP statistics cited by FAO. These figures cover food loss and waste across the wider food system rather than losses attributable specifically to packaging. Nevertheless, they underline the importance of packaging solutions that can preserve product quality, support appropriate portion sizes, and reduce avoidable damage.
Packaging manufacturers are therefore focusing on material efficiency, forming precision, improved sealing, and compatibility with recycling systems. However, a higher barrier specification does not automatically make a package more sustainable. Food blister packaging must be evaluated according to its ability to protect the product, its material composition, manufacturing requirements, available collection and sorting infrastructure, and end-of-life performance.
Food Blister Packaging Market Overview:
The global food blister packaging market is segmented by type, material, technology, and region. These categories reflect the different packaging configurations, polymer characteristics, production processes, and regional demand conditions influencing market development.
Type: By type, the global food blister packaging market is categorized into compartments, slides, and wallets. Compartment blister packaging is expected to remain an important category because separate cavities can organize individual products, limit direct contact between items, and support portion control. Slide and wallet formats can provide convenient opening, compact presentation, and additional space for branding or product information.
Material: By material, the market is divided into PVC, PVDC, PP, and others. PVC remains relevant because of its formability, clarity, rigidity, and established processing characteristics. PP is also important in applications requiring particular heat resistance, chemical compatibility, or material-specific recycling considerations. PVDC is generally used as a barrier component rather than as a direct substitute for every structural polymer. The appropriate choice depends on food-contact compliance, barrier requirements, cost, and recyclability.
Technology: By technology, the global food blister packaging market is categorized into cold-form and thermoformed packaging. Thermoforming heats a suitable sheet and shapes it into cavities using a mold. Cold-forming relies on mechanical forming without the conventional heat-softening process used in thermoforming. For food applications, thermoforming is relevant to clear, rigid, and presentation-oriented packs, while cold-forming can be considered where a specific barrier construction is required. The commercial suitability of either technology depends on the food product and the complete package structure.
Region: The market covers North America, Europe, Asia-Pacific, South America, and the Middle East and Africa. North America benefits from established packaged-food manufacturing, organized retail, and demand for convenient formats. Asia-Pacific presents opportunities associated with urbanization, expanding food-processing capacity, and retail modernization. Europe is particularly important for developments in recyclable packaging design and regulatory compliance.
Market participants compete on packaging quality, forming accuracy, sealing performance, production efficiency, customization, material innovation, and customer support. In addition to the cost of the packaging material, food producers evaluate machine compatibility, production speed, packaging-line downtime, transport efficiency, and the ability to maintain consistent quality across manufacturing batches.
Top Trends Shaping the Global Food Blister Packaging Market:
Technological advancement
Technological advancement is influencing the food blister packaging market through improvements in forming equipment, sealing systems, inspection technology, and production-line automation. Modern thermoforming equipment can be configured to handle different cavity shapes, film specifications, and package dimensions. Better process control helps manufacturers maintain forming depth, wall thickness, seal integrity, and dimensional consistency, particularly when producing large quantities of uniform packages.
Automated inspection can help identify incomplete seals, damaged cavities, foreign particles, and other visible defects before products leave the packaging line. When combined with appropriate quality-management procedures, these systems can reduce the risk of defective packs reaching distributors and consumers. Digital production monitoring can also help operators identify process deviations, monitor material consumption, and reduce unnecessary downtime.
A relevant 2026 industry development is MULTIVAC's announcement of its RX Ultimate thermoforming packaging machine on April 7, 2026. According to the company's official announcement, the system incorporates multi-sensor process control, online connectivity, and a matrix heating system designed to improve process reliability and enable consistent processing of recyclable films while minimizing film thickness. Although the equipment is intended for thermoforming applications generally rather than exclusively for food blister packs, the development illustrates how machine design can support more material-efficient packaging production.
Growth in sustainable packaging design
Sustainability is becoming an important consideration in the selection of food blister materials. Traditional multilayer structures can offer useful combinations of strength, sealability, and barrier protection, but their mixed compositions may complicate sorting and recycling. Manufacturers are consequently assessing mono-material designs, reduced-gauge films, improved material utilization, and alternative backing materials.
However, a package described as recyclable by its manufacturer may not be recycled in every market. Actual outcomes depend on the composition of the finished package, the availability of collection and sorting systems, the acceptance criteria of recyclers, and contamination from food residues. Manufacturers should therefore distinguish between a package designed for recyclability and one that is demonstrably recycled at scale.
Regulation is reinforcing this direction. The European Union's Packaging and Packaging Waste Regulation (EU) 2025/40 began applying on August 12, 2026. The European Commission states that the regulation establishes a common framework covering packaging and packaging waste and introduces restrictions on PFAS in food-contact packaging above specified limits. Broader recyclability and recycled-content requirements are subject to phased implementation, including measures scheduled for 2030. These requirements are relevant to companies supplying food packaging to European markets, although the specific obligations depend on the product, material, and applicable provision.
Increasing demand for portion-controlled formats
Portion-controlled blister formats are relevant to confectionery, chewing gum, breath mints, nuts, dried fruit, snack pieces, and selected specialty food products. Individual cavities can prevent products from shifting freely inside a package and make quantities easier to identify. Depending on the design, separate compartments can also help limit direct contact between different food items.
These advantages can be particularly useful for premium confectionery and products sold in vending machines, convenience stores, and travel retail. Food manufacturers can customize the number, shape, and depth of cavities to suit product dimensions and presentation requirements. Nevertheless, portion control does not necessarily reduce total packaging consumption: a blister pack with many individual cavities may use more material than a simple pouch. Packaging design must therefore balance convenience, product protection, and material efficiency.
Improved product visibility and retail presentation
Transparent blister cavities allow consumers to inspect the appearance, size, and arrangement of food products before purchase. This can support product differentiation in retail environments where packaging visibility influences consumer choice. Printed backing cards, branded sleeves, and clear product information can further improve shelf presentation.
For premium products, customized cavity designs can reinforce the visual identity of the brand. However, clear packaging must also be evaluated for light sensitivity, temperature exposure, and the potential effect of oxygen and moisture on food quality. Products that deteriorate under light or require a stronger barrier may need opaque materials, protective secondary packaging, or a different packaging format.
Expansion of food e-commerce and distribution networks
Online food retail creates additional requirements for packaging that can withstand handling, sorting, transportation, and last-mile delivery. Blister packaging can help secure individual items and maintain their arrangement during movement, particularly for compact products that are vulnerable to crushing or abrasion.
However, food blister packaging is not suitable for every e-commerce application. Fresh meat, chilled seafood, bulk groceries, and products requiring substantial liquid containment may be better served by trays, vacuum packaging, flexible pouches, or other specialized formats. Blister packs are most competitive where their rigidity, product visibility, and individual-cavity design deliver a clear functional advantage.
Food Blister Packaging Market Growth Drivers vs. Challenges
Opportunities:
Cost-efficient and application-specific packaging: PVC and other established thermoplastics offer a combination of formability, clarity, and manufacturing familiarity. These characteristics can make them commercially attractive for selected food applications. Nevertheless, the lowest-cost raw material does not always deliver the lowest total packaging cost. Food producers must also account for forming performance, sealing compatibility, material waste, product damage, and regulatory compliance. The market opportunity lies in selecting the most appropriate material for each product rather than assuming that one polymer is universally superior.
Increasing hygiene and product-integrity requirements: Sealed blister cavities can reduce direct handling of individual products and provide a visible indication of whether the package has been opened or damaged. This can be valuable for single-serving foods, confectionery, and products distributed through multiple retail channels. However, blister packaging cannot independently guarantee food safety. Hygienic manufacturing, suitable food-contact materials, validated sealing processes, and appropriate storage conditions remain essential.
Demand for improved shelf-life performance: Food manufacturers are seeking packaging structures that help limit moisture transfer, oxygen exposure, and other deterioration mechanisms. A correctly engineered barrier system can help preserve selected product characteristics during storage and distribution. The required protection varies substantially between dry snacks, fatty foods, fresh produce, and moisture-sensitive confectionery. Consequently, material development and application testing provide opportunities for packaging suppliers.
Development of recyclable and lightweight structures: Packaging manufacturers can pursue opportunities by reducing unnecessary material use and developing structures compatible with established recycling streams. The commercial challenge is to achieve these improvements without compromising the food's required barrier, mechanical strength, and sealing performance. Solutions that combine lower material consumption with reliable product protection may offer a stronger value proposition to food processors and brand owners.
Challenges:
Strict regulatory compliance: Food-contact packaging must meet the applicable requirements of the markets in which it is sold. In the United States, the Food and Drug Administration (FDA) explains that food-contact substances can include packaging materials, adhesives, colorants, and other components that contact food. Food additives used in food-contact applications must be authorized for their intended use before marketing. Manufacturers must assess migration, intended food types, temperature conditions, and other relevant requirements instead of relying on a general claim that a polymer is food-safe.
Recycling limitations and environmental scrutiny: Multilayer laminates, incompatible backing materials, labels, adhesives, and food contamination can complicate end-of-life processing. A material may technically be recyclable but lack a suitable collection and recycling pathway in the target market. Companies must therefore evaluate the entire package and avoid overstating environmental benefits without supporting evidence.
Raw-material price volatility: Packaging manufacturers remain exposed to changes in polymer, energy, transportation, and conversion costs. A change in resin prices can affect the economics of different material options, while specialized barrier structures may involve additional processing or qualification expenses. These fluctuations can place pressure on suppliers operating under long-term customer contracts.
Technical limitations and product suitability: Blister packaging cannot replace every food packaging format. Some foods require high oxygen barriers, modified-atmosphere packaging, vacuum sealing, leak resistance, refrigeration, or other controls that conventional blister formats may not provide independently. Package design must be validated for the actual food, shelf-life target, and distribution environment.
Capital investment and production integration: Modern thermoforming lines, automated inspection, and advanced sealing systems require investment and skilled operating personnel. Smaller manufacturers may face difficulties upgrading equipment, qualifying alternative materials, and maintaining consistent output while changing package designs. The transition may also require new molds, revised production parameters, and additional quality testing.
Food Blister Packaging Market Regional Analysis:
North America: North America represents an important market for food blister packaging because of its established packaged-food industry, extensive organized retail network, and demand for convenient consumer products. Blister formats can support confectionery, specialty snacks, portion-controlled products, and applications requiring individual product visibility. Packaging suppliers also benefit from the presence of established food processors and manufacturers investing in automated production. Regulatory compliance, packaging waste reduction, and the need to demonstrate product safety remain important considerations for market participants. The region's commercial opportunities will depend on the relative cost and performance of blister packs compared with flexible pouches, trays, and other alternatives.
Europe: Europe is an important market for packaging innovation, resource efficiency, and regulatory compliance. The application of Regulation (EU) 2025/40 from August 12, 2026, has increased the importance of reviewing material composition, food-contact substances, packaging design, and waste-management requirements for businesses selling into the region. The regulation's PFAS restrictions in food-contact packaging are particularly relevant to material selection. Manufacturers supplying blister packs must also consider how their finished structures will be collected, sorted, and recycled in the markets where they are placed. The opportunity is strongest for suppliers able to demonstrate appropriate product protection while meeting applicable environmental and food-contact requirements.
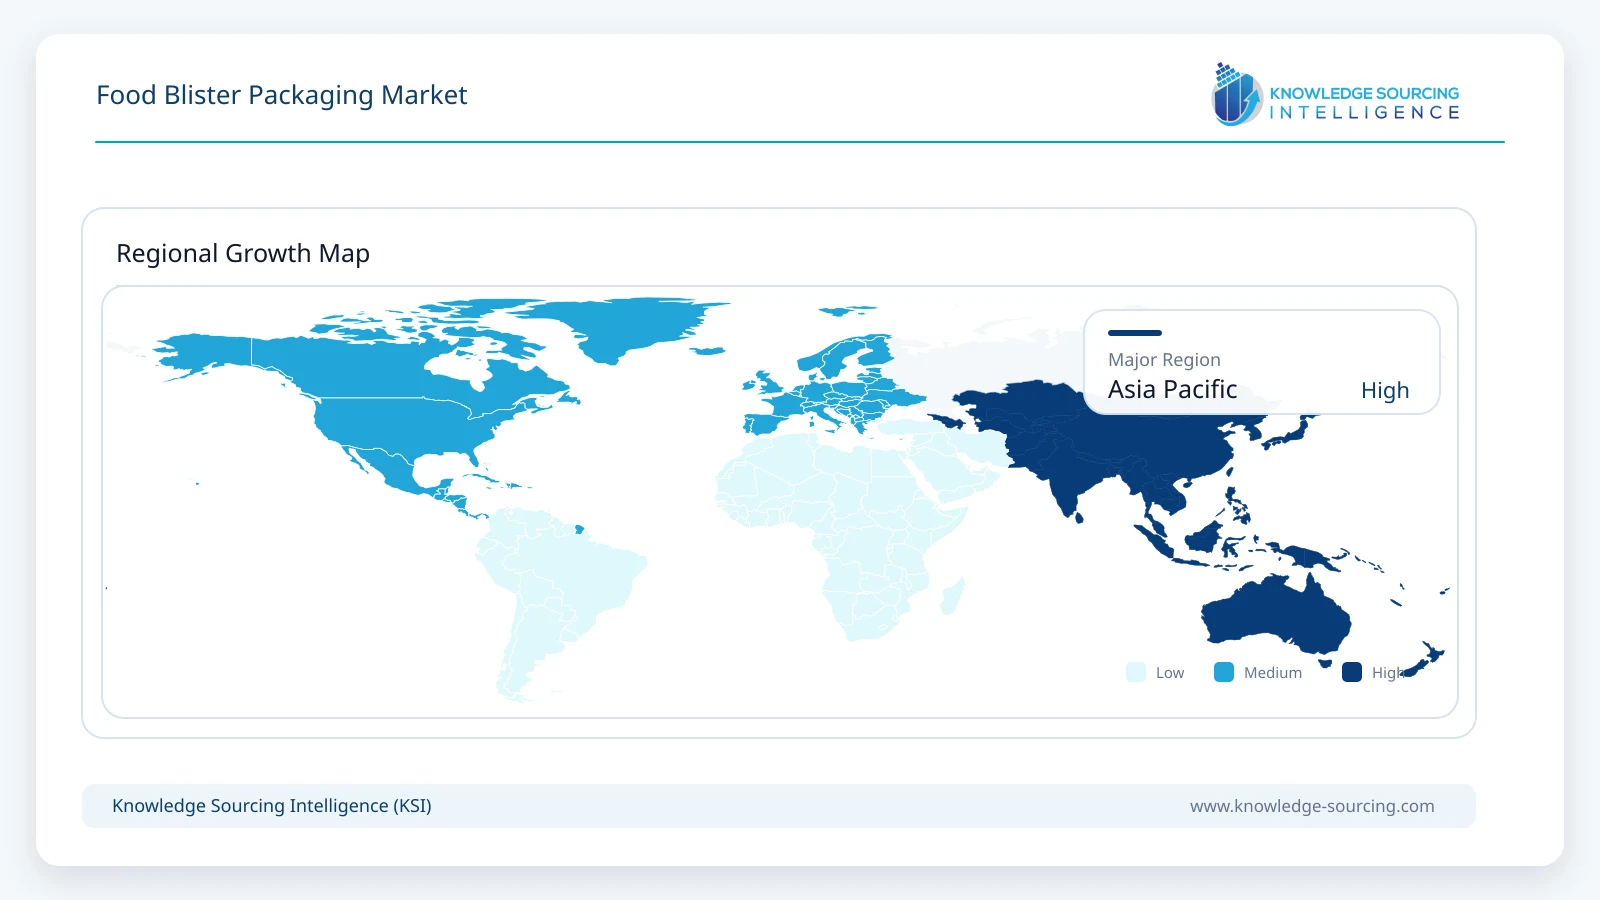
Asia-Pacific: Asia-Pacific is expected to offer substantial growth opportunities as food-processing capacity, urban populations, packaged-food distribution, and organized retail expand across the region. India, China, Japan, and South Korea represent important markets with different levels of industrial development, consumer purchasing power, and packaging infrastructure. The expansion of modern retail and online food distribution can increase the need for packaging that protects products during handling and presents them consistently to consumers.
India's packaging sector also operates within an established regulatory framework for plastic waste management. The Ministry of Environment, Forest and Climate Change maintains the Plastic Waste Management Rules and associated amendments on its official website. These rules and the extended producer responsibility framework are relevant to businesses placing covered plastic packaging on the Indian market. The precise obligations depend on the applicable category and regulatory provisions.
For blister packaging manufacturers, the region offers opportunities in affordable packaging formats, automated food processing, improved distribution protection, and product-specific barrier designs. However, adoption will depend on material costs, local recycling infrastructure, food-contact compliance, and the ability to supply packaging at the required production scale.
South America: South America's food blister packaging market is supported by packaged-food manufacturing, supermarket distribution, confectionery consumption, and demand for improved product presentation. Brazil and other larger economies offer potential applications in snack foods and selected specialty products. Market development will depend on the availability of suitable packaging materials, investments in processing equipment, and the economics of competing formats. Recycling infrastructure and local waste-management requirements will also influence the choice between conventional plastics, alternative materials, and more easily separable packaging structures.
Middle East and Africa: The Middle East and Africa offer opportunities associated with urban retail development, food distribution, packaged snack consumption, and investment in food-processing infrastructure. Blister packaging can provide useful product protection and portion separation for selected foods distributed through supermarkets and convenience stores. However, climate conditions, transportation distances, and differences in cold-chain availability mean that material and package specifications must be adapted to the intended application. Regional recycling capacity and the cost of imported packaging materials may also affect adoption.
Food Blister Packaging Market Competitive Landscape:
The food blister packaging market includes packaging converters, thermoforming specialists, material suppliers, machinery manufacturers, and companies offering integrated packaging systems. The competitive environment is shaped by material expertise, tooling capabilities, forming and sealing performance, customization, production capacity, regulatory documentation, and the ability to provide consistent quality.
Companies compete by developing packaging formats for specific food applications, improving manufacturing efficiency, and responding to customer requirements for recyclability and reduced material consumption. Equipment suppliers also influence market development because forming and sealing systems determine which materials can be processed efficiently at commercial scale.
The companies and suppliers listed include Abhinav Enterprises, Sonic Packaging, Competent Packaging Industries, Vinpac Innovations, Real Packaging, Sudham Packaging Industries, Thermopack, Macpac Ltd., Dongguan Jiasheng Plastic Packaging Products Co., Ltd., and Jiangyin Jiaou New Materials Co., Ltd. Their inclusion should not be interpreted as a verified market-share ranking. Their current product portfolios, food-contact qualifications, geographic coverage, and direct involvement in food blister packaging should be independently assessed before making company-specific competitive claims.
Broader packaging technology developments also provide relevant context. Machinery manufacturers such as MULTIVAC are developing thermoforming systems intended to process recyclable films more consistently, while food packaging companies are introducing solutions designed to improve dispensing, product integrity, and operational efficiency. Such announcements demonstrate wider packaging-industry priorities, but they do not establish that every development is a dedicated food blister product.
Food Blister Packaging Market Developments:
September 2026: Sealed Air announced the launch of CRYOVAC ZeroPrep hand-dispensing pouches for foodservice condiment applications on September 22, 2026. The resealable, pre-filled format is designed to simplify dispensing and reduce preparation and cleanup requirements. Although this is a flexible-pouch development rather than a blister-pack launch, it illustrates the continuing focus on food hygiene, ease of use, and operational efficiency across food packaging.
August 2026: The European Union's Packaging and Packaging Waste Regulation began applying on August 12, 2026. The European Commission confirmed that restrictions on PFAS above specified limits in food-contact packaging became applicable from that date. The regulation is relevant to food blister packaging suppliers serving the European market because it reinforces the need to evaluate material formulations, food-contact compliance, and packaging design. This is a regulatory development rather than a commercial product launch.
April 2026: MULTIVAC announced its RX Ultimate thermoforming packaging machine on April 7, 2026, ahead of interpack 2026. The company highlighted multi-sensor process control, online connectivity, matrix heating, and the ability to process recyclable films while minimizing film thickness. The development is relevant to the broader thermoforming equipment sector and may inform material-efficient food packaging production, although the announcement does not establish that the machine is specifically designed for food blister packaging.
April 2026: Coveris announced PFAS-free, mono-material packaging innovations for pet food on April 22, 2026, ahead of Interzoo 2026. The company described packaging formats designed for dry and wet pet food, snacks, and treats, with a focus on recyclability and product protection. These are flexible packaging developments for animal food rather than direct evidence of a human-food blister product launch. They nevertheless demonstrate how food-related packaging suppliers are responding to material and regulatory considerations.
May 2025: Romaco's Noack N 760 blister packaging machine was introduced as a platform capable of manufacturing recyclable blister packs from PET mono-material. The company's announcement described the use of PET/PET structures as an alternative to conventional PVC/aluminium blister packs, with a focus on maintaining barrier performance. The announcement concerns blister packaging technology primarily discussed in pharmaceutical applications; it should not be treated as a verified food-packaging product launch. It is relevant as an example of ongoing development in mono-material blister manufacturing.
Food Blister Packaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.28 billion |
| Total Market Size in 2031 | USD 4.01 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Material, Technology, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Compartment
Slide
Wallet
By Material
PVC
PVDC
PP
Others
By Technology
Cold-Form
Thermoformed
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY 
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE 
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL FOOD BLISTER PACKAGING MARKET BY TYPE
5.1. Introduction
5.2. Compartment
5.3. Slide
5.4. Wallet
6. GLOBAL FOOD BLISTER PACKAGING MARKET BY MATERIAL
6.1. Introduction
6.2. PVC
6.3. PVDC
6.4. PP
6.5. Others
7. GLOBAL FOOD BLISTER PACKAGING MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Cold-Form
7.3. Thermoformed
8. GLOBAL FOOD BLISTER PACKAGING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By Material
8.2.3. By Technology
8.2.4. By Country
8.2.4.1. USA
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Type
8.3.2. By Material
8.3.3. By Technology
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Type
8.4.2. By Material
8.4.3. By Technology
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Spain
8.4.4.5. Others
8.5. Middle East and Africa
8.5.1. By Type
8.5.2. By Material
8.5.3. By Technology
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. UAE
8.5.4.3. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By Material
8.6.3. By Technology
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. India
8.6.4.4. South Korea
8.6.4.5. Taiwan
8.6.4.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Abhinav Enterprises
10.2. Sonic Packaging
10.3. Competent Packaging Industries
10.4. Vinpac Innovations
10.5. Real Packaging
10.6. Sudham Packaging Industries
10.7. Thermopack
10.8. Macpac Ltd.
10.9. Dongguan Jiasheng Plastic Packaging Products Co. Ltd.
10.10. Jiangyin Jiaou New Materials Co., Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the forecast market size for food blister packaging by 2031?
Market projected to reach USD 4.01 billion by 2031 at 4.1% CAGR.
Which region is estimated to attain a greater market share?
North America is estimated to attain a greater market share.
What are the primary drivers for Food Blister Packaging Market growth?
Industrialization, packaged meat/fruit demand, and e-commerce fuel growth.
Which material segment is forecasted to grow significantly?
The PVC material category is forecasted to grow significantly.
Which technology category is estimated to attain greater market share?
Cold-form technology is estimated to attain greater market share.
Which food blister packaging type is estimated to grow notably?
The compartment category is estimated to grow notably.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Food Blister Packaging Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-food-blister-packaging-market