
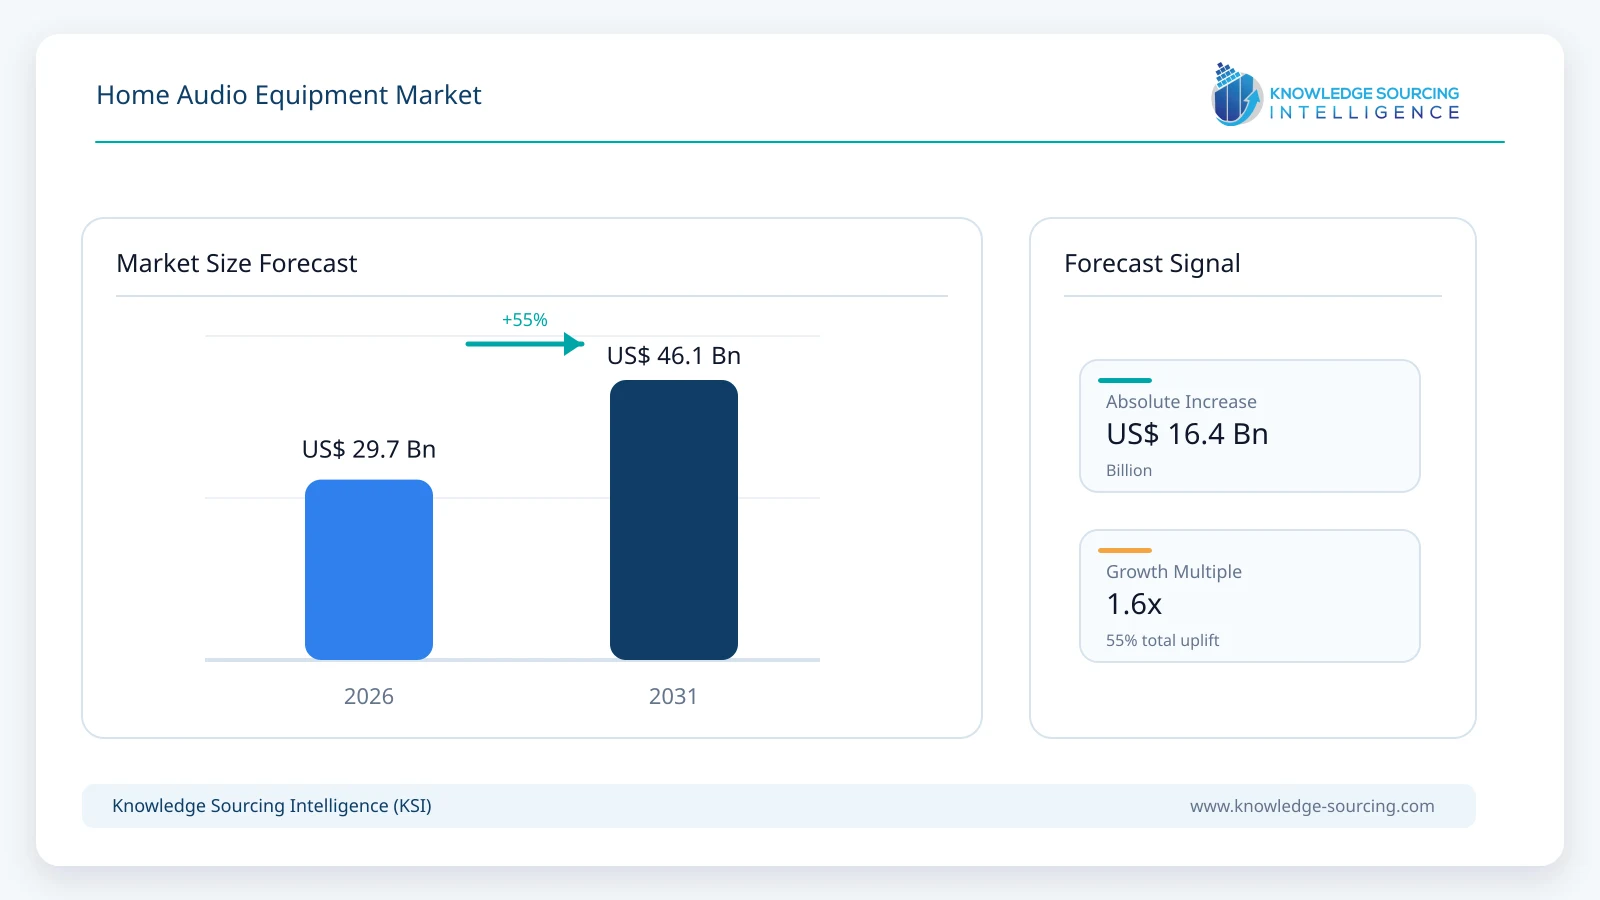
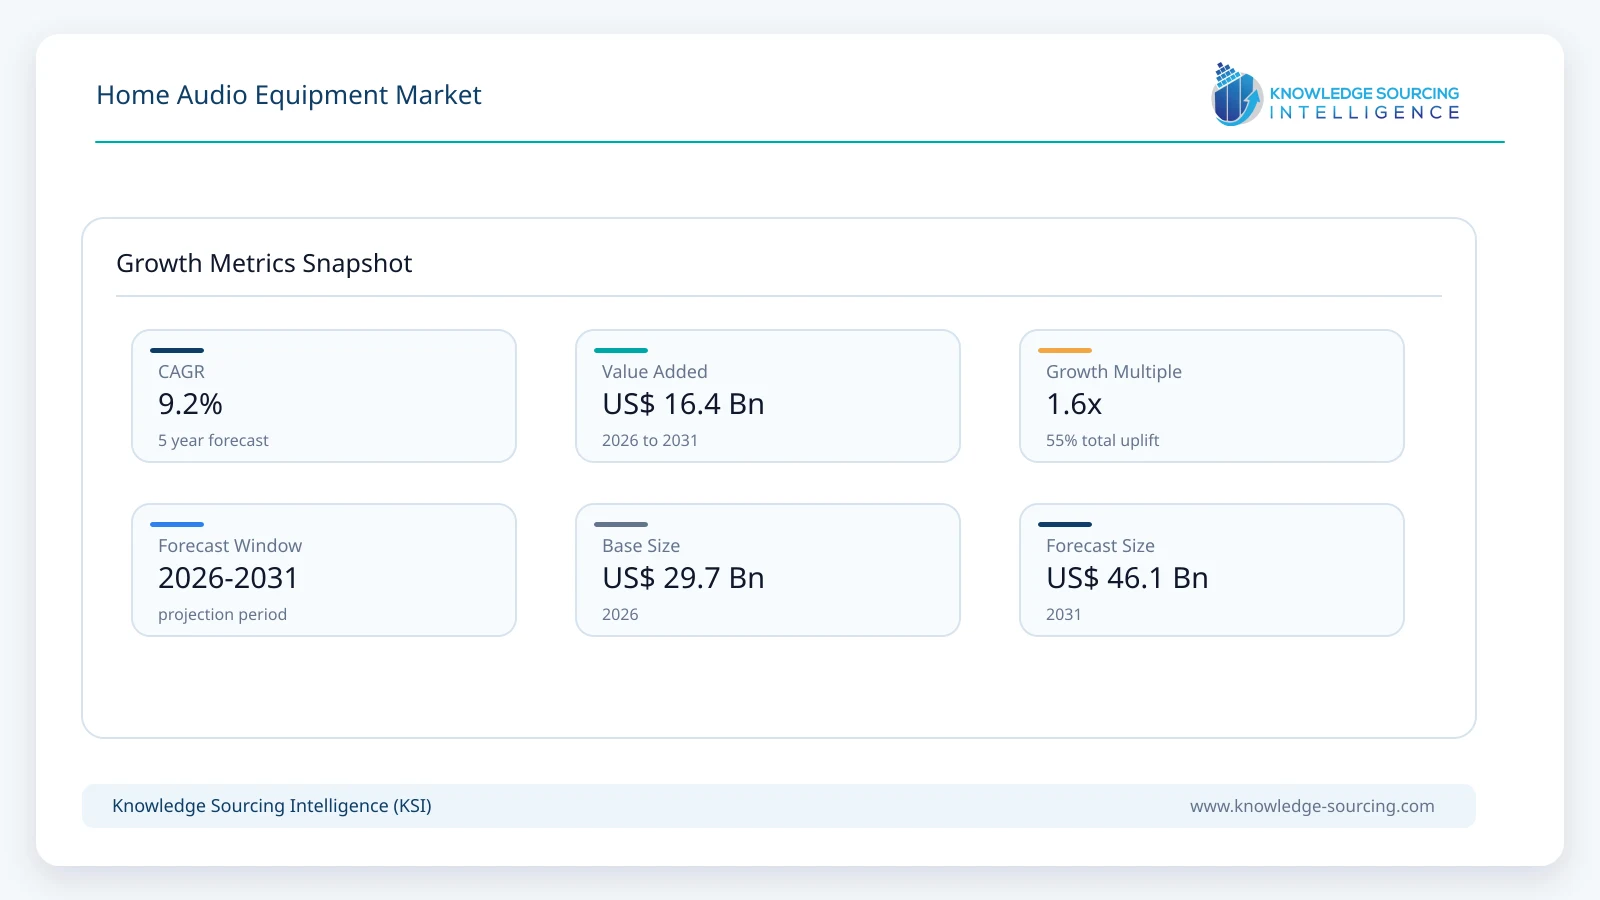
The Home Audio Equipment Market is estimated at approximately USD 29.7 billion in 2026 and is projected to reach about USD 46.1 billion by 2031, at a CAGR of 9.2% during the forecast period.
Highlights:
- 1Soundbars account for about 34% of 2026 revenue as television audio upgrades accelerate.
- 2Wireless and networked products represent roughly 72% of 2026 market value globally.
- 3North America contributes about 35% of 2026 revenue, while Asia Pacific grows faster.
- 4Online channels account for approximately 44% of 2026 sales and continue gaining share.
- 5Modular wireless surrounds are reducing installation barriers for premium home-cinema systems.
- 6Software, AI tuning and ecosystem compatibility increasingly determine product differentiation and retention.
Home audio is shifting away from isolated hardware toward connected entertainment ecosystems. The living-room television remains the largest purchase trigger, but the value proposition increasingly combines cinema sound, music streaming, gaming, voice control and whole-home playback. Soundbars have become the primary upgrade path for mainstream households because they improve dialogue clarity and surround performance without the installation complexity of a conventional multi-speaker system. Premium models now use up-firing and side-firing drivers, wireless subwoofers, room calibration and virtualized or object-based sound to recreate a wider soundstage from a compact form factor.
The premium segment remains structurally important even as mass-market prices fall. Sonos reported USD 1.44 billion in fiscal 2025 revenue and nearly 53.4 million registered products across approximately 17.1 million households. In the first nine months of fiscal 2026, company revenue increased 4.1% year over year, while third-quarter speaker revenue increased materially as product volume improved. These results illustrate that installed ecosystems can support repeat purchasing across additional rooms, subwoofers, surrounds and home-theater components rather than relying solely on first-time buyers.
Industry consolidation is also changing the supplier landscape. HARMAN completed the acquisition of Sound United in September 2025, adding Bowers & Wilkins, Denon, Marantz, Definitive Technology, Polk Audio, HEOS, Classe and Boston Acoustics. Gentex completed the acquisition of VOXX in April 2025, bringing Premium Audio Company and its Klipsch, Onkyo and Integra brands into a larger connected-home and automotive electronics group. These transactions broaden the scale available for product development, distribution and ecosystem integration across premium speakers, AV receivers and home-theater electronics.
Market Trends
Soundbars Are Becoming Modular Home-Theater Platforms
Soundbars are moving beyond the role of a single television accessory. Suppliers increasingly design them as the central element of an expandable theater system, allowing customers to add subwoofers and rear speakers over time. Sony expanded its BRAVIA Theatre range in June 2026 with Theatre Trio, Bar 7, Bar 5, Sub 9, Sub 8 and new rear-speaker products. BRAVIA Direct Connect also allows compatible televisions to connect directly with selected subwoofers and rear speakers. LG took a similar modular approach with its 2026 Sound Suite, pairing the H7 soundbar with separate wireless surrounds and a wireless subwoofer through Dolby Atmos FlexConnect. This architecture lowers installation friction while preserving an upgrade path into higher-value configurations.
Whole-Home Audio Is Becoming a Software and Ecosystem Business
Networked speakers increasingly compete on software continuity, interoperability and multi-room control rather than acoustic hardware alone. In September 2026, Sonos introduced Sonos 27 with AI control through external assistants and agents, improved device movement across rooms and tighter integration between home-theater and personal-audio products. The company also introduced Beam Ultra, a compact 7.1.2 Dolby Atmos soundbar, after launching Sonos Play and Era 100 SL earlier in 2026. Similar ecosystem strategies are visible in Apple HomePod, Amazon Echo, Google Nest and Samsung SmartThings-linked audio products, although dedicated audio brands retain an advantage in premium acoustic performance and expandable theater configurations.
AV Receivers Retain a Distinct Enthusiast and Gaming Position
Soundbars continue to absorb mainstream home-theater demand, but AV receivers remain relevant for consumers who prioritize discrete channels, large passive speakers, gaming performance and system customization. Yamaha introduced the RX300A and RX500A in May 2026 with Dolby Atmos, 4K/120Hz and 8K video support, enhanced wireless streaming and simplified operation. New receivers are therefore being positioned not only as traditional hi-fi electronics but as central switching and processing platforms for consoles, televisions, streaming services and multi-channel cinema systems. The segment grows more slowly than soundbars but retains higher average transaction values and stronger attachment to specialist speaker purchases.
AI and Room-Adaptive Processing Are Expanding the Value of Software
Room correction, dialogue enhancement and automatic speaker mapping are moving into a wider range of home-audio products. Sony uses Sound Field Optimization and Voice Zoom within its BRAVIA ecosystem, Sonos applies Trueplay and AI-assisted speech enhancement, and premium receivers use automated calibration to compensate for room geometry and speaker placement. These features help manufacturers defend price premiums even as amplifiers, wireless chipsets and basic speaker hardware become more standardized. Over the forecast period, product differentiation increasingly depends on the quality of tuning software, app reliability and long-term update support.
Market Drivers
Larger Televisions and Streaming Content Increase Demand for External Audio
Television screen sizes have increased while cabinet depth has decreased, creating a persistent gap between visual performance and integrated speaker capability. Streaming platforms, sports, gaming and premium movie releases further raise expectations for dialogue clarity, bass and surround effects. Home audio therefore benefits from the installed base of large televisions and the growing availability of Dolby Atmos, DTS:X and spatial-audio content. Soundbars and wireless theater systems provide the simplest upgrade for mainstream households, while dedicated receivers and speaker packages serve consumers seeking more precise multi-channel reproduction.
Wireless Connectivity and Smart-Home Integration Broaden the Addressable Customer Base
Wi-Fi, Bluetooth, AirPlay, voice assistants and app-based setup have reduced the technical barriers associated with traditional home audio. Wireless subwoofers and surrounds allow households to add channels without routing speaker cable, while multi-room platforms let the same system serve music and television audio across several rooms. This convergence expands the category beyond conventional audiophiles and home-theater enthusiasts to mainstream smart-home users who value convenience and system-level control.
Premiumization and Repeat Purchases Support Revenue per Household
The market benefits from an upgrade cycle in which customers can expand an existing ecosystem rather than replace it. A soundbar purchase can lead to a subwoofer, rear speakers, a second-room speaker or upgraded receiver, increasing lifetime revenue per household. Sonos reported that approximately 45% of fiscal 2025 new product registrations came from existing customers, illustrating the value of ecosystem retention. Premium brands also benefit from higher willingness to pay for acoustic design, industrial design, lossless playback, spatial audio and room optimization.
Market Restraints
Long Replacement Cycles, Interoperability Friction and Price Compression Limit Faster Growth
Home audio hardware is durable and often remains in service for many years, particularly passive speakers and AV receivers. This limits replacement frequency compared with smartphones or televisions. Fragmented ecosystems can also create compatibility problems involving HDMI eARC, wireless rear speakers, app support, voice assistants and software updates. At the lower end of the market, intense price competition in soundbars and smart speakers compresses margins, while premium products remain exposed to discretionary-spending cycles. Tariffs, logistics costs and semiconductor or acoustic-component sourcing can further affect pricing and demand in import-dependent markets.
Segment Analysis
By Product Type - Soundbars
Soundbars remain the largest product category because they combine clear television-audio improvement, compact installation and increasingly advanced surround capability. The segment is projected to reach approximately USD 16.9 billion by 2031. Premium soundbars are moving toward 7.1.2, 9.1.4 and comparable immersive configurations, while mainstream models increasingly bundle wireless subwoofers and app-based calibration. Smart and networked home speakers grow slightly faster as multi-room audio, AI control and whole-home ecosystems expand, while Blu-ray and dedicated disc-player demand continues to contract.
By Technology - Wireless and Networked
Wireless and networked home audio is projected to generate approximately USD 36.6 billion by 2031. The segment includes Wi-Fi and Bluetooth speakers, wireless soundbars, app-controlled theater systems, network receivers and modular wireless surrounds. Growth is supported by easier installation and the ability to synchronize several rooms. Wired products retain an important role in premium passive-speaker systems, fixed custom installations and enthusiast AV configurations, but their share gradually declines as wireless performance improves.
By Distribution Channel - Offline
Offline channels remain important because premium speakers, soundbars and receiver-based systems benefit from demonstration, specialist advice and bundled installation. Consumer-electronics chains and specialty audio retailers continue to account for a substantial portion of high-value purchases. Online channels grow faster and are projected to approach parity with offline sales by 2031 as direct-to-consumer brands, marketplaces and retailer websites improve comparison, reviews, financing and delivery for large electronics products.
By Application - TV and Home Cinema
TV and home-cinema applications remain the largest demand pool and are projected to generate approximately USD 25.9 billion by 2031. Soundbars, wireless surrounds, subwoofers and AV receivers are directly tied to television and streaming-video upgrades. Music and whole-home listening remains the second-largest use case and benefits from smart speakers, high-resolution streaming and multi-room systems. Gaming grows faster from a smaller base because low-latency HDMI, 4K/120Hz support and immersive sound are increasingly integrated into receivers and premium soundbars.
By Geography - North America
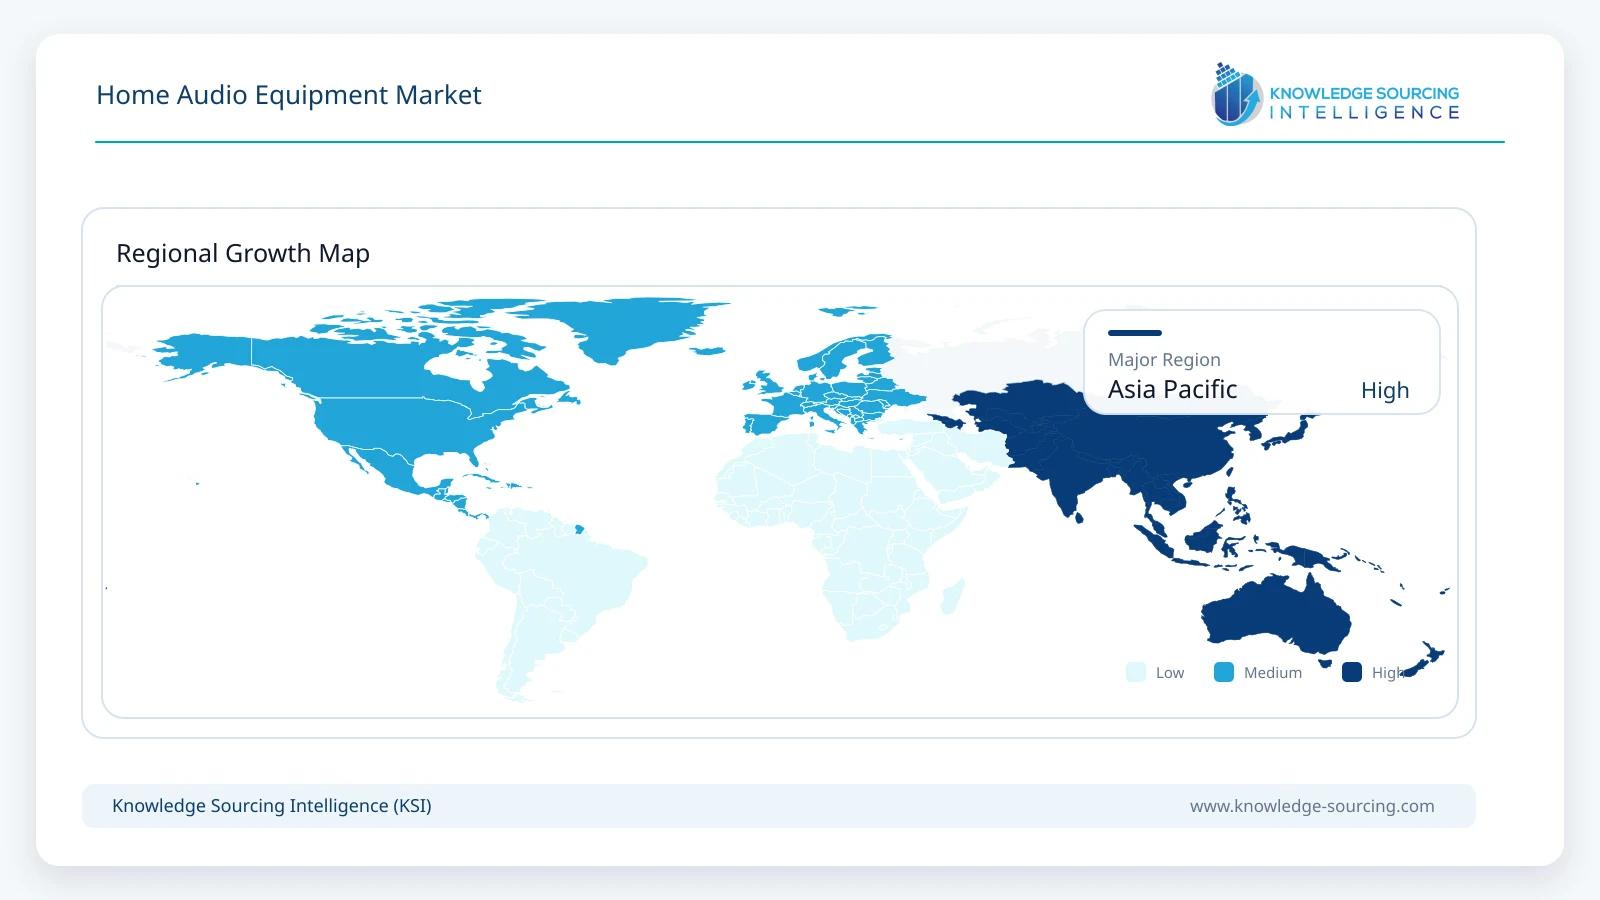
North America remains the largest regional market in 2026 and is projected to generate approximately USD 15.8 billion by 2031. The United States combines high television penetration, premium audio spending, streaming-service adoption and strong retail presence for Sonos, Bose, JBL, Klipsch, Denon, Marantz and other brands. Asia Pacific grows faster and is expected to approach or exceed North America by the end of the forecast period, supported by large consumer-electronics markets in China, Japan, India and South Korea and rapid adoption of affordable wireless soundbars and smart speakers.
Competitive Environment
Competition spans global electronics groups, dedicated audio specialists and smart-platform companies. Samsung Electronics participates through Samsung-branded soundbars and HARMAN, whose portfolio includes JBL, Harman Kardon and, following the Sound United acquisition, Bowers & Wilkins, Denon, Marantz, Polk Audio, Definitive Technology, HEOS and Classe. Sony integrates audio closely with its BRAVIA television ecosystem, while LG is emphasizing modular wireless cinema sound through Sound Suite. Bose and Sonos remain major independent premium brands with strong direct-to-consumer and specialty-retail presence.
Yamaha remains a leading supplier of AV receivers, amplifiers and home-theater electronics. Gentex now owns Premium Audio Company through the 2025 VOXX acquisition, including Klipsch, Onkyo and Integra, and the group used CES 2026 to showcase new powered speakers and receiver concepts. Bang & Olufsen, KEF, Cambridge Audio, Lenbrook, Devialet, Sonance and Vervent Audio Group compete across premium speakers, streaming electronics, custom installation and audiophile segments. Apple, Amazon and Google are important in smart-speaker ecosystems, although their strategies are more closely tied to platform engagement than conventional specialist audio retail.
Competitive advantage increasingly depends on four capabilities: acoustic engineering, software reliability, ecosystem interoperability and channel reach. Brands with strong installed bases can monetize repeat purchases and accessories, while traditional hi-fi companies differentiate through sound quality, industrial design and specialist distribution. Consolidation is likely to remain strategically important because a broader portfolio allows suppliers to cover soundbars, passive speakers, AV receivers, wireless systems and custom installation while sharing software, sourcing and global distribution.
Recent Developments
September 2026: Sonos introduced Beam Ultra with true 7.1.2 Dolby Atmos alongside the Sonos 27 audio operating system and expanded AI control.
June 2026: Sony India expanded the BRAVIA Theatre portfolio with Theatre Trio, Bar 7, Bar 5, new subwoofers and wireless rear speakers.
May 2026: Yamaha introduced the RX300A and RX500A AV receivers with Dolby Atmos, 4K/120Hz, 8K support and enhanced streaming.
March 2026: Sonos launched Sonos Play and Era 100 SL to strengthen its multi-room home speaker lineup.
January 2026: LG announced U.S. availability for its modular Sound Suite, led by the H7 Dolby Atmos FlexConnect soundbar.
September 2025: HARMAN completed the acquisition of Sound United, adding Bowers & Wilkins, Denon, Marantz, Polk Audio and other premium brands.
Home Audio Equipment Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 29.7 billion |
| Total Market Size in 2031 | USD 46.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Technology, Distribution Channel, Application, Geography |
| Companies |
|
Market Segmentation
By Product Type
Soundbars
Smart and Wireless Home Speakers
Home Theater Systems and Speaker Packages
AV Receivers, Amplifiers and Hi-Fi Components
Blu-ray/DVD Players and Others
By Technology
Wired
Wireless and Networked
By Distribution Channel
Online
Offline
Specialty Electronics and Audio Stores
Mass Merchants and Consumer Electronics Chains
Others
By Application
TV and Home Cinema
Music and Whole-Home Audio
Gaming
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Larger Televisions and Streaming Content Increase Demand for External Audio
3.1.2. Wireless Connectivity and Smart-Home Integration Broaden the Addressable Customer Base
3.1.3. Premiumization and Repeat Purchases Support Revenue per Household
3.2. Market Restraints
3.2.1. Long Replacement Cycles, Interoperability Friction and Price Compression Limit Faster Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Dolby Atmos, DTS:X and Spatial Audio
4.2. Room Calibration and AI-Enabled Dialogue Enhancement
4.3. Wi-Fi, Bluetooth LE Audio and Multi-Room Networking
4.4. Wireless Subwoofers and Rear Speakers
4.5. HDMI eARC, 4K/120Hz and 8K Pass-Through
4.6. Lossless and High-Resolution Audio Streaming
4.7. Software-Defined Audio and Voice/AI Control
5. HOME AUDIO EQUIPMENT MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Soundbars
5.3. Smart and Wireless Home Speakers
5.4. Home Theater Systems and Speaker Packages
5.5. AV Receivers, Amplifiers and Hi-Fi Components
5.6. Blu-ray/DVD Players and Others
6. HOME AUDIO EQUIPMENT MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Wired
6.3. Wireless and Networked
7. HOME AUDIO EQUIPMENT MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.3. Offline
7.3.1. Specialty Electronics and Audio Stores
7.3.2. Mass Merchants and Consumer Electronics Chains
7.3.3. Others
8. HOME AUDIO EQUIPMENT MARKET BY APPLICATION
8.1. Introduction
8.2. TV and Home Cinema
8.3. Music and Whole-Home Audio
8.4. Gaming
8.5. Others
9. HOME AUDIO EQUIPMENT MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. United Kingdom
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East & Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Thailand
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Brand and Ecosystem Positioning
10.3. Product and Technology Benchmarking
10.4. Mergers, Acquisitions and Portfolio Consolidation
10.5. Distribution and Channel Strategy
10.6. Competitive Dashboard
11. COMPANY PROFILES
11.1. Samsung Electronics Co., Ltd.
11.2. Sony Group Corporation
11.3. LG Electronics Inc.
11.4. Bose Corporation
11.5. Sonos, Inc.
11.6. Yamaha Corporation
11.7. Panasonic Holdings Corporation (Technics)
11.8. Apple Inc.
11.9. Amazon.com, Inc.
11.10. Google LLC
11.11. Bang & Olufsen A/S
11.12. Gentex Corporation
11.13. Sonance
11.14. Lenbrook International
11.15. GP Acoustics International Limited (KEF)
11.16. Audio Partnership Plc (Cambridge Audio)
11.17. Devialet S.A.
11.18. Vervent Audio Group
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











