
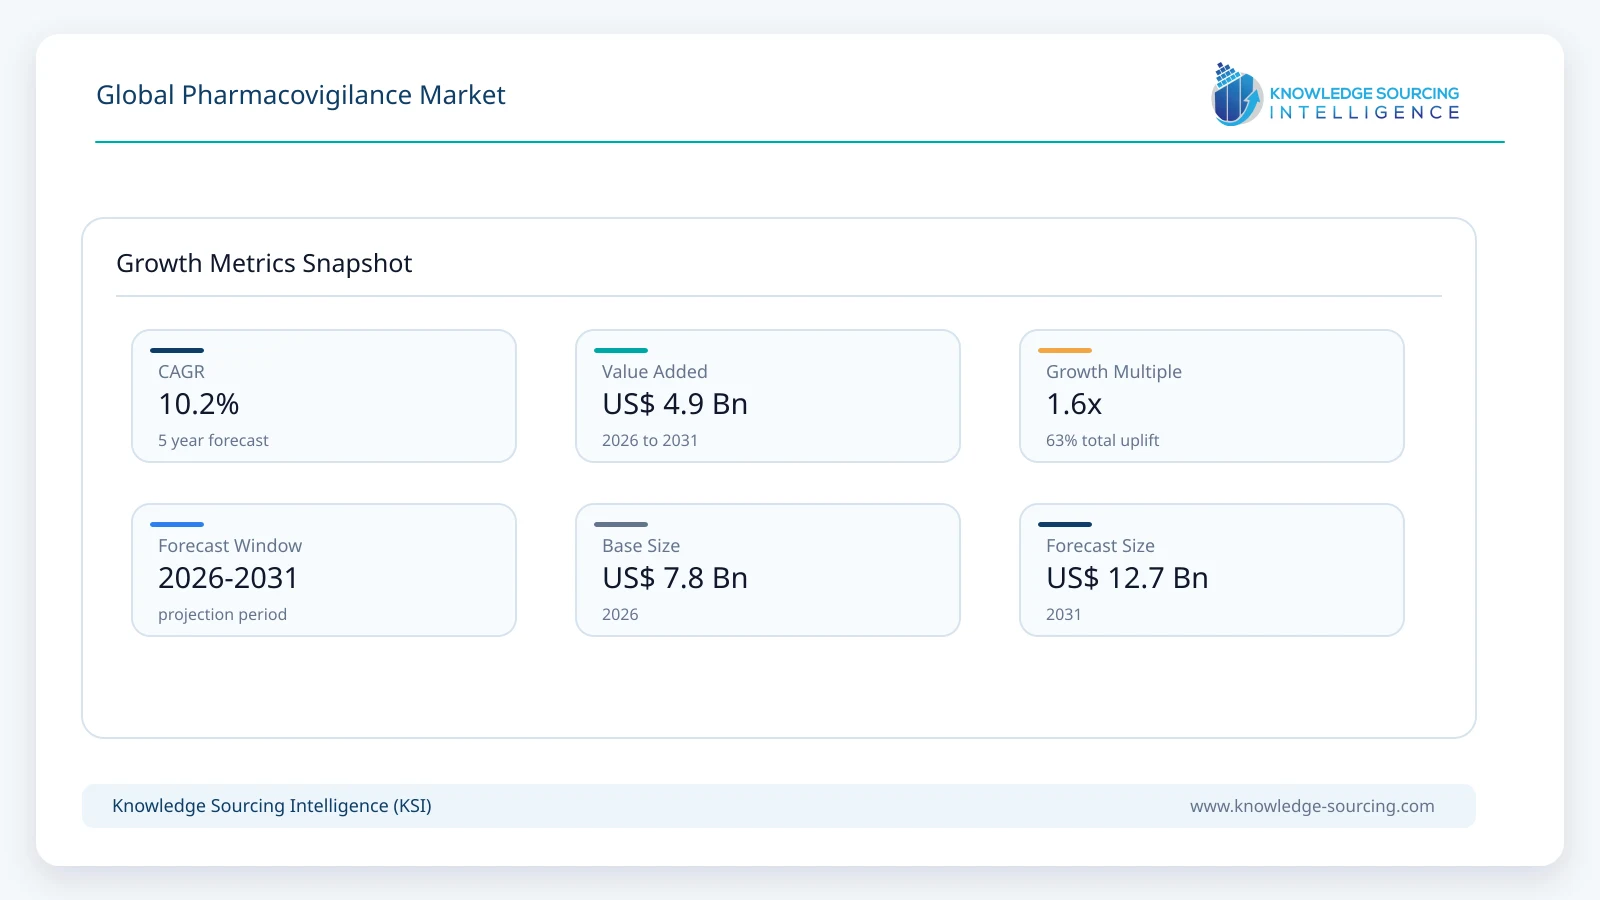
The global pharmacovigilance market is estimated at USD 7.80 billion in 2026 and is forecast to reach USD 12.70 billion in 2031, representing a CAGR of 10.24% over the forecast period.
Highlights:
- 1The market is estimated at USD 7.80 billion in 2026, with double-digit growth through 2031.
- 2Post-marketing safety remains the largest workload because marketed products generate continuous global reporting obligations.
- 3AI is moving from pilot use toward governed intake, triage, narrative, literature, and signal workflows.
- 4Outsourcing continues to deepen as sponsors seek scalable case-processing capacity and country-level regulatory coverage.
- 5Advanced therapies, specialty medicines, and broader real-world data sources increase medical-review and surveillance complexity.
- 6North America remains the largest commercial market, while Asia Pacific expands fastest through delivery hubs and biopharma growth.
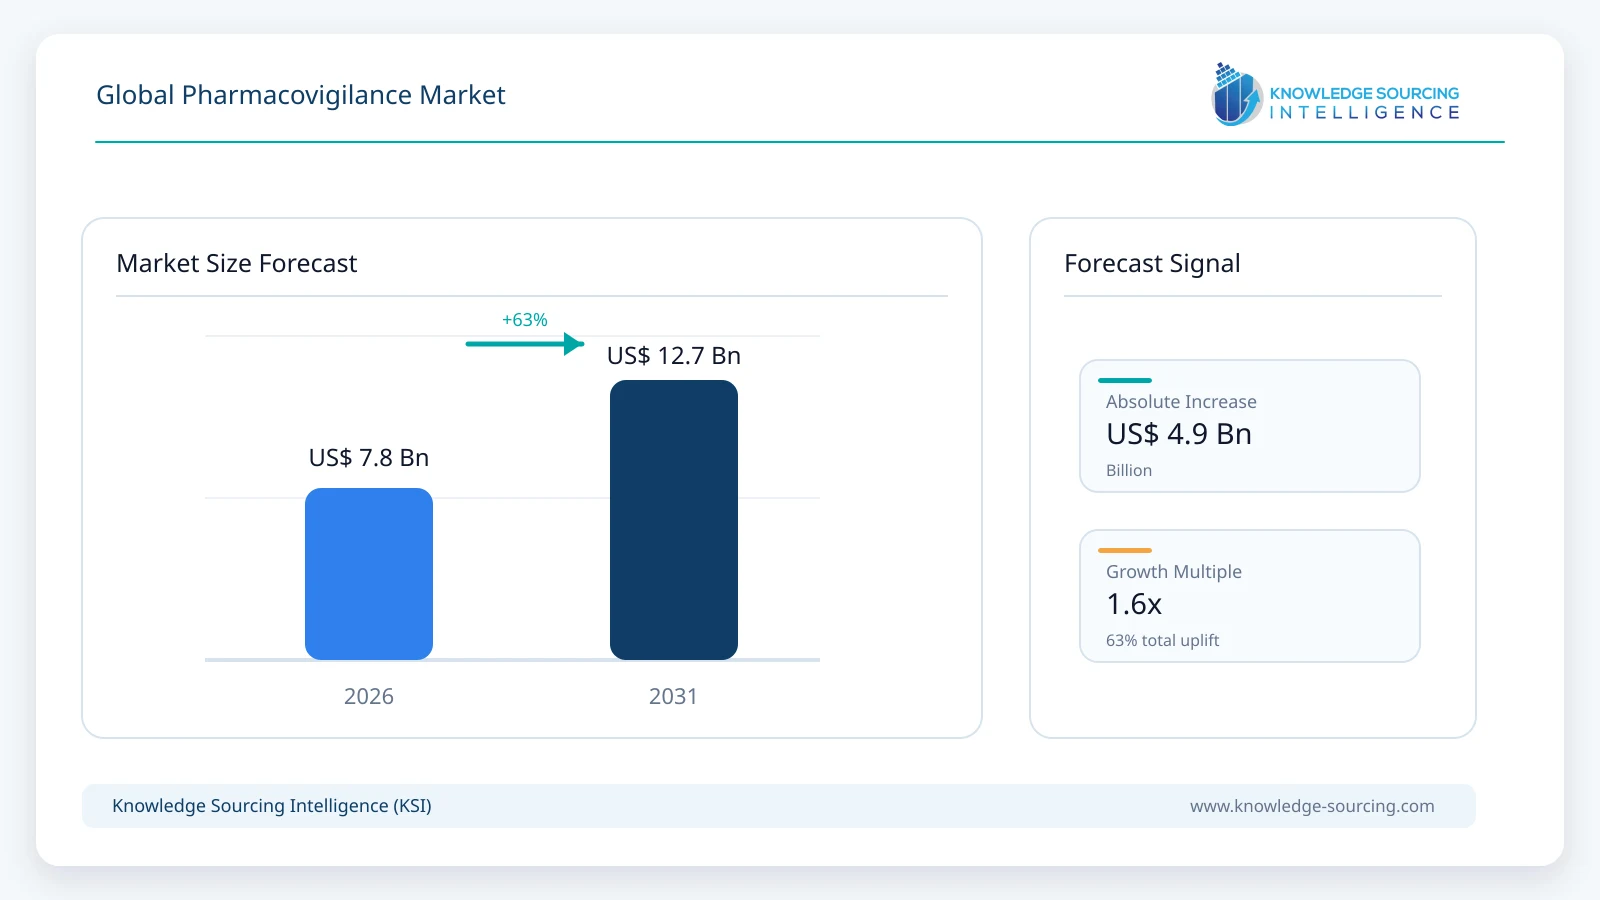
These operating indicators support a global external-services market materially larger than simple per-case processing revenue. A complete pharmacovigilance program also requires medical assessment, expedited and periodic reporting, signal management, risk plans, literature surveillance, local affiliate coverage, database administration, quality systems, audits, and regulatory intelligence. Technology reduces manual effort in selected steps but does not eliminate the medical, compliance, and governance layers that account for a substantial share of spend.
The forecast assumes continued growth in marketed medicine portfolios, biologics and advanced therapies, more data from patient-support programs and digital channels, increasing regulatory expectations for near-real-time surveillance, and further transfer of safety operations to specialist providers. Growth is moderated by automation-led productivity gains, price pressure in commoditized case processing, sponsor consolidation, and the need to validate AI systems before they can be used in regulated decision-making.
Pharmacovigilance Market Trends
AI Moves Into Governed Production Workflows
Pharmacovigilance providers are shifting AI from isolated pilots into controlled workflow components for intake, duplicate detection, data extraction, narrative support, literature screening, coding assistance, and signal analytics. The commercial effect is not simply lower headcount. Providers are increasingly selling a combination of safety expertise, automation, validation, audit trails, and human oversight. Parexel’s 2026 acquisition of Vitrana and PrimeVigilance’s deployment of Oracle Argus illustrate how service companies are integrating technology platforms directly into their operating models.
Regulatory acceptance remains risk-based rather than automatic. AI-supported work that influences safety decisions requires documented intended use, validation, quality controls, and traceability. This favors larger providers and specialists able to combine medical expertise with regulated technology implementation.
Regulators Modernize Safety Data Infrastructure
The U.S. FDA began implementing the Adverse Event Monitoring System (AEMS) in March 2026 to consolidate previously separate adverse-event reporting systems and strengthen data quality, case processing, analytics, and cross-product surveillance. EMA has also been modernizing EudraVigilance analytics; its 2025 report states that a minimum viable product for Signal and Safety Analytics was deployed in December 2025 with additional enhancements planned in 2026.
These changes raise the technical bar for sponsors and service providers. Interfaces, E2B-compliant reporting, data quality, reconciliation, and inspection-ready evidence increasingly become part of the pharmacovigilance service proposition rather than back-office IT tasks.
Post-Marketing Surveillance Becomes More Data Intensive
Safety monitoring is expanding beyond spontaneous adverse-event reports. Literature, registries, patient-support programs, digital engagement channels, real-world evidence, and product-specific risk-management commitments create more surveillance inputs. At the same time, specialty therapies and advanced modalities often have smaller trial populations and clinically complex risks, increasing the importance of medical review after launch.
This shifts value toward integrated teams that can combine high-volume operations with safety science. Providers that offer signal detection, epidemiology, benefit-risk assessment, risk-minimization support, and global affiliate coverage can capture work that is less exposed to unit-price competition than standard case entry.
FSP and Full-Service Models Coexist
Sponsors increasingly use multiple outsourcing structures. Full-service pharmacovigilance transfers end-to-end responsibility to a provider, while functional service provider models supply dedicated teams embedded in sponsor processes and technology. Project-based consulting remains important for migrations, remediation, inspection readiness, and mergers or portfolio transfers.
The result is a market where scale and flexibility matter simultaneously. Large CROs can support multi-country portfolios and very high case volumes, while specialist pharmacovigilance firms compete on responsiveness, local coverage, medical depth, and safety-system expertise.
Local Affiliate Coverage Remains Difficult to Automate Away
Country-level pharmacovigilance obligations continue to create demand for qualified-person, local responsible-person, literature, intelligence, and authority-contact services. Even where case processing is centralized, local reporting rules and inspection expectations can require in-country or region-specific expertise.
Global networks therefore remain commercially important. Providers are investing in affiliate models and partner networks across Latin America, Asia Pacific, Europe, and the Middle East to offer sponsors one governance layer across many national requirements.
Global Pharmacovigilance Market Segment Analysis
By Service Type
ICSR Intake, Case Processing and Reporting
ICSR intake, case processing, medical coding, quality review, and regulatory submission are estimated to represent approximately 41.0% of the 2026 market, equivalent to about USD 3.20 billion. This remains the largest service pool because every clinical and marketed portfolio generates recurring safety cases with strict reporting timelines. Volume can be very large: Cognizant reports more than four million adverse-event case versions processed annually, while Fortrea reports more than one million ICSRs annually.
Automation is reducing manual touches per case, but expanding data sources and sponsor portfolios offset part of that productivity gain. The segment is therefore expected to grow below the overall market while remaining the largest revenue pool through 2031.
By Service Type
Signal Detection, Benefit-Risk and Risk Management
Signal detection, safety surveillance, benefit-risk assessment, and risk-management support are estimated at approximately USD 1.33 billion in 2026, or about 17.0% of market revenue. This segment is expected to grow faster than routine case processing because regulators and sponsors are placing more emphasis on continuous signal evaluation across multiple data sources, not only individual spontaneous reports.
AI and advanced analytics increase the amount of information that can be screened, but clinically meaningful signal assessment remains dependent on medical and statistical judgment. That combination of technology and specialist expertise supports higher value per engagement and makes this one of the strongest growth areas within pharmacovigilance services.
By Product Lifecycle
Post-Marketing Safety
Post-marketing pharmacovigilance is estimated at approximately USD 4.91 billion in 2026, representing about 63.0% of the total market. Once a product is marketed, obligations continue across spontaneous reporting, literature review, periodic reports, signal management, risk-management plans, labeling changes, local affiliate activities, and regulatory queries. Marketed portfolios also remain under surveillance for many years, creating a recurring installed base of work.
Pre-approval safety remains substantial, particularly for complex development programs, vaccines, oncology, rare disease, and advanced therapies, but the breadth and duration of post-marketing obligations keep commercialized products as the larger revenue pool.
By Delivery Model
Full-Service and Managed Pharmacovigilance
Full-service and managed pharmacovigilance models are estimated at approximately USD 4.21 billion in 2026, or 54.0% of global market revenue. Sponsors use these models to transfer operational scale, global coverage, and technology responsibility while retaining governance and medical oversight. The model is particularly attractive to smaller biotechnology companies launching their first products and to large companies seeking to consolidate fragmented regional operations.
Functional service provider and staff-augmentation models remain important for sponsors that want greater control over processes and systems. Consulting and project work adds a smaller but higher-value layer around transformations, remediation, audits, and M&A integration.
By End User
Pharmaceutical Companies
Pharmaceutical companies are estimated to account for approximately USD 5.38 billion of pharmacovigilance services revenue in 2026, or about 69.0% of the market. Large marketed portfolios, global authorization footprints, and continuous regulatory obligations make pharmaceutical companies the largest buyers. Biotechnology companies represent the fastest-expanding buyer group as emerging sponsors progress complex assets toward approval without building fully internal safety organizations.
Medical-device vigilance and consumer-health safety services are adjacent opportunities but are treated separately where regulatory frameworks and reporting systems materially differ from medicinal-product pharmacovigilance.
By Geography
North America
North America is estimated at approximately USD 3.04 billion in 2026, representing about 39.0% of global market revenue. The United States combines the world’s largest pharmaceutical revenue pool, extensive clinical development, high outsourcing penetration, and demanding FDA post-marketing requirements. The FDA’s AEMS modernization also creates additional technology and data-integration work for sponsors and service providers.
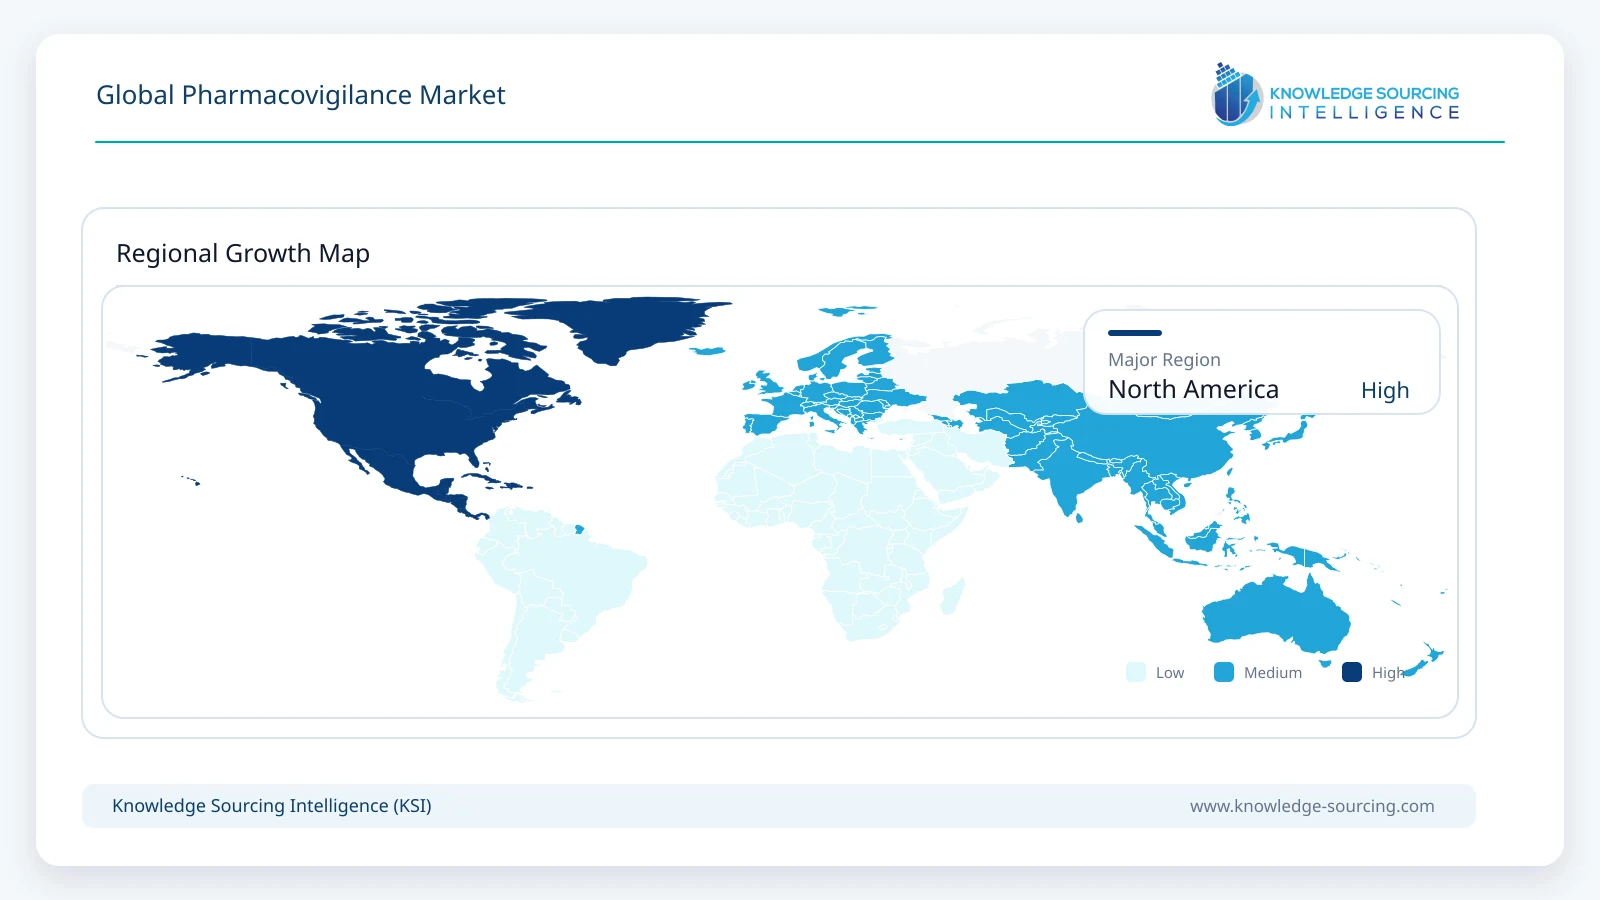
Asia Pacific is expected to grow faster than North America through 2031. Growth is supported by expanding biopharmaceutical R&D, increasing local regulatory maturity, and the region’s role as a global delivery base for case processing, medical review, aggregate reporting, and safety technology operations.
Market Drivers
Increasing Medicine Utilization and Product Complexity
A larger and more complex portfolio of marketed medicines produces more safety data and more product-specific surveillance obligations. Biologics, oncology therapies, cell and gene therapies, and rare-disease products can require intensive medical assessment even where patient numbers are relatively small.Regulatory Reporting and Continuous Benefit-Risk Monitoring
FDA, EMA, PMDA, MHRA, and other authorities require sponsors to maintain compliant pharmacovigilance systems, submit expedited and periodic reports, detect signals, and update risk-management measures. These are recurring legal obligations rather than discretionary analytics projects.Growth of Outsourcing and Functional Service Models
Sponsors increasingly seek flexible capacity, 24-hour processing coverage, lower fixed infrastructure requirements, and access to country-specific expertise. Outsourcing is especially attractive during launches, acquisitions, portfolio transfers, and sudden case-volume increases.Expansion of Safety Data Sources
Patient-support programs, literature, registries, digital channels, real-world evidence, and connected care generate additional safety information. More sources increase both intake workload and the need for deduplication, reconciliation, and advanced signal detection.Safety Technology Modernization
Migration toward cloud safety databases, automated intake, analytics, and governed AI creates implementation, validation, integration, and managed-service demand in addition to traditional pharmacovigilance operations.
Market Restraints
Automation and Pricing Pressure in Routine Case Processing
Case intake and data-entry work is increasingly automated. Providers must convert productivity improvements into lower unit costs while protecting quality, which constrains revenue growth in the most standardized services.AI Validation and Regulatory Governance
AI can accelerate safety workflows, but regulated use requires intended-use controls, validation, traceability, data-quality safeguards, and human oversight. Implementation can therefore be slower and more expensive than generic enterprise automation.Data Privacy and Cross-Border Constraints
Safety cases can contain sensitive health and personal information. Global delivery models must address privacy laws, data residency, security, and contractual restrictions across jurisdictions.Fragmented Local Requirements
Reporting timelines, local literature expectations, qualified-person requirements, and authority interfaces differ by market. This increases operating complexity and reduces the extent to which one global workflow can be standardized.Specialist Talent Requirements
Medical review, signal assessment, benefit-risk evaluation, and inspection readiness require experienced safety physicians, pharmacists, scientists, and regulatory specialists. Shortages in these skills can constrain scaling and raise delivery costs.
Competitive Environment
The pharmacovigilance market combines large CROs, technology-enabled business-process providers, and specialist drug-safety firms. IQVIA, Parexel, ICON, Fortrea, Syneos Health, and the PPD clinical research business of Thermo Fisher Scientific compete with broad clinical-development relationships and global delivery scale. Cognizant and Indegene bring strong technology and process-transformation capabilities, while PrimeVigilance, ProPharma, APCER Life Sciences, ProductLife Group, PharmaLex, Navitas Life Sciences, ClinChoice, and Medpace compete through specialist safety operations, local coverage, consulting, and flexible service models.
Scale is most important in high-volume case operations, where utilization, automation, follow-the-sun delivery, and database expertise determine cost. Medical depth and regulatory credibility become more important in signal management, safety science, risk management, aggregate reporting, and inspection support. Providers are therefore investing in AI-enabled tools while retaining human medical review as the final control for high-impact decisions.
Technology ownership is becoming a differentiator. Parexel acquired Vitrana in April 2026 to add an AI-enabled end-to-end pharmacovigilance platform, while PrimeVigilance has integrated Oracle Argus into its service model. This does not eliminate specialist software vendors; instead, it shifts competition toward service providers capable of operating, validating, and improving safety technology as part of an outsourced program.
Recent Developments
March 2026: The U.S. FDA moved FAERS data into the new Adverse Event Monitoring System (AEMS), part of a broader plan to consolidate adverse-event reporting systems and strengthen data quality, workflows, analytics, and cross-product surveillance.
April 2026: Parexel announced the acquisition of Vitrana, adding an AI-enabled pharmacovigilance technology platform designed to integrate with major safety databases and automate end-to-end safety workflows.
March 2026: EMA published its 2025 EudraVigilance annual report, reporting approximately 1.77 million ICSRs received in 2025 and noting deployment of a Signal and Safety Analytics minimum viable product in December 2025 with further enhancements expected during 2026.
September 2025: PrimeVigilance acquired Prudentia Group, combining global pharmacovigilance operations with safety-technology, process, and management consulting capabilities.
July 2025: PrimeVigilance expanded its technology-enabled drug-safety model using Oracle Argus, with an emphasis on AI-supported case management, workflow optimization, and regulatory compliance.
2025-2026: Major providers including IQVIA, ICON, Cognizant, Parexel, and Indegene increased emphasis on governed AI, automation, and advanced analytics across case intake, literature surveillance, signal management, and reporting.
Market Outlook
The pharmacovigilance market is expected to maintain high-single-digit to low-double-digit growth through 2031. Routine case processing will remain the largest service pool but will become more automated and price competitive. A greater share of incremental value is expected to come from safety science, signal analytics, global affiliate coverage, risk management, safety-system transformation, and technology-enabled managed services.
The strongest providers will combine three capabilities: global operational scale, medically credible safety expertise, and validated technology. Sponsors are unlikely to replace qualified safety judgment with autonomous AI, but they will increasingly expect providers to demonstrate measurable reductions in manual effort, faster cycle times, better data quality, and stronger oversight.
North America should remain the largest revenue market, while Asia Pacific gains share as a biopharmaceutical growth region and global delivery center. The forecast remains sensitive to pharmaceutical R&D cycles, provider pricing, sponsor consolidation, and the pace at which AI productivity is translated into lower service prices.
Global Pharmacovigilance Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 7.80 billion |
| Total Market Size in 2031 | USD 12.70 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.24% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Service Type, Product Lifecycle, Delivery Model, End-User, Geography |
| Companies |
|
Market Segmentation
By Service Type
ICSR Intake, Case Processing and Reporting
Aggregate Reporting and Medical Writing
Signal Detection and Safety Surveillance
Benefit-Risk and Risk Management
QPPV, Local Affiliate and Regulatory Intelligence Services
Safety Database, Migration and Technology Services
By Product Lifecycle
Pre-Approval / Clinical Development Safety
Post-Marketing Safety
By Delivery Model
Full-Service / Managed Pharmacovigilance
Functional Service Provider / Dedicated Teams
Consulting and Project-Based Services
By End User
Pharmaceutical Companies
Biotechnology Companies
Medical Device and Consumer Health Companies
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Increasing Medicine Utilization and Product Complexity
4.1.2. Regulatory Reporting and Continuous Benefit-Risk Monitoring
4.1.3. Growth of Outsourcing and Functional Service Models
4.1.4. Expansion of Safety Data Sources
4.1.5. Safety Technology Modernization
4.2. Market Restraints
4.2.1. Automation and Pricing Pressure in Routine Case Processing
4.2.2. AI Validation and Regulatory Governance
4.2.3. Data Privacy and Cross-Border Constraints
4.2.4. Fragmented Local Requirements
4.2.5. Specialist Talent Requirements
5. PHARMACOVIGILANCE MARKET BY SERVICE TYPE
5.1. ICSR Intake, Case Processing and Reporting
5.2. Aggregate Reporting and Medical Writing
5.3. Signal Detection and Safety Surveillance
5.4. Benefit-Risk and Risk Management
5.5. QPPV, Local Affiliate and Regulatory Intelligence Services
5.6. Safety Database, Migration and Technology Services
6. PHARMACOVIGILANCE MARKET BY PRODUCT LIFECYCLE
6.1. Pre-Approval / Clinical Development Safety
6.2. Post-Marketing Safety
7. PHARMACOVIGILANCE MARKET BY DELIVERY MODEL
7.1. Full-Service / Managed Pharmacovigilance
7.2. Functional Service Provider / Dedicated Teams
7.3. Consulting and Project-Based Services
8. PHARMACOVIGILANCE MARKET BY END USER
8.1. Pharmaceutical Companies
8.2. Biotechnology Companies
8.3. Medical Device and Consumer Health Companies
8.4. Others
9. PHARMACOVIGILANCE MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Southeast Asia
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Full-Service versus FSP Positioning
10.3. Safety Technology and AI Capabilities
10.4. Global Affiliate and QPPV Coverage
10.5. Recent Developments
10.6. Competitive Dashboard
11. COMPANY PROFILES
11.1. IQVIA Holdings Inc.
11.2. Parexel International Corporation
11.3. ICON plc
11.4. Fortrea Holdings Inc.
11.5. Syneos Health
11.6. Thermo Fisher Scientific - PPD Clinical Research
11.7. Cognizant Technology Solutions Corporation
11.8. PrimeVigilance (Ergomed Group)
11.9. ProPharma Group
11.10. APCER Life Sciences
11.11. ProductLife Group
11.12. PharmaLex
11.13. Indegene Limited
11.14. Navitas Life Sciences
11.15. ClinChoice
11.16. Medpace Holdings, Inc.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Abbreviations
Navigate
Trusted by the world's leading organizations











