
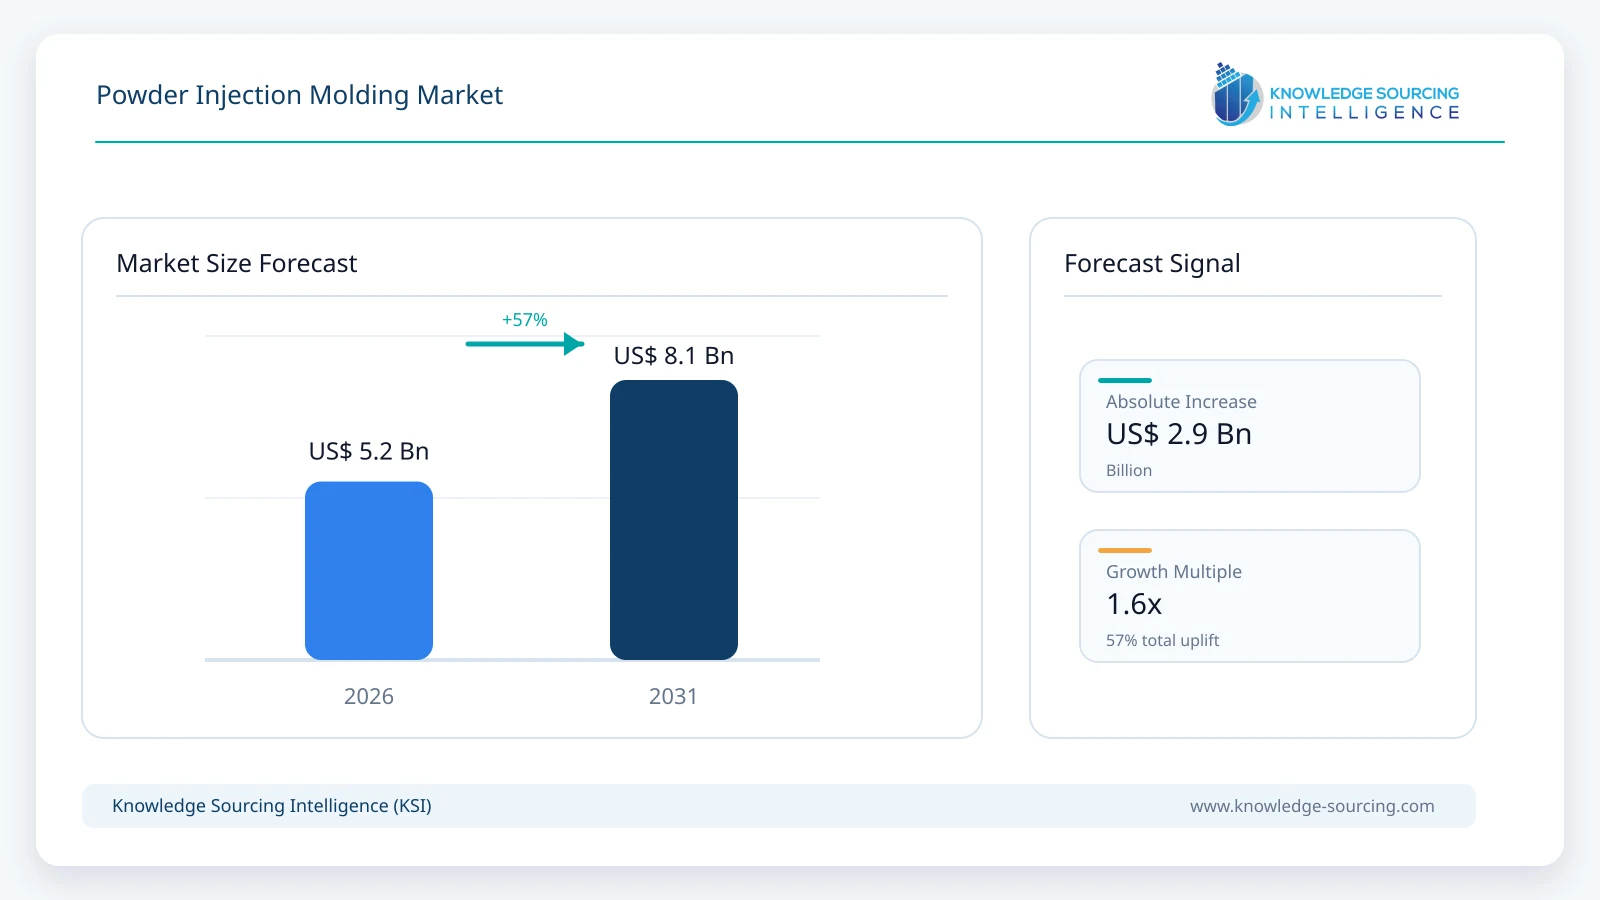
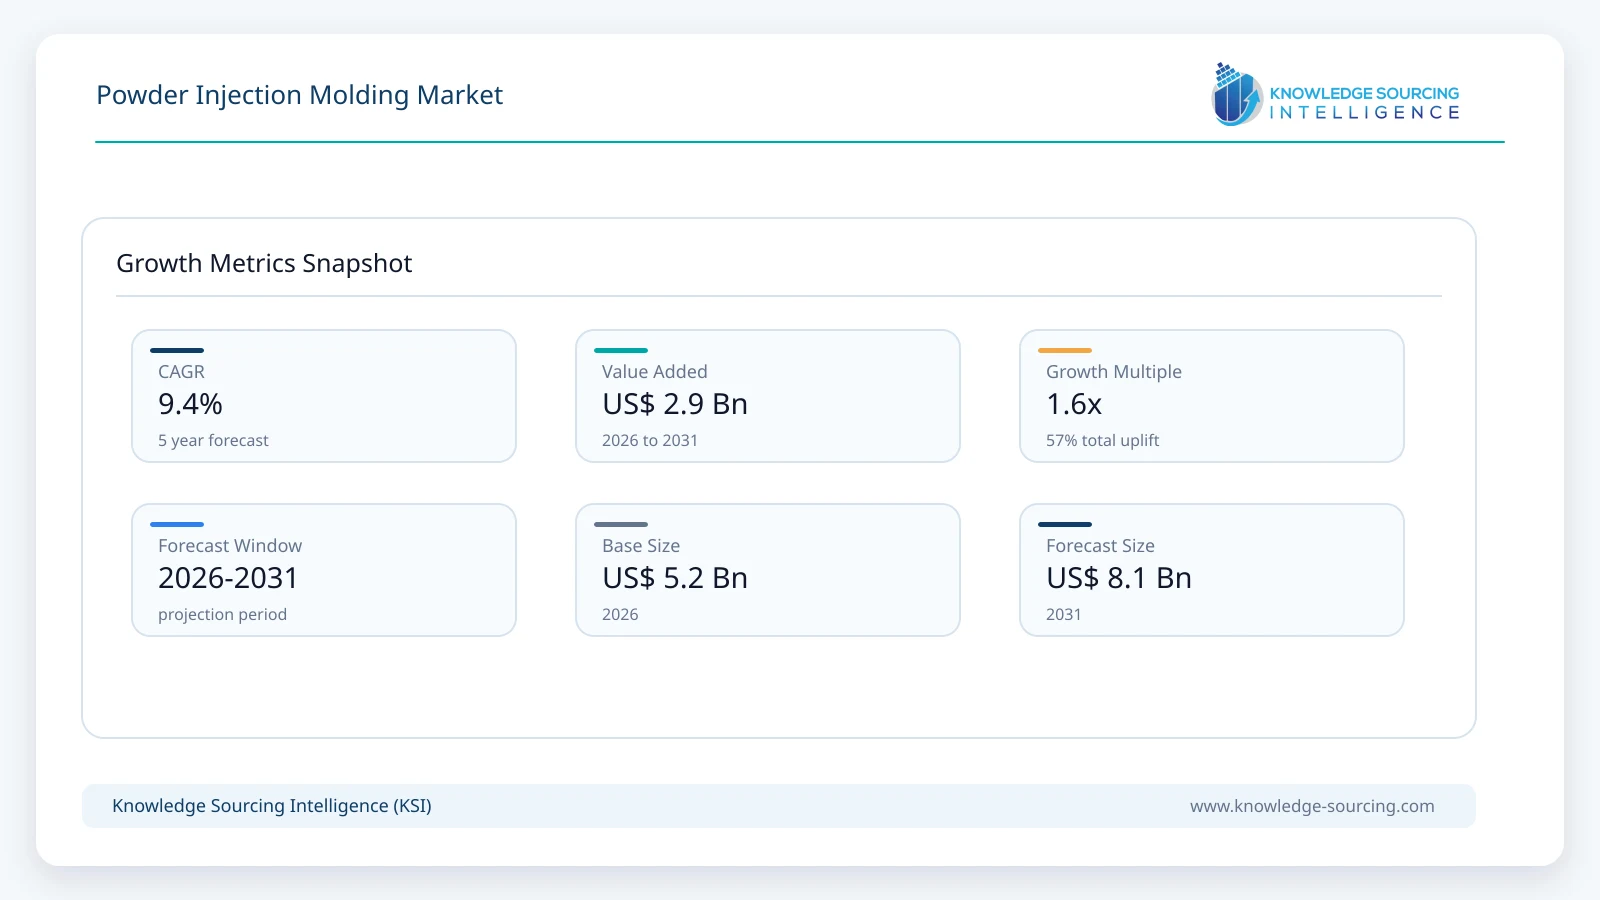
The global powder injection molding market is estimated at USD 5.15 billion in 2026 and is forecast to reach USD 8.08 billion in 2031, representing an implied CAGR of 9.4% during the period.
Key Highlights
• Metal injection molding accounts for approximately 78.0% of global powder injection molding revenue in 2026, equivalent to about USD 4.02 billion.
• Automotive applications represent approximately 31.0% of global 2026 revenue, or about USD 1.60 billion, reflecting high-volume use in precision mechanisms, powertrain, safety and thermal-management components.
• Electrical and electronics applications account for approximately 25.0% of 2026 revenue, supported by hinges, camera structures, connector parts, wearables and thermal-management components.
• Medical and dental applications are estimated at approximately USD 0.88 billion in 2026 and are expected to grow faster than the overall market as minimally invasive devices and complex surgical components expand.
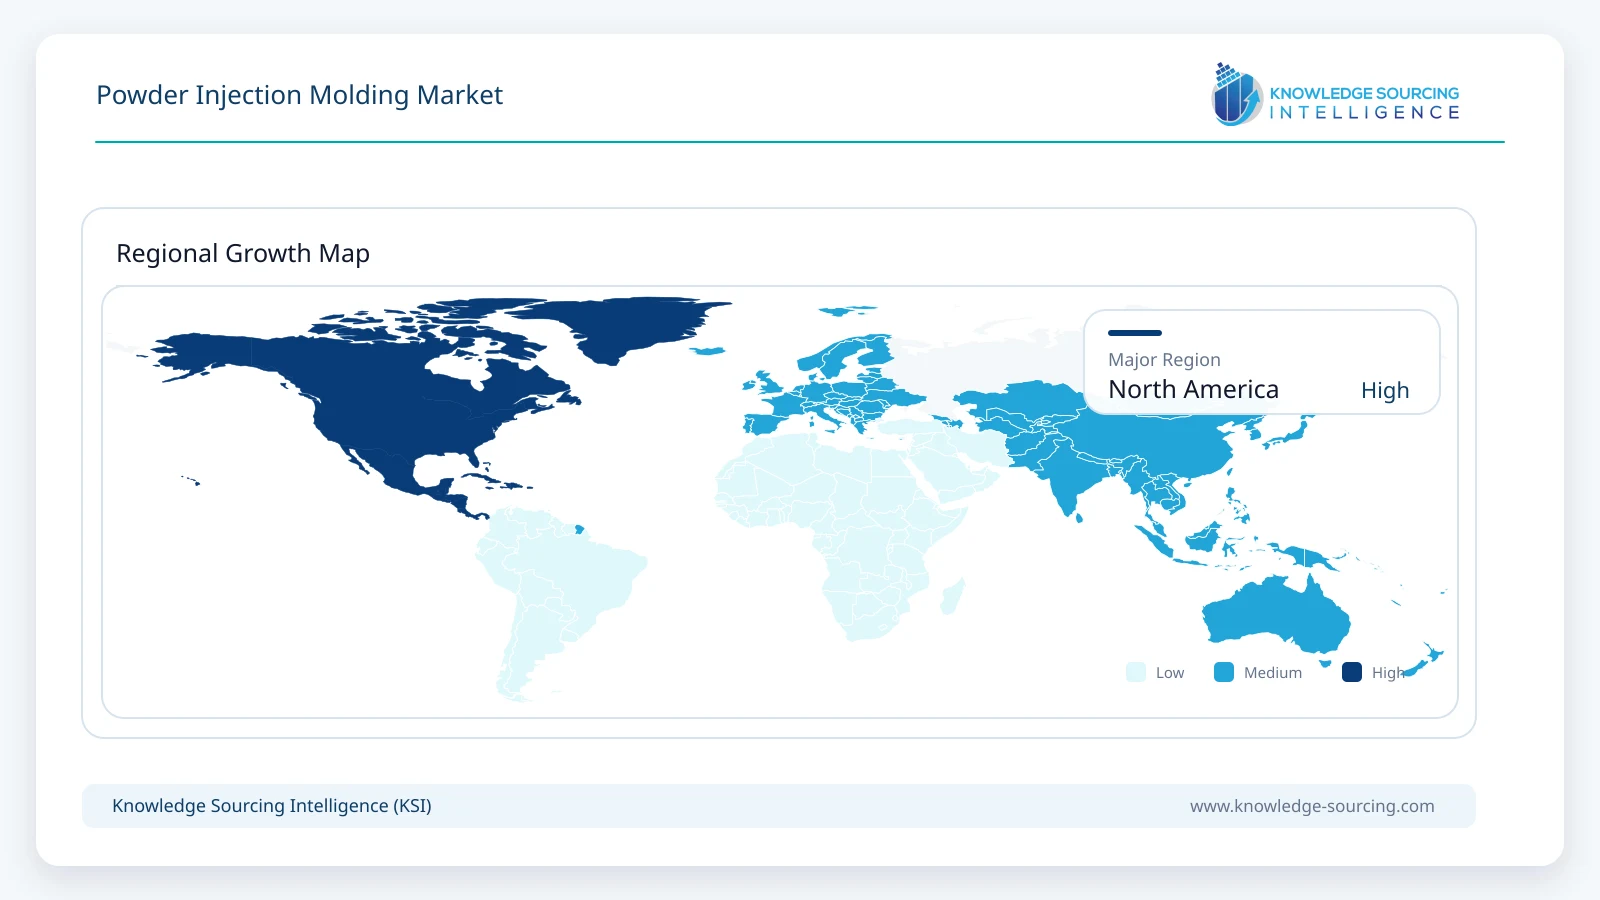
• Asia Pacific accounts for approximately 48.0% of global 2026 revenue, equivalent to about USD 2.47 billion, because of its concentration of consumer-electronics, automotive and precision-component manufacturing.
• Growth is increasingly supported by micro-MIM, copper and specialty-alloy parts, medical devices and regionalized production, while high tooling cost and long debinding/sintering cycles remain structural constraints.
Market Overview
Powder injection molding (PIM) combines fine metal or ceramic powder with a thermoplastic or wax-based binder to create an injectable feedstock. The feedstock is molded into a green part, debound to remove the binder and then sintered to near-full density. The market has two main commercial branches: metal injection molding (MIM) and ceramic injection molding (CIM). Both are used when customers require complex geometry, high production volumes and material properties that are difficult to achieve economically through machining or conventional casting.
The market estimate in this report is based on finished PIM parts and contract-manufacturing revenue rather than the entire ecosystem. Feedstock suppliers such as BASF, powder producers, injection-molding machine manufacturers and furnace suppliers are important to the industry but are not added to PIM component revenue. This distinction removes a major source of double counting and also means the competitive participant list is focused on companies that manufacture MIM or CIM parts at commercial scale.
The 2026 estimate is triangulated using public information on MIM company scale, component output, powder-industry shipment trends, regional manufacturing intensity, material consumption, end-market applications and pricing for precision parts. MPIF reported that North American MIM and metal additive-manufacturing powder shipments began to recover during 2025 and expected more meaningful growth in 2026, with demand strongest in medical and stainless-steel applications. Company disclosures also show expanding capacity in India and continued high-volume MIM production for electronics, automotive and medical devices.
The forecast is intentionally non-uniform. The modeled path is approximately USD 5.15 billion in 2026, USD 5.60 billion in 2027, USD 6.11 billion in 2028, USD 6.69 billion in 2029, USD 7.35 billion in 2030 and USD 8.08 billion in 2031. Growth accelerates modestly as inventory corrections in metal powders normalize, new MIM programs scale and medical, aerospace, optical-communication and electronics applications add higher-value parts.
PIM competes with CNC machining, investment casting, die casting, stamping and additive manufacturing. Its strongest economic position is in small to medium-sized components with complex three-dimensional features and annual volumes high enough to amortize tooling. BASF describes MIM as a near-net-shape process with roughly 95-98% material utilization, while GKN highlights thin walls, internal features and near-wrought mechanical properties. Those characteristics explain why PIM is most attractive when customers can redesign multiple machined features into a single molded part.
Powder Injection Molding Market Trends
Micro-PIM Expands Precision at Smaller Part Sizes
Micro-PIM is extending the process toward miniature medical, electronics and sensor components that would be difficult to machine economically. The commercial opportunity is not simply smaller parts; it is the ability to mold thin walls, micro-features and complex internal geometries in one repeatable process. Suppliers with advanced tooling, mold-flow simulation and tight sintering control can therefore differentiate beyond conventional high-volume MIM.
Copper and Thermal-Management Parts Gain Importance
Data-center optics, power electronics, electrification and compact electronic devices are creating demand for geometrically complex copper parts with high thermal and electrical conductivity. The 2026 MPIF awards included a pure-copper MIM heat-dissipation device for high-power optical modules, illustrating that MIM is moving beyond stainless steel and low-alloy steel into applications where thermal design is a primary requirement.
Medical Applications Shift Toward Complex Functional Assemblies
Medical MIM is evolving from simple brackets and instrument components toward articulation parts, robotic-surgery components, endoscopic tools and implant-related hardware. High material density, corrosion resistance and repeatability make MIM attractive where multiple machined components can be consolidated. ISO 13485 capability and validation discipline increasingly influence supplier selection.
Regionalization Changes Capacity Investment
Customers are seeking shorter and more resilient precision-component supply chains. OptiMIM has established a manufacturing site in Hyderabad, while INDO-MIM operates large capacity in India and the United States and expanded its Indian footprint with a Chennai facility. Regionalization does not eliminate Asia Pacific scale, but it increases demand for suppliers that can qualify the same process across multiple countries.
Additive Manufacturing Becomes a Development Complement
Metal additive manufacturing is increasingly used for prototypes and bridge production before programs move into high-volume MIM. Rather than replacing MIM across its core economics, binder-based and powder-bed processes often reduce development time and allow customers to validate geometry before committing to production tooling. Suppliers that operate both technologies can shorten the path from design iteration to serial production.
Segment Analysis
By Type - Metal Injection Molding
Metal injection molding is estimated at approximately USD 4.02 billion in 2026, representing about 78.0% of global PIM revenue. Stainless steels and low-alloy steels remain the largest material families, while titanium, copper, cobalt-chrome, nickel alloys and magnetic materials support higher-value applications. MIM dominates because automotive, electronics, medical and industrial customers consume a much larger volume of precision metal components than injection-molded technical ceramics.
Ceramic injection molding is estimated at approximately USD 1.13 billion in 2026. It is smaller but grows slightly faster because alumina and zirconia components are gaining use where electrical insulation, wear resistance, chemical stability or biocompatibility are more important than metallic conductivity.
By Application - Automotive
Automotive applications are estimated at approximately USD 1.60 billion in 2026, making them the largest application segment. MIM is used in turbocharger systems, locking and safety mechanisms, transmission and valvetrain parts, sensors and increasingly electrification-related components. The segment benefits from very high production volumes but remains sensitive to vehicle platforms, price pressure and changes in internal-combustion powertrain content.
Medical and dental applications are estimated at approximately USD 0.88 billion in 2026 and are the fastest-growing major application group. Growth is supported by minimally invasive surgery, robotic and articulated instruments, dental components and higher use of stainless steel, cobalt-chrome and titanium in complex geometries.
By Application - Electrical and Electronics
Electrical and electronics applications are estimated at approximately USD 1.29 billion in 2026. Asia-based MIM suppliers produce high volumes of hinges, connector interfaces, camera and wearable-device structures, shielding and thermal-management parts. Product cycles are shorter than in medical or automotive markets, making tooling speed and rapid scale-up important competitive factors.
By Geography - Asia Pacific
Asia Pacific is estimated at approximately USD 2.47 billion in 2026. China remains a major center for consumer-electronics and precision MIM production, while India is expanding rapidly through INDO-MIM and new capacity from other suppliers. Japan, South Korea, Singapore and Southeast Asia contribute advanced materials, electronics and medical manufacturing. North America remains strong in medical, defense and specialist MIM, while Europe retains deep expertise in automotive, industrial and high-precision applications.
Market Drivers
Miniaturization and Component Consolidation
MIM and CIM can integrate undercuts, holes, threads, thin walls and other features into one molded component. This can replace multiple machined or assembled pieces, lowering part count and production labor in high-volume programs.
Medical and Minimally Invasive Devices
Surgical instruments, robotic devices and dental components require small geometries, corrosion resistance and repeatable dimensional control. These requirements align closely with MIM economics and quality systems.
Consumer Electronics and Wearables
High-volume electronics programs require compact metal structural parts with cosmetic finish and tight tolerances. MIM is established in hinges, camera structures, connectors and wearable-device components, particularly in Asia.
Material Efficiency and Sustainability
Near-net-shape processing substantially reduces machining scrap. BASF cites 95-98% material utilization for MIM, which becomes increasingly valuable when components use stainless steel, titanium, cobalt-chrome, copper or other higher-cost alloys.
Regional Supply-Chain Investment
Manufacturers are adding capacity closer to customers to reduce logistics risk and support local qualification. New facilities and joint ventures in India demonstrate this shift while preserving access to large pools of skilled precision-manufacturing labor.
Market Restraints
High Tooling Cost
Precision molds, fixtures and sintering setters create a meaningful up-front investment. PIM is therefore less attractive for low-volume programs unless suppliers use bridge tooling or additive-manufacturing prototypes to reduce development risk.
Debinding and Sintering Cycle Time
Molded green parts require controlled binder removal and high-temperature sintering. These stages add lead time, energy use and capacity constraints compared with conventional plastic injection molding.
Shrinkage and Dimensional Control
MIM parts typically shrink materially during sintering. GKN notes approximately 16-18% shrinkage in its process, which must be predicted and controlled through tooling, feedstock consistency, furnace conditions and part support.
Powder and Alloy Cost
Fine metal and ceramic powders can be expensive and sensitive to supply conditions. Titanium, nickel alloys, cobalt-chrome and high-purity copper raise material cost, while powder morphology and particle-size requirements limit sourcing flexibility.
Competition from Machining, Casting and Additive Manufacturing
PIM does not win every geometry or volume. CNC machining remains competitive for lower quantities, die casting can be more economical for larger parts, and additive manufacturing continues to improve for complex low-volume metal components.
Competitive Environment
The PIM market combines large global MIM manufacturers with specialist regional suppliers and ceramic component companies. INDO-MIM has one of the industry’s largest installed MIM capacities and a vertically integrated model spanning feedstock, tooling, molding, finishing and assembly. GKN Powder Metallurgy combines MIM with broader powder and materials expertise, while OptiMIM, ARC Group Worldwide, Advanced Powder Products, Parmatech and Smith Metal Products serve precision programs across medical, industrial, defense and consumer markets.
Asia Pacific has a particularly deep supplier base for consumer electronics and high-volume MIM. Hangzhou Sino-MIM and Jiangsu Gian Technology participate in complex electronics and automotive components, while Singapore-based Advanced Materials Technologies combines MIM, CIM and related processing. Europe remains differentiated in specialized materials, micro-MIM and industrial engineering through companies such as Schunk, Sintex and Parmaco.
Competitive advantage depends on more than molding capacity. Feedstock development, tool design, shrinkage control, furnace consistency, secondary machining, heat treatment, surface finishing, metrology and customer qualification all affect delivered economics. Suppliers able to move from prototype to high-volume production while keeping these operations in-house can shorten lead times and reduce the risk of tolerance drift between process stages.
Recent Developments
June 2026: The Metal Powder Industries Federation reported early recovery in MIM demand, with medical and stainless-steel applications showing particular resilience and industry participants expecting stronger growth as inventory corrections normalize.
June 2026: INDO-MIM received MIM Design Excellence Grand Prizes for a complex rifle housing and a multi-part vessel-sealing device, demonstrating high-density stainless-steel MIM in both defense and advanced medical applications.
June 2026: Hangzhou Sino-MIM received an MPIF MIM Grand Prize for a pure-copper heat-dissipation device used in high-power optical modules, highlighting expanding MIM use in thermal management and optical communications.
June 2026: ARC Group Worldwide received an MPIF Award of Distinction for a MIM hinge upper cam used in a damping mechanism, reinforcing continued commercial use in high-volume hardware applications.
2026: OptiMIM Global operates a new MIM manufacturing facility in Hyderabad, India, with tooling, molding, debinding, sintering, machining and assembly capabilities for automotive, medical, electronics, industrial and aerospace customers.
2025-2026: INDO-MIM expanded its geographic and medical capabilities after acquiring PDV Medtec in the United States in 2025 and continued to broaden production and qualification across India and North America.
Market Outlook
The powder injection molding market is expected to expand steadily through 2031 as designers move more complex metal and ceramic components into high-volume near-net-shape manufacturing. MIM will remain the dominant process, but CIM should gain share in medical, electronics, energy and other applications that require insulation, wear resistance or chemical stability.
Automotive remains the largest revenue pool, but the mix of growth is shifting toward medical devices, electronics, optical communications, defense and aerospace. The transition does not eliminate automotive demand; it reduces the market’s dependence on conventional engine-related parts and increases the importance of precision components tied to electrification, sensing and thermal management.
The most competitive suppliers will combine material and feedstock expertise with advanced tooling, strong debinding and sintering control, secondary operations and multi-region capacity. Additive manufacturing will increasingly support prototyping and bridge production, while MIM and CIM retain the cost advantage for qualified high-volume programs with complex geometry.
Global Powder Injection Molding Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.15 billion |
| Total Market Size in 2031 | USD 8.08 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | TYPE, APPLICATION, GEOGRAPHY |
| Companies |
|
Market Segmentation
By Type
Metal Injection Molding (MIM)
Ceramic Injection Molding (CIM)
By Application
Automotive
Electrical and Electronics
Medical and Dental
Aerospace and Defense
Industrial and Consumer Products
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Miniaturization and Component Consolidation
4.1.2. Medical and Minimally Invasive Devices
4.1.3. Consumer Electronics and Wearables
4.1.4. Material Efficiency and Sustainability
4.1.5. Regional Supply-Chain Investment
4.2. Market Restraints
4.2.1. High Tooling Cost
4.2.2. Debinding and Sintering Cycle Time
4.2.3. Shrinkage and Dimensional Control
4.2.4. Powder and Alloy Cost
4.2.5. Competition from Machining, Casting and Additive Manufacturing
5. POWDER INJECTION MOLDING MARKET BY TYPE
5.1. Metal Injection Molding (MIM)
5.2. Ceramic Injection Molding (CIM)
6. POWDER INJECTION MOLDING MARKET BY APPLICATION
6.1. Automotive
6.2. Electrical and Electronics
6.3. Medical and Dental
6.4. Aerospace and Defense
6.5. Industrial and Consumer Products
6.6. Others
7. POWDER INJECTION MOLDING MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. United Kingdom
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. Japan
7.5.3. India
7.5.4. South Korea
7.5.5. Southeast Asia
7.5.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. MIM and CIM Capability Positioning
8.3. Materials, Tooling and Sintering Capabilities
8.4. Regional Manufacturing Footprint
8.5. Recent Developments
8.6. Competitive Dashboard
9. COMPANY PROFILES
9.1. INDO-MIM
9.2. GKN Powder Metallurgy
9.3. OptiMIM
9.4. ARC Group Worldwide
9.5. Advanced Powder Products, Inc.
9.6. Smith Metal Products
9.7. Schunk Sintermetalltechnik GmbH
9.8. Sintex a/s
9.9. Parmaco Metal Injection Molding AG
9.10. Morgan Technical Ceramics
9.11. Hangzhou Sino-MIM Technology Co., Ltd.
9.12. Jiangsu Gian Technology Co., Ltd.
9.13. Advanced Materials Technologies Pte Ltd
9.14. Parmatech Corporation
9.15. NPI
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Abbreviations
Navigate
Trusted by the world's leading organizations











