
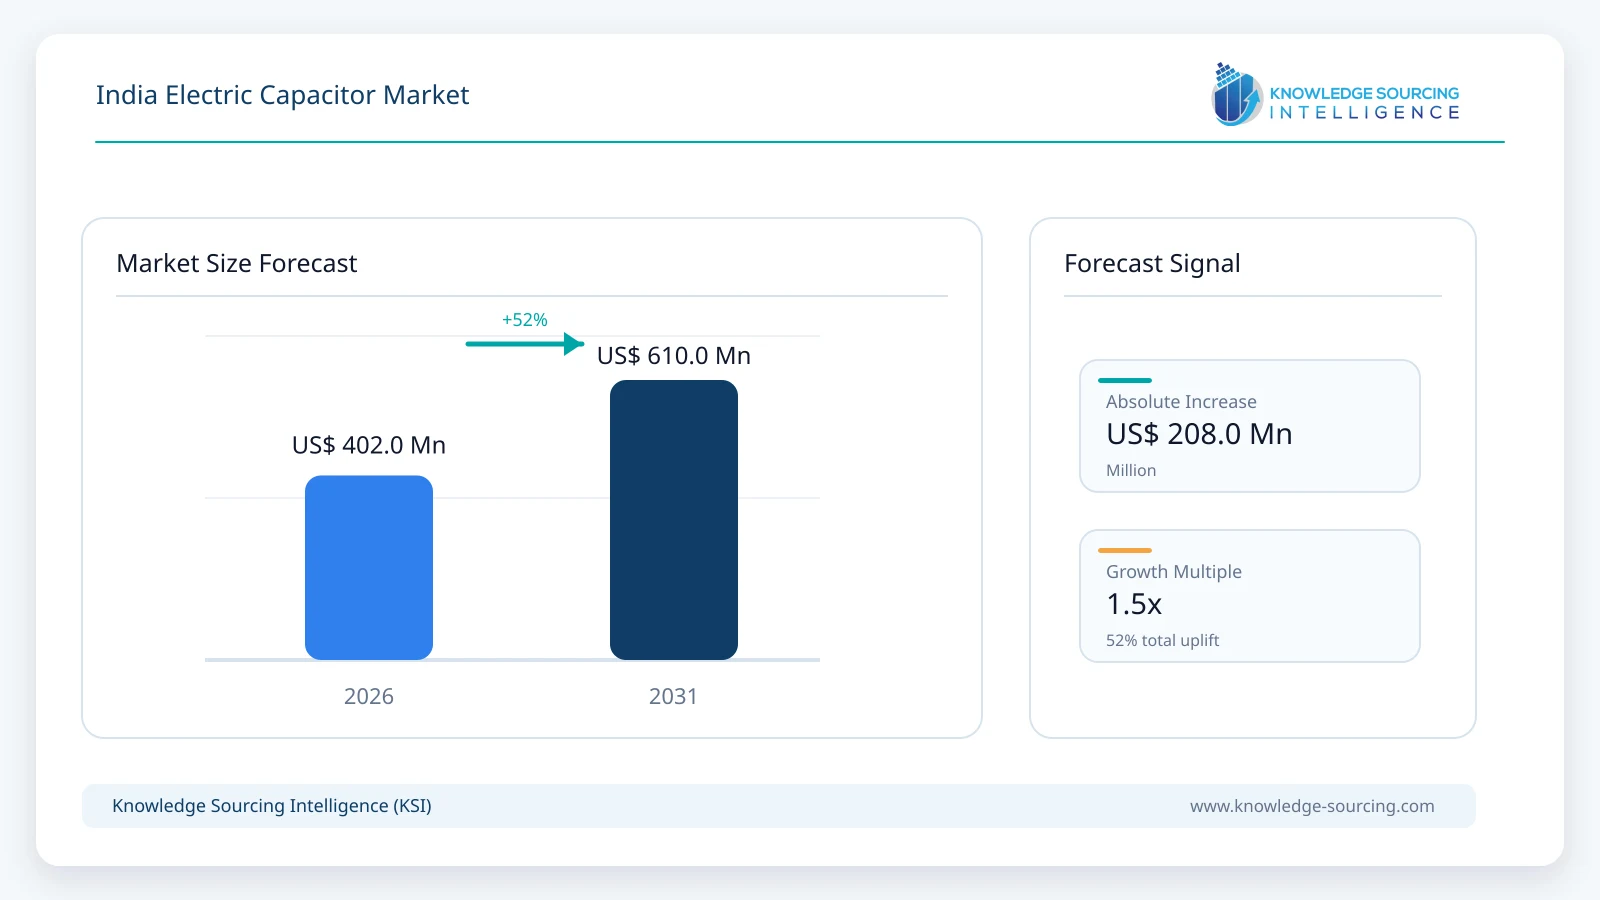
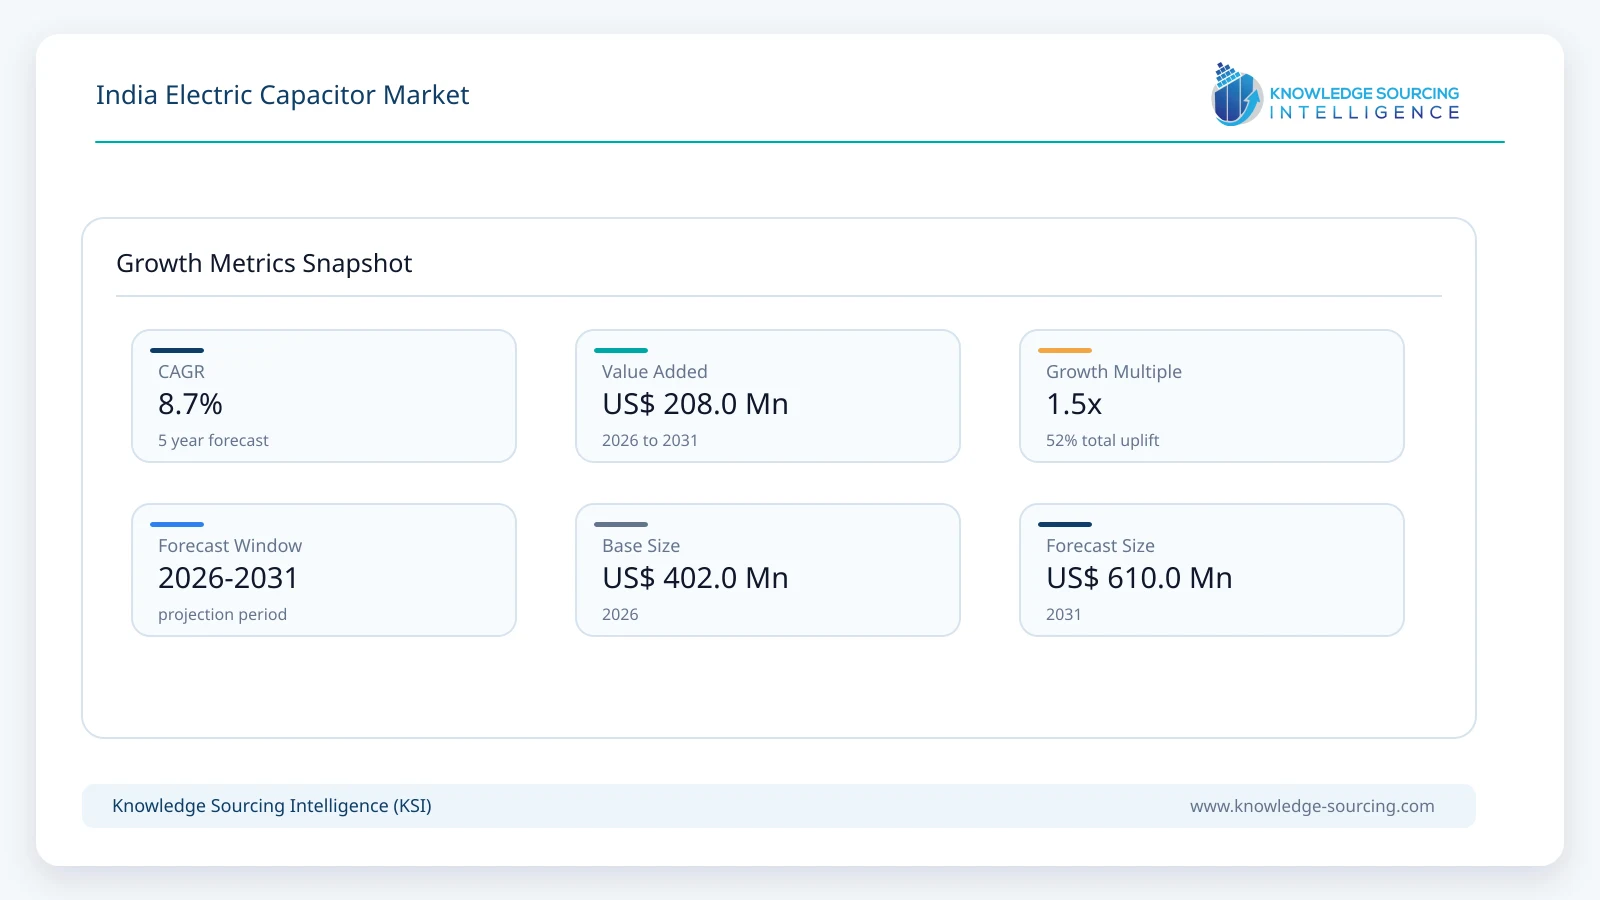
The India Electric Capacitor Market is forecast to grow at a CAGR of 8.7%, reaching USD 610.0 million in 2031 from USD 402.0 million in 2026.
Highlights:
- 1The India electric capacitor market is forecast to expand at a CAGR of 8.70%, driven by electronics and electrification demand.
- 2ICT and consumer electronics form the largest application segment, with capacitors essential in mobiles, appliances, IT hardware, and telecom as domestic production reaches Rs 13.11 lakh crore.
- 3Supercapacitors are projected to grow considerably among types (aluminum, ceramic, tantalum, paper/film, others), supported by EV regenerative braking, renewable storage, and high-power industrial uses.
- 4Rising EV adoption under PM E-DRIVE fuels demand for advanced capacitors in powertrains, inverters, BMS, and chargers, with millions of two- and three-wheelers already incentivized.
- 5Renewable energy expansion (295.55 GW capacity) and power-infrastructure growth drive capacitor needs in solar/wind inverters, grid stabilization, and energy-storage systems nationwide.
- 6Maharashtra is expected to lead regional expansion, backed by strong FDI, industrial base, EV/electronics policies, and planned capacity additions from 36 GW to 81 GW by 2030.
Market Trends:
Rising demand for electronic and electrical systems, supported by the rapid expansion of domestic electronics manufacturing, automotive electrification, telecommunications, IT hardware, and industrial equipment, is strengthening the requirement for capacitors across India. Capacitors are essential passive components used for energy storage, filtering, voltage stabilization, power conversion, signal conditioning, and noise suppression in electronic and electrical systems. Government support for domestic component manufacturing is also becoming an important market driver. In March 2025, the Government of India approved the Electronics Components Manufacturing Scheme (ECMS) with an outlay of ?22,919 crore to develop a stronger domestic electronics component ecosystem, with non-SMD passive components and SMD passive components included among the targeted segments.
The demand outlook is further supported by the rapid expansion of India's electronics manufacturing base. According to the Government of India, electronics production increased from approximately Rs 1.9 lakh crore in FY 2014–15 to Rs 13.11 lakh crore in FY 2025–26, while electronics exports reached Rs 4.24 lakh crore in FY 2025–26. Electronics production also increased 15.8% year-on-year from Rs 11.32 lakh crore in FY 2024–25, highlighting the continued expansion of domestic manufacturing capacity. This broader manufacturing expansion supports demand for passive components, including capacitors, across mobile devices, IT hardware, telecom equipment, consumer electronics, automotive systems, and industrial electronics.
Government initiatives are also moving beyond finished-product assembly toward localized component and material production. In March 2026, the Ministry of Electronics and Information Technology approved additional ECMS projects covering non-SMD and SMD passive capacitors, while a separate project was approved for metallized film used in capacitor manufacturing. These approvals directly strengthen domestic capacitor and capacitor-material capabilities and are intended to reduce dependence on imported components. By August 2026, 106 ECMS applications covering 30 products across 15 states had been approved, representing expected investment of Rs 69,548 crore, projected production of RS 5,34,101 crore, and approximately 74,628 direct jobs.
Automotive electrification represents another important source of component demand. The Government's PM E-DRIVE dashboard recorded more than 49 lakh electric two-wheelers and over 2.8 lakh electric three-wheelers across the programme's cumulative sales data by September 2026. Electrified vehicles require increasingly sophisticated power-electronic architectures, battery-management systems, charging systems, inverters, and control electronics, where capacitors are used for filtering, energy buffering, voltage stabilization, and power conversion. The expansion of EV manufacturing and supporting infrastructure therefore broadens the application base for capacitors beyond conventional consumer electronics.
India's semiconductor and advanced electronics initiatives are also creating additional opportunities for passive components. In April 2026, the Government reported that 249 applications had been received under ECMS for components, base materials, and capital equipment, including PCBs, capacitors, and laminates. The Government has also approved semiconductor projects with investment commitments of about Rs1.6 lakh crore, supporting the development of a broader semiconductor-to-system manufacturing ecosystem. Together, these initiatives are encouraging greater localization of electronic components and strengthening demand for capacitors across telecommunications, consumer electronics, automotive, industrial, strategic, and IT hardware applications.
The Indian electric capacitor market therefore encompasses a diverse range of products serving power electronics, consumer devices, telecommunications equipment, automotive systems, renewable-energy equipment, industrial machinery, and electrical infrastructure. Policy emphasis is increasingly shifting from assembling finished electronics toward manufacturing components, materials, and supporting equipment domestically. The ECMS, electronics manufacturing expansion, semiconductor investments, and growing EV ecosystem are consequently strengthening the domestic supply chain for capacitors while creating opportunities for manufacturers to expand production, introduce higher-value products, and integrate more deeply into India's electronics and electrical manufacturing ecosystem.
List of Top India Electric Capacitor Companies:
Some of the major companies include Murata Manufacturing Co., Ltd., Walsin Technologies Corporation, and Panasonic Corporation.
Murata Manufacturing Co., Ltd. offers ceramic capacitors product type GRM with applications in consumer equipment, industrial equipment, automotive infotainment, and medical equipment
Walsin Technologies Corporation offers Multilayer Ceramic Chip Capacitors for the application of smartphones, networking devices, automotive electronics, etc.
Panasonic Corporation offers Conductive Polymer Aluminum Electrolytic Capacitors (SP-Cap), with different types, rated voltage, capacitance, and equivalent series resistance.
Market Drivers:
Increased demand for consumer electronics
One of the key factors supporting the growth of the Indian electric capacitor market is the rapid expansion of electronics manufacturing and domestic consumption of electronic products across the country. Government data indicates that India’s electronics production increased from approximately Rs 1.9 lakh crore in FY2014-15 to Rs 13.11 lakh crore in FY2025-26, representing nearly a seven-fold increase. Electronics exports also reached approximately Rs 4.24 lakh crore in FY2025-26, while electronics production increased 15.8% year-on-year during the same period. This expansion across mobile phones, consumer electronics, industrial electronics, telecommunications, automotive electronics, and other equipment is creating broader requirements for capacitors used in power management, filtering, energy storage, and circuit stabilization.
Changing consumption patterns, rising digital connectivity, domestic manufacturing initiatives, and increasing localization of electronics supply chains are further strengthening the underlying demand environment. India produced approximately Rs 6.27 lakh crore worth of mobile phones in FY2025-26, while mobile phone exports reached around Rs 2.59 lakh crore. The Government reported that approximately 99.2% of mobile phones used in India are now manufactured domestically, highlighting the substantial expansion of the local electronics production base. In July 2026, the Government also approved the Rs 62,500 crore Mobile Phone Manufacturing Scheme, designed to increase production scale, deepen domestic value addition, strengthen component supply chains, and support manufacturing from FY2026-27 through FY2030-31. These developments are expected to support demand for electronic components, including capacitors, across mobile and associated manufacturing ecosystems.
The expansion of semiconductor and advanced electronics manufacturing is providing an additional structural demand driver. Under the Semicon India Programme, the Government had approved 12 semiconductor projects with a total committed investment of approximately Rs 1.64 lakh crore by 2026, covering semiconductor fabrication, advanced packaging, assembly, testing, and related manufacturing activities. In July 2026, the Government additionally approved Semicon 2.0 with an outlay of Rs 1,27,500 crore, targeting semiconductor design, fabrication, advanced packaging, machinery, materials, and talent development. As capacitors are used throughout electronic power-management and signal-conditioning circuits, the development of these domestic manufacturing capabilities is broadening the potential component requirement across industrial, consumer, automotive, telecommunications, and strategic electronics applications.
Growing renewable-energy deployment is another important factor influencing capacitor demand in India, particularly through solar inverters, power-conversion equipment, grid-connected systems, and energy-storage applications. The Ministry of New and Renewable Energy reported 295.55 GW of cumulative renewable-energy capacity as of August 31, 2026, including approximately 168.04 GW of solar capacity and 58.52 GW of wind capacity. In addition, the PM Surya Ghar: Muft Bijli Yojana had installed approximately 39.72 lakh rooftop solar systems benefiting 48.03 lakh households by July 22, 2026, while the programme recorded more than 50 lakh beneficiary households by August 2026. The continued deployment of solar generation and distributed power systems is increasing the requirement for reliable power-electronic components, including capacitors used for DC-link, filtering, voltage stabilization, and energy-management functions.
Government efforts to strengthen domestic component manufacturing are also becoming increasingly relevant. The Electronics Components Manufacturing Scheme (ECMS) had approved 106 projects by August 2026, with projected investment of Rs 69,548 crore, while the programme includes initiatives covering critical electronic components and raw materials. Such policies are intended to strengthen local supply chains and reduce dependence on imported components. Together with expanding electronics production, semiconductor manufacturing, mobile-device production, renewable-energy installations, and industrial electrification, these developments are creating a broader and increasingly diversified demand base for electric capacitors across India’s electronics and electrical equipment ecosystem.
Rising popularity of electric vehicles
The increasing adoption of electric vehicles (EVs) is strengthening the requirement for reliable power-electronic components, including electric capacitors used for energy storage, voltage stabilization, filtering, power conversion, and smoothing within vehicle electrical and electronic systems. Capacitors support the efficient operation of inverters, DC-link circuits, onboard chargers, regenerative-braking systems, and other power-management applications that are important to electric mobility. As EV architectures become more sophisticated and incorporate higher-power propulsion and charging systems, component requirements increasingly emphasize electrical performance, thermal stability, compact design, reliability, and longer operating life. India therefore represents an important opportunity for electric capacitor manufacturers as vehicle electrification expands across two-wheelers, three-wheelers, passenger vehicles, buses, and commercial vehicles.
Government support is continuing to accelerate India's transition toward electric mobility. The Ministry of Heavy Industries' PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE) Scheme, notified in September 2024, was introduced with an overall outlay of Rs 10,900 crore and subsequently extended in August 2025 until March 31, 2028. The programme supports electric two-wheelers, three-wheelers, ambulances, trucks, and other eligible vehicle categories while also supporting charging infrastructure and domestic manufacturing capabilities. As of March 12, 2026, the Ministry reported that 18,01,307 electric vehicles had been incentivized under PM E-DRIVE since its implementation, demonstrating the scale of government-supported EV deployment in India.
The momentum has continued into 2026. The official PM E-DRIVE dashboard recorded 10,48,304 registered and temporarily registered electric vehicles during financial year 2026–27 as of October 6, 2026, including 9,60,342 registered electric two-wheelers and 5,646 registered or temporarily registered electric three-wheelers in the scheme's reported categories. The programme's model-approval database also shows continued introduction and approval of new electric vehicle models during 2026, including electric two-wheelers, three-wheelers, and trucks. This expanding vehicle base creates additional requirements for capacitors used throughout EV power-conversion and electrical-control systems.
Beyond direct vehicle incentives, the government's continued emphasis on domestic EV manufacturing and charging infrastructure is broadening the addressable application base for capacitor technologies. The PM E-DRIVE framework incorporates a phased manufacturing approach, while the growing deployment of electric mobility across personal, shared, commercial, and public transportation is increasing the need for dependable power-electronic components. Consequently, capacitor demand is increasingly connected not only with vehicle production but also with charging equipment, power-management systems, and supporting electrification infrastructure. The expansion of EV adoption across multiple vehicle categories and the continued introduction of new government-approved models provide a sustained foundation for electric capacitor applications in India's automotive and broader power-electronics ecosystem.
Growing electricity consumption
Power infrastructure remains fundamental to India’s economic development, industrial activity, urbanization, and digital transformation. Reliable and adequate electricity infrastructure is essential for supporting manufacturing, transportation, data centres, telecommunications, commercial facilities, and residential consumption. India’s power generation portfolio continues to combine conventional sources, including coal, lignite, natural gas, hydro and nuclear power, with rapidly expanding renewable sources such as solar, wind, biomass, small hydro, and waste-to-energy. The diversification of generation capacity is also accompanied by investments in transmission, energy storage, and grid flexibility to accommodate increasing renewable penetration.
India’s electricity system has expanded substantially in recent years as demand from industry, infrastructure, urban centres, and electrification continues to increase. According to the Central Electricity Authority, electricity generation reached approximately 1,824.2 billion kWh (1,824.2 BU) in 2024–25, compared with 1,624.2 BU in 2022–23. Coal and lignite accounted for approximately 1,331.9 billion kWh, while renewable energy sources contributed about 255.0 billion kWh, alongside hydro and nuclear generation. India also reached a record 241 GW peak power demand on June 9, 2025, without a peak shortage, while approximately 34 GW of generation capacity was added during FY2024–25, including 29.5 GW from renewable sources.
The scale and composition of India’s power infrastructure are also changing rapidly. Total installed generation capacity exceeded 500 GW in September 2025, reaching 500.89 GW, with non-fossil sources accounting for more than 51% of the capacity. By December 31, 2025, total installed capacity had reached 513.73 GW, including 266.79 GW of non-fossil capacity. As of August 31, 2026, MNRE reported approximately 295.55 GW of renewable energy capacity, including 168.04 GW of solar and 58.52 GW of wind capacity, further demonstrating the rapid expansion of India’s electricity infrastructure.
Electric capacitors support this expanding electricity infrastructure by performing functions such as power-factor correction, voltage stabilization, filtering, energy storage, power conditioning, and reduction of electrical disturbances. Their applications extend across generation facilities, substations, transmission and distribution networks, industrial equipment, renewable-energy installations, and electrical control systems. The increasing integration of variable solar and wind generation also places greater emphasis on grid stability, reactive-power management, and energy-storage technologies. The Ministry of Power has, for example, approved a 30 GWh battery energy storage system (BESS) viability-gap-funding scheme and reported pumped-storage projects under development to improve renewable-energy integration and grid flexibility. Consequently, continued expansion of generation capacity, renewable integration, transmission infrastructure, and electricity demand is expected to support requirements for capacitors across India’s power ecosystem.
Segment Analysis:
ICT and consumer electronics
Electric capacitors are widely used in laptops, air conditioners, refrigerators, washing machines, etc. Thus, with the growing demand for electronic products, demand for electric capacitors is also projected to increase during the next five years. IT hardware and consumer durables are the major application areas for electric capacitors, and the high growth rate across these industries is projected to further drive the electric capacitors market in India during the forecast period.
Furthermore, the rising trend in the adoption of hybrid capacitors and polymers is also anticipated to continue propelling the market growth. Some of the leading players operating in the market are KEMET Corporation, Yageo Corporation, Panasonic Corporation, Murata Manufacturing Co., Ltd., Capxon International Electronic Co., Ltd., and Walsin Technology Corporation.
Supercapacitors are expected to grow considerably
Based on type, the Indian electric capacitor market is segmented into aluminum, ceramic, tantalum, paper and film, supercapacitors, and others. Within this landscape, supercapacitors are gaining relevance from India’s accelerating electrification, renewable-energy expansion, electric mobility, and demand for high-power, rapid-charge energy-storage technologies. Unlike conventional batteries, supercapacitors can deliver and absorb power rapidly, making them particularly relevant for applications requiring frequent charge-discharge cycles, regenerative braking, voltage support, and short-duration power delivery. The Government of India’s continued expansion of renewable and non-fossil generation is strengthening the broader requirement for advanced electrical-energy management technologies. India had 300.50 GW of non-fossil-fuel installed capacity as of July 31, 2026, representing more than 54% of total installed generation capacity and more than 60% of the government’s 500 GW non-fossil capacity target for 2030.
The growth of renewable generation is also increasing the importance of energy-storage and power-management solutions. According to the Ministry of New and Renewable Energy, India’s total renewable-energy capacity reached 295.55 GW as of August 31, 2026, including 168.04 GW of solar, 58.52 GW of wind, and 52.06 GW of large hydro capacity. Solar capacity alone increased by more than 17.7 GW during April–August 2026. The Ministry of Power has also reported that the Central Electricity Authority estimates India will require 60.63 GW of energy-storage capacity by 2029–30, comprising 18.98 GW from pumped-storage projects and 41.65 GW from battery-energy-storage systems. This requirement reinforces the wider need for technologies that can support rapid power balancing, although large-scale storage deployment is currently being driven primarily by BESS and pumped storage rather than supercapacitors.
Supercapacitors are therefore positioned more strongly in high-power and short-duration applications where rapid charging and discharging provide a technical advantage. The Department of Science and Technology has highlighted their high power density, rapid charging capability, long cycle life, and suitability for transportation and renewable-energy applications. Government-supported research is also advancing the technology: ARCI researchers developed a porous-graphene-based supercapacitor operating at 3.4 V, with reported power density of up to 17,000 W/kg, 33% higher energy storage than a conventional commercial electrode, and 96% performance retention after 15,000 charge-discharge cycles. Such developments can improve the suitability of supercapacitors for electric vehicles, solar systems, industrial equipment, and other applications requiring high-power bursts.
Electric mobility and railway electrification provide additional application opportunities. Indian Railways reported that approximately 99.6% of its broad-gauge network was electrified by July 2026, while more than 1,260 MW of solar and wind capacity had been commissioned to support lower-carbon railway operations. Supercapacitors can complement electrified transport systems by absorbing and releasing power rapidly, particularly in regenerative-braking and peak-power applications. Government-supported research has previously demonstrated indigenous supercapacitor technologies for EV regenerative braking, while more recent DST research continues to target higher-voltage and higher-energy devices for electric-mobility applications.
Furthermore, domestic technology development is creating additional momentum for the Indian supercapacitor segment. In October 2025, the Technology Development Board under the Department of Science and Technology sanctioned financial assistance to Westech Power Management for an indigenous mobile high-power containerized supercapacitor energy-storage system targeted at industrial and defence applications. The project is designed around rapid charging and discharging and aims to support pulse power, grid stabilization, industrial automation, and field-deployable defence operations. These government-backed initiatives, combined with continuing research into advanced electrode materials, higher operating voltages, and longer cycle life, indicate expanding opportunities for supercapacitors in specialized high-power applications across India.
Maharashtra is expected to lead the market expansion
By state, the Indian electric capacitor market is segmented into Maharashtra, Tamil Nadu, Uttar Pradesh, Delhi (NCR), Telangana, and others. Maharashtra remains an important manufacturing and investment hub for the expansion of India’s electric capacitor market, supported by its large industrial base, electronics and automotive ecosystem, power infrastructure, and increasingly supportive investment policies. The Maharashtra Industries, Investment & Services Policy 2025, effective for the 2026–2030 period, further strengthens the state’s focus on industrial investment, manufacturing, infrastructure, and technology-oriented industries.
The state's investment position provides an important foundation for demand across electrical and electronic components. According to the latest Department for Promotion of Industry and Internal Trade (DPIIT) state-wise FDI data, Maharashtra received US$107.09 billion in cumulative FDI equity inflows from October 2019 through March 2026, compared with US$70.59 billion for Karnataka and US$50.63 billion for Gujarat. This represents a substantial increase from the previously available October 2019–June 2024 figure and confirms the continuing importance of Maharashtra as an investment destination.
Maharashtra's extensive electricity infrastructure provides another important demand driver for electric capacitors used in power-quality management, power electronics, voltage regulation, filtering, and power-factor correction. The state's energy-transition plan targets an increase in existing generating capacity from 36 GW to 81 GW by 2030, representing approximately 45 GW of additional capacity, with renewable energy's contribution to the energy portfolio targeted to rise from 14% to 53%. The plan involves generation, transmission, and distribution and is backed by a proposed investment of approximately Rs 3.3 lakh crore. The Central Electricity Authority continues to publish monthly state-level installed-capacity data, including reports through June 2026, reflecting the continuing expansion and modernization of India's electricity infrastructure.
Renewable-energy development further strengthens the requirement for capacitors and associated power-electronics equipment. According to the Maharashtra Energy Development Agency, the state had 15,367.289 MW of renewable-energy capacity installed by June 30, 2025, including 6,639.716 MW of solar, 5,350.91 MW of wind, 2,732.80 MW of bagasse-based cogeneration, and other renewable sources. The state also reported 10,136.086 MW of commissioned solar capacity when grid-connected projects and rooftop solar were combined. Maharashtra has subsequently introduced its Renewable Energy & Energy Storage Policy 2025–26 to 2035–36, creating an additional policy framework for renewable generation and energy-storage deployment.
Electronics, automotive, and electric-mobility manufacturing provide additional avenues for capacitor demand. Maharashtra's official industrial-policy framework identifies electronics, automobiles, EVs, pharmaceuticals, chemicals, and emerging technologies among its major industrial sectors. Its electronics policy supports electronics-product manufacturing and the development of R&D, design, engineering, and innovation capabilities, while the state has also introduced an updated Electric Vehicle Policy 2025 focused on EV adoption, charging infrastructure, power electronics, EV supply equipment, and battery-related technologies. These applications require capacitors across vehicle electronics, charging systems, power-conversion equipment, control systems, and energy-storage interfaces.
Government initiatives therefore provide a broader foundation for Maharashtra's electric capacitor demand. The state's 2025 industrial policy, renewable-energy and energy-storage framework, EV policy, and continuing electronics-manufacturing initiatives collectively support investment in electrical, electronic, mobility, and clean-energy infrastructure. Given the state's strong FDI position, industrial concentration, expanding renewable capacity, and planned power-system investment, Maharashtra is well positioned to remain one of the key state-level demand centers for electric capacitors in India, although state-level capacitor market leadership should be determined through verified manufacturer, production, shipment, and end-use data rather than inferred solely from broader industrial indicators.
Key Developments:
September 2026: Murata Manufacturing Co., Ltd. announced its participation in electronica India 2026 in Bengaluru under “Scaling the Future from India,” highlighting advanced electronic components and strengthening local customer support through its India offices and Chennai manufacturing facility.
August 2026: CapXon Electronic Technology introduced an ultra-low-profile conductive polymer aluminum electrolytic capacitor measuring 6.3 × 3.9 mm, expanding compact capacitor solutions while managing the company’s regional sales operations through its Singapore office.
June 2026: Rubycon opened its India Pune branch, strengthening its local presence and customer support capabilities in India’s growing automotive, industrial, communications, and electronics capacitor applications.
October 2025: KYOCERA AVX launched its KGP Series stacked commercial-grade MLCCs, offering higher capacitance within the same mounting area for industrial and high-frequency applications, supporting component miniaturization and sustainability requirements.
India Electric Capacitor Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 402.0 million |
| Total Market Size in 2031 | USD 610.0 million |
| Forecast Unit | Million |
| Growth Rate | 8.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Polarization, Voltage, Industry Vertical |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Aluminium
Ceramic
Tantalum
Paper and Film
Supercapacitor
Others
By Polarization
Polarized
Non-Polarized
By Voltage
High Voltage
Low Voltage
By Industry Vertical
Consumer Electronics
Automotive
Communication & Technology
Energy & Power
Industrial Electronics
Others
Table of Contents
1. Introduction
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholders
2. Research Methodology
2.1. Research Design
2.2. Research Process
2.3. Data Validation
3. Executive Summary
3.1. Key Findings
3.2. Analyst View
4. Market Dynamics
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Supplier
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. India Electric Capacitor Market By Type
5.1. Introduction
5.2. Aluminium
5.3. Ceramic
5.4. Tantalum
5.5. Paper And Film
5.6. Supercapacitor
5.7. Others
6. India Electric Capacitor Market By Polarization
6.1. Introduction
6.2. Polarized
6.3. Non-polarized
7. India Electric Capacitor Market By Voltage
7.1. Introduction
7.2. High Voltage
7.3. Low Voltage
8. India Electric Capacitor Market By Industry Vertical
8.1. Introduction
8.2. Consumer Electronics
8.3. Automotive
8.4. Communication & Technology
8.5. Energy & Power
8.6. Industrial Electronics
8.7. Others
9. India Electric Capacitor Market By State
9.1. Introduction
9.2. Maharashtra
9.3. Tamil Nadu
9.4. Uttar Pradesh
9.5. Delhi (NCR)
9.6. Telangana
9.7. Others
10. Competitive Environment and Analysis
10.1. Major Players and Strategy Analysis
10.2. Emerging Players and Market Lucrativeness
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. Company Profiles
11.1. KEMET Corporation
11.2. AVX Corporation (A subsidiary under Kyocera Corporation)
11.3. Yageo Corporation
11.4. Panasonic Corporation
11.5. Nichicon Corporation
11.6. Murata Manufacturing Co., Ltd.
11.7. Rubycon Corporation
11.8. Capxon International Electronic Co., Ltd.
11.9. Walsin Technology Corporation





Frequently asked questions
What is the projected market size and growth rate for India's Electric Capacitor Market?
Reaching USD 610.0 million by 2031, growing at an 8.70% CAGR.
What are the primary growth drivers for India's Electric Capacitor Market?
EVs, renewable energy, electronics expansion, and government initiatives are key drivers.
What forecast period does the India Electric Capacitor Market report cover?
The report provides strategic insights and forecasts from 2026 to 2031.
How do government initiatives influence the India Electric Capacitor Market?
ECMS promotes local manufacturing, strengthening domestic component ecosystem and reducing imports.
Which industries are key consumers of electric capacitors in India?
Electronics, automotive, telecommunications, IT hardware, and industrial equipment are major consumers.
What role does electric vehicle adoption play in the capacitor market?
Rising EV adoption significantly drives demand for advanced capacitors in powertrains.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). India Electric Capacitor Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/india-electric-capacitor-market