
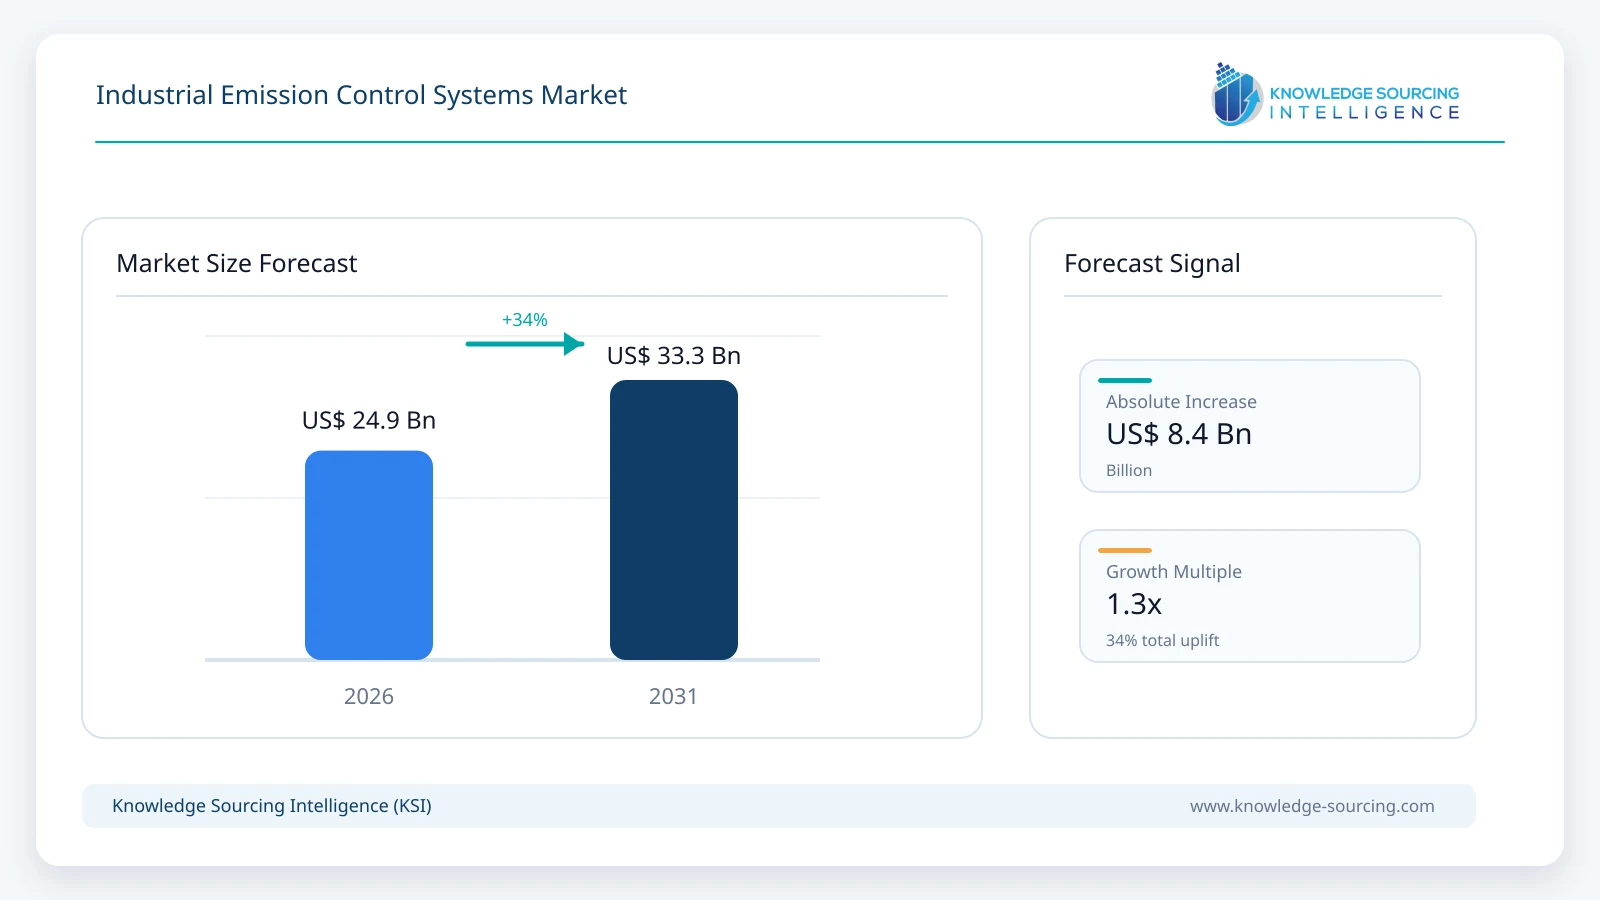
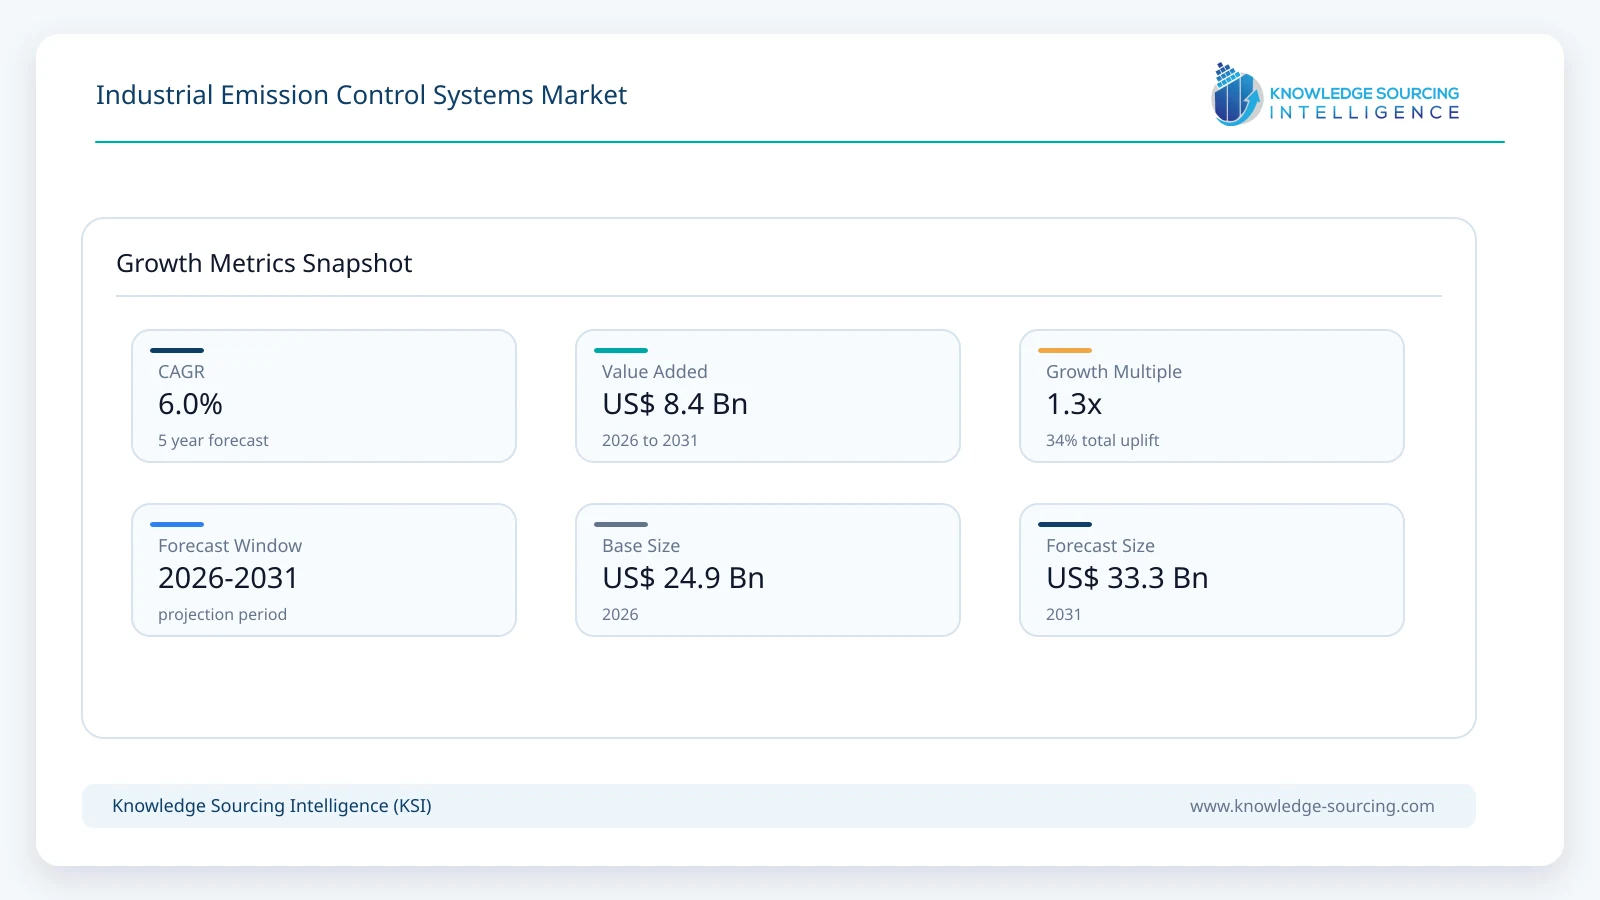
The global Industrial Emission Control Systems Market is growing at a CAGR of approximately 6.0%, from USD 24.9 billion in 2026 to USD 33.3 billion by 2031.
Highlights:
- 1Electrostatic precipitators account for approximately 31% of global market revenue in 2026.
- 2Power plants generate about USD 8.3 billion of industrial emission-control revenue in 2026.
- 3Asia Pacific is projected to grow at approximately 6.8% annually through 2031.
- 4Brownfield retrofits are increasing as operators modernize control systems without replacing core production assets.
- 5Integrated particulate, SOx and NOx systems are gaining importance in power, cement and metallurgical applications.
- 6Digital controls are improving reagent use, energy efficiency and availability across large emission-control installations.
Industrial emission control systems capture or neutralize pollutants generated by combustion and industrial processes before they are discharged to the atmosphere. Core technologies include electrostatic precipitators, fabric filters, wet and dry scrubbers, cyclones, selective catalytic reduction systems and other catalytic or adsorption-based equipment. Equipment selection depends on pollutant type, gas volume, temperature, particulate loading, fuel or feedstock composition, process integration and the applicable emissions limit. In large plants, multiple technologies are often combined because particulate matter, sulfur oxides, nitrogen oxides, acid gases and trace pollutants require different treatment mechanisms.
The supply market is increasingly service-led. Large installed systemsc operate for decades and require catalyst replacement, electrode modernization, reagent optimization, and digital control retrofits. ANDRITZ's 2026 Suzano contract, for example, covers modernization of five electrostatic precipitators rather than greenfield equipment. Mitsubishi Power similarly positions selective catalytic reduction, electrostatic precipitation and flue-gas desulfurization as an integrated air-quality-control system. These recurring modernization requirements create a more resilient revenue base than new-build capital expenditure alone.
Market Trends
Brownfield modernization is becoming a larger share of industrial emission-control spending
Many industrial plants are extending asset lives rather than replacing major boilers, kilns, furnaces or process lines, increasing demand for retrofits that improve emissions performance within existing footprints. Modernization can involve new high-frequency power supplies for electrostatic precipitators, replacement internals, higher-efficiency filter media, catalyst upgrades, scrubber modifications or digital process controls. ANDRITZ's 2026 Aracruz project includes switched integrated rectifier technology, new precipitator internals and upgraded ash handling, illustrating how modernization can improve both emission performance and operational reliability. This market is attractive to established suppliers because installed-base knowledge, outage planning and integration capability create barriers to new entrants.
Digital optimization is moving from monitoring toward active process control
Digitalization is increasingly used to optimize energy consumption, reagent dosage, pressure drop and collection efficiency across air-pollution-control systems. Thermax markets automated digital controllers for electrostatic precipitators, while ANDRITZ positions smart systems around optimizing both energy and reagent use. Operators are interested in these upgrades because environmental equipment can itself consume meaningful power, compressed air, water and sorbents. Real-time process data therefore creates an opportunity to lower operating cost while maintaining compliance. Over the forecast period, digital control and predictive maintenance are expected to become more important differentiators, particularly in large multi-stage systems.
Market Drivers
Tighter industrial-emissions regulation is sustaining retrofit and compliance investment
Industrial operators face increasingly detailed emissions requirements across major markets. The European Union's IED 2.0 tightens emission-limit conditions, broadens covered activities and increases the importance of best available techniques across large installations. In the United States, sector-specific rules continue to govern hazardous air pollutants, particulate matter, sulfur oxides, nitrogen oxides and other emissions even as carbon-policy requirements evolve. Emerging markets are also enforcing tighter controls in power, cement, metals and refining as urban air-quality pressure increases. These rules create recurring demand for new control systems, monitoring upgrades and retrofits because plants must maintain compliance throughout long operating lives rather than only at commissioning.
Industrial expansion in Asia is increasing the installed base of large emission-control systems
Asia Pacific remains the main source of new heavy-industrial capacity in several sectors, including power, steel, cement, chemicals, refining and pulp and paper. New plants generally require pollution-control equipment at commissioning, while existing facilities add or modernize systems as local regulations tighten. India is a particularly important market for flue-gas desulfurization and particulate control in coal-fired power generation, while China maintains a very large installed base of power and industrial emission-control systems. Thermax reports more than 35,000 air-pollution-control installations globally and continues to serve particulate and gaseous-emission applications across heavy industry, illustrating the scale of demand generated by industrial expansion and modernization.
Market Restraint
High capital cost and plant-specific integration can delay environmental upgrades
Large industrial emission-control projects can require substantial capital expenditure, long engineering cycles and production outages for installation or tie-ins. Brownfield plants may have limited space, complex ducting, old control systems and operating constraints that make retrofit engineering difficult. Operating costs can also be significant because scrubbers consume reagents and water, fabric filters require compressed air and replacement bags, and large fans or electrostatic systems add auxiliary power demand. When regulations allow long compliance schedules or plants face uncertain remaining asset lives, operators may defer major upgrades. This can create uneven order timing for suppliers even when the long-term need for emission control remains strong.
Segment Analysis
By Equipment Type - Electrostatic Precipitators
Electrostatic precipitators remain one of the largest equipment categories because they can treat very high flue-gas volumes with comparatively low pressure drop and are widely installed in power generation, cement, pulp and paper, metals and other heavy industries. The segment is projected to reach approximately USD 10.0 billion by 2031. Modern systems increasingly use upgraded power electronics, improved electrodes and digital controls to raise fine-particulate capture and reduce energy consumption. Wet electrostatic precipitators extend the technology into fine aerosol and acid-mist removal downstream of scrubbers. Fabric filters continue gaining ground in applications requiring very low particulate limits, but the enormous installed base of ESPs sustains modernization and service demand.
By Application - Power Plants
Power plants are projected to account for approximately 32% of global industrial emission-control revenue by 2031. The segment remains large because thermal power stations use combinations of electrostatic precipitators or baghouses, flue-gas desulfurization, selective catalytic reduction and related wastewater or ash-handling systems. Growth differs by region: coal retirements limit new-build opportunity in parts of Europe and North America, while India and several Asian markets continue to require large-scale retrofit or compliance investment. Babcock & Wilcox's approximately USD 130 million U.S. air-quality-control award in September 2026 shows that even mature power markets can generate substantial brownfield environmental projects when existing generating assets remain strategically important.
By Geography - Asia Pacific
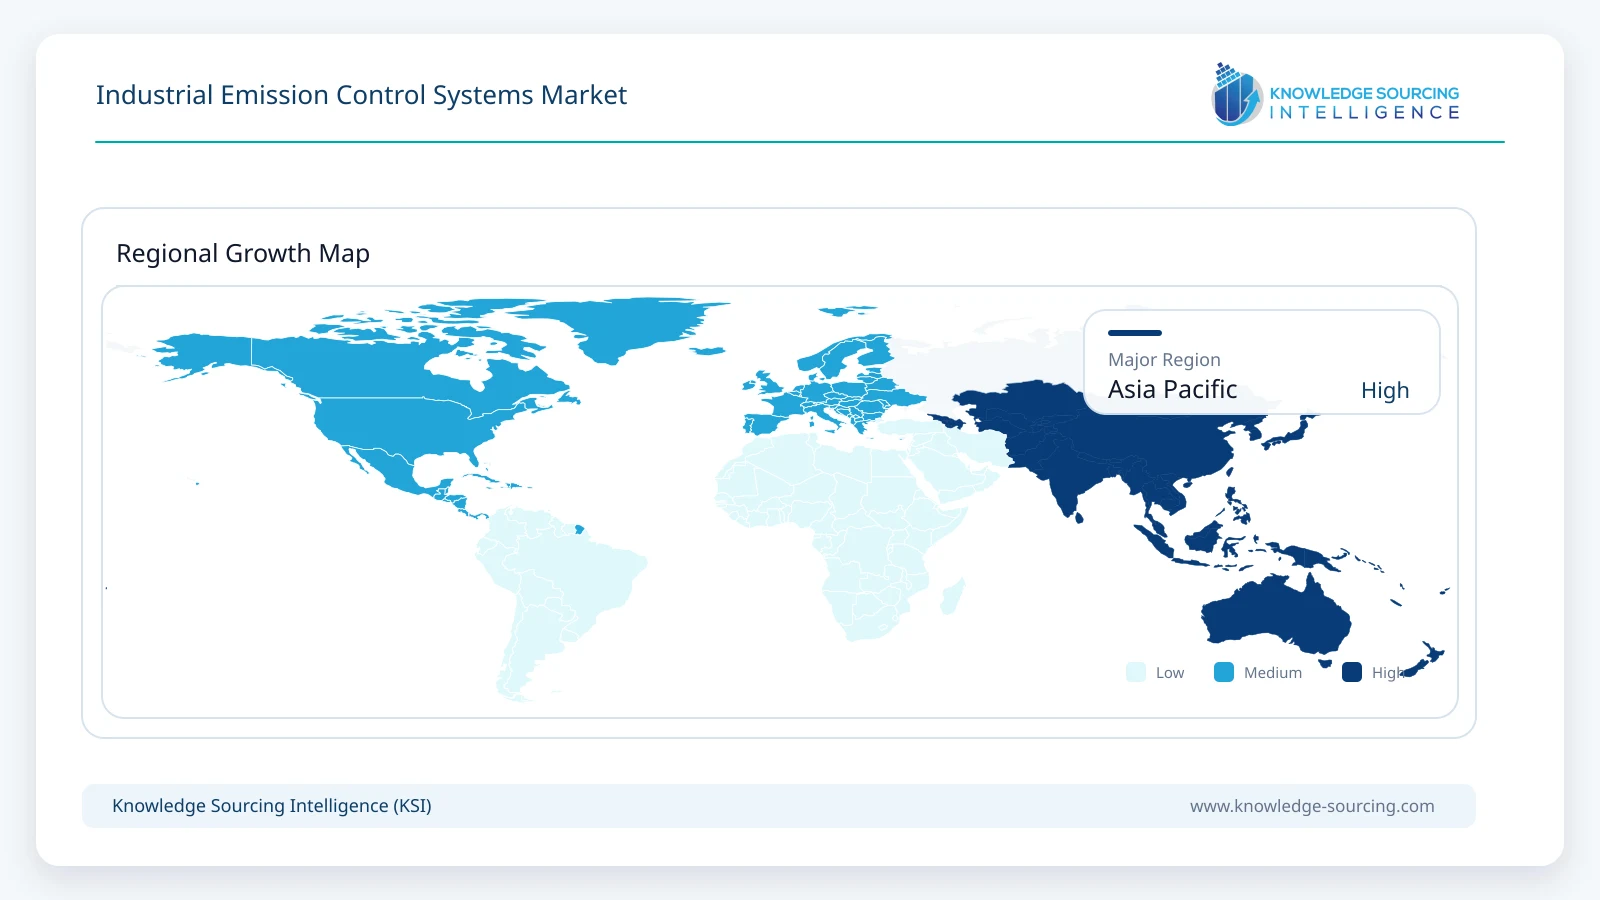
Asia Pacific is projected to generate approximately USD 15.9 billion in industrial emission-control revenue by 2031. The region combines the world's largest concentration of coal-fired power capacity with major cement, steel, chemicals, refining, mining and pulp-and-paper industries. China has a deep domestic supplier base, while India continues to invest in flue-gas desulfurization, particulate control and industrial air-quality systems. Japan and South Korea provide advanced technology and engineering capabilities, and Southeast Asian industrialization adds incremental demand. The region's faster growth relative to mature Western markets reflects both new industrial capacity and the modernization of older plants under progressively tighter local emissions standards.
Competitive Environment
The market combines global engineering groups, power-environment specialists and industrial filtration companies. ANDRITZ, Babcock & Wilcox, Mitsubishi Power, Thermax and CECO Environmental compete across large engineered systems and aftermarket services. Dürr, Nederman, Donaldson, Valmet, FLSmidth, Fujian Longking, Ducon, John Cockerill, AAF International, Camfil APC and KC Cottrell address different combinations of filtration, scrubbing, particulate control, catalytic treatment and industrial ventilation.
Competitive advantage depends heavily on installed-base references, process knowledge, emissions guarantees and lifecycle service capability. Large projects often require integration with boilers, kilns, furnaces or process lines and can include civil works, ducting, electrical systems, reagent handling and digital controls. Suppliers with local engineering and service teams are better positioned in brownfield projects because shutdown windows are limited and plant-specific constraints are significant. At the same time, specialized filtration companies can compete effectively in smaller industrial systems where standardized modular equipment and rapid delivery matter more than full EPC capability.
Recent Developments
September 2026: Babcock & Wilcox received a limited notice to proceed on an approximately USD 130 million air-quality-control project for a U.S. coal-fired power plant.
July 2026: Suzano selected ANDRITZ to modernize five electrostatic precipitators at its Aracruz pulp mill in Brazil, with the final upgraded unit scheduled to start in 2027.
March 2026: CECO Environmental raised its full-year 2026 orders outlook to more than USD 1.5 billion, reflecting strong demand across environmental and industrial infrastructure markets.
Industrial Emission Control Systems Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 24.9 billion |
| Total Market Size in 2031 | USD 33.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Equipment Type, Application, Geography |
| Companies |
|
Market Segmentation
By Equipment Type
Scrubbers
Filters
Electrostatic Precipitators
Cyclone Separators
Catalytic Reactors
Others
By Application
Power Plants
Mines and Metallurgical Plants
Chemical Manufacturers
Oil and Gas Refineries
Paper Mills
Coating and Printing
Rubber and Plastic Manufacturers
Cement
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Tighter Industrial-Emissions Regulation Is Sustaining Retrofit and Compliance Investment
3.1.2. Industrial Expansion in Asia Is Increasing the Installed Base of Large Emission-Control Systems
3.2. Market Restraint
3.2.1. High Capital Cost and Plant-Specific Integration Can Delay Environmental Upgrades
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. High-Efficiency Particulate Capture
4.2. Integrated SOx and NOx Control
4.3. Digital Optimization and Predictive Maintenance
5. INDUSTRIAL EMISSION CONTROL SYSTEMS MARKET BY EQUIPMENT TYPE
5.1. Introduction
5.2. Scrubbers
5.3. Filters
5.4. Electrostatic Precipitators
5.5. Cyclone Separators
5.6. Catalytic Reactors
5.7. Others
6. INDUSTRIAL EMISSION CONTROL SYSTEMS MARKET BY APPLICATION
6.1. Introduction
6.2. Power Plants
6.3. Mines and Metallurgical Plants
6.4. Chemical Manufacturers
6.5. Oil and Gas Refineries
6.6. Paper Mills
6.7. Coating and Printing
6.8. Rubber and Plastic Manufacturers
6.9. Cement
6.10. Others
7. INDUSTRIAL EMISSION CONTROL SYSTEMS MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Italy
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. ANDRITZ AG
9.2. Babcock & Wilcox Enterprises, Inc.
9.3. Mitsubishi Power, Ltd.
9.4. Thermax Limited
9.5. CECO Environmental Corp.
9.6. Dürr Group
9.7. Nederman Holding AB
9.8. Donaldson Company, Inc.
9.9. Valmet Oyj
9.10. FLSmidth & Co. A/S
9.11. Fujian Longking Co., Ltd.
9.12. Ducon Infratechnologies Limited
9.13. John Cockerill
9.14. AAF International
9.15. Camfil APC
9.16. KC Cottrell Co., Ltd.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











