
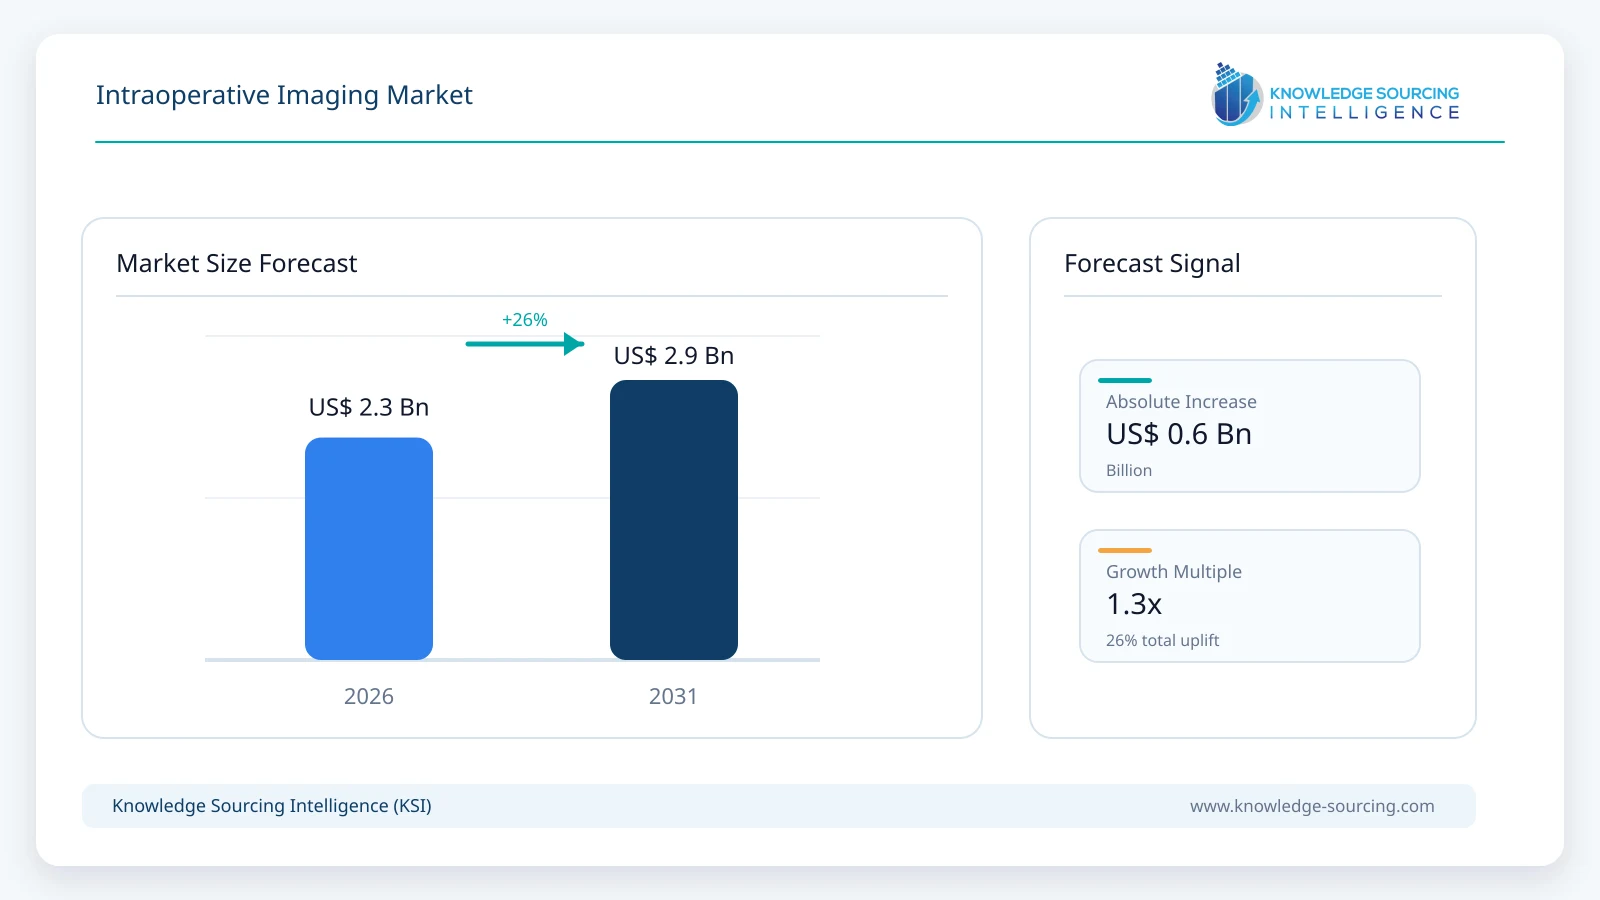
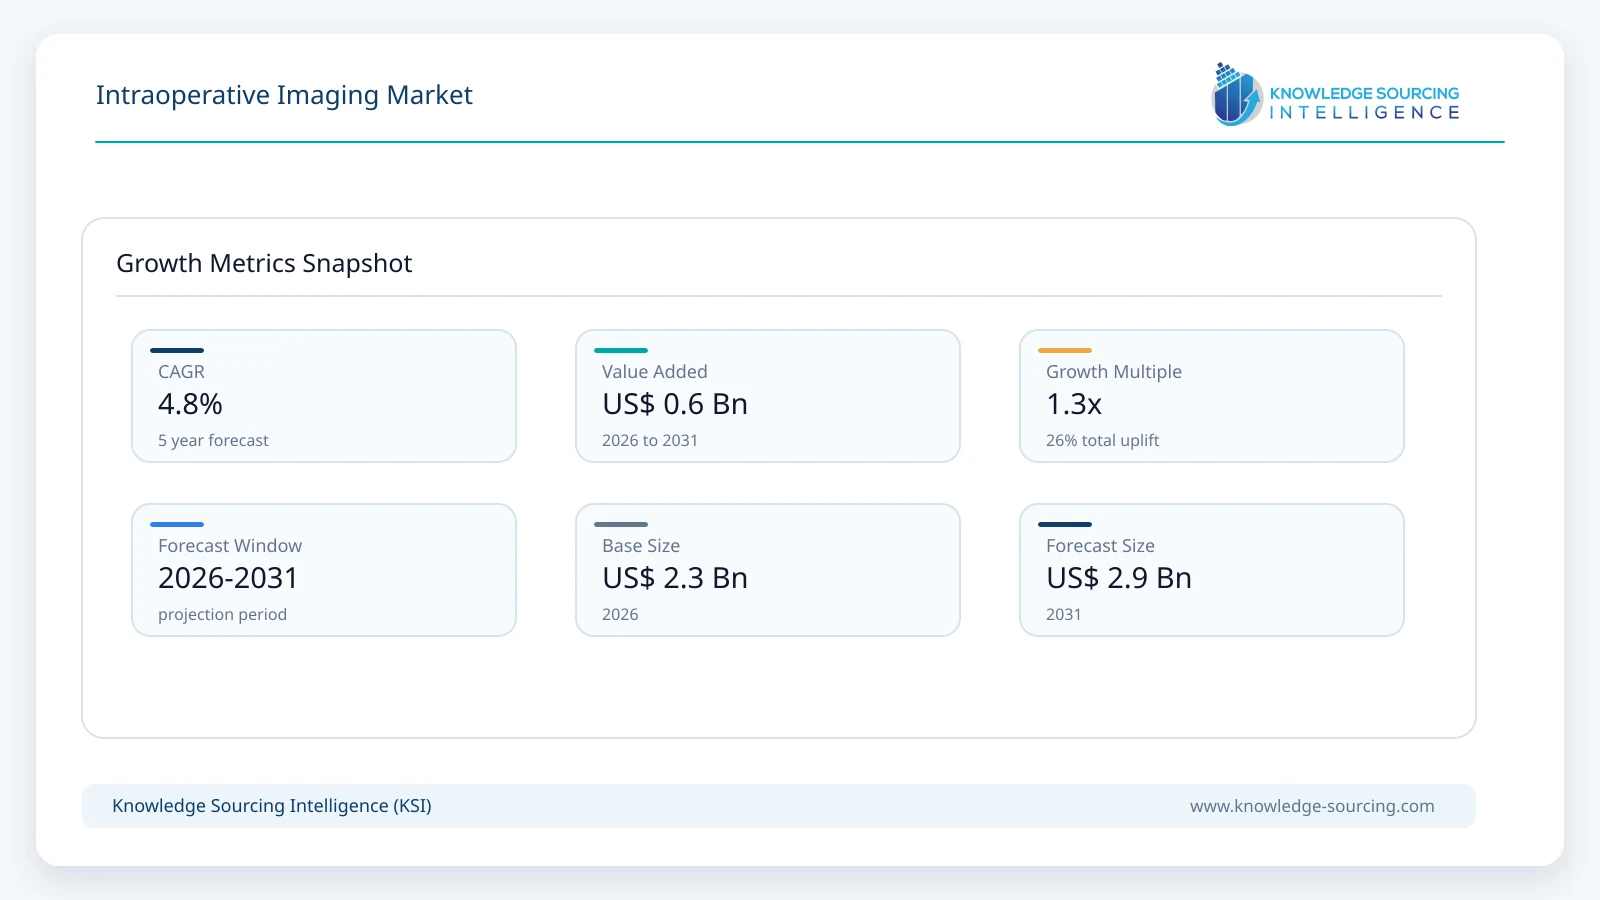
The Intraoperative Imaging market is set to reach USD 2.87 billion in 2031, growing at a CAGR of 4.8% between 2026 and 2031, from USD 2.28 billion in 2026.
Highlights:
- 1Integration of artificial intelligence into intraoperative systems enhances real-time image quality, automated guidance, and surgical decision support across complex procedures.
- 2Hybrid operating rooms combining multimodal imaging modalities enable continuous visualization without patient transfer, improving precision in neurosurgery and orthopedics.
- 3Fluorescence-guided techniques using specialized agents provide clear real-time differentiation of tumor margins and critical anatomical structures during oncologic resections.
- 4Mobile and automated C-arm platforms increase operational flexibility, streamline workflows, and support diverse applications in vascular, trauma, and minimally invasive surgeries.
Intraoperative Imaging systems used inside the operating room to guide surgeons in real time are being shaped by government rules that determine how rapidly new devices reach hospitals and how much hospitals are paid for using them, together with heavy investment by major suppliers racing to launch smarter, smaller, AI-powered imaging systems. Companies including Medtronic, Brainlab, Siemens Healthineers, GE HealthCare, and Philips are all launching new FDA-cleared systems within months of each other, while U.S. regulators are also reshaping how much hospitals get paid for using these machines.
The Breakthrough Devices Program is a program run by the FDA that facilitates the availability of new medical devices to patients earlier when they are intended to treat or diagnose serious or life-threatening diseases. The program not only brings new products to market but also accelerates the development, review and approval process, without compromising the FDA's normal safety standards.
As part of that regulatory foundation, the FDA has cleared a bunch of new intraoperative imaging and navigation systems during the past year, including Medtronic's Stealth AXiS system, Siemens Healthineers' Artis interventional imaging line and GE HealthCare's Allia Moveo and SIGNA MRI systems, all of which went through the FDA's 510(k) clearance process.
In February 2026, Medtronic's own newsroom reports that it got FDA clearance for its Stealth AXiS surgical system for spine surgery, designed to be expandable to brain and ENT surgery.
In addition to Medtronic, Brainlab's press release also details that it was the first fully robotic mobile imaging system to be FDA cleared, offering parts that move independently around the patient, reducing radiation exposure and enabling greater flexibility in positioning during surgery.
Furthermore, GE HealthCare launched its new compact imaging machine, Allia Moveo, in December 2025, designed with AI tools to improve image quality in real time, is cable-free and moves easily around a densely occupied operating room, and has since been FDA-cleared.
The FDA determines the rate of hospitals using these systems, and the Centers for Medicare & Medicaid Services (CMS) determines their profitability.
The reimbursement policy also has a significant impact on the revenue hospitals can recover from costly imaging equipment, and therefore their willingness to spend on new equipment in the wake of constant new upgrades by suppliers.
Overall, the pattern across regulators and suppliers points in the same direction. Government rules are encouraging faster, safer device approval while also tightening how much hospitals get paid for using imaging equipment. In response, suppliers are packing more value, AI, robotics, and navigation into each new system rather than competing only on the imaging hardware itself.
Market Drivers
Growing demand for Minimally Invasive Surgeries
Hospitals and surgeons are shifting more procedures away from traditional open surgery toward minimally invasive techniques, which rely on small incisions guided by real-time imaging instead of a surgeon's direct line of sight. This shift is a direct driver of the intraoperative imaging market, since every minimally invasive or robotic procedure needs an imaging system to show the surgeon what's happening inside the body in real time.
The U.S. Centers for Disease Control and Prevention's National Center for Health Statistics point to the development of non-invasive or minimally invasive techniques that allow procedures that used to require weeks of recovery to be completed in just a few days, as well as the improvement in anesthesia and analgesia, contributing to the long-term growth in ambulatory (same-day) surgery.
This transition is being realized directly on the company's results. According to Intuitive Surgical's own SEC filing, in 2025, Intuitive's da Vinci surgical systems were used approximately 3,153,000 times globally, an increase of around 18% compared to 2024, both in the U.S. and on the international market.
By year-end, Intuitive had more than 12,100 of its da Vinci and Ion systems in use. The company has also seen a rise in system utilization (procedures performed per system per year), indicating that hospitals are not only expanding the number of systems, but using each one more heavily, according to its 2025 annual report.
Each of these robotic procedures requires the use of the imaging system to operate safely, as opposed to opening up the patient to view the soft tissue, bone or blood vessels in real time.
That is why imaging and robotics companies are integrating these two technologies into a single platform rather than offering them as two separate systems. As Medtronic notes in its newsroom, its Stealth AXiS system has been designed to be an intelligent platform that brings surgical planning, navigation and robotics together to meet the growing demand for less invasive, image-guided surgical procedures.
Philips makes the same point on its own product pages, describing its Azurion imaging platform as the centerpiece of the "Hybrid Operating Room", designed to support both traditional open surgery and minimally invasive procedures using the same imaging system. This approach allows hospitals to avoid maintaining separate rooms or equipment for each surgical method.
Taken together, this data shows a clear cycle driving the market. As more procedures move toward minimally invasive and robotic techniques, demand for intraoperative imaging grows in lockstep, since imaging is the technology that makes minimally invasive surgery possible in the first place.
Growing Burden of Chronic Diseases
Intraoperative imaging technologies are vital in accurately diagnosing and treating chronic conditions such as cancer, cardiovascular disorders, and neurological conditions. Therefore, the rising cases of chronic diseases are expected to aid the intraoperative imaging market. For example, there were around 13.0 million visits to doctors' offices in the US, with coronary atherosclerosis and other forms of chronic ischemic heart disease being the most common diagnoses as per the 2019 National Medical Ambulatory Service by the CDC. Moreover, according to WHO estimates, non-communicable chronic diseases are responsible for 82% of all fatalities and 67% of premature deaths in Egypt.
Rising Image-Guided Surgical Procedures
Intraoperative imaging makes image-guided surgical procedures more efficient and safer by enabling in-flight visualization and accurate navigation. The rising image-guided surgical procedure is therefore one of the major growth drivers of the intraoperative imaging market. There are various advantages associated with image-guided surgeries that are driving the adoption. For instance, Surgeons receive real-time feedback during the procedure, allowing them to assess the efficacy of their interventions immediately. Moreover, for complex surgeries, such as spinal procedures or brain surgeries, image-guided systems provide navigational support, assisting surgeons in reaching their target areas accurately.
Advancements in Medical Technology
The continuous progress in medical imaging technologies has resulted in the creation of increasingly advanced and accurate intraoperative imaging devices, which is expanding the intraoperative imaging market. Medical imaging technologies, including MRI, CT scans, and ultrasound, have become more sophisticated, providing clearer and more detailed images for accurate diagnosis and treatment planning. For instance, Pie Medical Imaging launched an AI-powered echocardiography platform in January 2023. It enables robust visualization of stress-echo imaging and diastolic function. Additionally, Block Technology launched the Cube Mobile Imaging business to provide healthcare providers with comfortable patient scanning environments.
Aging Population
The global aging population is increasing, leading to a higher number of surgeries, especially those related to age-related health issues. Intraoperative imaging technologies assist in complex surgeries, making them safer for elderly patients. According to the WHO, people are more prone to have many ailments at once as they get older. Therefore, the aging population is expected to propel the intraoperative imaging market. For instance, one in six individuals on the planet will be 60 or older by 2030. By this point, there will be 1.4 billion people over the age of 60 as compared to 1 billion people in 2020, as per the WHO. Moreover, according to estimations from the World Health Organization (WHO), the number of individuals aged 80 or older is expected to triple from 2020 to 2050, reaching a staggering 426 million.
Market Restraints and Challenges
The intraoperative imaging market has experienced growth and development; however, some restraints or challenges can impact its expansion. For example, intraoperative imaging devices, especially advanced and cutting-edge technologies, can be expensive to acquire and maintain. The high upfront costs of these systems may deter some healthcare facilities, particularly in resource-limited settings, from investing in them. Moreover, effective utilization of intraoperative imaging systems requires well-trained and skilled healthcare professionals, including surgeons and radiologists. The shortage of trained personnel could limit the widespread adoption of these technologies, particularly in low-income and backward regions.
Major Segment Analysis
Neurosurgery
Application-wise, the intraoperative imaging market is segmented into neurosurgery, orthopedic surgery, ENT surgery, oncology surgery, trauma & emergency surgery, cardiovascular, spinal surgery and others. Ongoing efforts to increase operational efficiency have escalated the demand for real-time visual information, which is expected to support the adoption of intraoperative imaging.
The high prevalence of minimally invasive surgeries has increased the demand for advanced imaging technologies for MIS procedures, supporting market expansion. The neurosurgery segment is projected to grow at a steady rate fueled by the high prevalence of neurosurgical conditions that require surgical intervention.
High-stakes procedures such as epilepsy surgery, deep brain stimulation, and brain tumor resection require real-time imaging to enhance surgical precision, supporting the adoption of iMRI, iCT, and intraoperative ultrasound technologies in neurosurgery.
Studies published in the National Institutes of Health (NIH) indicate annual reporting of 22.6 million new neurosurgical cases globally, of which 13.8 million require surgical intervention. Such a high reporting rate, followed by the shortage of working staff, has accelerated reliance on advanced imaging options for neurosurgeons.
Favorable government regulations supporting technological adoption, followed by advancements in robotic surgeries, have shaped the market trajectory, especially in global economies like China and the United States.
Strategic collaborations of key market players are supporting new developments. For instance, in January 2026, IMRIS announced its collaboration with SpinTech to integrate the latter’s neuro-imaging software in IMRIS’s “InVision” surgical platform. Such a partnership increases surgical precision for neurosurgical procedures.
Investment in new product development has encouraged new innovations, such as Esaote’s “I-Genius” intraoperative MRI system, which is designed to provide real-time monitoring during glioma surgery.
Similarly, partnerships supporting iMRI adoption in neurosurgery have improved market outlook. Hence, companies like IMRIS have invested in such trends by partnering with the University of Michigan to bolster its “InVision Operating Suite” adoption.
Regional Analysis
North America: the US
Continued advancements in medical technology in the United States, supported by growing efforts to integrate AI into healthcare, have expanded the market potential for intraoperative imaging. The country’s high volume of surgical procedures has further strengthened demand for these imaging solutions.
Growing chronic disease prevalence, such as cardiovascular disease, has escalated the prevalence of surgical interventions for such diseases in major US states. According to the Society of Thoracic Surgeons Adult Cardiac Surgery Registry Database, New Jersey reported 10,931 cases of cardiac surgery, consisting of 7,035 open-heart surgeries and 3,896 TAVRs.
Implementation of the “Advanced Research Projects Agency for Health (ARPA-H)” has supported the development of novel technologies supporting precision surgeries, especially for cancer, in the USA, boosting market outlook.
Strategic tie-ups of market players like IMRIS with US institutions to support intraoperative MRI adoption in neurosurgery, followed by FDA approval of AI-enabled intraoperative imaging solutions such as “Claire™ OCT+AI”, have amplified the market landscape.
Companies such as GE Healthcare and Medtronic enjoy a wide customer base in the United States, and the recent integration of GE’s “bkActiv” with Medtronic’s “Stealth AXiS” has improved the regional market transparency.
Company Profiles
GE HealthCare has adopted a strategy centered on expanding its image-guided surgery portfolio through technological innovation, strategic acquisitions, and digital integration. The company's acquisition of BK Medical significantly strengthened its position in intraoperative imaging by adding real-time surgical ultrasound capabilities, enabling surgeons to visualize anatomy during procedures and make informed clinical decisions.
GE HealthCare focuses on delivering comprehensive imaging ecosystems that integrate mobile C-arms, intraoperative ultrasound, advanced visualization software, and AI-enabled workflow solutions to improve surgical precision and efficiency. The company is also emphasizing interoperability by integrating its imaging platforms with surgical navigation and robotic-assisted surgery systems, enabling seamless data exchange in hybrid operating rooms.
Siemens Healthineers AG is a leading player in the healthcare industry, specializing in providing a wide range of medical imaging, diagnostics, and laboratory equipment and services. It offers conventional intraoperative 3D imaging in orthopedic trauma surgery.
Medtronic is a global medical technology company that specializes in various medical areas, including cardiac and vascular, minimally invasive therapies, restorative therapies, and diabetes management. It offers an O-arm™ intraoperative 2D/3D imaging system to be used in spine, cranial, and orthopaedics procedures.
Ziehm Imaging GmbH is a German-based medical technology company specializing in manufacturing mobile C-arm imaging systems. Ziehm Imaging's C-arm devices provide high-quality X-ray imaging capabilities that are essential for intraoperative visualization and navigation during surgical procedures.
Recent Developments
July 2026: Johnson & Johnson introduced its Monarch Platform integrated with AI-powered MONARCH QUEST navigation technology in the Middle East, enabling advanced real-time imaging and robotic bronchoscopy procedures at Cleveland Clinic Abu Dhabi.
March 2026: Olympus Corporation announced the U.S. launch of the VISERA ELITE™ III surgical imaging platform, offering True 4K, Yellow Enhancement, and advanced fluorescence-guided surgery to elevate intraoperative visualization and surgical workflow efficiency.
2026: GE HealthCare announced the commercial availability of digital integration between the bkActiv™ intraoperative ultrasound system and Medtronic's Stealth AXiS™ surgical navigation system, enabling real-time ultrasound imaging to be incorporated into cranial surgical navigation workflows and enhancing surgical precision.
May 2025: GE HealthCare launched CleaRecon DL, an advanced artificial intelligence-driven 3D reconstruction technology built to optimize and sharpen cone-beam computed tomography image quality during live interventional procedures.
Intraoperative Imaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.28 billion |
| Total Market Size in 2031 | USD 2.87 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Product (2021-2031)
By Application (2021-2031)
By End User (2021-2031)
By Geography (2021-2031)
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. INTRAOPERATIVE IMAGING MARKET BY PRODUCT (2021-2031)
5.1. Introduction
5.2. Intraoperative CT (iCT)
5.3. Intraoperative Ultrasound (iUS)
5.4. Intraoperative MRI (iMRI)
5.5. Mobile C-arm Systems
6. INTRAOPERATIVE IMAGING MARKET BY APPLICATION (2021-2031)
6.1. Introduction
6.2. Neurosurgery
6.3. Orthopedic Surgery
6.4. ENT Surgery
6.5. Oncology Surgery
6.6. Trauma & Emergency Surgery
6.7. Cardiovascular Surgery
6.8. Spinal Surgery
6.9. Others
7. INTRAOPERATIVE IMAGING MARKET BY END USER (2021-2031)
7.1. Introduction
7.2. Hospitals
7.3. Ambulatory Surgical Centers (ASCs)
7.4. Specialty Surgical Centers & Clinics
8. INTRAOPERATIVE IMAGING MARKET BY GEOGRAPHY (2021-2031)
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Indonesia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. GE Healthcare Technologies Inc.
10.2. Siemens Healthineers AG
10.3. Koninklijke Philips N.V.
10.4. Medtronic plc
10.5. Ziehm Imaging GmbH
10.6. Brainlab AG
10.7. Shimadzu Corporation
10.8. NeuroLogica Corporation (Samsung NeuroLogica)
10.9. IMRIS (Deerfield Imaging)
10.10. Stryker Corporation
10.11. Esaote
11. RESEARCH METHODOLOGY
12. LIST OF FIGURES
13. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











