
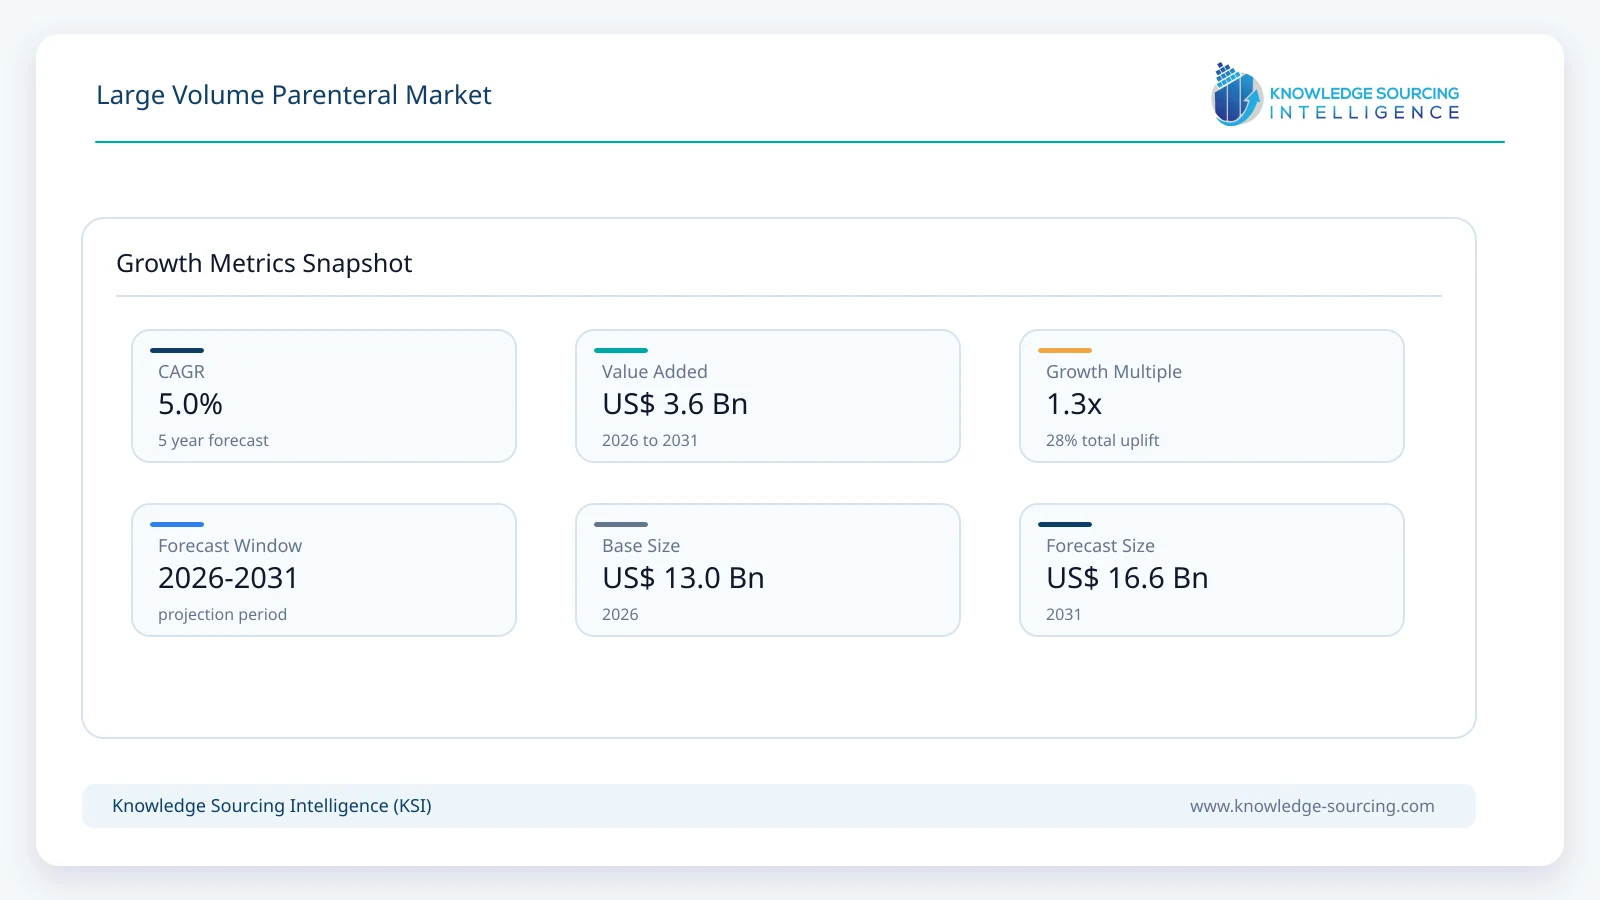
The Global Large Volume Parenteral Market is forecast to grow at a CAGR of 5.05%, reaching USD 16.64 billion in 2031 from USD 13.01 billion in 2026.
Highlights:
- 134% of market value in 2026Sodium Chloride/Saline Solutions account for approximately , making them the largest solution category.
- 26.6% annually through 2031Parenteral Nutrition Solutions are projected to grow at approximately , making them the fastest-growing major solution type.
- 3100–250 mLThe segment accounts for approximately 39% of market value in 2026, while Above 500 mL records the strongest growth within the volume segmentation.
- 456% of market value in 2026Fluid & Electrolyte Replacement accounts for approximately , while Nutrition records the strongest application growth.
- 567% of packaging value in 2026Flexible Plastic Bags account for approximately , followed by Plastic Bottles/Other Rigid Plastic Containers and Glass Bottles.
- 672% of market value in 2026Hospitals represent approximately , while Home Healthcare records the strongest end-user growth from a smaller base.
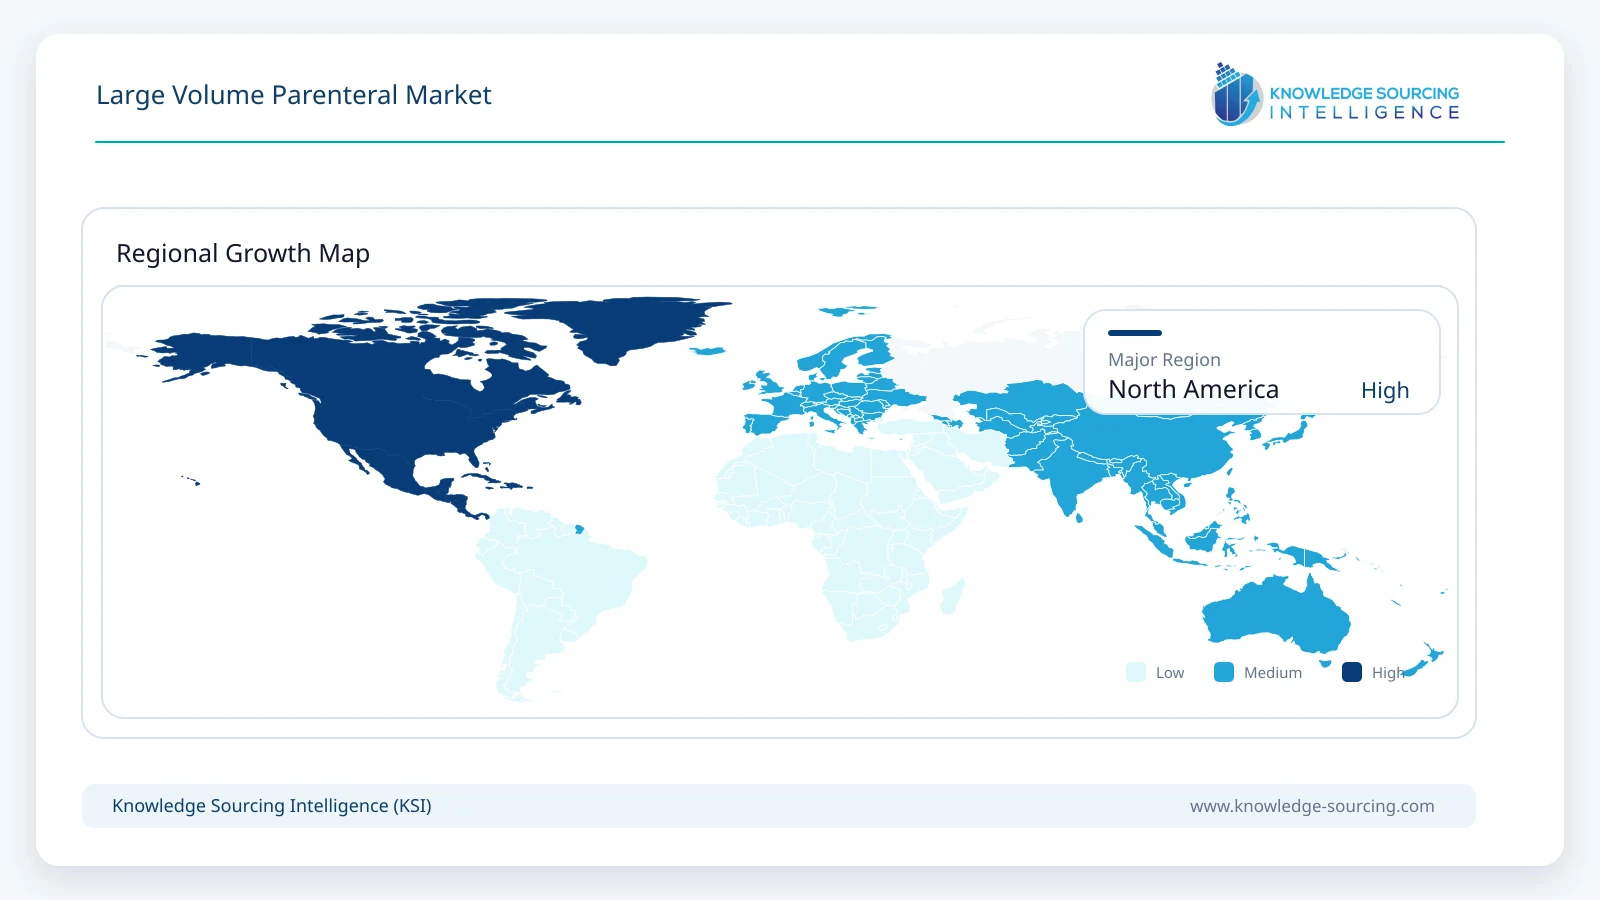
- 7North America remains the largest regional market, while Asia Pacific records the strongest major-region growth.
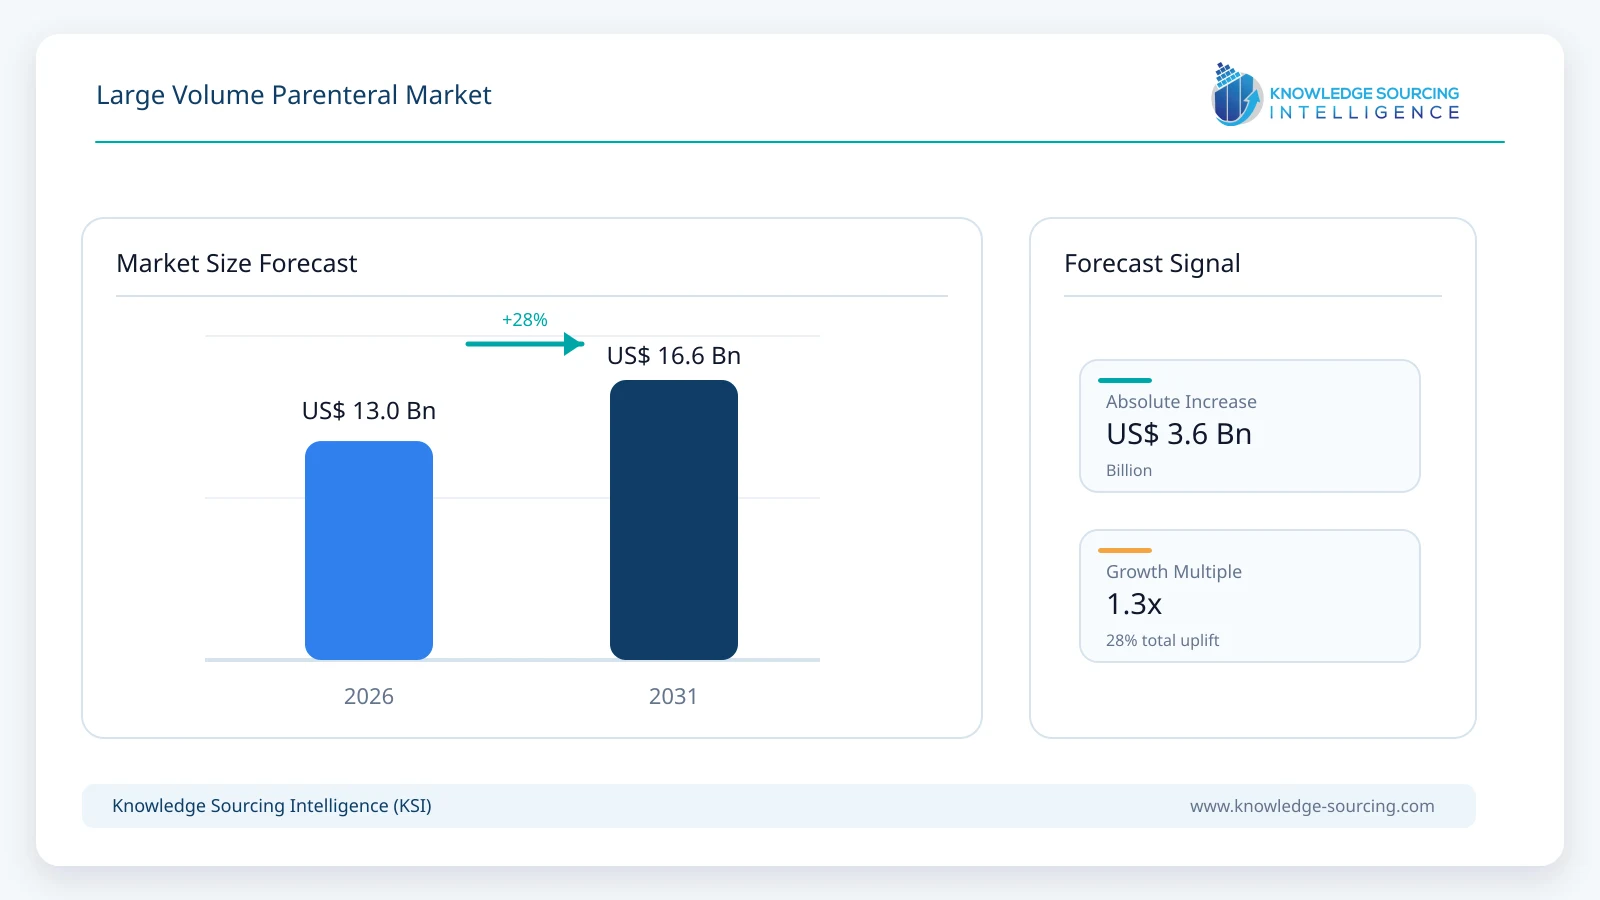
Large volume parenterals are sterile aqueous preparations generally supplied in single-dose containers of 100 mL or more for intravenous fluid therapy, electrolyte replacement, nutritional support, and administration of other medicines. The market includes sodium chloride and saline solutions, balanced electrolyte formulations, dextrose solutions, parenteral nutrition products and other sterile fluids packaged in flexible bags, rigid plastic containers and glass bottles. Demand is closely linked to hospital admissions, surgery, emergency medicine, critical care and the management of patients who cannot maintain sufficient fluid or nutritional intake orally.
The market remains anchored in mature products, but the underlying mix is changing. Sodium Chloride/Saline Solutions remain the largest solution category because normal saline is used widely for hydration, fluid replacement and drug administration, while balanced electrolyte products are gaining importance in resuscitation and replacement therapy. Parenteral Nutrition Solutions represent a smaller value pool but grow faster as hospitals treat more critically ill, oncology and gastrointestinal patients requiring sustained intravenous nutritional support. Flexible Plastic Bags remain the dominant packaging platform because they are lightweight, collapse during infusion and reduce breakage risk, but rigid plastic bottles remain sufficiently important in markets such as Japan, China and India to warrant separate analysis. These shifts support steady value growth even though many of the underlying formulations have been in clinical use for decades.
Supply resilience is becoming as strategically important as formulation and packaging. The temporary shutdown of Baxter’s North Cove facility after Hurricane Helene disrupted IV-fluid availability across the United States and required FDA intervention, temporary imports and expanded production from alternative suppliers. Europe also experienced shortages of intravenous and irrigation solutions during 2025 before regulators reported normalization in April 2026. These events demonstrated that LVPs are operationally critical medicines even though many individual products are low priced and difficult to differentiate pharmacologically. Manufacturers are therefore investing greater attention in manufacturing redundancy, safety stock, alternative production sites and distributor inventory. B. Braun’s Supply Assurance Program, designed to hold 45 days of inventory at participating distributor warehouses, illustrates how continuity of supply is becoming a competitive attribute alongside sterile-manufacturing quality and contract pricing.
Growth Drivers and Trends
Hospital and Surgical Care Sustain Core LVP Consumption
Large volume parenterals are fundamental to hospital care because intravenous fluids are used across emergency medicine, surgery, intensive care, oncology and general inpatient treatment. Patients experiencing dehydration, blood loss, sepsis, trauma or major surgery frequently require fluids before oral intake can be restored, while IV solutions also function as carriers for medicines that need controlled administration. This gives the LVP market a broader clinical base than many pharmaceutical categories and reduces dependence on any one therapeutic area. The market therefore grows primarily with healthcare utilisation, hospital capacity and access to institutional treatment rather than with individual drug launches. Expansion of hospital systems in emerging economies provides additional demand, while mature healthcare markets continue to consume large volumes because of ageing populations, complex treatment patterns and high procedure rates. The essential nature of these products creates recurring demand even where procurement prices remain under pressure.
Balanced Electrolyte Solutions Gain Importance in Fluid Therapy
Normal saline remains the largest individual solution family, but balanced electrolyte solutions are gaining importance in fluid resuscitation and replacement therapy. These products contain broader electrolyte combinations and are designed to approximate physiological fluid composition more closely than simple sodium chloride solutions. B. Braun’s existing portfolio includes sodium chloride, dextrose combinations, Lactated Ringer’s and Isolyte formulations across multiple container sizes, while Baxter and Fresenius Kabi maintain comparable balanced-fluid portfolios. The shift does not displace saline because normal saline remains deeply embedded in hospital protocols and is widely used as a diluent and general-purpose fluid. Instead, balanced solutions increase their share gradually where clinicians prefer broader electrolyte compositions for surgery, critical care and other fluid-replacement applications. Their higher clinical differentiation supports growth above the basic saline category, contributing to a more varied solution mix within the overall LVP market through 2031.
Parenteral Nutrition Expands Across Complex Care Pathways
Parenteral Nutrition Solutions are projected to grow at approximately 6.6% annually through 2031, supported by critical care, oncology, gastrointestinal disease and selected home-care applications where patients cannot receive adequate nutrition through the gastrointestinal tract. These products can deliver glucose, amino acids, lipids, electrolytes, vitamins and trace elements through standardized or multi-chamber systems, making them substantially more complex than routine hydration fluids. B. Braun and Fresenius Kabi both maintain extensive nutrition portfolios covering hospital and outpatient use, and multi-chamber bags simplify preparation by separating components until administration. Growth is also supported by longer survival among patients with complex chronic conditions and greater use of specialized nutritional support outside intensive-care environments. Because parenteral nutrition requires greater formulation control, packaging compatibility and clinical management, it represents a smaller but higher-value category than routine electrolyte replacement and contributes disproportionately to value growth within the LVP market.
Manufacturing Resilience Becomes Part of Hospital Procurement
Recent supply disruptions have changed how hospitals and distributors evaluate IV-fluid suppliers. Following Hurricane Helene, the loss of production at Baxter’s North Cove facility affected a substantial portion of U.S. IV-solution availability and prompted FDA to authorize temporary imports and additional supply measures. Similar shortages were recorded in Europe during 2025 before regulators reported the situation resolved in April 2026. These events demonstrated that supply continuity cannot be evaluated solely through historical contract performance because individual manufacturing sites can represent a large portion of national availability. Manufacturers with multiple qualified sterile-production facilities, stronger inventory buffers and broader geographic footprints therefore gain an advantage even when their products are pharmacologically similar to those of competitors. B. Braun’s decision to maintain 45 days of inventory at selected distributor warehouses illustrates this shift toward resilience as a formal purchasing consideration rather than an operational issue managed only after shortages occur.
Flexible and Rigid Plastic Containers Continue Replacing Glass
Plastic packaging has become the principal LVP platform because it reduces shipping weight, breakage risk and handling complexity compared with traditional glass bottles. Flexible bags dominate current hospital use and collapse naturally as fluid is infused, while rigid or semi-rigid plastic bottles remain commercially important in several regional markets. Fresenius Kabi manufactures freeflex bags alongside KabiPac polyolefin containers, Otsuka has a long-established polypropylene IV bottle platform, and Kelun markets collapsible polypropylene bottles for infusion solutions. This evidence supports treating Flexible Plastic Bags and Plastic Bottles/Other Rigid Plastic Containers as separate packaging categories rather than combining all plastic systems into one segment. Glass remains relevant where chemical compatibility, established manufacturing processes or regional clinical preferences support its use, but its share continues to moderate as validated plastic systems expand. Packaging therefore represents a genuine source of competitive differentiation rather than simply a container choice.
Market Restraints
Sterile Manufacturing Requires Substantial Fixed Investment
Large volume parenterals are comparatively inexpensive medicines, but manufacturing them requires substantial capital investment in purified-water systems, sterile filling, container production or handling equipment, terminal sterilisation, microbiological control and validated clean environments. This creates an economic structure in which manufacturers need large production volumes and high plant utilisation to distribute fixed costs effectively. New entrants may find it difficult to compete in basic saline or dextrose because procurement prices are low while regulatory and infrastructure requirements remain high. Existing suppliers therefore gain advantages from scale, established hospital contracts and qualified manufacturing networks. The same economics can contribute to supply concentration because investing in redundant sterile capacity may appear unattractive during periods of normal supply. Recent shortages have highlighted the systemic risk of this concentration, but solving it requires additional production investment that may not generate high margins under routine procurement conditions.
Product Integrity Failures Can Affect Large Quantities of Essential Supply
LVP products are administered directly into the bloodstream, making sterility, particulate control and container integrity critical quality requirements. Flexible bags need to withstand manufacturing, sterilisation, transport, storage and clinical handling without developing leaks or seal failures, while rigid containers need equivalent protection against defects and contamination. In August 2026, FDA issued a warning letter to Fresenius Medical Care after identifying deficiencies in investigations involving leaking large-volume parenteral bags, including complaints associated with bag perforations. Such events demonstrate why apparently minor packaging defects can become strategically important in a market where large production batches supply hospitals across wide geographic areas. Quality failures can trigger recalls, remove significant quantities from circulation and exacerbate shortages if alternative suppliers have limited spare capacity. Container engineering and investigation systems therefore remain central to competitive performance even though the underlying IV solution itself may be relatively simple.
Supply Concentration Can Create System-Level Shortages
Concentration among a relatively small number of major manufacturers improves production efficiency but creates significant healthcare-system exposure when individual plants experience natural disasters, contamination events or operational shutdowns. The North Cove disruption illustrated the scale of this risk in the United States, while European shortages during 2025 demonstrated that the issue is not confined to one market. Hospitals can manage some risk by qualifying multiple suppliers and maintaining higher inventories, but IV fluids are bulky products that require substantial warehouse capacity and logistics planning. Manufacturers likewise face a trade-off between efficient centralized production and the cost of maintaining redundant capacity. The market therefore needs greater resilience without eliminating the scale efficiencies that keep basic LVP products affordable. This tension is likely to influence procurement contracts, distributor inventory strategies and capacity investment throughout the forecast period.
Standard Solutions Face Strong Pricing Pressure
Sodium chloride, dextrose and several balanced electrolyte formulations are mature products with limited pharmacological differentiation, which places considerable emphasis on procurement price and supply reliability. Hospital systems and group purchasing organizations can compare equivalent products across manufacturers, restricting the ability of suppliers to raise prices substantially without a packaging, service or supply advantage. Manufacturers need highly automated production, efficient sterilisation and high plant utilisation to protect margins while continuing to meet stringent quality requirements. This encourages companies to supplement standard fluids with more differentiated products such as multi-chamber nutrition bags, premixed medicines and advanced container systems. The result is a market where basic solutions continue to drive large volumes, while a growing share of incremental value comes from packaging, specialized formulations and supply-chain services rather than from conventional saline alone.
Packaging Changes Require Extensive Pharmaceutical Validation
Changing an LVP container requires considerably more work than changing normal consumer packaging because the container is part of the drug-delivery system and remains in prolonged contact with the sterile solution. Manufacturers must evaluate extractables, leachables, sterilisation behaviour, mechanical integrity, oxygen and moisture characteristics and long-term product stability before adopting new materials. This slows the industry’s transition toward non-PVC, non-DEHP or lower-impact packaging even when the operational advantages are clear. Flexible bags and polyolefin containers continue to gain share because major manufacturers have already completed the required validation for broad product ranges, but packaging innovation remains incremental rather than immediate. Environmental considerations therefore influence the market alongside clinical and manufacturing requirements, with successful packaging platforms needing to satisfy sustainability objectives without compromising sterile-product stability or hospital handling.
Segment Analysis
By Solution Type
Sodium Chloride/Saline Solutions Remain the Largest Solution Category
Sodium Chloride/Saline Solutions account for approximately 34% of market value in 2026, reflecting their extensive use for hydration, fluid replacement and administration of compatible medicines. Normal saline is one of the most broadly utilized IV fluids across emergency departments, operating rooms, intensive-care units and general inpatient wards, giving the category a large recurring demand base despite limited formulation differentiation. Major manufacturers supply saline across several container sizes and packaging formats, and FDA’s shortage response following the North Cove disruption specifically identified 0.9% sodium chloride as one of the products requiring additional supply. The category grows more slowly than specialized solutions because hospital penetration is already high, but its essential clinical role ensures that it remains the largest solution family through 2031. Balanced Electrolyte Solutions gain share gradually, while saline’s scale continues to make it central to manufacturing, procurement and hospital inventory planning.
Parenteral Nutrition Solutions Record the Strongest Growth
Parenteral Nutrition Solutions are projected to grow at approximately 6.6% annually through 2031, faster than the broader LVP market because they address more specialized and increasingly complex clinical requirements. These products are used when patients cannot absorb sufficient nutrients through oral or enteral feeding and may include amino acids, glucose, lipid emulsions, electrolytes, vitamins and trace elements delivered separately or through multi-chamber bags. B. Braun and Fresenius Kabi maintain broad nutrition portfolios covering intensive care, oncology, gastrointestinal disease and selected home-treatment pathways, illustrating the category’s expansion beyond short-duration hospital use. Multi-chamber systems also simplify preparation and reduce handling steps by allowing components to remain separated until administration. The combination of greater formulation complexity, higher value per container and growing use among medically complex patients allows nutrition to increase its share gradually even while standard saline and electrolyte fluids continue to dominate total market volume.
By Volume
100–250 mL Remains the Largest Volume Category
The 100–250 mL segment accounts for approximately 39% of market value in 2026, supported by its flexibility across routine fluid therapy, electrolyte products and IV drug administration. These containers provide enough volume for hydration or dilution while allowing clinicians greater dosing control than a full 500 mL or 1,000 mL format. Current manufacturer portfolios reinforce the importance of this range, with B. Braun, Baxter and Fresenius Kabi supplying 100 mL and 250 mL products across sodium chloride, dextrose and balanced electrolyte formulations. The segment benefits from broad hospital usage rather than dependence on a single therapeutic application, giving it a stable demand base through the forecast period. Growth remains slightly below some larger-volume products because market penetration is already extensive, but the versatility of 100–250 mL containers across wards, emergency departments and pharmacy admixture ensures that the segment retains the largest share of market value through 2031.
Above 500 mL Records the Strongest Volume Growth
Above 500 mL products are projected to grow at approximately 5.8% annually through 2031, supported by hydration, maintenance therapy and parenteral nutrition applications requiring sustained fluid delivery. One-litre containers remain common across sodium chloride, dextrose and balanced electrolyte solutions, while specialized nutritional formulations can extend beyond 1,000 mL depending on patient requirements and delivery method. The segment benefits from continued hospital demand but also from the increasing use of multi-chamber nutrition systems and longer-duration infusion therapy. During recent IV-fluid shortages, restoration of larger-volume saline and electrolyte products was treated as a high priority because of their importance across routine inpatient care. These clinical requirements allow the segment to grow slightly faster than lower-volume categories, although 100–250 mL remains larger because it serves a wider range of drug-administration and general hospital applications.
By Application
Fluid & Electrolyte Replacement Remains the Largest Application
Fluid & Electrolyte Replacement accounts for approximately 56% of market value in 2026, making it the dominant application because dehydration, surgery, trauma, sepsis and other acute conditions frequently require intravenous fluid management. The category includes normal saline, balanced crystalloids, dextrose-containing fluids and other formulations used for resuscitation, maintenance and replacement therapy. Its large share reflects broad hospital usage rather than premium pricing, with the same basic products used across emergency departments, operating rooms, critical-care units and general inpatient wards. Demand therefore tracks hospital activity and procedure volumes more closely than pharmaceutical innovation. Although mature, the category continues to grow steadily because healthcare systems are treating larger and more complex patient populations, while improved access to institutional care in emerging markets expands the number of patients receiving IV therapy. The segment’s growth is moderate, but its clinical breadth keeps it firmly at the centre of the LVP market through 2031.
Nutrition Records the Strongest Application Growth
Nutrition is projected to grow at approximately 6.6% annually through 2031, supported by increasing treatment of critically ill, oncology and gastrointestinal patients who cannot meet nutritional requirements through oral or enteral feeding. Parenteral nutrition can provide glucose, amino acids, lipids, electrolytes, vitamins and trace elements over extended periods and is increasingly delivered through multi-chamber systems that simplify hospital preparation while reducing contamination risk. The application is also expanding gradually beyond intensive-care settings into selected long-duration and home-treatment pathways, particularly for patients with chronic intestinal failure or other conditions requiring sustained intravenous support. These clinical requirements make nutrition a smaller but more technically differentiated value pool than routine electrolyte replacement, with higher formulation complexity and greater value per container supporting growth above the overall market rate. As multi-chamber bags and ambulatory infusion systems become more widely available, nutrition gains share without challenging fluid replacement as the largest application.
By Packaging Container
Flexible Plastic Bags Dominate LVP Packaging
Flexible Plastic Bags account for approximately 67% of packaging value in 2026 and remain the principal LVP container because they combine low weight, reduced breakage risk and efficient clinical handling. Unlike rigid containers, flexible bags collapse as the solution is infused, supporting closed-system administration and reducing the need for external air entry. Major manufacturers have also shifted toward non-PVC or non-DEHP materials across parts of their portfolios, with Fresenius Kabi’s freeflex platform and B. Braun’s modern IV-solution systems demonstrating the industry’s emphasis on material compatibility and handling efficiency. Flexible bags are projected to grow at approximately 5.6% annually through 2031, allowing them to increase share gradually as hospitals favour packaging that reduces transport weight and simplifies storage. The category also supports multi-chamber nutrition systems, giving flexible packaging an important role in both routine hydration and higher-value specialized formulations.
Plastic Bottles Form a Distinct Secondary Packaging Segment
Plastic Bottles and Other Rigid Plastic Containers account for approximately 22% of market value in 2026, making them too significant to remain hidden within a generic “other” category. Otsuka pioneered polypropylene IV bottles in Japan, Fresenius Kabi manufactures KabiPac polyolefin containers and Kelun markets collapsible polypropylene bottles for infusion solutions, demonstrating sustained commercial use across major Asian and international markets. Rigid plastic containers offer lower breakage risk than glass while maintaining handling characteristics preferred in some manufacturing and clinical environments. Their growth remains below flexible bags because hospitals continue moving toward lighter collapsible formats, but the segment retains meaningful market value in countries where bottle-based infusion manufacturing is well established. Treating rigid plastic separately also improves market analysis because it distinguishes the broader transition away from glass from the narrower shift toward flexible-bag systems.
By End User
Hospitals Account for the Majority of Market Value
Hospitals account for approximately 72% of LVP market value in 2026 because emergency departments, operating rooms, intensive-care units, oncology wards and general inpatient services collectively consume large volumes of IV fluids, drug diluents and parenteral nutrition products. The industry’s manufacturing and distribution systems are consequently structured primarily around institutional hospital demand, including bulk procurement contracts, distributor inventories and large-volume sterile production. Hospitals also have the widest requirement for product variety because they need standard saline and electrolyte solutions alongside specialized nutrition, drug-administration and critical-care products. Their share moderates gradually as ambulatory treatment and home-based therapies expand, but absolute hospital consumption continues to increase throughout the forecast period. The continuing dominance of hospitals also explains why supply assurance has become such an important competitive factor: interruptions in LVP availability affect multiple clinical departments simultaneously and can force healthcare systems to ration or substitute basic fluids across a broad range of patients.
Home Healthcare Records the Strongest End-User Growth
Home Healthcare is projected to grow at approximately 7.1% annually through 2031, albeit from a small base, as selected long-duration therapies move outside institutional settings. Parenteral nutrition provides the clearest opportunity because clinically stable patients with chronic intestinal failure or other conditions may continue intravenous nutritional support at home after initial hospital treatment. B. Braun provides structured home parenteral nutrition services in selected European markets, while ambulatory pumps and multi-chamber bags from major infusion suppliers make long-duration administration more manageable outside hospitals. Home use remains far more limited than inpatient fluid therapy because patients require careful clinical monitoring, training and supply coordination, but the segment creates a higher-growth distribution channel for specialized LVP products. Its expansion complements rather than replaces hospital demand because treatment typically begins in an institutional setting before suitable patients transition to long-term home management.
Geographical Outlook
North America Remains the Largest Regional Market
North America accounts for approximately 35% of global LVP market value in 2026, supported by high hospital utilisation, extensive surgical activity and widespread intravenous fluid therapy. The United States also contains major manufacturing capacity operated by Baxter, B. Braun and Fresenius Kabi, giving the region a substantial role in both consumption and production. Recent shortages have exposed the disadvantages of concentrated manufacturing, however, with disruption at Baxter’s North Cove site requiring emergency measures including temporary imports and increased output from alternative facilities. This experience is influencing procurement strategies as hospitals place greater emphasis on diversified suppliers and manufacturers strengthen inventory planning. North America’s mature healthcare infrastructure limits the pace of volume expansion relative to Asia Pacific, but high per-patient usage, large hospital systems and greater penetration of specialized nutrition and advanced packaging keep the region the largest value market through 2031.
Asia Pacific Records the Strongest Major-Region Growth
Asia Pacific is projected to grow at approximately 6.3% annually through 2031, supported by expanding hospital infrastructure, rising healthcare expenditure and substantial regional sterile-manufacturing capacity. Japan maintains a mature infusion market led by Otsuka and other established pharmaceutical suppliers, while China has developed large domestic manufacturers including Sichuan Kelun Pharmaceutical and Shijiazhuang No. 4 Pharmaceutical. India combines multinational production with a broad domestic sterile-products industry and continues to use flexible bags, plastic bottles and glass containers across different product categories. The region therefore benefits from both rising consumption and local manufacturing rather than depending heavily on imported LVP products. Lower per-capita healthcare utilisation in several Asian markets also provides greater room for long-term expansion than in North America or Western Europe, allowing the region to gain share gradually while North America remains the largest individual market.
Recent Developments
In August 2026, the U.S. FDA issued a warning letter to Fresenius Medical Care following inspection of its Ogden, Utah facility, citing deficiencies in investigations involving leaking large-volume parenteral bags and requiring a more comprehensive assessment of bag failures and printing-related perforations. The development is commercially significant because flexible bags now represent the majority of LVP packaging and container-integrity failures can remove substantial quantities of essential sterile products from the supply chain. The action reinforces the importance of packaging validation, complaint investigation and manufacturing controls as companies shift further away from traditional glass containers toward advanced plastic systems.
In April 2026, the European Medicines Agency updated its shortage notice for intravenous and irrigation solutions to confirm that the shortage affecting perfusion solutions had been resolved. The European disruption had involved several major suppliers and followed similar supply concerns in the United States, demonstrating that IV-fluid availability has become a broader strategic issue rather than an isolated manufacturing event. The normalization of supply does not eliminate the underlying concentration risk and is likely to keep regulatory attention focused on production capacity, qualified alternative suppliers and inventory resilience.
In December 2025, B. Braun launched its Supply Assurance Program, designed to maintain 45 days of inventory at selected distributor warehouse locations while retaining additional safety stock across its own distribution network. The initiative is notable because it turns supply continuity into an explicit commercial service rather than treating inventory solely as an internal operational issue. For essential products such as saline and balanced electrolyte solutions, hospitals increasingly value predictable availability alongside price, particularly after recent shortages forced institutions to modify fluid-use protocols and seek alternative suppliers.
During 2025 and 2026, major LVP manufacturers continued expanding or emphasizing advanced plastic packaging systems. Fresenius Kabi maintains manufacturing capability across freeflex bags, KabiPac polyolefin bottles and glass containers, while Kelun continues to commercialize collapsible polypropylene infusion bottles and Otsuka maintains both soft-bag and rigid-plastic technologies. The presence of multiple validated packaging architectures confirms that the market is not accurately represented by a simple Glass-versus-Bag split and supports the inclusion of rigid plastic containers as a distinct segment.
Competitive Environment
The Global Large Volume Parenteral Market combines multinational infusion companies with strong regional sterile-manufacturing specialists. Baxter, B. Braun and Fresenius Kabi maintain broad international portfolios covering basic fluids, balanced electrolytes, nutrition and advanced packaging systems, while Otsuka Pharmaceutical Factory has a particularly strong position in Japan and broader Asian clinical nutrition. Chinese manufacturers such as Sichuan Kelun Pharmaceutical and Shijiazhuang No. 4 Pharmaceutical operate substantial infusion businesses and increasingly compete through container technology, scale and exports rather than through low-cost standard fluids alone. India adds a large regional manufacturing base through companies including Aculife Healthcare, Albert David, Akums, Amanta Healthcare, Axa Parenterals and BML Parenteral Drugs. Competition is therefore becoming multidimensional: basic saline and glucose remain highly price sensitive, while manufacturers increasingly differentiate through sterile-manufacturing reliability, flexible or rigid plastic packaging, nutrition portfolios, geographic redundancy and inventory assurance.
Analyst View
The Global Large Volume Parenteral Market remains anchored in routine hospital fluid therapy, while value creation increasingly shifts toward balanced electrolytes, parenteral nutrition and advanced packaging. Sodium Chloride/Saline Solutions remain the largest solution family because of their extensive use across hospital care, while Parenteral Nutrition is gaining importance as medically complex patients require sustained intravenous nutritional support. Flexible Plastic Bags dominate packaging, but rigid plastic bottles retain sufficient scale to warrant independent analysis, particularly in Asian markets. Hospitals remain the principal end user, while Home Healthcare continues developing through longer-duration nutrition and ambulatory therapy. The most important strategic change, however, lies in supply resilience. Recent shortages have shown that manufacturers able to combine sterile-production quality with multiple qualified facilities, modern packaging and stronger inventory availability can create a competitive advantage even in a mature market where many formulations themselves offer limited differentiation.
Large Volume Parenteral Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.01 billion |
| Total Market Size in 2031 | USD 16.64 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.05% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution Type, Volume, Application, Packaging Container |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solution Type
· Sodium Chloride/Saline Solutions
· Balanced Electrolyte Solutions
· Dextrose Solutions
· Parenteral Nutrition Solutions
· Other LVP Solutions
By Volume
· 100 mL–250 mL
· 250 mL–500 mL
· Above 500 mL
By Application
· Fluid & Electrolyte Replacement
· Nutrition
· Vehicle/Diluent for Drug Administration
· Others
By Packaging Container
· Flexible Plastic Bags
· Plastic Bottles/Other Rigid Plastic Containers
· Glass Bottles
By End User
· Hospitals
· Ambulatory/Surgical & Specialty Care
· Home Healthcare
· Others
By Geography
· North America
o United States
o Canada
o Mexico
· South America
o Brazil
o Argentina
o Others
· Europe
o United Kingdom
o Germany
o France
o Italy
o Spain
o Others
· Middle East and Africa
o Saudi Arabia
o UAE
o Israel
o South Africa
o Others
· Asia Pacific
o China
o Japan
o India
o South Korea
o Taiwan
o Thailand
o Indonesia
o Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Sterile Manufacturing and Supply Resilience
3.7. Regulatory Environment
3.8. Analyst View
4. PRODUCT AND PACKAGING OUTLOOK
4.1. Standard Crystalloid Solutions
4.2. Balanced Electrolyte Solutions
4.3. Parenteral Nutrition Systems
4.4. Flexible IV Bags
4.5. Blow-Fill-Seal and Rigid Plastic Containers
4.6. Multi-Chamber Bags
4.7. Container Integrity and Material Compatibility
5. LARGE VOLUME PARENTERAL MARKET BY SOLUTION TYPE
5.1. Introduction
5.2. Sodium Chloride/Saline Solutions
5.3. Balanced Electrolyte Solutions
5.4. Dextrose Solutions
5.5. Parenteral Nutrition Solutions
5.6. Other LVP Solutions
6. LARGE VOLUME PARENTERAL MARKET BY VOLUME
6.1. Introduction
6.2. 100 mL–250 mL
6.3. 250 mL–500 mL
6.4. Above 500 mL
7. LARGE VOLUME PARENTERAL MARKET BY APPLICATION
7.1. Introduction
7.2. Fluid & Electrolyte Replacement
7.3. Nutrition
7.4. Vehicle/Diluent for Drug Administration
7.5. Others
8. LARGE VOLUME PARENTERAL MARKET BY PACKAGING CONTAINER
8.1. Introduction
8.2. Flexible Plastic Bags
8.3. Plastic Bottles/Other Rigid Plastic Containers
8.4. Glass Bottles
9. LARGE VOLUME PARENTERAL MARKET BY END USER
9.1. Introduction
9.2. Hospitals
9.3. Ambulatory/Surgical & Specialty Care
9.4. Home Healthcare
9.5. Others
10. LARGE VOLUME PARENTERAL MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. United Kingdom
10.4.2. Germany
10.4.3. France
10.4.4. Italy
10.4.5. Spain
10.4.6. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. Israel
10.5.4. South Africa
10.5.5. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. Japan
10.6.3. India
10.6.4. South Korea
10.6.5. Taiwan
10.6.6. Thailand
10.6.7. Indonesia
10.6.8. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Manufacturing Footprint Analysis
11.3. Solution Portfolio Analysis
11.4. Packaging Technology Benchmarking
11.5. Supply-Chain and Inventory Strategies
11.6. Mergers, Agreements and Product Developments
11.7. Competitive Dashboard
12. COMPANY PROFILES
12.1. Baxter International Inc.
12.2. B. Braun Melsungen AG
12.3. Fresenius Kabi AG
12.4. Otsuka Pharmaceutical Factory, Inc.
12.5. Sichuan Kelun Pharmaceutical Co., Ltd.
12.6. Shijiazhuang No. 4 Pharmaceutical Co., Ltd.
12.7. JW Pharmaceutical Corporation
12.8. ICU Medical, Inc.
12.9. Aculife Healthcare Pvt. Ltd.
12.10. Albert David Limited
12.11. Akums Drugs & Pharmaceuticals Ltd.
12.12. Amanta Healthcare Ltd.
12.13. Axa Parenterals Ltd.
12.14. BML Parenteral Drugs
12.15. Eurolife Healthcare Pvt. Ltd.
12.16. Nirlife Healthcare
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for the Global Large Volume Parenteral market from 2025 to 2030?
The Global Large Volume Parenteral Market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 5.05%. The market is projected to reach USD 16.64 billion by 2031, growing from an estimated USD 13.01 billion in 2026.
Which application segments hold the largest share and show the fastest growth within the Large Volume Parenteral market?
Fluid & Electrolyte Replacement accounts for the largest share, approximately 56% of market value in 2026. The Nutrition application segment, particularly Parenteral Nutrition Solutions, is projected to be the fastest-growing major solution type, with an annual growth rate of approximately 6.6% through 2031.
What are the dominant volume and packaging segments in the Large Volume Parenteral market, and which segments are experiencing the strongest growth?
The 100–250 mL segment represents the largest share by volume, accounting for approximately 39% of market value in 2026, while the Above 500 mL segment records the strongest growth. In terms of packaging, Flexible Plastic Bags are dominant, representing about 67% of packaging value in 2026, followed by Plastic Bottles and Glass Bottles.
Which geographical regions are identified as the largest and fastest-growing markets for Large Volume Parenterals?
North America remains the largest regional market for Large Volume Parenterals. However, the Asia Pacific region is identified as recording the strongest major-region growth, indicating significant emerging opportunities and market expansion.
What are the key evolving trends and strategic considerations impacting the Large Volume Parenteral market?
The Large Volume Parenteral Market is experiencing a shift in its underlying product mix, with balanced electrolyte products gaining importance alongside the faster growth of Parenteral Nutrition Solutions. Additionally, supply resilience has emerged as a strategically important factor, as highlighted by past disruptions affecting IV-fluid availability.
What are the primary end-user segments for Large Volume Parenterals, and where are the most significant growth opportunities for end-users?
Hospitals represent the largest end-user segment, accounting for approximately 72% of the market value in 2026. Despite its smaller current base, Home Healthcare records the strongest end-user growth, indicating a significant evolving opportunity in patient care outside traditional hospital settings.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Large Volume Parenteral Market – Strategic Insights and Forecasts, 2026–2031. https://www.knowledge-sourcing.com/report/large-volume-parenteral-market