
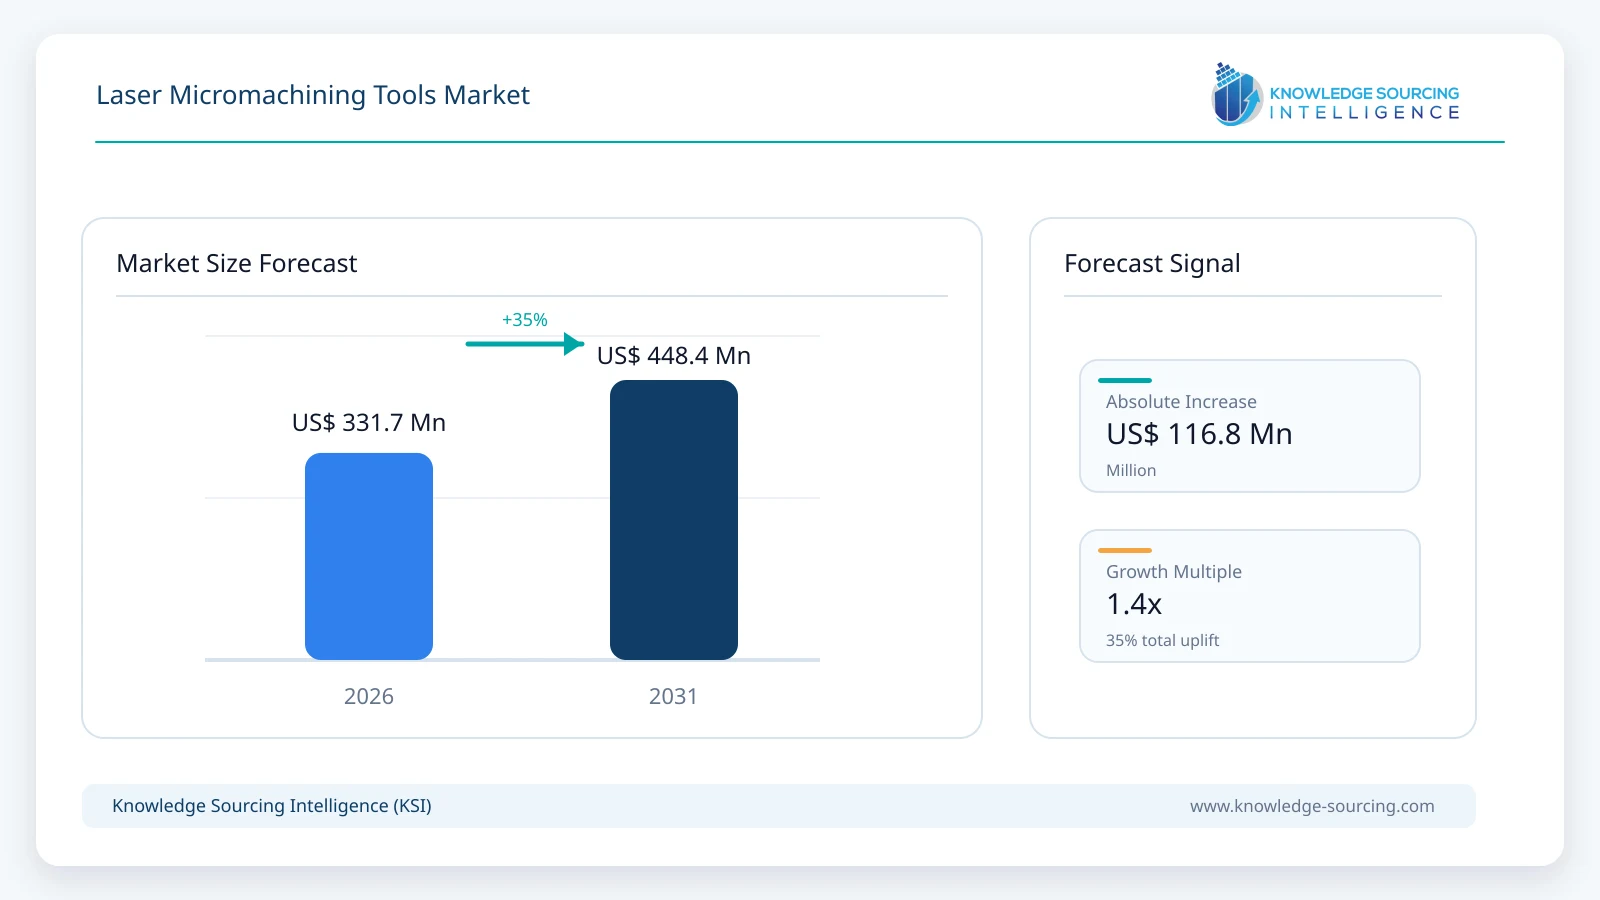
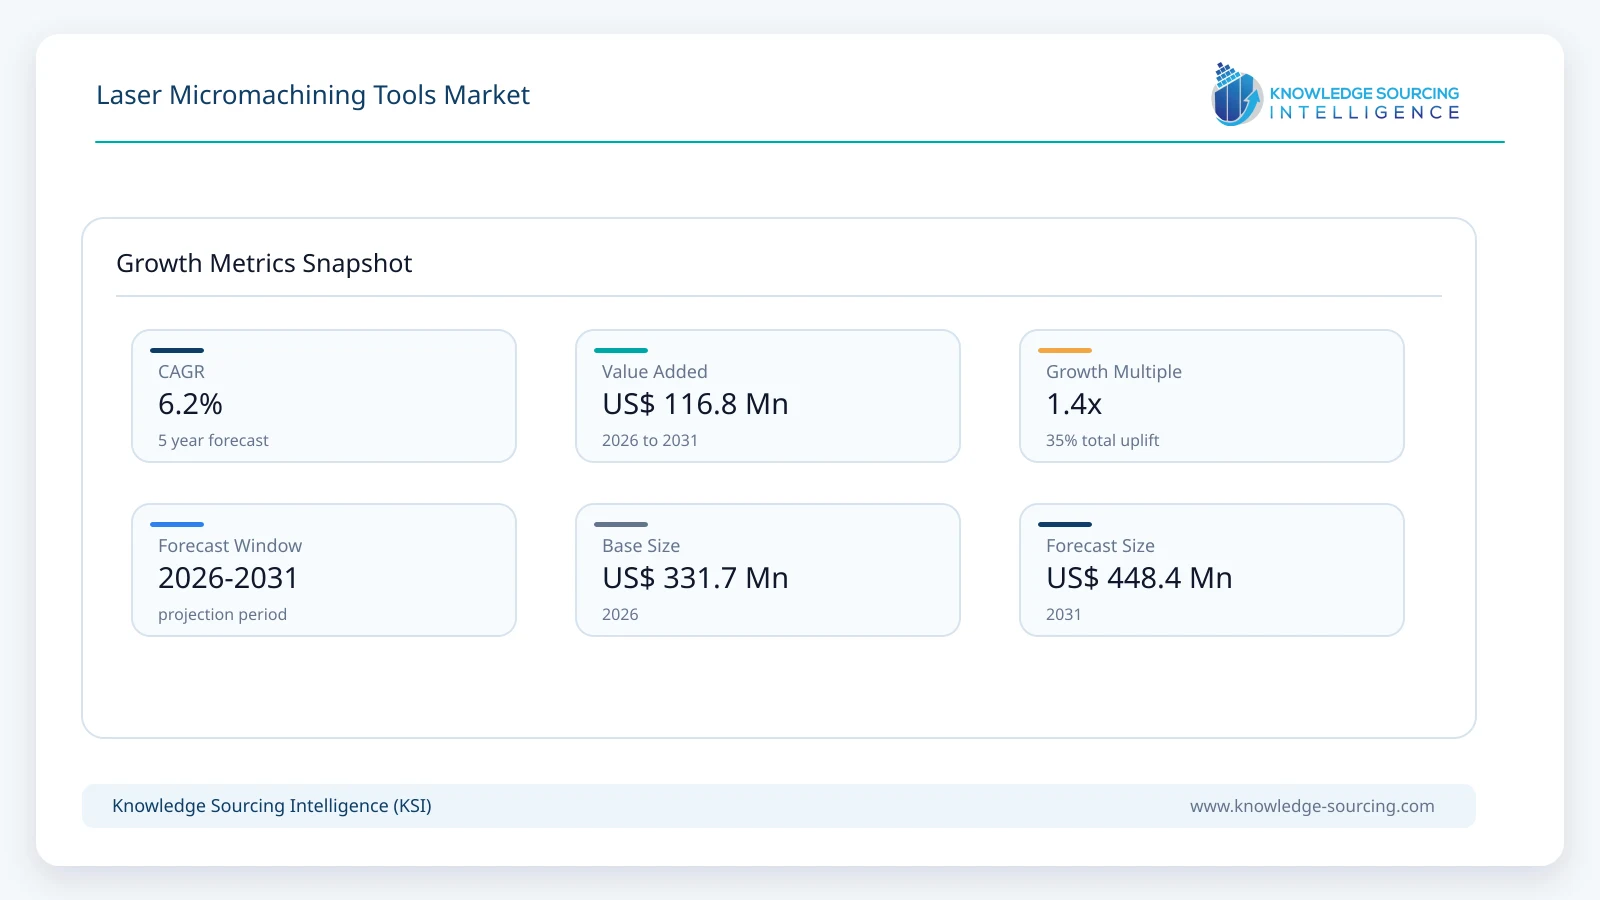
The Laser Micromachining Tools Market is expected to grow from USD 331.67 million in 2026 to USD 448.43 million by 2031, at a CAGR of 6.22% during the forecast period (2026–2031).
Highlights:
- 1Precise laser drilling enables burr-free holes in medical implants for enhanced surgical performance and patient safety.
- 2High-speed cutting of metals optimizes automotive component production while reducing overall manufacturing time.
- 3Advanced micromachining supports microelectronics fabrication through accurate etching and structuring processes.
- 4Contact-free micromachining improves efficiency in aerospace turbine blade repairs by minimizing material waste.
The global laser micromachining tools market is driven by the continued miniaturization of electronic, semiconductor, medical, and energy components, which require feature sizes, edge quality, and thermal-damage limits that conventional mechanical machining cannot achieve. Manufacturers select laser micromachining workstations and turnkey systems based on substrate compatibility, achievable precision, throughput, automation, and process qualification rather than laser-source specifications alone.
Semiconductor singulation and brittle-substrate processing remain core demand areas. 3D-Micromac positions its microDICE platform for thermal laser separation of silicon and silicon carbide wafers and its microSHAPE platform for cutting, drilling and structuring glass and sapphire, illustrating how turnkey systems are engineered around specific substrates.
Medical device manufacturing is a precision-intensive end use. IPG Photonics offers its Versa Small Tube Cutter for tube diameters of 0.25–25 mm with a stated cutting accuracy of ±10 µm, addressing stent, catheter and hypotube production where burr, heat-affected zone, and dimensional tolerance must be validated.
Suppliers differentiate through motion precision and multi-operation capability. Coherent’s ExactCut 430 combines 150/300 W pulsed IR fiber lasers with a stated XY positioning accuracy of ±2 µm, while GFH’s GL.smart integrates drilling, cutting, and laser turning of rotational microcomponents with dual-station processing.
Pulse duration and wavelength flexibility are becoming platform-level choices. Oxford Lasers offers its C Series production systems with nanosecond, picosecond and femtosecond sources at 355, 532 and 1064 nm, allowing process transfer from R&D to volume production on a common machine architecture.
Safety and qualification requirements shape procurement. IEC 60825-1 and ISO 11553-1 govern laser product and laser machine safety, including beam guarding and enclosure requirements, whereas end-use performance, such as dimensional validation of medical microcomponents, requires separate customer-specific process qualification.
AI Impact on the Laser Micromachining Tools Market
Artificial intelligence is transforming laser micromachining from recipe-driven operation towards closed-loop process control and self-optimizing production systems. In the near-term, its primary applications are expected to focus on process development, in-line quality assurance, and improved machine utilization. Furthermore, AI capabilities are increasingly being integrated into software and sensor packages by system integrators rather than being offered standalone products.
Faster process qualification: Machine-learning models trained on pulse energy, repetition rate, scan speed, and focal-position data shorten recipe development for new materials and reduce the number of trial cuts needed before production release.
In-line monitoring and inspection: Coaxial vision, photodiode, and acoustic sensors combined with AI classifiers detect debris, recast, microcracks and burr in real time, enabling adaptive parameter correction and reducing dependence on offline inspection.
Predictive maintenance and uptime: Analytics on laser power drift, optics contamination and chiller performance support condition-based servicing, which is most valuable for fully automated and integrated production systems.
Competitive implication: Vendors able to combine turnkey machines with process software, sensors and data services are better positioned in high-mix semiconductor, medical and battery applications, while standalone and manual systems face pressure to add connectivity and smart-control features.
Key Market Indicators
Indicator | Latest Development | Commercial Meaning |
Semiconductor manufacturing expansion | Ongoing investments in advanced packaging and wafer fabrication globally | Increases demand for micro-drilling, scribing, and precision material processing systems |
Electric vehicle battery production | Rapid expansion of battery cell manufacturing facilities worldwide | Supports demand for laser structuring, welding preparation, and electrode processing |
Medical device miniaturization | Growing use of minimally invasive devices and implantable products | Creates demand for ultra-precise machining with minimal thermal damage |
Ultrafast laser adoption | Rising deployment of picosecond and femtosecond laser systems in precision manufacturing | Improves machining accuracy for high-value applications requiring tight tolerances |
Photonics and optoelectronics production | Increased use of optical components, sensors, and photonic devices | Expands demand for micro-structuring and precision surface processing |
Industrial automation investment | Manufacturing facilities continue integrating automated production systems | Encourages adoption of laser platforms compatible with digital manufacturing environments |
Key indicator: Semiconductor and advanced electronics manufacturing continue to increase the need for micron-scale processing accuracy across wafer, packaging, and component production.
Commercial meaning: Precision requirements are shifting procurement toward higher-performance laser platforms and specialized application solutions.
Market Drivers
Growing electronics and semiconductor manufacturing.
The expansion of semiconductor and electronics manufacturing is a major growth driver for the Laser Micromachining Tools Market. As electronic devices become smaller, more powerful, and increasingly complex, manufacturers need advanced equipment that can process delicate materials with high precision. Laser micromachining tools use focused laser energy to perform operations such as cutting, drilling, scribing, ablation, and surface structuring, making them suitable for manufacturing intricate electronic components and semiconductor devices.
Advanced semiconductor packaging, compact integrated circuits and high-density interconnections require increasingly precise material processing. Depending on the process and material involved, laser micromachining can support applications such as wafer dicing, thin-wafer processing, and microvia formation.
Smartphones, wearable devices, sensors, and other compact electronics require smaller components and finer structural features. Laser tools enable manufacturers to produce precise cuts, holes, and patterns in thin substrates and delicate materials that may be difficult to process using conventional mechanical techniques.
Laser processing is a non-contact manufacturing method, which reduces mechanical forces on workpieces and avoids conventional cutting-tool wear. Ultrafast laser systems can also limit heat transfer to surrounding material when appropriately configured, making them valuable for applications involving sensitive components.
Continued investment in semiconductor fabrication, electronics production, and advanced packaging increases the need for specialized precision manufacturing equipment. This supports demand for laser micromachining tools offering accurate processing, repeatability, and compatibility with increasingly complex materials and component designs.
Growing adoption of ultrafast laser technologies.
Picosecond and femtosecond lasers have gained commercial importance because they reduce heat-affected zones and enable processing of sensitive materials with minimal damage. Research and industrial deployment continue expanding across photonics, semiconductor manufacturing, medical devices, and advanced materials processing. Ultrafast laser systems are increasingly selected for applications where conventional laser technologies struggle to meet quality specifications.
Expansion of electric vehicle and battery manufacturing capacity.
Battery manufacturing requires highly controlled material processing for electrode preparation, current collector structuring, insulation processing, and component marking. Manufacturers are investing heavily in production capacity and automation, creating demand for precision laser systems capable of maintaining throughput while supporting increasingly complex battery designs.
Increasing complexity of medical devices.
Medical device manufacturers continue developing smaller implants, diagnostic instruments, microfluidic systems, and minimally invasive surgical tools. These products often require burr-free machining, high dimensional accuracy, and strict quality control. Laser micromachining provides processing capabilities that support regulatory and performance requirements without introducing excessive mechanical deformation.
Growth of photonics and precision optics manufacturing.
Optical communication systems, photonic integrated circuits, laser components, sensors, and imaging devices require precise micro-structuring of glass, ceramics, and specialized materials. The growing importance of photonics in telecommunications, sensing, industrial automation, and scientific applications continues to support investment in advanced laser processing technologies.
Market Restraints and Challenges
High capital investment requirements.
Ultrafast laser systems, precision motion platforms, beam delivery components, and process monitoring equipment require substantial upfront investment. Smaller manufacturers often face challenges justifying expenditures when production volumes remain uncertain. Capital intensity can extend procurement cycles and limit adoption among cost-sensitive users.
Complex process development and qualification.
Achieving optimal machining performance frequently requires extensive parameter optimization for specific materials and applications. Semiconductor, aerospace, and medical customers often impose lengthy qualification procedures before approving new manufacturing processes. These requirements increase implementation costs and slow commercialization timelines.
Shortage of specialized technical expertise.
Operating advanced laser micromachining systems requires expertise in optics, materials science, process engineering, automation, and quality control. Recruiting and retaining qualified personnel remains difficult in many manufacturing regions. The skills gap can limit equipment utilization and increase training costs.
Supply chain dependence for critical optical components.
Laser sources, precision optics, motion systems, and control electronics often depend on specialized suppliers. Component shortages, trade restrictions, and geopolitical tensions can affect production schedules and lead times. Manufacturers continue diversifying supply chains to reduce exposure to these risks.
Competition from alternative precision manufacturing technologies.
Micro milling, electrical discharge machining (EDM), chemical etching, and additive manufacturing technologies remain viable alternatives for certain applications. Buyers frequently evaluate these processes against laser solutions based on cost, throughput, material compatibility, and production scale requirements.
Laser Micromachining Tools Market Segment Analysis
Electronics and Semiconductor Manufacturing
Among end-user categories, electronics and semiconductor manufacturing represents one of the most commercially important demand segments for laser micromachining tools. Semiconductor fabrication, advanced packaging, printed circuit board production, display manufacturing, and sensor fabrication all require processing capabilities that can achieve increasingly smaller feature sizes while maintaining production consistency.
Purchasing criteria within this segment differ from many industrial applications. Yield improvement, process repeatability, contamination control, and equipment uptime often receive greater emphasis than initial acquisition cost. Manufacturers frequently evaluate laser systems based on their ability to integrate into automated production lines and support high-volume manufacturing environments.
Ultrafast lasers are receiving increased attention within semiconductor and electronics applications because they can process fragile substrates with reduced thermal effects. Advanced packaging technologies, microvias, wafer scribing, and precision structuring applications continue to create demand for high-performance laser platforms capable of supporting evolving production requirements. Suppliers with strong application engineering capabilities often gain an advantage because customers require process optimization alongside equipment procurement.
Aerospace and Defense
Aerospace and defense segment is expected to show considerable growth, fueled by the increasing use in manufacturing precision aerospace components.
Strong focus on precision components adoption in aerospace applications ranging from fuel systems to aerospace electronics supports the market outlook. Companies such as GFH GmbH have capitalized on this trend through their 5-axis “GL.evo” and 16-axis “GL.smart”.
Growth in global aircraft shipments, which, according to the General Aviation Manufacturers Association (GAMA), reached 791 units in Q1 2026, showcasing near 18% growth over Q1, further support greater adoption of laser micromachining tools in aerospace.
Strategic supply partnerships between market players and global aircraft manufacturers, namely Airbus and Boeing, followed by the establishment of laser micromachining laboratories in collaboration with global defence technology developers like Lockheed Martin, propel the laser micromachining adoption.
Bolstering growth in defense spending, which reached nearly USD 2,887 billion in 2025 and has experienced continued progression over the years, has improved the development of controlled laser processing for defense electronics and avionics.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
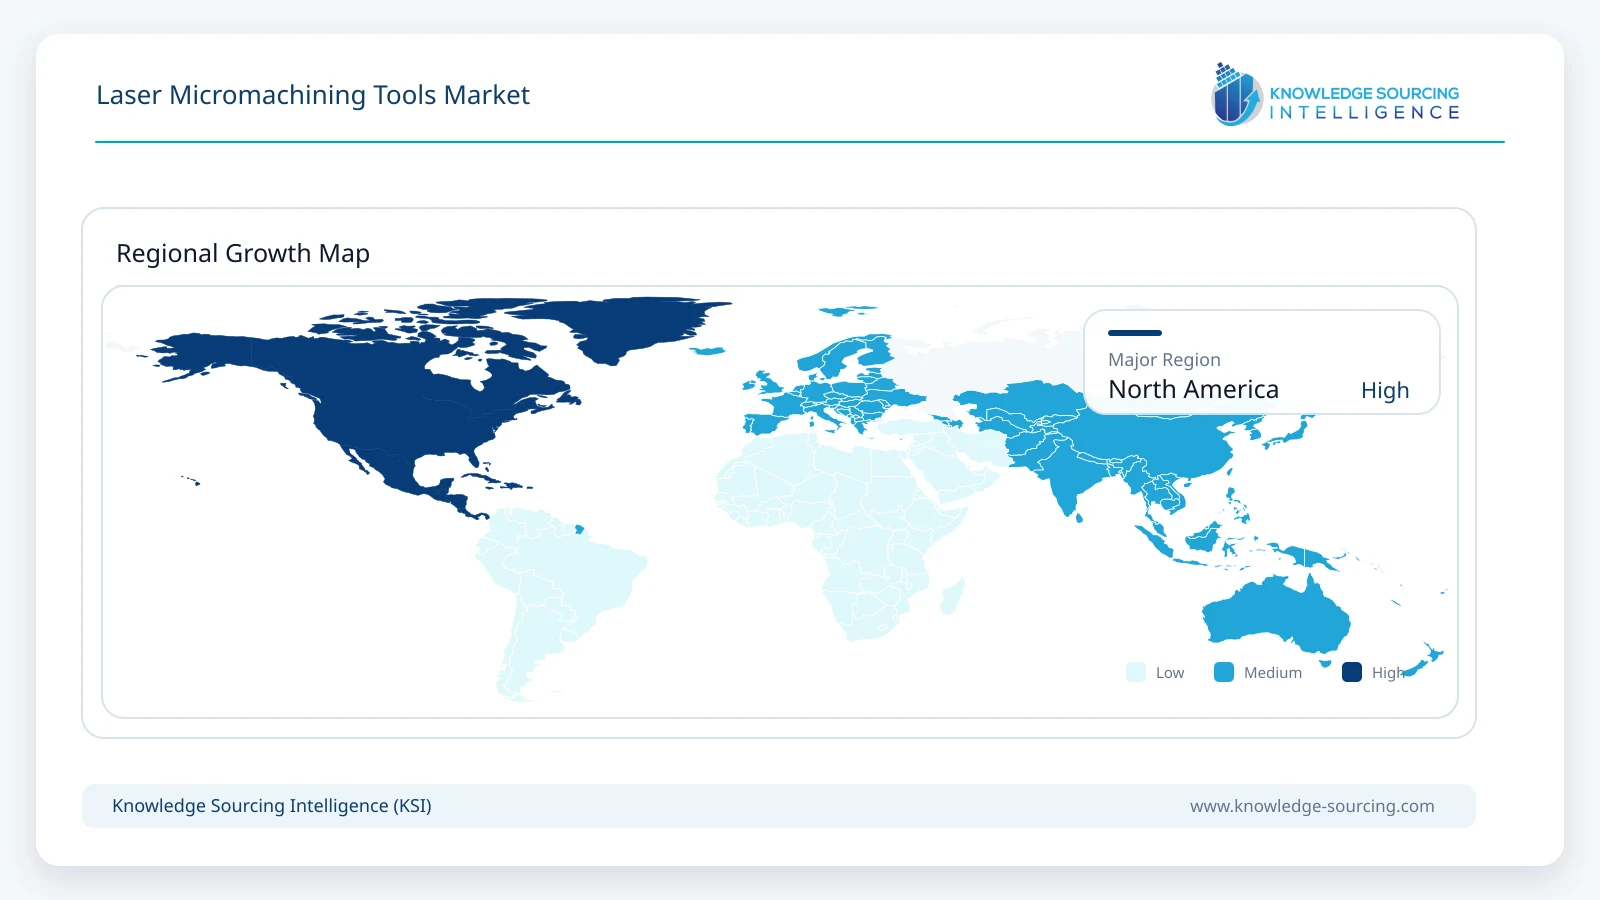
North America | Semiconductor, aerospace, defense, and medical manufacturing investment | High operating and labor costs |
Europe | Precision engineering, automotive, photonics, and industrial automation | Energy costs and industrial economic uncertainty |
Asia Pacific | Electronics manufacturing, semiconductor capacity expansion, battery production | Intense pricing competition |
Middle East & Africa | Emerging industrial diversification and manufacturing investment | Limited specialized manufacturing infrastructure |
North America
The United States remains an important market due to its concentration of semiconductor facilities, aerospace manufacturers, medical device companies, and research institutions. Government-supported semiconductor manufacturing investments and domestic supply chain initiatives continue supporting demand for advanced manufacturing technologies. Buyers typically prioritize automation, process validation, and service support capabilities.
Dominating the global technological outlook, US industrial initiatives, including “Manufacturing Extension Partnership (MEP)” support the adoption of advanced-laser processing technologies in major sectors, such as electronics, automotive, and aerospace & defence.
Likewise, the country pioneers global defence expenditure with nearly 33% of total spending (According to the 2025 SIPRI Fact Sheet), which could further expand market opportunities for laser micromachining for defense electronics development.
The implementation of the “CHIPS and Science Act” outlines the framework to propel domestic chip manufacturing in the US, which is expected to drive the laser micromachining tools for precision welding & drilling in miniaturized devices and advanced packaging.
Booming AI integration and digital automation supported by the “AI Action Plan” supports new innovations such as the recent launch of AI-powered “WELDForm” and “Automatic Parameter Tuning” by nLIGHT Inc. to bolster advanced battery manufacturing.
Supportive initiatives implemented by the Advanced Materials and Manufacturing Technologies Office (AMMTO) are expected to foster competitive R&D and demonstrative laser development for clean energy in the US, thereby accelerating market expansion.
Europe
Germany, France, the United Kingdom, and Italy maintain strong positions in industrial manufacturing, automotive production, photonics, and precision engineering. European demand is characterized by a focus on production quality, energy efficiency, and advanced automation. Several laser technology suppliers and photonics specialists maintain substantial manufacturing and research activities within the region.
Asia Pacific
China, Japan, South Korea, and Taiwan represent critical demand centers due to their extensive electronics and semiconductor manufacturing ecosystems. Battery production expansion, display manufacturing, consumer electronics production, and government-backed industrial development programs continue driving equipment demand. The region also contains a growing number of domestic laser technology suppliers competing alongside international manufacturers.
Middle East and Africa
Industrial diversification initiatives, aerospace investments, and expanding manufacturing capabilities support selective demand for precision processing technologies. Adoption remains concentrated within higher-value manufacturing activities rather than broad industrial deployment.
South America
Brazil remains the largest regional manufacturing center, with demand concentrated in automotive, electronics assembly, medical devices, and industrial production. Investment levels remain lower than those observed in North America, Europe, or Asia Pacific, but specialized applications continue creating opportunities for precision manufacturing technologies.
Competitive Landscape
The laser micromachining tools market exhibits characteristics of a technology-driven industry where performance, process expertise, and application support often outweigh pure price competition. Entry barriers remain relatively high due to optical engineering requirements, application knowledge, intellectual property, and customer qualification processes.
Companies such as TRUMPF SE + Co. KG, Coherent Corp., and IPG Photonics Corporation compete through laser source technology, global service networks, application expertise, and manufacturing scale. Their portfolios frequently extend beyond micromachining equipment, allowing broader customer engagement across industrial laser applications.
Specialized providers including 3D-Micromac AG, LASEA Group, GFH GmbH, and Oxford Lasers Ltd. focus on niche applications requiring advanced process development and customization.
Competition increasingly centers on:
Ultrafast laser performance
Automation integration capabilities
Application-specific process expertise
Software and process control functionality
Global service and support coverage
Manufacturing throughput improvements
Multi-material processing capability
Partnerships with automation providers, semiconductor equipment manufacturers, and research organizations continue to shape product development strategies across the industry.
Recent Developments
April 2026: TRUMPF introduced the TruLaser Tube 7000 fiber laser tube-cutting machine to the North American market, featuring 9 kW laser power, higher productivity, enhanced flexibility, and improved precision processing of complex tube geometries.
March 2026: Coherent announced new 700mW uncooled 980nm micro-pump lasers, extending its compact laser platform portfolio with higher efficiency and power density, supporting next-generation precision photonics and laser-based manufacturing systems.
January 2026: Coherent Corp launched the Sapphire XT visible laser platform on January 15, 2026, delivering a compact 1 W OPS laser solution supporting advanced life science applications—such as super-resolution microscopy and DNA sequencing—as well as semiconductor processing innovations.
January 2026: IPG Photonics announced at SPIE Photonics West (January 20, 2026) that it would showcase new laser sources and integrated technologies for micro-machining, expanding precision manufacturing capabilities across industrial and scientific applications.
January 2026: Coherent Corp. introduced a germanium-free electro-optic modulator for CO? laser via drilling. The technology supports sub-microsecond pulse generation at laser powers up to 300 W.
Regulatory and Policy Environment
Laser micromachining tools operate within a framework of industrial safety regulations, laser classification standards, worker protection requirements, export controls, and industry-specific manufacturing standards. Compliance requirements vary by application and geography.
Medical device manufacturing requires validation and documentation standards that influence equipment qualification procedures. Aerospace applications often require extensive process verification and traceability. Semiconductor customers typically impose strict contamination control and process consistency requirements throughout the manufacturing chain.
Export controls affecting advanced manufacturing technologies and photonics equipment continue influencing supplier strategies, particularly in markets involving semiconductor production and defense-related applications. Companies increasingly evaluate regional manufacturing footprints and supply chain resilience as part of long-term planning.
Outlook and Strategic Implications
Demand fundamentals remain closely tied to manufacturing precision requirements rather than general industrial production growth. Semiconductor expansion, electronics miniaturization, battery manufacturing investment, and medical device innovation are expected to remain the most influential demand drivers during the forecast period.
Suppliers that combine laser technology with process expertise, automation integration, and application support are likely to strengthen their competitive position. Equipment performance alone is becoming less decisive as customers increasingly seek complete manufacturing solutions.
Key strategic considerations include:
Expansion of ultrafast laser adoption across industrial applications.
Increased integration of laser systems into automated production environments.
Greater emphasis on application-specific engineering support.
Supply chain diversification for critical optical and electronic components.
Continued investment in semiconductor, battery, and photonics manufacturing.
Market performance through 2031 will depend largely on the pace of advanced manufacturing investment, the commercialization of next-generation semiconductor and battery technologies, and the industry's ability to deliver precision processing solutions at commercially viable production speeds.
Market Segmentation
By Laser Type
Fiber Lasers
Ultraviolet (UV) Lasers
Solid-State Lasers
CO2 Lasers
Others
By Machine Configuration
Standalone/Manual Systems
Semi-Automated Systems
Fully Automated & Integrated Production Systems
Others
By Application
Drilling
Cutting & Milling
Marking & Engraving
Scribing
Texturing & Patterning
Structuring
Others
By End-User
Automotive
Aerospace and Defense
Medical Devices & Healthcare
Electronics and Semiconductor Manufacturing
Optoelectronics and Photonics
Energy and Battery Manufacturing
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
South Africa
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory, Safety Standards & Certification Landscape
4.2. Global Laser Micromachining Tools Manufacturing & Equipment Ecosystem
4.3. Laser Micromachining Equipment Shipment & Deployment Analysis
4.4. Supply Chain Analysis
4.5. AI Adoption & Integration in Laser Micromachining Systems
4.6. Strategic Recommendations
5. TECHNOLOGICAL OUTLOOK
5.1. Advancement in laser architecture and wavelength selection
5.2. AI-enabled process control
5.3. Enhanced beam-delivery and motion control techologies development
5.4. Digital Integration and Manufacturing Scalability of Standalone Lasers
6. LASER MICROMACHINING TOOLS MARKET BY LASER TYPE (2021-2031)
6.1. Introduction
6.2. Fiber Lasers
6.3. Ultraviolet (UV) Lasers
6.4. Solid-State Lasers
6.5. CO2 Lasers
6.6. Others
7. LASER MICROMACHINING TOOLS MARKET BY MACHINE CONFIGURATION (2021-2031)
7.1. Introduction
7.2. Standalone/Manual Systems
7.3. Semi-Automated Systems
7.4. Fully Automated & Integrated Production Systems
7.5. Others
8. LASER MICROMACHINING TOOLS MARKET BY APPLICATION (2021-2031)
8.1. Introduction
8.2. Drilling
8.3. Cutting & Milling
8.4. Marking & Engraving
8.5. Scribing
8.6. Texturing & Patterning
8.7. Structuring
8.8. Others
9. LASER MICROMACHINING TOOLS MARKET BY END-USER (2021-2031)
9.1. Introduction
9.2. Automotive
9.3. Aerospace and Defense
9.4. Medical Devices & Healthcare
9.5. Electronics and Semiconductor Manufacturing
9.6. Optoelectronics and Photonics
9.7. Energy and Battery Manufacturing
9.8. Others
10. LASER MICROMACHINING TOOLS MARKET BY GEOGRAPHY (2021-2031)
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. Germany
10.4.2. France
10.4.3. United Kingdom
10.4.4. Spain
10.4.5. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. South Africa
10.5.3. UAE
10.5.4. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. India
10.6.3. Japan
10.6.4. South Korea
10.6.5. Taiwan
10.6.6. Indonesia
10.6.7. Thailand
10.6.8. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
11.5. Integrated Equipment Benchmarking & Capability Comparison
11.6. AI Capabilities, Software Integration & Smart Manufacturing Initiatives
12. COMPANY PROFILES
12.1. 3D-Micromac AG
12.2. Coherent Corp.
12.3. IPG Photonics Corporation
12.4. AMADA Weld Tech
12.5. CHARMILLES (UNITED MACHINING SOLUTIONS)
12.6. TRUMPF SE + Co. KG
12.7. Han's Laser Technology Industry Group Co., Ltd.
12.8. LASEA Group
12.9. Oxford Lasers Ltd.
12.10. GFH GmbH
13. RESEARCH METHODOLOGY
14. LIST OF FIGURES
15. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











