
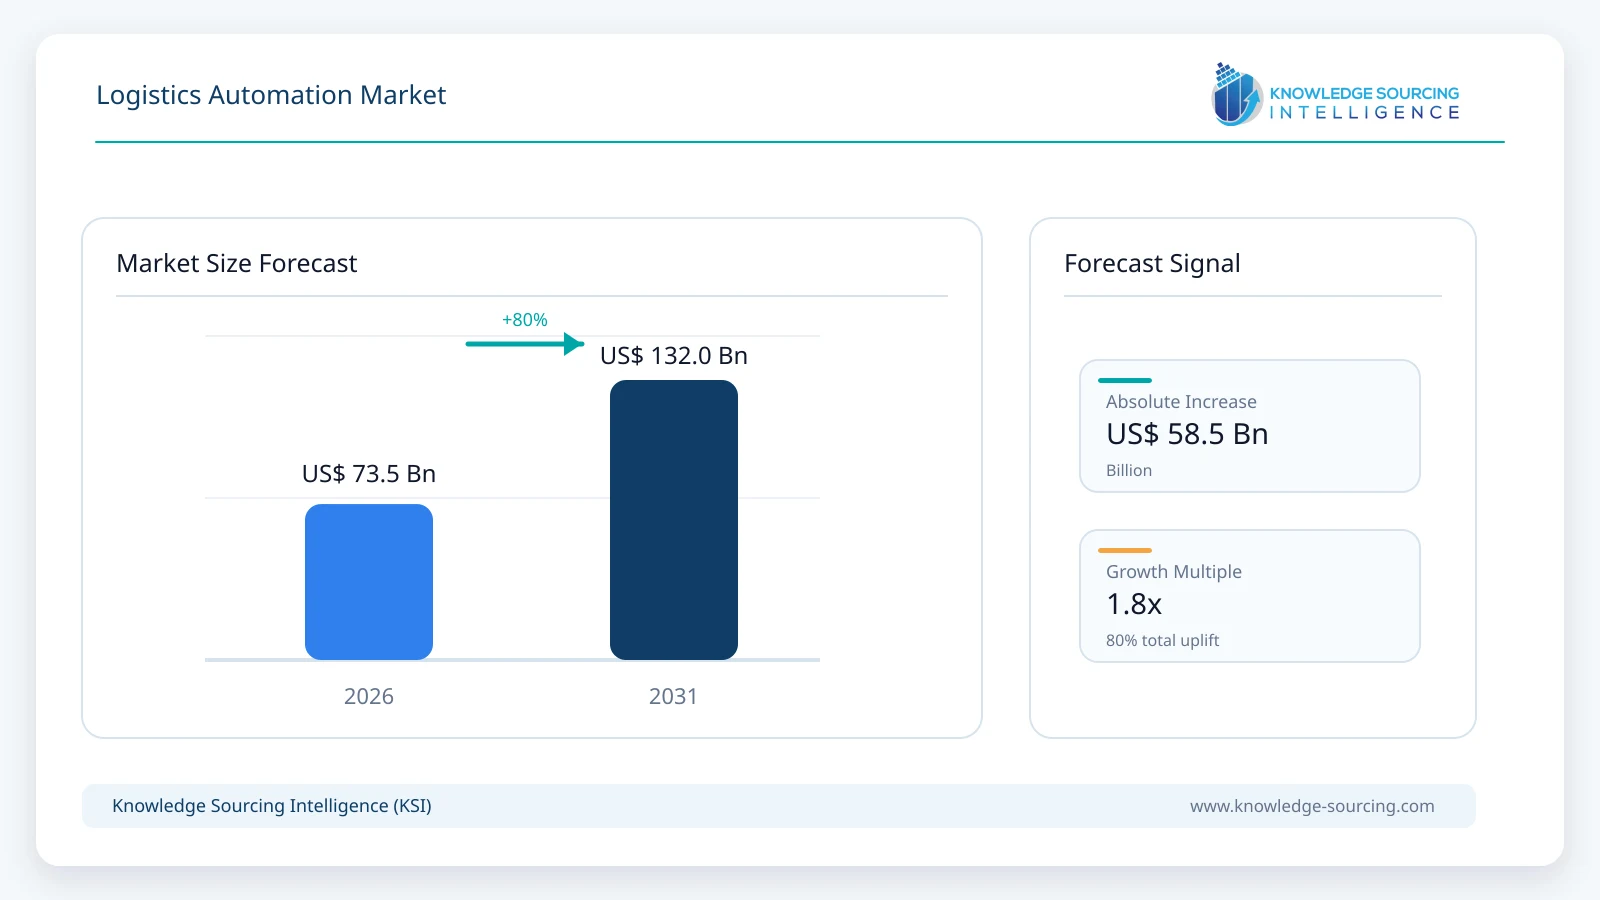
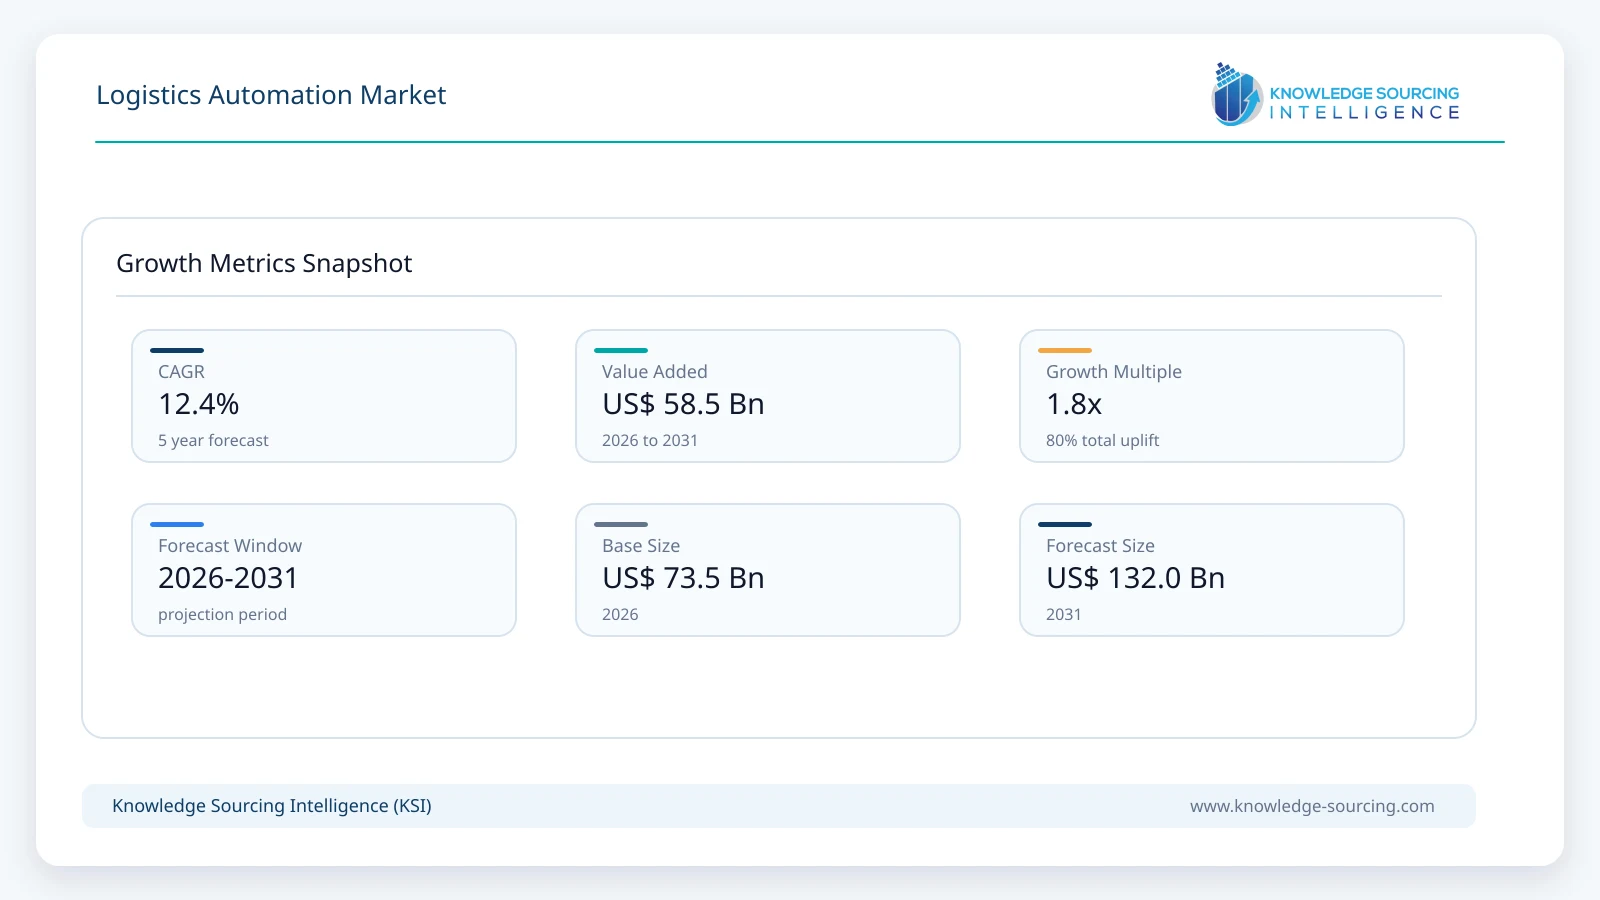
The global logistics automation market is forecast to grow from USD 73.5 billion in 2026 to USD 132.0 billion in 2031, representing a CAGR of 12.4% over the forecast period.
Highlights:
- 1Hardware is estimated to account for approximately 62.0% of global logistics automation revenue in 2026 because AS/RS, conveyors, sortation, robotics, AMRs and other physical systems remain the largest project cost components.
- 2Large enterprises are estimated to generate approximately 69.0% of global market spending in 2026 due to high-volume distribution networks, multi-site automation programs and the capital required for large integrated projects.
- 3Warehouse and storage management applications are estimated to account for approximately 76.0% of global market revenue in 2026, reflecting the concentration of automation investment inside fulfillment centers, distribution centers and production logistics.
- 4Retail is estimated to represent approximately 29.0% of global market revenue in 2026 as e-commerce, omnichannel fulfillment and grocery distribution continue to drive high-throughput automation projects.
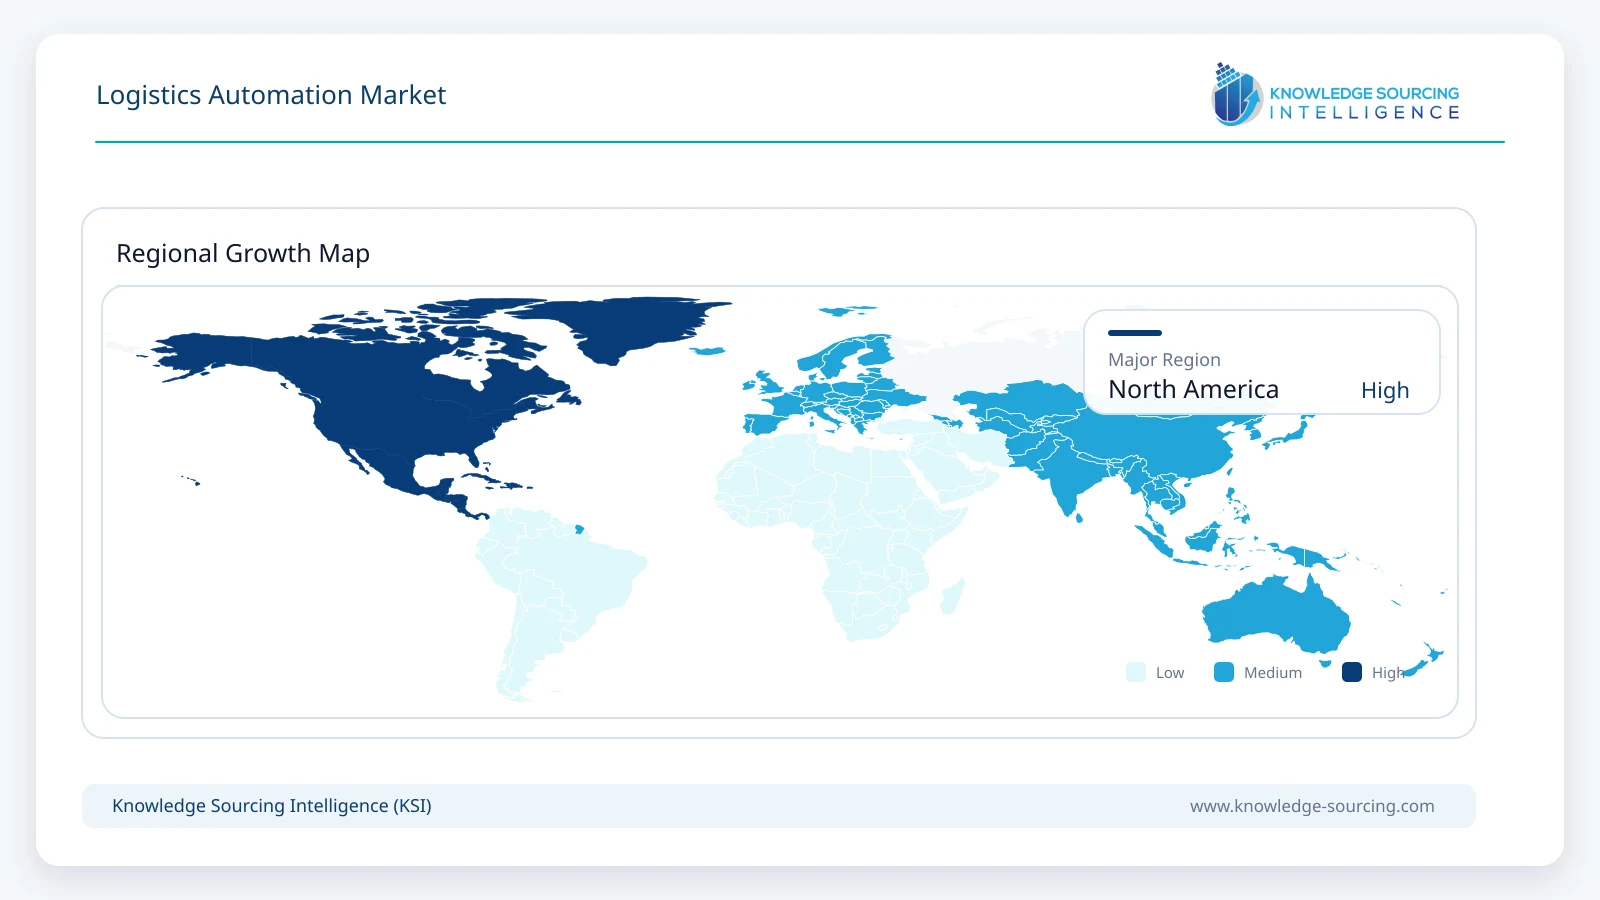
- 5North America is estimated to account for approximately 34.0% of global market revenue in 2026, supported by e-commerce, labor constraints, large distribution networks and continued investment in high-density warehouse automation.
- 6The 2026 technology cycle is shifting from isolated machines toward integrated orchestration-vendors are combining AS/RS, AMRs, robotic picking, sortation and warehouse-execution software within one coordinated automation layer.
Current vendor scale supports a large and rapidly expanding market. KION reported EUR 3.07 billion of 2025 revenue in Supply Chain Solutions, including Dematic project and service activity, with order intake up 39.5%. KNAPP reported EUR 2.135 billion of turnover in FY 2025/26 and EUR 2.51 billion of order intake. Daifuku published its 2026 integrated report against a backdrop of continued automation investment, while AutoStore, Exotec, Symbotic and other robotics-focused companies continue expanding high-density goods-to-person systems.
The industry is moving from fixed automation versus flexible robotics toward hybrid systems. Large facilities increasingly combine conveyors and AS/RS for predictable high-volume flow with AMRs, robotic arms and software orchestration for variable tasks. This allows operators to preserve high throughput while adapting to changing SKU mixes, channels and peak demand.
Labor availability remains a structural driver, but the buying decision is becoming more disciplined. After rapid post-pandemic investment, customers are focusing more heavily on payback, scalability, service support and the ability to expand automation without rebuilding entire facilities. Modular systems and software-defined orchestration therefore gain importance.
Market Trends
Warehouse Execution Software Becomes the Orchestration Layer
Automation projects increasingly require software that coordinates storage, robots, conveyors, picking stations and labor in real time. Warehouse execution systems sit between enterprise planning applications and physical automation, making decisions about order sequencing, routing and equipment utilization.
AI is beginning to extend this layer from prediction toward real-time task allocation and exception handling. Vendors are investing in agentic and data-driven orchestration, but customers still require deterministic controls for safety-critical equipment.
Modular Goods-to-Person Systems Expand
High-density cube storage, mobile-rack robotics and shuttle systems are growing because they can increase storage density and reduce walking. AutoStore and Exotec are prominent examples of modular goods-to-person architectures that can add robots, bins or stations as demand increases.
Modularity lowers the risk of committing to one fixed capacity level and allows automation to be deployed in both new facilities and existing buildings with constrained footprints.
Robotics Move Beyond Transport into Picking and Handling
AMRs are now widely used for horizontal movement, while robotic arms are expanding into depalletization, piece picking, induction and palletizing. Better vision and machine learning allow automation to handle a wider range of package shapes and product variability.
This expands automation upstream and downstream from storage systems, increasing the proportion of warehouse workflows that can operate with reduced manual handling.
Automation-as-a-Service Broadens Access
Robotics-as-a-Service and subscription-style commercial models allow customers to deploy flexible robots with lower upfront capital. This is particularly useful for seasonal operations or facilities where demand can change quickly.
Large fixed systems remain capital-intensive, but service-based models are broadening automation adoption among smaller sites and creating recurring revenue for robotics vendors.
Logistics Automation Market Segment Analysis
By Component
Hardware
Hardware is estimated at approximately USD 45.57 billion in 2026. The segment includes AS/RS equipment, conveyors, sorters, shuttles, AMRs, AGVs, robotic arms, automated pallet systems, sensors and other physical automation components.
Hardware remains the largest value pool because major distribution-center projects require substantial mechanical and robotic infrastructure. Software and services are gaining importance, but the physical system still represents the majority of project capital expenditure.
By Enterprise Size
Large Enterprises
Large enterprises are estimated at approximately USD 50.72 billion in 2026. Major retailers, manufacturers, wholesalers, parcel operators and 3PLs operate high-volume networks where automation can be standardized across multiple facilities.
These organizations can support multi-year capital programs and often require integrated systems combining storage, sortation, robotics, software and lifecycle services. Smaller enterprises increasingly adopt modular automation, but large customers remain the dominant revenue source.
By Application
Warehouse and Storage Management
Warehouse and storage management applications are estimated at approximately USD 55.86 billion in 2026. This includes receiving, storage, replenishment, picking, sortation, packing and internal material movement within distribution and fulfillment facilities.
The segment dominates because most physical automation is deployed inside buildings rather than in long-haul transportation. High-density storage and goods-to-person systems continue to gain share as facilities seek more throughput from limited floor space.
By End-User Industry
Retail
Retail is estimated at approximately USD 21.32 billion in 2026. E-commerce, omnichannel fulfillment, grocery distribution and direct-to-consumer operations require high order accuracy, short cut-off times and the ability to manage large SKU counts.
Retail automation spans large regional distribution centers, store-replenishment facilities and smaller urban fulfillment sites. The sector remains an important early adopter of goods-to-person robotics and high-speed sortation.
By Geography
North America
North America is estimated at approximately USD 24.99 billion in 2026. The region combines large e-commerce and retail networks with high warehouse labor costs and strong investment by grocery, wholesale, healthcare and third-party logistics operators.
Symbotic, Honeywell Intelligrated, Dematic, AutoStore integrators, Exotec and other vendors are expanding deployments across the region. Large facilities increasingly prioritize dense storage, scalable robotics and software orchestration.
Market Drivers
Labor Availability and Operating Cost Pressure
Warehouses face persistent difficulty recruiting and retaining workers for repetitive picking, transport and pallet-handling tasks. Automation reduces walking, lifting and repetitive movement while allowing labor to focus on exceptions and value-added work.
Higher wages and safety expectations improve the return on automation investments, particularly in large facilities operating multiple shifts.
E-Commerce and Omnichannel Fulfillment
Consumers expect shorter delivery windows while retailers manage both store replenishment and individual e-commerce orders from increasingly connected inventory pools. This increases order complexity and peaks.
Goods-to-person storage, sortation and orchestration software help facilities process more order lines with higher accuracy and less travel.
Warehouse Space and Storage Density
Industrial real-estate costs make cubic utilization increasingly valuable. High-density AS/RS and robotic storage systems can increase the number of SKUs stored within an existing footprint.
This is particularly attractive in urban and high-cost logistics markets where expanding a building can be more expensive than automating it.
AI, Vision and Robotics Performance
Improved machine vision, motion planning and AI are expanding the tasks that robots can perform reliably. Robotic arms can handle a wider range of parcels and products, while AMRs navigate more dynamic environments.
Software improvements also increase utilization of installed equipment by optimizing task assignment, routing and order sequencing.
Market Restraints
High Upfront Capital and Payback Requirements
Large automation projects can require substantial investment in equipment, software, building modifications and integration. Customers increasingly require clear throughput, labor and service-level benefits before approving projects.
Economic uncertainty can delay projects even when the long-term business case remains attractive.
Integration Complexity
Automation must integrate with warehouse management systems, enterprise systems, inventory data and existing material-handling equipment. Brownfield facilities may contain several generations of controls and interfaces.
Complex integration can extend commissioning schedules and increase dependence on experienced systems integrators.
Demand Volatility and SKU Complexity
Facilities must handle changes in product mix, packaging, order size and seasonal peaks. Highly fixed automation can underperform when the operating profile changes substantially.
This encourages modular designs but can make capacity planning more difficult for long-lived systems.
Service and Maintenance Dependence
Highly automated facilities rely on equipment uptime. A failure in storage, sortation or control software can affect a large portion of operations.
Customers therefore require strong local service, spare-parts availability, remote diagnostics and lifecycle support, raising the barrier for smaller vendors entering mission-critical deployments.
Regional Outlook
North America
North America is a leading market for high-value warehouse automation because of labor costs, large distribution networks and strong e-commerce penetration. Retail, grocery, wholesale and healthcare distribution are important customers.
Exotec announced major 2026 deployments with Komar Distribution Services and other operators, while Symbotic continues to expand AI-enabled robotic systems for large retail and wholesale networks.
Europe
Europe has a dense automation-vendor ecosystem including KNAPP, SSI Schaefer, TGW, Swisslog, Vanderlande and Dematic operations. Germany, the Netherlands, Austria, France, the United Kingdom and the Nordics are important demand centers.
High labor costs, limited warehouse space and strong manufacturing sectors support both fixed and flexible automation.
Asia Pacific
Asia Pacific combines large manufacturing and e-commerce markets with major automation suppliers such as Daifuku and Geek+. China, Japan, South Korea, Australia, India and Southeast Asia are expanding both greenfield and retrofit automation.
Exotec entered the South Korean market with a 2026 MUSINSA project, illustrating continued expansion of European robotics providers into the region.
Middle East and Africa
Gulf countries are investing in automated logistics hubs, e-commerce fulfillment and pharmaceutical distribution as part of broader infrastructure and diversification programs.
African adoption remains more selective and is concentrated in large retailers, food and beverage, mining supply chains and multinational distribution operations.
South America
Brazil and other major markets are adopting automation in retail, manufacturing, food and beverage and third-party logistics. High labor variability and large distribution distances can support automation in high-volume hubs.
Currency and financing conditions influence project timing, creating demand for scalable and modular systems.
Competitive Environment
The market includes large integrated material-handling groups and rapidly growing robotics specialists. Daifuku, Dematic, Vanderlande, KNAPP, SSI Schaefer, Swisslog, Honeywell Intelligrated and TGW compete for large integrated warehouse projects, while AutoStore, Exotec, Symbotic, Geek+, GreyOrange and other specialists differentiate through modular or robotics-led architectures.
KION reported EUR 3.07 billion of 2025 Supply Chain Solutions revenue and a 39.5% increase in order intake, while KNAPP reported EUR 2.135 billion of FY 2025/26 turnover and EUR 2.51 billion of order intake. These figures demonstrate that individual leading vendors already generate multi-billion-euro revenue within the broader global automation market.
Competition increasingly centers on software ownership, integration capability and lifecycle service rather than individual machines. Customers want one accountable partner for throughput, system availability and future expansion, which favors vendors with strong WES/WCS software and global support networks.
Recent Developments
August 2026: Exotec highlighted the increasing role of agentic AI, physical AI, modular automation and Robotics-as-a-Service in warehouse operations as customers shift from experimentation toward operational deployment.
June 2026: KNAPP reported FY 2025/26 turnover of EUR 2.135 billion, up 7.6%, and order intake of EUR 2.51 billion, supported by robotics and AI-related innovation.
June 2026: DSV and Exotec announced a strategic partnership around a Venlo logistics center using approximately 100 Skypod robots and around 90,000 bins and trays.
March 2026: Exotec and Komar Distribution Services announced a 760,000-square-foot automated fulfillment center in Savannah designed to increase throughput by up to 50% and storage density by 30%.
2026: Daifuku emphasized a shift toward balanced automation portfolios combining fixed systems and flexible mobile technologies, reflecting more disciplined investment after the post-pandemic automation surge.
Market Outlook
The logistics automation market is expected to remain one of the faster-growing industrial automation categories through 2031. Labor constraints, e-commerce, high warehouse real-estate costs and improved robotics economics support continued investment, but buyers will focus increasingly on measurable payback and operational resilience rather than technology novelty.
Modular architectures, software orchestration and integrated robotics are expected to gain share. Large fixed AS/RS and conveyor systems will remain important for predictable high-volume flows, while AMRs, goods-to-person robots and AI-enabled handling expand flexibility around those core systems.
Logistics Automation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 73.5 billion |
| Total Market Size in 2031 | 132.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Enterprise Size, Application, End-User Industry, Geograohy |
| Companies |
|
Market Segmentation
By Component
Hardware
Automated Storage and Retrieval Systems
Conveyor and Sortation Systems
AGVs and AMRs
Robotic Picking and Palletizing
Other Automation Hardware
Software
Warehouse Execution and Control Software
Automation Analytics and Optimization
Services
Integration and Commissioning
Maintenance and Lifecycle Services
By Enterprise Size
Small Enterprises
Medium Enterprises
Large Enterprises
By Application
Warehouse and Storage Management
Transportation and Cross-Dock Automation
By End-User Industry
Retail
Manufacturing
Food and Beverage
Pharmaceutical and Healthcare
Third-Party Logistics
Automotive
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Netherlands
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
South Korea
Australia
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency and Study Period
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Technology and Application Summary
3.4. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Labor Availability and Operating Cost Pressure
4.1.2. E-Commerce and Omnichannel Fulfillment
4.1.3. Warehouse Space and Storage Density
4.1.4. AI, Vision and Robotics Performance
4.2. Market Restraints
4.2.1. High Upfront Capital and Payback Requirements
4.2.2. Integration Complexity
4.2.3. Demand Volatility and SKU Complexity
4.2.4. Service and Maintenance Dependence
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. LOGISTICS AUTOMATION MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.2.1. Automated Storage and Retrieval Systems
5.2.2. Conveyor and Sortation Systems
5.2.3. AGVs and AMRs
5.2.4. Robotic Picking and Palletizing
5.2.5. Other Automation Hardware
5.3. Software
5.3.1. Warehouse Execution and Control Software
5.3.2. Automation Analytics and Optimization
5.4. Services
5.4.1. Integration and Commissioning
5.4.2. Maintenance and Lifecycle Services
6. MARKET BY ENTERPRISE SIZE
6.1. Introduction
6.2. Small Enterprises
6.3. Medium Enterprises
6.4. Large Enterprises
7. MARKET BY APPLICATION
7.1. Introduction
7.2. Warehouse and Storage Management
7.3. Transportation and Cross-Dock Automation
8. MARKET BY END-USER INDUSTRY
8.1. Introduction
8.2. Retail
8.3. Manufacturing
8.4. Food and Beverage
8.5. Pharmaceutical and Healthcare
8.6. Third-Party Logistics
8.7. Automotive
8.8. Others
9. MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. United Kingdom
9.4.3. France
9.4.4. Netherlands
9.4.5. Italy
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Others
9.6. Asia Pacific
9.6.1. Japan
9.6.2. China
9.6.3. India
9.6.4. South Korea
9.6.5. Australia
9.6.6. Southeast Asia
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Integrated Systems Competition
10.3. Robotics and Goods-to-Person Competition
10.4. Warehouse Software and Orchestration
10.5. Partnerships, Acquisitions and Capacity Expansion
10.6. Competitive Dashboard
11. COMPANY PROFILES
11.1. Daifuku Co., Ltd.
11.2. Dematic / KION Group
11.3. KNAPP AG
11.4. Vanderlande Industries / Toyota Industries
11.5. SSI Schaefer Group
11.6. Swisslog Holding AG
11.7. Honeywell Intelligrated
11.8. AutoStore Holdings Ltd.
11.9. Symbotic Inc.
11.10. Exotec
11.11. Geekplus Technology Co., Ltd.
11.12. GreyOrange
11.13. TGW Logistics Group
11.14. Mecalux, S.A.
11.15. WITRON Logistik + Informatik GmbH
12. APPENDIX
Navigate
Trusted by the world's leading organizations











