
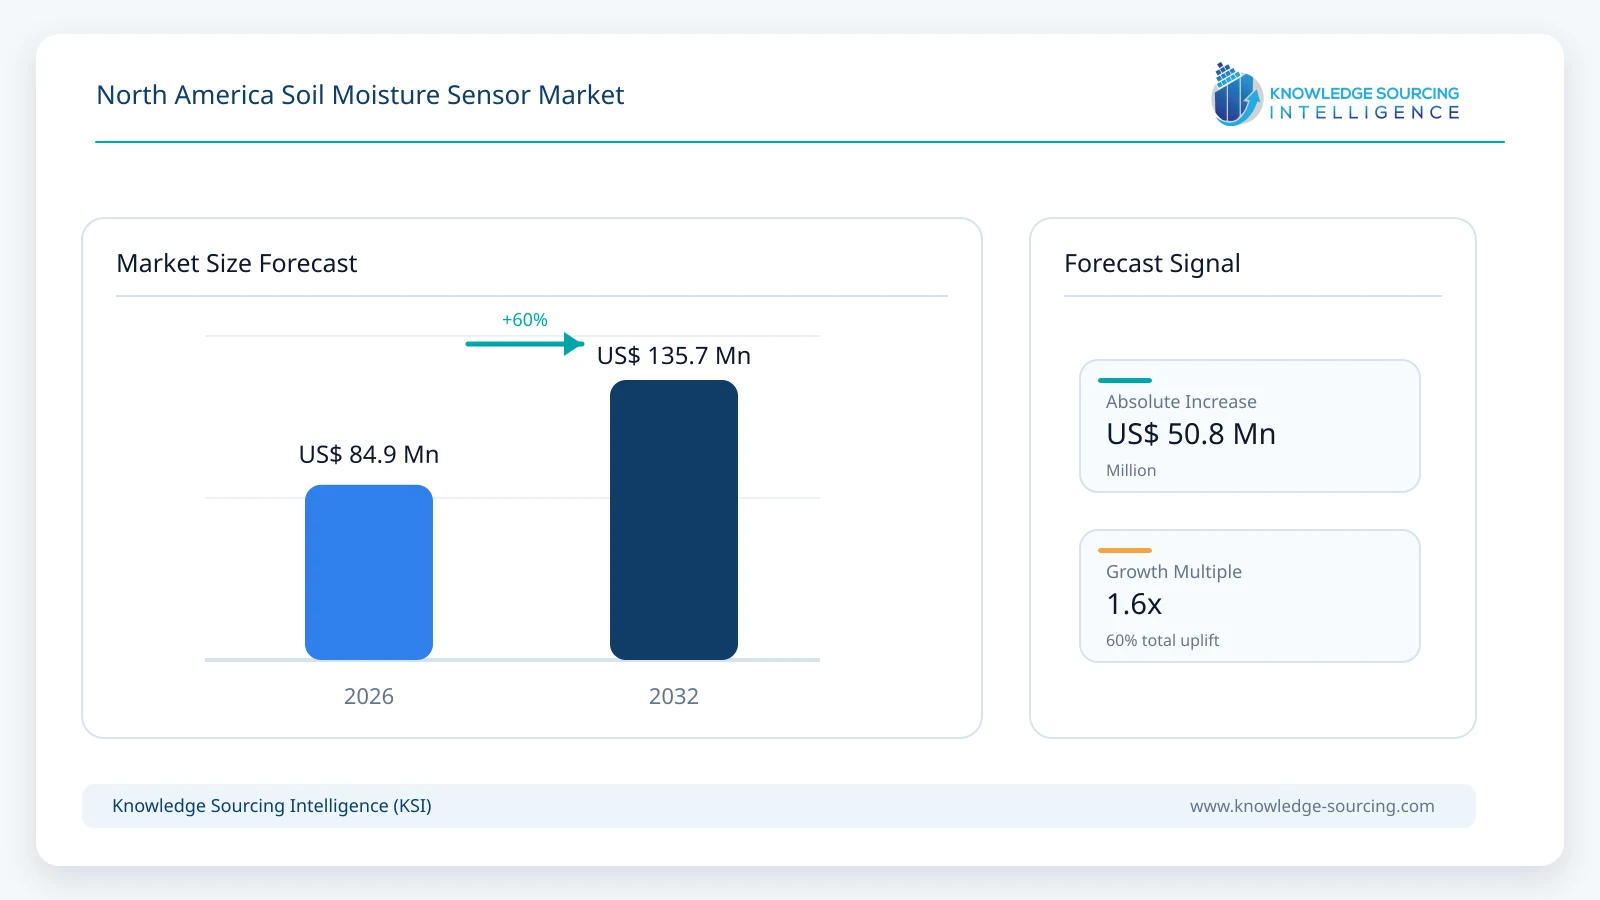
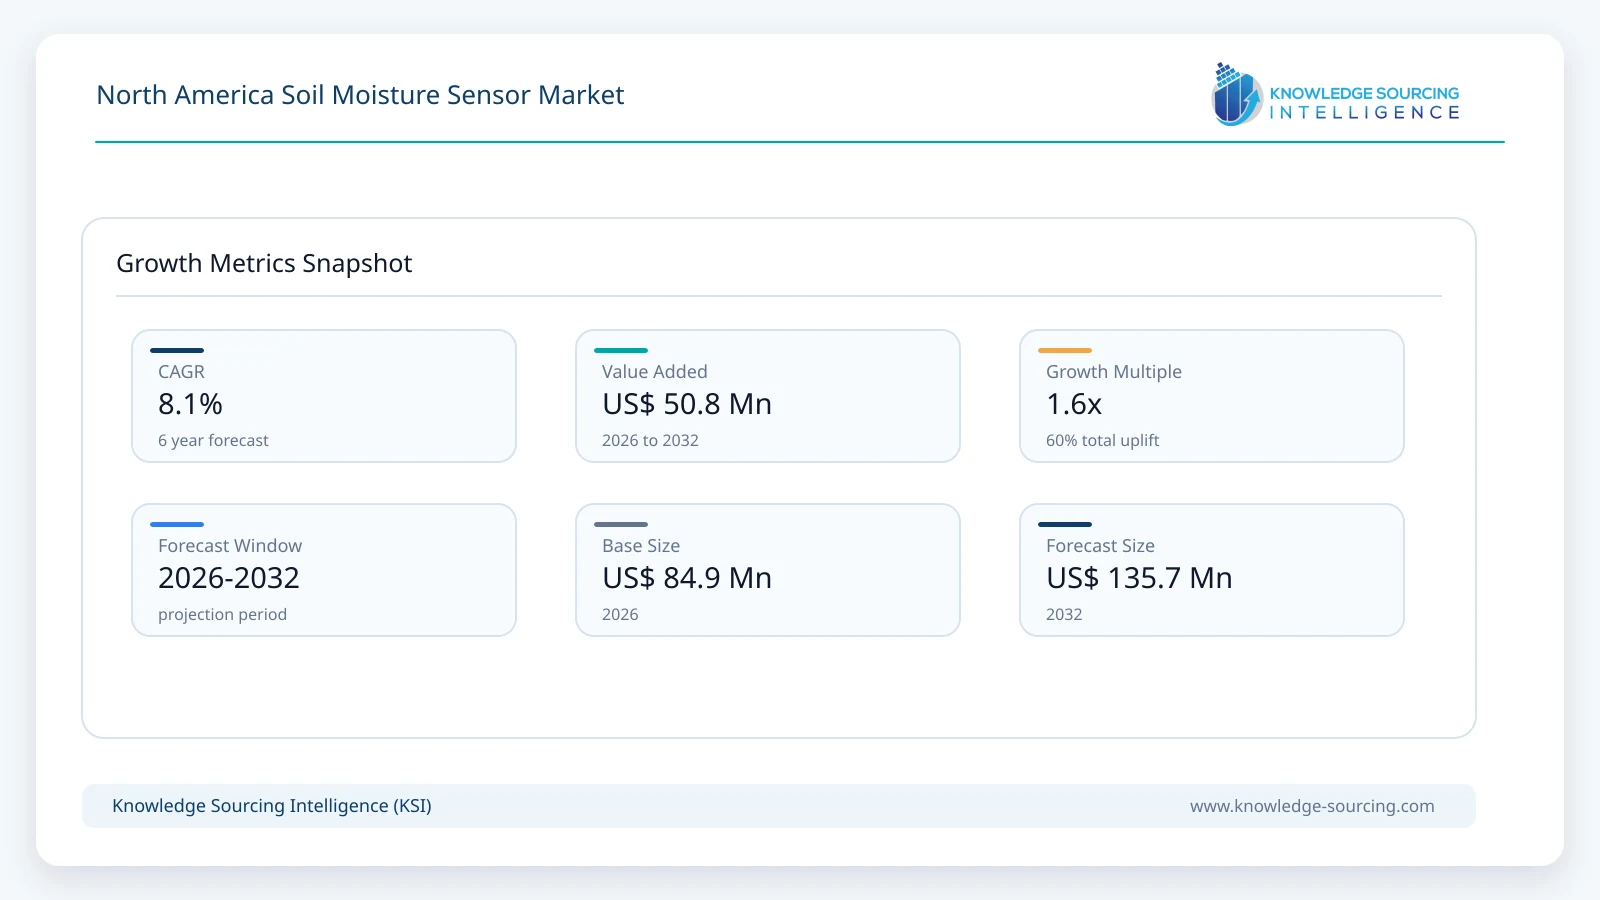
The North America soil moisture sensor market is estimated at USD 84.9 million in 2026 and is expected to reach USD 135.7 million by 2032, expanding at an 8.1% CAGR during the forecast period.
Highlights:
- 1Agriculture is the selected numerical segment, estimated at US$27.90 million in 2026, or 32.8% of regional revenue, rising to US$48.90 million by 2032 at a 9.80% CAGR.
- 2The United States leads 2026 regional demand at an estimated US$60.18 million, driven by irrigated production, turf management and environmental sensing.
- 3USDA survey evidence shows soil-moisture sensors remain far from universal on American irrigating farms, giving suppliers a substantial conversion opportunity.
- 4Water-potential and volumetric sensors serve different agronomic decisions; laboratory-grade precision, durable construction and compatibility with existing logger networks drive price differentiation.
- 5Canada and Mexico offer different expansion routesCanadian buyers emphasize precision and all-weather reliability, whereas Mexican growers prioritize irrigation productivity and affordable deployment.
Market demand spans irrigated agriculture, sports turf, research networks, construction monitoring and residential landscaping. Sensors measure either the soil’s volumetric water content or its water potential, giving users a practical basis for irrigation timing, root-zone assessment and environmental monitoring. The commercial market includes installed probes and dedicated handheld sensing instruments, but excludes irrigation pumps, controllers, standalone communications gateways, construction services and recurring software subscriptions. This distinction matters because a connected irrigation project can carry far more expenditure than its actual sensing hardware. In 2026, the United States represents the largest national market, with Canada and Mexico serving smaller but commercially distinct customer bases. Product value increasingly depends on sensor accuracy under variable salinity and soil textures, unattended field longevity and compatibility with existing data loggers. Consequently, vendors compete on lifetime measurement reliability and installation economics, not simply the lowest sensor purchase price.
Demand is supported by an extensive installed irrigation base but constrained by uneven technology adoption. USDA data show that 212,714 American farms irrigated 53.1 million acres in 2023, while 27,831 farms reported using soil-moisture sensing devices to determine irrigation timing. That difference indicates a sizeable potential user population, although it should not be interpreted as an annual sales figure. The sensor procurement decision turns on measurable water savings, crop-value exposure, number of sensing depths, labour requirements and replacement intervals. A precision probe can justify a premium when it prevents irrigation decisions based on unreliable root-zone readings, particularly for orchards, vineyards, greenhouses and high-value vegetables. Broad-acre operations are more price sensitive and may start with limited monitoring points before expanding across fields. The result is a heterogeneous market in which sophisticated multi-parameter probes coexist with simpler granular-matrix sensors. Growth depends on moving beyond demonstration projects toward repeatable deployment models, reliable local support and integration with routine irrigation decisions.
Market Dynamics
Water scarcity and irrigation economics
The strongest commercial catalyst is the rising cost of mismanaged irrigation rather than the mere presence of drought. Soil measurements become valuable when they allow growers to decide which field requires irrigation, how deeply water has penetrated and whether a second application would waste pumping energy or nutrients. In 2023, USDA estimated that American producers applied 81.0 million acre-feet of irrigation water and spent US$3.3 billion on energy for pumping. Those figures establish the economic stakes, although only a limited portion of that expenditure can be attributed directly to sensing equipment. Water availability differs sharply among California orchards, Nebraska pivots and irrigated horticulture, making uniform deployment assumptions unreliable. Suppliers that demonstrate a clear reduction in management effort can move from occasional spot measurements to multi-depth monitoring across larger acreages. Sensors must also work through mixed soils, electrical conductivity variations and harsh field conditions. That creates demand for robust probe construction and dependable calibration, while encouraging suppliers to package measurement outputs with decision tools without conflating the software revenue with sensor sales.
Commercial restraints and procurement choices
A sensor can be inexpensive in isolation but costly to install, interpret and maintain at the farm level. Growers require representative measurement locations, appropriate depth selection and knowledge of crop-specific water thresholds; a poorly placed probe can produce false confidence rather than better irrigation decisions. Even within a single field, root-zone conditions differ because of soil texture, compaction and slope. Devices that use different measurement principles may not generate interchangeable readings, particularly in saline or highly organic soil. Low-cost resistive sensors suit some irrigation scheduling tasks, while research networks require stronger repeatability and documented calibration. Premium products also compete with manual soil checks, evaporation estimates and established irrigation routines, all of which impose limited hardware spending. These barriers help explain why the installed irrigation area cannot be converted directly into sensor revenue. Suppliers improve adoption by offering practical installation guidance, visible agronomic benefits and compatibility with existing data collection systems. The commercial advantage lies in making measurements actionable without imposing disproportionate operational complexity on customers.
Technology, pricing and supply chain
Hardware economics vary substantially by measurement principle and intended application. Manufacturer-listed products illustrate this dispersion: Davis Instruments lists a soil-water-potential sensor at US$95, METER lists its TEROS 12 volumetric moisture sensor at US$271, and Acclima lists its TDR-310W near US$322–331. These are listed product prices, not uniform realized selling prices, and professional handheld readers can cost materially more. A basic sensor may need a separate reading unit, while a digital probe can connect to an existing SDI-12 logger. Procurement comparisons therefore need to account for accessories, cables, batteries, installation time, calibration and the replacement cycle. Electronics, corrosion-resistant rods, waterproof housings and reliable dielectric measurements remain core determinants of product cost. The North American supplier base includes specialist sensor producers, broader environmental-instrument manufacturers and irrigation-system companies. Software integration can create recurring relationships, but the measurement device remains the appropriate revenue unit for this market definition. Companies that can document sensor stability across years of field exposure have a stronger commercial basis for premium pricing and wider research adoption.
Regulatory and program environment
Public programs support the adoption of better irrigation practices but do not create a universal requirement to install electronic soil-moisture sensors. In the United States, the USDA Natural Resources Conservation Service maintains Irrigation Water Management Practice Standard 449, which addresses scientifically grounded water application and allows soil-moisture monitoring when appropriate to the management plan. Payments and eligibility depend on local program rules and practice specifications. In Canada, federal and provincial agricultural initiatives prioritize water efficiency and climate resilience, although not all funding can be attributed to soil-sensor purchases. Mexico faces major regional challenges around aquifer pressure, irrigation efficiency and energy costs, especially in intensive export agriculture. CONAGUA has identified approximately 6.1 million hectares equipped with irrigation infrastructure, giving a sense of the potential deployment setting without proving current sensor adoption. Vendors should prioritize programs where monitoring produces a measurable operational return instead of treating broad environmental policies as automatic procurement mandates. Institutional demand also comes from universities, weather networks, golf courses and civil-engineering firms that require defensible, repeatable environmental observations.
Major Segment Analysis
Agriculture: the selected numerical segment
Agricultural soil-moisture sensing is estimated at US$27.90 million in 2026, accounting for 32.8% of North American sensor revenue, and is forecast to reach US$48.90 million in 2032 at a 9.80% CAGR. The segment includes soil-water-potential instruments and volumetric sensors purchased by growers and farm service providers for irrigated crops, controlled-environment production and irrigation scheduling. Its growth reflects a mix of replacement demand, new deployments and wider use of multiple depths within existing monitored fields. A mature irrigation operation does not necessarily need more probes every year; sensor procurement depends on soil variability, the number of management zones and device lifespan. High-value perennial crops can justify several sensing positions, while broad-acre row crops may deploy a few representative monitoring stations. A more connected system can raise the attractiveness of soil measurements without making gateways or recurring analytics fees part of sensor hardware revenue. The practical buying criterion remains whether measurements change irrigation decisions reliably enough to save water, reduce pumping or protect crop yield. This makes installation quality and agronomic interpretation as important as device specifications.
Other application segments
Landscape and residential care represent another substantial outlet, with purchases tied to automatic irrigation control, municipal water conservation and commercial property maintenance. Turf managers often value portable measurement tools and consistent surface readings, while homeowners place greater weight on simplicity and price. Research institutions, weather-monitoring networks and universities buy higher-precision probes designed to produce comparable observations over long periods. Construction and geotechnical customers use moisture measurements to understand material conditions and instrumented ground behaviour, although these applications require different calibration and integration from agricultural irrigation. Sports facilities create a specialized demand for portable turf instruments, and weather-forecasting networks need consistent multi-site observations. These markets must be evaluated separately because their product mix, replacement frequency and contract values differ. The research category may command a relatively high selling price per instrument, but does not necessarily generate the largest shipment volume. Supplier strategies should therefore differentiate by application rather than assuming that one sensor, connectivity plan or distribution channel can serve every end user effectively.
Geographical Analysis
United States
The United States is estimated to contribute US$60.18 million in 2026 and US$94.77 million in 2032, making it the region’s largest national market. Irrigation demand is concentrated in commercially important production belts, including California, Nebraska, Arkansas, Texas and Idaho. USDA reported that these five states accounted for around half of American irrigated acres in 2023. Yet demand is not proportional to acreage alone. Water-intensive permanent crops, high-value vegetables and managed turf can support greater spending per site than low-margin broad-acre crops. Environmental research networks and university programs also support demand for calibrated, long-lived probes, while residential and commercial landscaping increases shipment volume for less expensive instruments. The purchasing cycle differs markedly between research agencies ordering long-duration measurement networks and growers buying irrigation-management equipment before planting. Sensor manufacturers must compete through agronomic support, installation procedures, field durability and device interoperability. Wider use of precision irrigation is likely to sustain growth, but the measured market includes sensor hardware, not the full value of adjacent pumps, controllers or software services.
Canada
Canada’s soil-moisture sensor market is estimated at US$12.25 million in 2026 and US$19.15 million in 2032. Its application mix reflects irrigated field crops in Alberta and Saskatchewan, specialized horticulture in Ontario and British Columbia, research programs and municipal landscape management. Statistics Canada’s 2024 Agricultural Water Survey documents irrigation methods, water use and regional differences, providing a public reference for agricultural demand without measuring sensor sales directly. Hardware selection is influenced by freezing conditions, seasonal installation windows and the need for dependable measurement through changing soil temperatures. Buyers in research and environmental monitoring require calibrated equipment and compatible data loggers, whereas commercial growers need practical decision support and service availability. The market consequently supports both rugged volumetric probes and lower-cost soil-water-potential devices. Provincial support programs can improve the economics of efficiency projects, although funding is not equivalent to automatic orders for sensors. Suppliers with reliable local distribution, application advice and field maintenance capabilities are better positioned than sellers competing exclusively on catalogue price. Growth should remain connected to specific deployments rather than a generalized national claim about climate policy.
Mexico
Mexico is estimated to account for US$12.51 million of North American soil-moisture sensor revenue in 2026, reaching US$21.76 million in 2032. Export-oriented horticulture, fruit production and water-constrained irrigated agriculture form the central commercial opportunity, particularly where a missed irrigation cycle can damage high-value crop output. CONAGUA’s long-term water planning has identified around 6.1 million hectares with irrigation infrastructure, but that figure is an infrastructure baseline rather than a current count of equipped sensor sites. Farms vary greatly in capital availability and technical support, making product affordability and ease of use especially important. Large growers may specify multi-depth instruments and connectivity to farm-management platforms, while smaller operations often prefer a limited number of robust monitoring points. Water-potential sensors can offer a less expensive entry route in suitable soils, whereas high-precision volumetric probes support more complex irrigation control. Distribution partnerships, Spanish-language implementation support and durable field equipment materially affect adoption. The market’s growth potential is substantial, but it remains sensitive to farm economics and locally available water-management expertise.
Competitive Environment and Analysis
Competition combines specialist measurement technology firms, irrigation equipment suppliers and integrated agronomy platforms. METER Group and Campbell Scientific emphasize measurement quality, calibration and research-grade instrumentation. Acclima and Stevens Water Monitoring Systems offer differentiated dielectric sensing approaches, while IRROMETER serves agricultural buyers seeking soil-water-tension measurement. Spectrum Technologies addresses sports turf, field scouting and portable monitoring, and Toro uses soil sensing as part of its irrigation ecosystem. CropX integrates its own root-zone sensor products with a broader agronomic platform, and Davis Instruments offers compatible sensors within its monitoring network. Royal Eijkelkamp distributes soil-sensing instruments, including products manufactured by other firms, while Pessl Instruments supplies its own monitoring equipment. The supplier comparison should separate direct sensor makers from product resellers and integrated service platforms. No reliable public source establishes a North American revenue-based market-share ranking for this exact hardware scope. Competitive positioning therefore rests on documented product functionality, price bands, support capability and channel access rather than unsupported claims that any one participant leads all applications.
Recent Developments
April 2026: CropX introduced the Apex multi-depth soil sensor, extending root-zone measurements across configurable probe lengths within its agronomy platform. The launch reinforces competition between individual measurement devices and integrated data-based offerings.
March 2026: CropX introduced CropX Vision for vineyard water-stress assessment using field imagery, underlining the growing use of plant-response measurements alongside soil-based sensors rather than as a direct substitute for them.
November 2025: CropX and Reinke announced a unified platform integration linking CropX field data with Reinke’s ReinCloud environment, increasing opportunities to combine soil information with irrigation-system operation.
North America Soil Moisture Sensor Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 84.9 million |
| Total Market Size in 2032 | USD 135.7 million |
| Forecast Unit | Million |
| Growth Rate | 8.1% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Type, Application |
| Companies |
|
Market Segmentation
By Type
Water Potential Sensors
Volumetric Moisture Sensors
By Application
Agriculture
Construction
Sports
Research
Weather Forecasting
Landscape and Residential Care
Others
By Geography
United States
Canada
Mexico
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Historical Market Context
1.3. Market Definition
1.4. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Estimation Approach and Assumptions
2.3. Market Reconciliation
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry
4.4. Industry Value Chain Analysis
4.5. Technology and Price Analysis
5. NORTH AMERICA SOIL MOISTURE SENSOR MARKET ANALYSIS, BY TYPE
5.1. Introduction
5.2. Water Potential Sensors
5.3. Volumetric Moisture Sensors
6. NORTH AMERICA SOIL MOISTURE SENSOR MARKET ANALYSIS, BY APPLICATION
6.1. Introduction
6.2. Agriculture
6.3. Construction
6.4. Sports
6.5. Research
6.6. Weather Forecasting
6.7. Landscape and Residential Care
6.8. Others
7. NORTH AMERICA SOIL MOISTURE SENSOR MARKET ANALYSIS, BY GEOGRAPHY
7.1. Introduction
7.2. United States
7.2.1. By Type
7.2.2. By Application
7.3. Canada
7.3.1. By Type
7.3.2. By Application
7.4. Mexico
7.4.1. By Type
7.4.2. By Application
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Emerging Players and Market Opportunities
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. METER Group
9.2. Campbell Scientific
9.3. IRROMETER Company
9.4. Acclima
9.5. The Toro Company
9.6. Spectrum Technologies
9.7. Stevens Water Monitoring Systems
9.8. CropX Technologies
9.9. Davis Instruments
9.10. Pessl Instruments
9.11. Royal Eijkelkamp
10. RESEARCH METHODOLOGY AND SOURCES
11. LIST OF FIGURES
12. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











