
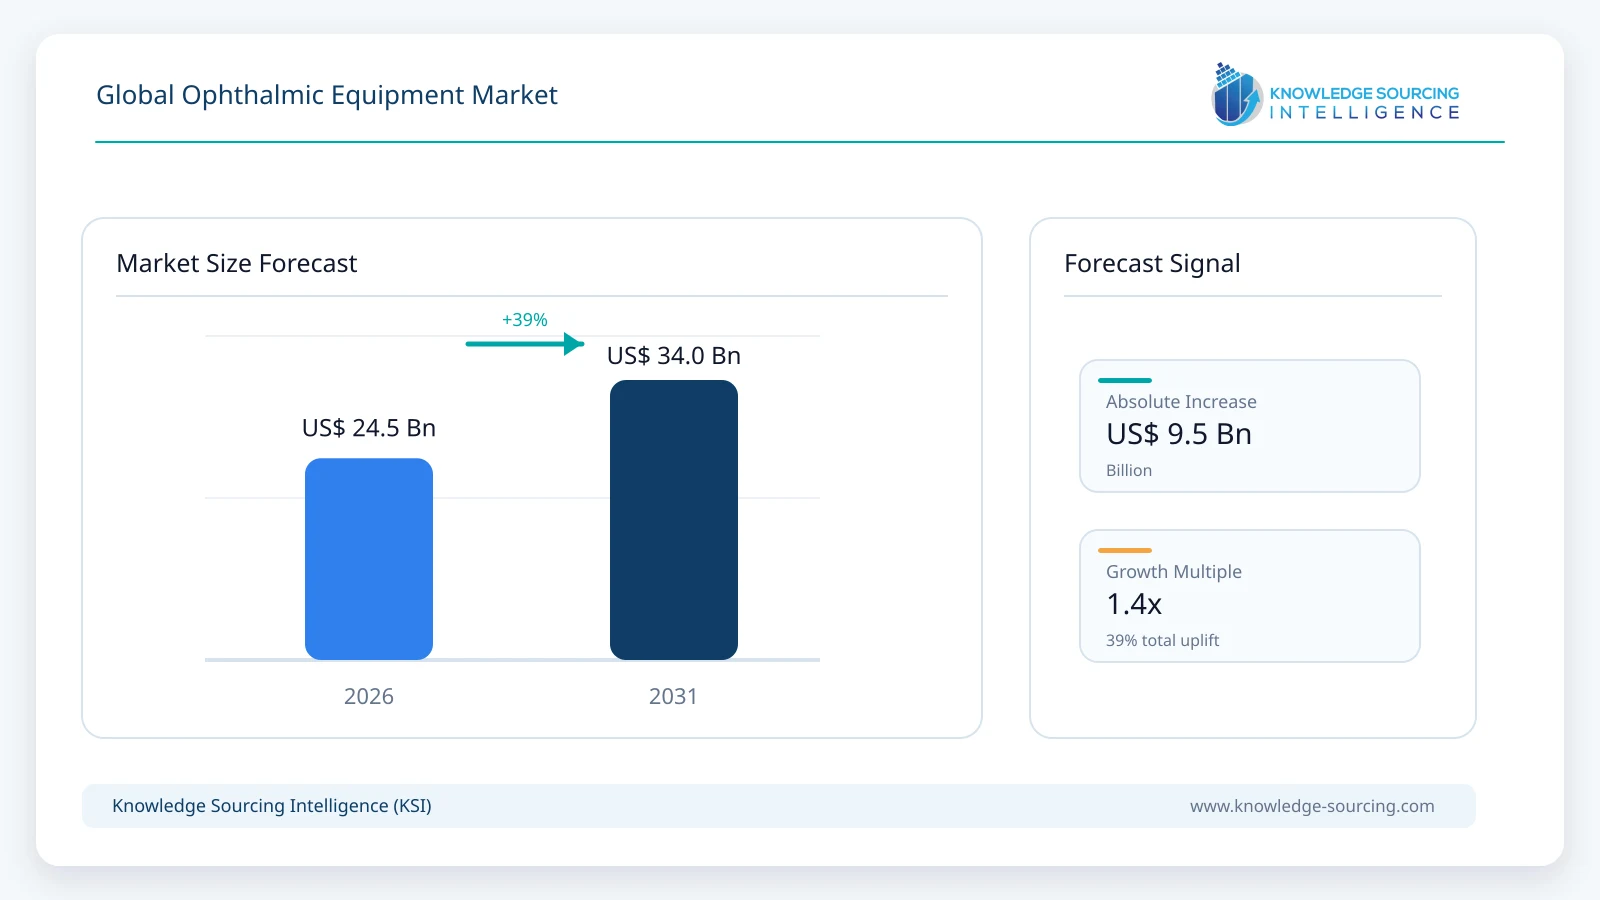
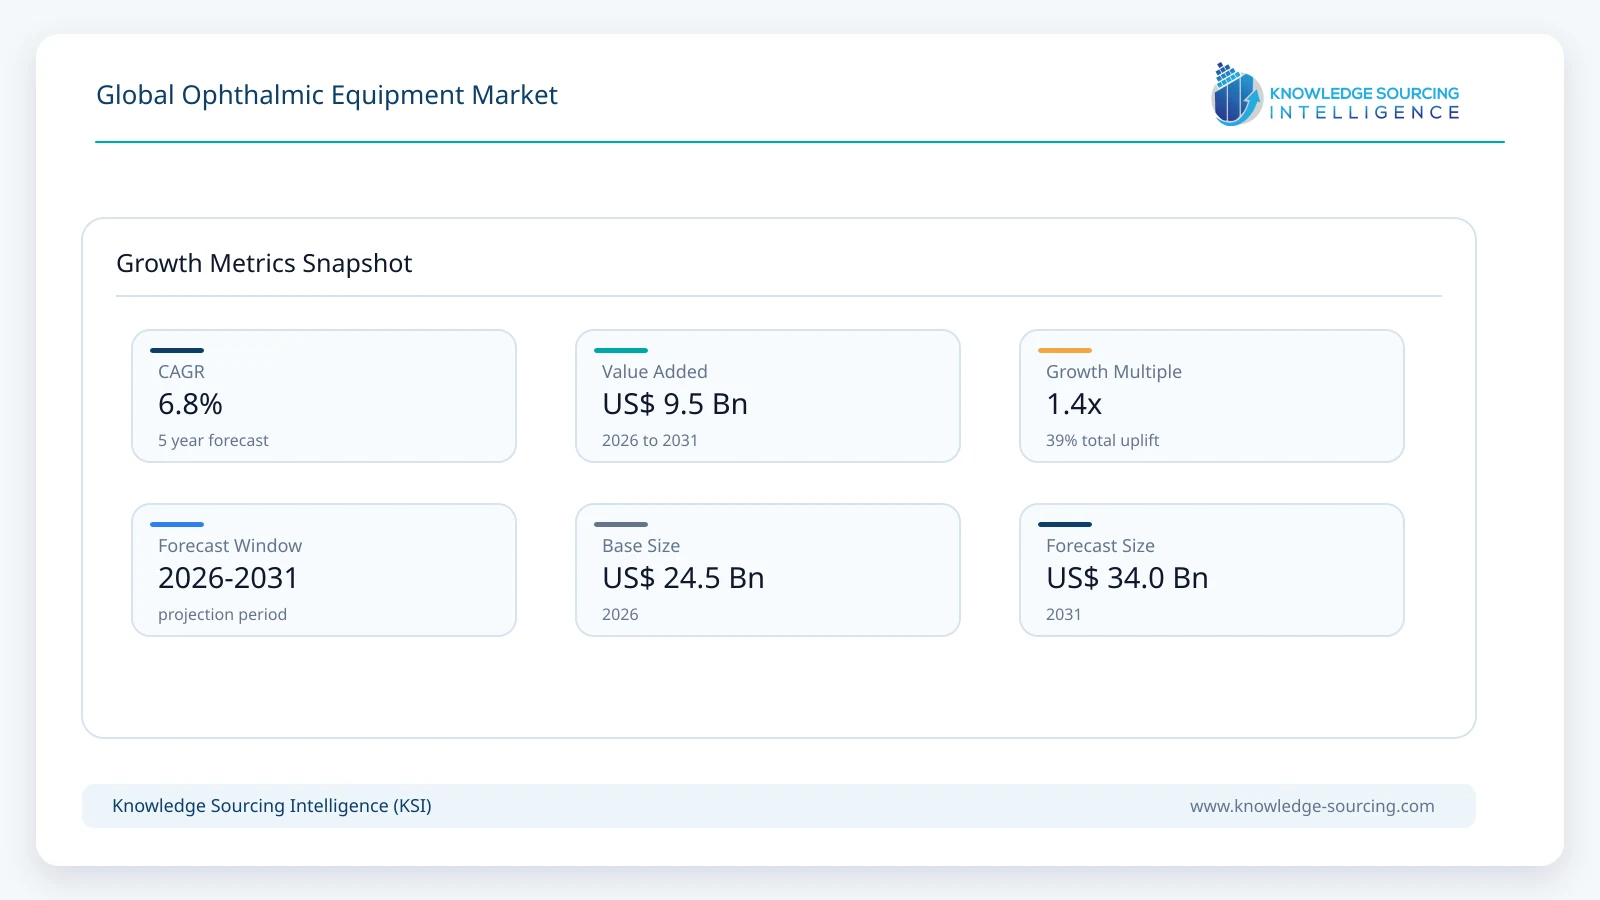
The global ophthalmic equipment market is forecast to grow from USD 24.50 billion in 2026 to USD 34.00 billion in 2031, representing a CAGR of 6.80% across the forecast period.
Highlights:
- 1Surgical devices are expected to remain the largest product category, accounting for approximately 68.0% of global ophthalmic equipment revenue in 2026.
- 2Hospitals are estimated to account for approximately 44.0% of 2026 market revenue because high-acuity cataract, retinal, glaucoma and complex diagnostic workflows remain concentrated in hospital-based ophthalmology departments.
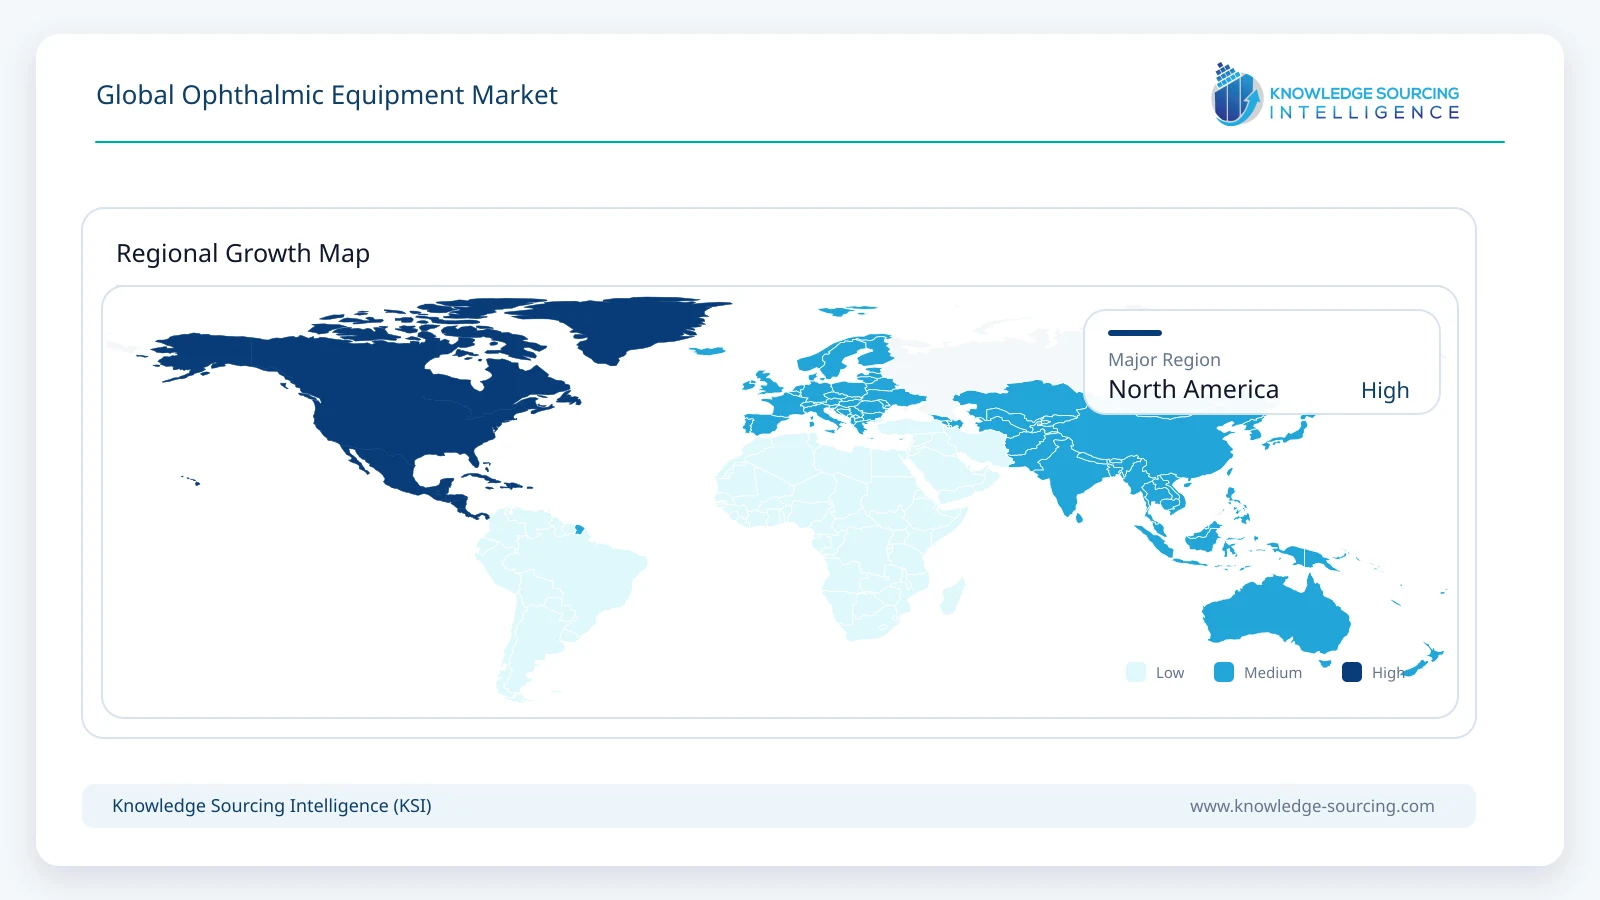
- 3North America is estimated to represent approximately 37.0% of global ophthalmic equipment revenue in 2026, supported by high procedure volumes, premium technology adoption and a large installed base of ophthalmology practices and ambulatory surgery centers.
- 4Global eye-care need remains structurally high. The World Health Organization states that at least 2.2 billion people live with near or distance vision impairment and at least 1 billion cases could have been prevented or remain unaddressed.
- 5Major suppliers continue to invest across connected diagnostics and surgery. Alcon reported USD 5.8 billion of Surgical revenue in 2025, while Carl Zeiss Meditec reported EUR 1.72 billion of Ophthalmology revenue in fiscal 2024/25.
- 6The 2026 product cycle is increasingly centered on integrated imaging, digital visualization, automated acquisition and connected surgical platforms rather than stand-alone instruments.
Commercial evidence also points to a large global device base. Alcon generated USD 5.8 billion from its Surgical business in 2025, including implantables, consumables and equipment, while Carl Zeiss Meditec generated EUR 1.72 billion from its Ophthalmology strategic business unit in fiscal 2024/25. Topcon reported JPY 84.3 billion of Eye Care revenue in its 2025 reporting cycle, and Revenio's 2026 combination with Visionix created a diagnostic eye-care group with more than EUR 250 million in illustrative 2025 sales.
The market is increasingly organized around connected clinical workflows. Diagnostic systems are moving toward multimodal acquisition, automated image capture, cloud-compatible data management and AI-supported interpretation. Surgical platforms are similarly converging around integrated visualization, fluidics, laser functionality, intraoperative imaging and procedure-specific consumables. This shift increases the value of installed ecosystems and raises switching costs for clinics and hospitals.
The forecast reflects continued procedure growth, replacement of aging installed equipment, higher adoption of premium diagnostics and surgical systems, and wider access to eye care in emerging markets. Growth is moderated by capital intensity, long equipment replacement cycles, reimbursement variability and the persistence of lower-cost legacy systems in price-sensitive markets.
Ophthalmic Equipment Market Trends
Multimodal Imaging and AI Become Core Diagnostic Capabilities
Ophthalmic diagnostics are moving from isolated instruments toward multimodal platforms that combine OCT, fundus imaging, angiography, anterior-segment imaging and clinical data management. The objective is not only higher image quality but also faster acquisition, consistent longitudinal comparison and easier movement of data between devices and clinical systems.
Heidelberg Engineering used ARVO 2026 to present a multimodal imaging platform with ultra-high-resolution OCT and automated DICOM workflows linked to AI analysis. ZEISS introduced the ALTA DUO 300 in September 2026, combining OCT and fundus imaging within its retina workflow. Topcon continues to expand automated OCT platforms such as Maestro2 and newer swept-source systems. These developments support higher equipment value per installation while reducing operator dependence.
Surgical Platforms Converge Across Cataract and Retina Workflows
Ophthalmic surgery is shifting toward modular platforms that support multiple procedure types and integrate fluidics, visualization, laser functions and digital guidance. Hospitals and high-volume surgery centers increasingly evaluate systems on total workflow efficiency and compatibility with procedure-specific consumables rather than on a single technical specification.
Alcon's UNITY VCS combines anterior- and posterior-segment surgical functionality, while the 2026 UNITY M launch extends the platform into premium ophthalmic microscopy. ZEISS continues to integrate DORC vitreoretinal technologies into its retina workflow, and Bausch + Lomb remains active in combined cataract and vitreoretinal systems. The result is a stronger ecosystem model in which capital equipment drives recurring procedure-linked revenue.
Automation Expands Access to Advanced Diagnostics
Automated alignment, robotic acquisition and compact device footprints are lowering the operator burden associated with advanced ophthalmic imaging. This is particularly relevant for high-throughput clinics, optical retail, community screening and regions where specialist technician availability is limited.
Topcon's Maestro2 combines automated OCT and fundus imaging, NIDEK continues to expand automated diagnostic platforms, and Revenio's combination with Visionix broadens its offering across tonometry, retinal imaging, OCT, refraction and software. Automation can increase patient throughput and improve reproducibility, supporting wider deployment outside tertiary eye hospitals.
Digital Visualization Changes the Ophthalmic Operating Room
Surgical microscopes are increasingly becoming digital visualization hubs rather than purely optical instruments. Heads-up displays, intraoperative OCT, image enhancement and digital overlays can improve ergonomics and support more information-rich procedures.
Haag-Streit promoted its METIS 3D digital heads-up module during 2026, while Heidelberg Engineering prepared commercial expansion of its OPERA digital surgical visualization platform with intraoperative OCT. ZEISS and Alcon are also strengthening digital visualization within broader surgical ecosystems, indicating that the operating microscope is becoming part of a connected procedural platform.
Global Ophthalmic Equipment Market Market Segmentation
By Product
Surgical Devices
Surgical devices are estimated at approximately USD 16.66 billion in 2026. The segment includes cataract and vitreoretinal surgical systems, ophthalmic lasers, surgical microscopes, glaucoma procedure devices, intraocular lenses, instruments and procedure-specific consumables used directly in ophthalmic surgery.
Cataract surgery is the largest procedural value pool because of the global burden of age-related lens opacity, the high volume of cataract procedures and the recurring use of intraocular lenses and single-use consumables. Vitreoretinal surgery, refractive procedures and glaucoma interventions add additional high-value equipment and consumable demand.
The segment is increasingly supported by integrated platforms. Alcon's Surgical business generated USD 5.8 billion in 2025 and includes implantables, consumables and equipment. ZEISS has expanded its retina position through DORC, BVI is launching the Virtuoso platform in European markets, and Bausch + Lomb continues to commercialize cataract and vitreoretinal equipment. These portfolios demonstrate the importance of combining capital equipment with recurring procedure-linked products.
By End User
Hospitals
Hospitals are estimated at approximately USD 10.78 billion in 2026. They remain the largest end-user group because complex cataract, retinal, glaucoma and trauma cases often require operating-room infrastructure, anesthesia support, advanced imaging and multidisciplinary care.
Hospital ophthalmology departments are major purchasers of surgical microscopes, vitreoretinal platforms, phacoemulsification systems, lasers and high-end diagnostic imaging. Academic and tertiary centers also adopt advanced OCT, angiography, perimetry and digital workflow systems earlier because they manage complex disease and clinical research.
Ambulatory surgery centers and dedicated ophthalmology clinics are gaining importance, particularly in North America and parts of Asia, but hospitals retain a substantial share of global value because high-acuity procedures and public-sector eye-care programs remain hospital centered in many countries.
Market Drivers
Large and Growing Burden of Vision Impairment
The global prevalence of cataract, glaucoma, diabetic retinopathy, refractive error and retinal disease creates sustained demand for diagnostic and surgical capacity. WHO continues to report at least 2.2 billion people with vision impairment, including at least 1 billion cases that could have been prevented or remain unaddressed. Expanding access to eye care therefore requires both new equipment and higher utilization of existing systems.
Ageing Populations and Procedure Growth
Many major ophthalmic conditions are strongly age related. As populations age, cataract surgery, retinal imaging, glaucoma monitoring and other ophthalmic procedures increase. This supports recurring demand for surgical consumables and replacement demand for diagnostic and operating-room equipment.
Expansion of Eye-Care Infrastructure in Emerging Markets
Government programs, private hospital expansion and specialist eye-care networks are increasing access to ophthalmology in Asia Pacific, the Middle East, Latin America and Africa. WHO notes that 90% of people with unaddressed vision impairment or blindness live in low- and middle-income countries, creating a substantial long-term need for scalable diagnostics and surgical capacity.
Technology-Led Replacement of Installed Systems
Advanced OCT, multimodal imaging, automated capture, intraoperative OCT and digital visualization are encouraging providers to replace older equipment before physical end-of-life. Upgrades can improve throughput, image quality, interoperability and procedure efficiency, creating a technology-driven replacement cycle.
Growth of Ambulatory and Specialty Eye-Care Networks
Dedicated ophthalmology clinics and ambulatory surgery centers are expanding procedure capacity outside general hospitals. These facilities often standardize around integrated diagnostic and surgical ecosystems, supporting demand for compact automated devices, efficient surgical consoles and connected data systems.
Market Restraints
High Capital Cost of Advanced Systems
Swept-source OCT, femtosecond lasers, surgical microscopes and integrated vitreoretinal platforms can require substantial upfront investment. Smaller clinics may extend replacement cycles, lease equipment or prioritize a narrower set of essential devices when financing conditions are restrictive.
Long Replacement Cycles
Ophthalmic capital equipment is designed for multi-year use. Reliable legacy systems can remain clinically serviceable for long periods, especially where procedure volumes are moderate. This limits annual unit replacement despite continued growth in eye-care demand.
Reimbursement and Procedure Economics
Adoption of premium surgical systems and diagnostic technologies depends partly on reimbursement, procedure volumes and the economics of each care setting. Where reimbursement is limited, providers may favor established lower-cost technologies even when newer systems offer workflow advantages.
Specialist Training and Workflow Requirements
Advanced imaging and surgical platforms still require trained clinicians, technicians and biomedical support. Limited specialist availability can reduce utilization in lower-resource settings and delay the economic case for premium systems.
Regulatory and Service-Network Complexity
Medical-device approvals, cybersecurity requirements, software updates and post-market service obligations increase the cost of global commercialization. Suppliers need strong regional service networks because equipment downtime can directly affect procedure capacity and clinical schedules.
Regional Outlook
North America
North America is estimated at approximately USD 9.07 billion in 2026. The region combines high procedure volumes, broad access to advanced diagnostic technologies, a large ambulatory surgery center base and strong adoption of premium cataract, retinal and glaucoma technologies.
The United States remains the core regional market and is home to major suppliers including Alcon, Johnson & Johnson Vision, Bausch + Lomb, Glaukos and BVI Medical. Provider purchasing is increasingly influenced by workflow integration, service support, digital connectivity and recurring procedure economics.
North America is expected to retain a leading position through 2031, although Asia Pacific is likely to gain share as hospital capacity, private eye-care networks and domestic manufacturing expand in China, India and Southeast Asia.
Competitive Landscape
The ophthalmic equipment market combines large diversified eye-care companies with specialist diagnostic and surgical technology providers. Alcon leads across cataract and vitreoretinal surgery, while Carl Zeiss Meditec spans diagnostics, refractive surgery, cataract, retinal surgery and visualization. Topcon, NIDEK, Haag-Streit, Heidelberg Engineering and Revenio are particularly important in diagnostic and examination equipment.
Competition increasingly centers on installed ecosystems rather than isolated devices. Suppliers seek to connect imaging, planning, surgery, consumables, software and service into common workflows. This strengthens recurring revenue and can increase customer retention because data formats, consumables and operating procedures become embedded in clinical practice.
Mergers and acquisitions are also reshaping the market. ZEISS has integrated DORC into its retina workflow, EssilorLuxottica is building a med-tech ecosystem around Heidelberg Engineering and RetinAI, and Revenio completed its acquisition of Visionix in May 2026. These combinations broaden product portfolios and improve cross-selling across diagnostics, optical retail and ophthalmology.
Recent Developments
September 2026: ZEISS introduced the ALTA DUO 300, combining OCT and fundus imaging within the ZEISS Retina Workflow, while continuing the integration of DORC products under the ZEISS brand.
September 2026: Alcon launched UNITY M, a premium ophthalmic microscope designed for integration with the broader UNITY surgical platform, with commercial rollout beginning in the United States and Japan followed by additional markets.
September 2026: BVI Medical launched Virtuoso across European markets as a next-generation platform for ophthalmic surgery and expanded its EURETINA 2026 program around vitreoretinal applications.
May 2026: Revenio completed the acquisition of Visionix, creating a broader eye-care diagnostic group spanning tonometry, retinal imaging, OCT, refraction, screening and workflow software.
April 2026: Heidelberg Engineering presented its next-generation multimodal imaging platform with ultra-high-resolution OCT and AI-linked DICOM workflows at ARVO 2026.
2026: Haag-Streit expanded its digital surgical and diagnostic offering with the METIS 3D heads-up module, Elara 900 slit lamp and new Octopus perimeter platforms.
Market Outlook
The ophthalmic equipment market is expected to expand steadily through 2031 as global eye-care demand rises and providers modernize diagnostic and surgical infrastructure. Growth is likely to be strongest where equipment upgrades increase throughput, automate acquisition, integrate imaging and data, or support multiple procedure types within a common platform.
Surgical devices will remain the largest value pool because cataract, vitreoretinal and glaucoma procedures combine capital equipment with recurring implant and consumable demand. Diagnostic equipment will also gain strategic importance as OCT, fundus imaging, perimetry and AI-supported workflows move toward earlier detection and longitudinal disease management.
Asia Pacific is expected to increase its contribution to global growth as care capacity expands, while North America and Europe remain important markets for premium technology and replacement demand. Competitive advantage will increasingly depend on the breadth of the clinical ecosystem, regulatory execution, service coverage, software interoperability and the ability to support both high-volume and decentralized eye-care settings.
Global Ophthalmic Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 24.50 billion |
| Total Market Size in 2031 | USD 34.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.80% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product
Diagnostic Devices
Optical Coherence Tomography and Retinal Imaging Systems
Fundus Cameras
Autorefractors and Keratometers
Perimeters and Visual Field Analyzers
Tonometers
Biometers, Slit Lamps and Other Diagnostic Devices
Surgical Devices
Cataract Surgery Systems and Devices
Vitreoretinal Surgical Systems and Devices
Refractive Surgery Lasers
Glaucoma Surgery Devices
Surgical Microscopes and Digital Visualization
Intraocular Lenses, Instruments and Procedure Consumables
By End User
Hospitals
Ophthalmology Clinics and Ambulatory Surgical Centers
Diagnostic and Optometry Centers
Academic and Research Institutions
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Market Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Large and Growing Burden of Vision Impairment
4.1.2. Ageing Populations and Procedure Growth
4.1.3. Expansion of Eye-Care Infrastructure in Emerging Markets
4.1.4. Technology-Led Replacement of Installed Systems
4.1.5. Growth of Ambulatory and Specialty Eye-Care Networks
4.2. Market Restraints
4.2.1. High Capital Cost of Advanced Systems
4.2.2. Long Replacement Cycles
4.2.3. Reimbursement and Procedure Economics
4.2.4. Specialist Training and Workflow Requirements
4.2.5. Regulatory and Service-Network Complexity
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. GLOBAL OPHTHALMIC EQUIPMENT MARKET BY PRODUCT
5.1. Introduction
5.2. Diagnostic Devices
5.2.1. Optical Coherence Tomography and Retinal Imaging Systems
5.2.2. Fundus Cameras
5.2.3. Autorefractors and Keratometers
5.2.4. Perimeters and Visual Field Analyzers
5.2.5. Tonometers
5.2.6. Biometers, Slit Lamps and Other Diagnostic Devices
5.3. Surgical Devices
5.3.1. Cataract Surgery Systems and Devices
5.3.2. Vitreoretinal Surgical Systems and Devices
5.3.3. Refractive Surgery Lasers
5.3.4. Glaucoma Surgery Devices
5.3.5. Surgical Microscopes and Digital Visualization
5.3.6. Intraocular Lenses, Instruments and Procedure Consumables
6. GLOBAL OPHTHALMIC EQUIPMENT MARKET BY END USER
6.1. Introduction
6.2. Hospitals
6.3. Ophthalmology Clinics and Ambulatory Surgical Centers
6.4. Diagnostic and Optometry Centers
6.5. Academic and Research Institutions
6.6. Others
7. GLOBAL OPHTHALMIC EQUIPMENT MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. United Kingdom
7.4.2. Germany
7.4.3. France
7.4.4. Italy
7.4.5. Spain
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. Japan
7.6.3. India
7.6.4. South Korea
7.6.5. Australia
7.6.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Diagnostic and Surgical Portfolio Positioning
8.3. Digital Workflow and Ecosystem Competition
8.4. Mergers, Acquisitions, Agreements and Partnerships
8.5. Competitive Dashboard
9. COMPANY PROFILES
9.1. Alcon Inc.
9.2. Carl Zeiss Meditec AG
9.3. Johnson & Johnson Vision
9.4. Bausch + Lomb Corporation
9.5. Topcon Corporation / Topcon Healthcare
9.6. NIDEK Co., Ltd.
9.7. Haag-Streit Holding AG
9.8. Heidelberg Engineering GmbH (EssilorLuxottica)
9.9. Revenio Group (iCare / Visionix)
9.10. Glaukos Corporation
9.11. BVI Medical
9.12. Appasamy Associates Pvt. Ltd.
9.13. OCULUS Optikgeräte GmbH
9.14. Lumibird Medical / Quantel Medical
9.15. Ziemer Ophthalmic Systems AG
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Abbreviations





Frequently asked questions
What is the projected market size and CAGR for ophthalmic equipment?
The Global Ophthalmic Equipment Market is forecast to reach $34.00 billion by 2031, with 6.80% CAGR.
Which product category holds the largest share in the ophthalmic equipment market?
Surgical devices are the largest, accounting for 68.0% of 2026 market revenue.
Which end-user segment dominates the ophthalmic equipment market?
Hospitals lead, representing approximately 44.0% of 2026 market revenue.
Which geographical region is expected to lead the ophthalmic equipment market?
North America leads, projected to hold 37.0% of global revenue in 2026.
What are the key technological trends influencing ophthalmic equipment?
Trends include integrated imaging, AI-supported diagnostics, and connected surgical platforms.
What are the primary drivers for ophthalmic equipment market growth?
Growth is driven by high eye-care need, procedure growth, and premium system adoption.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Ophthalmic Equipment Market Size, Share & Growth Forecast (2026-2031). https://www.knowledge-sourcing.com/report/ophthalmic-equipment-market