Pet Food Packaging Market - Strategic Insights and Forecasts (2026-2031)
Pet Food Packaging Market Size, Share, Growth, Forecasts and Trends By Material (Plastic, Paper and Paperboard, Metal, Others), Packaging Type (Bags and Pouches, Metal Cans, Trays and Cups, Cartons and Rigid Paper Containers, Others), Type of Food (Dry Food and Treats, Wet Food, Fresh / Refrigerated Food), Animal (Dog Food, Cat Food, Other Companion Animals), Distribution Channel (Offline, Online), and Geography
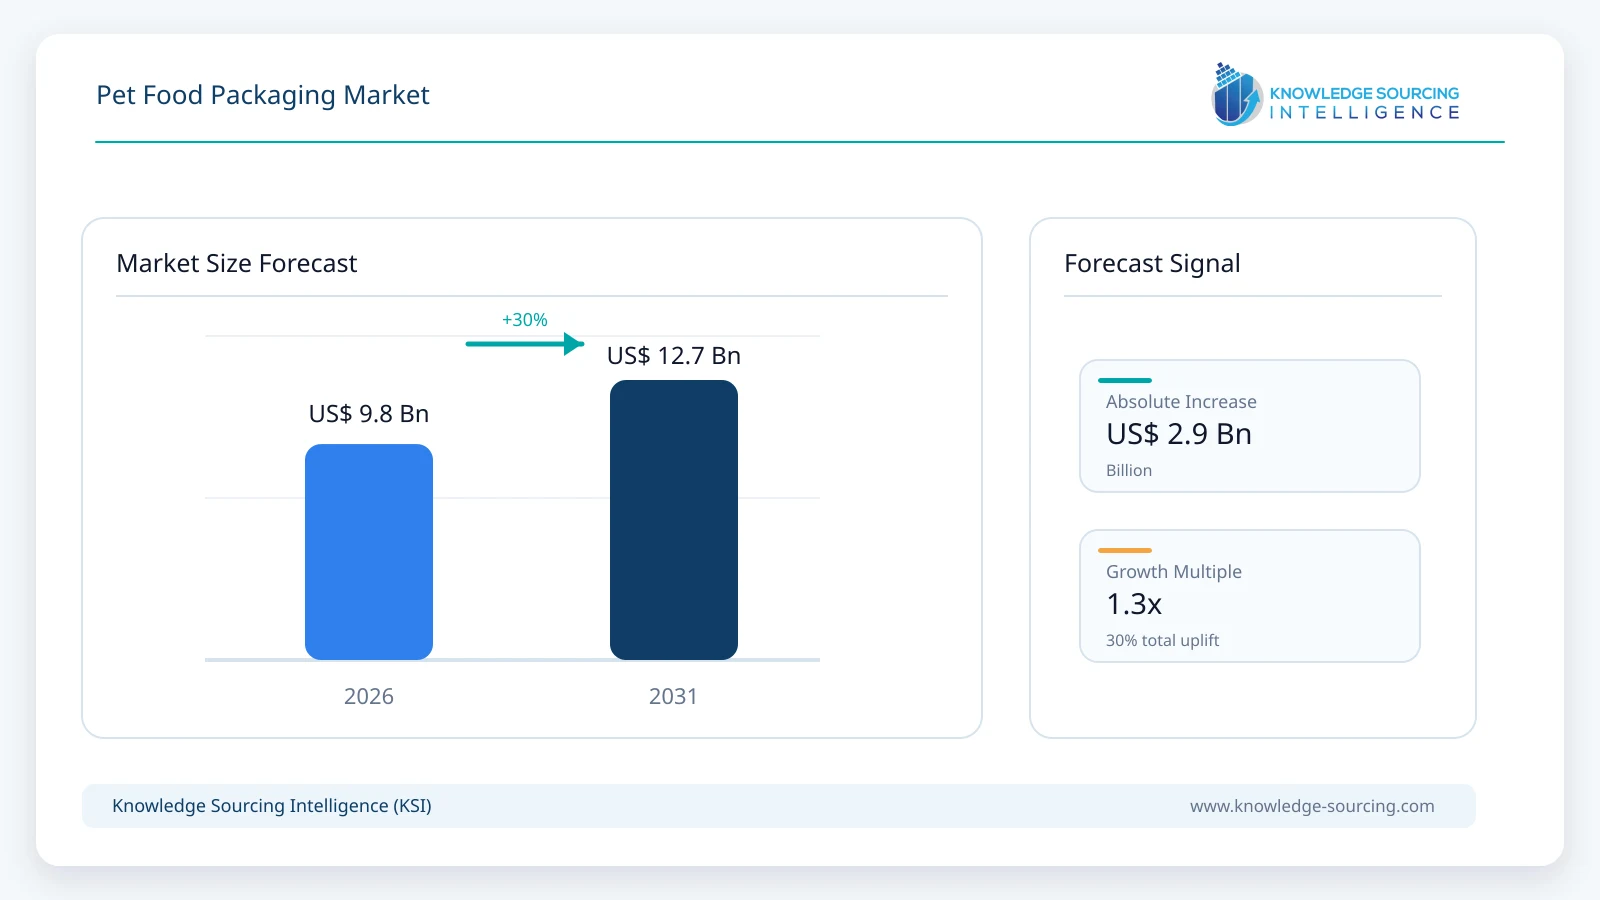
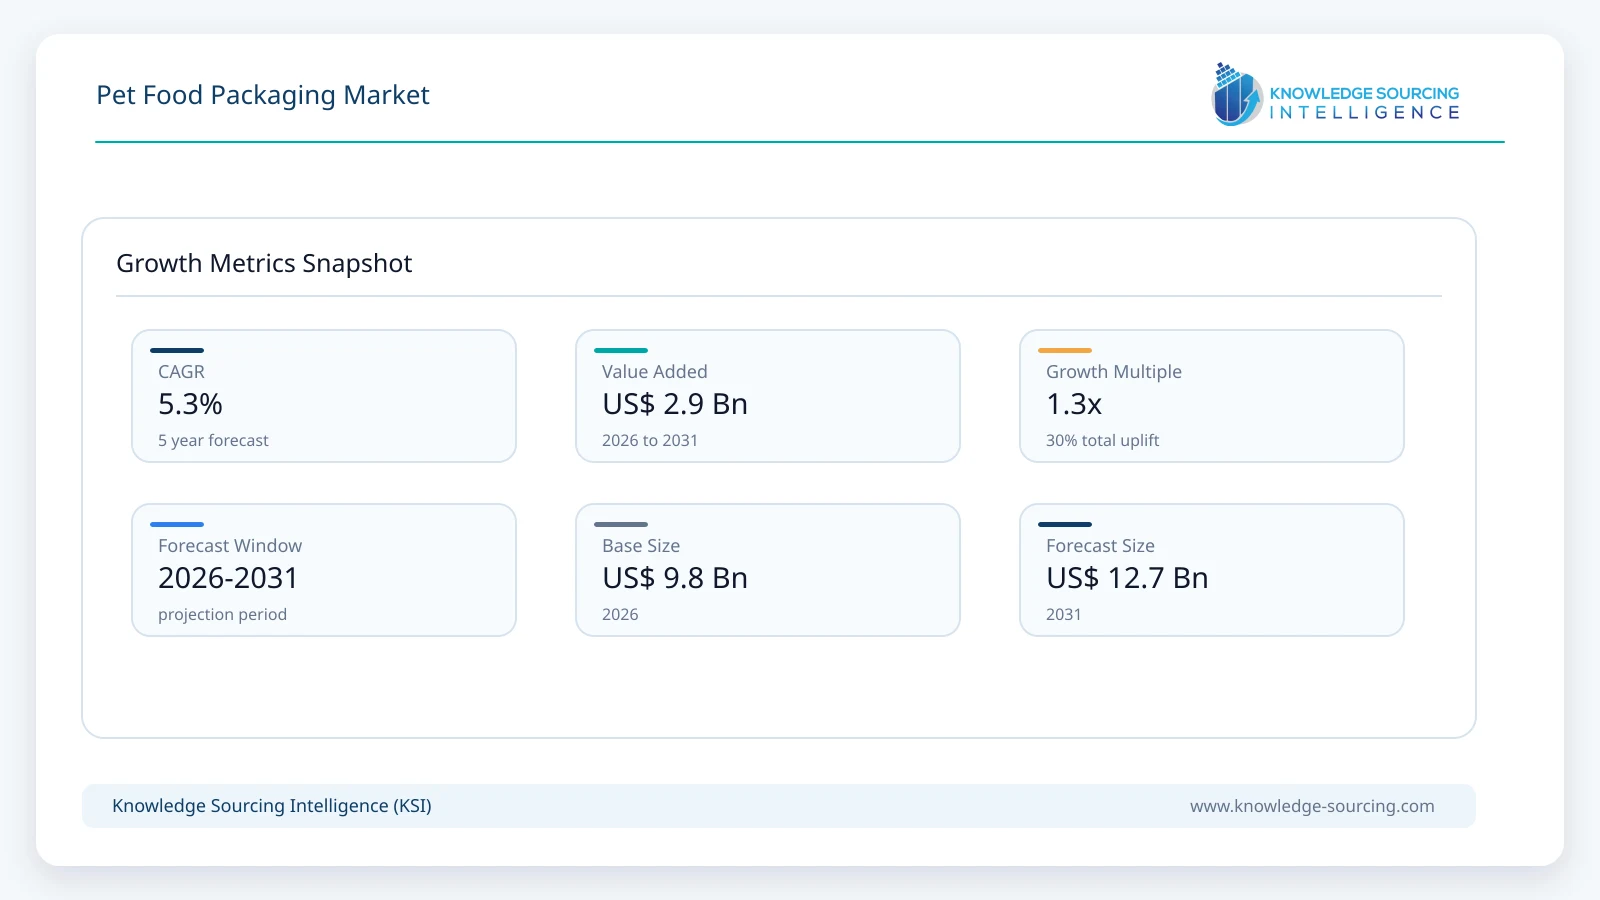
The Pet Food Packaging Market is projected to expand at a 5.3% CAGR, attaining USD 12.67 billion in 2031 from USD 9.77 billion in 2026.
Highlights:
1
Plastic-based flexible packaging accounts for approximately 58% of global pet-food packaging value in 2026.
2
Bags and pouches remain the largest format because dry food, treats and premium products favor flexible packs.
3
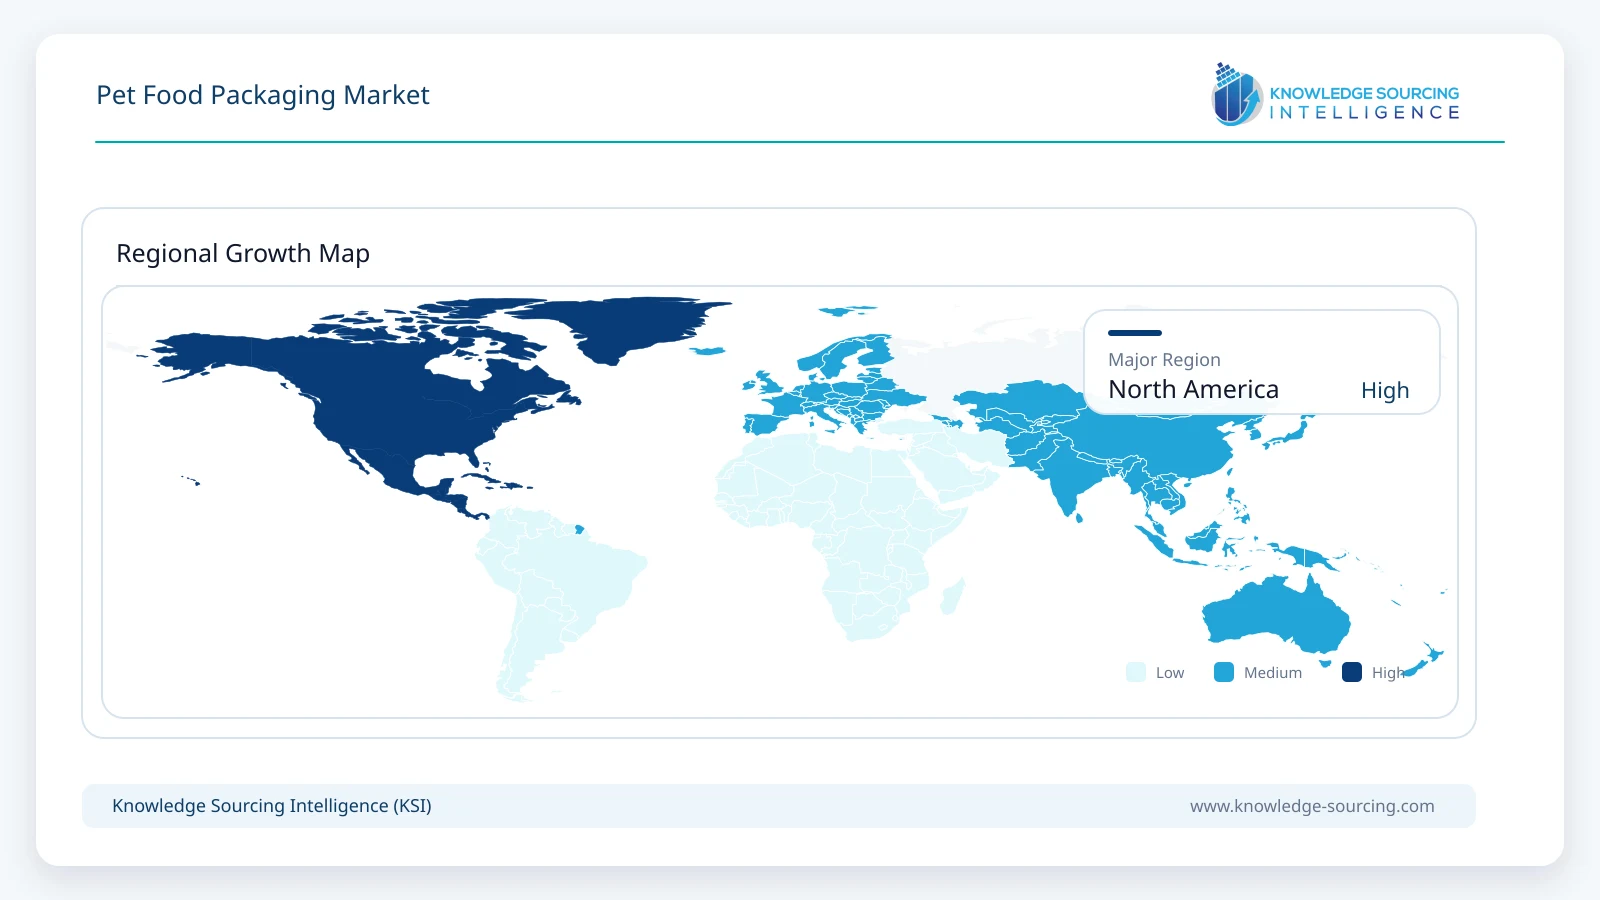
North America contributes approximately 36% of 2026 revenue, supported by high pet-food spending and premiumization.
4
U.S. pet food and treat expenditure reached USD 68.3 billion in 2025 and is projected at USD 69.7 billion in 2026.
5
European pet-food sales reached EUR 29.4 billion across 8.6 million tonnes in the latest FEDIAF statistics.
6
EU packaging rules applying from August 2026 restrict PFAS in food-contact packaging and accelerate redesign.
Pet food packaging has to perform across very different product conditions. Dry kibble and treats require moisture, oxygen and grease barriers alongside tear resistance and reclosure. Wet food requires retort performance and long ambient shelf life, historically favoring metal cans, foil-containing pouches and high-barrier trays. Fresh and refrigerated pet food introduces cold-chain, leak-resistance and e-commerce durability requirements. This diversity explains why the market remains materially multi-format even as recyclability standards push suppliers toward mono-material and paper-based alternatives.
Demand fundamentals remain favorable. The American Pet Products Association reported USD 158 billion of U.S. pet-industry expenditure in 2025, including USD 68.3 billion on pet food and treats, and projects total pet-industry spending of USD 165 billion in 2026. FEDIAF's 2026 statistics report EUR 29.4 billion of annual European pet-food sales and 8.6 million tonnes of products. These are not packaging-market values, but they demonstrate the underlying product base from which packaging demand is generated. Premium recipes, treats, fresh food and single-serve portions typically carry higher packaging value per kilogram than conventional bulk dry food.
Regulation is becoming a direct packaging-design variable. The EU Packaging and Packaging Waste Regulation began applying on 12 August 2026 and restricts PFAS in food-contact packaging above specified thresholds. It also moves the broader packaging market toward recyclability and recycled-content requirements. Pet-food converters are responding with mono-PE and mono-PP structures, paper-based bags and PFAS-free designs. Coveris used Interzoo 2026 to launch PFAS-free mono-material solutions, while Mondi markets recyclable FlexiBag and retortable mono-material pouches for dry and wet pet-food applications.
Market Trends
Recyclable Mono-Material Structures Are Replacing Complex Laminates
Flexible pet-food packs have traditionally used multilayer laminates to combine stiffness, print quality, puncture resistance and oxygen or moisture barriers. The recycling challenge is that mixed structures are difficult to process in standard waste streams. Suppliers are therefore developing mono-PE and mono-PP alternatives with enhanced coatings, metallization and barrier layers. ProAmpac showcased QUADFLEX Recyclable and PRO-EVO Recyclable products at Petfood Forum and Interzoo 2026, while Coveris introduced PFAS-free MonoFlex variants and Mondi continues to expand its re/cycle pet-care portfolio. The technical challenge is maintaining seal integrity and shelf life without reintroducing non-compatible materials.
Wet Pet Food Is Diversifying Beyond Conventional Metal Cans
Metal cans remain a major wet-food format because they tolerate retort processing, provide excellent barrier performance and are widely recycled. However, brands are adding pouches, polypropylene cups, trays and retortable cartons to improve portioning, convenience and logistics. In September 2026, Amcor and Chinese pet-food brand Ge Wu An launched an inverted polypropylene pet-food cup designed to release the meal cleanly into a bowl. Tetra Pak is promoting Tetra Recart as a lightweight carton alternative for wet food, while Winpak supplies retort cups and trays. This expansion creates format competition without eliminating the established can base.
Fresh and Refrigerated Pet Food Is Raising Barrier and E-Commerce Requirements
The growth of fresh and gently processed pet food changes packaging economics because products may require cold-chain distribution, leak-resistant seals and direct-to-consumer shipping durability. Sealed Air markets CRYOVAC films, rollstock and vertical-pouch systems specifically for fresh dog and cat food, while Printpack identifies fresh-food expansion as one of the major packaging trends shaping 2026. Fresh formats generally use more specialized barrier structures and smaller packs than traditional dry kibble, increasing packaging value per kilogram of food even when total category volumes remain lower.
Packaging Is Becoming Part of the Premium Pet-Food Proposition
Pet-food brands increasingly use matte finishes, high-definition graphics, windows, tactile effects, portioning and resealable features to communicate quality. American Packaging Corporation and Winpak both market high-impact printed pouches and reclose options for pet food, while Sonoco uses rigid paper containers and metal cans across treats and wet-food applications. This premiumization matters because packaging can influence brand perception in a category where pets are treated increasingly as family members and owners scrutinize ingredients, freshness and convenience.
Market Drivers
Pet-Food Premiumization Increases Packaging Value per Unit
Premium diets, functional treats, fresh food and single-serve wet formats typically require stronger barrier performance, more sophisticated printing and additional convenience features than economy bulk food. This shifts packaging demand toward high-barrier pouches, trays, cups and resealable bags. The effect is particularly visible in North America and Western Europe, where pet-food expenditure is high and consumers have broad access to super-premium, veterinary, fresh and functional products.
E-Commerce Raises the Importance of Durability and Efficient Shipping
Online pet-food sales place primary packaging into distribution environments that involve parcel handling rather than pallet-to-shelf movement. Large kibble bags need puncture resistance and strong seals, while wet-food multipacks must minimize leakage and excess shipping weight. Flexible packaging, cartons and lighter rigid containers can reduce transport mass relative to traditional formats. Tetra Pak highlights the logistics benefits of flat-packed Tetra Recart cartons, while ProAmpac and Sealed Air explicitly position pet-food products for e-commerce performance.
The EU PPWR adds concrete design pressure around recyclability, recycled content and substances of concern. From 12 August 2026, food-contact packaging containing PFAS above specified thresholds cannot be placed on the EU market. Pet-food packaging often needs grease and moisture resistance, making material reformulation commercially important. Suppliers with in-house film development, coatings, barrier structures and recycling expertise are better positioned to help brand owners transition without sacrificing shelf life or processing speed.
Market Restraints
Barrier Requirements and Recycling Goals Can Conflict Technically and Economically
Pet food can be difficult to package sustainably because fat, moisture, oxygen sensitivity and retort processing require high barrier performance. Multi-layer structures solve these problems effectively but may be difficult to recycle, while simpler mono-material structures can require new coatings, sealants or machinery adjustments. Metal and paper-based alternatives may have stronger recycling pathways but different cost, weight and processing characteristics. Brand owners therefore face a trade-off between shelf life, line efficiency, consumer convenience, regulatory compliance and end-of-life performance. Resin, aluminum, steel and paperboard price volatility can further pressure converter margins.
Segment Analysis
By Material - Plastic
Plastic-based packaging is estimated at approximately USD 5.67 billion in 2026 and remains the largest material segment. Flexible films and rigid polypropylene formats provide low weight, barrier customization, printability and compatibility with bags, pouches, cups and trays. The segment is changing internally as mono-PE and mono-PP structures gain share over conventional mixed laminates. Paper and paperboard are expected to grow faster from a smaller base in dry-food bags, treats and retortable cartons, while metal remains structurally important in wet food because of retort performance and recyclability.
By Packaging Type - Bags and Pouches
Bags and pouches are estimated at approximately USD 4.50 billion in 2026 and represent the largest packaging-format segment. They dominate dry kibble, treats and an increasing share of wet food because they can combine barrier protection with reclosure, easy opening, premium graphics and efficient transport. Metal cans remain the principal rigid wet-food format, while trays, cups, rigid paper containers and cartons provide differentiated single-serve and premium alternatives.
By Type of Food - Dry Food
Dry food is estimated to account for approximately USD 5.56 billion of packaging demand in 2026. Its large physical volume and frequent use of multi-kilogram bags create substantial packaging consumption, particularly in dog food. Wet food is smaller by tonnage but often carries higher packaging value per kilogram because it uses retort cans, trays, cups or high-barrier pouches. Fresh and refrigerated food, included within the relevant food-format categories, grows faster from a low base because it relies on high-performance barrier and cold-chain packaging.
By Animal - Dog Food
Dog-food packaging is estimated at approximately USD 5.96 billion in 2026 and remains the largest animal segment because dogs account for high food consumption per pet and a large share of dry-food and treat volumes. Cat food packaging has a higher exposure to wet, single-serve and portion-controlled formats, which raises packaging value intensity. Other companion-animal categories remain smaller and use a broader mix of pouches, cartons and rigid containers.
By Distribution Channel - Offline
Offline retail is estimated at approximately USD 7.33 billion in 2026 and remains the largest distribution channel. Supermarkets, pet-specialty stores, veterinary channels and mass merchants continue to account for most packaged pet-food sales globally. Online channels grow faster because subscriptions and direct-to-consumer fresh-food models are expanding, but they also impose stricter requirements for package durability, leakage prevention and efficient parcel shipping.
By Geography - North America
North America is estimated at approximately USD 3.52 billion in 2026 and remains the largest regional market. The United States combines high pet ownership, USD 68.3 billion of 2025 pet-food and treat spending, strong premiumization and an advanced fresh-food and e-commerce ecosystem. Europe is a major market for recyclable and PPWR-compliant formats, while Asia Pacific is expected to grow faster as packaged pet food expands in China, India and Southeast Asia and local brands adopt higher-value wet and premium products.
Competitive Environment
Competition spans flexible converters, metal-can manufacturers, rigid-container suppliers and carton-system companies. Amcor, Mondi, ProAmpac, Huhtamaki, Constantia Flexibles, Coveris, American Packaging Corporation, Printpack and Hood Packaging are important in flexible pet-food packaging. Sonoco combines metal and rigid-paper formats, while Crown and Silgan remain important in food cans. Winpak participates in retort trays, cups, films and pouches; Sealed Air is strong in fresh-food and flexible systems; Tetra Pak offers retortable cartons, and Smurfit Westrock supplies paper-based pet-food packaging for retail and e-commerce. for wet pet food. Supplier breadth matters because pet-food companies increasingly want recyclable alternatives without changing filling-line performance or shelf-life targets.
Recent Developments
September 2026: Amcor and Ge Wu An launched the Li Kou inverted polypropylene wet-pet-food cup in China, using top and bottom seal films for cleaner serving.
August 2026: The EU Packaging and Packaging Waste Regulation began applying, including PFAS limits for food-contact packaging placed on the EU market.
May 2026: ProAmpac presented recyclable and high-performance packaging for dry, wet, freeze-dried pet food and treats at Interzoo 2026.
April 2026: Coveris launched PFAS-free mono-material pet-food packaging solutions at Interzoo in preparation for EU PPWR requirements.
April 2026: Drools and Tetra Pak announced large-scale fresh pet-food production in India using Tetra Recart packaging and INR 180 crore of investment.
April 2025: Amcor completed its combination with Berry Global, consolidating two major flexible and rigid packaging portfolios.
Pet Food Packaging Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 9.77 billion
Total Market Size in 2031
USD 12.67 billion
Forecast Unit
Billion
Growth Rate
5.3%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Material, Packaging Type, Type of Food, Animal, Distribution Channel, Geography
Companies
Amcor plc
Mondi plc
ProAmpac LLC
Sonoco Products Company
Huhtamaki Oyj
Market Segmentation
By Material
Plastic
Paper and Paperboard
Metal
Others
By Packaging Type
Bags and Pouches
Metal Cans
Trays and Cups
Cartons and Rigid Paper Containers
Others
By Type of Food
Dry Food and Treats
Wet Food
Fresh / Refrigerated Food
By Animal
Dog Food
Cat Food
Other Companion Animals
By Distribution Channel
Offline
Online
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Pet-Food Premiumization Increases Packaging Value per Unit
3.1.2. E-Commerce Raises the Importance of Durability and Efficient Shipping