
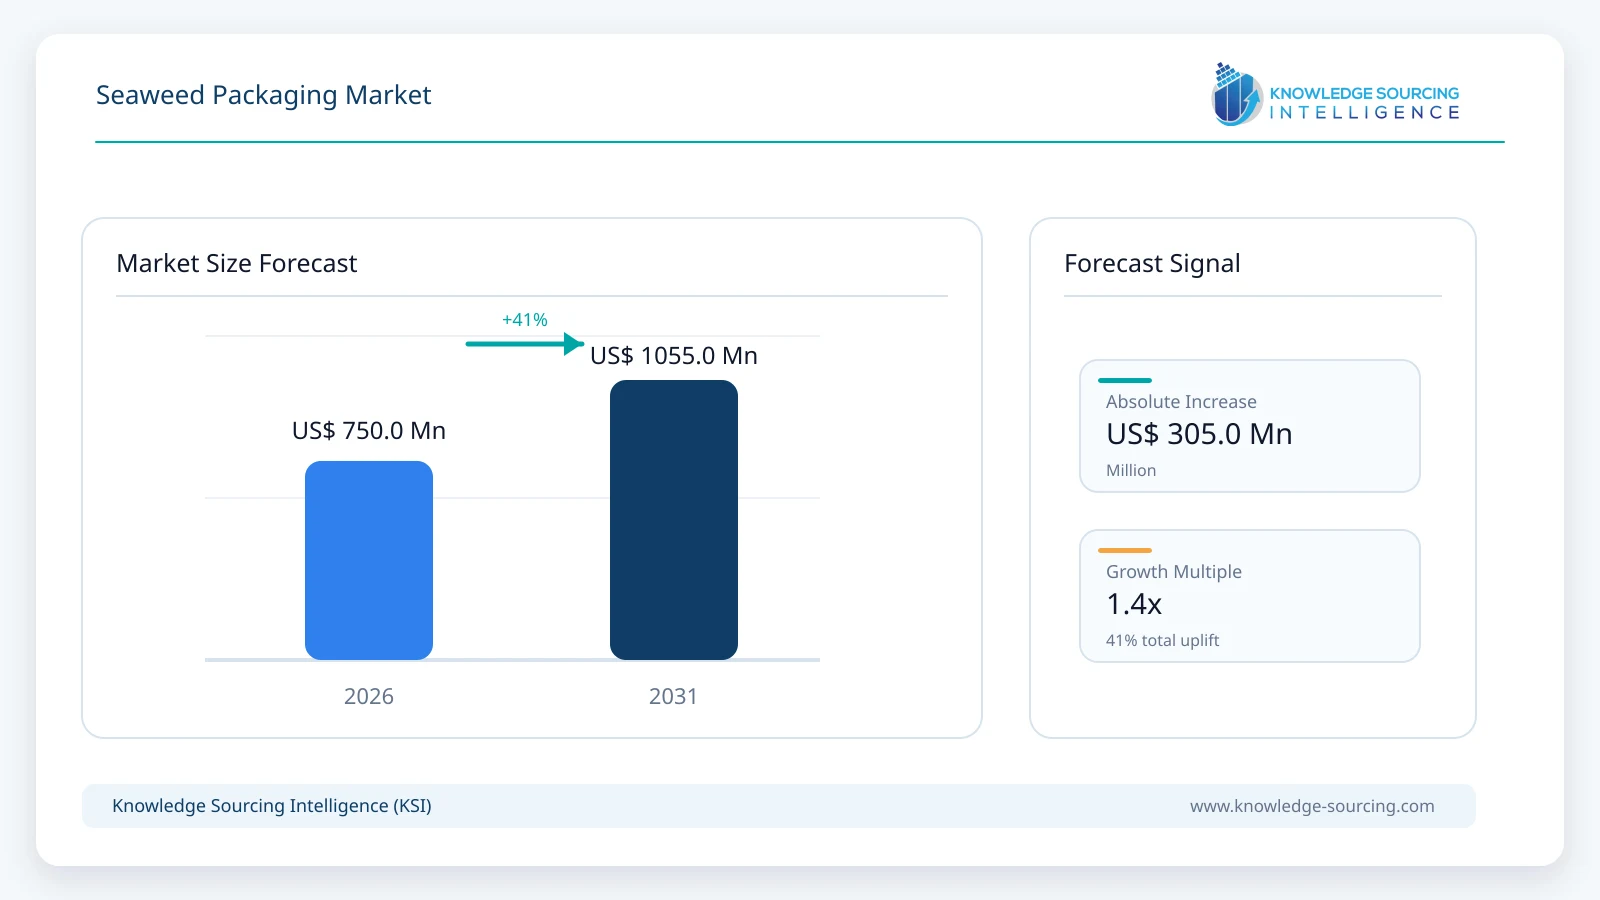
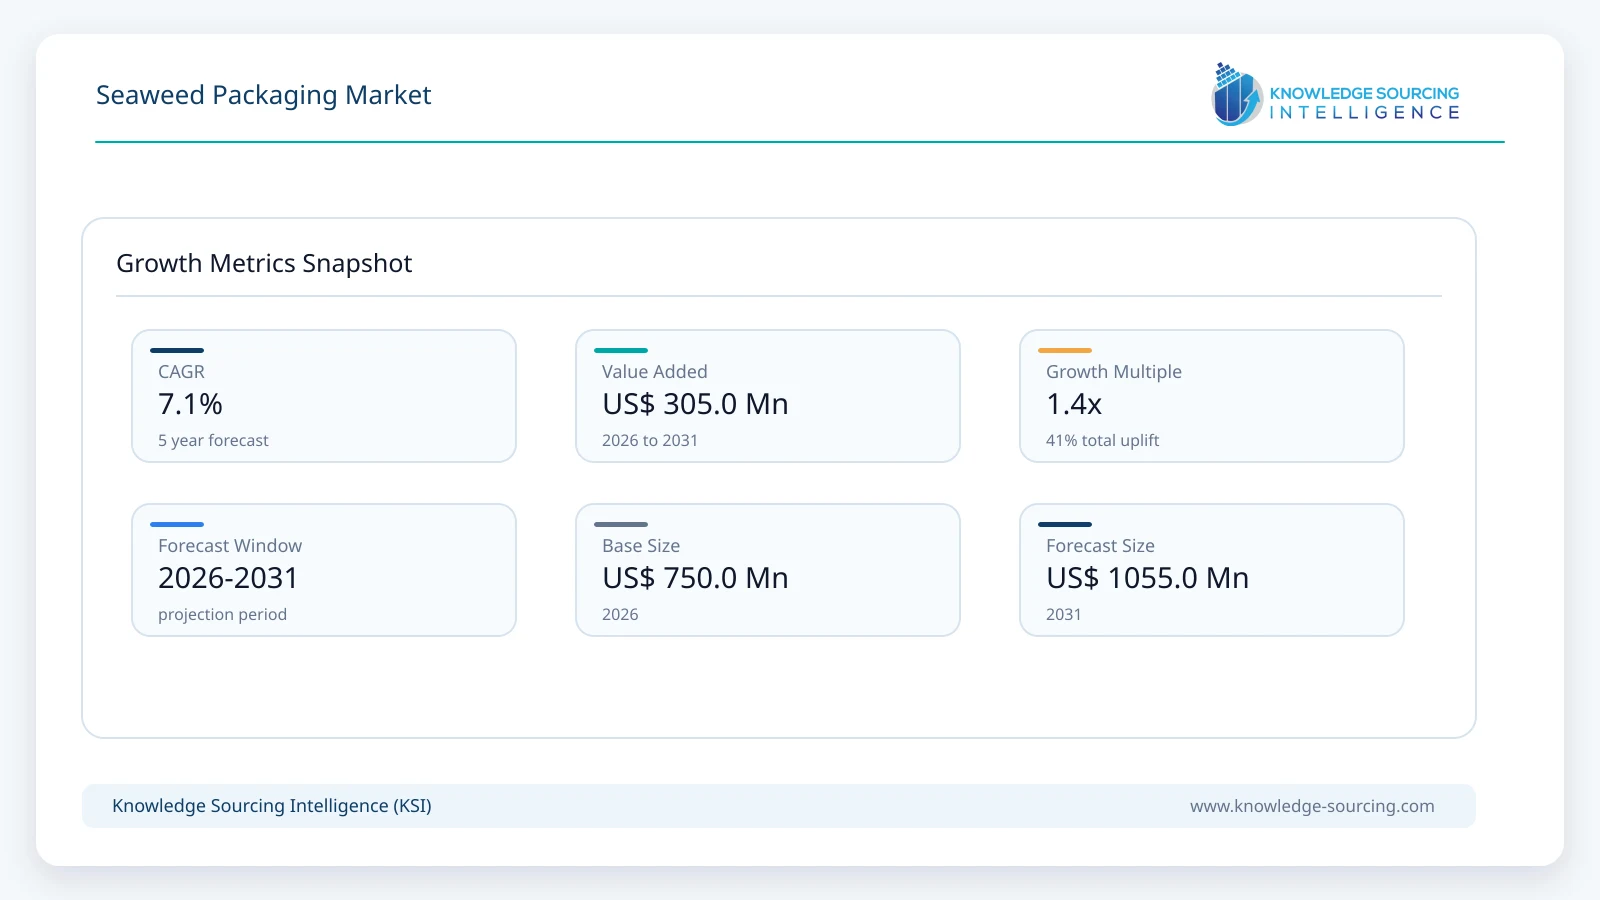
The global seaweed packaging market is estimated at USD 750.0 million in 2026 and is projected to reach USD 1,055.0 million by 2031, growing at a CAGR of approximately 7.1% during the forecast period.
Highlights:
- 1Films and flexible packaging account for approximately 39% of global seaweed packaging revenue in 2026.
- 2Food and beverage applications generate about USD 412.5 million of market value in 2026.
- 3Direct sales account for approximately 66% of seaweed packaging revenue in 2026.
- 4Europe represents roughly 35% of global seaweed packaging market value in 2026.
- 5Barrier coatings are becoming a practical route for replacing hidden plastic in fiber-based packaging.
- 6Commercial adoption is increasing where seaweed materials can use established film and paper-converting infrastructure.
Seaweed packaging includes films, flexible materials, coatings, coated paperboard, rigid formats and edible or dissolvable structures in which seaweed or seaweed-derived polymers form a meaningful part of the material system. The commercial opportunity is broader than fully seaweed-based packaging because many scalable products combine seaweed-derived functionality with paper, plant-based binders or certified compostable polymers. This allows suppliers to target high-volume applications while progressively increasing renewable content and reducing fossil-plastic use.
The market is still fragmented and technology-led. Notpla has commercialized seaweed-coated foodservice container and flexible edible formats, Sway supplies home-compostable flexible films and polybags, Kelpi develops seaweed-derived high-barrier coatings for fiber packaging, and B'ZEOS is developing seaweed-based pellets for films, pouches and rigid applications. Zerocircle is scaling coated paperboard and foodservice formats in India and Europe, while companies including Loliware, Marine Innovation, Searo Labs, FlexSea and Sea6 Energy are developing seaweed-derived resins, films or molded products. This diversity makes material performance and converter compatibility more important than a single dominant product architecture.
Market Trends
Barrier coatings are emerging as a lower-friction route to commercial scale
Replacing the thin plastic layer inside paper-based packaging is becoming one of the most commercially attractive applications for seaweed-derived materials. Notpla's foodservice containers use a natural seaweed coating instead of conventional plastic lining, while Kelpi is working with Amcor to evaluate seaweed-derived high-barrier coatings within Amcor's fiber-packaging portfolio. Zerocircle is similarly commercializing grease-resistant coated paperboard for food packaging. Coating-based systems can scale faster than fully new packaging substrates because converters can retain much of the existing paperboard structure, printing process and package design while changing the functional barrier layer.
Flexible seaweed films are moving from pilots toward standardized commercial formats
Flexible seaweed packaging is also progressing toward repeatable commercial production. Sway's TPSea Flex is produced using conventional blown-film and conversion infrastructure and is sold through distributors including EcoEnclose and Atlantic Packaging. The company reports deployments with fashion and outdoor brands and is scaling polybag use with customers during 2026. B'ZEOS offers seaweed-based pellets for protective films, wrapping films, flowpacks and pouches, while Searo Labs and FlexSea continue developing natural films and biopolymers for flexible applications. The commercial challenge is increasingly less about proving film formation and more about cost, consistency, sealing performance, barrier properties and certification.
Market Drivers
Packaging regulation is increasing the value of verified plastic-free and compostable alternatives
Packaging regulation is creating stronger incentives to remove fossil-plastic components from single-use formats. The European Union's Packaging and Packaging Waste Regulation establishes new requirements around packaging design, waste reduction and end-of-life performance, while the Single-Use Plastics framework has already affected how natural-polymer materials are classified. Notpla's seaweed coating has received recognition in the Netherlands as a natural, non-chemically modified material outside the conventional plastic definition used under the Single-Use Plastics framework. These regulatory distinctions matter commercially because brand owners increasingly need packaging materials that meet both performance and legal end-of-life requirements rather than relying only on broad sustainability claims.
Converter partnerships are shortening the route from biomaterial development to packaging deployment
The second major driver is the growing involvement of established packaging converters and distributors. Kelpi's 2026 collaboration with Amcor gives its coating technology access to a global fiber-packaging development platform, while its Guardpack partnership targets liquid-filled sachets. Sway is using existing film-manufacturing equipment and commercial distributors rather than building a vertically integrated packaging network. Zerocircle similarly works with packaging manufacturers and foodservice brands to integrate seaweed coatings into current production workflows. These partnerships reduce the capital required for material developers and improve the probability that new formulations can reach commercial volume.
Market Restraint
Cost, performance consistency and end-of-life infrastructure still limit mass-market substitution
Seaweed-derived packaging remains more expensive and operationally less standardized than conventional polyethylene, polypropylene and plastic-coated paper. High-volume packaging buyers require consistent barrier performance, sealing behavior, printability, shelf life and machine speed across large production runs. Compostable materials also depend on clear disposal pathways; a product that is technically compostable may still enter landfill where collection infrastructure is absent. Some emerging seaweed films blend natural feedstocks with certified compostable polymers to achieve industrial performance, which can complicate claims around renewable content and recyclability. These factors slow substitution in commodity packaging where price and production reliability dominate purchasing decisions.
Seaweed Packaging Market Segment Analysis
By Product Type
Films and Flexible Packaging
Films and flexible packaging are projected to generate approximately USD 455 million in market revenue by 2031. The segment includes polybags, wrapping films, pouches, sachets and specialty flexible structures. Sway has demonstrated a route to scale through blown-film manufacturing and commercial distributors, while B'ZEOS is developing pellet grades compatible with established conversion methods. Seaweed films remain technically demanding because flexible packaging requires a combination of tensile strength, heat sealing, moisture resistance and barrier performance at low material thickness. Their growth potential is substantial because conventional flexible packaging is difficult to recycle and used at very high volumes.
By Application
Food and Beverages
Food and beverage applications are projected to grow at approximately 6.8% annually through 2031. The segment includes coated takeaway boxes, trays, cups, edible or dissolvable sachets, wraps and barrier materials used in food-to-go and foodservice packaging. Notpla's SeaView range and coated containers demonstrate how seaweed can replace hidden plastic while retaining familiar paper-based packaging formats. Zerocircle and Marine Innovation also target foodservice containers and coated board. Food applications remain commercially attractive because single-use formats have short functional lives, making permanent fossil-plastic barriers especially difficult to justify from a waste perspective.
By Distribution Channel
Direct Sales
Direct sales are projected to generate approximately USD 665 million by 2031. Material developers still work closely with brand owners and converters because seaweed packaging frequently requires application testing, material qualification and packaging-line trials before adoption. This favors direct technical selling and co-development, particularly for coatings, sachets and custom flexible films. Indirect distribution is becoming more important as products mature; Sway's availability through packaging distributors shows how standardized seaweed packaging can move into normal procurement channels once material performance and conversion specifications are established.
By Geography
Europe
Europe is projected to reach approximately USD 375 million in seaweed packaging revenue by 2031. The region combines strong packaging regulation with an active biomaterials ecosystem led by companies such as Notpla, Kelpi, B'ZEOS, Searo Labs and FlexSea.
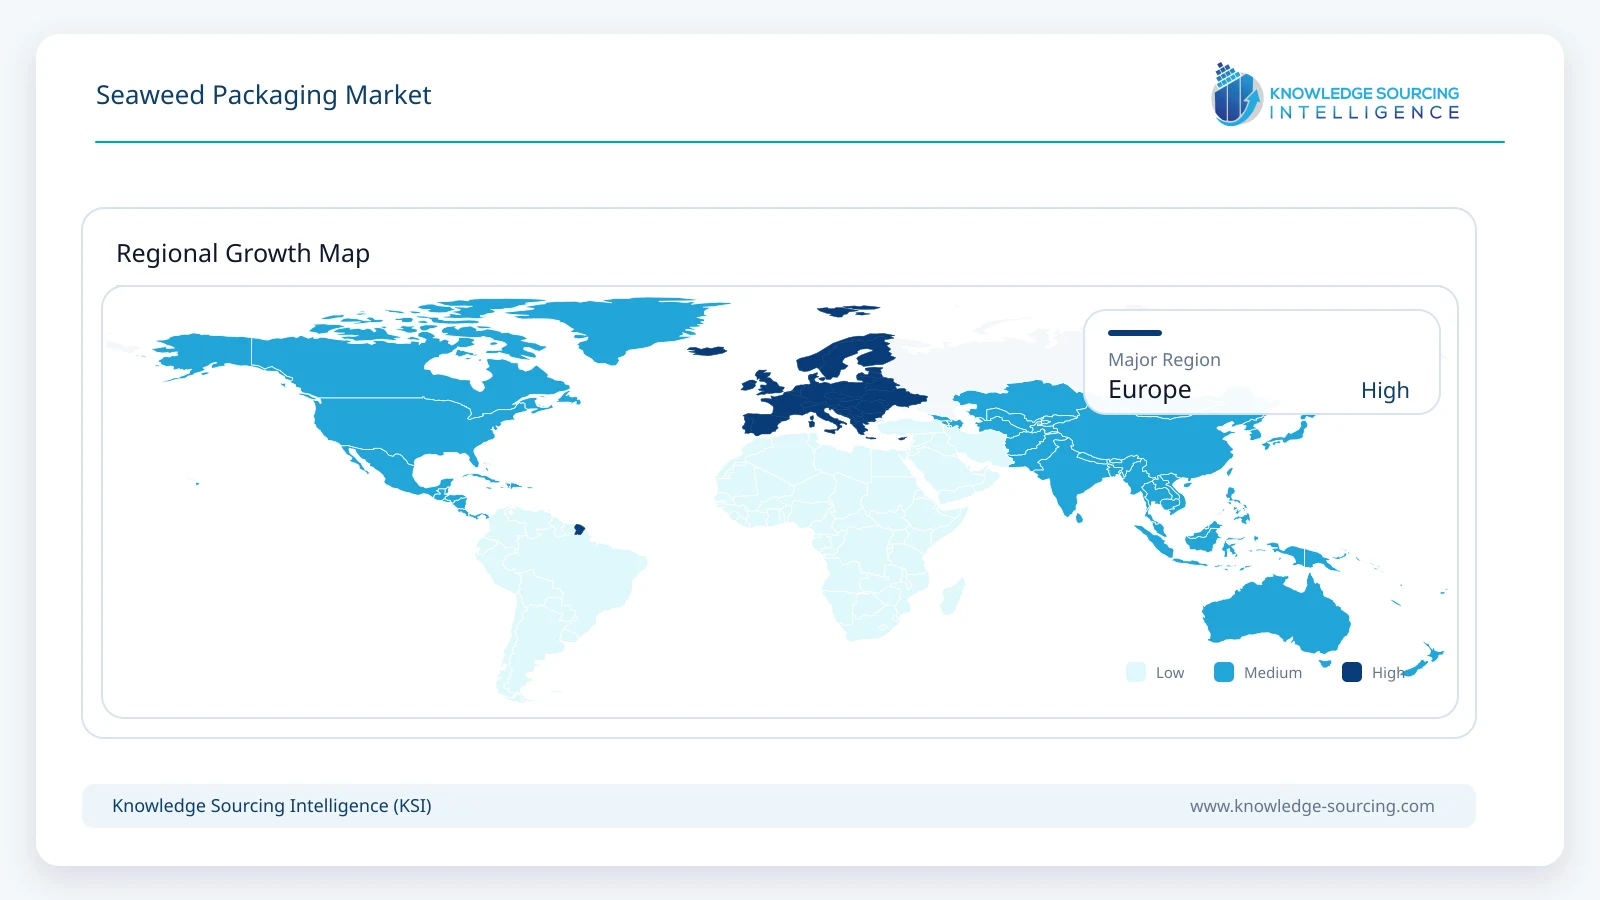
The European Union's packaging rules strengthen commercial interest in plastic reduction, recyclability and compostability, while established paper and packaging converters provide a route for new coatings and films to scale. North America is building momentum through flexible-film and retail-packaging deployments, while Asia Pacific benefits from a large seaweed production base and emerging packaging companies in India, Indonesia and South Korea.
Competitive Environment
Competition is defined by material platform rather than conventional packaging scale. Notpla leads in seaweed-coated foodservice packaging and edible flexible formats, Sway has progressed furthest in seaweed-based flexible film sold through mainstream packaging distributors, and Kelpi is building a commercialization pathway through coatings and partnerships with established converters. B'ZEOS is developing pelletized feedstocks for multiple packaging formats, while Zerocircle has commercial activity in coated foodservice packaging. Loliware and Sea6 Energy extend the competitive landscape into seaweed-derived resins and bioplastics, with additional innovation coming from Marine Innovation, Searo Labs, FlexSea and other specialists.
The strategic bottleneck is scale-up rather than laboratory formulation. Companies that can run materials on existing extrusion, coating, thermoforming or paper-converting lines have a clear commercial advantage because they reduce the need for customers to purchase new equipment. Partnerships with global packaging companies and distributors are therefore becoming as important as proprietary chemistry. The market is likely to remain fragmented through 2031, but a smaller group of material platforms could gain disproportionate share if they achieve consistent industrial-scale production, certification and cost reduction.
Recent Developments
June 2026: Kelpi partnered with Amcor to evaluate seaweed-derived high-barrier coatings across Amcor's fiber-based packaging portfolio.
May 2026: Notpla launched SeaView, a food-to-go range combining seaweed-coated fiber packaging with a transparent seaweed-based window.
April 2026: Kelpi announced the first planned commercial deployment of its seaweed-derived coating through refill-sachet brand Homethings.
January 2026: Kelpi partnered with Guardpack to develop seaweed-coated paper sachets for liquid-filled applications.
Seaweed Packaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 750.0 million |
| Total Market Size in 2031 | USD 1,055.0 million |
| Forecast Unit | Million |
| Growth Rate | 7.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Application, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product Type
Films and Flexible Packaging
Coatings and Coated Paper / Board
Rigid, Molded and Edible Formats
By Application
Food and Beverages
Retail, Apparel and E-Commerce
Personal Care and Cosmetics
Pharmaceutical and Healthcare
Others
By Distribution Channel
Direct Sales
Indirect Sales
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Packaging Regulation Is Increasing the Value of Verified Plastic-Free and Compostable Alternatives
3.1.2. Converter Partnerships Are Shortening the Route from Biomaterial Development to Packaging Deployment
3.2. Market Restraint
3.2.1. Cost, Performance Consistency and End-of-Life Infrastructure Still Limit Mass-Market Substitution
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Seaweed-Derived Barrier Coatings
4.2. Flexible Films and Thermoplastic Seaweed Resins
4.3. Edible, Dissolvable and Home-Compostable Formats
5. SEAWEED PACKAGING MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Films and Flexible Packaging
5.3. Coatings and Coated Paper / Board
5.4. Rigid, Molded and Edible Formats
6. SEAWEED PACKAGING MARKET BY APPLICATION
6.1. Introduction
6.2. Food and Beverages
6.3. Retail, Apparel and E-Commerce
6.4. Personal Care and Cosmetics
6.5. Pharmaceutical and Healthcare
6.6. Others
7. SEAWEED PACKAGING MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Direct Sales
7.3. Indirect Sales
8. SEAWEED PACKAGING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Notpla Limited
10.2. Sway Innovation Co.
10.3. Kelpi
10.4. B'ZEOS
10.5. Zerocircle
10.6. Loliware Inc.
10.7. Sea6 Energy Pvt. Ltd.
10.8. Marine Innovation Co., Ltd.
10.9. Searo Labs
10.10. FlexSea Ltd.
10.11. Evoware
10.12. Oceanium Ltd.
10.13. muj?
10.14. Amcor plc
10.15. EcoEnclose
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











