
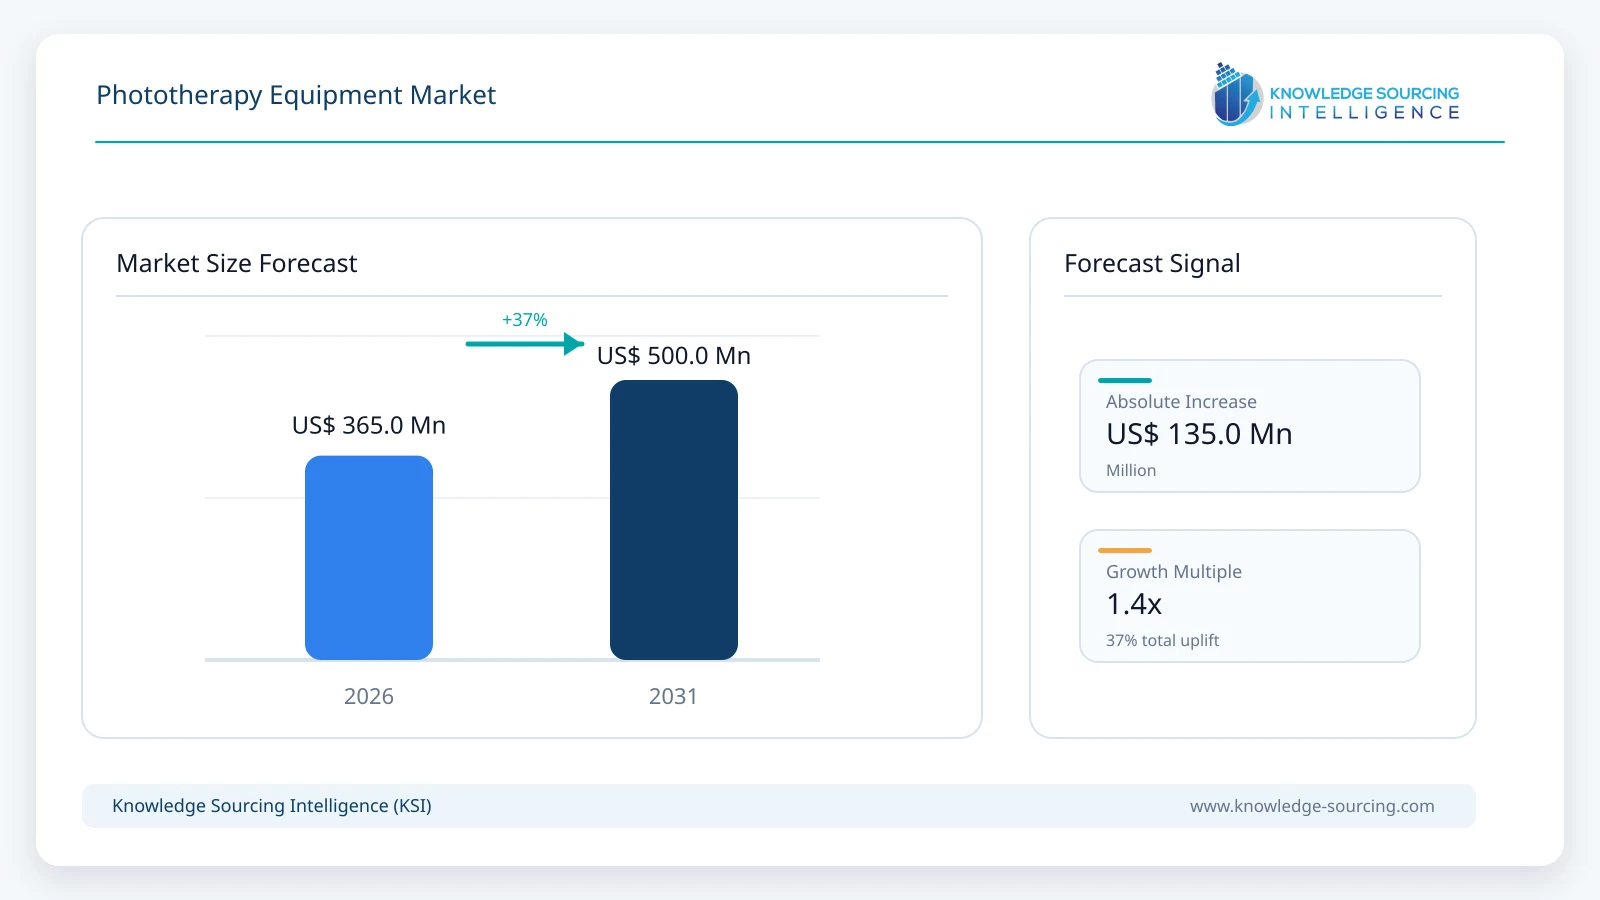
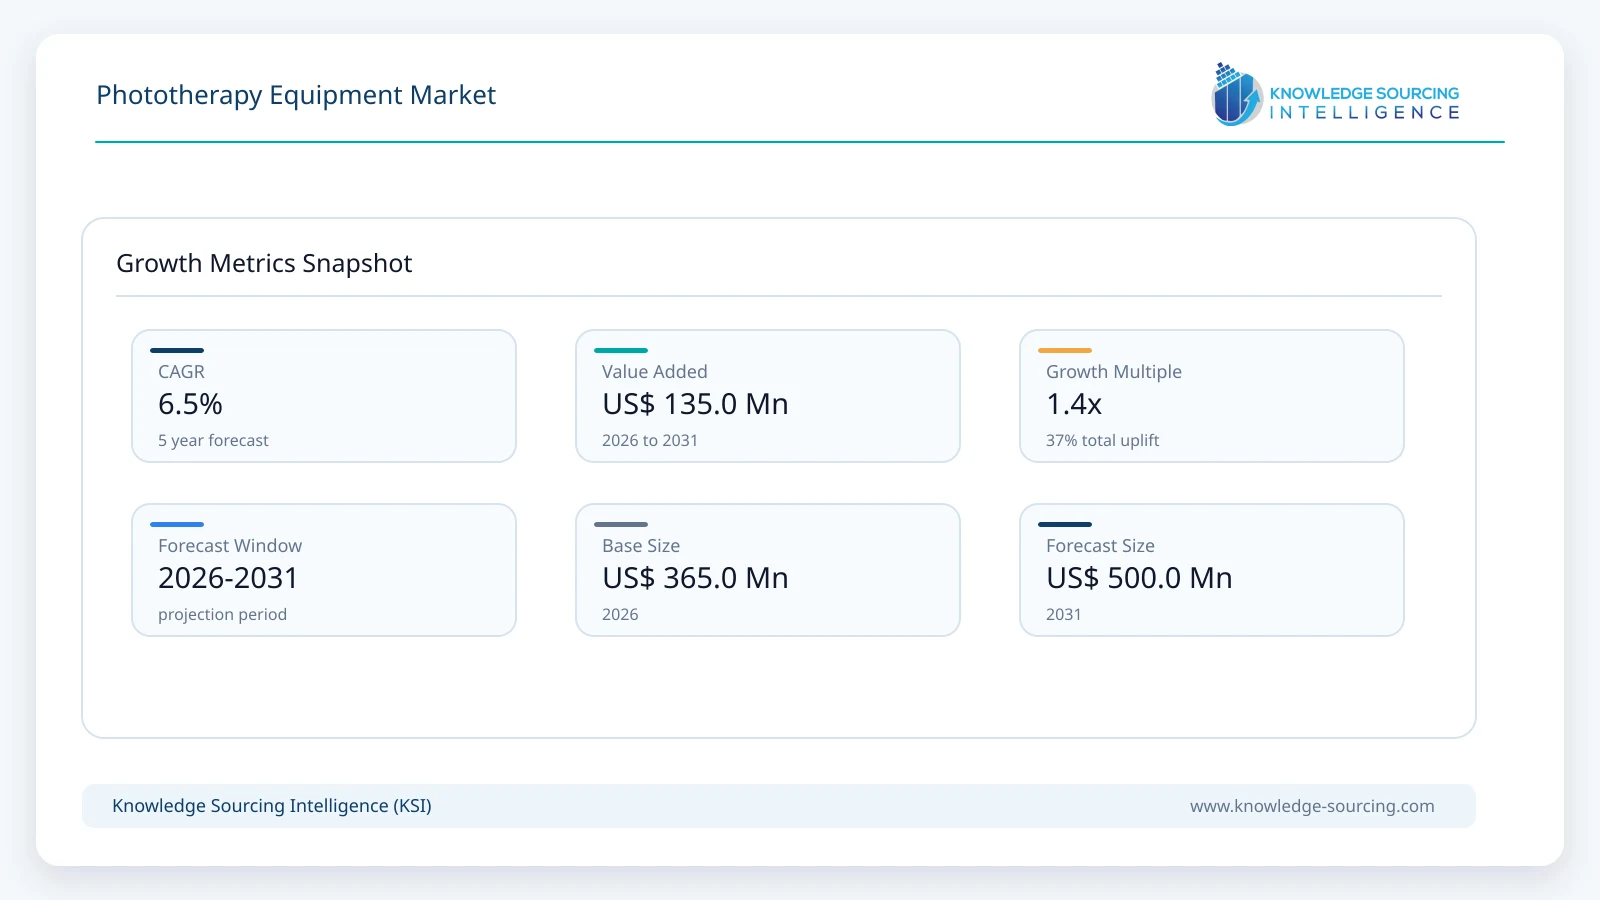
The global phototherapy equipment market is estimated at USD 365.0 million in 2026 and is projected to reach USD 500.0 million by 2031, growing at a CAGR of 6.5% across 2026-2031.
Highlights:
- 1Dermatology applications account for an estimated 68% of global 2026 equipment revenue.
- 2Blue LED platforms are becoming the standard configuration for new neonatal phototherapy installations.
- 3Home narrowband UVB adoption is supported by stronger comparative clinical evidence and adherence.
- 4Wearable neonatal systems are expanding treatment options beyond conventional overhead phototherapy configurations.
- 5FDA clearances in 2025–2026 show continuing innovation in both neonatal and dermatology systems.
The estimate is restricted to finished regulated phototherapy equipment and excludes treatment-service revenue, general wellness light products, cosmetic-only devices, and adjacent photodynamic-therapy platforms.
Technology development is shifting value toward narrow-spectrum, dose-controlled, and portable equipment. In neonatal care, blue LEDs have largely displaced fluorescent and halogen sources in new installations because they provide clinically useful wavelengths with long operating life and lower heat generation. In dermatology, full-body cabinets remain relevant for generalized disease, while targeted handheld, excimer, and digitally controlled home systems are expanding treatment access. The market is therefore moving from a purely hospital-capital-equipment model toward a mixed institutional and prescribed-home ecosystem.
Market Drivers
Large and persistent neonatal jaundice treatment requirement
Global births remain above 130 million annually, creating a large recurring clinical base for jaundice screening and treatment. The American Academy of Pediatrics states that more than 80% of newborn infants develop some degree of jaundice and recommends intensive phototherapy when bilirubin thresholds are met. Current guidance emphasizes narrow-spectrum blue light, adequate irradiance, and broad body-surface exposure, supporting replacement of older fluorescent equipment with calibrated LED systems. Demand is particularly important in countries expanding facility-based births and neonatal intensive-care capacity, where phototherapy is a comparatively low-complexity intervention with high clinical value.
Chronic dermatology demand supports repeat equipment utilization
Phototherapy remains an established treatment for psoriasis, vitiligo, eczema, and other photo-responsive disorders despite the expansion of biologic and small-molecule therapies. The global psoriasis population alone is measured in the tens of millions, while treatment may require multiple sessions per week during induction. This repeated-use pattern supports durable utilization of office-based cabinets and targeted systems. STRATA Skin Sciences reported 842 XTRAC systems placed in U.S. dermatology offices at the end of 2025 and generated USD 30.7 million of total 2025 revenue, illustrating the commercial scale achievable within a single targeted-phototherapy platform.
Evidence base for home phototherapy improves the adoption case
The 2024 LITE randomized clinical trial compared home and office narrowband UVB phototherapy for psoriasis across 783 patients and found home treatment noninferior for physician- and patient-reported outcomes. Home patients also showed higher treatment adherence, while avoiding repeated travel to clinics. This evidence is commercially important because home systems address two of the main barriers to office phototherapy: geographic access and treatment frequency. The result supports continued growth for prescribed full-body panels, localized devices, and digitally controlled home units, particularly in North America.
Portable and family-centered neonatal systems broaden addressable settings
New-generation neonatal systems increasingly prioritize uninterrupted feeding, skin-to-skin contact, and treatment outside a fixed NICU bed. Natus offers a neoBLUE blanket platform for hospital and home use, while new products such as Gerium Medical's BiliWrap and TheraB's SnugLit demonstrate the shift toward wrap and wearable formats. The U.S. FDA cleared BiliWrap in May 2025 and SnugLit in January 2026; Natus subsequently announced the acquisition of TheraB in February 2026. These developments indicate growing strategic interest in portable neonatal phototherapy rather than only conventional overhead lamps.
Market Restraints
Risk of burns, erythema, thermal stress, ocular injury, or incorrect dosing requires controlled irradiance, training, and appropriate patient selection.
Capital cost and reimbursement differences can limit access to full-body cabinets, excimer systems, and home devices.
Biologic therapies and other systemic treatments compete with phototherapy in moderate-to-severe dermatology indications.
Long replacement cycles for LED neonatal systems reduce recurring capital demand once hospitals complete modernization programs.
Regulatory requirements under FDA Class II rules, EU MDR, IEC standards, and local registrations raise development and market-entry costs.
Global Phototherapy Equipment Market Segment Analysis
By Therapeutic Platform
UVB/UVA dermatology systems form the largest platform group because they serve recurring treatment pathways across psoriasis, vitiligo, eczema, and selected other conditions. The category ranges from full-body cabinets to localized hand-foot and handheld systems and increasingly includes prescribed home equipment. Targeted 308 nm excimer systems represent a smaller but higher-value subsegment, supported by dermatologist adoption and continuing FDA clearances from manufacturers such as Xuzhou Kernel Medical and Boston Aesthetics.
Blue-light neonatal phototherapy systems remain the second major platform. The neonatal-jaundice segment is estimated at approximately USD 115.0 million in 2026 and is expected to expand faster than the overall market as emerging economies add NICU and maternity capacity and as blanket, under-body, and wearable formats increase addressable use. LED products from Natus, GE HealthCare, Dräger, Atom Medical, Phoenix, Fanem, Bistos, Ningbo David, and other suppliers demonstrate the breadth of active competition.
By Application
Skin-disease treatment is the largest application, supported by long-duration disease management and repeated exposure schedules. Psoriasis is the most commercially significant indication, followed by vitiligo and atopic dermatitis/eczema. Neonatal jaundice management is a distinct clinical market with lower unit prices on average but very broad geographic requirements. The product mix is moving toward high-intensity blue LED systems, under-body pads, and wearable solutions that can maintain therapy while improving infant handling and caregiver interaction.
By End User
Hospitals, dermatology clinics, and physician offices remain the largest purchasing channel because they operate intensive neonatal units, full-body UV equipment, and targeted excimer platforms. Home care is the fastest-developing end-use setting, supported by prescribed NB-UVB units and neonatal blanket or wearable systems. The home segment is expected to grow at roughly 8% annually through 2031, outpacing institutional demand, although physician supervision, payer coverage, and dosing controls remain important adoption conditions.
Regional Analysis
North America
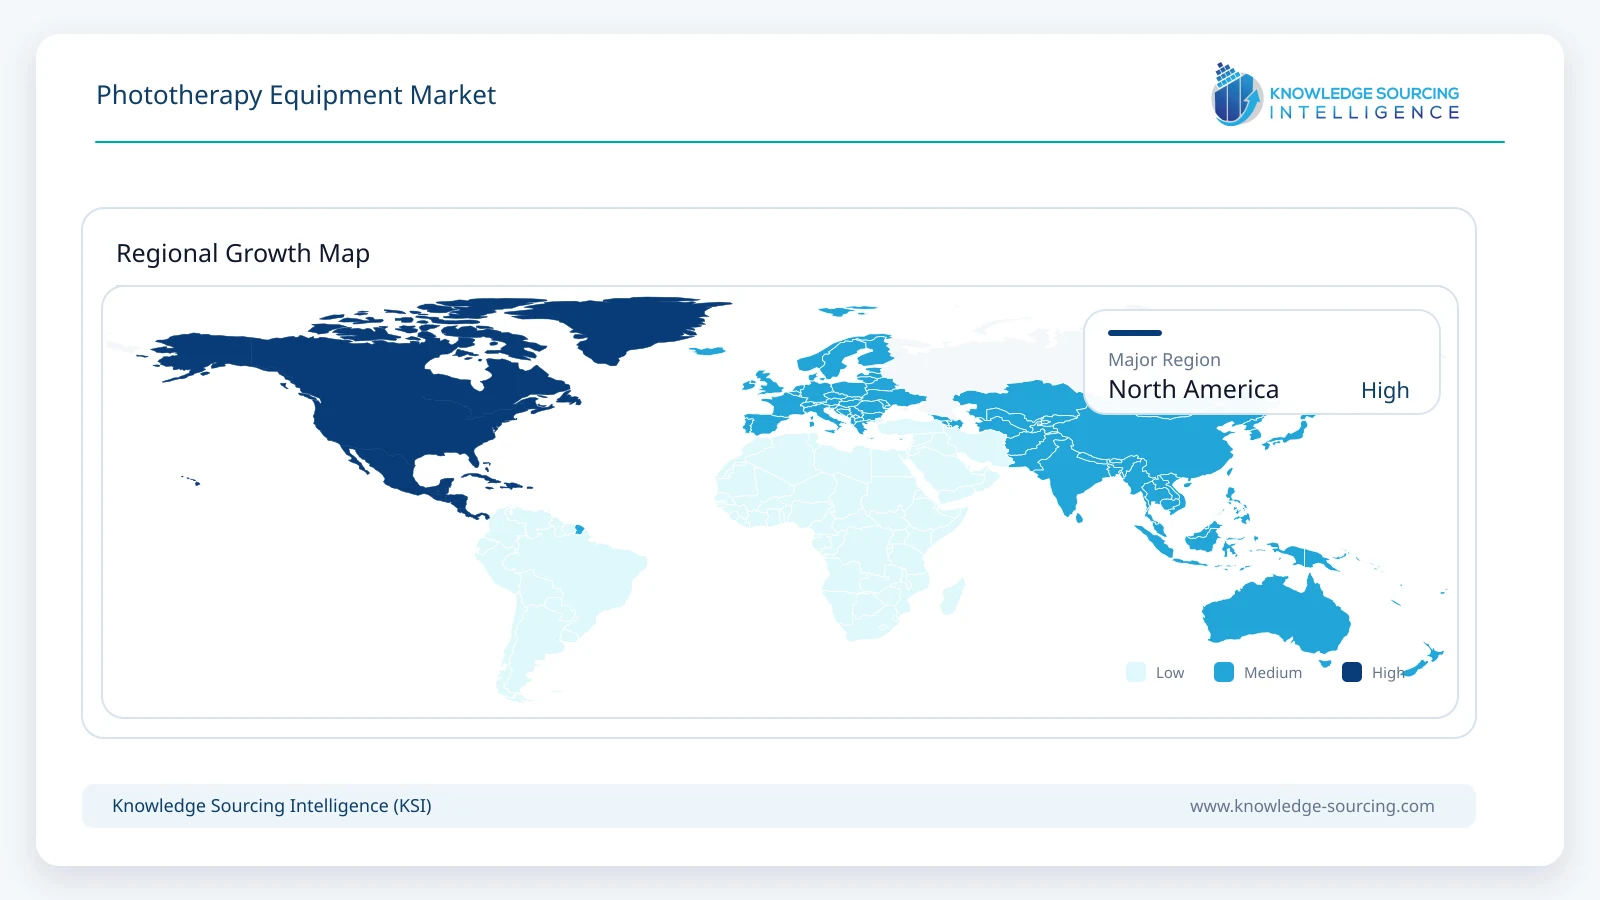
North America represents the largest regional market, estimated at about 39% of global 2026 revenue. The United States combines a large dermatology practice base, established reimbursement for medically necessary phototherapy, active home-phototherapy suppliers, and a mature regulatory pathway for Class II UV and neonatal phototherapy devices. The region also has a large installed base of targeted excimer systems and remains an important launch market for portable neonatal platforms.
Europe
Europe has a mature dermatology phototherapy infrastructure and broad clinical use of narrowband UVB. EU MDR compliance and device-portfolio rationalization can increase supplier costs, while the discontinuation of new phototherapy-equipment sales by Herbert Waldmann illustrates the pressure on legacy equipment portfolios. Demand remains concentrated in replacement systems, modern dosimetry, and selected home-care products.
Asia Pacific
Asia Pacific is expected to record the fastest overall growth. High annual birth volumes in India and other South Asian markets support neonatal equipment procurement, while China has developed a substantial domestic supplier base for both neonatal and dermatology equipment. Xuzhou Kernel Medical, Shanghai SIGMA High-Tech, Ningbo David Medical Device, and other regional manufacturers are increasingly obtaining international regulatory clearances, expanding their export potential.
South America and Middle East & Africa
Growth in these regions is linked primarily to neonatal-care infrastructure, replacement of fluorescent systems with LEDs, and selective adoption of dermatology phototherapy in private and specialist clinics. Cost-sensitive procurement favors durable LED systems with long light-source life, portable designs, and equipment that can operate across multiple clinical settings.
Competitive Environment
The competitive landscape is fragmented between neonatal-care OEMs, dermatology phototherapy specialists, and targeted excimer-system companies. Large medical-device groups such as GE HealthCare and Dräger compete in neonatal care alongside focused suppliers including Natus Sensory, Atom Medical, Phoenix Medical Systems, Fanem, Bistos, Ningbo David Medical Device, and Nice Neotech. Dermatology equipment is led by specialist manufacturers such as Daavlin, National Biological Corporation, Solarc Systems, STRATA Skin Sciences, Xuzhou Kernel Medical Equipment, and Shanghai SIGMA High-Tech.
Competitive differentiation is increasingly based on irradiance stability, treatment-area coverage, dose controls, digital treatment management, portability, home-use compatibility, and regulatory approvals. Herbert Waldmann has discontinued the production and sale of phototherapy equipment, while Signify participates mainly as a lighting-component supplier rather than a finished phototherapy-system manufacturer.
Recent Developments
February 2026: Natus Sensory announced the acquisition of TheraB Medical, adding the SnugLit wearable neonatal phototherapy platform to its newborn-care portfolio.
January 2026: The U.S. FDA granted 510(k) clearance to TheraB Medical's SnugLit wearable phototherapy system for infant hyperbilirubinemia in hospital or home settings.
February 2026: Johns Hopkins Dermatology added STRATA Skin Sciences' XTRAC 308 nm excimer laser for inflammatory and autoimmune skin conditions, including psoriasis and vitiligo.
April 2025: The U.S. FDA cleared APK Technology's ultraviolet phototherapy device under the dermatological UV device pathway.
March 2025: The U.S. FDA cleared Boston Aesthetics' 308 nm UV phototherapy systems for dermatological indications.
February 2025: The U.S. FDA cleared Xuzhou Kernel Medical Equipment's 308 nm excimer phototherapy device family.
December 2024: The U.S. FDA cleared Shanghai SIGMA High-Tech's home-use UV phototherapy device family for psoriasis, vitiligo, and atopic dermatitis.
Market Outlook
The phototherapy equipment market is expected to grow steadily rather than explosively through 2031. The strongest value creation is likely to come from replacement of legacy fluorescent neonatal equipment, expansion of intensive blue-LED capacity in emerging-market hospitals, targeted dermatology platforms, and prescribed home phototherapy. The boundary between institutional and home treatment will continue to blur as manufacturers add dosing controls, portable form factors, and physician-managed workflows. At the same time, the market will remain constrained by long equipment life, reimbursement variability, and competition from pharmaceutical dermatology treatments. Suppliers that combine strong regulatory documentation with clinically measurable irradiance, treatment monitoring, and simplified home-use designs are positioned to capture a disproportionate share of incremental demand.
Global Phototherapy Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 365.0 million |
| Total Market Size in 2031 | USD 500.0 million |
| Forecast Unit | Million |
| Growth Rate | 6.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Therapeutic Platform, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Therapeutic Platform
UVB/UVA Phototherapy Systems
Blue-Light Neonatal Phototherapy Systems
308 nm Excimer Laser and Lamp Systems
Fiber-Optic and Wearable Phototherapy Systems
By Application
Psoriasis
Vitiligo
Atopic Dermatitis and Eczema
Neonatal Jaundice Management
Other Photo-Responsive Conditions
By End User
Hospitals and Neonatal Care Centers
Dermatology Clinics and Physician Offices
Home Care
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1 Market Definition
1.2 Scope of the Study
1.3 Currency, Units, and Study Period
2. RESEARCH METHODOLOGY
2.1 Research Design
2.2 Secondary and Primary Research Framework
2.3 Market Estimation and Validation
3. EXECUTIVE SUMMARY
3.1 Market Snapshot
3.2 Key Trends and Strategic Findings
4. MARKET DYNAMICS
4.1 Market Drivers
4.1.1 Neonatal Jaundice Treatment Requirement
4.1.2 Chronic Dermatological Disease Burden
4.1.3 Expansion of Home Phototherapy
4.1.4 LED and Portable-System Innovation
4.2 Market Restraints
4.2.1 Safety and Dose-Control Requirements
4.2.2 Reimbursement and Capital-Cost Constraints
4.2.3 Competition from Systemic Dermatology Therapies
4.3 Market Opportunities
4.3.1 Wearable and Fiber-Optic Neonatal Systems
4.3.2 Digitally Controlled Home Phototherapy
4.3.3 Emerging-Market NICU Expansion
4.4 Regulatory Environment
5. PHOTOTHERAPY EQUIPMENT MARKET BY THERAPEUTIC PLATFORM
5.1 UVB/UVA Phototherapy Systems
5.2 Blue-Light Neonatal Phototherapy Systems
5.3 308 nm Excimer Laser and Lamp Systems
5.4 Fiber-Optic and Wearable Phototherapy Systems
6. PHOTOTHERAPY EQUIPMENT MARKET BY APPLICATION
6.1 Psoriasis
6.2 Vitiligo
6.3 Atopic Dermatitis and Eczema
6.4 Neonatal Jaundice Management
6.5 Other Photo-Responsive Conditions
7. PHOTOTHERAPY EQUIPMENT MARKET BY END USER
7.1 Hospitals and Neonatal Care Centers
7.2 Dermatology Clinics and Physician Offices
7.3 Home Care
8. PHOTOTHERAPY EQUIPMENT MARKET BY GEOGRAPHY
8.1 North America
8.1.1 United States
8.1.2 Canada
8.1.3 Mexico
8.2 South America
8.2.1 Brazil
8.2.2 Argentina
8.2.3 Others
8.3 Europe
8.3.1 Germany
8.3.2 France
8.3.3 United Kingdom
8.3.4 Italy
8.3.5 Spain
8.3.6 Others
8.4 Middle East and Africa
8.4.1 Saudi Arabia
8.4.2 United Arab Emirates
8.4.3 South Africa
8.4.4 Others
8.5 Asia Pacific
8.5.1 China
8.5.2 India
8.5.3 Japan
8.5.4 South Korea
8.5.5 Australia
8.5.6 Southeast Asia
8.5.7 Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1 Market Positioning and Product Portfolio Analysis
9.2 Technology and Regulatory Differentiation
9.3 Partnerships, Acquisitions, and Product Launches
9.4 Vendor Competitiveness Matrix
10. COMPANY PROFILES
10.1 Natus Sensory (Natus Medical Incorporated)
10.2 GE HealthCare
10.3 Drägerwerk AG & Co. KGaA
10.4 Atom Medical Corporation
10.5 Phoenix Medical Systems Pvt. Ltd.
10.6 Nice Neotech Medical Systems Pvt. Ltd.
10.7 Fanem Ltda.
10.8 Ningbo David Medical Device Co., Ltd.
10.9 Bistos Co., Ltd.
10.10 Daavlin Distributing Co.
10.11 National Biological Corporation
10.12 Solarc Systems Inc.
10.13 STRATA Skin Sciences, Inc.
10.14 Xuzhou Kernel Medical Equipment Co., Ltd.
10.15 Shanghai SIGMA High-Tech Co., Ltd.
10.16 Gerium Medical Ltd.
Navigate
Trusted by the world's leading organizations











