
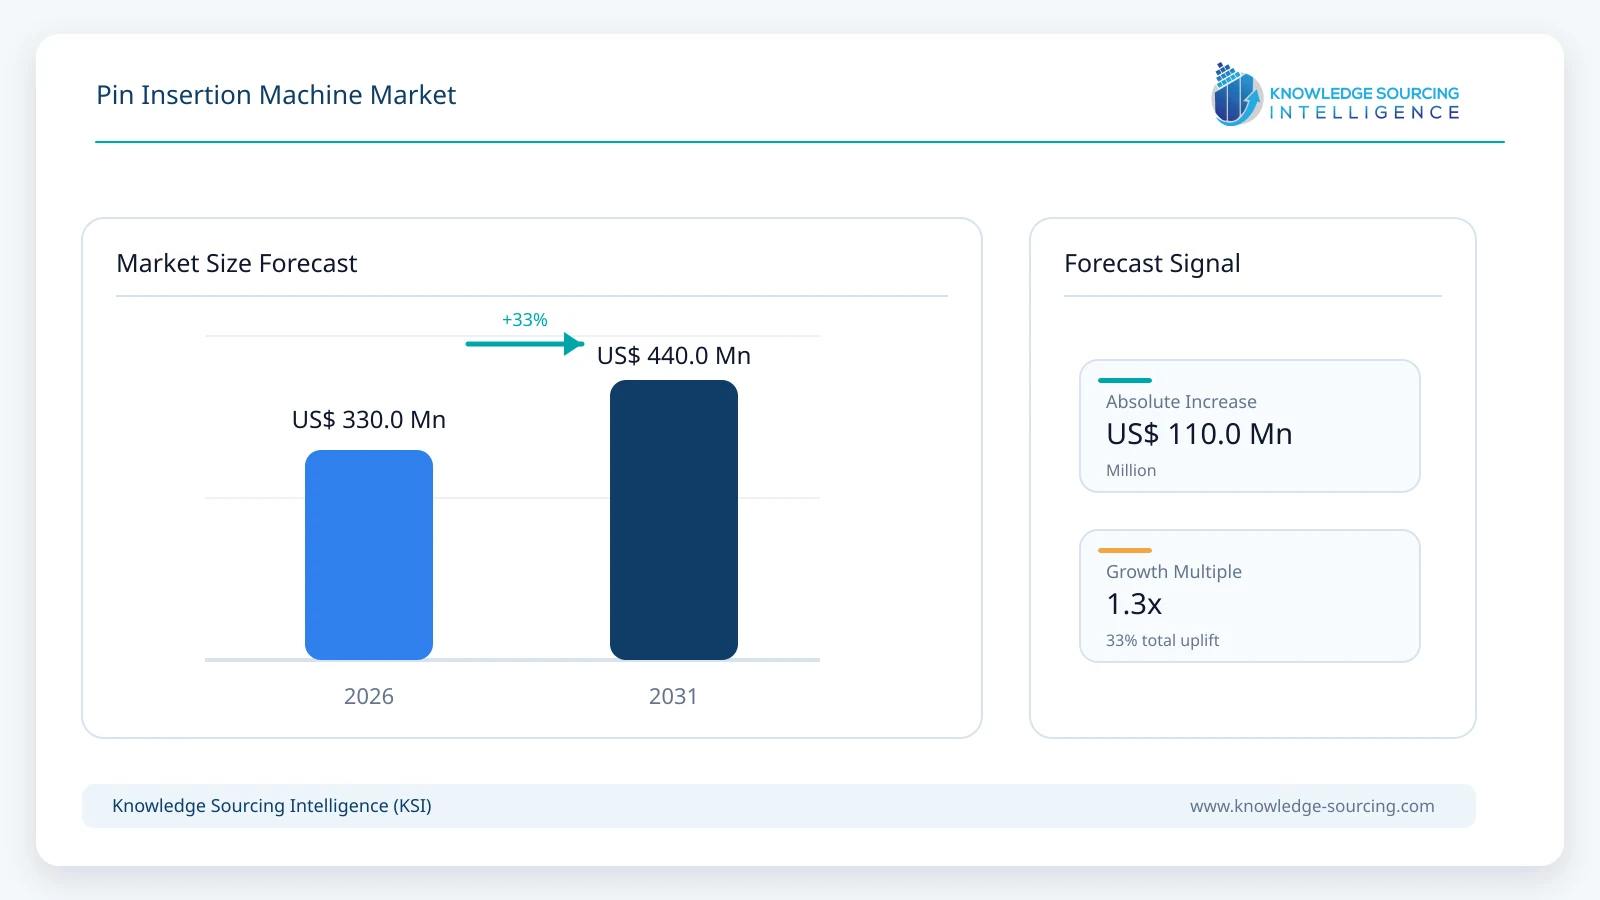
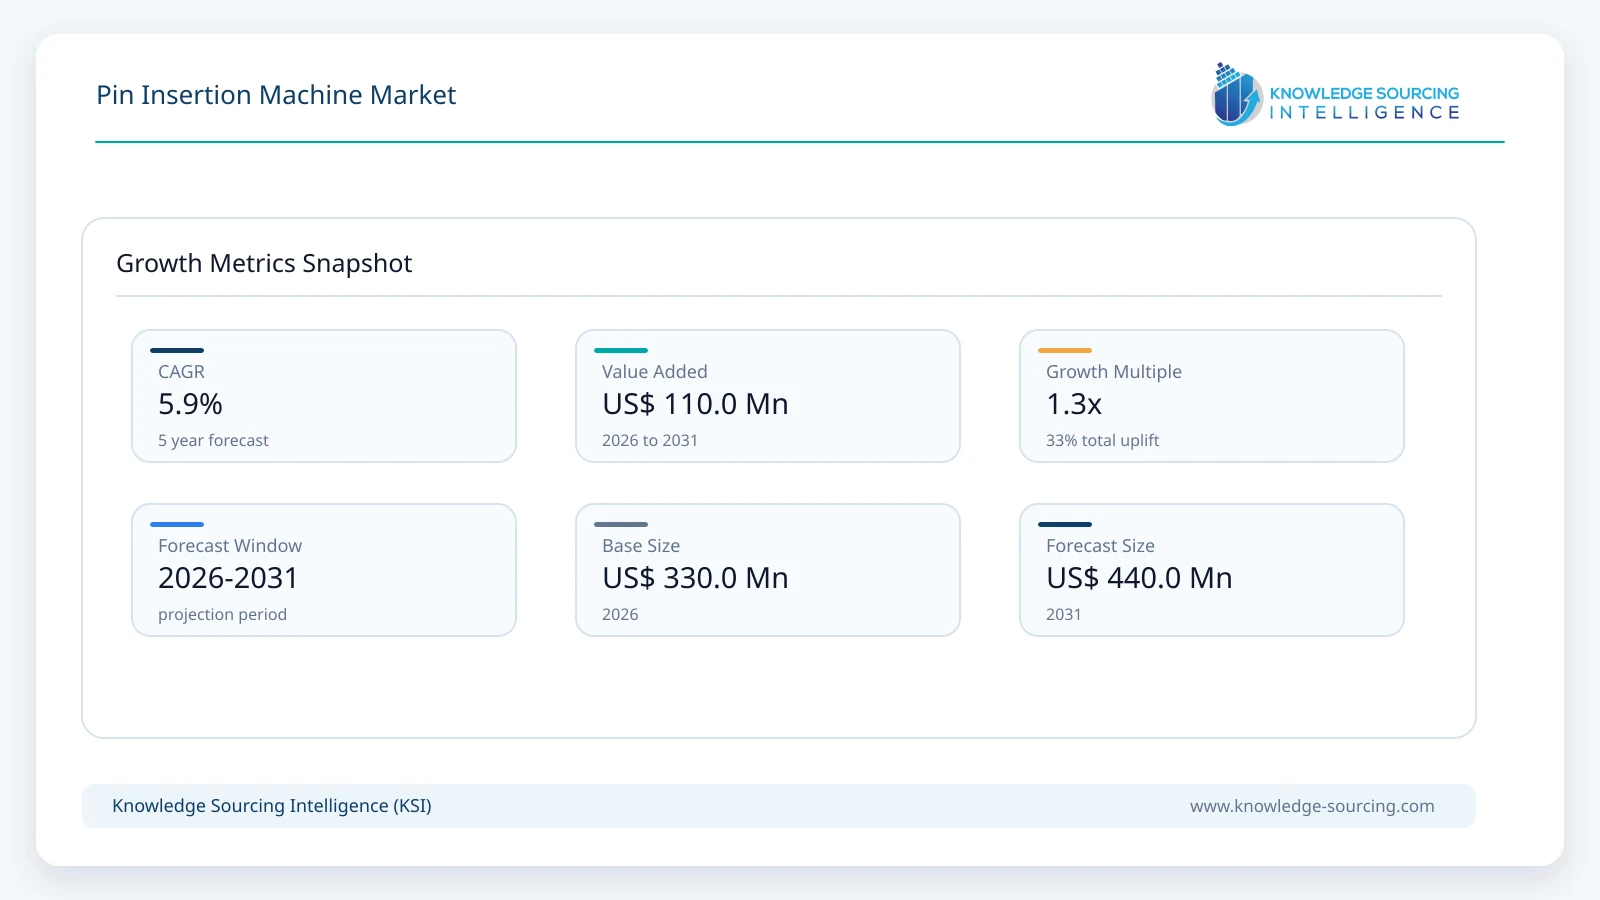
The pin insertion machine market is expected to grow at a CAGR of 5.9%, reaching a market size of USD 440.0 million in 2031 from USD 330.0 million in 2026.
Highlights:
- 1Press-fit applications account for approximately 61% of global pin insertion machine revenue in 2026.
- 2Fully automatic insertion platforms are projected to grow at approximately 7.2% annually through 2031.
- 3Automotive electronics generate about USD 118.0 million of global machine demand in 2026.
- 4Asia Pacific accounts for approximately 47% of global pin insertion machine revenue in 2026.
- 5Force-displacement monitoring and traceability are becoming standard requirements in high-reliability electronic assembly.
- 6Compact multi-head platforms and faster tooling changeovers are improving economics for high-mix production.
A pin insertion machine combines a component feeder, insertion head, workpiece positioning system, tooling or anvil support and a control platform. In electronic applications, reeled or bulk pins are cut or separated, oriented and inserted into plated through-holes, housings or module substrates under controlled force. Mechanical pin inserters use related feeding and pressing principles to install spring pins, dowels, rivets and other non-threaded fasteners. Dedicated PCB systems are differentiated by insertion rate, board envelope, number of insertion heads, tool-change time, positioning accuracy, force monitoring and compatibility with production-line interfaces such as SMEMA.
Press-fit technology is commercially important because the compliant zone of the terminal deforms during insertion and maintains contact pressure inside the plated through-hole. IEC 60352-5 and the IPC-9797/IPC-HDBK-9798 framework formalize requirements for high-reliability press-fit connections. TE Connectivity describes press-fit as a solderless approach used extensively in automotive electronic control units and provides corresponding single-pin insertion equipment. This links machine demand to the expansion of power electronics, vehicle controllers, industrial drives and other assemblies in which reliable interconnection and process traceability are more important than the lowest possible equipment price.
Market Trends
Force Monitoring, Vision Correction and Traceability Are Moving Into the Core Machine Specification
Insertion equipment is increasingly purchased as a quality-control platform rather than a simple mechanical press. TE Connectivity offers real-time force monitoring, vision-based PCB alignment and traceability on its higher-end platforms. Lazpiur combines insertion-force monitoring with pin-height measurement, material verification and camera inspection, while Eberhard uses panel-thickness measurement, force monitoring and vision inspection in high-speed PCB pin insertion. UMG Technologies similarly integrates vision pin inspection, reel scanning and production-data collection with MES connectivity. These functions reduce the risk of bent pins, incomplete insertion and board damage while creating a digital production record for automotive, power-electronics and other high-reliability customers.
Machine Architecture Is Becoming More Modular for High-Mix Production
Electronics manufacturers increasingly need one platform to process several terminal geometries and product variants. This favors quick-change tooling, multiple insertion heads and software-driven setup rather than dedicated single-product equipment. TE supports up to four insertion heads on several platforms and conversion-kit changes in less than ten minutes, while Autosplice offers transferable tooling across its bench-top, standalone and inline machines. Lazpiur supports multiple terminal types with quick-change product-specific kits, and FINECS offers separate FINESERT Pro and Lite architectures for different cost and customization requirements. Modularization lowers the economic threshold for automation in high-mix facilities and creates recurring revenue from tooling, conversion kits, calibration and service.
Market Drivers
Automotive Electrification and Power Electronics Increase the Need for Reliable Solderless Interconnections
Vehicle electrical and electronic architectures contain a growing number of control units, sensors, power modules and high-density interconnects. Nearly 22 million electric cars were produced globally in 2025, more than 25% above the previous year, according to the International Energy Agency. Press-fit connections are used in automotive control units because they avoid thermal stress and can provide durable mechanical and electrical contact under vibration and temperature cycling. TE Connectivity specifically positions compliant pin technologies for applications including engine management, ABS, airbag controllers and other vehicle systems, while Coreal markets high-precision pin insertion for IGBT and SiC power modules. The increase in EV and power-electronics production therefore expands the installed base of assembly lines that can justify force-monitored automated insertion.
Electronics Manufacturing Investment Supports New Lines and Higher Automation Content
Broader electronics investment supports demand beyond vehicles. SEMI forecast global semiconductor manufacturing equipment sales of USD 165.9 billion in 2026, up 23.2% year on year, with additional growth expected through 2028. Pin insertion machines are not semiconductor wafer-fabrication tools, but the same investment cycle expands downstream packaging, power-module, server, industrial-control and electronics assembly capacity. The effect is strongest where new factories adopt higher levels of automation from the outset. Asia Pacific benefits disproportionately because China, Taiwan and Korea remain the largest semiconductor-equipment destinations and also host large automotive, appliance, connector and electronics-manufacturing ecosystems.
Market Restraint
Application-Specific Tooling and Qualification Keep Switching Costs High and Limit Standardization
Pin insertion equipment is highly configurable, and the machine platform is only part of the purchased system. Tooling, feeders, anvils, fixtures, vision recipes and force windows are adapted to a particular pin geometry and workpiece. Automotive and other high-reliability users then qualify both the component and the insertion process, which makes supplier changes more disruptive than replacing a general-purpose assembly machine. High-end inline systems also compete for capital budgets with connector seating presses, odd-form placement equipment and selective-soldering solutions. These factors slow replacement cycles, particularly in lower-volume factories, even as they strengthen recurring service and tooling revenue for incumbent equipment suppliers.
Segment Analysis
By Technology - Press-Fit
Press-fit technology is projected to generate approximately USD 292.0 million in pin insertion machine revenue by 2031. The segment benefits from automotive electronic control units, power modules, industrial drives, servers and other assemblies where solderless connection can reduce thermal exposure and support reliable mechanical retention. TE Connectivity, Autosplice, Lazpiur, UMG Technologies and Fohrenbach all maintain equipment specifically designed around compliant or press-fit terminals. Through-hole solder-terminal insertion remains relevant where components are subsequently soldered, while broader odd-form insertion overlaps with multifunctional placement platforms rather than dedicated pin inserters.
By Automation Level - Fully Automatic
Fully automatic pin insertion systems are projected to approach USD 282.0 million in revenue by 2031. Their economics are strongest in high-volume electronics manufacturing because automatic feeding, board handling, multiple insertion heads and inline integration reduce direct labor while improving repeatability. TE platforms can process multiple contact types with automatic head changing, Autosplice offers inline AIS configurations, and UMG Technologies provides SMEMA-compatible high-volume inserters. Semi-automatic systems remain important for lower-volume manufacturing, prototypes and applications that require operator loading, while manual inserters retain a smaller niche in maintenance, laboratory and low-rate mechanical assembly.
By Industry - Automotive Electronics
Automotive electronics are projected to reach approximately USD 168.0 million of pin insertion machine revenue by 2031. The segment combines high production volumes with strict process validation, making force monitoring, vision correction, barcode traceability and automated error detection commercially valuable. Growth is supported by expanding electronic content in both combustion and electric vehicles, including domain controllers, power-conversion modules, battery-management systems and safety electronics. Industrial machinery and energy equipment form another important demand pool, while consumer electronics and appliances favor flexible platforms where rapid model changeover is critical.
By Geography - Asia Pacific
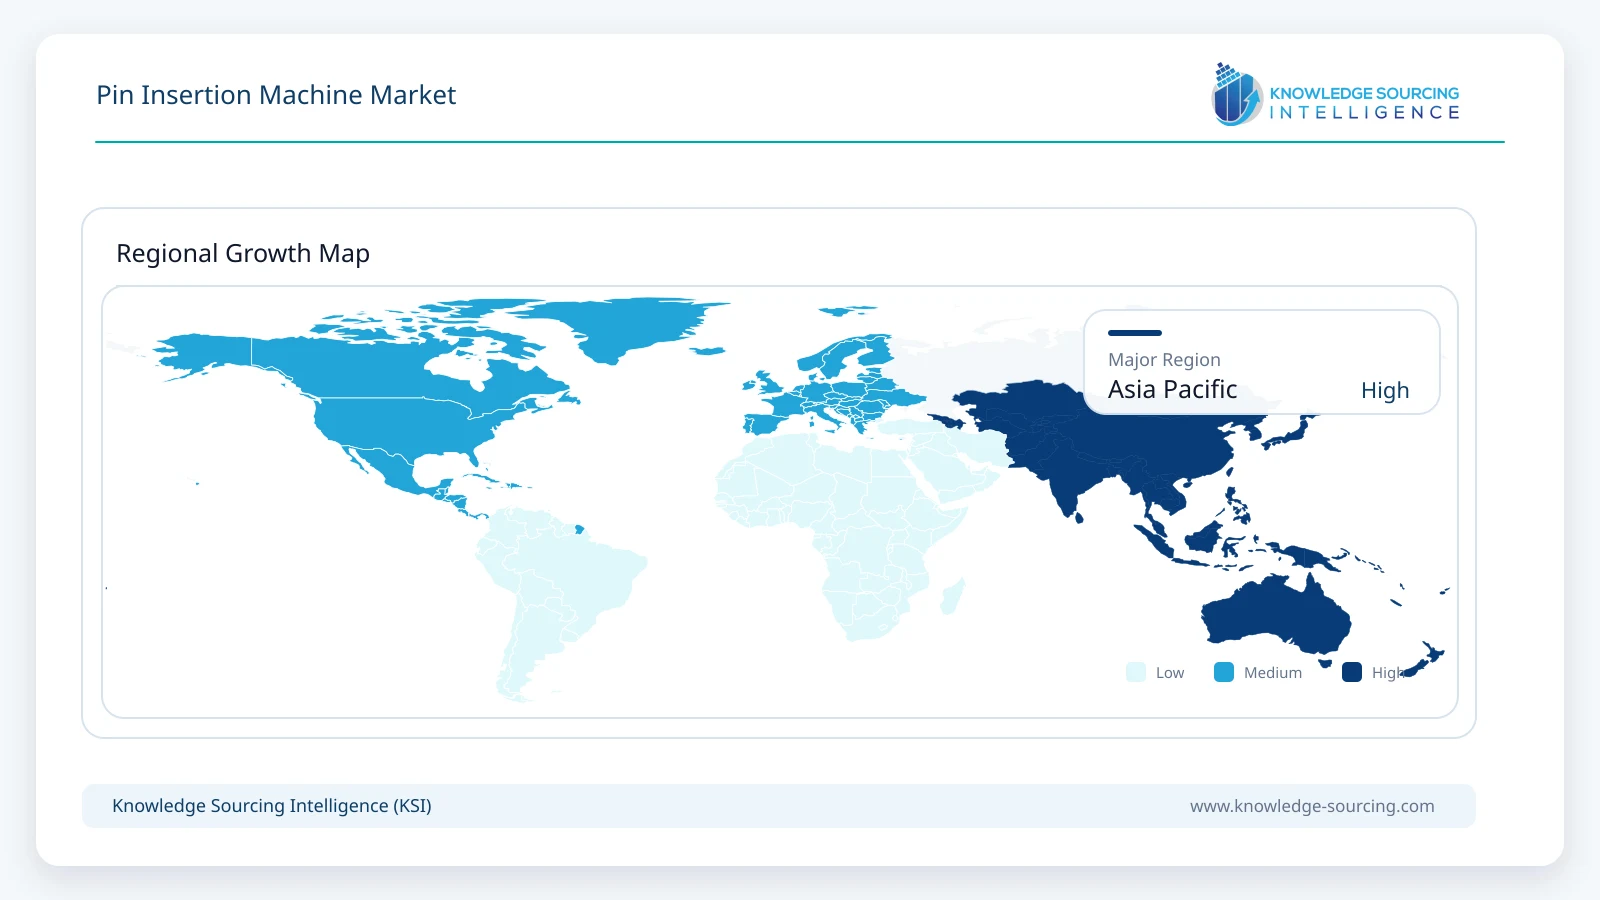
Asia Pacific is projected to reach approximately USD 220.0 million in pin insertion machine revenue by 2031. China combines the largest electric-vehicle manufacturing base with extensive electronics, appliance and connector production, while Japan remains important through precision electronics and suppliers such as FINECS. South Korea and Taiwan add semiconductor and server-related electronics demand, and Southeast Asia is attracting additional electronics assembly investment. The region also has a growing local equipment base through companies such as Shenzhen Zhizhan and Coreal Technology, increasing competition with established European, Japanese and North American suppliers.
Competitive Environment
The market combines connector companies with proprietary application tooling, specialist pin-insertion manufacturers and broader automation suppliers. TE Connectivity has one of the broadest dedicated portfolios, spanning P-series machines from lower-volume to high-speed multi-head configurations. Autosplice combines press-fit terminals with its own insertion systems, while Lazpiur, Eberhard, UMG Technologies and Fohrenbach compete in high-speed electronic insertion. SPIROL and Visumatic are stronger in mechanical fastener insertion, and FINECS links continuous-pin supply with proprietary FINESERT equipment. Chinese suppliers such as Shenzhen Zhizhan and Coreal Technology are expanding localized automation for automotive electronics, power modules and 3C applications.
Competition is increasingly based on total process capability. Customers compare insertion speed and accuracy together with tool-change time, line integration, force monitoring, data traceability, local service and the ability to process terminals from more than one supplier. Installed tooling creates switching costs, but modular machines can also weaken lock-in by allowing manufacturers to qualify additional pin types without replacing the base platform. Regional service capacity is therefore a material competitive factor because equipment downtime can interrupt an entire assembly cell and because new terminal geometries often require rapid tooling support.
Recent Developments
August 2026: Lazpiur published its 2026 machinery catalogue highlighting its current high-speed pin-insertion portfolio, including modular systems for press-fit PCB assembly with force monitoring and vision control.
July 2026: SEMI raised its global semiconductor manufacturing equipment outlook to USD 165.9 billion for 2026, strengthening the capacity-investment backdrop for downstream electronic assembly and packaging automation.
2026: Coreal Technology expanded its power-semiconductor automation offering around automatic pin insertion for IGBT and SiC modules using 3D vision and insertion-force control.
August 2025: TE Connectivity published its next-generation pin insertion machine catalogue covering P8, P4 and related platforms with faster changeover, traceability and multi-head processing options.
Pin Insertion Machine Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 330.0 million |
| Total Market Size in 2031 | USD 440.0 million |
| Forecast Unit | Million |
| Growth Rate | 5.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Automation Level, Industry, Geography |
| Companies |
|
Market Segmentation
By Technology
Press-Fit
Through-Hole / Solder-Terminal Insertion
Mechanical and Other Pin Insertion
By Automation Level
Manual
Semi-Automatic
Fully Automatic
By Industry
Automotive Electronics
Industrial Machinery and Automation
Consumer Electronics and Appliances
Energy and Power Electronics
IT and Telecommunications
Medical and Other Applications
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Automotive Electrification and Power Electronics Increase the Need for Reliable Solderless Interconnections
3.1.2. Electronics Manufacturing Investment Supports New Lines and Higher Automation Content
3.2. Market Restraint
3.2.1. Application-Specific Tooling and Qualification Keep Switching Costs High and Limit Standardization
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Force-versus-Distance Monitoring
4.2. Vision-Guided Pin Alignment
4.3. Multi-Head and Quick-Change Tooling
4.4. MES Connectivity and Digital Traceability
5. PIN INSERTION MACHINE MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Press-Fit
5.3. Through-Hole / Solder-Terminal Insertion
5.4. Mechanical and Other Pin Insertion
6. PIN INSERTION MACHINE MARKET BY AUTOMATION LEVEL
6.1. Introduction
6.2. Manual
6.3. Semi-Automatic
6.4. Fully Automatic
7. PIN INSERTION MACHINE MARKET BY INDUSTRY
7.1. Introduction
7.2. Automotive Electronics
7.3. Industrial Machinery and Automation
7.4. Consumer Electronics and Appliances
7.5. Energy and Power Electronics
7.6. IT and Telecommunications
7.7. Medical and Other Applications
8. PIN INSERTION MACHINE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Indonesia
8.6.7. Thailand
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Product Launches, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. TE Connectivity plc
10.2. Autosplice, Inc.
10.3. Eberhard AG Automations- und Montagetechnik
10.4. Lazpiur S.A.
10.5. SPIROL International Corporation
10.6. UMG Technologies, Inc.
10.7. FINECS Co., Ltd.
10.8. Föhrenbach Application Tooling N.V.
10.9. SYNEO
10.10. SM Contact
10.11. Visumatic Industrial Products
10.12. Zierick Manufacturing Corporation
10.13. Shenzhen Zhizhan Electronics Co., Ltd.
10.14. Coreal Technology Co., Ltd.
10.15. Universal Instruments Corporation
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











