
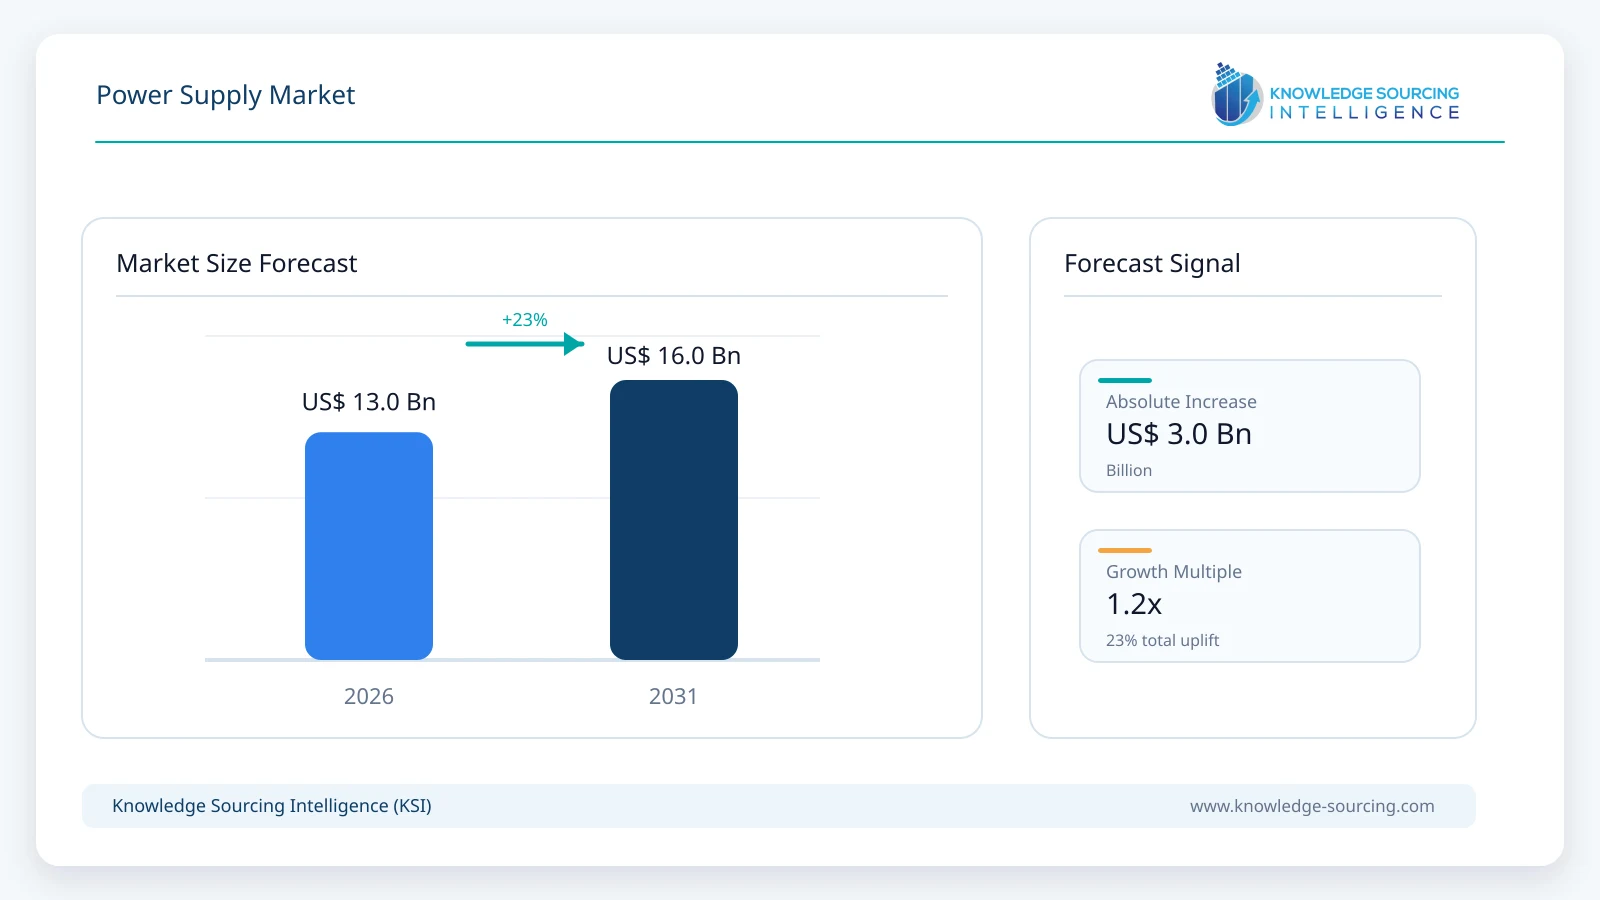
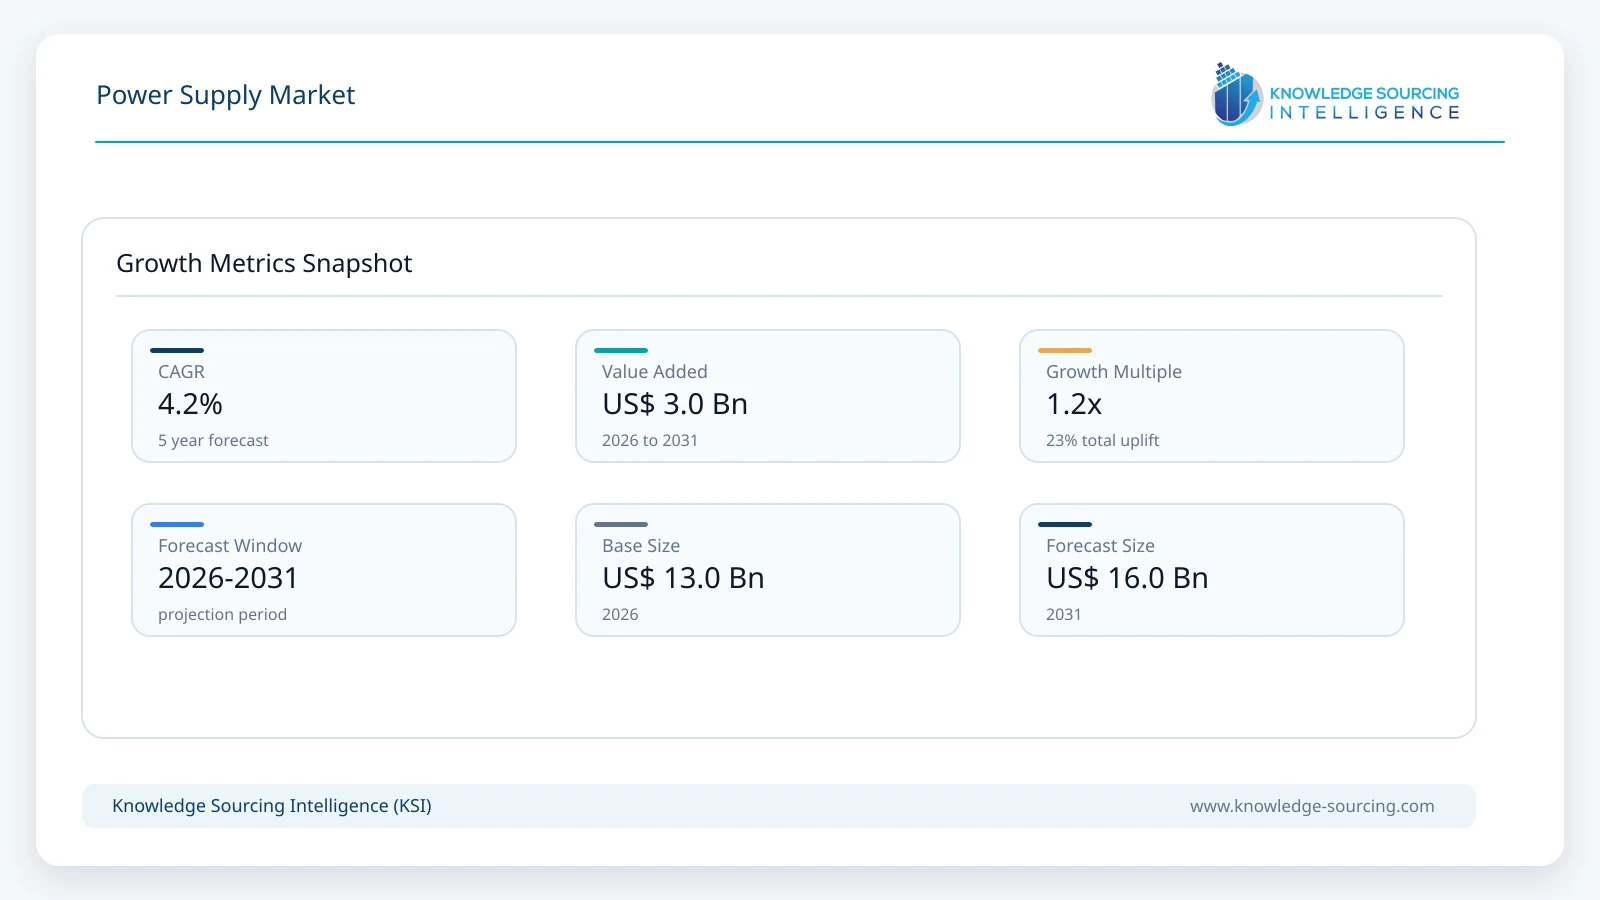
The power supply market is estimated at USD 13.04 billion in 2026 and is projected to reach USD 16.03 billion by 2031, growing at a CAGR of 4.2% during this period.
Highlights:
- 1Open-frame products account for approximately 56% of global power supply revenue in 2026.
- 2Single-output power supplies generate about USD 8.35 billion of market value in 2026.
- 3In 2026, DIN-rail power supplies represent approximately 31% of global revenue.
- 4Telecommunications accounts for about one-quarter of global power supply demand in 2026.
- 5Asia Pacific represents approximately 44% of global power supply revenues.
- 6Higher power density and digital monitoring are becoming core requirements in new industrial designs.
Power supplies convert available electrical input into the voltage, current and power quality required by an electronic load. AC-DC units convert mains input into regulated direct current. DC-DC converters change one DC voltage level into another and can provide isolation, regulation or both. The same electrical function can be delivered in different mechanical formats depending on the host system. Open-frame products are integrated inside equipment. Enclosed and panel-mounted units add mechanical protection. DIN-rail products are optimized for control cabinets, while PCB-mounted converters support compact embedded designs.
The market is highly application-specific. Medical equipment requires strict isolation, leakage-current and safety performance. Industrial automation prioritizes long service life, surge tolerance and operation across wide temperature ranges. Telecommunications and computing equipment emphasize power density, efficiency and redundancy. Aerospace and defense systems require ruggedized products and long qualification cycles. This diversity favors suppliers with broad certification capabilities and manufacturing platforms that can support standard, modified-standard and custom products.
Market Trends
Power density is increasing across both board-mounted and industrial power architectures
Manufacturers are raising output power without increasing enclosure size at the same rate. TDK-Lambda launched a 12.5 kW three-phase power supply in September 2026 for distributed power architectures and DC microgrids. Advanced Energy introduced a 600 W full-brick AC-DC supply in March 2026 with higher output in the same form factor as its earlier generation. XP Power has also expanded baseplate-cooled brick products for sealed and space-constrained equipment. The common objective is to increase usable system power while reducing cooling, cabling and enclosure requirements.
DIN-rail systems are adding intelligence, communication and higher peak-power capability
Industrial control cabinets increasingly require power supplies that can report operating condition and integrate with protection or monitoring systems. Phoenix Contact offers QUINT POWER units with IO-Link connectivity and preventive function monitoring. TDK-Lambda expanded its DIN-rail range in June and August 2026 with new output-voltage options and programmable isolated DC-DC converters. RECOM introduced several high-density DIN-rail AC-DC products during 2026, including 240 W and 480 W units. These products support automation systems that need compact installation and higher visibility into the DC power layer.
Distributed DC architectures are expanding beyond telecom into AI and high-density computing
AI computing is increasing interest in higher-voltage DC distribution and localized conversion near the load. Advanced Energy introduced 800 V DC-DC converters in June 2026 for next-generation AI data center architectures. TDK-Lambda's 385 V DC three-phase front end targets a similar distributed architecture in which high-voltage DC is converted closer to the final electronic load. The trend increases demand for efficient DC-DC conversion, hot-swappable front ends and digitally controlled power modules. It also broadens the use of power supplies that were previously concentrated in telecommunications and server equipment.
Market Drivers
Factory automation and distributed control systems expand DIN-rail and panel-mounted demand
Industrial automation is increasing the number of controllers, sensors, actuators, gateways and communication devices installed inside electrical cabinets. Each subsystem requires reliable low-voltage DC power. Modern factories also place more electronics closer to production equipment, which increases the need for compact supplies with high immunity to electrical noise, heat and vibration. DIN-rail products benefit directly because they can be installed and replaced quickly in standardized control panels. Growth in robotics, machine vision and automated inspection adds further load at the factory edge.
Medical and analytical equipment support demand for high-reliability certified power supplies
Medical equipment uses regulated DC power across displays, motors, sensors, computing subsystems and imaging electronics. Designers often select pre-certified supplies to reduce the certification burden for the complete device. Advanced Energy offers medical AC-DC platforms with IEC 60601-1 approvals across open-frame, enclosed and configurable formats. XP Power also targets healthcare equipment with medically approved AC-DC products and external adapters. Demand is supported by diagnostic imaging, patient monitoring, laboratory automation and home healthcare equipment.
Telecommunications and edge computing sustain demand for compact high-efficiency conversion
Telecommunications remains a major end market because network equipment requires continuous power conversion from site-level DC buses or AC input to multiple board-level voltages. 5G radios, transport equipment and edge computing increase power density while limiting available space. Manufacturers are responding with higher-efficiency AC-DC front ends and board-mounted DC-DC converters. The same architectures are increasingly used in networking and AI computing equipment, extending the demand base for high-density power modules.
Market Restraint
Price pressure and long qualification cycles limit rapid substitution between suppliers
Standard power supplies face persistent price competition because many applications can be served by products with similar electrical ratings. At the same time, switching suppliers is not always simple. Mechanical dimensions, safety approvals, electromagnetic compatibility, thermal performance and connector layouts can be built into the host equipment design. Medical, semiconductor and aerospace customers may require lengthy qualification before adopting an alternative source. Manufacturers must therefore balance low cost with long product availability, certification support and reliable supply.
Segment Analysis
By Frame Type - Open Frame
Open-frame power supplies form the largest frame-type segment because they are integrated directly into equipment enclosures and avoid the cost and volume of a separate case. The segment accounts for approximately 56% of market revenue in 2026, equivalent to about USD 7.30 billion. Medical devices, instrumentation, communications equipment and industrial electronics are major applications. Enclosed-frame products grow slightly faster in harsh or exposed installations where mechanical protection and self-contained cooling are more important.
By Output - Single Output
Single-output power supplies remain the largest output configuration because most systems use a primary regulated DC rail and perform further conversion closer to individual loads. The segment is estimated at approximately USD 8.35 billion in 2026 and is projected to reach in double-digits by 2031. Multiple-output and dual-output products remain important in medical, instrumentation and legacy industrial systems that require several isolated voltage rails from one supply.
By Type - DIN Rail Mount
DIN-rail power supplies are the largest mounting-type segment and account for approximately 31% of global revenue in 2026, or about USD 4.04 billion. Growth is supported by factory automation, process control, building systems and distributed energy applications. PCB-mounted power supplies remain important in compact electronics, while panel and wall-mounted products serve systems that require easier replacement or external power conversion.
By End User - Telecommunications
Telecommunications is the largest end-user segment and accounts for approximately 25% of market value in 2026. The segment is projected to reach approximately USD 4.00 billion by 2031 as network densification, edge computing and higher equipment power density support demand. Medical and healthcare power supplies grow faster than the overall market because certification, isolation and reliability requirements support higher-value designs.
By Geography - Asia Pacific
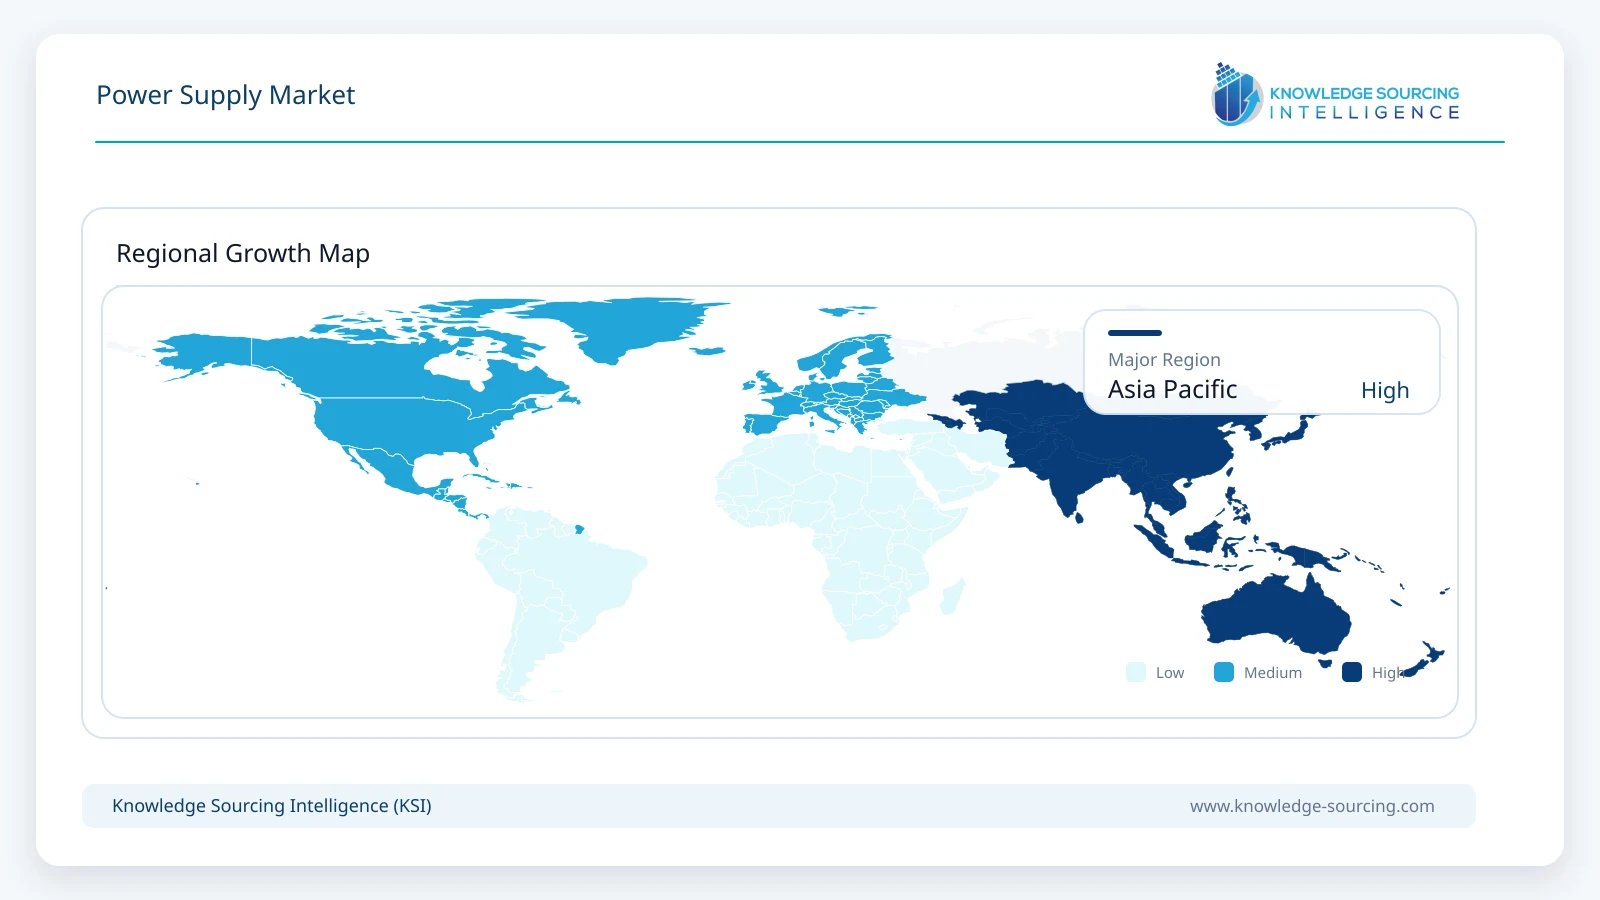
Asia Pacific is the largest regional market and represents approximately 44% of global revenue in 2026. The region combines a large electronics manufacturing base with strong demand from industrial automation, telecommunications and automotive electronics. China, Japan, Taiwan, South Korea and Southeast Asia are important manufacturing locations, while India is expanding its electronics and automation base.
Competitive Environment
TDK-Lambda, Delta Electronics, Advanced Energy and XP Power compete across broad AC-DC and DC-DC portfolios. TDK-Lambda has strong positions in industrial, medical and programmable power. Advanced Energy combines Artesyn, SL Power and Excelsys product families with higher-power precision platforms. XP Power focuses on medical, industrial, semiconductor and analytical equipment and reported GBP 230.1 million of revenue in 2025.
COSEL, MEAN WELL, PULS, Phoenix Contact and RECOM are important suppliers in industrial and embedded power. Phoenix Contact and PULS are especially visible in DIN-rail power for automation. RECOM has expanded its AC-DC portfolio and entered discrete power components during 2026. COSEL and MEAN WELL compete across standardized power supplies with broad distribution and long product lifecycles.
Bel Power Solutions, Vicor, Murata, OmniOn Power, TRACO Power, Siemens and Weidmüller add depth in board-level, telecom and industrial applications. Bel's Power Solutions and Protection segment benefited from stronger networking, data center and aerospace demand in 2025. Vicor focuses on high-density power modules, while OmniOn Power serves telecommunications, data center and industrial power architectures. Competition centers on efficiency, power density, certification, reliability and application engineering support.
Recent Developments
September 2026: TDK-Lambda launched a 12.5 kW three-phase power supply for distributed DC power architectures.
September 2026: RECOM introduced new 50 W and 100 W DC-DC converters for industrial, transportation and telecom applications.
August 2026: TDK-Lambda introduced programmable DIN-rail isolated DC-DC converters with 120 W and 240 W outputs.
July 2026: Advanced Energy launched an 1100 W half-brick power-factor-correction module for high-density power systems.
July 2026: TDK-Lambda expanded its HWS3000 programmable AC-DC series with a wide-range three-phase input model.
July 2026: RECOM added a 30 W ultra-slim DIN-rail AC-DC product for space-constrained distribution panels.
June 2026: Advanced Energy introduced 800 V DC-DC converters for next-generation AI data center power architectures.
June 2026: TDK-Lambda expanded its D1SE DIN-rail range with 12 V, 48 V and 72 V output models.
Power Supply Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.04 billion |
| Total Market Size in 2031 | USD 16.03 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Frame Type, Output, Type, End User, Geography |
| Companies |
|
Market Segmentation
By Frame Type
Open Frame
Enclosed Frame
By Output
Single Output
Multiple Output
Dual Output
By Type
DIN Rail Mount
Wall Mount
PCB Mount
Panel Mount
By End User
Telecommunications
Consumer Electronics
Medical and Healthcare
Aerospace and Defense
Automotive
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Factory Automation and Distributed Control Systems Expand DIN-Rail and Panel-Mounted Demand
3.1.2. Medical and Analytical Equipment Support Demand for High-Reliability Certified Power Supplies
3.1.3. Telecommunications and Edge Computing Sustain Demand for Compact High-Efficiency Conversion
3.2. Market Restraint
3.2.1. Price Pressure and Long Qualification Cycles Limit Rapid Substitution Between Suppliers
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Gallium Nitride and Silicon Carbide Power Conversion
4.2. High-Density AC-DC Front Ends
4.3. Digital Control and Power Monitoring
4.4. Distributed High-Voltage DC Architectures
4.5. Thermal Management and Fanless Design
5. POWER SUPPLY MARKET BY FRAME TYPE
5.1. Introduction
5.2. Open Frame
5.3. Enclosed Frame
6. POWER SUPPLY MARKET BY OUTPUT
6.1. Introduction
6.2. Single Output
6.3. Multiple Output
6.4. Dual Output
7. POWER SUPPLY MARKET BY TYPE
7.1. Introduction
7.2. DIN Rail Mount
7.3. Wall Mount
7.4. PCB Mount
7.5. Panel Mount
8. POWER SUPPLY MARKET BY END USER
8.1. Introduction
8.2. Telecommunications
8.3. Consumer Electronics
8.4. Medical and Healthcare
8.5. Aerospace and Defense
8.6. Automotive
8.7. Others
9. POWER SUPPLY MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. United Kingdom
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Taiwan
9.6.6. Thailand
9.6.7. Indonesia
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Product and Technology Positioning
10.4. Mergers, Acquisitions, Agreements and Collaborations
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. TDK-Lambda Corporation
11.2. Delta Electronics, Inc.
11.3. Advanced Energy Industries, Inc.
11.4. XP Power Limited
11.5. COSEL Co., Ltd.
11.6. MEAN WELL Enterprises Co., Ltd.
11.7. PULS GmbH
11.8. Phoenix Contact GmbH & Co. KG
11.9. RECOM Power GmbH
11.10. TRACO Electronic AG
11.11. Bel Fuse Inc. / Bel Power Solutions
11.12. Vicor Corporation
11.13. Murata Manufacturing Co., Ltd.
11.14. OmniOn Power Inc. (AcBel Group)
11.15. Siemens AG
11.16. Weidmüller Interface GmbH & Co. KG
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











