
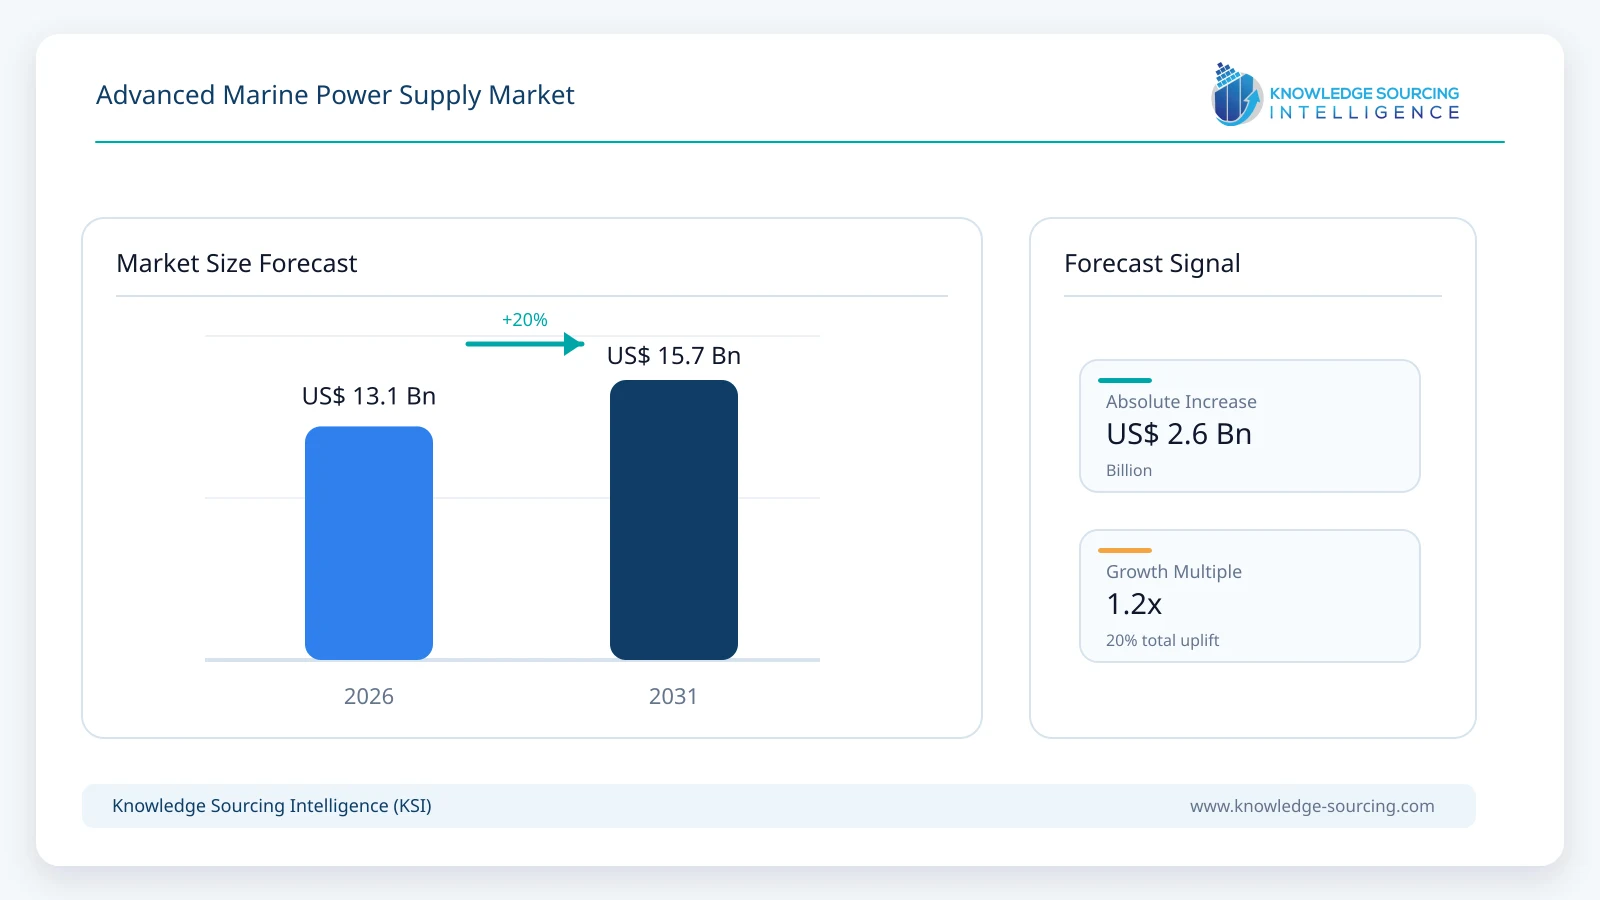
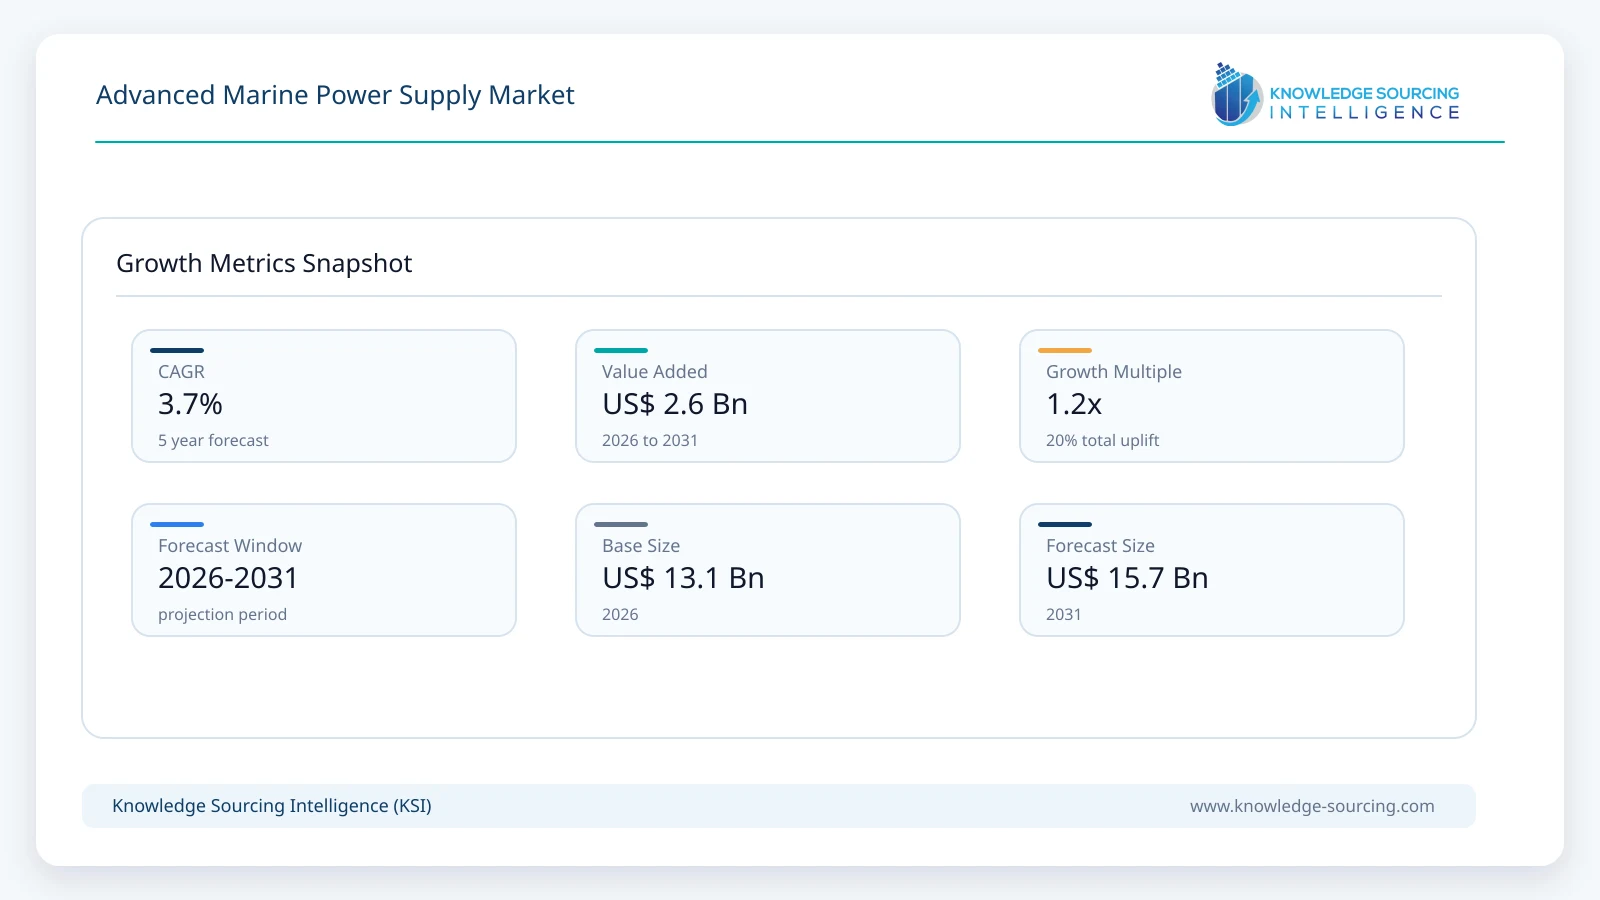
The Advanced Marine Power Supply Market is projected to grow at a CAGR of 3.7%, reaching USD 15.7 billion in 2031 from USD 13.1 billion in 2026 throughout the forecast period.
Highlights:
- 1Power conversion equipment remains the largest product group as electric drives, DC distribution, battery interfaces and shore connections require coordinated power electronics.
- 2Merchant vessels provide the largest application base, supported by cargo, passenger and hybrid offshore fleet electrical packages.
- 3Marine energy storage is gaining share in ferry, tug and hybrid-vessel programs where predictable operating cycles support useful battery deployment.
- 4Generator-based direct supply continues to dominate shipboard architectures, even as renewable-linked and battery-assisted systems gain relevance.
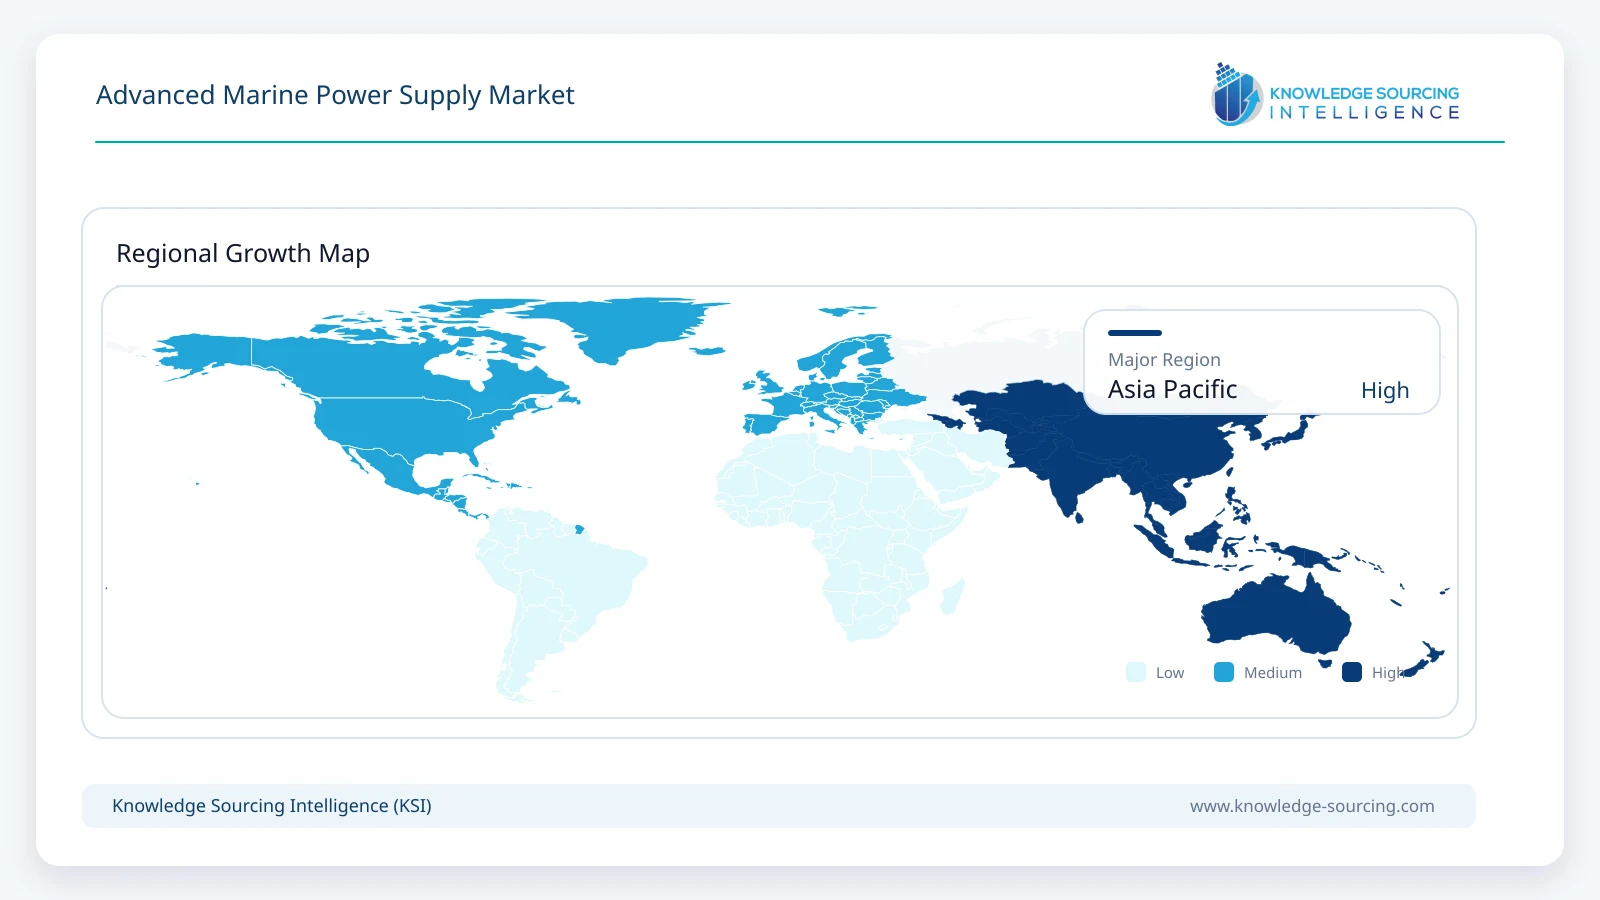
- 5Asia Pacific leads equipment procurement through its concentrated shipbuilding and marine electrical supply chains in China, South Korea and Japan.
- 6European shore-power investment is advancing under port infrastructure targets and future vessel-side connection requirements for covered ships and ports.
Advanced marine power supply systems deliver and regulate electricity for ship propulsion, navigation, communication, auxiliaries and shore-connected operation. Shipowners purchase converters, battery systems, switchboards, protection equipment and energy controls either as engineered packages or as components within broader electrical plants. The choice of architecture depends on vessel load cycles, redundancy requirements and whether electrical power comes from onboard generators, storage, shore supply or a combination of sources.
Commercial demand is anchored in shipbuilding and refurbishment rather than a uniform electrification cycle across all vessel classes. ABB supplies DC-based distribution and shore-power equipment, Wärtsilä integrates hybrid machinery and energy management, and Corvus Energy specializes in marine batteries. Owners evaluate these systems against fuel consumption, uptime, crew familiarity and the cost of installation and classification, with particularly strong interest where operating profiles involve frequent starts, stops or port stays.
Marine electrical plants are increasingly designed around several operating modes rather than one continuously running set of generators. A workboat may rely on batteries for short load peaks, a ferry may recharge during its turnaround, and an oceangoing vessel may use a variable-speed shaft generator to reduce auxiliary-engine running. The technical challenge is to coordinate power sources while keeping protection, stability and redundancy acceptable to owners and class societies.
ABB’s Onboard DC Grid allows generators and storage to connect through a common DC distribution system. Wärtsilä has supplied hybrid architectures combining DC hubs, battery capacity and integrated power management, including repeat installations for Aasen Shipping. Kongsberg Maritime offers propulsion and energy-management packages, while Corvus Energy supplies battery systems configured for specific marine duty cycles. These vendors participate at different levels of system integration and seldom compete on identical contractual scope.
Industrial power-electronics modules, marine cables, circuit protection, thermal management and automation platforms support the finished systems. High-power charging creates an additional interface with the port electrical network, where frequency conversion, substation capacity and connection geometry can govern economics as much as vessel hardware. For system suppliers, engineering responsibility and long-term service access are therefore important alongside the initial equipment price.
Market Trends
DC Distribution Is Expanding the Role of Power Electronics
Vessel power systems increasingly use DC links to join generators, batteries and variable-speed drives without forcing every source to operate through a conventional fixed-frequency AC arrangement. The benefit is operating flexibility: generators can run closer to efficient load points, while storage supplies rapid variations associated with maneuvering and dynamic positioning. Marine-rated converters and fault-protection systems consequently represent a larger part of electrical design work.
ABB’s May 2026 contract with Navantia for two Spanish Navy hydrographic vessels includes Onboard DC Grid, variable-speed generation and storage integration. The order demonstrates demand for DC architectures beyond passenger ferries, where early battery applications were concentrated. Such installations also create switching costs because software settings, fault studies and propulsion interfaces must be tested together.
Hybridization Is Spreading Into Cargo and Offshore Vessel Programs
Hybrid power plants are moving into applications where full battery-electric voyages remain impractical. Bulk carriers and offshore service vessels still require high energy density for long missions, but batteries can absorb transients, support hotel loads and reduce generator cycling. Operators are most receptive when these functions can be specified at newbuild stage rather than introduced through difficult retrofits.
Wärtsilä’s November 2025 repeat order for an Aasen Shipping bulk carrier used a 620 kWh battery, DC hub and energy controls; the equipment was planned for shipyard delivery in 2027. Rolls-Royce’s July 2026 announcement confirmed delivery of mtu engines for Starnav offshore vessels whose electrical plants combine generator sets with battery-supported propulsion. These programs show a gradual shift toward combined thermal and electrical systems, not the disappearance of onboard combustion generation.
Shore Power Is Turning Ports Into Electrical System Buyers
Port electrification extends the marine power-supply sale from vessels to terminal substations, frequency conversion and berth connections. Technical complexity increases where ships with different voltages, grid frequencies and hotel loads use shared infrastructure. Port authorities must coordinate electrical capacity with terminal availability and operating schedules, making project engineering a decisive part of supplier selection.
ABB secured a Rotterdam contract in January 2026 for installations totaling more than 100 MVA at three container terminals. Its September 2026 Portsmouth commissioning demonstrated commercial use of high-voltage shore supply by ferries and a cruise ship. Under European rules, covered ports face supply targets by the end of 2029, with qualifying passenger and container vessels facing at-berth connection obligations from 2030.
Energy Controls Are Being Sold as an Operating Capability
Marine power-management controls determine how reliably vessel batteries, variable-speed generators and propulsion loads operate as one electrical plant. Battery capacity provides limited operational benefit unless software can coordinate charging windows, generator dispatch, reserve margins and load priorities. For owners, verified fuel performance and predictable emergency behavior are more persuasive than headline battery capacity alone.
Kongsberg Maritime’s conversion work on the ferry MF Hamlet includes upgrades to K-Chief automation and energy management, while ABB markets PEMS alongside its DC equipment for electric tugs. Suppliers able to tune controls during commissioning and maintain them through the vessel’s operating life are gaining an advantage over vendors selling isolated conversion components.
Advanced Marine Power Supply Market Segment Analysis
By Product Type
Power Conversion Equipment
Power conversion equipment accounts for the largest share of advanced marine electrical expenditure because every complex shipboard plant requires controlled conversion between sources, buses and motor drives. Converters also support shaft generators, variable-frequency motors and shore-power connections. Power density, cooling and protection reliability have direct consequences for engine-room space and class approval.
This product group is estimated to represent approximately 51% of market value in 2026. ABB and Siemens supply high-power electrical equipment, while Semikron Danfoss participates upstream through power-semiconductor technology. Buyers typically select equipment through the shipbuilder or systems integrator, which makes demonstrated compatibility and commissioning responsibility more important than a stand-alone component price.
Conversion revenue is expected to grow steadily even as its overall share eases toward 2031. Higher battery use increases demand for converters, but it also raises the relative value of dedicated storage. New vessel architectures may reduce some conventional distribution hardware while adding more sophisticated power electronics and controls.
By Power Supply
Direct Power Supply
Direct power supply remains the largest category because most commercial and naval vessels continue to generate their electricity onboard, principally through engine-driven generators and integrated distribution systems. Deep-sea merchant ships need reliable power at sea and cannot depend on routine high-capacity shore charging during voyages. This supports a large installed base of conventional generation with increasingly advanced conversion and energy controls.
The direct-power category is estimated to represent around 82% of global expenditure in 2026. Rolls-Royce mtu marine generator sets, Caterpillar marine power offerings and systems engineered by ABB or Wärtsilä serve different parts of this demand. Even vessels that integrate batteries typically retain a generator-based primary supply, while storage enables peak shaving, short low-emission operation or improved load management.
Renewable-linked and hybrid packages are gaining relative share from a smaller base, especially where shore power, battery cycling and route predictability strengthen the business case. The distinction is commercial rather than a claim that batteries always receive renewable electricity; purchasing decisions remain tied to specified electrical architecture and contracting scope.
By Application
Merchant Vessels
Merchant vessels generate the largest application revenue pool because the segment combines cargo fleets, passenger shipping and their auxiliary electrical systems. Shipowners procuring new vessels increasingly assess electrical flexibility alongside main-engine efficiency, especially when longer operating lives expose them to changing port rules and fuel choices. Cargo-ship adoption is nevertheless measured, as large ocean-going ships require dependable power over long passages.
Merchant applications are estimated at 48% of market revenue in 2026. Wärtsilä’s bulk-carrier hybrids show that power management can improve conventional vessel operations, while ferry programs reveal where short routes permit higher battery utilization. Vessel owners generally prefer complete engineered packages with clear performance responsibility and service networks covering international routes.
Merchant demand is expected to remain the principal volume market, although naval projects and shore-power infrastructure can carry higher electrical content per installation. Suppliers able to bridge onboard equipment and port interfaces are positioned to compete for wider project scopes as maritime decarbonization requirements mature.
Market Drivers
Emissions Compliance Is Raising the Value of Electrical Flexibility
FuelEU Maritime requires reductions in the greenhouse-gas intensity of energy used by covered ships and adds at-berth electricity requirements for qualifying vessels at specified ports. Operators can respond through several fuel and power arrangements, but power management and shore interfaces provide practical options alongside fuel substitution. The exact technical response depends on trading pattern and installed machinery.
Equipment orders benefit when owners design new vessels with space, controls and electrical connections that can support later operating changes. The IMO’s proposed Net-Zero Framework remained under negotiation after the October 2025 adjournment, so procurement arguments should rely on rules already in force rather than treating future global measures as adopted law.
Short-Route Vessels Create Repeatable Battery-Electric Economics
Ferries and harbour craft operate predictable routes with frequent quay access, allowing engineers to match battery sizing to voyage energy and available charging time. Such duty cycles avoid the impractical battery capacities that would be required for many long-distance ships. Energy efficiency and local air-quality benefits can offset capital costs when utilization is high.
ABB’s June 2026 order for two electric tugs at Cochin Shipyard uses its DC and energy management equipment to support variable tug loads. Route-specific system packages also generate follow-on opportunities for charging controls, maintenance and replacement components once operators commit to electrified fleets.
Shipbuilders Are Specifying Integrated Electrical Packages
Electrical architectures now link propulsion converters, energy storage, generators, automation and safety controls across several suppliers. Specifying these functions separately can create interface disputes during commissioning, especially where system behavior must be validated under fault conditions. Shipyards and owners consequently value a responsible integrator with marine references.
ABB’s naval DC-grid orders and Kongsberg’s ferry-conversion programs illustrate the importance of combined engineering and control scope. Suppliers able to package proven hardware with simulation, installation support and lifecycle service can capture more value without relying on an exceptional rise in vessel numbers.
Naval and Government Programs Sustain Specialized Power Demand
Naval vessels increasingly carry surveillance sensors, communication systems and operational equipment that impose demanding electrical-quality and availability requirements. Hydrographic, patrol and auxiliary vessels also require quiet operations, redundant power and sophisticated load management. Qualification requirements make these projects different from standard commercial generation packages.
ABB’s Spanish Navy hydrographic vessel contract includes DC distribution with variable-speed generators and energy-storage interfaces. Government-funded ship programs provide relatively durable project pipelines, but revenue emerges over design, construction and commissioning milestones rather than immediately on contract announcement.
Port Electrification Creates New Infrastructure Contracts
High-voltage shore power requires port owners to procure switchgear, transformers, frequency conversion, cable handling and control systems suited to vessel loads. European AFIR targets for covered TEN-T ports by the end of 2029 create a defined infrastructure-planning horizon. The port must also secure sufficient grid capacity and manage simultaneous berths.
Rotterdam’s ABB shore-power program illustrates the scale of multi-terminal engineering contracts, while Portsmouth shows that commissioned facilities are entering regular ship operations. Such projects broaden demand beyond onboard equipment and favor suppliers experienced in both industrial distribution and maritime connection standards.
Market Restraints
Retrofit Space and Integration Risks Limit Vessel Conversions
Existing vessels often lack suitable spaces for batteries, converter rooms and additional ventilation, while their electrical protection systems were not designed around bidirectional energy flows. Retrofitting can require dry-dock time, new cable routes, structural changes and recertification. These costs can overwhelm projected fuel savings for older vessels.
Conversion projects therefore concentrate on ships with sufficient remaining life or unusually favorable duty cycles. Kongsberg’s MF Hamlet project illustrates the depth of propulsion, switchboard and controls work involved even when the objective is technically well defined.
Marine Battery Safety Requires Extensive Qualification
Marine batteries need thermal management, compartment protection, monitoring and documented behavior under electrical or mechanical faults. Failure containment is especially important in enclosed shipboard environments where crew evacuation and firefighting options are constrained. Classification and flag-state approval add time to product substitution and plant redesign.
DNV maintains battery-power and safety classification requirements, while IMO technical discussions in 2026 continued work on battery-system safety guidelines. Suppliers cannot treat industrial storage modules as ship-ready equipment without marine-specific engineering and verification.
Shore Charging Is Constrained by Grid Access and Port Economics
A suitable berth is not automatically a charging berth. High-power marine connections can require substation reinforcement, land allocation, frequency conversion and cables compatible with different ship sizes. Port authorities must also establish tariffs and allocate investment costs between terminals, shipowners and electricity suppliers.
Large projects may be viable at high-volume ferry or container terminals but difficult to justify at irregularly used berths. Uneven port adoption limits the usefulness of vessel-side shore power for operators trading across multiple regions, particularly before network coverage becomes more consistent.
Complex Electronics Increase Maintenance and Cybersecurity Demands
Integrated systems replace some mechanical operating tasks with dependence on converters, software and communication links. A converter failure, incorrect load-sharing parameter or compromised monitoring interface can affect several propulsion and auxiliary functions simultaneously. Crews need training that reflects the complete electrical plant rather than individual components.
Owners must budget for diagnostic access, software support, spare parts and periodic commissioning checks. Integrators with international service capacity are better placed to address these obligations, but long-term support costs remain part of the purchasing decision.
Cost-Sensitive Shipowners Prioritize Proven Payback
Battery systems, DC switchboards and high-power converters can carry higher acquisition and engineering costs than established electrical packages. Owners facing volatile freight revenue may defer retrofits or specify limited hybrid capability rather than full electrification. The economics vary substantially with annual operating hours, fuel prices and available shore electricity.
UNCTAD described weak maritime trade growth and continued route uncertainty in its 2025 review. These conditions make procurement discipline important: operators are likely to fund technologies that improve reliability or meet defined operating requirements before pursuing projects dependent on uncertain long-term savings.
Regional Outlook
Asia Pacific
Asia Pacific accounts for an estimated 36% of advanced marine power supply revenue in 2026 and remains the leading region through 2031. China, South Korea and Japan concentrate a large part of global commercial ship construction and the associated electrical-integration supply chain. Shipyard activity supports demand for converters, switchboards and generator controls, even where delivered vessels remain conventionally fueled.
India adds a different growth route through harbor craft and government-backed port electrification. ABB’s 2026 agreement with Cochin Shipyard for electric tugs demonstrates how regional policy initiatives can translate into equipment orders. Competitive advantage rests on qualification with shipyards, localized service and the ability to adapt platforms to differing vessel classes.
Europe
European demand is supported by ferry electrification, marine electrical engineering clusters and investment in shore-side electricity. Port authorities subject to AFIR requirements are planning equipment that can serve container and passenger ships, while operators assess vessel-side connection capability ahead of FuelEU Maritime obligations beginning in 2030 for covered circumstances.
ABB’s Rotterdam and Portsmouth projects provide a direct view of the market: one emphasizes construction of multi-terminal capacity, the other demonstrates connection of ships at an operating port. European suppliers also benefit from system design and retrofit expertise, although grid upgrades, berth utilization and permitting can determine when orders become revenue.
Competitive Landscape
Marine electrical equipment is supplied through a combination of integrated plant providers, specialized component manufacturers and shipboard storage companies. ABB competes through DC distribution, propulsion and shore-power engineering; Wärtsilä brings hybrid system integration and power management; Siemens and Schneider Electric contribute electrical and automation technology. Kongsberg Maritime addresses propulsion and vessel-control integration, while Caterpillar and Rolls-Royce mtu have strong generator-set and auxiliary power positions.
Corvus Energy and other marine-qualified storage suppliers compete where battery performance, safety approval and commissioning support influence the choice of system. Semikron Danfoss participates further upstream through power-electronic technology, whereas Victron Energy addresses smaller-vessel conversion and charging applications. These companies do not compete for the same invoice on every project; shipyards and integrators determine which elements are supplied directly and which are embedded in complete electrical plants.
Supplier differentiation increasingly turns on engineering interfaces and service availability rather than a single converter efficiency figure. Defense and large merchant projects require reference installations, rigorous documentation and worldwide support. In ports, contractors must combine marine connections with grid distribution and civil-program scheduling. Public disclosures do not establish a reliable global market-share ranking across such mixed revenue categories.
Recent Developments
September 2026: ABB reported that the high-voltage, multi-berth shore-power installation at Portsmouth International Port was operational, following connections by Brittany Ferries vessels and a cruise-ship call. The project demonstrates use beyond pilot status.
July 2026: Rolls-Royce reported delivery of mtu Series 4000 engines for Starnav hybrid offshore support vessels. The orders support continued use of conventional onboard generation within battery-assisted propulsion architectures.
June 2026: ABB announced a contract with Cochin Shipyard to equip two electric harbor tugs with DC distribution and power and energy management systems for delivery to the operator in 2027.
May 2026: ABB said Navantia had selected DC-based electrical distribution and propulsion systems for two Spanish Navy coastal hydrographic vessels scheduled for delivery by 2028.
January 2026: ABB was selected for a Port of Rotterdam shore-power program with planned aggregate capacity above 100 MVA across three container terminals, targeted for service beginning in 2028.
November 2025: Wärtsilä announced another hybrid propulsion order for Aasen Shipping bulk carriers, including a 620 kWh battery, DC hub and power management, with equipment deliveries planned for 2027.
Market Outlook
Advanced marine electrical systems are likely to expand through successive vessel-design decisions rather than a single technology shift. Batteries will remain most compelling in short-route and hybrid duty cycles, while merchant and naval fleets continue to rely on generator-based electrical capacity. The commercial opportunity for suppliers is to make different power sources operate within a reliable, class-approved plant.
Ports will become a more visible purchaser of high-power electrical systems as European infrastructure commitments move toward their 2029 and 2030 milestones. Regional spending patterns will remain uneven because shipyard pipelines, grid readiness and berth utilization differ widely. Suppliers with marine references, software integration capabilities and worldwide service support are better placed to convert equipment specifications into repeat contracts.
The industry should therefore be assessed through the quality of the installed electrical architecture, not only its energy source. Variable-speed generation, protected DC distribution and useful energy controls can create value on conventional and low-emission vessels alike. The main constraint is the cost and complexity of applying these technologies reliably across diverse ships and ports.
Advanced Marine Power Supply Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.1 billion |
| Total Market Size in 2031 | USD 15.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Power Supply, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
Energy Storage Systems
Power Conversion Equipment
Others
By Power Supply
Direct Power Supply
Renewable Power Supply
By Application
Defence & Navy Vessels
Merchant Vessels
Port & Harbor Infrastructure
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Advanced Marine Power Supply Market Size, 2026–2031
1.3. Product, Power Supply and Regional Direction
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Emissions Compliance Is Raising the Value of Electrical Flexibility
3.1.2. Short-Route Vessels Create Repeatable Battery-Electric Economics
3.1.3. Shipbuilders Are Specifying Integrated Electrical Packages
3.1.4. Naval and Government Programs Sustain Specialized Power Demand
3.1.5. Port Electrification Creates New Infrastructure Contracts
3.2. Market Restraints
3.2.1. Retrofit Space and Integration Risks Limit Vessel Conversions
3.2.2. Marine Battery Safety Requires Extensive Qualification
3.2.3. Shore Charging Is Constrained by Grid Access and Port Economics
3.2.4. Complex Electronics Increase Maintenance and Cybersecurity Demands
3.2.5. Cost-Sensitive Shipowners Prioritize Proven Payback
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Marine Power Conversion and DC Distribution
4.2. Energy Storage and Hybrid Power Plants
4.3. Power Management, Protection and Automation
4.4. Shore Power and High-Capacity Charging
4.5. Generator Integration and Alternative-Fuel Readiness
5. ADVANCED MARINE POWER SUPPLY MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Energy Storage Systems
5.3. Power Conversion Equipment
5.4. Others
6. ADVANCED MARINE POWER SUPPLY MARKET BY POWER SUPPLY
6.1. Introduction
6.2. Direct Power Supply
6.3. Renewable Power Supply
7. ADVANCED MARINE POWER SUPPLY MARKET BY APPLICATION
7.1. Introduction
7.2. Defence & Navy Vessels
7.3. Merchant Vessels
7.4. Port & Harbor Infrastructure
7.5. Others
8. ADVANCED MARINE POWER SUPPLY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Indonesia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. ABB Ltd.
10.2. Wärtsilä Corporation
10.3. Siemens AG
10.4. Caterpillar Inc.
10.5. Corvus Energy
10.6. Semikron Danfoss
10.7. Schneider Electric SE
10.8. Kongsberg Maritime AS
10.9. Rolls-Royce Power Systems AG
10.10. Victron Energy B.V.
10.11. Eaton Corporation plc
10.12. GE Vernova Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market value by 2031?
The Advanced Marine Power Supply Market will reach USD 15.7 billion by 2031.
What is the forecast CAGR for this market?
The Advanced Marine Power Supply Market is projected to grow at a 3.7% CAGR.
Which product group is the largest in this market?
Power conversion equipment remains the largest product group.
What is the largest application base for these systems?
Merchant vessels provide the largest application base.
Which region leads in marine power supply equipment procurement?
Asia Pacific leads equipment procurement in shipbuilding.
Who are key players in the Advanced Marine Power Supply Market?
ABB, Wärtsilä, and Corvus Energy are key suppliers.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Advanced Marine Power Supply Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/advanced-marine-power-supply-market