
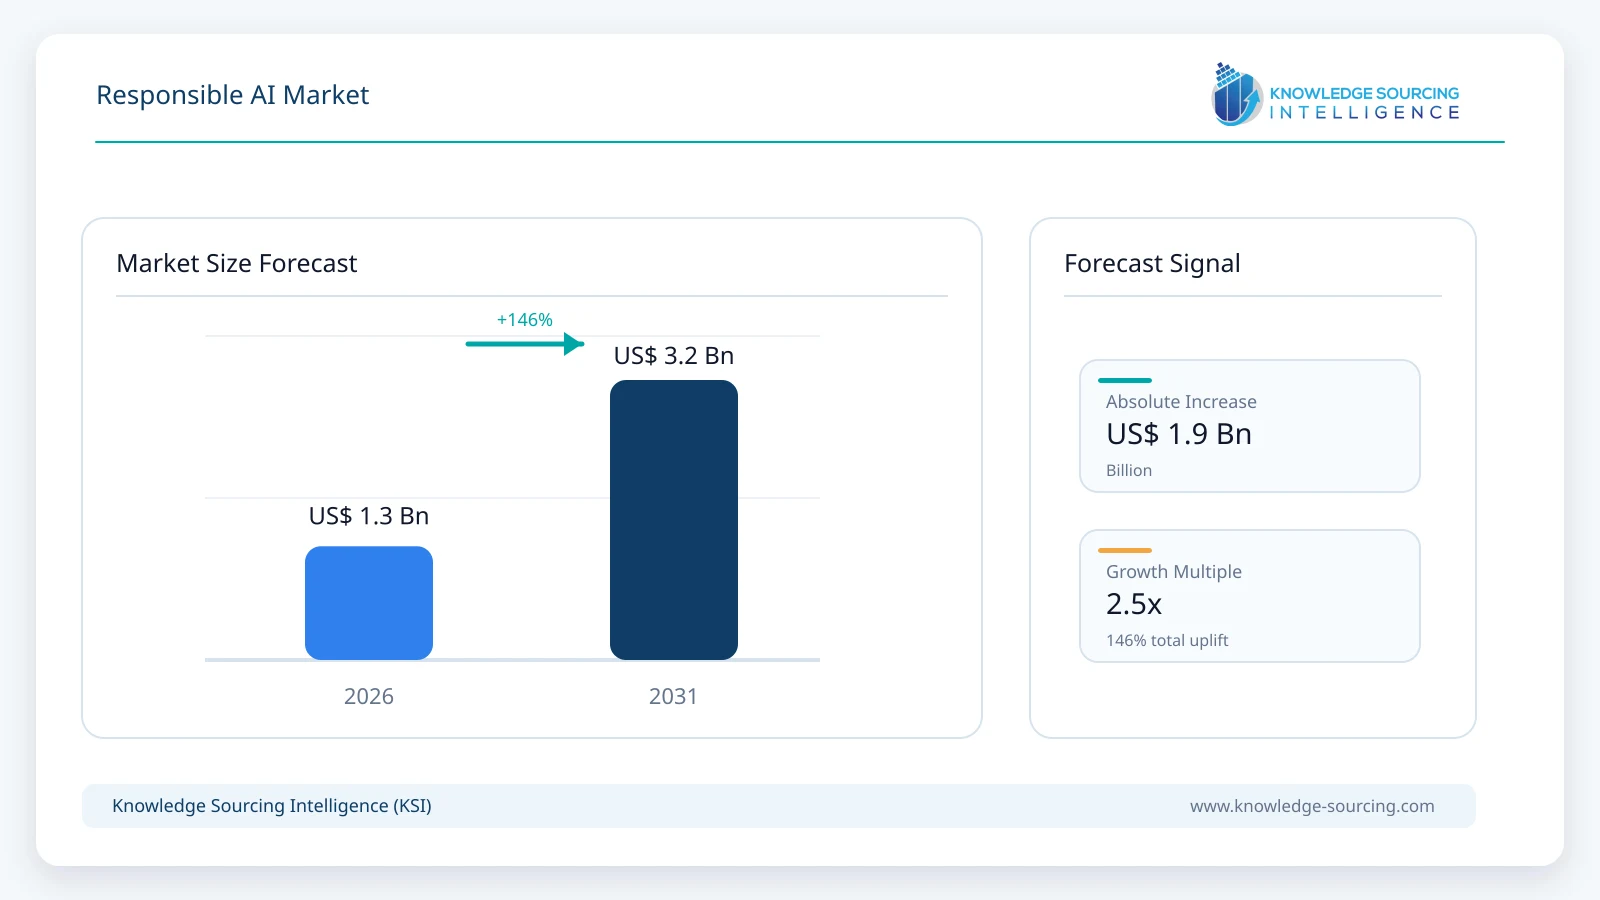
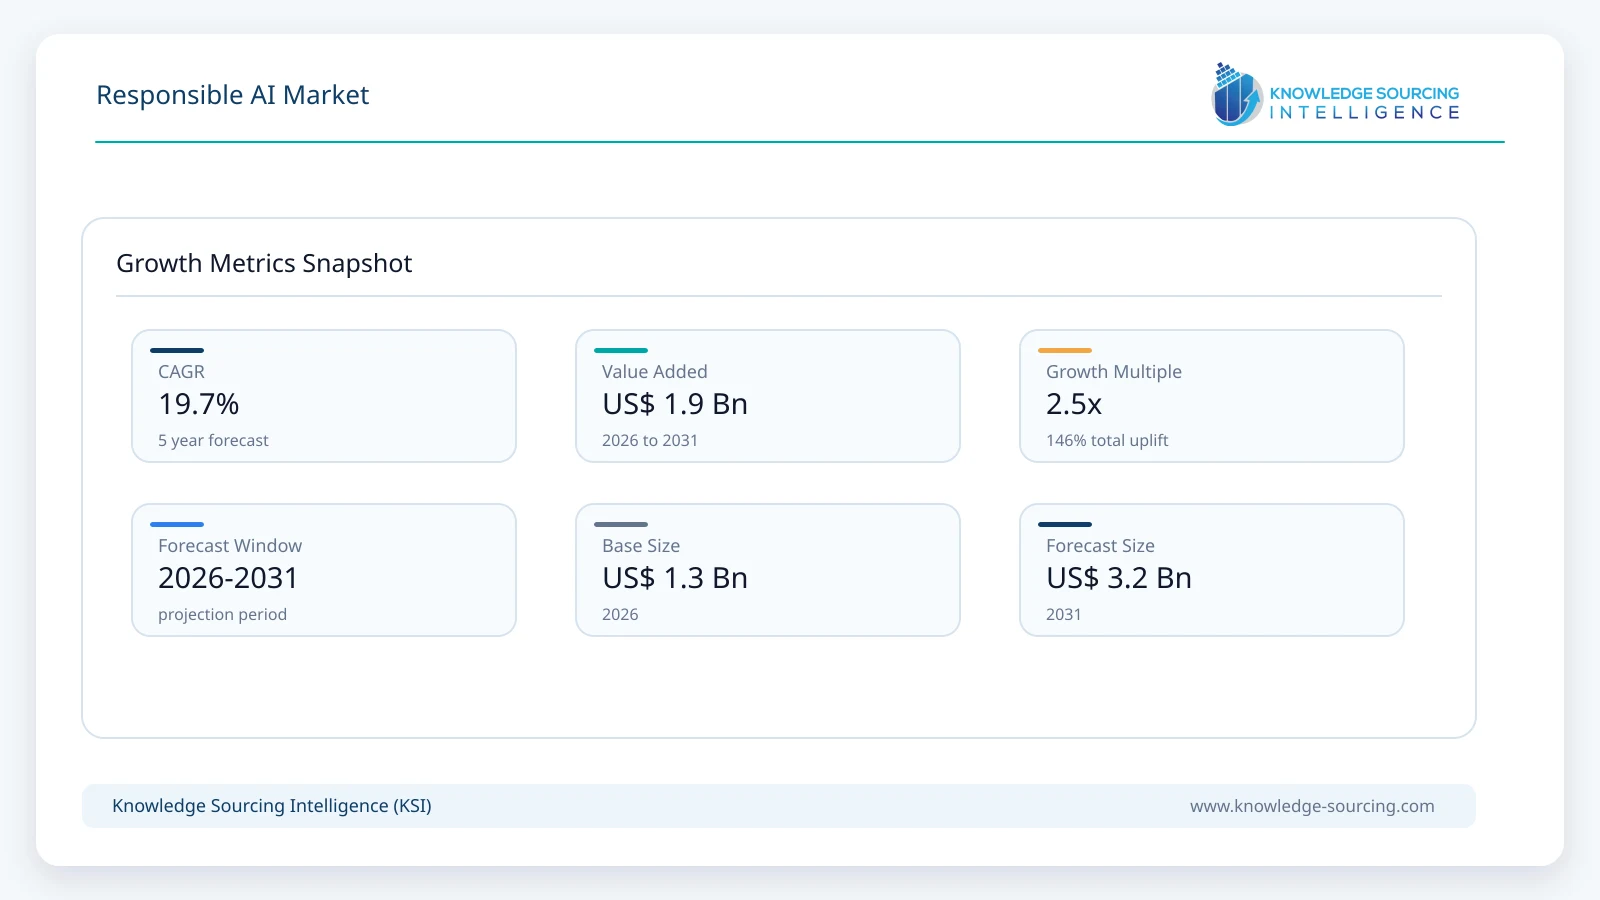
The Responsible AI market is forecast to grow at a CAGR of 19.7%, reaching USD 3.2 billion in 2031 from USD 1.3 billion in 2026.
Highlights:
- 1Software and governance platforms account for approximately 61% of market value in 2026.
- 2Cloud deployment represents approximately 72% of Responsible AI spending in 2026.
- 3BFSI accounts for approximately 26% of market demand, the largest end-user segment.
- 4Asia Pacific records the fastest regional growth through 2031.
- 5Agent governance and runtime policy enforcement are becoming core enterprise requirements.
- 6AI inventories are expanding from models to applications, agents and third-party AI services.
Responsible AI Market Overview
Responsible AI covers the technologies and professional services used to govern, assess, monitor and control artificial intelligence across its lifecycle. The market includes AI inventories, model and agent governance, risk classification, bias and fairness testing, explainability, evaluation, audit evidence, regulatory mapping, model monitoring, guardrails, runtime policy enforcement and associated consulting and assurance services. The scope increasingly overlaps with the term AI governance, as enterprises move from high-level ethical principles toward operational controls that determine which AI systems can be deployed, how they are monitored and what evidence must be retained.
The adoption environment changed materially during 2025 and 2026. Enterprises are no longer governing only internally developed machine-learning models. AI is entering organizations through copilots, foundation-model APIs, third-party applications, and autonomous agents capable of accessing data and executing business actions. OneTrust’s September 2026 survey of 1,200 senior decision-makers found that 74% of respondents had departmental or scaled AI adoption, while only 47% reported clear governance, oversight and controls. This widening implementation gap is increasing demand for technology that identifies AI assets, assigns ownership, applies risk policies, and maintains controls after deployment.
The market is consequently moving away from periodic assessments and spreadsheet-based governance. Modern platforms increasingly provide centralized inventories covering models, applications, vendors and agents; map systems against frameworks such as the EU AI Act, NIST AI RMF and ISO/IEC 42001; automate approval workflows; and integrate runtime monitoring with security and observability infrastructure. Software platforms therefore account for the majority of market value and gain further share through 2031.
Major Market Drivers
Agentic AI Is Turning Governance Into an Operational Control Layer
The transition from predictive models and conversational AI toward autonomous agents materially changes the governance requirement. Conventional AI systems generally produce recommendations or content that a human reviews before action. Agents can instead access applications, retrieve sensitive information, invoke APIs, communicate with other agents, and execute transactions. Governance therefore has to control not only what a model generates but also what an AI system is permitted to do.
Microsoft reported in February 2026 that active AI agents were already being used by 80% of Fortune 500 companies. Its security framework increasingly treats agents as identities requiring ownership, access controls, monitoring, and governance comparable to human users.
Technology providers are responding with infrastructure designed specifically for this environment. ServiceNow expanded AI Control Tower in May 2026 to discover, observe, govern, secure, and measure AI systems and agents across third-party enterprise environments. Google Cloud introduced Agent Identity, Agent Gateway, and expanded Model Armor integration to govern agent interactions and enforce policies at runtime. IBM’s Agentic Control Plane similarly provides centralized visibility and control over enterprise agents.
This changes the economics of Responsible AI. Governance is increasingly purchased as persistent enterprise infrastructure rather than as a one-time ethics assessment or compliance project.
Regulation and Standards Are Being Converted Into Operational Requirements
Responsible AI spending is also increasing as organizations translate regulatory frameworks into internal workflows, controls and documentation.
The EU AI Act entered broad application on 2 August 2026, when the AI Office and national authorities also began exercising enforcement powers and new transparency requirements became applicable. The subsequent AI Omnibus extended certain high-risk obligations: Annex III high-risk use cases now apply from December 2027, while requirements for high-risk AI embedded in regulated products apply from August 2028.
The United States follows a different model. Executive Order 14110 was revoked on January 20, 2025. The current federal policy framework is led by Executive Order 14179, America’s AI Action Plan, and OMB memoranda including M-25-21 for federal AI use and governance. M-25-21 directs agencies to accelerate AI adoption while maintaining safeguards for civil rights, civil liberties, and privacy.
Voluntary standards remain commercially important alongside regulation. NIST is revising AI RMF 1.0 and continues to maintain its Generative AI Profile, while ISO/IEC 42001 establishes requirements for an organizational AI management system covering responsible development and use.
Organizations therefore require governance tools capable of mapping one AI system against multiple legal, regulatory, and voluntary frameworks without rebuilding the control environment for every jurisdiction.
Major Market Restraints
Regulatory Fragmentation Makes Global Governance Architectures Difficult to Standardize
Organizations operating internationally face AI rules that differ substantially in legal basis, scope, risk classification, implementation timing and enforcement.
The European Union uses a horizontal risk-based regulatory framework. The United States combines federal procurement and agency requirements with sectoral regulation and state-level legislation. Other jurisdictions are creating separate approaches around privacy, automated decision-making, generative AI, data governance and model accountability.
Requirements can also change during implementation. The EU’s 2026 AI Omnibus, for example, altered the timetable for high-risk systems while enforcement and transparency provisions continued moving forward.
This creates a practical problem for enterprise buyers. A Responsible AI platform must identify which obligations apply to a particular system according to location, intended use, model type, affected population and industry, while retaining enough flexibility to accommodate regulatory change.
Smaller organizations face a greater burden because legal interpretation, technical testing, documentation and monitoring require expertise that may be distributed across compliance, legal, data science, cybersecurity and business functions.
Governance Can Become a Bottleneck When Controls Are Poorly Integrated
Responsible AI programs can slow deployment when risk assessments and approvals depend heavily on manual questionnaires, disconnected spreadsheets and sequential review.
This becomes increasingly problematic as enterprises deploy hundreds or thousands of AI assets through SaaS applications, internal development and third-party models. Shadow AI can also emerge when employees or business units bypass governance processes that are perceived as too slow.
The technology challenge is therefore not simply to identify risk. Governance needs to connect policies with the systems in which AI is designed and operated. AI inventories must remain current, controls need to integrate with development and security infrastructure, and monitoring information must feed back into governance decisions.
The competitive advantage increasingly shifts toward platforms that automate lower-risk approvals, integrate with existing cloud and development environments, and maintain evidence continuously without forcing every AI use case through the same review process.
Market Trends
AI Inventory Is Expanding From Models to the Entire AI Estate
Earlier model-governance systems largely catalogued internally developed machine-learning models. This approach is increasingly insufficient because enterprise AI now includes third-party foundation models, embedded AI features, applications, autonomous agents and externally supplied services.
OneTrust, Credo AI, Holistic AI, IBM and ServiceNow increasingly position AI inventory as the starting point for governance. The objective is to discover where AI is being used, identify owners, record business purpose and data access, classify risk and connect each AI asset with applicable controls.
The expansion is commercially significant because it increases the number of objects requiring governance. A single enterprise application can involve several foundation models, multiple agents, external tools and proprietary datasets, each creating separate dependencies and risks.
Governance Is Moving From Documentation to Runtime Enforcement
Responsible AI platforms historically concentrated on policies, assessments and audit documentation. The market is now moving toward controls that can intervene while AI systems operate.
AWS expanded Amazon Bedrock Guardrails during 2026 with centralized cross-account safeguards and APIs capable of applying individual checks at different stages of an agentic workflow. Google Cloud is integrating Model Armor with Agent Gateway and agent runtimes, while Holistic AI and other dedicated governance vendors are developing policy enforcement and runtime controls for agents.
This represents a significant product transition. Governance systems increasingly need to translate policy into executable controls rather than simply document whether a policy exists.
Audit Evidence Is Becoming Continuous
Enterprise governance is also moving away from point-in-time certification toward ongoing evidence collection.
IBM introduced Enforcement Tracking for watsonx Orchestrate in August 2026, automatically capturing agent evaluation metrics as evidence within watsonx.governance. The system extends governance tracking across traditional machine learning, large language models and agents.
Continuous evidence improves auditability because organizations can demonstrate how an AI system behaved after approval instead of relying exclusively on pre-deployment testing.
The approach is particularly relevant to regulated financial, healthcare and public-sector applications, where model behavior can change as underlying data, prompts, workflows and external models evolve.
Governance Is Expanding From Risk Control to Business Accountability
AI governance is beginning to incorporate whether deployed systems deliver their intended business outcomes.
IBM introduced Business Value Alignment in watsonx.governance in September 2026 to connect AI initiatives with strategic objectives, business cases, KPIs and realized outcomes.
This broadens the governance function beyond ethics and compliance. Enterprises increasingly want to know whether an AI system remains authorized, performs reliably, complies with policy and continues to justify its cost.
Responsible AI platforms are consequently converging with wider AI management and control-plane architectures.
Segment Analysis:
By Component
Software Tools and Platforms
Software and platforms account for approximately 61% of global Responsible AI market value in 2026 and are projected to reach around 64% by 2031.
The segment includes enterprise AI inventories, governance workflow platforms, model and agent risk management, testing and evaluation, compliance mapping, monitoring, explainability tools, runtime guardrails and automated evidence management.
Growth is being driven by the inability of manual governance processes to scale with enterprise AI deployment. AI assets increasingly change after approval as underlying models are updated, prompts evolve and agents gain access to additional tools. Continuous monitoring and policy enforcement therefore become more important than periodic reviews.
Large technology providers are integrating governance into broader AI platforms, while dedicated vendors compete through framework mapping, AI discovery, risk intelligence and lifecycle governance.
By Deployment
Cloud
Cloud deployment accounts for approximately 72% of global market value in 2026 and is projected to reach approximately 80% by 2031.
Responsible AI increasingly needs to monitor AI systems distributed across cloud platforms, SaaS applications and foundation-model providers. Cloud deployment enables governance policies, risk libraries and regulatory mappings to be updated centrally while allowing organizations to monitor rapidly changing AI estates.
The segment also benefits from increasing integration between governance tools and hyperscale AI infrastructure. AWS, Microsoft and Google increasingly embed safety, monitoring and policy capabilities directly within their AI services.
On-premises and private deployment remains relevant for defense, financial services, critical infrastructure and organizations operating highly sensitive AI workloads. However, its market share declines as hybrid and cloud-connected governance architectures become more capable.
By End User
Banking, Financial Services and Insurance
BFSI represents approximately 26% of global Responsible AI market value in 2026, making it the largest end-user segment.
Financial institutions have long operated formal model-risk-management frameworks, making them comparatively prepared to extend governance into machine learning and generative AI. However, AI introduces additional challenges around unstructured model outputs, autonomous agents, third-party foundation models, bias, explainability and data leakage.
Responsible AI requirements span credit decisioning, fraud detection, customer service, investment analysis, underwriting, compliance and internal productivity applications. Financial institutions therefore require combinations of model inventory, approval workflow, explainability, testing, monitoring, audit evidence and third-party AI risk management.
BFSI remains the largest end-user through 2031, although manufacturing, automotive and broader enterprise technology adoption grow faster from smaller bases.
By Geography
North America
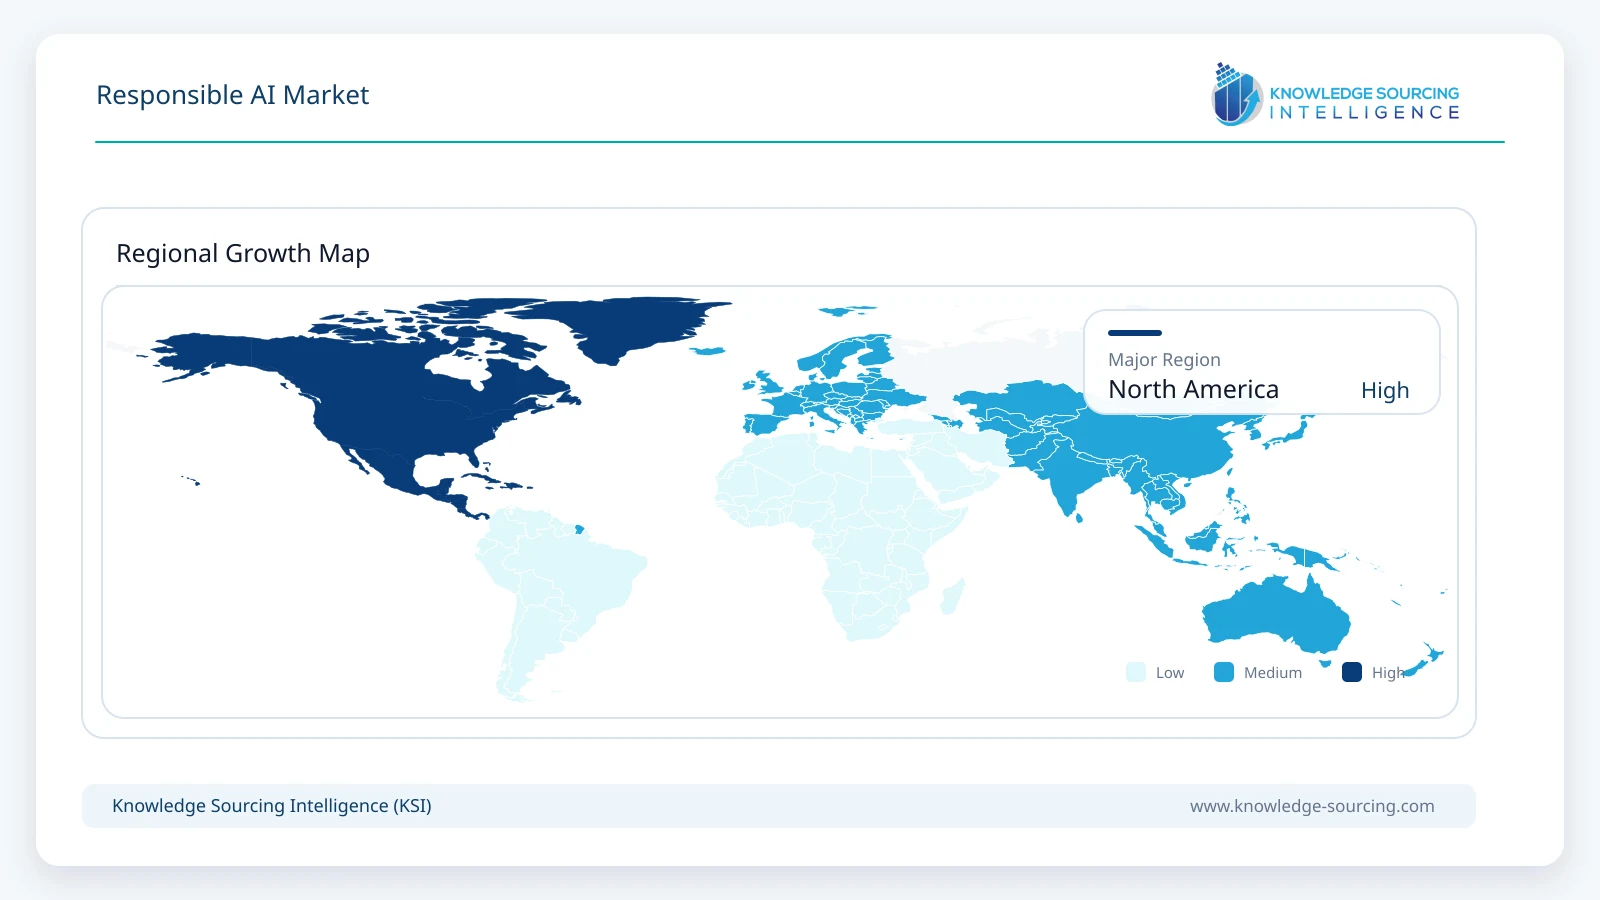
North America accounts for approximately 43% of global market value in 2026, making it the largest regional Responsible AI market.
The region benefits from the presence of major cloud platforms, AI model developers, enterprise software providers and specialist AI governance companies. The United States also has a mature ecosystem of financial services, healthcare, technology and regulated enterprises that already use formal risk-management processes.
The federal policy environment changed materially in 2025. Executive Order 14110 was revoked and replaced by a more innovation-oriented policy under Executive Order 14179 and America’s AI Action Plan, while OMB continues to impose governance requirements on federal agency AI use and acquisition. NIST AI RMF also remains an important voluntary framework used by private and public-sector organizations.
North America remains the largest regional market through 2031 but gradually loses share as regulatory implementation in Europe and enterprise AI adoption across Asia Pacific accelerate.
Competitive Landscape
The Responsible AI market is developing into a distinct enterprise software category rather than remaining a collection of ethics-consulting services.
IBM combines AI governance with its broader watsonx environment and is expanding from model governance toward agent governance, enforcement evidence and business-value tracking. ServiceNow is positioning AI Control Tower as a cross-enterprise governance layer capable of discovering and managing AI outside the ServiceNow environment.
AWS, Microsoft and Google Cloud integrate Responsible AI controls into their cloud and AI infrastructure. Their advantage is proximity to model deployment, identity, security, data and application infrastructure. AWS emphasizes Bedrock Guardrails, Microsoft increasingly integrates AI and agent governance with its security architecture, and Google is expanding Agent Gateway, Agent Identity and Model Armor.
A separate group of specialist companies is emerging around dedicated AI governance. OneTrust integrates AI governance with privacy, data and enterprise risk workflows. Credo AI focuses specifically on AI inventories, policy mapping, risk controls and lifecycle governance, while Holistic AI combines discovery, testing, monitoring and runtime enforcement.
Professional-services firms remain important because many organizations require assistance designing governance operating models, interpreting regulation and integrating controls with existing technology. Accenture, Deloitte, PwC, KPMG and Capgemini therefore participate alongside software vendors rather than competing solely as implementation partners.
The market remains fragmented, with competition increasingly determined by AI asset discovery, framework mapping, agent governance, runtime enforcement, ecosystem integration and the ability to produce audit-ready evidence.
Recent Developments
September 9, 2026: IBM introduced Business Value Alignment in watsonx.governance, connecting AI initiatives with business objectives, KPIs and realized outcomes.
August 11, 2026: IBM introduced Enforcement Tracking for watsonx Orchestrate, allowing agent-evaluation information to be captured as governance evidence continuously.
August 2, 2026: European Commission and national authorities began enforcing applicable AI Act provisions, while new Article 50 transparency requirements became effective.
May 5, 2026: ServiceNow expanded AI Control Tower to discover, observe, govern, secure and measure AI deployed across enterprise systems.
April 22, 2026: Google Cloud introduced additional agent-governance capabilities, including Agent Identity and Agent Gateway, and expanded Model Armor integration for agentic workloads.
April 3, 2026: AWS introduced centralized cross-account enforcement for Amazon Bedrock Guardrails, allowing organizations to apply safety policies across multiple AWS accounts.
Market Outlook
Responsible AI is moving from a policy-led discipline into an operational software layer for enterprise AI.
The strongest demand increasingly comes from organizations managing large portfolios of models, applications and agents rather than from standalone ethical-AI projects. Software platforms gain share as governance becomes continuous, automated and integrated with cloud, security and development infrastructure.
Agentic AI creates an additional growth layer because organizations must govern not only model outputs but also identity, permissions, tool access and autonomous actions. AI inventories, runtime controls, evaluation, evidence collection and policy enforcement consequently become central product capabilities.
Regulatory requirements continue to influence purchasing, but compliance is not the market’s only long-term driver. Enterprises increasingly require governance to prevent unmanaged AI, reduce operational incidents, maintain visibility over third-party systems and determine whether AI investments continue to deliver business value.
Responsible AI Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.3 billion |
| Total Market Size in 2031 | USD 3.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Deployment, End-User, Geography |
| Companies |
|
Market Segmentation
BY Component
Software Tools and Platforms
AI Inventory and Governance Workflow
AI Risk and Compliance Management
Model and Agent Testing and Evaluation
Explainability and Bias Management
Monitoring and Observability
Guardrails and Runtime Policy Enforcement
Audit Evidence and Regulatory Mapping
Services
Advisory and Governance Framework Implementation
AI Risk Assessment and Testing
Audit and Assurance
Managed Governance Services
Others
BY Deployment
Cloud
On-Premises and Private Environment
BY End User
Banking, Financial Services and Insurance
Healthcare and Life Sciences
Government and Public Sector
IT and Telecommunications
Manufacturing and Automotive
Retail and Consumer
Others
BY Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Netherlands
Italy
Spain
Switzerland
Others
Middle East and Africa
UAE
Saudi Arabia
Israel
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Singapore
Australia
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Market Estimation
2.6. Data Triangulation
2.7. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Agentic AI and Autonomous Enterprise Systems
4.1.2. Operationalization of AI Regulation and Governance Standards
4.1.3. Increasing Enterprise AI Inventories and Third-Party AI Usage
4.1.4. Transition From Manual Governance to Continuous Controls
4.2. Market Restraints
4.2.1. Regulatory Fragmentation Across Jurisdictions
4.2.2. Governance Integration and Operational Complexity
4.2.3. Shortage of Cross-Functional AI Risk Expertise
4.2.4. Governance Friction and Shadow AI
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. AI Governance and Regulatory Landscape
4.7. Strategic Recommendations
5. TECHNOLOGY AND GOVERNANCE OUTLOOK
5.1. Enterprise AI Inventory
5.2. Model Governance
5.3. Agent Governance
5.4. AI Risk Classification
5.5. Explainability and Interpretability
5.6. Bias and Fairness Testing
5.7. AI Evaluation and Red Teaming
5.8. Runtime Guardrails
5.9. Policy-as-Code and Automated Enforcement
5.10. Continuous Monitoring and Evidence Collection
5.11. AI Vendor and Third-Party Risk Management
6. RESPONSIBLE AI MARKET BY COMPONENT
6.1. Software Tools and Platforms
6.1.1. AI Inventory and Governance Workflow
6.1.2. AI Risk and Compliance Management
6.1.3. Model and Agent Testing and Evaluation
6.1.4. Explainability and Bias Management
6.1.5. Monitoring and Observability
6.1.6. Guardrails and Runtime Policy Enforcement
6.1.7. Audit Evidence and Regulatory Mapping
6.2. Services
6.2.1. Advisory and Governance Framework Implementation
6.2.2. AI Risk Assessment and Testing
6.2.3. Audit and Assurance
6.2.4. Managed Governance Services
6.2.5. Others
7. RESPONSIBLE AI MARKET BY DEPLOYMENT
7.1. Cloud
7.2. On-Premises and Private Environment
8. RESPONSIBLE AI MARKET BY END USER
8.1. Banking, Financial Services and Insurance
8.2. Healthcare and Life Sciences
8.3. Government and Public Sector
8.4. IT and Telecommunications
8.5. Manufacturing and Automotive
8.6. Retail and Consumer
8.7. Others
9. RESPONSIBLE AI MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Netherlands
9.3.5. Italy
9.3.6. Spain
9.3.7. Switzerland
9.3.8. Others
9.4. Middle East and Africa
9.4.1. UAE
9.4.2. Saudi Arabia
9.4.3. Israel
9.4.4. South Africa
9.4.5. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Singapore
9.5.6. Australia
9.5.7. Taiwan
9.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Product Launches and Platform Expansion
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. IBM Corporation
11.2. ServiceNow, Inc.
11.3. OneTrust, LLC
11.4. Microsoft Corporation
11.5. Amazon Web Services, Inc.
11.6. Google LLC
11.7. SAS Institute Inc.
11.8. Fair Isaac Corporation
11.9. SAP SE
11.10. Credo AI
11.11. Holistic AI
11.12. Accenture plc
12. APPENDIX
Navigate
Trusted by the world's leading organizations











