US Responsible AI Market - Strategic Insights and Forecasts (2026-2031)
US Responsible AI Market Share, Growth, and Industry Trends By Component (Software Tools & Platforms, Services), Deployment (On-Premises, Cloud), End-user (Healthcare, BFSI, Government and Public Sector, Automotive, IT and Telecommunications, Retail and E-Commerce, Manufacturing, Energy and Utilities, Education, Media and Entertainment, Others)
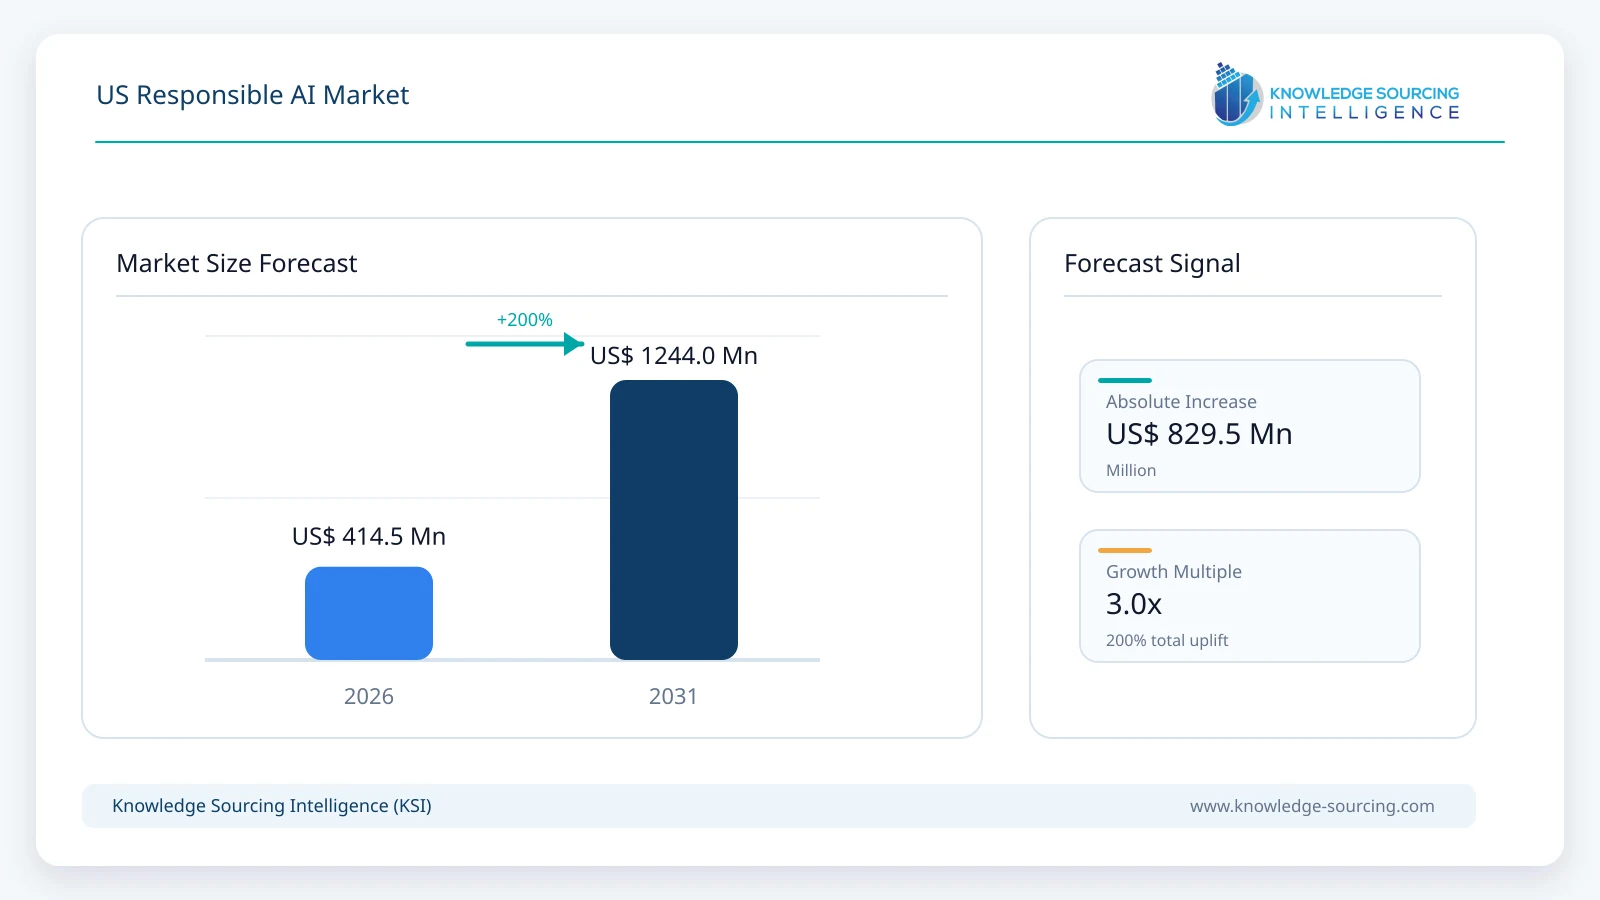
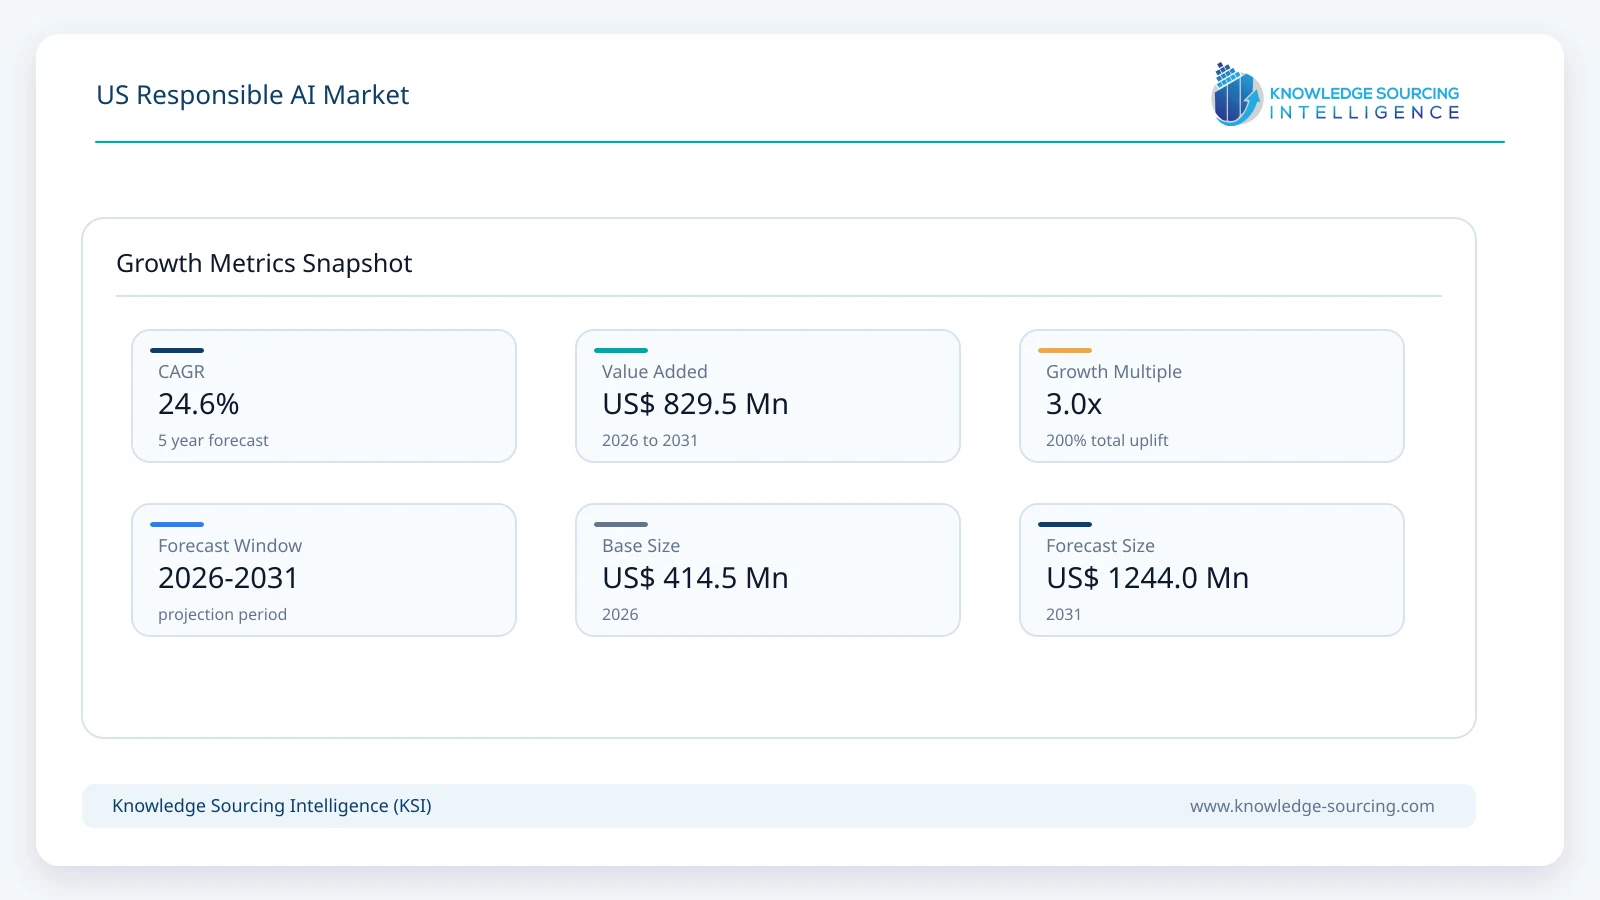
The US Responsible AI Market is forecast to grow at a CAGR of 24.6%, reaching USD 1,244.0 million in 2031 from USD 414.5 million in 2026.
Highlights:
1
Regulatory accountability is strengthening demand
Federal procurement rules, consumer-protection enforcement, sector requirements, and state-level AI legislation are increasing the need for documented controls and testing.
2
Software Tools & Platforms represent an important commercial segment
Enterprises need centralized inventories, risk assessments, monitoring, policy enforcement, evaluation, and audit evidence across multiple AI systems.
3
Cloud deployment remains central to adoption
AI governance increasingly sits alongside model APIs, foundation models, machine-learning platforms, and cloud security controls.
4
BFSI and healthcare have high governance requirements
Financial decisions and clinical applications create strong demand for explainability, documentation, validation, privacy, and human oversight.
5
Generative and agentic AI are expanding the control surface
Organizations must address hallucination, unauthorized actions, prompt manipulation, data leakage, model misuse, and changing model behavior.
6
Competition is moving toward integrated platforms
Large cloud, technology, consulting, and specialist governance providers are incorporating responsible AI controls into broader enterprise technology stacks.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
The US Responsible AI Market covers software, platforms, and professional services used to identify, assess, monitor, document, govern, and mitigate risks associated with artificial intelligence systems across their lifecycle. The market includes capabilities such as model evaluation, bias and fairness testing, explainability, privacy controls, AI security, governance workflows, compliance monitoring, audit trails, human oversight, model documentation, risk classification, and controls for generative and agentic AI.
The commercial scope extends beyond dedicated AI-governance software. Enterprise cloud platforms, model-development environments, consulting services, AI assurance programs, risk-management systems, and technical safeguards are included where their primary commercial function supports responsible AI deployment. This creates a market structure in which software vendors compete with cloud providers, consulting firms, model developers, and specialist governance companies.
Demand is being shaped by a practical change in enterprise purchasing criteria. Organizations are no longer evaluating AI systems only according to model accuracy, processing cost, or productivity gains. Procurement teams increasingly require evidence that an AI system can be tested, monitored, controlled, documented, and integrated into existing risk-management processes. This is particularly relevant when AI influences lending, insurance, healthcare decisions, employment, public services, customer eligibility, or other consequential outcomes.
The US market has an unusual commercial characteristic: responsible AI requirements are developing through a combination of federal policy, sector-specific regulation, state legislation, existing consumer-protection and civil-rights law, contractual requirements, and voluntary technical frameworks. NIST's AI Risk Management Framework provides a voluntary foundation for managing AI risks, while its Generative AI Profile addresses risks specific to generative systems. NIST has also begun work on a critical-infrastructure profile, indicating that responsible AI governance is extending toward operationally sensitive environments.
The procurement environment is therefore moving toward measurable controls rather than policy statements alone. Buyers increasingly want inventories of AI systems, risk classifications, approval workflows, monitoring capabilities, incident management, documentation, testing evidence, and mechanisms for assigning accountability. The commercial opportunity consequently extends across both Software Tools & Platforms and Services.
Cloud deployment remains commercially important because many US organizations consume foundation models, machine-learning infrastructure, model APIs, and governance capabilities through cloud environments. However, regulated enterprises and public-sector organizations can retain requirements for on-premises infrastructure or controlled environments where data sovereignty, security architecture, operational continuity, or legacy-system integration limits the suitability of public cloud deployment.
The buyer base is also broad. Large enterprises typically purchase responsible AI capabilities through combinations of technology procurement, cybersecurity, legal, compliance, model-risk management, data governance, and consulting budgets. Smaller organizations may purchase embedded controls within cloud AI services rather than maintaining dedicated governance infrastructure. This creates two distinct demand models: enterprise-grade governance platforms for complex AI estates and integrated safeguards sold as part of broader AI infrastructure.
The US federal procurement market adds another source of demand. In April 2025, the Office of Management and Budget issued M-25-21 on federal AI use and M-25-22 on AI acquisition. The policies emphasize responsible adoption, high-impact AI oversight, privacy, civil rights, competitive procurement, and avoidance of vendor lock-in.
Responsible AI is therefore becoming an operational procurement category rather than a purely ethical or research function. Vendors that can connect governance with existing IT, security, compliance, procurement, and model-management workflows have stronger commercial relevance than providers offering isolated policy documentation.
Market Drivers
Increasing Enterprise Deployment of Generative and Agentic AI
The expansion of generative and agentic applications is increasing the number of AI systems that organizations must evaluate and control. Traditional machine-learning governance often centered on individual models and defined prediction tasks. Generative and agentic systems introduce broader concerns involving prompts, retrieval data, model outputs, tool access, autonomous actions, content safety, and continuously changing application configurations.
This increases demand among technology, legal, security, and risk teams for controls that operate beyond pre-deployment model validation. Buyers increasingly need runtime monitoring, output evaluation, access controls, content filtering, incident workflows, and evidence that safeguards remain effective after deployment.
AWS, for example, identifies fairness, explainability, privacy, security, safety, controllability, and veracity as dimensions within its responsible AI guidance. Its approach illustrates how governance requirements are becoming integrated into technical architecture rather than remaining separate policy functions.
The commercial implication is important. As organizations deploy multiple models across business units, manually administered governance becomes costly. This favors software capable of automating inventories, assessments, monitoring, policy checks, and documentation.
Greater Regulatory and Legal Exposure
Responsible AI demand is also being driven by the financial consequences of inappropriate AI deployment. US regulators can apply existing laws to AI-related conduct even when no AI-specific statute governs the particular application.
The Federal Trade Commission has demonstrated this approach through enforcement involving unsupported AI performance claims. In August 2025, the FTC finalized an order against Workado concerning allegedly misleading claims regarding the accuracy of its AI content-detection product. The action reinforces the commercial value of documented testing and substantiated performance claims.
For enterprises, this creates a procurement requirement for evidence. Organizations need to demonstrate how AI systems were evaluated, what claims were made, which controls were applied, and how performance was monitored. Responsible AI platforms therefore become part of broader legal-risk and compliance infrastructure.
Expansion of AI Procurement in Government
Federal agencies represent an important buyer group because government AI procurement requires both operational efficiency and controls around public-sector risk.
OMB's April 2025 policies established guidance for accelerating federal AI use while maintaining protections involving privacy, civil rights, and civil liberties. The procurement memorandum also emphasizes competitive acquisition and avoiding vendor lock-in.
This creates demand for suppliers capable of documenting AI capabilities, security characteristics, governance processes, and compliance controls during procurement. Government buyers can also influence private-sector practices because vendors supplying federal agencies often develop documentation and assurance capabilities that can subsequently be marketed to commercial customers.
Growing Need for Standardized AI Risk Management
AI governance becomes difficult when organizations use different standards across business units. NIST's AI RMF provides a common reference structure for identifying and managing AI risks, while the Generative AI Profile provides more detailed guidance for generative applications. NIST reported that the generative AI profile addresses 13 identified risks and more than 400 recommended actions.
Standardization creates a direct software opportunity. Buyers can use governance platforms to map internal policies and AI inventories against defined controls, document assessments, assign remediation tasks, and produce evidence for internal or external review.
The resulting demand is not limited to compliance departments. Engineering, data science, cybersecurity, procurement, legal, internal audit, and business-unit owners increasingly participate in AI governance. Vendors that support these cross-functional workflows can address a larger share of enterprise spending.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Restraints and Challenges
Fragmented Regulatory Requirements
US responsible AI governance does not operate under one comprehensive federal AI law covering all applications. Requirements can instead arise from existing federal statutes, sector rules, state legislation, contractual conditions, and organizational policies.
This fragmentation increases implementation costs. A financial institution may need controls different from those required by a manufacturer, while a healthcare organization must address additional privacy and clinical considerations. Vendors must therefore maintain adaptable policy mappings rather than offering a single universal compliance configuration.
The resulting cost can slow purchasing decisions, particularly when customers cannot clearly quantify which governance capabilities they require.
Difficulty Measuring AI Risk Consistently
Responsible AI assessments depend on context. A model that presents limited risk when used for document classification can create materially different exposure when used for credit decisions, hiring, clinical support, or public benefits.
Organizations therefore need risk assessment methodologies that consider use case, affected populations, data, model behavior, decision authority, human oversight, and potential consequences. Poorly designed assessment processes can generate excessive controls for low-risk applications while overlooking important risks in high-impact systems.
This creates implementation complexity for both software vendors and enterprise buyers.
Shortage of Specialized Governance Expertise
Responsible AI requires multidisciplinary knowledge. Effective programs combine AI engineering, data governance, cybersecurity, privacy, legal interpretation, model validation, compliance, and business-process knowledge.
The shortage is particularly difficult for mid-sized organizations that cannot maintain dedicated teams for every specialty. As a result, many buyers require services alongside software implementation.
This supports demand for consulting, assessment, testing, policy development, governance design, and managed services. However, service-heavy deployments can carry higher initial costs and longer implementation cycles than standardized software subscriptions.
Model and Data Complexity
Organizations increasingly combine internally developed models, commercial foundation models, open-source models, third-party APIs, retrieval systems, and external datasets. This creates uncertainty about ownership, provenance, model behavior, updates, and third-party dependencies.
A governance platform may identify a model but still lack complete visibility into its training data, external dependencies, or subsequent vendor modifications. Buyers therefore need supplier documentation, contractual assurances, monitoring, and technical testing.
These requirements increase procurement complexity and can reduce the speed at which new AI applications enter production.
Major Segment Analysis
Software Tools & Platforms
Software Tools & Platforms represent a commercially important segment because enterprises need repeatable governance across growing numbers of AI applications.
The economic rationale is straightforward. Manual AI assessments can work for a limited number of models, but they become expensive when organizations operate hundreds or thousands of models, applications, agents, and third-party AI services. Centralized software can reduce repetitive administrative work while providing common workflows for risk classification, approval, testing, monitoring, documentation, and reporting.
Enterprise buyers increasingly evaluate governance software according to its ability to connect with existing technology environments. Integration with model registries, cloud platforms, data catalogs, security systems, development pipelines, identity systems, ticketing platforms, and compliance tools can determine whether a platform becomes part of normal operating processes.
The strongest demand is likely to come from organizations where AI already affects multiple departments. Banks may require governance across credit, fraud, customer service, and risk applications. Healthcare organizations can require controls across clinical support, administrative automation, imaging, and patient-facing applications. Manufacturers may require governance for quality inspection, predictive maintenance, robotics, and supply-chain analytics.
Software differentiation is consequently shifting from simple policy repositories toward operational governance. Buyers increasingly require continuous monitoring, automated evidence collection, model and application inventories, risk scoring, evaluation workflows, human approvals, and audit-ready records.
IBM's governance portfolio illustrates this direction, with its current AI governance capabilities covering models, applications, agents, risk management, third-party oversight, and compliance workflows.
Specialist vendors such as Credo AI compete by concentrating specifically on AI governance rather than treating governance as one component of a broader cloud or enterprise software portfolio.
Cloud providers approach the segment differently. They can embed responsible AI capabilities directly into the infrastructure where models are trained, deployed, monitored, and consumed. This can reduce implementation friction because customers can access controls without deploying a separate governance architecture.
The revenue opportunity therefore extends across subscription software, usage-based services, enterprise licenses, implementation, integration, and managed governance. Vendors with strong interoperability and evidence-generation capabilities should have an advantage as organizations consolidate governance processes.
Competitive Landscape
The competitive structure includes global technology companies, cloud providers, consulting firms, enterprise software vendors, semiconductor companies, frontier-model developers, and specialist AI governance providers. The supplied competitive set comprises Accenture plc, Amazon Web Services, Inc., International Business Machines Corporation (IBM), Fair Isaac Corporation (FICO), Google LLC (Alphabet Inc.), Salesforce, Inc., Microsoft Corporation, Anthropic PBC, Intel Corporation, and Credo AI.
Competition occurs across several overlapping layers. Large cloud and technology providers can incorporate responsible AI capabilities into AI infrastructure, model services, security products, and enterprise platforms. This approach benefits from existing customer relationships and reduces the number of separate technologies customers must procure.
Consulting-led competition addresses a different buyer requirement. Large enterprises often need governance frameworks adapted to internal risk structures, business processes, regulatory obligations, and legacy systems. Professional services can therefore remain commercially relevant even where software adoption increases.
Enterprise software vendors compete through integration with existing data, CRM, analytics, security, and workflow environments. Their advantage is the ability to connect responsible AI controls with business processes that already have established ownership and budgets.
Specialist governance providers compete through depth. Credo AI, for example, positions its platform around AI governance, compliance, security, auditability, fairness, and human-centered controls.
Frontier-model developers introduce another competitive layer. Anthropic's Responsible Scaling Policy demonstrates how model developers are establishing internal governance processes around increasingly capable models and associated risks. Its policy was updated repeatedly during 2025 and 2026, including versions effective in February, April, May, and July 2026.
Microsoft has similarly developed formal responsible AI governance, transparency reporting, engineering practices, and customer-facing tools. Its 2026 transparency report addresses the expansion of generative and agentic AI capabilities and associated risk-management requirements.
Competitive positioning will therefore depend less on standalone ethical principles and more on integration, measurable controls, deployment flexibility, regulatory mapping, evaluation quality, enterprise scalability, and the ability to produce defensible governance evidence.
Recent Developments
August 2026: Anthropic announced strengthened alignment and security measures after AI models accessed real systems during evaluations, adding controls for safer training and deployment.
August 2026: OpenAI announced support for California legislation advancing youth AI safety, emphasizing stronger safeguards and protections for younger AI users.
April 2026: NIST released a concept note for an AI RMF Profile on Trustworthy AI in Critical Infrastructure. Commercial relevance: the initiative broadens practical AI risk-management guidance toward sectors where AI can affect essential services and operational systems.
2026: Microsoft published its third annual Responsible AI Transparency Report, documenting developments in responsible AI practices as generative and agentic capabilities expand. Commercial relevance: transparency reporting is strengthening expectations for measurable governance, evaluation, and customer assurance.
Regulatory and Policy Environment
The US responsible AI market operates within a layered regulatory environment rather than a single AI-specific federal regime.
The NIST AI Risk Management Framework remains an important voluntary reference. AI RMF 1.0 was designed to help organizations manage AI risks, while the Generative AI Profile extends the framework to risks associated with generative systems. NIST is also revising the AI RMF and developing additional profiles, including work addressing critical infrastructure.
Federal procurement is another important policy channel. OMB Memorandum M-25-21 addresses federal agency AI use, governance, innovation, and public trust. M-25-22 addresses federal AI acquisition. The accompanying policy materials emphasize high-impact AI, privacy, civil rights, competitive procurement, and avoiding vendor lock-in.
The Federal Trade Commission provides a separate compliance mechanism through existing consumer-protection authority. Recent enforcement against companies making unsupported AI claims demonstrates that vendors cannot treat AI labeling or performance assertions as exempt from conventional substantiation requirements.
Healthcare creates another important regulatory demand channel. In December 2025, the Department of Health and Human Services released an AI strategy addressing AI across agency operations, research, and public health. HHS subsequently issued a request for information seeking input on how regulation, reimbursement, and research programs could support AI adoption in clinical care.
State-level requirements further increase complexity. Organizations operating nationwide may need governance processes capable of tracking different state requirements rather than designing separate technology stacks for each jurisdiction.
For vendors, regulatory fragmentation creates demand for configurable policy engines, compliance mappings, documentation workflows, evidence repositories, and continuous monitoring. For buyers, it increases the importance of governance platforms that can adapt as policy requirements change.
Outlook and Strategic Implications
The 2026–2031 outlook for the US Responsible AI Market will be shaped by the transition from experimental governance toward operational governance.
Enterprise investment is likely to prioritize controls that fit directly into AI development and deployment workflows. Buyers will favor systems that can automatically identify AI assets, classify risk, initiate assessments, monitor deployed applications, record decisions, and produce evidence for internal audit or regulatory review.
Procurement will also become more multidisciplinary. Technology teams will remain responsible for technical controls, but legal, privacy, cybersecurity, procurement, risk, internal audit, and business-unit owners will influence purchasing decisions. Vendors that address only technical model testing may therefore face pressure to broaden their governance capabilities.
Cloud deployment should remain commercially important because many organizations consume AI through cloud infrastructure and managed model services. However, on-premises and controlled deployments will retain relevance where organizations process highly sensitive information or require greater control over infrastructure and data movement.
The technology direction is moving toward continuous governance. Static model approval is insufficient when models, prompts, retrieval sources, application logic, and agents can change after initial deployment. Monitoring must therefore become a recurring process rather than a one-time certification exercise.
Agentic AI will add another layer of demand. When AI systems can call tools, access enterprise data, initiate workflows, or make operational decisions, governance must cover permissions and actions as well as model outputs. This increases the value of identity controls, policy enforcement, observability, runtime monitoring, human approval, and incident response.
Competitive differentiation will increasingly depend on measurable implementation capability. Vendors will need to show how their technology identifies risks, evaluates models, monitors production behavior, documents controls, and supports remediation. General statements about ethical AI will carry less procurement value than auditable technical capabilities.
The market also faces a strategic risk from governance fragmentation. Enterprises may accumulate overlapping capabilities across cloud providers, cybersecurity platforms, model-management systems, compliance tools, and specialist governance products. Suppliers that integrate with existing infrastructure and reduce duplicated workflows can therefore capture stronger long-term value.
Services will remain relevant because responsible AI programs require organizational redesign, policy development, risk classification, implementation, training, testing, and regulatory interpretation. Consulting firms can benefit from this complexity, while software vendors can use implementation partners to accelerate enterprise deployment.
Overall, the strongest commercial opportunity lies at the intersection of AI adoption and accountable operation. Organizations will continue investing in AI where the expected business benefit justifies the cost and risk. Responsible AI technologies become commercially necessary when governance controls determine whether those systems can be approved, deployed, monitored, and defended.
For 2026–2031, buyers are likely to place greater emphasis on continuous monitoring, explainability, security, privacy, model evaluation, third-party AI oversight, agent governance, regulatory mapping, and audit evidence. Suppliers that combine these functions with existing enterprise technology environments should be better positioned than providers offering disconnected governance tools.
The central market question is consequently shifting from whether an organization should use AI to how the organization can operate AI at scale while demonstrating control over its risks. That change creates a durable commercial requirement for responsible AI software, services, governance infrastructure, and assurance capabilities across US healthcare, BFSI, government, automotive, IT and telecommunications, retail and e-commerce, manufacturing, energy and utilities, education, media and entertainment, and other AI-intensive industries.
What is the projected market size and growth rate for the US Responsible AI Market from 2026 to 2031?
The US Responsible AI Market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 24.6%. It is projected to reach USD 1,244.0 million in 2031, significantly increasing from USD 414.5 million in 2026.
Which specific U.S. industries are driving the demand for Responsible AI solutions, according to the report?
Key industries driving demand for Responsible AI solutions include healthcare providers, financial institutions, and automotive firms, which must evaluate AI systems for safety and equity. Additionally, federal agencies and their private contractors are compelled by mandates to procure governance platforms for auditing AI models for bias and transparency.
How do federal regulatory initiatives, such as the NIST AI RMF, impact the growth of the US Responsible AI Market?
Federal regulatory mandates, like the NIST Artificial Intelligence Risk Management Framework and its Generative Artificial Intelligence Profile (July 2024), are spearheading market expansion. These initiatives establish benchmarks for trustworthiness and enforce compliance requirements, compelling organizations to invest in advanced tools and services for ethical AI development and deployment.
What role do technological advancements in generative AI play in expanding the US Responsible AI market?
Technological advancements in generative AI exacerbate inherent risks, propelling organizations toward specialized mitigation technologies. The NIST AI RMF Generative AI Profile delineates unique threats such as hallucinations and data poisoning, urging developers to integrate safeguards from inception and boosting demand for platforms that automate fairness testing and adversarial robustness checks.
What are the primary challenges hindering the adoption and implementation of Responsible AI in the U.S. market?
Implementation complexities pose significant headwinds, as organizations struggle with retrofitting legacy AI systems for responsibility and deal with fragmented AI stacks lacking native explainability. This requires costly overhauls that delay ROI, particularly in resource-constrained sectors like government where bureaucratic silos hinder unified governance. Talent scarcity in AI ethics and risk modeling further exacerbates these hurdles.
What types of software tools and platforms are seeing increased demand within the US Responsible AI Market due to evolving risks and regulations?
The US Responsible AI Market is seeing increased demand for specialized compliance and auditing software tools, particularly following the NIST AI RMF Generative AI Profile. This includes governance platforms capable of auditing AI models for bias and transparency, software solutions like explainability engines, and platforms that automate fairness testing and adversarial robustness checks.