
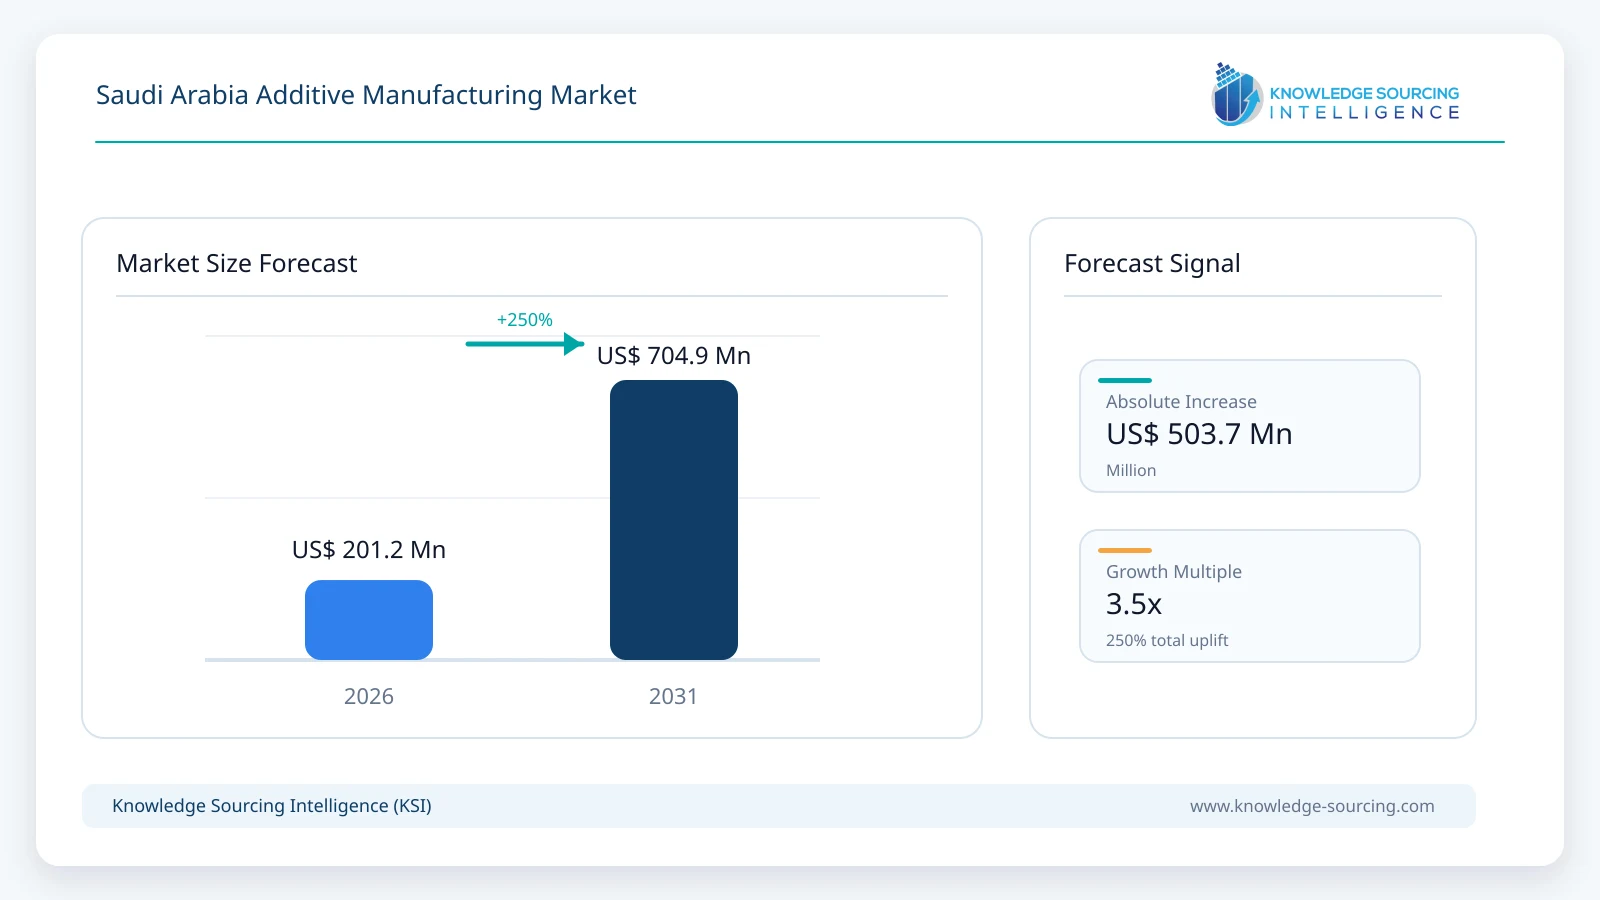
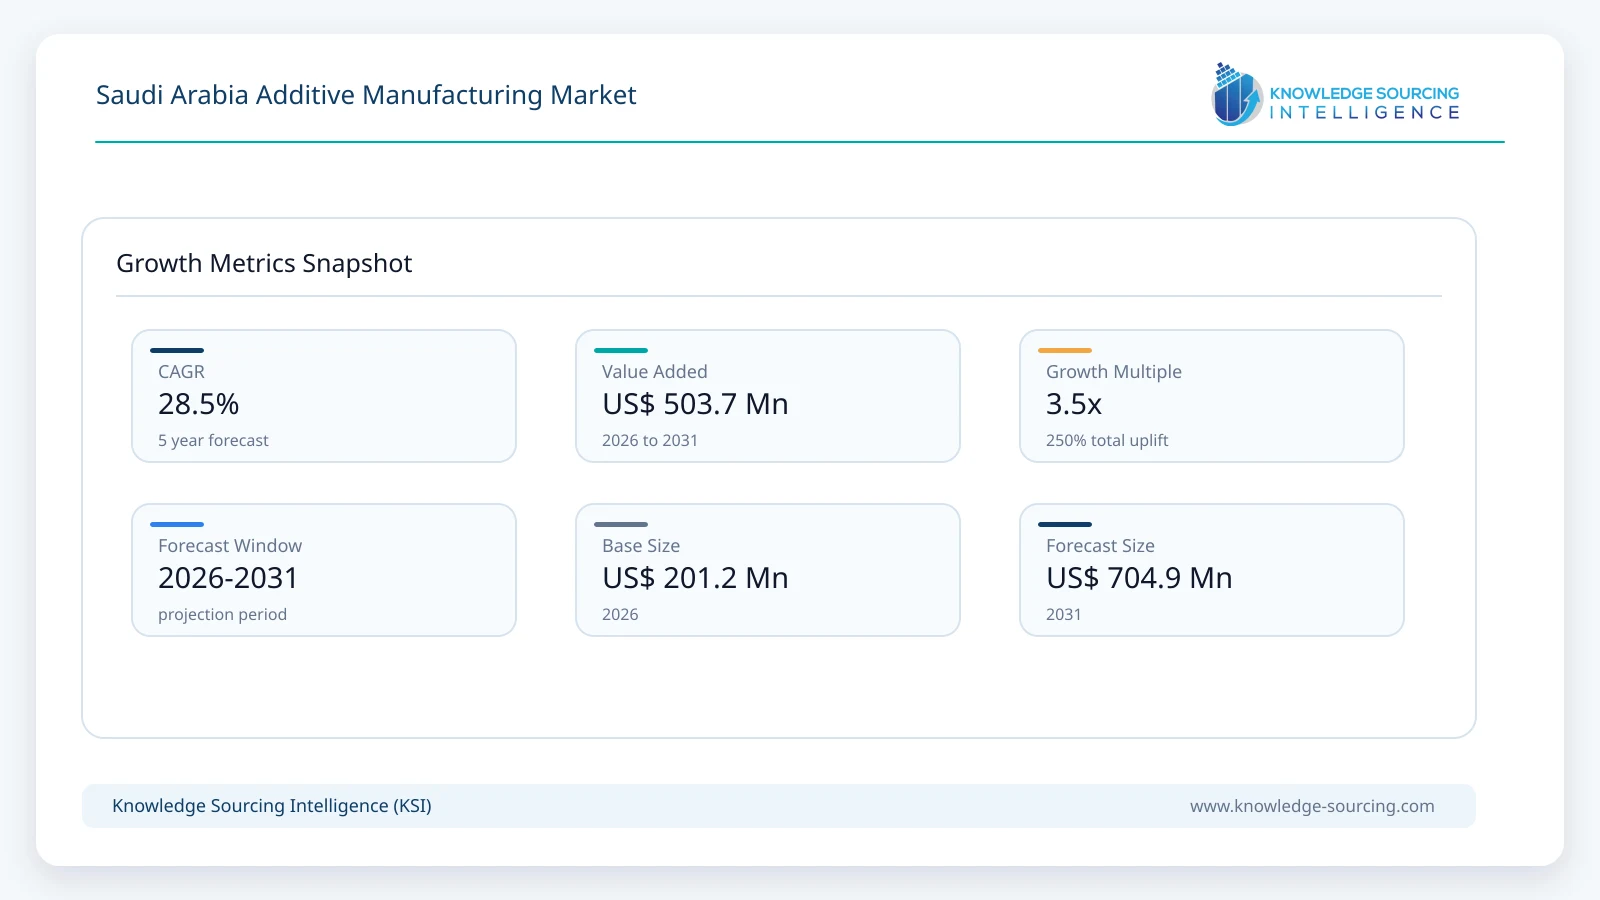
The Saudi Arabia Additive Manufacturing Market is forecast to grow at a CAGR of 28.5%, reaching USD 704.9 million in 2031 from USD 201.2 million in 2026.
Highlights:
- 1Hardware accounts for approximately 44% of Saudi Arabia additive manufacturing market value in 2026, supported by expanding in-country production capacity.
- 2Metals account for approximately 57% of additive manufacturing material revenue in 2026, led by energy, defense and industrial spare-part applications.
- 3Powder bed fusion accounts for approximately 39% of market value by technology in 2026, supported by industrial polymer and metal production.
- 4Oil & gas and energy account for approximately 32% of market demand in 2026, reflecting localized spare-part and digital-inventory programs.
- 5Aerospace and defense are expected to record the strongest end-user expansion through 2031 as military manufacturing localization accelerates.
Saudi Arabia is developing additive manufacturing as part of a broader advanced-manufacturing and localization strategy rather than treating 3D printing only as a prototyping technology. The Kingdom is building industrial capabilities around metal and polymer printing, reverse engineering, digital inventory, construction printing and medical applications. Government industrial policy explicitly includes 3D printing alongside artificial intelligence and the Internet of Things within the advanced-manufacturing technologies intended to improve productivity and strengthen domestic industrial capability. Saudi Aramco also identifies additive manufacturing as a tool for producing complex components and replacement parts closer to remote operating locations, while its iktva localization program supported the establishment of the Kingdom’s first additive manufacturing center.
The commercial market is increasingly anchored by local production infrastructure. NAMI, established by Dussur and 3D Systems and subsequently joined by Saudi Electricity Company as a strategic investor, provides industrial metal and polymer additive manufacturing, reverse engineering and digital-inventory capabilities. Immensa has also established a USD 15 million, 1,500-square-metre industrial additive manufacturing facility in Dammam with more than 30 specialized engineers and large-format metal laser-melting capability. These facilities are materially different from university laboratories or demonstration systems because they are designed to manufacture qualified components for energy, defense, petrochemical and other industrial customers.
The existing KSI market estimate remains appropriate for this update. The current page was published in 2026 and Search Console shows a significant ranking improvement, with average position moving from 28.2 to 10.7 across the two latest comparable 28-day periods. The more important issue is intent coverage. The page is already ranking near the first page for “Saudi Arabia metal additive manufacturing market,” making metal materials, industrial energy applications and localized production capability necessary parts of the public description and report structure.
Market Trends
• Industrial Additive Manufacturing Is Shifting Toward Localized Spare-Part Production
Saudi energy and industrial operators are increasingly using additive manufacturing to replace selected imported or obsolete components with locally produced parts. Saudi Electricity Company agreed in October 2025 to subscribe to a 30% stake in NAMI, with the partnership focused on digital inventory, reverse engineering and localized spare-part production. NAMI had already acquired 3D Systems metal and polymer platforms to support SEC applications including pump impellers, fuel burners, motor fans, heat sinks and heat exchangers. This model is commercially important because it combines digital warehousing with production on demand, reducing physical inventory and shortening supply timelines for low-volume critical parts.
• Defense Qualification Is Moving From Collaboration to Licensed Manufacturing
Defense has become one of the clearest production-scale growth areas. NAMI and Lockheed Martin agreed to qualify and additively manufacture aluminum components in Saudi Arabia for aerospace and defense applications, while NAMI received a military manufacturing license from the General Authority for Military Industries in 2026. The license allows regulated defense manufacturing and aligns additive manufacturing directly with the Kingdom’s objective of localizing more than 50% of military spending by 2030. The market opportunity therefore increasingly includes qualified metal components, process documentation and production services rather than only printer sales.
• Construction Printing Is Progressing Beyond Demonstration Projects
Large-format concrete printing is creating a separate application path from industrial metal and polymer systems. A Saudi Aramco case study presented in 2025 described a large 3D-printed building produced using a COBOD BOD2 printer and a concrete mix containing 99% locally sourced materials. The project reported approximately 50% lower construction time and 80% labor savings compared with conventional methods. Saudi developers and contractors are also using additive construction for multi-storey villas and other structures, supporting demand for large-format printers, concrete formulations, software and engineering services even though construction remains smaller than industrial manufacturing in current market value.
• Healthcare Is Building In-House Printing and Regulatory Test Environments
Healthcare adoption is broadening through hospital-based programs and public-sector innovation frameworks. King Faisal Specialist Hospital & Research Centre reported in April 2026 that its in-house 3D printing program was being used for patient-specific anatomical models and surgical planning, with operative-time reductions of up to 30% in selected cases. In July 2026, the Ministry of Health also identified 3D printing among the technologies eligible for its health innovation Sandbox. These developments support medical modeling, surgical guides and customized products while allowing clinical organizations to build design, imaging and quality-control expertise inside the Kingdom.
Segment Analysis
• By Component: Hardware
Hardware accounts for approximately 44% of market value in 2026 and remains the largest component segment. The share reflects the ongoing build-out of local industrial capacity, including metal powder-bed systems, polymer printers, large-format construction platforms and supporting post-processing equipment. NAMI operates 3D Systems metal and polymer platforms, while Immensa’s Dammam facility includes industrial metal laser-melting equipment. Hardware retains the largest near-term revenue pool, but its share is expected to moderate as materials, production services, software, qualification and maintenance create larger recurring revenue streams.
• By Material: Metals
Metals account for approximately 57% of material revenue in 2026, led by demand from oil & gas, power, aerospace and defense. Aluminum, stainless steel, nickel alloys and other engineering metals are suited to applications where localized production, complex geometry or replacement of obsolete parts can justify additive manufacturing costs. The Lockheed Martin and NAMI qualification program illustrates the increasing importance of aluminum for aerospace applications, while NAMI and Immensa are developing metal capabilities for energy and industrial components. Polymers remain important in prototyping, healthcare, fixtures and selected production applications, while concrete represents a distinct construction-material opportunity.
• By Technology: Powder Bed Fusion
Powder bed fusion accounts for approximately 39% of market value by technology in 2026. The category includes polymer selective laser sintering as well as metal laser powder-bed fusion and electron-beam systems used for higher-value industrial production. Saudi Arabia’s current localization programs favor these technologies because they support complex metal and polymer end-use parts with established industrial qualification pathways. Material extrusion and vat photopolymerization remain important for prototyping, healthcare and general-purpose applications, while directed energy deposition and binder jetting provide additional opportunities as the industrial ecosystem matures.
• By End-User: Oil & Gas and Energy
Oil & gas and energy account for approximately 32% of market demand in 2026 and represent the largest end-user value pool. Aramco has highlighted 3D printing as a way to simplify production of complex components and manufacture replacement parts closer to remote operations. NAMI’s collaboration with Saudi Electricity Company is building a digital inventory and localized production model for power-sector components, while Immensa’s Dammam center targets oil & gas, energy and petrochemical customers. This installed industrial base gives Saudi additive manufacturing a stronger spare-parts and maintenance orientation than many smaller country markets.
Market Drivers
• Industrial Localization and Digital Inventory
Vision 2030 and the National Industrial Strategy place strong emphasis on local manufacturing, supply-chain resilience and higher-value industrial activity. Additive manufacturing aligns with these objectives because selected parts can be digitized, reverse engineered and produced locally without dedicated tooling. The SEC investment in NAMI and the company’s five-year USD 26 million framework agreement with Modern Isotope Factory demonstrate that localization is progressing through commercial contracts rather than policy statements alone. Digital inventory is especially relevant for low-volume, long-lead and obsolete components across energy and infrastructure.
• Defense and Aerospace Localization
Saudi Arabia’s goal of localizing more than half of military spending by 2030 creates demand for qualified domestic manufacturing processes. NAMI’s GAMI manufacturing license and collaboration with Lockheed Martin provide a route for additive manufacturing to participate in this localization effort. Aerospace and defense applications also support higher-value metal systems, specialist powders, inspection equipment, process qualification and post-processing, creating a broader commercial ecosystem around each qualified component.
• Expansion of Advanced Manufacturing Capacity
The Kingdom is attracting private and state-backed investment in industrial additive manufacturing infrastructure. Immensa’s USD 15 million Dammam center, NAMI’s production facility and Aramco-supported additive manufacturing activity increase local machine capacity while developing application engineering and operator skills. Saudi industrial policy identifies 3D printing as part of advanced manufacturing alongside automation, AI and IoT, improving the likelihood that additive systems are integrated into broader digital production environments rather than deployed as isolated tools.
Market Restraints
• Qualification, Certification and Material Traceability
The fastest-growing Saudi applications are also among the most difficult to qualify. Defense, aerospace, power and medical components require validated materials, controlled process parameters, inspection and repeatability before they can replace conventional parts. Qualification can be application specific and may require extensive testing even when the underlying printer is already certified or proven elsewhere. This increases engineering cost and slows the conversion of a digital spare-part catalogue into approved production parts.
• High Capital and Skills Requirements
Industrial metal additive manufacturing requires more than the printer itself. Powder handling, inert-gas systems, heat treatment, machining, inspection, software and trained engineers can materially increase total investment. Saudi Arabia is expanding local engineering capability, but design-for-additive-manufacturing, process optimization and quality assurance skills remain specialized. Service bureaus and joint ventures partially address this constraint by allowing industrial users to qualify applications before investing in complete in-house production lines.
Competitive Landscape
Saudi Arabia’s competitive structure is led by local industrial service providers supported by international technology partners. NAMI is strategically important because it combines local ownership and industrial-policy alignment with 3D Systems equipment, materials and application expertise. Saudi Electricity Company’s planned 30% investment further connects the company with a large domestic energy customer. Immensa operates an industrial-scale Dammam facility focused on digital inventory and energy-sector spare parts. International suppliers including 3D Systems, EOS, HP, Stratasys, Materialise and Nikon SLM Solutions participate through equipment, materials, software or application support, while COBOD is relevant to construction printing. Competition increasingly depends on local engineering support, qualified application libraries, production service capability and relationships with major Saudi industrial customers rather than printer specifications alone.
Recent Developments
August 2026: NAMI announced that it had obtained a military manufacturing license from Saudi Arabia’s General Authority for Military Industries, enabling production of military equipment and defense components.
July 2026: Saudi Arabia’s Ministry of Health identified 3D printing among the technologies supported through its health innovation Sandbox initiative.
June 2026: NAMI signed a strategic framework agreement with MBK Global covering advanced manufacturing, AI, automation, digital twins and Industry 4.0 solutions.
April 2026: King Faisal Specialist Hospital & Research Centre reported that its in-house 3D printing program was supporting patient-specific surgical planning and reducing operative time by up to 30% in selected procedures.
October 2025: Saudi Electricity Company agreed to subscribe to a 30% stake in NAMI; 3D Systems also disclosed NAMI’s Lockheed Martin collaboration and a five-year USD 26 million framework agreement with Modern Isotope Factory.
Market Outlook
Saudi Arabia’s additive manufacturing market is expected to remain one of the faster-growing country markets through 2031 because the technology is closely aligned with national localization priorities and large domestic energy, defense and infrastructure sectors. Near-term growth is led by industrial hardware, metal materials and powder-bed-fusion systems, while services, digital inventory and application engineering gain a larger share as installed capacity expands. Oil & gas and energy remain the largest end-user value pool in 2026, while aerospace and defense are expected to record stronger growth as qualified production scales under GAMI and Vision 2030 localization programs. Construction and healthcare broaden the application base but follow different equipment, materials and regulatory pathways. The market is forecast to increase from USD 201.2 million in 2026 to USD 704.9 million by 2031, representing a CAGR of 28.5%.
Saudi Arabia Additive Manufacturing Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 201.2 million |
| Total Market Size in 2031 | USD 704.9 million |
| Forecast Unit | Million |
| Growth Rate | 28.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Material, Technology, End-User Industry |
| Companies |
|
Market Segmentation
By Component
Hardware
Software
Services
Material
By Material
Metals
Polymers
Concrete and Construction Materials
Other Materials
By Technology
Powder Bed Fusion
Selective Laser Sintering
Laser Powder Bed Fusion
Electron Beam Melting
Material Extrusion / Fused Deposition Modeling
Vat Photopolymerization / Stereolithography
Directed Energy Deposition
Binder Jetting
Others
By End-User Industry
Oil & Gas and Energy
Aerospace and Defense
Health Care
Construction
Automotive
Consumer and Other Industries
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Industrial Localization and Digital Inventory
3.1.2. Defense and Aerospace Localization
3.1.3. Expansion of Advanced Manufacturing Capacity
3.2. Market Restraints
3.2.1. Qualification, Certification and Material Traceability
3.2.2. High Capital and Skills Requirements
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Industrial Metal Additive Manufacturing
4.2. Polymer Additive Manufacturing
4.3. Digital Inventory and Reverse Engineering
4.4. Large-Format Construction Printing
4.5. Medical 3D Printing
5. SAUDI ARABIA ADDITIVE MANUFACTURING MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
5.5. Material
6. SAUDI ARABIA ADDITIVE MANUFACTURING MARKET BY MATERIAL
6.1. Introduction
6.2. Metals
6.3. Polymers
6.4. Concrete and Construction Materials
6.5. Other Materials
7. SAUDI ARABIA ADDITIVE MANUFACTURING MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Powder Bed Fusion
7.2.1. Selective Laser Sintering
7.2.2. Laser Powder Bed Fusion
7.2.3. Electron Beam Melting
7.3. Material Extrusion / Fused Deposition Modeling
7.4. Vat Photopolymerization / Stereolithography
7.5. Directed Energy Deposition
7.6. Binder Jetting
7.7. Others
8. SAUDI ARABIA ADDITIVE MANUFACTURING MARKET BY END-USER INDUSTRY
8.1. Introduction
8.2. Oil & Gas and Energy
8.3. Aerospace and Defense
8.4. Health Care
8.5. Construction
8.6. Automotive
8.7. Consumer and Other Industries
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Local Industrial Manufacturing Capacity
9.3. Metal versus Polymer Technology Positioning
9.4. Digital Inventory and Spare-Part Capabilities
9.5. Defense and Energy Qualification Capabilities
9.6. Partnerships, Investments and Collaborations
9.7. Competitive Dashboard
10. COMPANY PROFILES
10.1. National Innovation Industrial Company (NAMI)
10.2. Immensa Technology Labs
10.4. EOS GmbH
10.5. HP Inc.
10.6. Stratasys Ltd.
10.7. Materialise NV
10.8. Nikon SLM Solutions AG
10.9. COBOD International A/S
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Market Definition and Inclusion Criteria
11.5. Research Methodology
Navigate
Trusted by the world's leading organizations











