
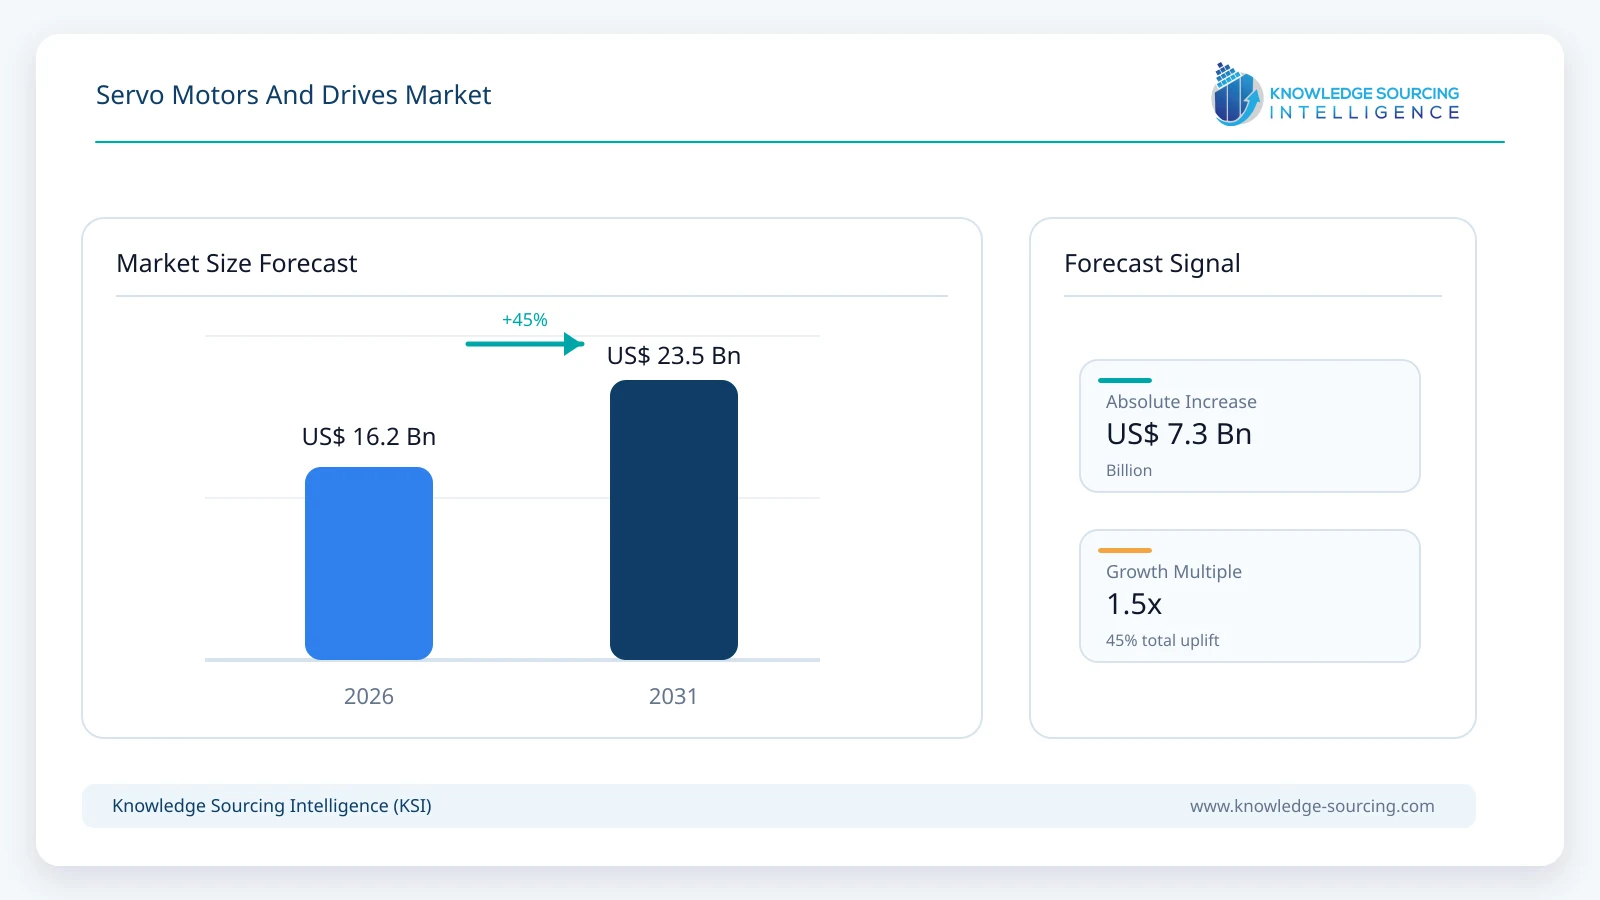
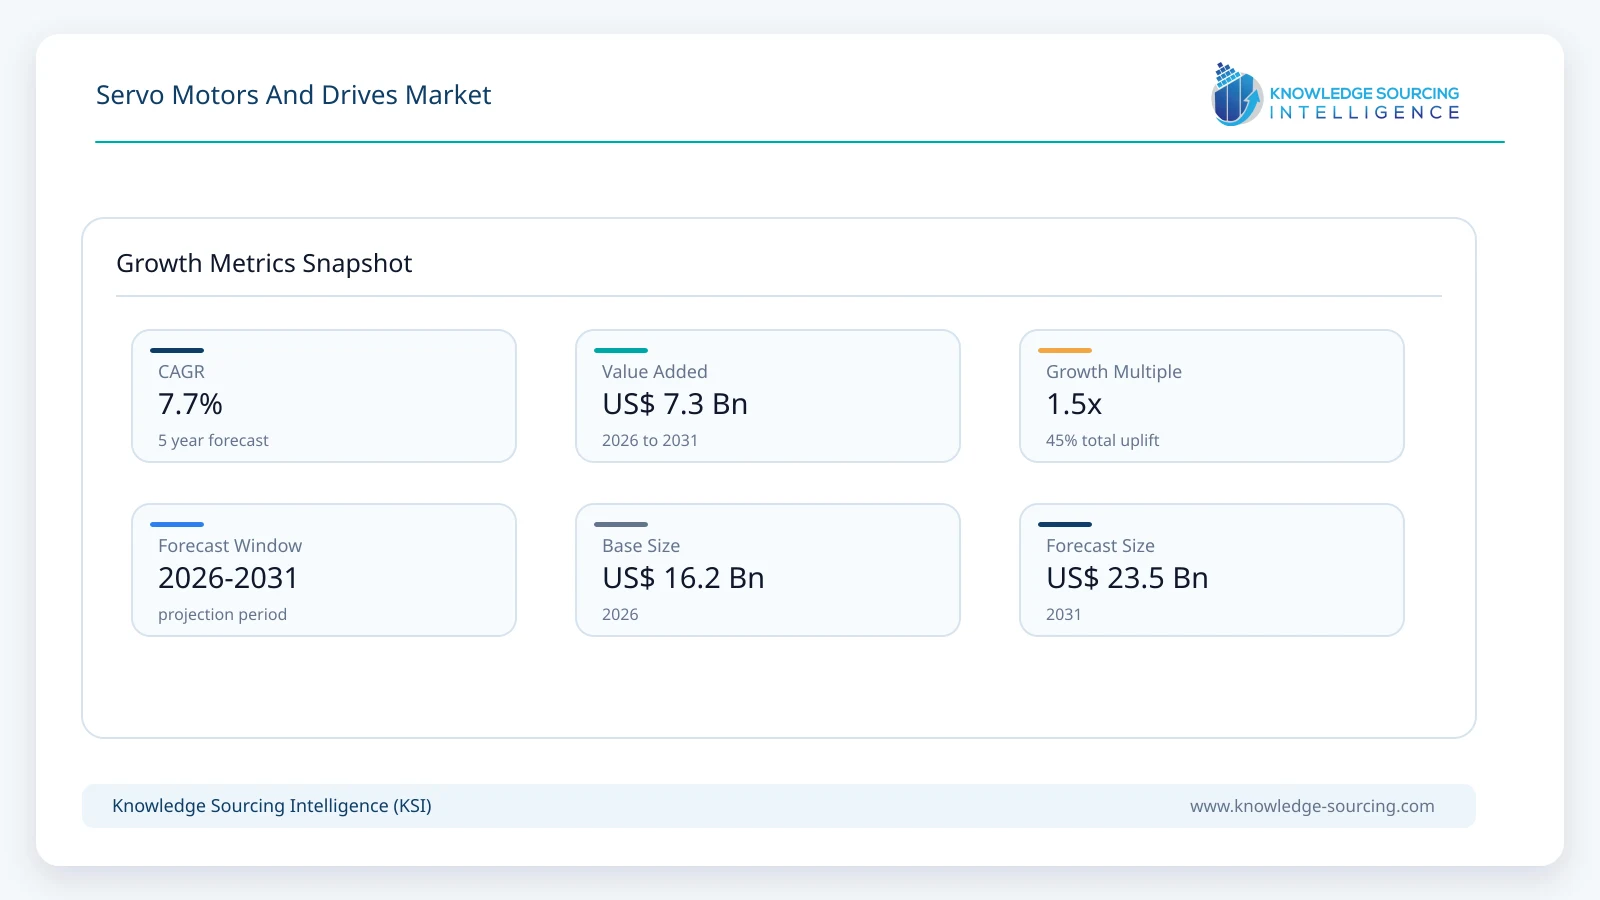
The global servo motors and drives market is estimated at USD 16.20 billion in 2026 and is projected to reach USD 23.50 billion by 2031, expanding at a CAGR of approximately 7.7% over the forecast period.
Highlights:
- 1Servo motors account for approximately 57% of global servo-system revenue in 2026.
- 2AC servo systems account for approximately 89% of market value in 2026.
- 3Robotics applications generate about USD 4.30 billion of global servo demand in 2026.
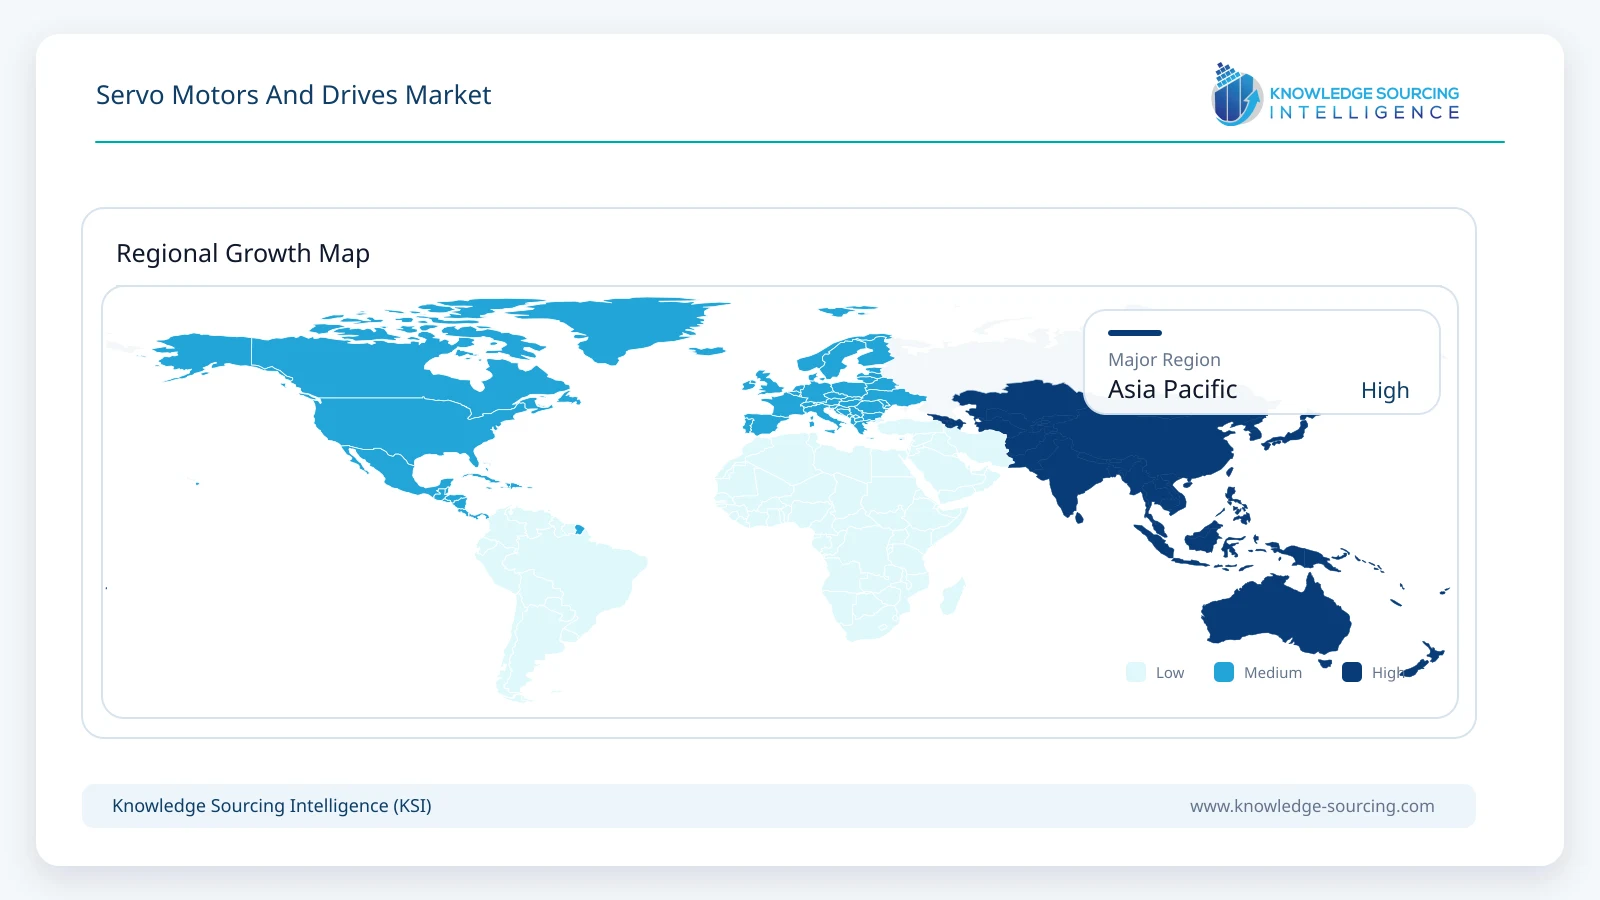
- 4Asia Pacific accounts for approximately 52% of global servo motors and drives revenue in 2026.
- 5Industrial Ethernet, integrated safety and high-resolution encoders are becoming standard selection criteria.
- 6Cabinet-free and distributed drive architectures are reducing wiring, footprint and machine commissioning time.
Servo systems are differentiated from general-purpose motors and variable-frequency drives by closed-loop control and the ability to respond rapidly to position, speed and torque commands. A typical system combines a permanent-magnet servo motor, encoder or resolver, servo amplifier or drive, controller, communication network and engineering software. Rotary servo motors dominate industrial installations, but linear and direct-drive motors are important where machines require very high acceleration, low backlash or direct load coupling. Drive selection is increasingly tied to network architecture, functional-safety requirements, regenerative energy handling, encoder resolution and the software environment used to configure the machine.
Leading suppliers increasingly sell the servo as part of a wider motion platform. Mitsubishi Electric positions MELSERVO-J5 around 200 V and 400 V servo amplifiers, 26-bit batteryless absolute encoders and support for CC-Link IE TSN. Yaskawa combines Sigma-X motors and SERVOPACK amplifiers with MECHATROLINK and EtherCAT options, while Siemens integrates SINAMICS servo drives with SIMOTICS motors and digital commissioning tools. Rockwell Automation, Bosch Rexroth, Beckhoff, Schneider Electric, OMRON, Delta Electronics, Panasonic Industry and Kollmorgen similarly link drives with controllers, safety and industrial networks. This system-level approach raises switching costs for machine builders because motion performance depends on the interaction between motor, drive, network and software rather than a single component.
Market Trends
Networked motion control is moving toward faster deterministic Ethernet and software-defined commissioning
Machine builders are replacing isolated pulse-train servo axes with deterministic industrial-Ethernet architectures that synchronize motion, safety and machine data. EtherCAT, EtherNet/IP, PROFINET, CC-Link IE TSN and MECHATROLINK are increasingly used to coordinate multi-axis systems and reduce hard wiring. Yaskawa expanded Sigma-X with 400 V models supporting EtherCAT and MECHATROLINK interfaces, while Mitsubishi Electric positions MELSERVO-J5 around CC-Link IE TSN and other high-speed networks. Siemens has also expanded SINAMICS S210 functionality with EtherNet/IP support and DriveSim Advanced for virtual commissioning. The commercial effect is a shift in purchasing criteria from motor torque and speed alone toward network compatibility, engineering software, diagnostics and lifecycle support.
Digital twins and self-tuning are reducing the engineering burden of higher-axis-count machines
Servo systems are becoming easier to commission even as machinery grows more complex. Auto-tuning, vibration suppression, load-inertia estimation, condition monitoring and machine simulation are moving into standard motion platforms. OMRON demonstrated integration of Sysmac Studio with NVIDIA Omniverse in 2025 to create physically accurate digital-twin environments using controllers, servo motors, sensors and safety devices. Yaskawa expanded its MPX1000 machine-controller platform in April 2026 with an architecture capable of synchronized control of up to 640 servomotors. These developments matter because semiconductor tools, battery lines, electronics assembly and packaging machines can contain dozens or hundreds of coordinated axes, making engineering hours and troubleshooting time a material part of machine cost.
Market Drivers
Factory automation and industrial robotics sustain the largest recurring demand pool
Industrial robots are one of the most visible demand sources for servo motors and drives because each articulated robot typically contains multiple high-performance axes, while adjacent automation equipment such as gantries, pick-and-place systems and autonomous material-handling equipment adds further motion demand. The International Federation of Robotics reported 542,076 industrial robot installations in 2024, the second-highest level on record, and an installed base of approximately 4.66 million units. Asia represented 74% of new robot deployments. Even when annual robot installations flatten, the installed base creates replacement, retrofit and spare-parts demand, while new automation categories expand the number of servo-controlled axes used per production line.
Electronics, semiconductor and battery manufacturing are raising precision and multi-axis requirements
Semiconductor and advanced-electronics equipment is a high-value servo application because wafer handling, lithography support, inspection, die bonding, packaging, component placement and precision stages require tight positioning and low settling time. SEMI forecast global semiconductor-manufacturing-equipment sales to reach USD 165.9 billion in 2026, up 23.2% year on year, supported by leading-edge logic, high-bandwidth memory, advanced packaging and AI-related investment. Yaskawa specifically identifies semiconductor and LCD manufacturing equipment, electronic-component mounters and secondary-cell production equipment among the target applications for its newer motion platforms. Battery-electrode coating, winding, stacking and inspection lines add another fast-growing group of synchronized axes, creating demand for compact drives, regenerative capability and high-speed network control.
Market Restraint
Cyclical machinery investment, integration complexity and platform lock-in can delay servo upgrades
Servo demand is linked to capital expenditure in machinery-intensive industries, so orders can weaken quickly when automotive, electronics, machine-tool or general-manufacturing investment slows. High-performance servo systems also carry a higher installed cost than simpler induction-motor and drive combinations because encoders, cables, controllers, safety functions and engineering software must be configured as an integrated system. Retrofitting an established machine is further complicated by mechanical dimensions, encoder interfaces, network protocols and validated motion profiles. As a result, machine builders often remain with an incumbent servo platform across several equipment generations, while end users may postpone upgrades until a broader machine redesign provides enough productivity or maintenance benefit to justify the change.
Servo Motors And Drives Market Segment Analysis
By Component
Servo Motors
Servo motors are projected to generate approximately USD 13.1 billion in market revenue by 2031. Their scale reflects the physical motor requirement on every controlled axis across robots, machine tools, packaging equipment, electronics assembly and process machinery. Permanent-magnet rotary servomotors remain the dominant form because they combine power density, dynamic response and broad availability, while linear and direct-drive motors serve specialized precision applications. Servo drives are expected to grow somewhat faster than motors as machines add more sophisticated safety, communication, regeneration and diagnostic functions, increasing electronic value per axis even when motor unit growth is moderate.
By Type
AC Servo Systems
AC servo systems are projected to reach approximately USD 21.1 billion in market value by 2031. They dominate new industrial installations because brushless permanent-magnet motors provide high efficiency, low maintenance and strong torque density across a wide power range. Modern AC servo platforms also support high-resolution absolute encoders, networked safety and regenerative operation. DC servo systems continue to serve selected legacy equipment, mobile systems, laboratory devices and lower-voltage applications, but their share is declining as compact AC and low-voltage brushless servo solutions become easier to integrate.
By Application
Robotics
Robotics applications are projected to grow at approximately 8.8% annually between 2026 and 2031. Demand comes from articulated industrial robots, SCARA robots, delta robots, collaborative robots, gantries and automated handling systems, all of which depend on tightly synchronized motion. The segment benefits from the large installed robot base and the spread of automation beyond automotive into electronics, metalworking, logistics, food processing and general industry. Semiconductor and electronics manufacturing is expected to grow faster from a smaller base because AI-related fab investment and advanced packaging are driving unusually strong equipment spending, but robotics remains the larger identifiable servo application across the forecast period.
By Geography
Asia Pacific
Asia Pacific is projected to reach approximately USD 12.8 billion in servo motors and drives revenue by 2031. The region combines the world's largest industrial-robot market with major semiconductor, electronics, battery, machine-tool and general automation supply chains.
China accounted for 54% of global industrial-robot deployments in 2024, while Japan, South Korea and Taiwan remain important centers for robotics, servo manufacturing, semiconductor equipment and electronics machinery. India is also increasing automation investment from a lower base. North America benefits from reshoring, semiconductor fabs, warehouse automation and advanced manufacturing, while Europe maintains a strong machine-building base and high adoption of networked safety and energy-efficient motion systems.
Competitive Environment
Competition is led by automation suppliers that can combine servo motors, amplifiers, controllers, industrial networks, safety and engineering software in a single architecture. Yaskawa and Mitsubishi Electric hold strong positions in Asian machinery and robotics, while Siemens, Bosch Rexroth, Beckhoff and Schneider Electric compete through integrated European machine-automation platforms. Rockwell Automation is important in North American integrated motion, and Delta Electronics, Panasonic Industry, OMRON, Kollmorgen, Parker Hannifin, Fuji Electric, Oriental Motor, Nidec, Moog and Lenze serve combinations of OEM, specialty-motion and regional automation markets.
Performance differentiation is increasingly software and architecture driven. Bosch Rexroth states that its ctrlX DRIVE cabinet-free platform can reduce space and cabling by up to 90%, while Yaskawa adds sensing and condition-monitoring functions to Sigma-X and supports large synchronized systems through MPX1000 controllers. Mitsubishi Electric combines high-resolution feedback with TSN-capable networking, and OMRON is linking servo engineering to digital-twin workflows. Product lifecycles are also accelerating: Mitsubishi Electric announced 2026 discontinuation plans for selected MR-J4 and MR-JN servo-amplifier families as customers transition toward newer platforms. This favors suppliers that can provide migration paths and long-term support in addition to headline motion specifications.
Recent Developments
August 2026: Mitsubishi Electric published production-discontinuation notices for selected MELSERVO-J4 field-network models and the MR-JN servo-amplifier series, highlighting the ongoing transition toward newer servo platforms.
April 2026: Yaskawa expanded its MPX1000 machine-controller lineup with the MPX1010 and SVF-12 motion unit, enabling synchronized control of up to 640 servomotors for large multi-axis equipment.
May 2025: Yaskawa expanded its Sigma-X AC servo-drive family with 400 V input models covering servo motors from 200 W to 15 kW and interfaces including EtherCAT and MECHATROLINK.
March 2025: OMRON demonstrated integration of Sysmac Studio with NVIDIA Omniverse to support physically accurate digital-twin development using controllers, servo motors, sensors and safety devices.
Early 2025: Bosch Rexroth introduced the ctrlX DRIVE cabinet-free IP65 servo-drive architecture, targeting lower wiring, smaller control cabinets and more modular machine design.
Servo Motors And Drives Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 16.20 billion |
| Total Market Size in 2031 | USD 23.50 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Type, Application, Geography |
| Companies |
|
Market Segmentation
BY COMPONENT
Servo Motors
Servo Drives
BY TYPE
AC Servo Systems
DC Servo Systems
BY APPLICATION
Robotics and Material Handling
Semiconductor and Electronics Manufacturing
Machine Tools and Metalworking
Packaging and Processing Machinery
Automotive and Battery Manufacturing
Printing, Textiles and Other Applications
BY GEOGRAPHY
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
South Korea
India
Taiwan
Southeast Asia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Factory Automation and Industrial Robotics Sustain the Largest Recurring Demand Pool
3.1.2. Electronics, Semiconductor and Battery Manufacturing Raise Precision and Multi-Axis Requirements
3.2. Market Restraint
3.2.1. Cyclical Machinery Investment, Integration Complexity and Platform Lock-In Can Delay Servo Upgrades
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Deterministic Industrial Ethernet and TSN Motion Networks
4.2. Integrated Functional Safety and Safe Motion
4.3. Cabinet-Free and Distributed Servo Drives
4.4. Digital Twins, Auto-Tuning and Predictive Diagnostics
5. SERVO MOTORS AND DRIVES MARKET BY COMPONENT
5.1. Introduction
5.2. Servo Motors
5.3. Servo Drives
6. SERVO MOTORS AND DRIVES MARKET BY TYPE
6.1. Introduction
6.2. AC Servo Systems
6.3. DC Servo Systems
7. SERVO MOTORS AND DRIVES MARKET BY APPLICATION
7.1. Introduction
7.2. Robotics and Material Handling
7.3. Semiconductor and Electronics Manufacturing
7.4. Machine Tools and Metalworking
7.5. Packaging and Processing Machinery
7.6. Automotive and Battery Manufacturing
7.7. Printing, Textiles and Other Applications
8. SERVO MOTORS AND DRIVES MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. South Korea
8.6.4. India
8.6.5. Taiwan
8.6.6. Southeast Asia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Yaskawa Electric Corporation
10.2. Mitsubishi Electric Corporation
10.3. Siemens AG
10.4. Rockwell Automation, Inc.
10.5. Bosch Rexroth AG
10.6. ABB Ltd.
10.7. Schneider Electric SE
10.8. Delta Electronics, Inc.
10.9. Panasonic Industry Co., Ltd.
10.10. OMRON Corporation
10.11. Kollmorgen Corporation
10.12. Beckhoff Automation GmbH & Co. KG
10.13. Parker Hannifin Corporation
10.14. Fuji Electric Co., Ltd.
10.15. Oriental Motor Co., Ltd.
10.16. Nidec Corporation
10.17. Moog Inc.
10.18. Lenze SE
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











