
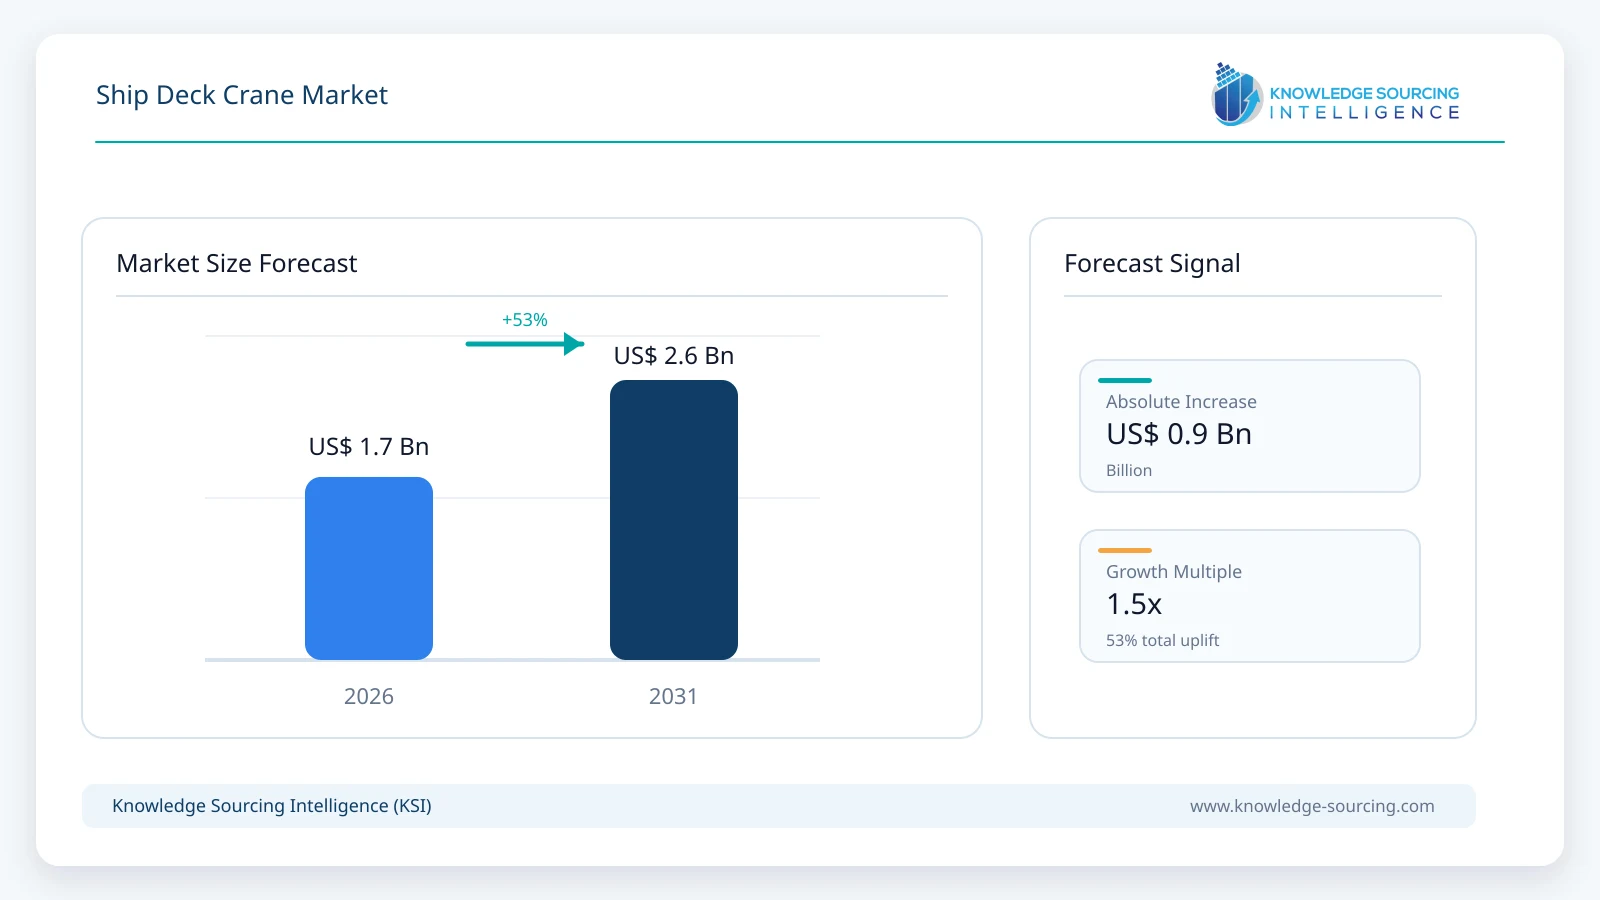
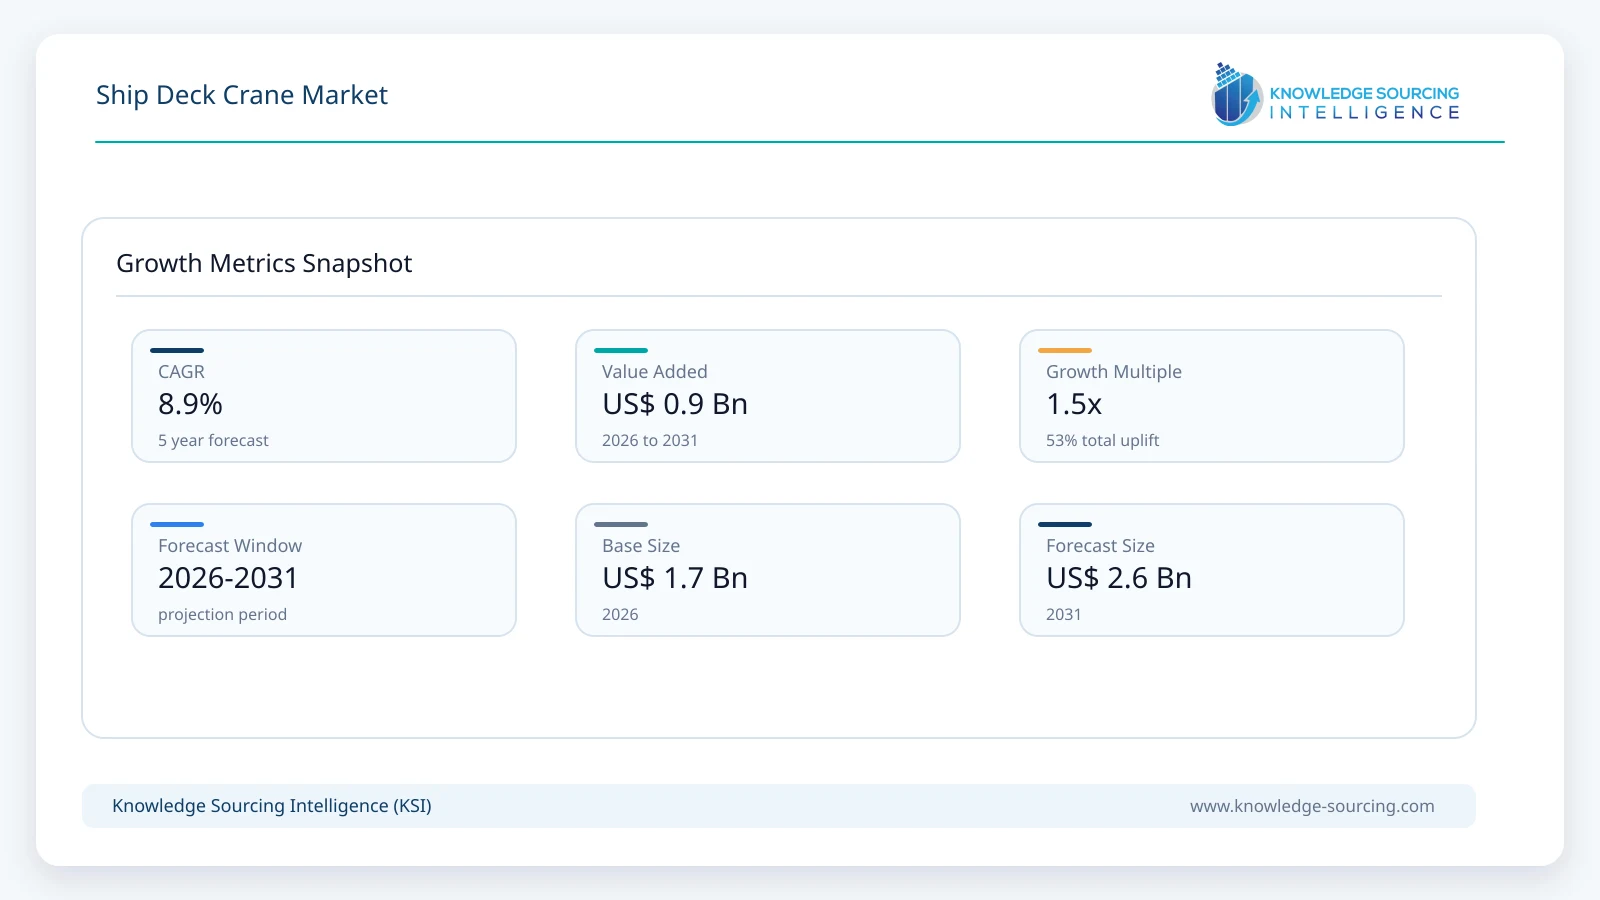
The Global Ship Deck Crane market is forecast to grow at a CAGR of 8.9%, reaching USD 2.60 billion in 2031 from USD 1.70 billion in 2026.
Highlights:
- 1Knuckle-boom and foldable cranes account for approximately 34% of global revenue in 2026.
- 2Offshore support and construction vessel demand is projected to grow at about 12.0% annually through 2031.
- 3Asia Pacific contributes approximately 49% of global ship deck crane revenue in 2026.
- 4Fleet renewal is sustaining cargo-crane demand even as seaborne trade volume grows at a moderate pace.
- 5Active heave compensation and electric drives are raising equipment value on offshore and special-purpose vessels.
- 6China, South Korea and Japan remain central to OEM demand because of their dominant shipbuilding positions.
Market Overview
Ship deck cranes are installed directly on vessels to handle cargo, stores, equipment, boats, subsea tools, and other loads during port or offshore operations. The live KSI page correctly identifies cargo handling and Asia Pacific shipbuilding as core demand factors, but the commercial market is broader than conventional geared cargo ships. Modern deck-crane demand spans multipurpose and heavy-lift vessels, offshore support vessels, construction and cable-laying vessels, research ships, naval platforms, dredgers, workboats, fishing vessels and wind-service fleets. Crane specifications vary significantly by vessel mission, from relatively standardized hydraulic cargo cranes to highly engineered active-heave-compensated systems for subsea lifting.
The supply side is also becoming more technology- and service-intensive. Mitsubishi Heavy Industries Machinery Systems continues to offer standard and heavy-duty cargo deck cranes from 30-tonne to 100-tonne classes with data logging and lifecycle-support functions. MacGregor and Liebherr are supplying 165-tonne, 250-tonne and 400-tonne-class cranes for offshore construction and heavy-lift vessels, while Heila, PALFINGER MARINE, KenzFigee and other specialized manufacturers compete in compact knuckle-boom, telescopic and offshore crane applications. The result is a market where unit volumes remain important, but revenue growth is increasingly influenced by crane complexity, motion compensation, certification, digital monitoring and long-term service contracts.
Market Trends
Electric drives and lower-energy crane architectures are moving into mainstream marine lifting
Marine crane manufacturers are increasingly offering electric or electro-hydraulic drive systems to reduce onboard fuel consumption, simplify integration with hybrid vessels and improve operational control. MacGregor states that electric drives are available across its merchant crane portfolio, while KenzFigee offers fully electric offshore and special-purpose cranes and Mitsubishi integrates data logging and upgrade functions into its S-Series deck cranes. The transition is particularly relevant for battery-hybrid ferries, research vessels, offshore wind vessels and other newbuilds designed around lower-emission auxiliary systems. Hydraulic cranes remain widely used because of their robustness and power density, but the competitive gap is narrowing as electric actuation and power-management technologies improve.
Active heave compensation and digital load management are increasing crane value per vessel
Offshore and subsea lifting requires the crane to compensate for vessel motion while maintaining precise load control, making active heave compensation a major source of product differentiation. MacGregor secured multiple 165-tonne and 400-tonne AHC crane orders during 2026, while Liebherr, SMST, KenzFigee and other suppliers maintain motion-compensated systems for construction, subsea and wind-service vessels. Digital monitoring is developing in parallel. Operators increasingly use load data, operating histories, remote diagnostics and condition-based maintenance to improve uptime and certification planning. These functions raise lifecycle service revenue and create stronger supplier relationships than conventional one-time crane sales.
Market Drivers
Fleet renewal and concentrated Asian shipbuilding support original-equipment crane demand
The global fleet continues to age even as new vessel deliveries remain concentrated in a small number of shipbuilding economies. UNCTAD reports around 116,000 merchant vessels of at least 100 gross tons at the start of 2026, with China, the Republic of Korea and Japan responsible for 91% of ships completed in 2025 by gross tonnage. Fleet renewal creates deck-crane demand where new geared bulk carriers, multipurpose ships, heavy-lift vessels and special-purpose vessels require factory-installed lifting systems. The concentration of shipbuilding also benefits crane suppliers with established production, licensing or service relationships in Asian yards. Mitsubishi, MacGregor, Liebherr and several European specialist manufacturers maintain strong links with Chinese, Korean and Japanese shipbuilders, making regional presence an important competitive advantage.
Offshore wind, subsea construction and research-vessel investment are increasing high-specification crane demand
Special-purpose vessels require materially higher-value lifting systems than conventional merchant ships because cranes must operate safely in dynamic sea states, handle subsea equipment or support complex offshore construction. During 2026, MacGregor secured a 400-tonne AHC crane for a floating wind farm construction vessel, multiple 165-tonne AHC crane orders for offshore construction vessels, and deck-crane packages for four new research vessels. Liebherr also secured 250-tonne heavy-lift ship-crane orders and continued offshore crane deliveries. These projects demonstrate how offshore wind, subsea construction, cable laying, ocean research and specialized project-cargo transport are increasing average crane value even though total vessel numbers in these categories are much smaller than the merchant fleet.
Market Restraint
Project-specific engineering and shipbuilding cycles create uneven order timing
Deck-crane revenue is tied closely to vessel construction schedules, yard capacity and individual newbuild programs. Large offshore and heavy-lift cranes can require extensive engineering, class approval, vessel-interface design and long manufacturing lead times, making revenue recognition uneven and exposing suppliers to project postponements. Merchant cargo-crane demand is also cyclical because shipowners can defer fleet renewal when freight markets weaken or fuel and regulatory uncertainty makes vessel specifications difficult to finalize. Suppliers therefore need a balanced mix of new equipment, retrofit, spare parts and service revenue to reduce dependence on large newbuild orders. MacGregor's current strategy explicitly emphasizes lifecycle service growth alongside equipment sales, illustrating the importance of recurring revenue in managing this cyclicality.
Segment Analysis
By Design - Knuckle-Boom and Foldable Cranes
Knuckle-boom and foldable cranes combine compact stowage with flexible outreach, making them suitable for offshore support vessels, workboats, research ships, fishing vessels and other decks where usable space is limited. Heila, PALFINGER MARINE, KenzFigee, SMST, MELCAL and Appleton Marine all maintain products in this design family, while larger AHC variants are used in subsea and construction work. The segment is projected to reach approximately USD 0.91 billion by 2031, supported by the shift toward multifunctional vessels that require a crane to handle stores, tools, boats or subsea equipment within a limited deck footprint. Stiff-boom and standard cargo cranes remain important on merchant vessels, while heavy-lift and lattice configurations serve narrower but higher-value project cargo and offshore applications.
By Vessel/Application - Offshore Support and Construction Vessels
Offshore support and construction vessels account for approximately 27% of global ship deck crane revenue in 2026. Their revenue share is substantially higher than their share of vessel numbers because these ships use larger and more technically complex cranes with active heave compensation, deepwater winches, specialized control systems and higher certification requirements. Offshore wind construction, subsea inspection and intervention, cable laying and field development all support demand for these systems. Merchant cargo and bulk vessels continue to form the largest installed-base opportunity, particularly for standardized cargo cranes, but offshore vessels contribute a disproportionate share of incremental market value because each crane package can be significantly more expensive.
By Geography - Asia Pacific
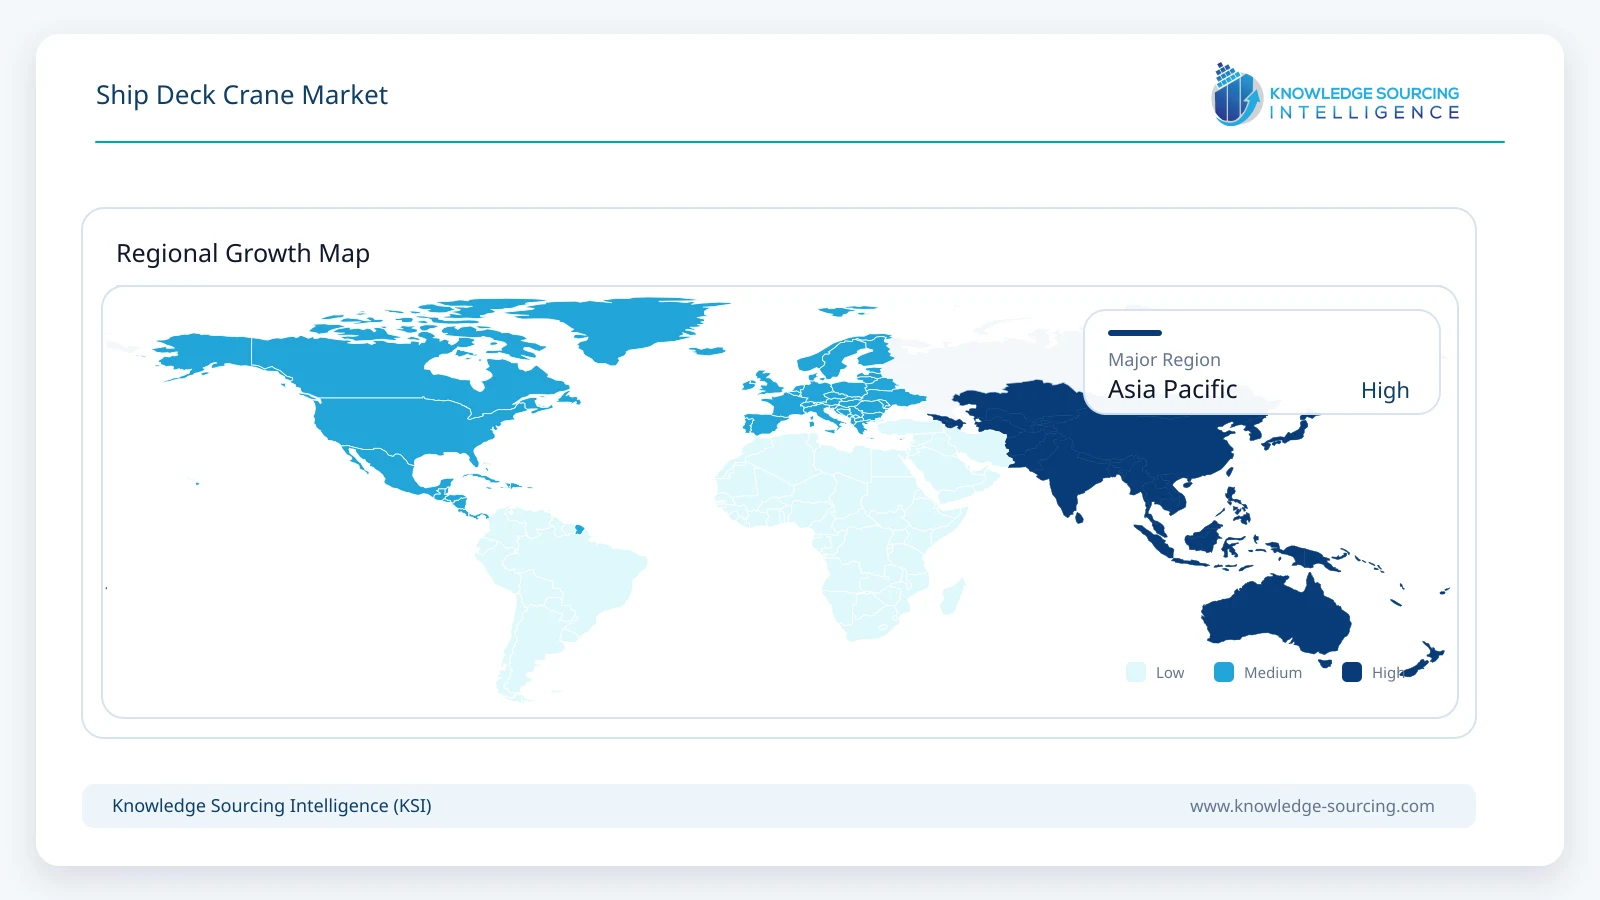
Asia Pacific is projected to generate approximately USD 1.31 billion in ship deck crane revenue by 2031. The region's position reflects its dominant shipbuilding base, led by China, the Republic of Korea and Japan, together with growing offshore and research-vessel construction in China, India and Southeast Asia. UNCTAD reports that the three leading Northeast Asian shipbuilding economies accounted for 91% of ships completed in 2025 by gross tonnage, while OECD analysis shows China alone delivered more than half of global shipbuilding output measured in compensated gross tonnage during 2025. Europe retains strong value positions in offshore, heavy-lift and specialized vessel equipment through suppliers headquartered in Germany, Norway, Finland, the Netherlands, Austria and Italy.
Competitive Environment
The market is fragmented by crane class but concentrated among established suppliers in high-specification marine and offshore applications. MacGregor, Liebherr and PALFINGER MARINE compete across broad ship and offshore crane portfolios, while Mitsubishi Heavy Industries Machinery Systems has a strong position in merchant cargo deck cranes. Heila, KenzFigee, Huisman, SMST and MELCAL focus heavily on engineered marine, offshore and subsea applications. Regional suppliers and specialist manufacturers remain important in workboats, fishing vessels, naval vessels and lower-capacity deck cranes.
Competitive advantage depends on more than lifting capacity. Shipyards and owners evaluate equipment weight, deck footprint, corrosion resistance, power consumption, class compliance, motion compensation, spare-parts availability and global service support. Suppliers with installed fleets can generate recurring service and modernization revenue over decades, while digital diagnostics and condition monitoring are strengthening lifecycle relationships. The premium end of the market therefore favors manufacturers with proven vessel references and global support, whereas standardized lower-capacity cranes face stronger price competition from regional Asian producers.
Recent Developments
September 2026: MacGregor secured orders to supply deck cranes, handling systems and deck machinery for four new oceanographic research vessels being built in Spain and India.
August 2026: MacGregor won an order for a 165-tonne active-heave-compensated crane for a Jan De Nul Ulstein SX121 newbuild under construction at China Merchants Heavy Industry.
April 2026: MacGregor received a repeat order for its 165-tonne AHC crane for a construction support offshore vessel being built by Hong Hua Yard for Atlantic Navigation.
February 2026: Liebherr secured an order for two LS 250 heavy-lift ship cranes for Hartman Seatrade, each rated at 250 tonnes with tandem lifting capability.
February 2026: MacGregor was selected to supply a 400-tonne AHC subsea crane for a floating wind farm construction vessel intended to support the Ulsan floating wind project in South Korea.
Ship Deck Crane Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.70 billion |
| Total Market Size in 2031 | USD 2.60 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Vessel / Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Design
Knuckle-Boom and Foldable Cranes
Stiff and Standard Cargo Deck Cranes
Telescopic Boom Cranes
Heavy-Lift, Lattice and Gantry Cranes
By Vessel / Application
Merchant Cargo and Bulk Carriers
Offshore Support and Construction Vessels
Research, Naval and Special-Purpose Vessels
Workboats, Fishing Vessels and Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Spain
Norway
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Australia
Singapore
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Fleet Renewal and Concentrated Asian Shipbuilding Support Original-Equipment Crane Demand
3.1.2. Offshore Wind, Subsea Construction and Research-Vessel Investment Increase High-Specification Crane Demand
3.2. Market Restraint
3.2.1. Project-Specific Engineering and Shipbuilding Cycles Create Uneven Order Timing
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Electric and Electro-Hydraulic Crane Drives
4.2. Active Heave Compensation
4.3. Digital Monitoring and Condition-Based Maintenance
5. SHIP DECK CRANE MARKET BY DESIGN
5.1. Introduction
5.2. Knuckle-Boom and Foldable Cranes
5.3. Stiff and Standard Cargo Deck Cranes
5.4. Telescopic Boom Cranes
5.5. Heavy-Lift, Lattice and Gantry Cranes
6. SHIP DECK CRANE MARKET BY VESSEL / APPLICATION
6.1. Introduction
6.2. Merchant Cargo and Bulk Carriers
6.3. Offshore Support and Construction Vessels
6.4. Research, Naval and Special-Purpose Vessels
6.5. Workboats, Fishing Vessels and Others
7. SHIP DECK CRANE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. United Kingdom
7.4.3. France
7.4.4. Spain
7.4.5. Norway
7.4.6. Netherlands
7.4.7. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. Japan
7.6.3. South Korea
7.6.4. India
7.6.5. Australia
7.6.6. Singapore
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. MacGregor
9.2. Liebherr Group
9.3. PALFINGER MARINE
9.4. Mitsubishi Heavy Industries Machinery Systems, Ltd.
9.5. Heila Cranes S.p.A.
9.6. Huisman Equipment B.V.
9.7. KenzFigee
9.8. SMST Designers & Constructors B.V.
9.9. MELCAL S.r.l.
9.10. Hawboldt Industries
9.11. Appleton Marine, Inc.
9.12. DMW Marine Group, LLC
9.13. Seatrax, Inc.
9.14. NOV Inc.
9.15. IKNOW Machinery Co., Ltd.
9.16. Jiangsu Masada Heavy Industries Co., Ltd.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size of the Ship Deck Crane market in 2031?
The Ship Deck Crane Market is forecast to reach USD 2.60 billion by 2031.
What is the growth rate (CAGR) for the Ship Deck Crane market?
The Ship Deck Crane Market is forecast to grow at an 8.9% CAGR.
Which region holds the largest share in the Ship Deck Crane market?
Asia Pacific contributes approximately 49% of global revenue.
What key factors drive Ship Deck Crane market demand?
Offshore support vessels and fleet renewal drive demand.
Which crane types are significant in the Ship Deck Crane market?
Knuckle-boom and foldable cranes account for 34% revenue.
What are key technological trends in ship deck cranes?
Electric drives and lower-energy crane architectures are trends.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Ship Deck Crane Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ship-deck-crane-market