
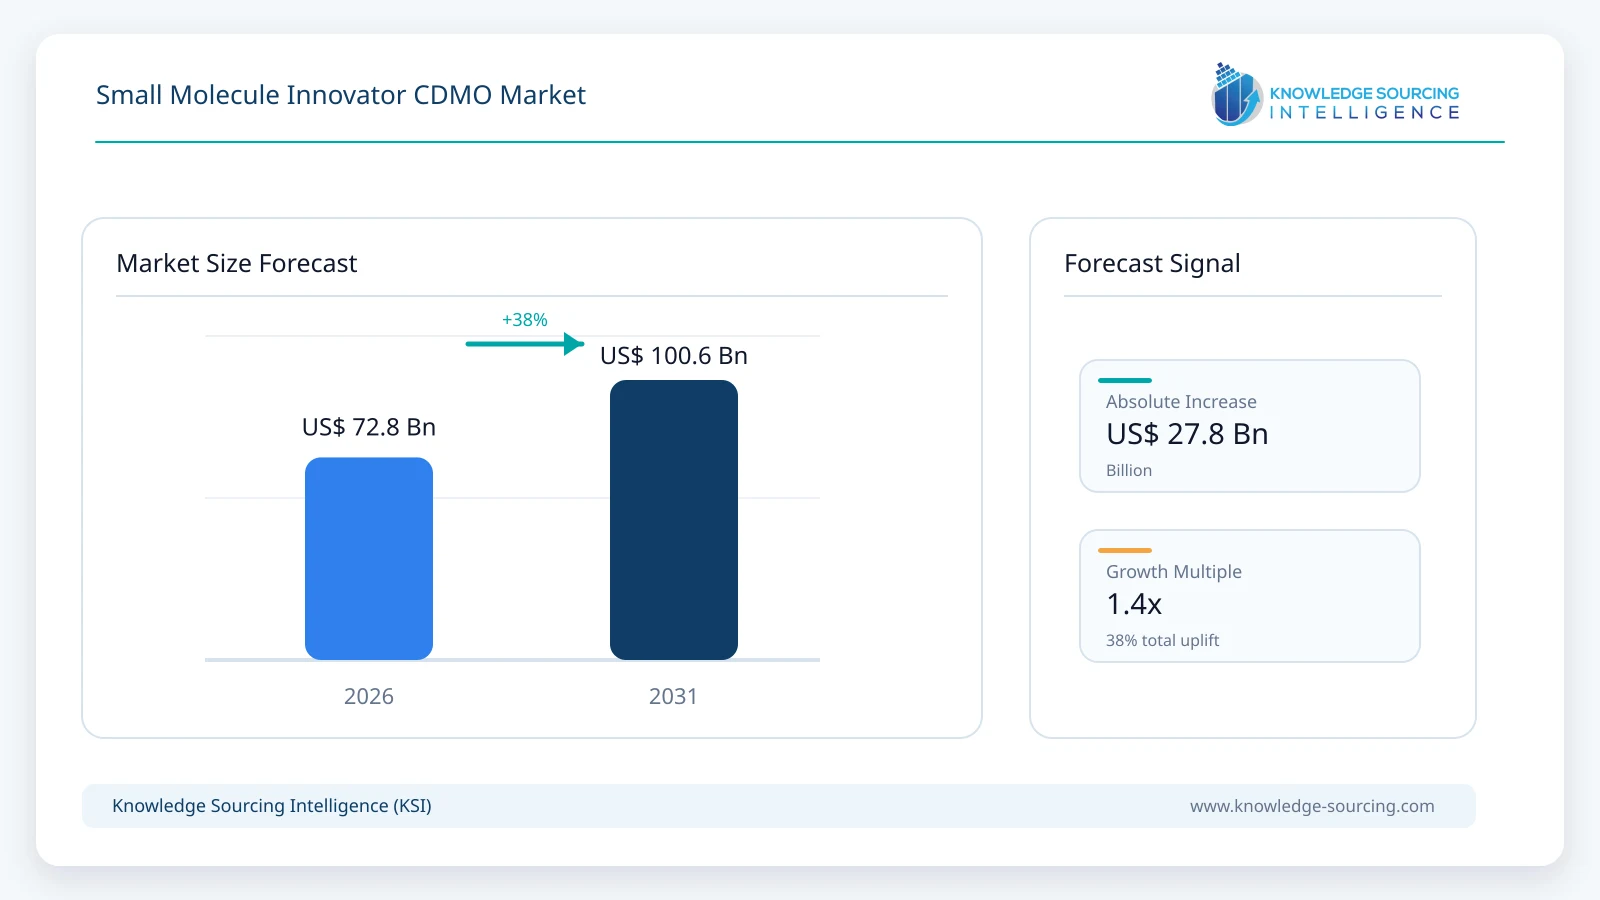
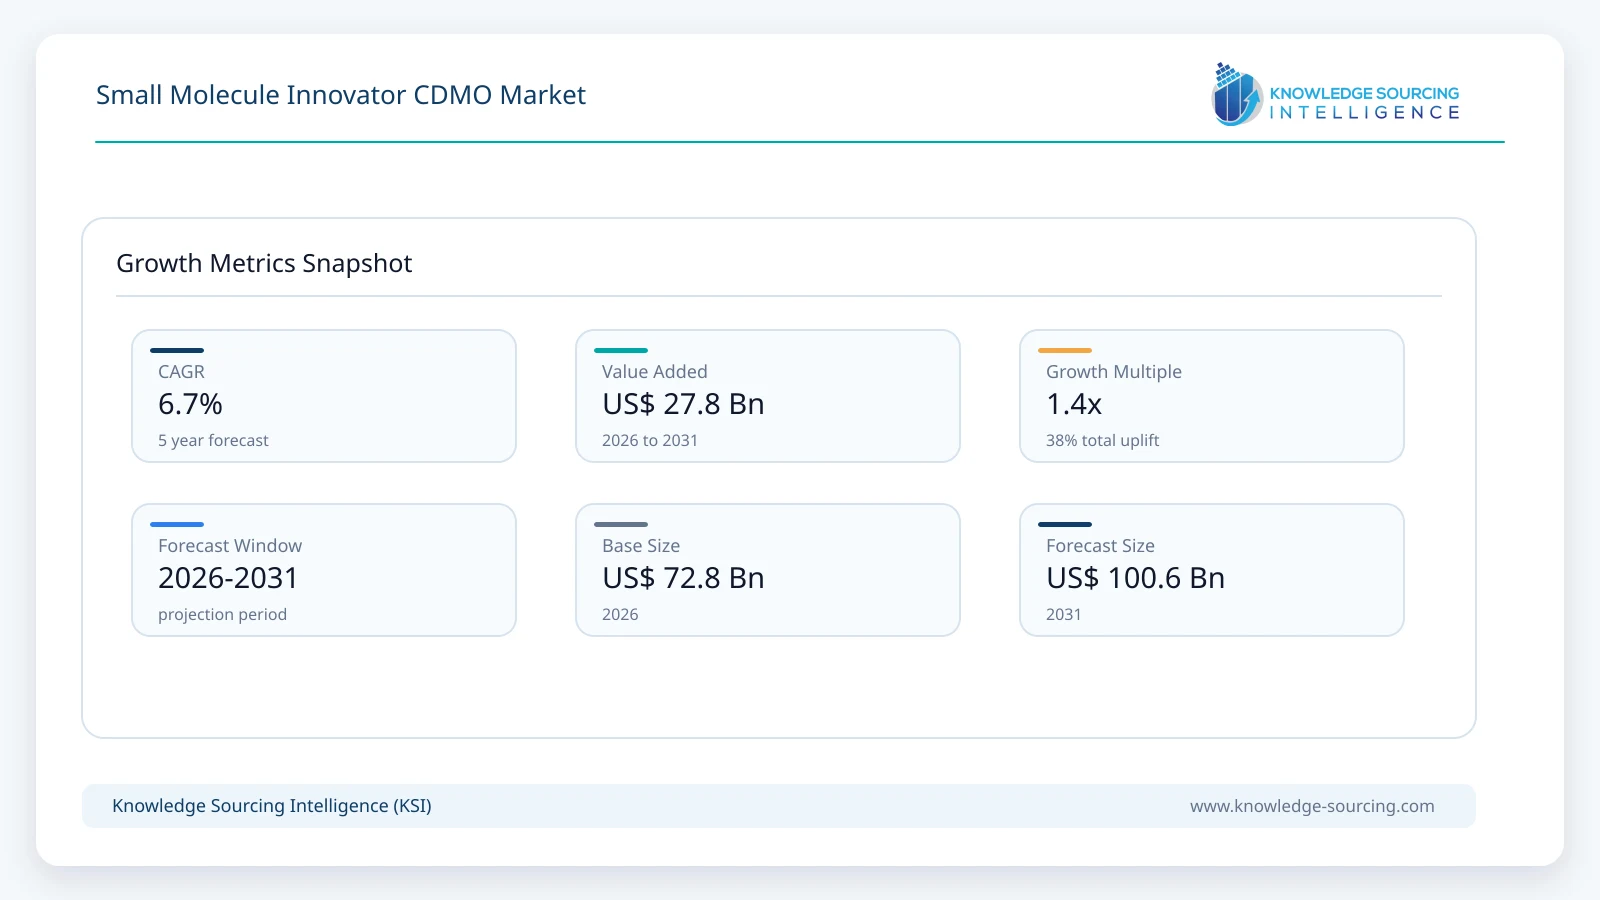
The Small Molecule Innovator CDMO Market is forecast to grow at a CAGR of approximately 6.7%, reaching USD 100.6 billion in 2031 from USD 72.8 billion in 2026.
Highlights:
- 1Small molecule API services account for approximately 61% of market value in 2026, supported by process development, scale-up and commercial drug-substance manufacturing.
- 2Commercial-stage programs account for approximately 58% of market value in 2026, reflecting higher manufacturing volumes and recurring supply requirements.
- 3Oncology represents approximately 34% of market demand by therapeutic area in 2026, supported by complex chemistry, HPAPIs and targeted therapies.
- 4North America accounts for approximately 37% of global market value in 2026, supported by a large innovator pipeline and high outsourcing intensity.
- 5Highly potent APIs, poorly soluble compounds and integrated API-to-drug-product programs are expected to grow faster than conventional small-molecule services through 2031.
The small molecule innovator CDMO market covers outsourced development and manufacturing services for innovative small-molecule drug candidates and commercial products, including active pharmaceutical ingredient development, process chemistry, scale-up, solid-state science, high-potency manufacturing, formulation, oral solid dosage manufacturing and associated analytical and regulatory support. The scope excludes commodity generic-only manufacturing where the principal activity is cost-based production of established off-patent molecules.
Small molecules remain central to pharmaceutical development despite the rapid growth of biologics and advanced modalities. Lonza reports that small molecules account for approximately 50% of molecules in clinical development, representing around 9,000 programs, and estimated the broader outsourced small-molecule CDMO market at approximately USD 78 billion in 2025. The company’s Advanced Synthesis platform subsequently recorded 27.7% constant-exchange-rate sales growth in the first half of 2026, with continued strong demand in Small Molecules and Bioconjugates.
The market is increasingly differentiated by technical capability rather than reactor volume alone. Innovator programs frequently involve challenging synthetic routes, highly potent compounds, stereochemistry, poorly soluble APIs, complex purification, particle engineering and demanding regulatory specifications. Lonza states that it supports more than 450 molecules annually across its small-molecule operations, while CordenPharma operates more than 1.2 million litres of small-molecule API reactor capacity across scales ranging from 20 litres to 28,000 litres.
Market Trends
• Integrated Drug Substance and Drug Product Development Is Becoming More Important
Innovator companies increasingly prefer CDMOs that can transition a molecule from route scouting and API development into formulation, clinical supply and commercial manufacturing without repeated technology transfers. Thermo Fisher’s Patheon business describes integration of drug substance and drug product development as a way to reduce hand-offs and identify scale-up and formulation risks earlier in the development process. CordenPharma and Lonza are similarly extending end-to-end capabilities across API, solid-state, formulation and finished-dose manufacturing. This model is particularly important to smaller biotechnology companies that may not maintain extensive internal CMC or manufacturing infrastructure.
• Complex Chemistry Is Increasing the Value of Specialist Capacity
Modern small-molecule pipelines contain a greater proportion of highly potent compounds, low-dose therapies, difficult synthetic steps and poorly soluble APIs. Cambrex is investing USD 120 million in expanded U.S. API capacity at Charles City, Iowa, including 140,000 litres of additional capacity designed for complex chemistry, controlled substances and highly potent APIs. Its Milan expansion adds process R&D and analytical-development capability specifically for increasingly complex small-molecule development.
• Bioavailability Enhancement Is Becoming a Larger Part of Small-Molecule CDMO Economics
Poor aqueous solubility remains a significant formulation challenge for innovator molecules. Spray-dried dispersion and other particle-engineering technologies are therefore moving further into commercial manufacturing. In September 2026, Lonza announced a new large-scale commercial spray-drying facility in Bend, Oregon, expected to be completed in 2029, creating a U.S. manufacturing hub for commercial spray-dried dispersions. The investment extends the role of CDMOs beyond conventional API synthesis into formulation technologies that directly influence whether a candidate can achieve acceptable exposure.
• Pharmaceutical Supply Chains Are Becoming More Geographically Diversified
CDMOs are expanding capacity across North America, Europe and Asia as pharmaceutical customers seek greater supply resilience and regional optionality. Siegfried completed the acquisition of three small-molecule drug-substance sites in the United States and Australia in May 2026 and opened a new large-scale facility in Minden, Germany, adding 100 m³ of reactor capacity. WuXi STA is simultaneously expanding API and oral solid-dose capacity across China, Switzerland, the United States and Singapore.
Market Drivers
• A Large Small-Molecule Innovator Pipeline Sustains Outsourcing Demand
Small molecules continue to represent approximately half of molecules in clinical development. This provides a large replenishing pipeline of programs requiring chemistry development, analytical work, clinical manufacturing and eventual commercial scale-up. Even though individual programs experience attrition, the aggregate pipeline creates recurring demand across early-stage and late-stage services.
• Increasing Molecule Complexity Encourages Specialist Outsourcing
Pharmaceutical companies can perform conventional chemistry internally, but complex or highly potent programs often require infrastructure and expertise that is expensive to maintain for intermittent use. CDMOs provide containment, specialized reactors, high-potency handling, crystallization, chromatography, spray drying and regulatory experience across multiple programs. Cambrex’s U.S. and European expansions and Lonza’s commercial spray-drying investment reflect continuing demand for capabilities that go beyond commodity manufacturing.
• Innovators Are Consolidating More Work With Fewer Strategic Partners
Large pharmaceutical and biotechnology companies are increasingly using integrated CDMO relationships to reduce transfer risk and simplify program management. Sai Life Sciences reported that it works with 19 of the top 25 global pharmaceutical companies, while its integrated CDMO pipeline expanded during FY2025-26. Thermo Fisher, Lonza, CordenPharma and WuXi STA are similarly structuring offerings around development-to-commercial continuity.
Market Restraints
• Biotechnology Funding Cycles Affect Early-Stage Program Flow
Early development outsourcing is sensitive to biotechnology financing because smaller innovators often depend on external capital to advance clinical assets. Piramal Pharma reported slower early-stage discovery and development orders during the first half of FY2026 before order activity improved as biotechnology funding recovered later in 2025. The effect is strongest for preclinical and early clinical projects, while established commercial manufacturing is more stable.
• Technology Transfer and Regulatory Qualification Limit Supplier Switching
Small-molecule manufacturing processes are closely tied to validated analytical methods, impurity profiles, raw-material controls and registered regulatory filings. Moving an advanced or commercial program between CDMOs can therefore require new validation, comparability work and regulatory submissions. These switching costs benefit established suppliers but also make customers cautious when allocating critical programs to newer manufacturing sites.
Segment Analysis
• By Product: Small Molecule API
Small molecule API services account for approximately 61% of market value in 2026 and remain the largest segment. API development starts with route scouting, analytical development and laboratory synthesis before moving through kilo-lab, pilot and commercial manufacturing. Innovator programs place particular value on route efficiency, impurity control, solid-state characteristics, intellectual-property considerations and reliable transfer between development and manufacturing scales. Piramal Pharma Solutions, for example, provides route scouting, process and analytical development, scale-up, HPAPI and commercial API manufacturing within an integrated drug-substance network.
Drug-product services represent the smaller but strategically important value pool and include formulation development, bioavailability enhancement, oral solid dose manufacturing and clinical or commercial packaging. Their share is expected to increase gradually as customers consolidate API and drug-product work with fewer CDMO partners.
• By Development Stage: Commercial
Commercial programs account for approximately 58% of market value in 2026. Although preclinical and clinical programs create the pipeline for future growth, approved products generate larger recurring manufacturing volumes and typically require long-term supply agreements, validation and lifecycle support. Siegfried reported that more than 90% of its 2025 revenues were generated from commercial-phase products, illustrating the revenue weight of mature programs within established CDMO portfolios.
Clinical-stage outsourcing remains strategically important because successful Phase II and Phase III programs can transition into higher-value commercial relationships. Sai Life Sciences ended FY2025-26 with 34 commercial molecules, 11 Phase III or pre-registration molecules and around 155 earlier-stage development programs, giving it a broad funnel for future manufacturing growth.
• By Therapeutic Area: Oncology
Oncology accounts for approximately 34% of market value in 2026 and remains the largest therapeutic area. Cancer pipelines contain substantial numbers of potent and structurally complex small molecules, including kinase inhibitors, targeted therapies and payload-like chemistries requiring stringent containment and impurity control. Demand therefore extends beyond basic synthesis into HPAPI manufacturing, specialized analytical methods, solid-state development and low-dose drug-product capability.
Neurology, metabolic disorders, cardiovascular disease, respiratory conditions and infectious diseases provide additional demand. The market is diversified across therapeutic areas because CDMO manufacturing requirements are determined primarily by chemistry, potency, dosage form and development stage rather than disease area alone.
Regional Outlook
• North America
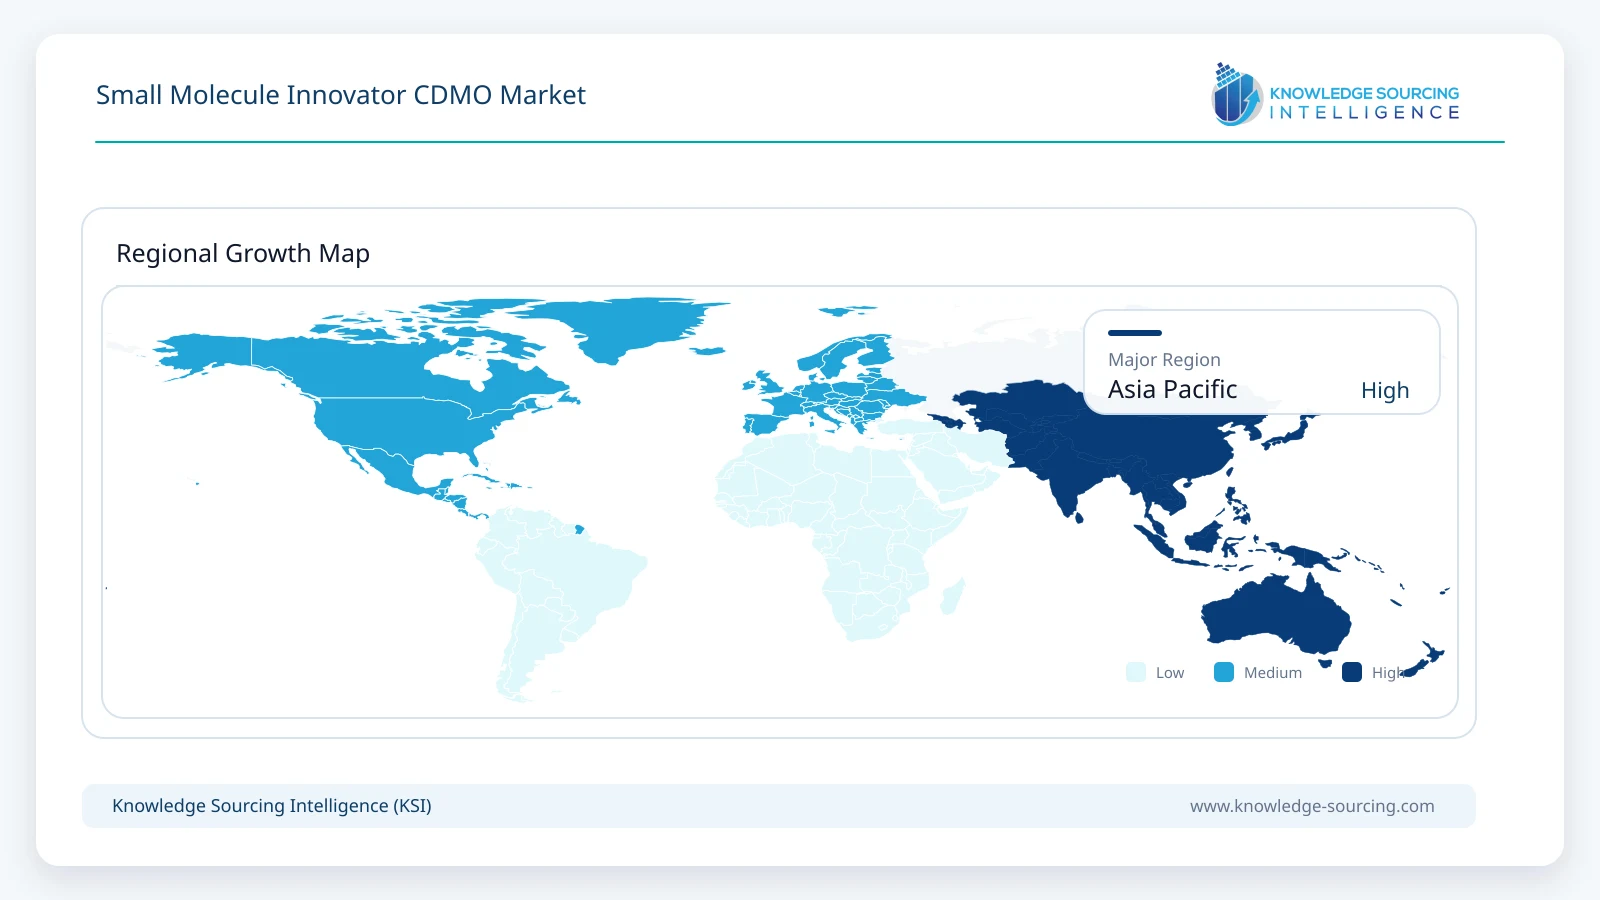
North America accounts for approximately 37% of global market value in 2026 and remains the largest regional market. The United States has a large biotechnology and pharmaceutical development pipeline and continues to attract new CDMO capacity. Cambrex is progressing a USD 120 million API expansion in Iowa, Lonza is developing commercial spray-drying capacity in Oregon, WuXi STA is preparing its Delaware oral solid-dose facility for operations by the end of 2026, and Siegfried has added U.S. drug-substance sites through acquisition.
Europe remains a major manufacturing and scientific center, particularly in Switzerland, Germany, Italy, France and the United Kingdom. Asia Pacific is expected to gain share through 2031 as India and China expand integrated development and commercial manufacturing capacity while maintaining cost and chemistry advantages. India is becoming particularly important in innovator-focused development and manufacturing, with Sai Life Sciences reporting INR 1,417 crore in CDMO revenue in FY2025-26 and planning substantial additional capital expenditure.
Competitive Landscape
The market is fragmented but increasingly favors CDMOs able to combine development science, differentiated manufacturing technologies and global regulatory track records. Lonza has extensive API, HPAPI, particle-engineering and drug-product capabilities and reported particularly strong Small Molecules performance during H1 2026. Thermo Fisher Scientific / Patheon combines API development with formulation and commercial drug-product manufacturing. WuXi STA continues to expand integrated API and dosage-form capacity across Asia, Europe and the United States.
Siegfried is expanding its small-molecule drug-substance network through acquisitions and new European capacity, while CordenPharma operates substantial API infrastructure and integrated drug-product capability. Cambrex remains strongly focused on small-molecule drug substance and complex chemistry. Piramal Pharma Solutions and Sai Life Sciences provide global innovators with development and manufacturing capacity spanning early-stage chemistry through commercial supply. Ardena and Catalent maintain differentiated positions in formulation, clinical supply and specialized drug-product development.
Recent Developments
September 2026: Lonza announced a new large-scale commercial spray-drying facility in Bend, Oregon, expected to be completed in 2029 and focused on commercial-scale bioavailability enhancement.
August 2026: Cambrex started construction of a USD 30 million R&D facility at its Milan site to expand analytical and process-development capabilities for complex small molecules.
June 2026: Siegfried inaugurated its new Minden drug-substance facility in Germany, adding 100 m³ of reactor capacity for complex and high-containment manufacturing.
May 2026: Siegfried completed its acquisition of three small-molecule drug-substance sites in the United States and Australia, expanding its global manufacturing network.
2026: WuXi STA continued construction and commissioning work across Delaware, Switzerland, China and Singapore, including new API and oral solid-dose capacity.
FY2025-26: Sai Life Sciences added four commercial molecules, taking its commercial portfolio to 34, while maintaining 11 Phase III/pre-registration programs and approximately 155 earlier-stage molecules.
Market Outlook
The small molecule innovator CDMO market is expected to remain structurally attractive through 2031 as pharmaceutical developers continue outsourcing increasingly complex chemistry, formulation and commercial manufacturing activities. Growth is no longer driven primarily by transferring standard synthesis to lower-cost facilities. Higher-value demand is shifting toward HPAPIs, difficult synthetic routes, solid-state development, particle engineering, bioavailability enhancement and integrated API-to-drug-product programs.
Commercial-stage manufacturing remains the largest revenue pool, but clinical-stage development is critical to future program conversion. North America retains the largest market share, while India and other Asian manufacturing hubs gain importance as global innovators diversify supply chains and use integrated development-to-commercial platforms.
Small Molecule Innovator CDMO Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 72.8 billion |
| Total Market Size in 2031 | USD 100.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, Development Stage, Therapeutic Area, Geography |
| Companies |
|
Market Segmentation
By Product
Small Molecule API
Small Molecule Drug Product
By Development Stage
Preclinical
Clinical
Commercial
By Therapeutic Area
Oncology
Cardiovascular Disease
Respiratory Disorders
Neurology
Metabolic Disorders
Infectious Disease
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Switzerland
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Innovator versus Generic CDMO Inclusion Criteria
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Innovator Pipeline and Commercial-Program Modelling
2.6. Segment Modelling
2.7. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Small Molecule Innovator CDMO Market Size, 2026-2031
3.3. Product Outlook
3.4. Development Stage Outlook
3.5. Therapeutic Area Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Large Small-Molecule Innovator Pipeline
4.1.2. Increasing Complexity of Small-Molecule Development
4.1.3. Consolidation Toward Integrated CDMO Partnerships
4.2. Market Restraints
4.2.1. Biotechnology Funding and Early-Stage Program Volatility
4.2.2. Technology Transfer and Regulatory Qualification Requirements
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Outsourcing and Supply-Chain Regionalization Trends
4.7. Regulatory and Quality Environment
5. TECHNOLOGY OUTLOOK
5.1. Highly Potent API Manufacturing
5.2. Continuous and Flow Chemistry
5.3. Solid-State and Crystallization Technologies
5.4. Spray-Dried Dispersions and Bioavailability Enhancement
5.5. Process Analytical Technology and Digital Process Development
6. SMALL MOLECULE INNOVATOR CDMO MARKET BY PRODUCT
6.1. Introduction
6.2. Small Molecule API
6.3. Small Molecule Drug Product
7. SMALL MOLECULE INNOVATOR CDMO MARKET BY DEVELOPMENT STAGE
7.1. Introduction
7.2. Preclinical
7.3. Clinical
7.4. Commercial
8. SMALL MOLECULE INNOVATOR CDMO MARKET BY THERAPEUTIC AREA
8.1. Introduction
8.2. Oncology
8.3. Cardiovascular Disease
8.4. Respiratory Disorders
8.5. Neurology
8.6. Metabolic Disorders
8.7. Infectious Disease
8.8. Others
9. SMALL MOLECULE INNOVATOR CDMO MARKET BY GEOGRAPHY
9.1. North America
9.1.1. By Product
9.1.2. By Development Stage
9.1.3. By Therapeutic Area
9.1.4. By Country
9.1.4.1. United States
9.1.4.2. Canada
9.1.4.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Switzerland
9.3.5. Italy
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. Taiwan
9.5.5. Thailand
9.5.6. Indonesia
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. API Development and Commercial Manufacturing Positioning
10.3. Drug Product and Integrated Service Positioning
10.4. HPAPI and Complex Chemistry Capabilities
10.5. Bioavailability Enhancement and Particle Engineering
10.6. Geographic Manufacturing Footprint
10.7. Partnerships, Acquisitions and Capacity Expansion
10.8. Competitive Dashboard
11. COMPANY PROFILES
11.1. Lonza Group AG
11.2. Thermo Fisher Scientific Inc. / Patheon
11.3. WuXi STA
11.4. Siegfried Holding AG
11.5. CordenPharma International
11.6. Piramal Pharma Solutions
11.7. Cambrex Corporation
11.8. Sai Life Sciences Limited
11.9. Catalent, Inc.
11.10. Ardena
12. APPENDIX
12.1. Market Definition and Scope
12.2. Innovator Program Inclusion and Exclusion Criteria
12.3. Currency and Conversion Assumptions
12.4. Base Year and Forecast Period
12.5. Market Estimation Approach
12.6. Primary and Secondary Research Framework
12.7. Data Triangulation and Validation
12.8. Abbreviations
Navigate
Trusted by the world's leading organizations











