
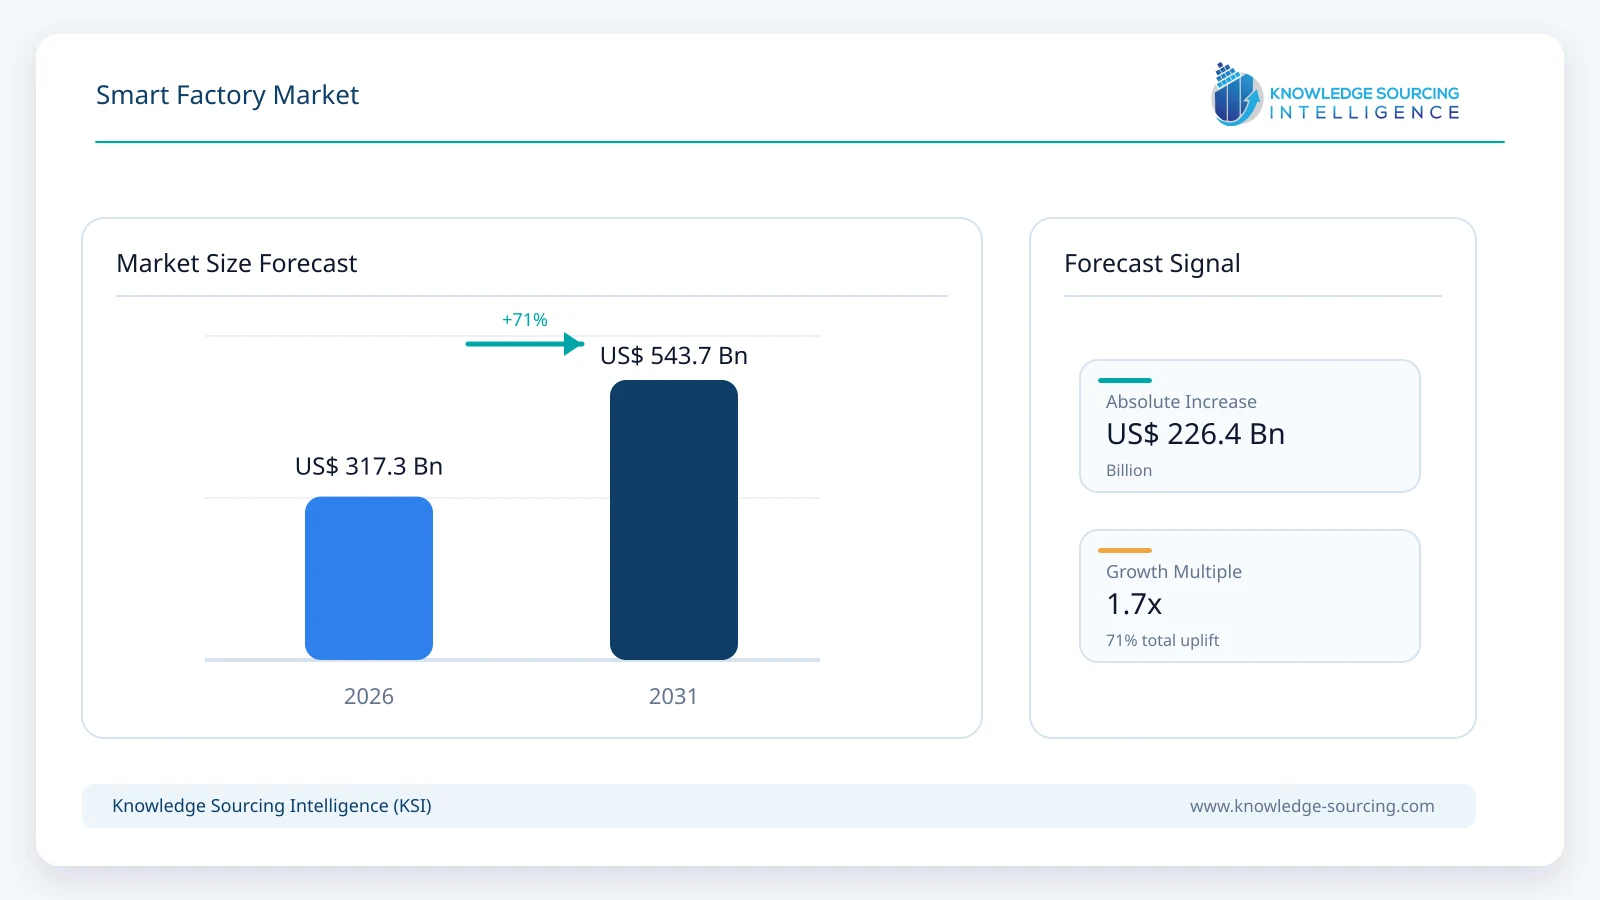
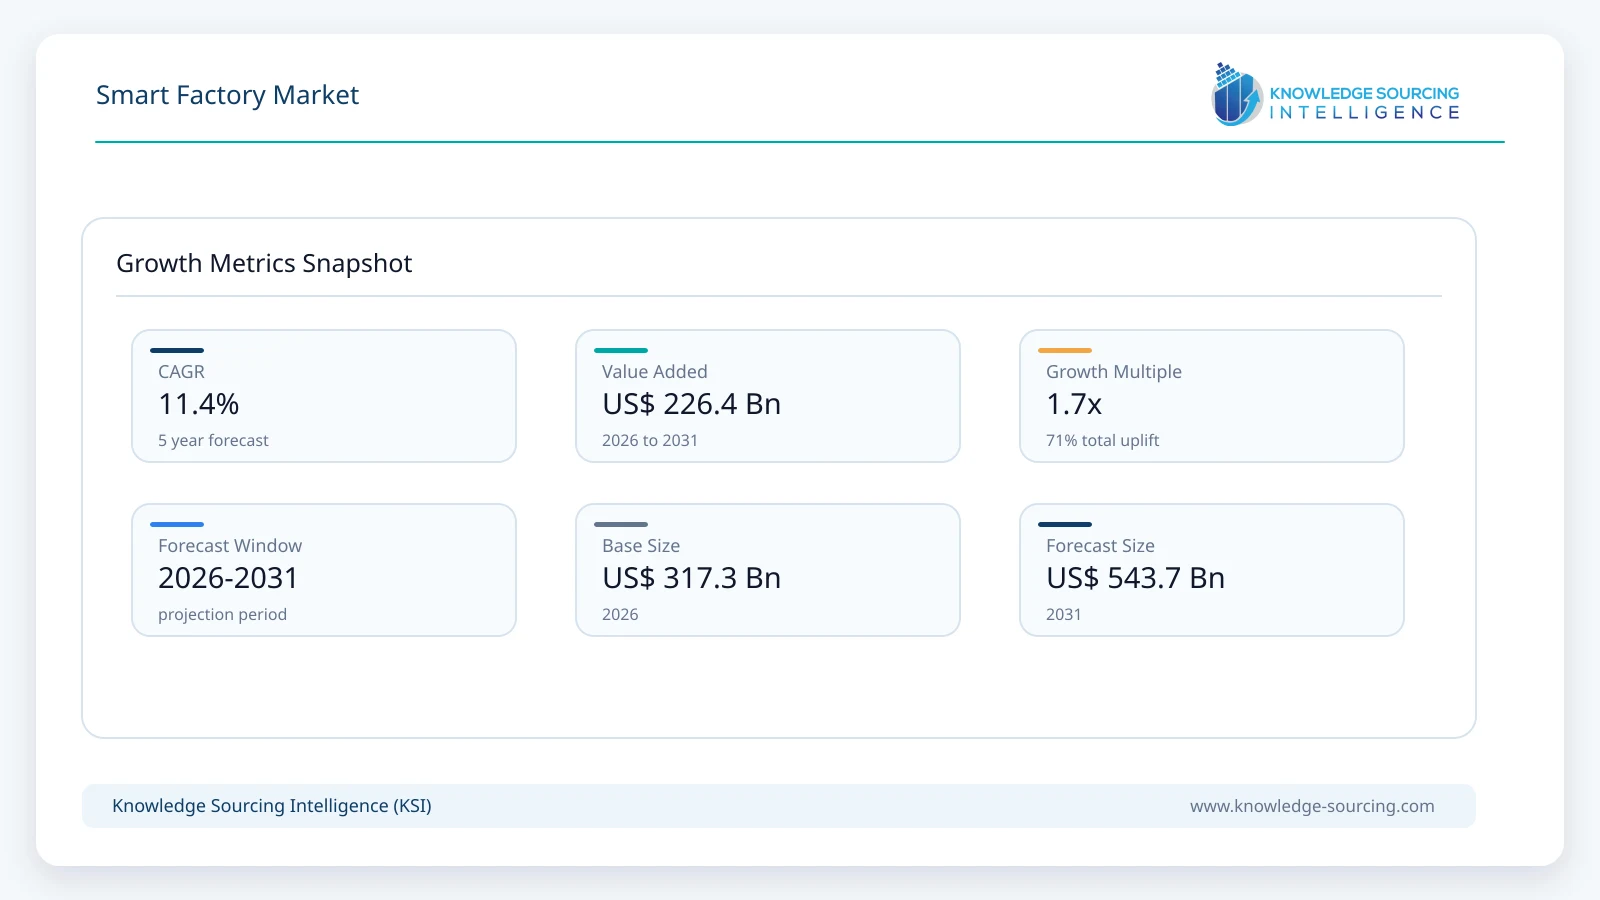
The smart factory market is set to reach USD 543.7 billion in 2031, growing at a CAGR of 11.4% from USD 317.3 billion in 2026.
Highlights:
- 1Integration of AI and IoT enables real-time data analytics and autonomous decision-making, transforming traditional manufacturing into highly responsive and intelligent production environments.
- 2Digital twin technology allows virtual simulation and optimization of factory operations, significantly improving efficiency, predictive maintenance, and product development cycles.
- 3Advanced robotics and collaborative automation enhance flexibility and precision on production lines while ensuring safer human-machine interaction across manufacturing processes.
- 4Seamless connectivity and data-driven ecosystems support end-to-end visibility, supply chain resilience, and sustainable manufacturing practices in modern smart factories.
The market for smart factories is growing rapidly as manufacturers in different sectors are rapidly adopting digital transformation technologies to improve operational efficiency, productivity, flexibility, and product quality. The rising need for automation across industries like automotive, electronics, pharmaceuticals, aerospace, food and beverages, and chemicals is the major factor driving market growth. The need to reduce labor costs, increase customization, and reduce production downtime and energy consumption drives industrial companies to upgrade their traditional factories to intelligent production lines. Suzuki Motor Corporation has officially introduced the work analysis AI software "Ollo Factory, " developed and provided by Ollo, Inc. The software will first be implemented at the assembly plant of the Sagara Plant in July 2025 and later in the engine plant in December 2025. The company is implementing this software under the Suzuki Smart Factory program, which is focused on advancing work analysis, training, and quality control at production sites through digitalization and real-time monitoring. The aim is to raise productivity levels and prevent defective products from being shipped from domestic plants.
Government initiatives are helping to accelerate the global adoption of smart factories.
Industry 4.0 in Germany, Made in China 2025, and Make in India promote automation in factories, digital manufacturing, robotics, and the integration of the Internet of Things (IoT).
In the same way, the Manufacturing USA program is supporting advanced manufacturing innovation and smart manufacturing technologies.
Moreover, the fast roll-out of 5G connectivity and edge computing is enhancing the speed of communications and data processing capabilities in factory ecosystems, thus allowing operations to be conducted more quickly and efficiently.
Delta has announced its participation at ELECRAMA 2025.
The company operated under the theme of smart manufacturing and launched its new D-Bot series Collaborative Robots (Cobots) into the Indian market.
Made for smart factory automation, the cobots efficiently carry out their tasks while including several various safety features that enable risk-free human-robot collaboration.
At Gulfood Manufacturing in Dubai, Tetra Pak showcased their next-generation Automation and Digitalisation (A&D) portfolio, Tetra Pak® Factory OS™.
The newly launched set of technologies for smart factories that are modular, open, and scalable will revolutionize the production of food and beverages (F&B) and create the basis for AI-ready factories.
Rapid industrialization and development of the manufacturing sector, as well as the increase in foreign direct investments in smart production technologies, have led the emerging economies in the Asia-Pacific, especially China, India, South Korea, and Southeast Asian countries, to become significant growth centers.
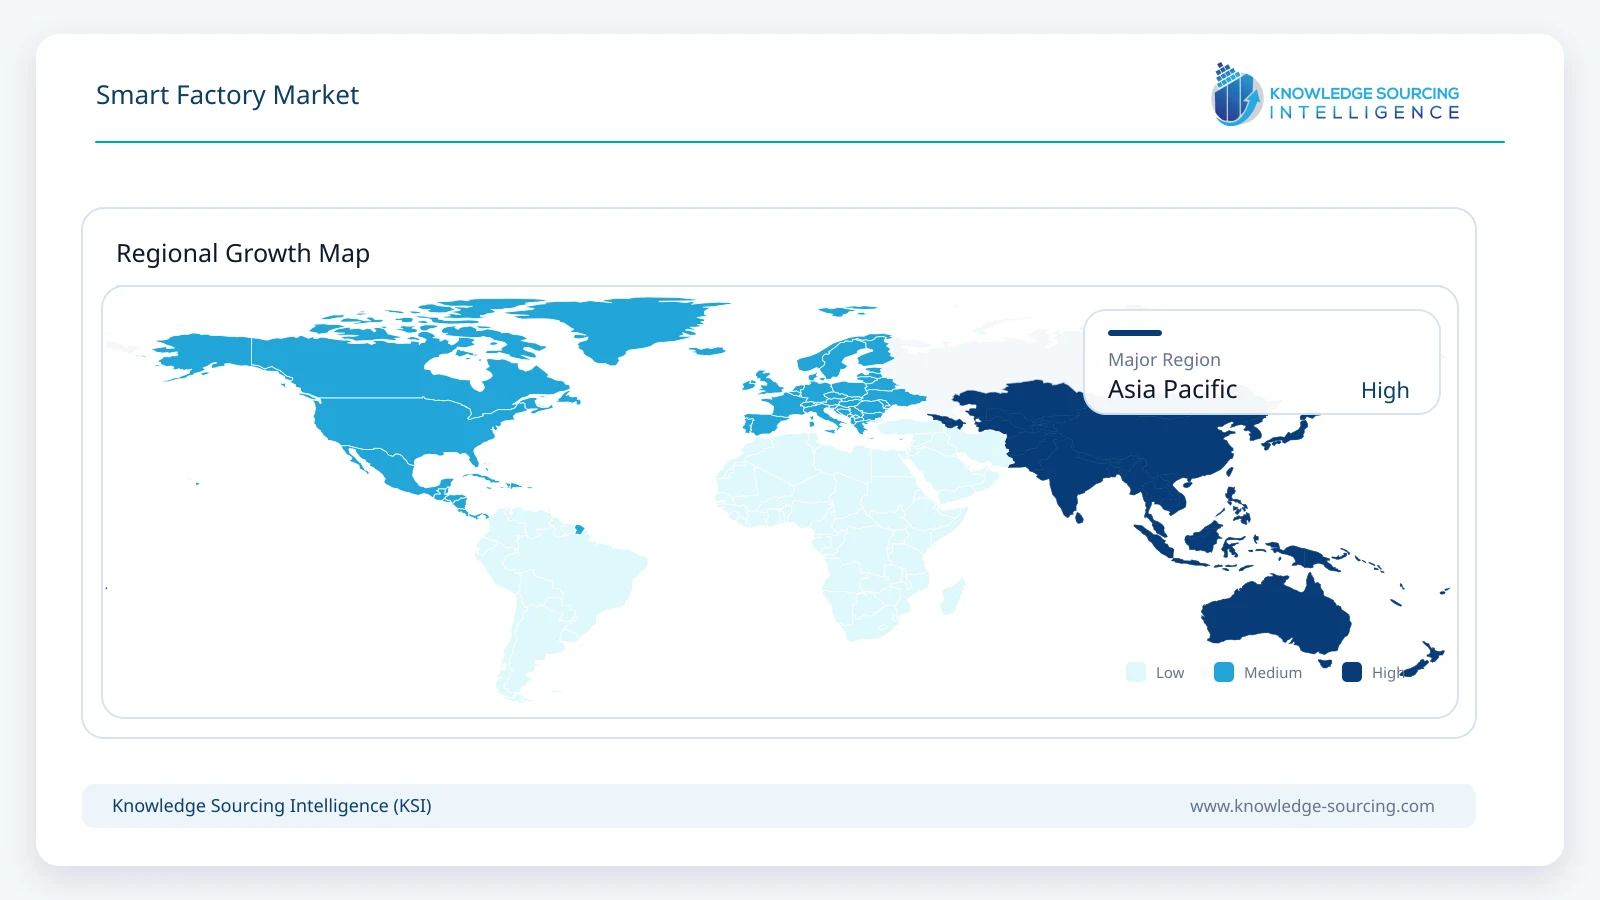
Asia-Pacific is the fastest-growing region in the Smart Factory Market due to rapid industrialization, rising automation adoption, and increasing investments in Industry 4.0 technologies across China, India, Japan, and South Korea.
Artificial Intelligence (AI) & Machine Learning (ML) are expected to be the fastest-growing segments due to increasing demand for predictive analytics, intelligent automation, and real-time operational decision-making in smart factories.
OPC UA is witnessing strong growth owing to its secure, interoperable, and platform-independent communication capabilities for connected industrial systems and Industry 4.0 environments.
In 2025, software was the major segment by component, accounting for X% share by value, followed by hardware, accounting for X% share in the same year.
The software segment is growing rapidly as manufacturers increasingly adopt analytics platforms, digital twin software, manufacturing execution systems (MES), and AI-driven monitoring solutions.
Cloud-based deployment is emerging as the fastest-growing segment due to its scalability, remote accessibility, lower infrastructure costs, and efficient data management capabilities.
Market Dynamics
Drivers
Rising Deployment of 5G Technology
The fast adoption of 5G technology is one of the main factors boosting the Smart Factory Market. It provides super-fast data transfer speeds, communication with very low delays, and highly reliable connections between machines. 5G allows for features such as real-time monitoring, fully autonomous robots, connected sensors, and highly advanced Industrial IoT implementations in the manufacturing environment. This technology improves operational efficiency, including predictive maintenance, remote handling, and the automation of decision-making processes, thus assisting manufacturers in raising productivity and minimizing the time production is stopped.
5G services have been deployed in every State and Union Territory of India. They are available in 99.9% of the districts of the country, with an 85% population coverage, as per the 2025 report of the Ministry of Communications.
Leading telecom operators such as Reliance Jio, Bharti Airtel, and Vodafone Idea are making investments in 5G architecture and network technologies to provide a high-speed connectivity experience.
As of October 2025, telecom service providers (TSPs) have installed 508 thousand 5G Base Transceiver Stations (BTSs) across India.
The growth of smart devices, IoT ecosystems, and the rising demand for applications like smart cities, autonomous systems, cloud gaming, and industrial automation are further pushing the necessity for strong 5G infrastructure.
The number of internet connections in India has surpassed the 1 billion milestone, compared to 251.5 million in March 2014, recording a 298.77% growth over the past 10 years.
Restraints and Opportunities
Market growth faces significant headwinds from high initial capital expenditure (CAPEX) and the complexity of retrofitting legacy brownfield facilities with modern sensors and vPLCs. The substantial investment required for hardware upgrades and workforce retraining can deter Small and Medium Enterprises (SMEs). However, this creates a significant opportunity for Cloud-Based and Hybrid deployment models, which offer scalable, lower-cost entry points through "Manufacturing-as-a-Service" (MaaS) frameworks. Another critical obstacle is the heightened cybersecurity risk associated with increased connectivity. This challenge has birthed a lucrative sub-market for Industrial Cybersecurity Solutions, as manufacturers must now secure cyber-physical systems against sophisticated ransomware and data breaches to maintain operational continuity.
Raw Material and Pricing Analysis
The smart factory hardware segment is heavily dependent on the supply of semiconductors, advanced sensors, and high-grade industrial robotics components. In 2025, the pricing of these components remains volatile due to geopolitical tensions and trade tariffs, particularly impacting the cost of PLCs and actuators imported from Europe and Japan. The need for industrial CMOS image sensors is rising, with new 1.3 MP to 67 MP models entering the market to support high-precision machine vision. Pricing for these specialized electronics directly influences the BOM (Bill of Materials) for smart factory integrators. Additionally, the cost of 18/8 food-grade stainless steel and specialized polymers used in automated food and pharmaceutical lines fluctuates with energy prices, impacting the overall cost of physical automation infrastructure.
Supply Chain Analysis
The smart factory supply chain is undergoing a strategic regionalization, moving away from a China-centric model toward localized "Greenfield" production hubs in the US, UK, and India. This shift is driven by the need to reduce logistical complexities and comply with regional sustainability mandates. For instance, companies like Schneider Electric and Rockwell Automation have recently commissioned large-scale smart plants in the UK and Wisconsin, respectively, to ensure proximity to key customers. Despite this, the supply chain remains dependent on a fragmented network of specialized component providers for AI-ready chips and high-torque servomotors. Logistical resilience is being bolstered by the use of Digital Logistics Twins, which allow manufacturers to orchestrate end-to-end supply chain movements and mitigate disruptions in real-time.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
European Union | AI Act (Regulation 2024/1689) | Increases Compliance Complexity: Introduces a risk-oriented approach to AI deployment. High-risk industrial systems must undergo conformity assessments and maintain extensive documentation. While it ensures safety, the compliance burden can delay the adoption of autonomous robotics in smaller factories. |
United States | CHIPS and Science Act / Trade Policy | Stimulates Domestic Hardware Demand: Government incentives for advanced manufacturing and digital infrastructure accelerate the construction of domestic smart factories. Reciprocal tariffs on imported PLCs and robotics, however, raise the cost of implementation for systems relying on non-US hardware. |
China | Made in China 2025 (Updated Targets) | Drives Localization: Targets to increase the domestic market share of industrial robots and high-end machinery. While China leads in volume, a continued reliance on high-end foreign components for high-horsepower and specialized machinery creates a dual market of domestic and imported technology. |
Key Developments
October 2026: Schneider Electric, NVIDIA and HPE announced a collaboration introducing Industrial AI Agents at the Edge to optimize industrial operations, energy efficiency and cybersecurity.
October 2026: Rockwell Automation announced FactoryTalk Conductor, an AI-native orchestration platform connecting AI agents, engineering software and workflows, with commercial availability planned for 2027.
October 2026: Siemens unveiled AI applications developed with NVIDIA at its Erlangen electronics factory, combining digital twins and agent-based production planning for adaptive manufacturing.
September 2026: Siemens launched Meet at the Machine with TRAK Machine Tools, integrating engineering software, automation and machine expertise to accelerate production preparation.
March 2026: Siemens announced an investment exceeding €200 million to build an AI-based, digitalized and automated Smart Infrastructure factory in Amberg, Germany, targeted for completion by 2030.
December 2025: ABB India introduced its ACS380-E next-generation industrial machinery drive, which operates at peak efficiency for automation applications. The drive supports dual Ethernet connections while its embedded security features enable USB-C setup and Industry 4.0 functions for textile, plastic, packaging, and intralogistics industries.
September 2025: Schneider Electric officially commissioned a 16,500 sq m smart manufacturing facility in Scarborough, North Yorkshire, for £42 million, designed to produce critical electrical equipment for the energy transition while operating as a net-zero site.
Market Segmentation
By Technology Type: Robotics and Automation
By Technology Type, the smart factory market is segmented into industrial internet of things (IIoT), robotics & automation, artificial intelligence (AI) & machine learning (ML), digital twins, industrial cybersecurity solutions, and industrial connectivity.
Robotics & automation is expected to show significant growth fueled by rapid technological advancement and Industry 4.0 evolution.
Ongoing investments in smart manufacturing have played a major role in utilizing next-generation automation concepts.
Articulated robots are a versatile type of industrial robots and are a major growth factor in the smart factory market. It integrates the Industry 4.0 technologies framework, which includes efficient, sustainable, and data-driven production, such as assembly, material handling, and processing.
According to the International Federation of Robotics (IFR) Industrial Robots 2025 report data, the global demand for robotics has doubled in the past decade. The report also predicts that robot installations will increase from 575 thousand units in 2025 to 700 thousand units by 2028, representing a 6% growth.
The articulated robots are a primary category in the industrial robot’s installation, having functions in diverse industries, especially in electronics, automotive, and general manufacturing. Smart factories depend on articulated robots as the physical execution layer for flexible, data-driven production.
The major market players, such as FANUC Corporation, Mitsubishi, Kawasaki Heavy Industry Ltd, and ABB, focus on ongoing innovation and launches to offer easier-to-deploy, smarter, and more flexible products, which is boosting the segment expansion.
For instance, in November 2025, Kawasaki Heavy Industries, Ltd. reported the launch of its 6-axis vertical articulated robot “RS025S” for the Asian region. It can handle a maximum payload capacity of 25 kg and can be integrated in electrical and electronic industries, along with other manufacturing industries.
Regional Analysis
Asia Pacific: China
Considered as the global manufacturing hub, China has emphasized promoting smart manufacturing with policies like the “15th Five-Year Plan” outlining modern industrial goals powered by AI and robotics applications.
With more than 30,000 basic-level smart factories established in the country as a part of nationwide industrial digitalization and upgrade, the scope of innovative concepts like ML and robotics automation is progressing in China.
Implementation of smart factory gradient cultivation initiatives by governing authorities like the Ministry of Industry and Information Technology (MIIT) has amplified the market expansion.
Accounting for nearly 54% of the global industrial robotics installations according to the International Federation of Robotics, China has shown constant growth in industrial automation over the years.
Besides basic-level smart factories, China also harbors nearly 7,000 advanced smart factories and 500 excellent smart factories, which have made China the largest intelligent manufacturing application base.
Growing technological affordability and ongoing investment in Industry 4.0 concepts have further bolstered smart factory transformation in China.
List of Companies
ABB
Siemens AG
Schneider Electric SE
Fanuc Corporation
Honeywell International Inc.
Robert Bosch GmbH
Emerson Electric Co.
Mitsubishi Electric Corporation
Addverb Technologies Limited
Luna Technologies Pvt Ltd
Kawasaki Heavy Industries, Ltd.
ABB is a global technology company with its main office in Zurich, Switzerland. The company offers electrification, robotics, motion, and industrial automation solutions, which help industrial operators from manufacturing, energy, transportation, and process industries to improve productivity and safety through digitalization and automation technologies. ABB provides services in more than 100 countries, using AI, Industrial IoT (IIoT), robotics, and cloud-based analytics to deliver industrial automation solutions for Industry 4.0 transformation projects.
ABB Ability digital platform, together with its robotics software and manufacturing execution systems (MES) industrial analytics solutions, establishes ABB as a leading company within the smart factory market. The company enables factories to achieve real-time monitoring, predictive maintenance, and process optimization, while empowering robotic automation and connected manufacturing operations. Its solutions support various industries, including automotive, food and beverage, electronics, pharmaceuticals, metals, and logistics by creating a smart manufacturing environment that connects production equipment with ERP systems and robotics and AI-powered operational intelligence.
Smart Factory Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 317.3 billion |
| Total Market Size in 2031 | USD 543.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology Type, Communication Protocol, Component, Deployment Model, Factory Scale, Application, Industry Vertical, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Technology Type
Industrial Internet of Things (IIoT)
Robotics & Automation
Articulated Robots
Cartesian Robots
SCARA Robots
Others
Artificial Intelligence (AI) & Machine Learning (ML)
Computer Vision
Generative AI
Natural Language Processing (NLP)
Digital Twins
Component Twins
Asset Twins
Process Twin
Unit Twin
Industrial Cybersecurity Solutions
DDoS Protection
API Security
Network Segmentation
Web Application Security
OT Security
Identity Access Management
Endpoint Detection and Response (EDR)
Industrial Connectivity
Cellular/Private 5G
Industrial Ethernet
Wi-Fi (6 & 6E)
Others
By Communication Protocol
OPC UA
MQTT
PROFINET
Ethernet/IP
Modbus
Others
By Component
Hardware
Industrial Sensors & Actuators
Programmable Logic Controllers (PLCs)
Machine Vision System
Edge Computers & Servers
Robotics Hardware
Others
Software
Supervisory Control and Data Acquisition (SCADA)
Enterprise Resource Planning (ERP)
Manufacturing Execution System (MES)
Digital Twin Software
Predictive Maintenance Software
AI & Data Analytics Platform
Services
By Deployment Model
On-Premise
Cloud-Based
Hybrid
By Factory Scale
Small-Scale Factories
Medium-Scale Factories
Large-Scale Factories
By Application
Predictive Maintenance
Quality Checking
Asset Tracking
Supply Chain Monitoring
Inventory & Warehouse Automation
Others
By Industry Vertical
Automotive
Electronics & Semiconductor
Aerospace & Defense
Pharmaceuticals & Healthcare
Food & Beverage
Chemicals & Materials
Energy & Utilities
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. AI, Generative AI, and Agentic Automation Impact on Smart Factory
5. SMART FACTORY MARKET BY TECHNOLOGY TYPE
5.1. Introduction
5.2. Industrial Internet of Things (IIoT)
5.3. Robotics & Automation
5.3.1. Articulated Robots
5.3.2. Cartesian Robots
5.3.3. SCARA Robots
5.3.4. Others
5.4. Artificial Intelligence (AI) & Machine Learning (ML)
5.4.1. Computer Vision
5.4.2. Generative AI
5.4.3. Natural Language Processing (NLP)
5.5. Digital Twins
5.5.1. Component Twins
5.5.2. Asset Twins
5.5.3. Process Twin
5.5.4. Unit Twin
5.6. Industrial Cybersecurity Solutions
5.6.1. DDoS Protection
5.6.2. API Security
5.6.3. Network Segmentation
5.6.4. Web Application Security
5.6.5. OT Security
5.6.6. Identity Access Management
5.6.7. Endpoint Detection and Response (EDR)
5.7. Industrial Connectivity
5.7.1. Cellular/ Private 5G
5.7.2. Industrial Ethernet
5.7.3. Wi-Fi (6 & 6E)
5.7.4. Others
6. SMART FACTORY MARKET BY COMMUNICATION PROTOCOL
6.1. Introduction
6.2. OPC UA
6.3. MQTT
6.4. PROFINET
6.5. Ethernet/IP
6.6. Modbus
6.7. Others
7. SMART FACTORY MARKET BY COMPONENT
7.1. Introduction
7.2. Hardware
7.2.1. Industrial Sensors & Actuators
7.2.2. Programmable Logic Controllers (PLCs)
7.2.3. Machine Vision System
7.2.4. Edge Computers & Servers
7.2.5. Robotics Hardware
7.2.6. Others
7.3. Software
7.3.1. Supervisory Control and Data Acquisition (SCADA)
7.3.2. Enterprise Resource Planning (ERP)
7.3.3. Manufacturing Execution System (MES)
7.3.4. Digital Twin Software
7.3.5. Predictive Maintenance Software
7.3.6. AI & Data Analytics Platform
7.4. Services
8. SMART FACTORY MARKET BY DEPLOYMENT MODEL
8.1. Introduction
8.2. On-Premise
8.3. Cloud-Based
8.4. Hybrid
9. SMART FACTORY MARKET BY FACTORY SCALE
9.1. Introduction
9.2. Small-Scale Factories
9.3. Medium-Scale Factories
9.4. Large-Scale Factories
10. SMART FACTORY MARKET BY APPLICATION
10.1. Introduction
10.2. Predictive Maintenance
10.3. Quality Checking
10.4. Asset Tracking
10.5. Supply Chain Monitoring
10.6. Inventory & Warehouse Automation
10.7. Others
11. SMART FACTORY MARKET BY INDUSTRY VERTICAL
11.1. Introduction
11.2. Automotive
11.3. Electronics & Semiconductor
11.4. Aerospace & Defense
11.5. Pharmaceuticals & Healthcare
11.6. Food & Beverage
11.7. Chemicals & Materials
11.8. Energy & Utilities
11.9. Others
12. SMART FACTORY MARKET BY GEOGRAPHY 
12.1. Introduction
12.2. North America
12.2.1. By Technology Type
12.2.2. By Communication Protocol
12.2.3. By Component
12.2.4. By Deployment Model
12.2.5. By Factory Scale
12.2.6. By Industry Vertical
12.2.7. By Country
12.2.7.1. USA
12.2.7.2. Canada
12.2.7.3. Mexico
12.3. South America
12.3.1. By Technology Type
12.3.2. By Communication Protocol
12.3.3. By Component
12.3.4. By Deployment Model
12.3.5. By Factory Scale
12.3.6. By Industry Vertical
12.3.7. By Country
12.3.7.1. Brazil
12.3.7.2. Argentina
12.3.7.3. Others
12.4. Europe
12.4.1. By Technology Type
12.4.2. By Communication Protocol
12.4.3. By Component
12.4.4. By Deployment Model
12.4.5. By Factory Scale
12.4.6. By Industry Vertical
12.4.7. By Country
12.4.7.1. United Kingdom
12.4.7.2. Germany
12.4.7.3. France
12.4.7.4. Italy
12.4.7.5. Spain
12.4.7.6. Others
12.5. Middle East and Africa
12.5.1. By Technology Type
12.5.2. By Communication Protocol
12.5.3. By Component
12.5.4. By Deployment Model
12.5.5. By Factory Scale
12.5.6. By Industry Vertical
12.5.7. By Country
12.5.7.1. Saudi Arabia
12.5.7.2. UAE
12.5.7.3. Israel
12.5.7.4. Others
12.6. Asia Pacific
12.6.1. By Technology Type
12.6.2. By Communication Protocol
12.6.3. By Component
12.6.4. By Deployment Model
12.6.5. By Factory Scale
12.6.6. By Industry Vertical
12.6.7. By Country
12.6.7.1. China
12.6.7.2. Japan
12.6.7.3. India
12.6.7.4. South Korea
12.6.7.5. Taiwan
12.6.7.6. Thailand
12.6.7.7. Indonesia
12.6.7.8. Others
13. COMPETITIVE ENVIRONMENT AND ANALYSIS
13.1. Major Players and Strategy Analysis
13.2. Market Share Analysis
13.3. Mergers, Acquisitions, Agreements, and Collaborations
13.4. Competitive Dashboard
14. COMPANY PROFILES
14.1. Hardware
14.1.1. ABB
14.1.2. Siemens AG
14.1.3. Schneider Electric SE
14.1.4. Fanuc Corporation
14.1.5. Honeywell International Inc.
14.1.6. Robert Bosch GmbH
14.1.7. Emerson Electric Co.
14.1.8. Mitsubishi Electric Corporation
14.1.9. Addverb Technologies Limited
14.1.10. Luna Technologies Pvt Ltd
14.1.11. Kawasaki Heavy Industries, Ltd.
14.2. Software
14.2.1. Siemens AG
14.2.2. Rockwell Automation, Inc.
14.2.3. Schneider Electric SE
14.2.4. Honeywell International Inc.
14.2.5. SAP SE
14.2.6. PTC Inc.
14.2.7. General Electric Company
14.2.8. Microsoft Corporation
14.2.9. Zetwerk Manufacturing India Pvt. Ltd.
14.2.10. Softlabs Group
14.3. Services
14.3.1. ABB
14.3.2. Schneider Electric SE
14.3.3. Siemens AG
14.3.4. Honeywell International Inc.
14.3.5. Rockwell Automation, Inc.
14.3.6. Larsen & Toubro Limited (L&T)
14.3.7. JRETS AI
14.3.8. Maruti Suzuki India Limited
15. LIST OF FIGURES
16. LIST OF TABLES





Frequently asked questions
What is the projected market size for smart factories by 2031?
The Smart Factory Market is projected to reach USD 543.7 billion by 2031.
What is the CAGR for the Smart Factory Market from 2026 to 2031?
The Smart Factory Market is growing at a CAGR of 11.4% from USD 317.3 billion in 2026.
What are the primary drivers of Smart Factory Market growth?
Digital transformation, automation, cost reduction, efficiency, and government initiatives drive growth.
Which key technologies are transforming smart factory environments?
AI, IoT, digital twin, advanced robotics, and collaborative automation are key technologies.
Which industries are rapidly adopting smart factory solutions?
Automotive, electronics, pharma, aerospace, food & beverages, and chemicals are adopting.
How do 5G connectivity and edge computing impact smart factories?
They enhance communication speed and data processing capabilities for operations.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Smart Factory Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/smart-factory-market