
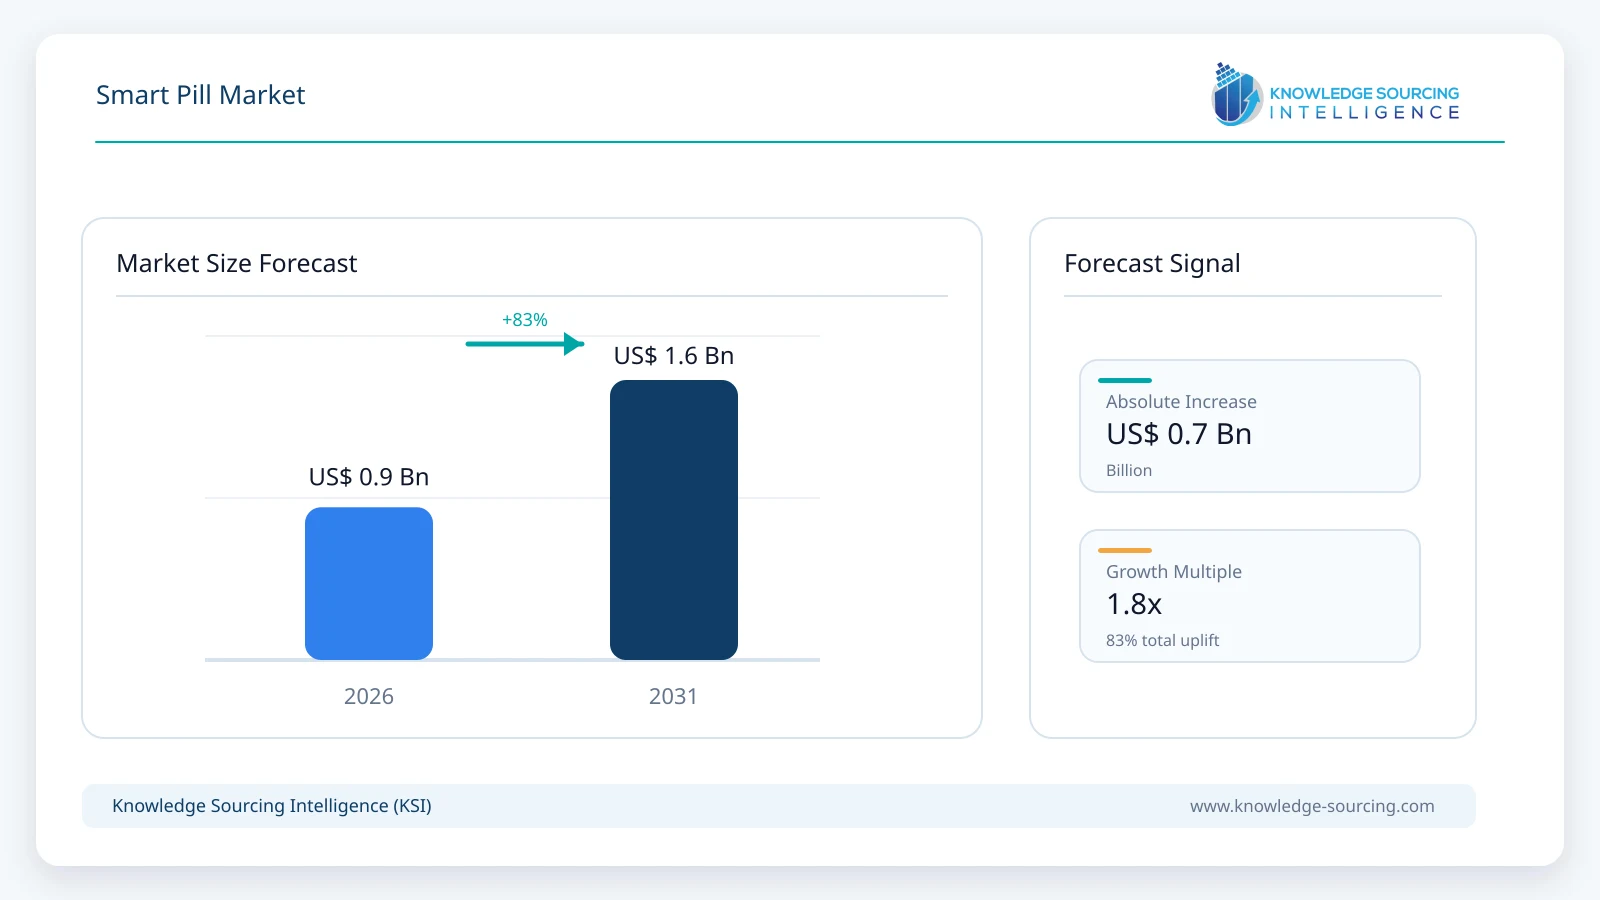
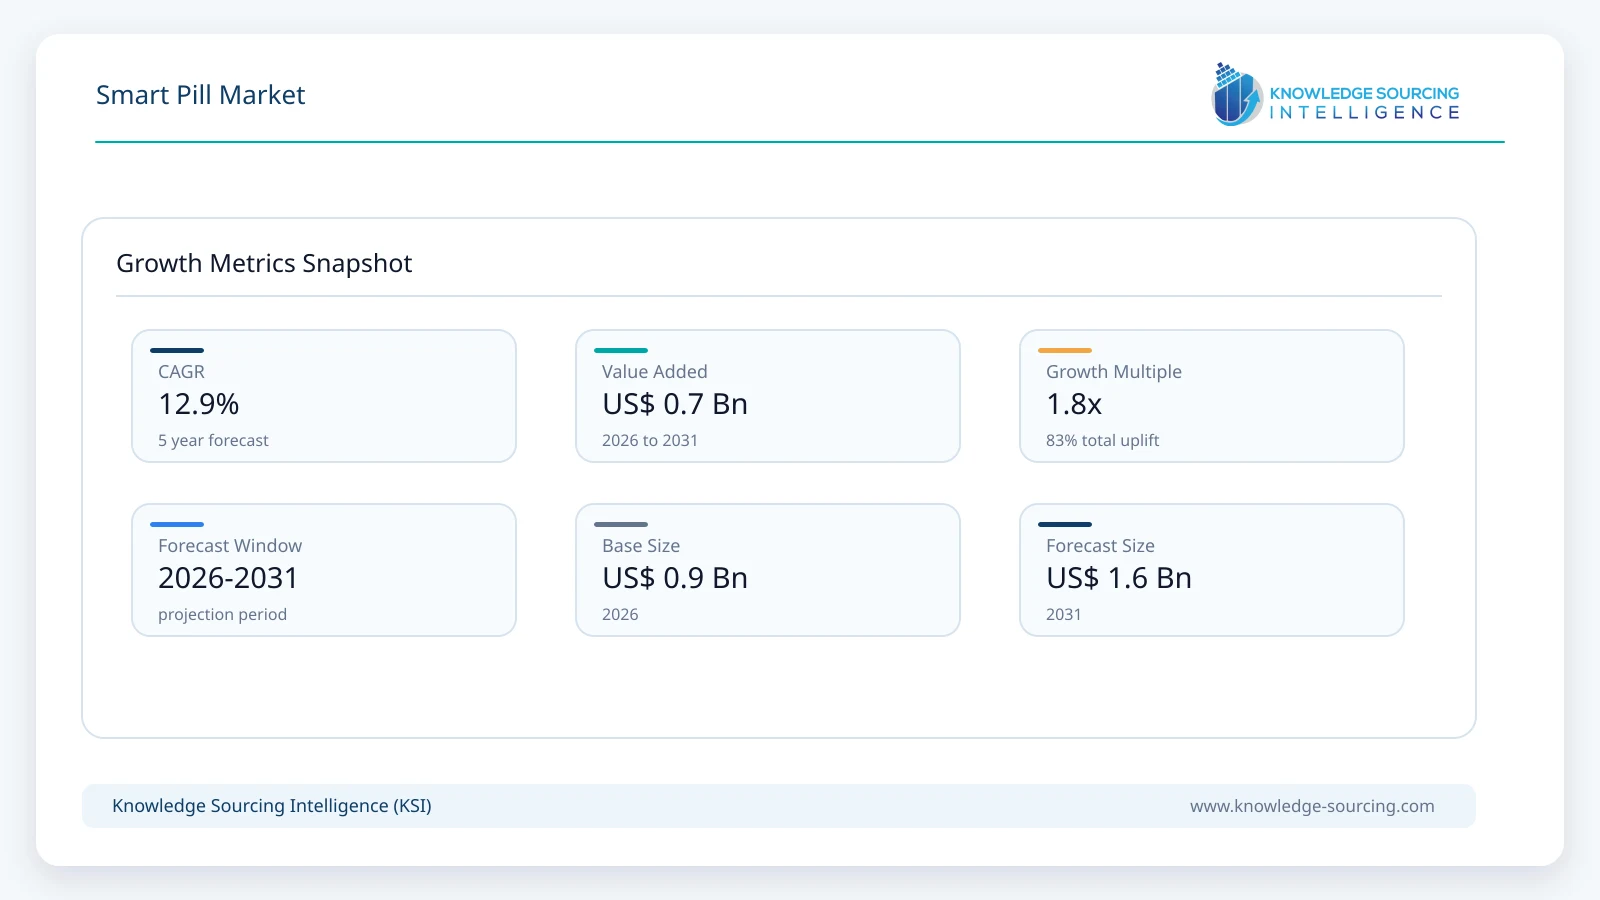
The global Smart Pill market is forecast to grow at a CAGR of 12.89%, reaching USD 1.65 billion in 2031 from USD 0.90 billion in 2026.
Highlights:
- 1Diagnostic Smart Pills dominate the product landscape, representing 75.0% of the global market in 2026, with revenues estimated at USD 0.675 billion, reflecting the strong adoption of ingestible diagnostic technologies for gastrointestinal and internal health monitoring.
- 2Capsule Endoscopy remains the leading application area, capturing 66.0% of total market value in 2026, equivalent to approximately USD 0.594 billion, supported by increasing preference for minimally invasive diagnostic procedures.
- 3Hospitals and Clinics account for the largest end-user contribution, generating an estimated USD 0.504 billion in 2026 and maintaining their position as the primary deployment setting for smart pill technologies worldwide.
- 4North America continues to lead regional demand, holding 41.0% of the global market in 2026, valued at nearly USD 0.369 billion, driven by advanced healthcare infrastructure and early adoption of digital health innovations.
- 5Smart pills are increasingly being integrated into remote care and monitored home healthcare models. This shift is supported by evolving telehealth policies and the need to manage aging populations with chronic diseases outside of traditional hospital settings.
- 6Beyond imaging, the market is evolving toward medication adherence monitoring. These smart pill-based solutions offer an objective mechanism for verifying drug ingestion under clinical supervision, which is critical for treating complex chronic conditions.
The advancement of smart pill and capsule endoscopy technology is increasingly driven by miniaturized imaging components, adaptive data acquisition, wireless transmission, and software designed to convert large volumes of gastrointestinal data into clinically useful information. Current commercial systems demonstrate how these technologies are being integrated into compact ingestible devices. For example, Medtronic’s PillCam SB 3 capsule measures 11.4 mm in diameter, weighs 3.0 g, operates for at least eight hours, and uses an adaptive frame rate of up to 6 frames per second to adjust image capture according to capsule movement through the small bowel. The system also transmits imaging data through an external sensor array, illustrating the importance of power management, communication efficiency, and reliable data collection within a very small device.
Artificial intelligence is becoming an increasingly important digital layer around capsule-based diagnostics. In March 2026, the U.S. Food and Drug Administration determined that Digestaid’s Deep Capsule AI-assisted reading software was substantially equivalent to an existing gastrointestinal capsule-endoscopy analysis device. The software is designed to assist clinicians in reviewing small-bowel capsule images for suspected bleeding and reduce image-review time, while retaining clinician responsibility for interpretation and clinical decision-making. FDA records also describe this device category as using software algorithms, including convolutional neural networks, to identify areas of interest and provide information on the anatomical location represented in capsule images.
Cloud connectivity is also extending the utility of capsule-generated data beyond the ingestible device itself. Medtronic’s PillCam Genius SB system combines an ingestible capsule with a wearable link device that receives and stores images, sends commands to the capsule, and provides patient notifications. Its associated cloud reader platform enables healthcare providers to review capsule studies remotely, while the system is designed to support appropriate at-home or hybrid capsule ingestion. These developments indicate a broader shift from standalone capsule imaging toward connected diagnostic workflows in which acquisition, transmission, software-assisted review, and remote access operate as an integrated ecosystem.
Consequently, smart pills are evolving beyond the concept of an ingestible camera toward digitally connected diagnostic platforms capable of generating, transmitting, organizing, and assisting with the interpretation of gastrointestinal information. At the regulatory level, the FDA's continued clearance of AI-enabled capsule-endoscopy analysis software during 2025–2026 demonstrates growing acceptance of software-assisted interpretation as a clinical support technology. However, current regulatory clearances emphasize that AI outputs support rather than replace clinician assessment, reinforcing the importance of human oversight, data quality, and clinical validation as smart pill technologies become more sophisticated.
Market Dynamics
Market Drivers
Clinical Need for Minimally Invasive Diagnostics: A core driver of the smart pill market is the patient and provider preference for non-invasive procedures. Capsule endoscopy provides a comprehensive view of the digestive tract that is not fully accessible via conventional endoscopy, reducing patient discomfort and the need for sedation.
Advancements in AI and Data Analytics: The incorporation of artificial intelligence into image review workflows has significantly reduced physician reading time and enhanced diagnostic accuracy. AI helps in identifying anomalies within thousands of captured images, making the technology more scalable for large-scale clinical use.
Aging Global Population: The growing demographic of elderly patients increases the prevalence of chronic diseases and gastrointestinal issues. Smart pills provide a safe, effective way to monitor these patients remotely, aligning with global shifts toward decentralized healthcare.
Strategic Pharmaceutical Partnerships: Pharmaceutical companies are exploring digital therapeutic support tools, using smart pills to track treatment efficacy and ensure adherence during clinical trials and commercial drug deployment.
Market Restraints and Opportunities
High Development Complexity: The smart pill market faces significant challenges regarding the development complexity and rigorous regulatory requirements for drug-device combinations. These hurdles remain a primary constraint on rapid market expansion into therapeutic applications.
Reimbursement Inconsistency: Variability and complexity in reimbursement frameworks for digital and ingestible technologies limit purchasing incentives for hospitals. In many regions, the lack of standardized coding for smart pill procedures hinders widespread adoption.
Battery and Data Challenges: Concerns regarding battery life for long-transit diagnostics and the cybersecurity risks associated with transmitting personal health data from the device to the cloud must be continuously addressed by manufacturers.
Therapeutic Delivery Opportunities: Significant opportunities exist in the development of targeted drug delivery. Smart pills designed to release biologics or high-potency drugs at specific sites in the GI tract can improve efficacy while reducing systemic side effects, creating entirely new revenue models for the pharmaceutical sector.
Raw Material and Pricing Analysis
Smart pill manufacturing relies on a combination of medical-grade polymers, electronic sensors, imaging components, batteries, and wireless communication modules. The cost structure is influenced by stringent biocompatibility requirements, precision manufacturing processes, and regulatory compliance testing. Diagnostic capsules, particularly those used for endoscopy, require high-resolution imaging sensors and reliable power sources, contributing to higher unit costs compared to conventional diagnostic tools.
Pricing variability is influenced by production scale, component sourcing, and regulatory certification costs. Established manufacturers benefit from economies of scale and long-term supplier relationships, while smaller or emerging companies often face higher per-unit production costs. As component miniaturization advances and manufacturing processes mature, gradual cost optimization is expected; however, pricing for advanced or multifunctional smart pills is likely to remain elevated due to development and validation expenses.
Supply Chain Analysis
The smart pill supply chain is characterized by a high degree of specialization and regulatory oversight. Core components such as imaging sensors and microelectronics are typically sourced from established electronics manufacturing regions, including North America, Europe, and East Asia. Assembly and final device integration often occur in controlled environments to meet medical device quality standards.
Supply chain resilience is increasingly important due to the sensitive nature of components and the need for consistent quality. Manufacturers are placing greater emphasis on supplier qualification, traceability, and redundancy to mitigate disruptions. For therapeutic smart pills, collaboration between pharmaceutical companies and device manufacturers adds an additional layer of complexity, requiring alignment across drug formulation, device engineering, and regulatory strategy.
Government Regulations
Region | Regulatory Authority | Impact on Market |
United States | Food and Drug Administration (FDA) | Regulates smart pills as medical devices or drug-device combinations, with approvals granted for specific indications and patient populations |
European Union | European Medicines Agency (EMA) / MDR | Imposes strict safety, performance, and traceability requirements for ingestible medical devices |
China | National Medical Products Administration (NMPA) | Governs local approval and commercialization, influencing domestic manufacturing competitiveness |
Global | ISO and IEC Standards | Establish quality and safety benchmarks for medical electronics and biocompatible materials |
Key Developments
August 2026: CapsoVision advanced its AI capsule endoscopy platform, completing the international commercial launch of its AI-assisted reading feature, AI Highlights™, for CapsoCam Plus® in the EU, anticipating U.S. FDA clearance in Q3 2026, and keeping CapsoCam Colon™ on track for Q4 2026 510(k) submission.
July 2026: AnX Robotica launched NaviCONNECT™, a cloud platform connecting its NaviCam® capsule endoscopy portfolio, enabling remote access to capsule studies, reporting, workflow management, and future AI integration.
May 2026: Atmo Biosciences received FDA clearance for its GI Contractility Frequency Map, an enhancement to the Atmo ingestible gas-sensing capsule platform, providing clinicians additional gastrointestinal contraction data for motility assessment.
Market Segmentation
By Product Type: Diagnostic Smart Pills
Diagnostic smart pills are the foundation of the current market implementation, accounting for a projected 69.1% share by 2031 and expanding at an 11% CAGR. These devices are capable of capturing high-resolution images and sensing physiological markers such as pH levels, pressure, and temperature. As governments worldwide support digital health infrastructure, diagnostic capsules are facilitating more frequent screening programs and reducing the burden on traditional endoscopy suites. The rapid acceptance of these pills means they are becoming a scalable mobile diagnostic medium within the modern medical ecosystem.
By Application: Capsule Endoscopy
Capsule endoscopy represents the most established and commercially mature segment within the smart pill market, accounting for 60.5% of the market in 2031. The clinical need to diagnose small bowel disorders that are difficult to assess using conventional endoscopic techniques drives this demand. The ingestible capsule enables full-length gastrointestinal imaging with minimal patient discomfort, supporting its use in both initial diagnosis and follow-up monitoring.
Technological advancements have improved image resolution, battery life, and data analysis efficiency. The incorporation of artificial intelligence into image review workflows has reduced physician reading time and enhanced diagnostic accuracy. These improvements have reinforced the role of capsule endoscopy as a standard diagnostic option in gastroenterology, supporting its leading market position and sustaining consistent demand from hospitals and specialty clinics.
By End-Use: Home Healthcare Settings
Home healthcare represents a significant end-use segment for smart pills, supported by increasing demand for remote monitoring and medication adherence solutions. Aging populations and the rising prevalence of chronic diseases are strengthening the need for technologies that enable effective patient management outside traditional clinical environments. In 2026, home healthcare accounts for 56.0% of the smart pills market, reflecting the growing adoption of connected solutions for monitoring medication adherence and selected physiological parameters remotely.
Adoption in this segment remains closely linked to telehealth infrastructure, remote patient monitoring capabilities, and payer support for home-based care services. By 2031, the segment’s share is expected to moderate to 53.5%, although its overall market presence will continue expanding. The gradual shift toward decentralized care models, improved digital health connectivity, and greater emphasis on reducing unnecessary hospital visits is expected to sustain demand for smart pills in home healthcare applications.
Regional Analysis
North America Market Analysis
North America retains a leading position in the smart pill market, accounting for 39.9% of the global market share in 2031, supported by its established healthcare infrastructure, regulatory clarity from the FDA, and relatively favorable reimbursement conditions. The United States, in particular, has witnessed high adoption of minimally invasive diagnostics, supported by major industry players and a high prevalence of gastrointestinal disorders. The integration of smart pill data into digital health platforms is well advanced in the region, as healthcare providers increasingly seek to improve patient outcomes through objective data collection.
South America Market Analysis
The smart pill market in South America is currently in a developing phase, with demand primarily concentrated in private healthcare facilities in countries like Brazil and Argentina. While public sector reimbursement limitations constrain broader adoption, growing urban populations and increasing awareness of non-invasive diagnostic options are supporting selective uptake. As regional healthcare transformation initiatives gain momentum, there is a significant opportunity for the implementation of smart pills in specialized clinics focusing on chronic disease management.
Europe Market Analysis
Europe is a highly sophisticated market for smart pills, characterized by high clinical standards and integration within structured national health insurance systems. In countries like Germany and the United Kingdom, diagnostic accuracy requirements and strong hospital infrastructure drive demand. The European Union’s focus on digital health and data interoperability provides a supportive environment for the adoption of smart pill technologies. Several European countries are leading pilots in utilizing ingestible sensors to stabilize healthcare costs by moving diagnostic procedures from inpatient to outpatient or home settings.
Middle East and Africa Market Analysis
The Middle East and Africa region is in the early stages of smart pill adoption but shows significant growth potential, particularly in the Gulf states. Saudi Arabia and the UAE are investing heavily in healthcare modernization as part of their national sustainability visions. Government-funded hospitals and specialized medical cities are the primary adopters of advanced diagnostic technologies. In Africa, the focus remains on improving basic diagnostic capabilities, where smart pills could eventually play a role in providing high-end diagnostics in regions lacking traditional endoscopic facilities.
Asia Pacific Market Analysis
The Asia Pacific region is a rapidly evolving market for smart pill technology, driven by massive population sizes, increasing healthcare expenditure, and expanding access to diagnostic services. China and Japan have taken significant steps in developing domestic smart pill solutions and establishing regulatory frameworks for their use. The segment is valued at USD 0.207 billion in 2026, representing 23.0% of the market, and is projected to increase its share to 24.5% by 2031. The integration of these devices into the digital grid of smart hospitals in South Korea and Australia is enabling more efficient patient throughput. The rise of private healthcare groups across India and Southeast Asia is also creating a high demand for advanced, non-invasive diagnostic tools that appeal to a growing middle class.
List of Companies
Medtronic
Olympus
CapsoVision
Rani Therapeutics
Check-Cap
IntroMedic
Ankon Medical Technologies
Jinshan Science and Technology
PillDrill
etectRx
Medtronic
Medtronic is the primary authority in the capsule endoscopy market. Its PillCam™ platform has set the global standard for non-invasive gastrointestinal imaging for over two decades. The system works by capturing images at a high frame rate, which are then transmitted to a recording device worn by the patient. Medtronic's software utilizes advanced algorithms to highlight potential areas of interest, such as bleeds or lesions, significantly reducing the diagnostic burden on gastroenterologists. The company’s global reach and established relationships with insurance providers make it the cornerstone of the smart pill industry.
Olympus
Olympus utilizes its deep heritage in optical technology to offer some of the highest-resolution capsule endoscopy systems on the market. Its software platforms are designed for high-volume hospital environments, allowing for rapid data download and streamlined report generation. Olympus focuses on the integration of capsule data with traditional endoscopic records, providing a holistic view of a patient’s gastrointestinal health. The company is currently investing in next-generation sensors to expand the diagnostic capabilities of its ingestible line.
CapsoVision
CapsoVision distinguishes itself through its "lead-less" technology. Unlike other systems that require the patient to wear a belt or sensors to capture data, the CapsoCam system stores all data directly on the capsule. Once the capsule is retrieved, the data is downloaded via a specialized docking station. This significantly improves the patient experience by allowing them to go about their normal activities without bulky external equipment. Their recent move into the pediatric market highlights their strategy of targeting underserved clinical demographics.
Smart Pill Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.90 billion |
| Total Market Size in 2031 | USD 1.65 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.89% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Disease Indication, Application, End Users |
| Companies |
|
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Reimbursement Scenario
3.8. Impact of AI and Digital Health Integration
3.9. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. SMART PILL MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Diagnostic Smart Pills
5.3. Drug Delivery Smart Pills
5.4. Monitoring and Adherence Smart Pills
6. SMART PILL MARKET BY DISEASE INDICATION
6.1. Introduction
6.2. Gastrointestinal Disorders
6.3. Neurological Disorders
6.4. Cardiovascular Diseases
6.5. Oncology
6.6. Infectious Diseases
6.7. Others
7. SMART PILL MARKET BY APPLICATION
7.1. Introduction
7.2. Capsule Endoscopy
7.3. Drug Delivery
7.4. Patient Monitoring and Medication Adherence
8. SMART PILL MARKET BY END USERS
8.1. Introduction
8.2. Hospitals and Clinics
8.3. Ambulatory Surgical Centers
8.4. Home Healthcare Settings
8.5. Diagnostic Laboratories
9. SMART PILL MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Thailand
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Medtronic plc
11.2. Olympus Corporation
11.3. CapsoVision, Inc.
11.4. Rani Therapeutics Holdings, Inc.
11.5. Otsuka America Pharmaceutical, Inc.
11.6. Check-Cap Ltd.
11.7. IntroMedic Co., Ltd.
11.8. etectRx, Inc.
11.9. AnX Robotica Corp.
11.10. Koninklijke Philips N.V.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF TABLES
LIST OF FIGURES
Navigate
Trusted by the world's leading organizations











