
The South America Bioadhesive Market is forecast to grow at a CAGR of 7.6%, reaching USD 0.39 billion in 2031 from USD 0.27 billion in 2026.
Highlights:
- 1Mandatory Reverse LogisticsBrazilian Decree No. 12,688 forces companies to recover 32% of plastic packaging by 2026, driving demand for adhesives that enable easier material separation.
- 2Feedstock AccessibilityAbundant regional supplies of corn, soy, and sugarcane derivatives are lowering the cost barriers for large-scale plant-based adhesive production.
- 3Healthcare ModernizationIncreasing adoption of biocompatible and non-toxic adhesives in medical wound care and surgical applications is accelerating demand for high-purity animal and plant derivatives.
- 4Green Building CertificationGrowing participation in sustainable construction standards is pushing contractors toward bio-based binders to meet low-VOC requirements for indoor air quality.
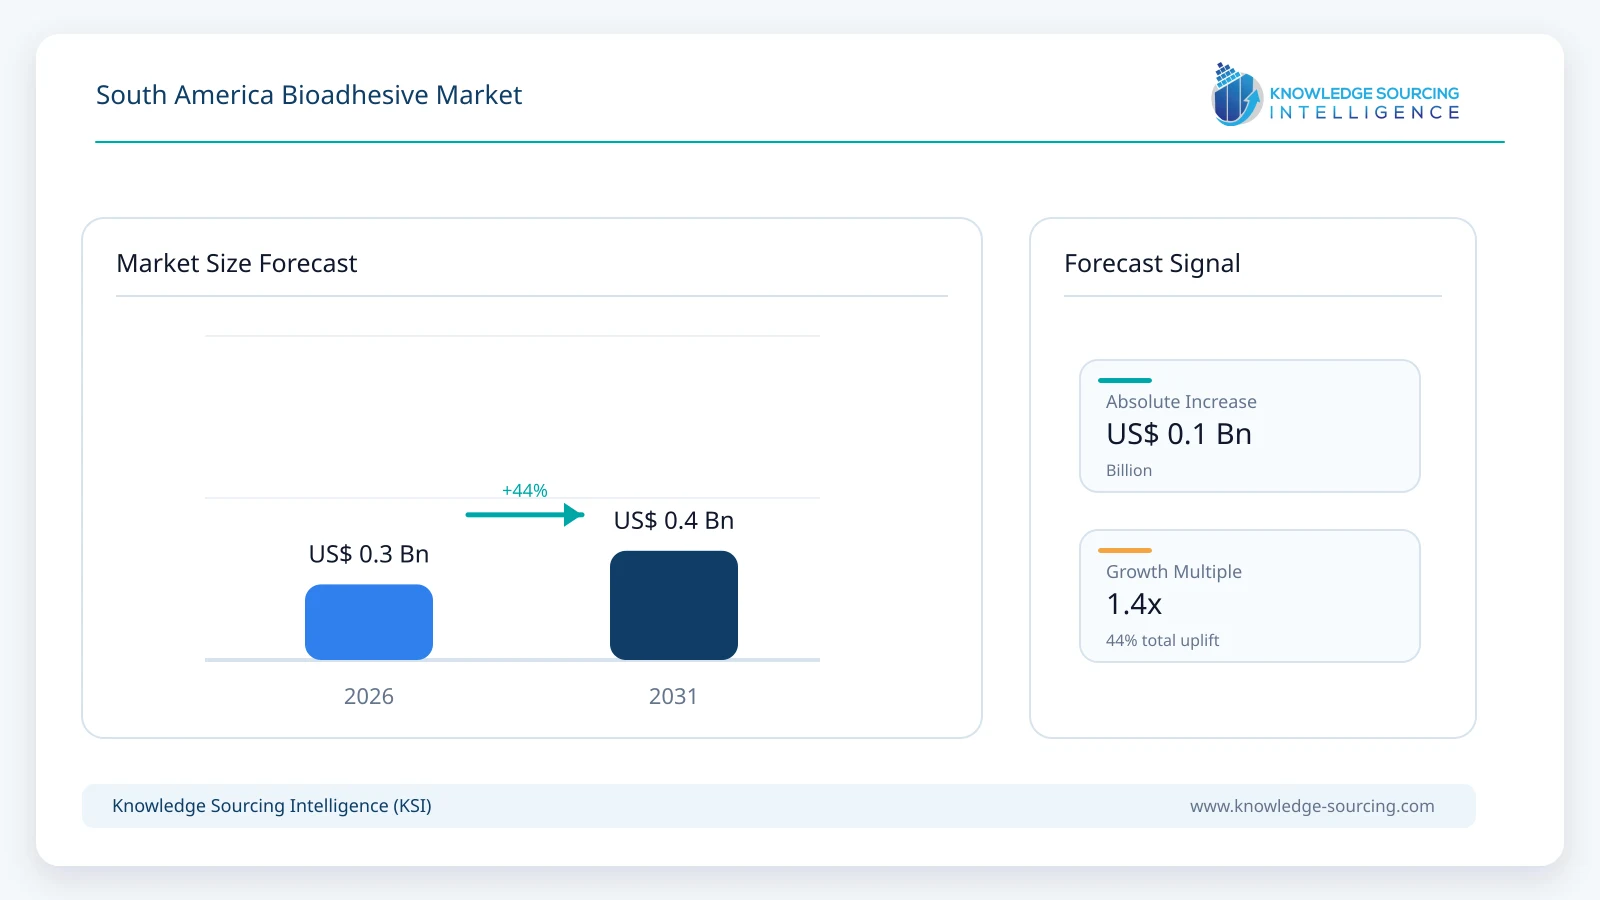
South America's bioadhesive market is undergoing a structural realignment driven by aggressive environmental legislation and a shift in corporate sustainability mandates. Brazil and Argentina are emerging as central hubs for this transition due to their massive agricultural feedstock availability, which provides a localized supply chain advantage for plant-based formulations. Regulatory influence is peaking, particularly in Brazil, where new decrees now mandate specific percentages of recycled content and reverse logistics for plastic packaging. This creates a critical strategic dependency on bio-based adhesives that do not contaminate recycling streams or impede the biodegradation of compostable materials. Consequently, major industrial players are prioritizing the integration of these adhesives to maintain market access and avoid non-compliance penalties under evolving regional environmental frameworks.
Market Dynamics
Market Drivers
Regulatory Compulsion: Brazil’s mandate for 22% minimum recycled content in plastic packaging by 2026 necessitates adhesives that are compatible with recycling processes.
Petrochemical Volatility: Fluctuating oil prices are encouraging manufacturers to shift toward stable, locally sourced biological feedstocks to secure long-term margin predictability.
Consumer Sentiment: Rising regional awareness regarding plastic pollution is forcing consumer goods brands to transition toward fully compostable packaging solutions.
Technological Maturation: Innovations in fermentation and cross-linking are closing the performance gap between bio-based and synthetic adhesives, making them viable for heavy-duty construction.
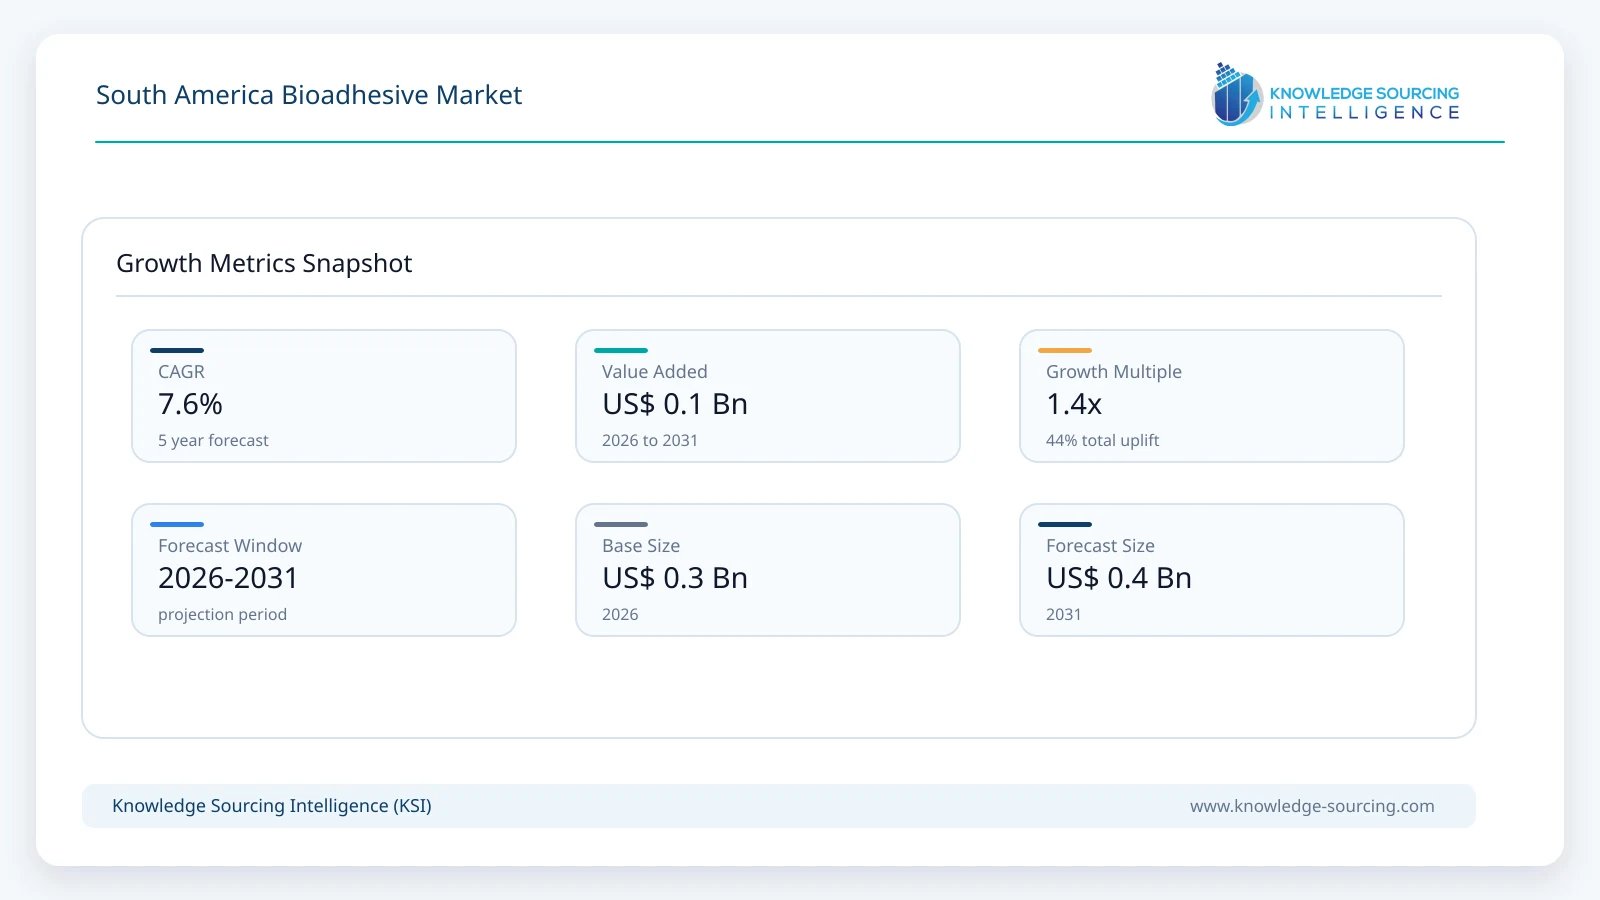
Restraints and Opportunities
Cost Sensitivity: Higher initial price points compared to traditional synthetics remain a constraint for small and medium-sized enterprises in developing regional economies.
Technical Limitations: Moisture resistance and shelf-life stability in humid tropical climates present ongoing engineering challenges for certain plant-based formulations.
Agricultural Diversification (Opportunity): Utilizing non-food crop residues as adhesive precursors offers a path to lower costs without competing with regional food security.
Nearshoring Synergy (Opportunity): South American production hubs are increasingly positioned to export bio-based products to North American markets seeking sustainable supply chain alternatives.
Supply Chain Analysis
The regional supply chain is shifting toward a vertically integrated model to mitigate raw material price fluctuations. Manufacturers are securing direct contracts with agricultural processors to guarantee the supply of starch, soy, and lignin. Digital tracking tools are being implemented to meet the transparency requirements of Brazil’s new reverse logistics laws. Regional distribution networks are expanding to provide localized technical support, ensuring that bioadhesive performance is optimized for the specific machinery used in South American packaging lines.
Government Regulations
Regulation/Policy | Country/Region | Impact on Market |
Decree No. 12,688 (2025) | Brazil | Mandates 22% recycled content in packaging by 2026, forcing the use of recycling-compatible adhesives. |
National Solid Waste Policy (PNRS) | Brazil | Assigns shared responsibility across the product lifecycle, driving demand for compostable bonding solutions. |
Environmental Classification Standards | Regional | Increasing regulatory measures for lower emission rates augment the necessity for low-VOC bioadhesives. |
Key Developments
Jowat SE Packaging Launch (March 2026): Jowat is premiering its Jowatherm® PO line at Interpack 2026, focusing on high-speed packaging adhesives that minimize stringing and improve process efficiency.
Henkel Bio-based Initiative (Feb 2026): Henkel is accelerating the transition from fossil-based to bio-based raw materials by replacing conventional ethyl acetate with sustainable alternatives in its adhesive formulations.
Market Segmentation
By Source
Plant-based sources are dominating the regional market due to the vast availability of agricultural starch and soy in Brazil and Argentina. Manufacturers are increasingly adopting these derivatives because they offer a drop-in solution for existing production lines without requiring extensive equipment overhauls. Animal-based adhesives, derived from collagen and casein, are maintaining a specialized niche in high-end woodworking and specific medical applications where high tack is required. This reliance on biological feedstocks is reducing the industry's exposure to global petrochemical supply shocks.
By Industry Vertical
The packaging and consumer goods sector is leading the demand shift as brands respond to Brazil’s 2026 recycled content mandates. Construction firms are gradually integrating bio-based binders into engineered wood and insulation to satisfy green building certifications and regional air quality standards. Healthcare providers are increasing their utilization of medical-grade bioadhesives for wound closure to minimize the risk of skin irritation and toxic leaching. These diverse industrial requirements are forcing adhesive producers to develop sector-specific formulations that balance performance with environmental compliance.
By Country
Brazil is functioning as the primary regional engine for bioadhesive growth as it implements the continent’s most stringent waste management and reverse logistics laws. Argentina is positioned as the fastest-growing market in the region, leveraging its robust paper and pulp industry to integrate bio-based bonding agents into export-grade packaging. Other regional economies are gradually aligning their environmental standards with the MERCOSUR framework, creating a broader, harmonized market for sustainable materials. This regional concentration is encouraging global players to establish local manufacturing and R&D centers within South American borders.
Regional Analysis
The South American landscape is being reshaped by the "Lula Decree" in Brazil, which effectively transforms recycled content from a voluntary ESG goal into a mandatory legal obligation by 2026. Argentina is capitalizing on this shift by expanding its capacity for elastic and bio-based adhesives to serve both domestic and regional industrial needs. Regional demand is concentrating in industrial corridors where proximity to agricultural feedstocks allows for lower logistics costs and a reduced carbon footprint. These developments are solidifying South America's role as a self-sufficient ecosystem for bioadhesive innovation and adoption.
List of Companies
Henkel AG & Co. KGaA
DuPont de Nemours, Inc.
Arkema S.A.
Ashland Global Holdings Inc.
Paramelt B.V.
Jowat SE
Ingredion Incorporated
EcoSynthetix Inc.
Tate & Lyle PLC
H.B. Fuller Company
Company Profiles
Henkel AG & Co. KGaA: Strategically distinct for its large-scale replacement of fossil-based ethyl acetate with bio-based alternatives, the company is positioning itself as a leader in "drop-in" sustainable industrial solutions.
Jowat SE: Distinguished by its focus on process efficiency, the company is launching new granulate-form adhesives for automated feed systems to support high-speed, low-waste packaging operations.
H.B. Fuller Company: Notable for its rigorous medical-grade testing, the company is successfully capturing the healthcare segment with ISO-certified, non-toxic adhesives designed for direct skin contact.
Analyst View
South America is evolving into a critical proving ground for bioadhesive scalability. The convergence of abundant biological feedstocks and strict new Brazilian packaging mandates is forcing a permanent structural shift from synthetic to bio-based solutions across the continent’s manufacturing base.
South America Bioadhesive Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.27 billion |
| Total Market Size in 2031 | USD 0.39 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Source, Industry Vertical, Country |
| Companies |
|
Market Segmentation
By Source
Plant Based
Animal Based
By Industry Vertical
Packaging
Construction
Healthcare
Consumer Goods
Others
By Country
Brazil
Argentina
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.3. Market Definition
1.4. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Force Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. SOUTH AMERICA BIOADHESIVE MARKET BY SOURCE
5.1. Introduction
5.2. Plant Based
5.3. Animal Based
6. SOUTH AMERICA BIOADHESIVE MARKET BY INDUSTRY VERTICAL
6.1. Introduction
6.2. Packaging
6.3. Construction
6.4. Healthcare
6.5. Consumer Goods
6.6. Others
7. SOUTH AMERICA BIOADHESIVE MARKET BY COUNTRY
7.1. Introduction
7.2. Brazil
7.3. Argentina
7.4. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Emerging Players and Market Lucrativeness
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. Henkel AG & Co. KGaA
9.2. DuPont de Nemours, Inc.
9.3. Arkema S.A.
9.4. Ashland Global Holdings Inc.
9.5. Paramelt B.V.
9.6. Jowat SE
9.7. Ingredion Incorporated
9.8. EcoSynthetix Inc.
9.9. Tate & Lyle PLC
9.10. H.B. Fuller Company
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











