
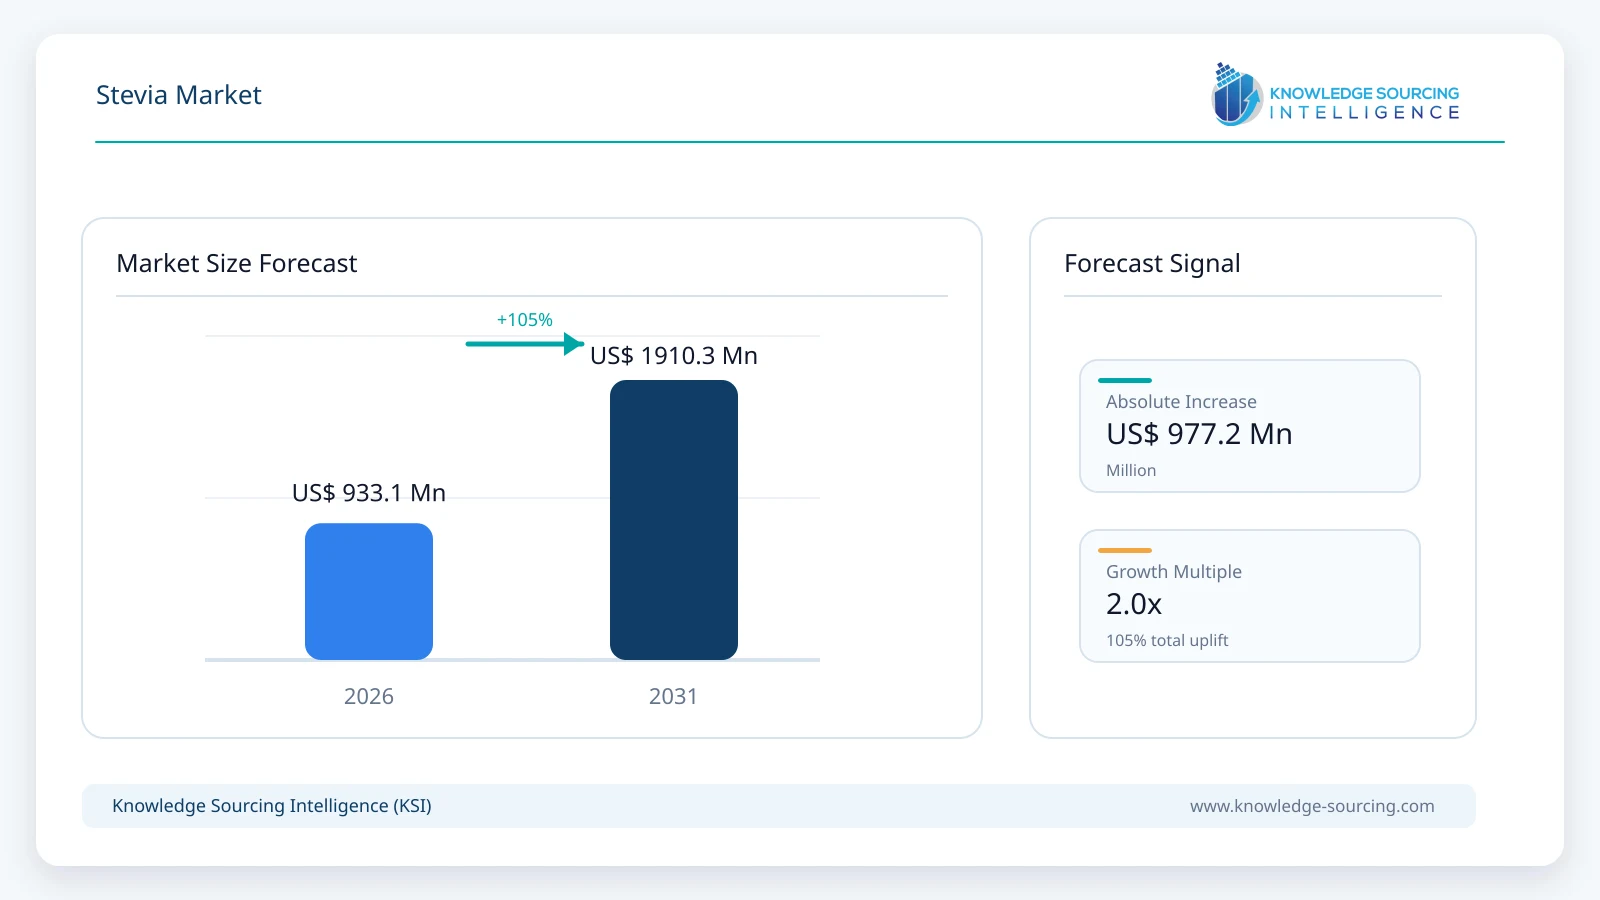
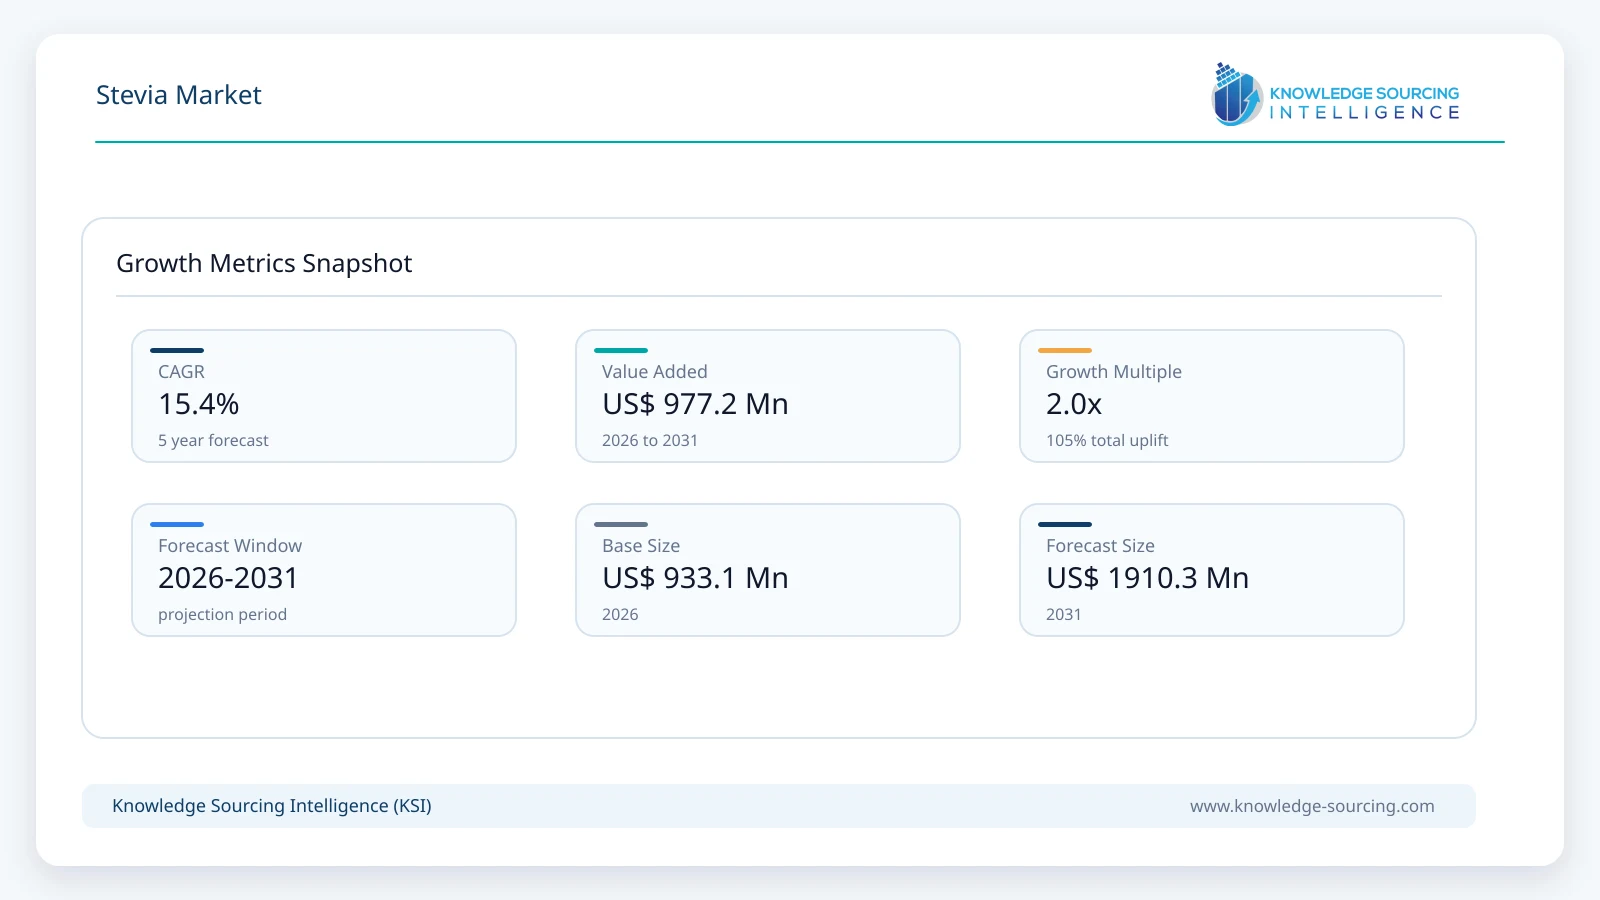
The Stevia Market is forecast to grow at a CAGR of 15.4%, reaching USD 1,910.3 million in 2031 from USD 933.1 million in 2026.
Highlights:
- 1Sugar reduction remains the principal commercial catalyst, particularly in beverages, dairy, tabletop sweeteners, and reduced-sugar packaged foods.
- 2Powdered and refined steviol glycosides remain commercially important because manufacturers require consistent potency, handling characteristics, and formulation performance.
- 3Asia Pacific has a structurally important supply position, supported by stevia cultivation, processing capabilities, and large food and beverage manufacturing bases.
- 4Fermentation and enzymatic conversion are expanding the usable glycoside portfolio, particularly for Reb M and other minor glycosides with improved sensory performance.
- 5Regulatory distinctions between crude stevia and purified steviol glycosides materially influence product economics, market access, and formulation decisions.
- 6Traceability and responsible sourcing are becoming procurement requirements, particularly for multinational food manufacturers with human-rights and supply-chain due-diligence commitments.
The Stevia Market covers the commercial production, processing, formulation, distribution, and sale of stevia-derived sweetening ingredients used across food, beverage, tabletop, and dairy applications. The market includes leaf-based products and refined steviol glycosides, with commercial offerings increasingly differentiated by purity, glycoside profile, taste performance, production route, and application suitability.
Stevia occupies a distinct position within the high-intensity sweetener category because manufacturers can achieve substantial sweetness with very small inclusion rates. The U.S. Food and Drug Administration states that certain high-purity steviol glycosides have been the subject of GRAS notices and are used as general-purpose sweeteners under their intended conditions of use. FDA also distinguishes these purified ingredients from whole-leaf and crude stevia extracts, which are not permitted as sweeteners in the United States.
The commercial importance of stevia therefore depends less on agricultural volume than on the value created during extraction, purification, glycoside selection, formulation, and application support. A small quantity of high-purity ingredient can replace a much larger quantity of sucrose in a formulation. This economics makes stevia particularly relevant to beverage, dairy, confectionery, tabletop sweetener, and reduced-sugar product manufacturers.
Buyer priorities have also moved beyond sweetness intensity. Large food and beverage manufacturers evaluate stevia according to taste profile, onset and duration of sweetness, aftertaste, solubility, thermal stability, compatibility with acids and proteins, label positioning, regulatory status, supply reliability, and cost-in-use. These criteria favor suppliers capable of supporting formulation work rather than simply supplying a commodity sweetener.
The supply structure contains agricultural producers, extraction and purification specialists, ingredient manufacturers, formulation partners, branded tabletop suppliers, and food and beverage companies. Competition consequently occurs at several levels. Leaf availability and agricultural quality influence upstream economics, while purification technology and glycoside composition influence downstream pricing and application performance.
Technology is becoming particularly important because the most desirable steviol glycosides occur naturally in relatively small quantities within the stevia leaf. Suppliers have therefore developed enzymatic conversion, bioconversion, and fermentation-based routes to obtain specific glycosides such as Rebaudioside M and Rebaudioside D. Cargill, for example, describes EverSweet as a fermentation-produced stevia sweetener based on Reb M and Reb D, while ADM describes its SweetRight Stevia Echo portfolio as using bioconversion to convert major steviol glycosides into minor glycosides.
The regulatory framework is also shaping commercial product development. Codex Alimentarius identifies steviol glycosides under INS 960 and now distinguishes several production routes, including steviol glycosides from Stevia rebaudiana, fermentation, enzymatic production, and glucosylation.
For the 2026–2031 period, market development will therefore depend on the ability of suppliers to combine regulatory compliance, predictable raw-material sourcing, improved taste, scalable processing, application support, and competitive cost-in-use. The supplied input does not include a market-size estimate or CAGR; therefore, no unsupported market value or growth rate is introduced in this RD.
Market Drivers
Expansion of Sugar-Reduction Formulation
Food and beverage manufacturers are under continuing pressure to reduce sugar while maintaining acceptable taste and consumer familiarity. Stevia provides an option for reducing sucrose content without relying solely on synthetic high-intensity sweeteners.
The commercial mechanism is straightforward: steviol glycosides deliver high sweetness intensity at low inclusion rates, reducing the quantity of caloric sugar required in a formulation. FDA identifies high-intensity sweeteners as ingredients used across products including baked goods, soft drinks, powdered beverages, candy, puddings, jams, dairy products, and other foods and beverages.
For manufacturers, however, sugar reduction is not simply an ingredient substitution exercise. Sugar contributes sweetness, bulk, texture, browning, freezing-point depression, and mouthfeel. Stevia primarily addresses sweetness. Formulators therefore frequently combine it with bulking agents, fibers, polyols, flavors, or other sweeteners.
This creates commercial opportunities for suppliers offering formulation systems rather than isolated stevia ingredients. Cargill, for example, positions its stevia products alongside complementary sweeteners, fibers, and texturizing ingredients for reduced-sugar formulations.
Demand for Improved Taste Profiles
Sensory performance remains one of the most important constraints on stevia adoption. Traditional steviol glycoside systems can produce bitterness, lingering sweetness, or other sensory characteristics at higher use levels. Manufacturers therefore increasingly seek specific glycoside compositions rather than generic stevia extracts.
Reb M and Reb D are particularly relevant because suppliers have developed technologies to increase their commercial availability. Cargill produces Reb M and Reb D through fermentation, while ADM's Echo platform uses enzymatic conversion of major glycosides into minor glycosides.
The commercial implication is a shift from selling stevia principally on sweetness intensity toward selling performance characteristics. Suppliers that can reduce aftertaste while maintaining cost-effective sugar reduction can compete for applications where conventional stevia had previously faced formulation limitations.
Expansion of Reduced-Sugar Beverages
Beverages remain particularly compatible with high-intensity sweeteners because sweetness is a major formulation component while physical bulk requirements are comparatively limited.
Carbonated drinks, flavored waters, energy drinks, hydration products, ready-to-drink teas, and other beverage categories can therefore use stevia in formulations targeting lower sugar or no added sugar.
The procurement decision is influenced by several variables, including solubility, acid stability, sweetness onset, flavor interactions, regulatory status, and cost per serving. Suppliers increasingly provide application-specific systems to address these variables.
Cargill's current product portfolio, for instance, identifies beverages, confectionery, dairy, protein drinks, snacks, and cereals among applications for its stevia solutions.
Development of Alternative Production Technologies
The economics of stevia are closely linked to the composition of the leaf. Desired minor glycosides can represent only a small proportion of naturally occurring steviol glycosides. Producing these molecules through fermentation or enzymatic conversion can reduce dependence on extracting large quantities of leaf material for a relatively small output of a specific glycoside.
This is encouraging investment in production technologies that provide greater consistency and control over glycoside composition. FDA's GRAS inventory demonstrates the continued regulatory activity surrounding alternative production methods. In 2026, FDA issued “no questions” responses for several Rebaudioside M preparations produced through enzymatic treatment of purified steviol glycosides or Rebaudioside A.
For ingredient manufacturers, this expands the addressable application base. For food manufacturers, it provides additional choices when balancing taste, label requirements, supply security, and cost.
Greater Supply-Chain Scrutiny
Multinational food companies increasingly assess agricultural supply chains through traceability, labor standards, sourcing geography, and environmental criteria. Stevia suppliers are consequently being evaluated on upstream controls as well as ingredient specifications.
Ingredion's 2025 sustainability disclosure identifies stevia as a priority agricultural crop and reports that its Tier 1 crops, including stevia, were more than 96% sustainably sourced at a minimum Silver level at the end of 2025. The company also describes traceability and non-Xinjiang sourcing controls associated with its stevia supply chain.
This changes procurement economics. Suppliers able to document farmer relationships, origin, audits, and responsible sourcing can improve their eligibility for multinational contracts, even when their ingredient price is not the lowest available.
Market Restraints and Challenges
Sensory Limitations at Higher Use Levels
Taste remains a core constraint because stevia cannot always replicate sucrose on a one-for-one sensory basis. Bitter or lingering notes can become more noticeable as manufacturers increase inclusion rates.
This affects beverages, dairy products, bakery products, and confectionery formulations differently. A beverage may tolerate certain flavor interactions that become unacceptable in a neutral dairy product. Bakery applications also introduce heat-processing and browning considerations.
Suppliers are mitigating this issue through glycoside selection, enzymatic modification, fermentation, flavor modulation, and blended sweetener systems. The result is higher technical value per kilogram but also greater formulation complexity.
Agricultural and Raw-Material Variability
Leaf-based stevia production remains exposed to agricultural conditions. Crop yields, cultivation practices, weather, disease pressure, labor availability, and farm-level quality can influence the cost and consistency of raw material.
Processors must control moisture, purity, glycoside composition, contaminants, and other specifications before extraction. Inconsistent leaf quality can increase processing costs and complicate customer qualification.
Long-term farmer contracts, agronomic support, traceability systems, and geographically diversified sourcing can reduce these risks. However, these measures also require additional supplier investment.
Regulatory Differences Between Markets
Stevia does not operate under one globally uniform regulatory framework. Countries and regions differ in permitted steviol glycoside types, food categories, maximum use levels, labeling requirements, and authorization procedures.
Codex provides an international reference framework, but individual jurisdictions maintain their own regulatory systems. The United States, for example, permits certain high-purity steviol glycosides under applicable GRAS conditions while restricting whole-leaf and crude extracts as sweeteners.
This creates additional compliance work for multinational manufacturers. Ingredient suppliers must maintain documentation for identity, purity, manufacturing process, intended use, and regulatory status across target markets.
Cost Competition from Alternative Sweeteners
Stevia competes with sugar, sucralose, aspartame, acesulfame potassium, monk fruit, erythritol, allulose, and other sweetening systems. Price comparison alone does not determine competitiveness because different ingredients perform different functions.
Nevertheless, procurement teams increasingly assess cost per finished product rather than ingredient price alone. A more expensive stevia ingredient can remain attractive if it enables greater sugar reduction, requires fewer masking ingredients, or simplifies the label and formulation.
Suppliers therefore face pressure to demonstrate measurable cost-in-use benefits rather than relying solely on natural-origin positioning.
Major Segment Analysis
Beverages by Application
Beverages represent one of the most commercially relevant applications for stevia because manufacturers can reduce sugar without needing stevia to reproduce the physical bulk of sucrose.
The category includes soft drinks, flavored water, sports and hydration beverages, energy drinks, teas, and other ready-to-drink products. Product developers typically seek sweetness systems that dissolve easily, remain stable in acidic formulations, provide a clean sensory profile, and work consistently across large production batches.
Buyer behavior is increasingly application-specific. Beverage companies do not simply purchase “stevia”; they evaluate a particular glycoside composition or blend against the product's flavor base and target sugar reduction.
This is particularly important as beverage manufacturers pursue deeper sugar reductions. At moderate reductions, Reb A-based systems may provide an economical solution. At higher reduction levels, formulators may require Reb M, Reb D, fermentation-derived systems, bioconverted ingredients, or combinations with other sweeteners and flavor modifiers.
The competitive implication is substantial. Suppliers with strong application laboratories and beverage formulation expertise can influence ingredient selection before commercial procurement begins. Once a sweetener becomes embedded in a beverage formula, changing suppliers can require sensory validation, stability testing, regulatory review, and production trials.
Stevia suppliers therefore compete through technical service as much as ingredient specifications. Cargill's current portfolio explicitly positions EverSweet across beverage, confectionery, dairy, protein, snack, and cereal applications, while its application materials describe combinations with complementary ingredients for sugar-reduction formulations.
The beverage segment should consequently remain strategically important through 2031. Its demand will depend on the depth of sugar reduction targeted by manufacturers, the sensory performance of new glycosides, regulatory approvals, and the ability of suppliers to lower cost-in-use.
Regional Analysis
North America
North America represents a mature formulation market where stevia competes within a broad high-intensity sweetener portfolio. The United States has a particularly developed regulatory framework for high-purity steviol glycosides.
FDA has reviewed numerous GRAS notices covering steviol glycosides with different compositions and production methods. Its current guidance also clearly distinguishes high-purity steviol glycosides from whole-leaf and crude stevia extracts.
The commercial market is therefore driven largely by food and beverage manufacturers seeking sugar reduction, calorie reduction, and differentiated ingredient systems. Canada and Mexico add regional opportunities, particularly for suppliers able to support multinational product launches across North American markets.
Competition is increasingly centered on sensory performance and cost-in-use rather than simply the availability of stevia extract. Cargill's EverSweet is approved across the U.S., Canada, Mexico, and EU according to the company's current materials.
Europe
Europe combines strong interest in sugar reduction with detailed regulatory controls for food additives and ingredients.
Steviol glycosides are included within the European regulatory framework, while EFSA continues to evaluate food-additive safety and applications. In 2026, EFSA updated its guidance on data requirements for food-additive applications, covering identity, manufacturing process, composition, stability, proposed uses, dietary exposure, and safety data.
The authorization of fermentation-derived steviol glycosides as E 960b is commercially relevant because it supports newer production technologies.
Demand is concentrated in packaged beverages, dairy, confectionery, and other products where manufacturers seek lower sugar formulations. European procurement also places considerable emphasis on traceability, sustainability documentation, and responsible sourcing.
Asia Pacific
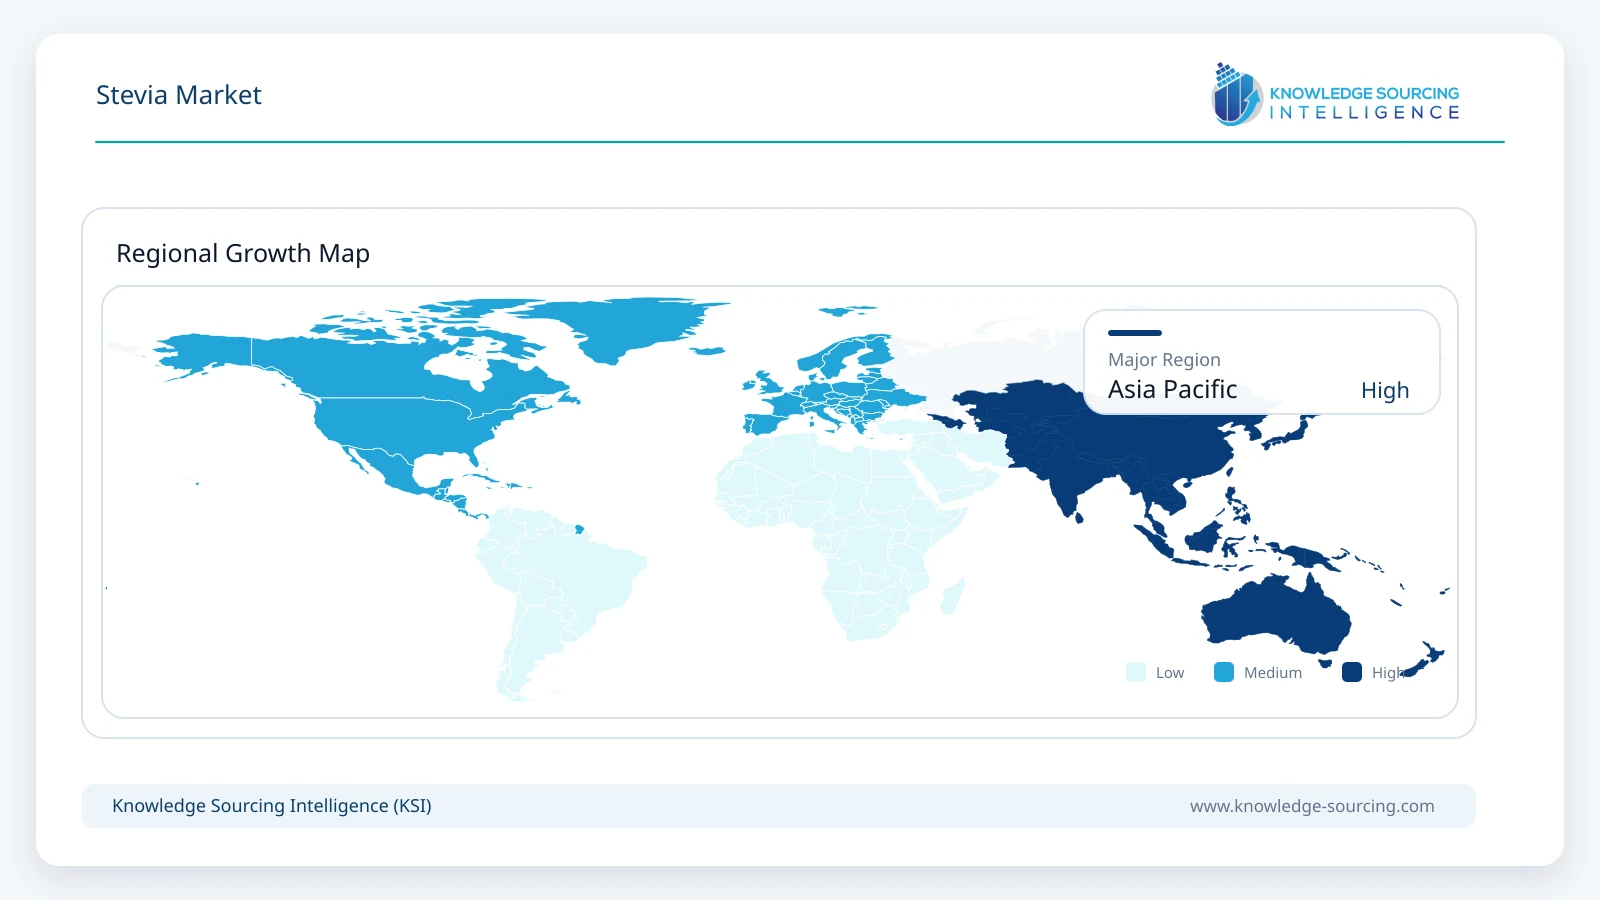
Asia Pacific is strategically important because it combines major food and beverage manufacturing markets with an established stevia cultivation and processing ecosystem.
China is particularly relevant to ingredient manufacturing and processing, while Japan has a long history of high-intensity sweetener use and sophisticated food formulation. India, South Korea, Indonesia, Taiwan, and Thailand provide additional demand through packaged beverages, dairy products, processed foods, and tabletop sweeteners.
The region also has strong relevance for upstream supply. Stevia cultivation and processing economics influence global ingredient availability, while the concentration of manufacturing capacity supports export-oriented supply chains.
The principal constraint is that regional demand is not uniform. Regulatory requirements, consumer acceptance, pricing, and product formulation practices vary substantially across individual countries. Suppliers therefore need country-specific regulatory and application strategies rather than a single Asia Pacific commercial model.
Middle East and Africa
Middle East and Africa represent a more fragmented opportunity structure. Demand is supported by processed food and beverage production, imported branded products, and interest in reduced-sugar formulations.
Gulf markets, particularly Saudi Arabia and the United Arab Emirates, are commercially relevant because of their developed modern retail systems and significant imported food presence. Manufacturers serving these markets must meet local labeling and food-additive requirements while maintaining consistency with international product specifications.
Price sensitivity remains important in several markets. Stevia adoption is therefore strongest where manufacturers can justify the ingredient through product positioning, sugar reduction, or formulation economics.
South America
South America has strategic significance because stevia originates from South America and the region includes major agricultural and food-processing economies.
Brazil represents the largest commercial opportunity within the supplied South American segmentation because of its extensive food and beverage industry. Argentina and other regional markets provide additional opportunities through packaged foods, beverages, and tabletop sweeteners.
The region also benefits from proximity to agricultural knowledge and stevia cultivation. However, supplier economics remain sensitive to agricultural costs, processing infrastructure, currency movements, and domestic purchasing power.
Competitive Landscape
The competitive structure includes ingredient companies, specialty stevia suppliers, branded sweetener businesses, and companies with upstream or application-specific capabilities.
Cargill, Incorporated competes through a broad sweetener portfolio that combines leaf-derived stevia with newer fermentation-based solutions. Its EverSweet platform uses Reb M and Reb D produced through fermentation, positioning the product around taste, sugar reduction, and resource efficiency.
Ingredion Incorporated has a significant position through its PureCircle stevia business and combines ingredient supply with sourcing, traceability, and formulation capabilities. Its 2025 disclosures show that stevia remains part of its priority agricultural sourcing program.
Archer Daniels Midland Company (ADM) competes through SweetRight stevia technologies, including its Echo platform based on bioconversion. Its approach emphasizes glycoside composition, sensory quality, and cost-in-use.
Pyure Brands, LLC, In The Raw, Biosweet Ventures, Sunwin Stevia International, Inc., and Stevia International, Inc. contribute to a broader competitive structure spanning consumer-facing sweeteners and ingredient supply.
Competition increasingly depends on product differentiation rather than simple extraction capacity. The most valuable differentiation points include glycoside composition, sensory performance, production technology, regulatory coverage, traceability, application support, and reliable supply.
Partnerships with food manufacturers are commercially important because stevia qualification often involves application testing before procurement contracts are finalized. Suppliers with strong technical teams can therefore influence formulation decisions early in product development.
Recent Developments
July 2026: MANE acquired an exclusive global license from Arzeda to produce and commercialize ViaLeaf™ Reb M, integrating production and commercialization to expand access to next-generation stevia solutions.
May 2026: Tate & Lyle expanded its collaboration with BioHarvest Sciences to develop multiple plant-based sweetener molecules, broadening its pipeline of scalable alternatives supporting sugar and calorie reduction.
February 2026: Tate & Lyle and Manus launched Yume™, with Yume™ M Stevia as its first ingredient, providing an all-Americas Reb M stevia sweetener produced at Manus’ U.S. bioconversion facility.
Regulatory and Policy Environment
Regulatory compliance is a central determinant of stevia commercialization because approval status depends on both the chemical identity of the steviol glycoside and its production route.
In the United States, FDA has reviewed numerous GRAS notices covering high-purity steviol glycosides, including Rebaudioside A, Rebaudioside D, Rebaudioside M, purified steviol glycosides, enzyme-modified products, and fermentation-derived materials.
FDA also makes an important distinction between refined steviol glycosides and crude or whole-leaf stevia. Whole-leaf and crude extracts are not permitted as sweeteners in the United States, while certain high-purity steviol glycosides have received FDA “no questions” responses under specified conditions.
At the international level, Codex lists steviol glycosides under INS 960 and identifies multiple forms, including steviol glycosides from Stevia rebaudiana, fermentation, enzymatic production, and glucosylation. The Codex GSFA database also specifies food-category provisions and maximum levels for applicable uses.
The European regulatory environment is also moving toward recognition of newer production methods. EFSA's current food-additive information identifies E 960b steviol glycosides from fermentation among recently authorized additives and has updated application guidance covering manufacturing processes, composition, stability, exposure, and safety data.
For suppliers, regulatory capability is therefore a commercial asset. Each new glycoside or production technology can require technical dossiers, safety assessment, specifications, exposure calculations, and market-specific authorization work.
Compliance also extends beyond food safety. Multinational buyers increasingly require evidence covering agricultural traceability, labor practices, environmental performance, and responsible sourcing. Ingredion's disclosed stevia controls illustrate how supplier qualification can extend into farmer traceability and human-rights due diligence.
Outlook and Strategic Implications
The Stevia Market is likely to become more differentiated through 2031 as food manufacturers move from generic stevia extraction toward application-specific sweetening systems.
The most important investment priority will be technology that improves the sensory profile of steviol glycosides while maintaining commercially viable production economics. Enzymatic conversion and fermentation have already established credible routes for producing glycosides such as Reb M. Recent FDA actions demonstrate that regulatory acceptance is continuing to expand around these technologies.
Procurement decisions will increasingly consider cost-in-use rather than price per kilogram. A high-purity ingredient may carry a higher unit price but require a much smaller inclusion rate or permit deeper sugar reduction. Conversely, a lower-priced ingredient can become less competitive if it requires masking flavors or additional formulation components.
Supply-chain transparency will become another procurement differentiator. Multinational food manufacturers need reliable documentation covering farm origin, processing, labor practices, and product specifications. Suppliers that cannot provide consistent traceability may face greater qualification barriers even when their ingredient pricing remains attractive.
The competitive structure should also favor companies with integrated technical capabilities. Ingredient suppliers that combine stevia sourcing, purification, glycoside modification, sensory testing, application laboratories, and regulatory support can address more of the customer's formulation problem.
Beverages are likely to remain a major commercial application because liquid products can incorporate high-intensity sweeteners efficiently and manufacturers can directly connect stevia use with sugar-reduction objectives. Dairy and confectionery will remain important but require more complex management of texture, flavor release, and processing conditions.
Regional strategies will diverge. North America and Europe will place greater emphasis on regulatory documentation, formulation performance, and responsible sourcing. Asia Pacific will remain important for both supply and consumption, while South America retains strategic relevance because of agricultural capabilities and food-processing demand. Middle Eastern markets will remain more selective and formulation-led.
The principal risks through 2031 include regulatory changes, raw-material variability, competition from alternative sweeteners, sensory limitations, and cost pressure from large food manufacturers. Suppliers must also manage the possibility that consumers become less receptive to any single sweetener category and demand broader ingredient diversification.
The strongest strategic opportunity lies in moving stevia further into precision sweetening: selecting specific glycosides, production methods, and ingredient combinations for individual food and beverage formulations. This approach increases technical value and reduces direct commodity-style price competition.
Overall, the next phase of the Stevia Market will be determined less by whether manufacturers want a plant-derived sweetener and more by whether suppliers can deliver the required taste, regulatory certainty, supply security, traceability, and cost-in-use at commercial scale. The companies that integrate these attributes into formulation-ready solutions should be better positioned to capture procurement decisions through 2031.
Stevia Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 933.1 million |
| Total Market Size in 2031 | USD 1,910.3 million |
| Forecast Unit | Million |
| Growth Rate | 15.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Form, Application, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Form
- Leaves
- Liquid Extract
- Powder
By Application
- Beverages
- Bakery and Confectionery
- Tabletop Sweeteners
- Dairy
- Others
By Distribution Channel
- Online
- Offline
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Others
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Others
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Taiwan
- Thailand
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Data Sources
2.4. Data Validation and Analysis
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Market Challenges
4.5. Porter’s Five Forces Analysis
4.5.1. Bargaining Power of Suppliers
4.5.2. Bargaining Power of Buyers
4.5.3. Threat of New Entrants
4.5.4. Threat of Substitutes
4.5.5. Competitive Rivalry in the Industry
4.6. Industry Value Chain Analysis
4.7. Analyst View
5. STEVIA MARKET ANALYSIS, BY FORM
5.1. Introduction
5.2. Leaves
5.2.1. Market Opportunities and Trends
5.2.2. Growth Prospects
5.3. Liquid Extract
5.3.1. Market Opportunities and Trends
5.3.2. Growth Prospects
5.4. Powder
5.4.1. Market Opportunities and Trends
5.4.2. Growth Prospects
6. STEVIA MARKET ANALYSIS, BY APPLICATION
6.1. Introduction
6.2. Beverages
6.2.1. Market Opportunities and Trends
6.2.2. Growth Prospects
6.3. Bakery and Confectionery
6.3.1. Market Opportunities and Trends
6.3.2. Growth Prospects
6.4. Tabletop Sweeteners
6.4.1. Market Opportunities and Trends
6.4.2. Growth Prospects
6.5. Dairy
6.5.1. Market Opportunities and Trends
6.5.2. Growth Prospects
6.6. Others
6.6.1. Market Opportunities and Trends
6.6.2. Growth Prospects
7. STEVIA MARKET ANALYSIS, BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.2.1. Market Opportunities and Trends
7.2.2. Growth Prospects
7.3. Offline
7.3.1. Market Opportunities and Trends
7.3.2. Growth Prospects
8. STEVIA MARKET ANALYSIS, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Form
8.2.2. By Application
8.2.3. By Distribution Channel
8.2.4. By Country
8.2.4.1. United States
8.2.4.1.1. Market Trends and Opportunities
8.2.4.1.2. Growth Prospects
8.2.4.2. Canada
8.2.4.2.1. Market Trends and Opportunities
8.2.4.2.2. Growth Prospects
8.2.4.3. Mexico
8.2.4.3.1. Market Trends and Opportunities
8.2.4.3.2. Growth Prospects
8.3. South America
8.3.1. By Form
8.3.2. By Application
8.3.3. By Distribution Channel
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.1.1. Market Trends and Opportunities
8.3.4.1.2. Growth Prospects
8.3.4.2. Argentina
8.3.4.2.1. Market Trends and Opportunities
8.3.4.2.2. Growth Prospects
8.3.4.3. Others
8.3.4.3.1. Market Trends and Opportunities
8.3.4.3.2. Growth Prospects
8.4. Europe
8.4.1. By Form
8.4.2. By Application
8.4.3. By Distribution Channel
8.4.4. By Country
8.4.4.1. Germany
8.4.4.1.1. Market Trends and Opportunities
8.4.4.1.2. Growth Prospects
8.4.4.2. France
8.4.4.2.1. Market Trends and Opportunities
8.4.4.2.2. Growth Prospects
8.4.4.3. United Kingdom
8.4.4.3.1. Market Trends and Opportunities
8.4.4.3.2. Growth Prospects
8.4.4.4. Spain
8.4.4.4.1. Market Trends and Opportunities
8.4.4.4.2. Growth Prospects
8.4.4.5. Italy
8.4.4.5.1. Market Trends and Opportunities
8.4.4.5.2. Growth Prospects
8.4.4.6. Others
8.4.4.6.1. Market Trends and Opportunities
8.4.4.6.2. Growth Prospects
8.5. Middle East and Africa
8.5.1. By Form
8.5.2. By Application
8.5.3. By Distribution Channel
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.1.1. Market Trends and Opportunities
8.5.4.1.2. Growth Prospects
8.5.4.2. United Arab Emirates
8.5.4.2.1. Market Trends and Opportunities
8.5.4.2.2. Growth Prospects
8.5.4.3. Others
8.5.4.3.1. Market Trends and Opportunities
8.5.4.3.2. Growth Prospects
8.6. Asia Pacific
8.6.1. By Form
8.6.2. By Application
8.6.3. By Distribution Channel
8.6.4. By Country
8.6.4.1. China
8.6.4.1.1. Market Trends and Opportunities
8.6.4.1.2. Growth Prospects
8.6.4.2. Japan
8.6.4.2.1. Market Trends and Opportunities
8.6.4.2.2. Growth Prospects
8.6.4.3. India
8.6.4.3.1. Market Trends and Opportunities
8.6.4.3.2. Growth Prospects
8.6.4.4. South Korea
8.6.4.4.1. Market Trends and Opportunities
8.6.4.4.2. Growth Prospects
8.6.4.5. Indonesia
8.6.4.5.1. Market Trends and Opportunities
8.6.4.5.2. Growth Prospects
8.6.4.6. Taiwan
8.6.4.6.1. Market Trends and Opportunities
8.6.4.6.2. Growth Prospects
8.6.4.7. Thailand
8.6.4.7.1. Market Trends and Opportunities
8.6.4.7.2. Growth Prospects
8.6.4.8. Others
8.6.4.8.1. Market Trends and Opportunities
8.6.4.8.2. Growth Prospects
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Product and Technology Developments
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Cargill, Incorporated
10.2. Ingredion Incorporated
10.3. Archer Daniels Midland Company (ADM)
10.4. Pyure Brands, LLC
10.5. In The Raw
10.6. Biosweet Ventures
10.7. Sunwin Stevia International, Inc.
Navigate
Trusted by the world's leading organizations











