
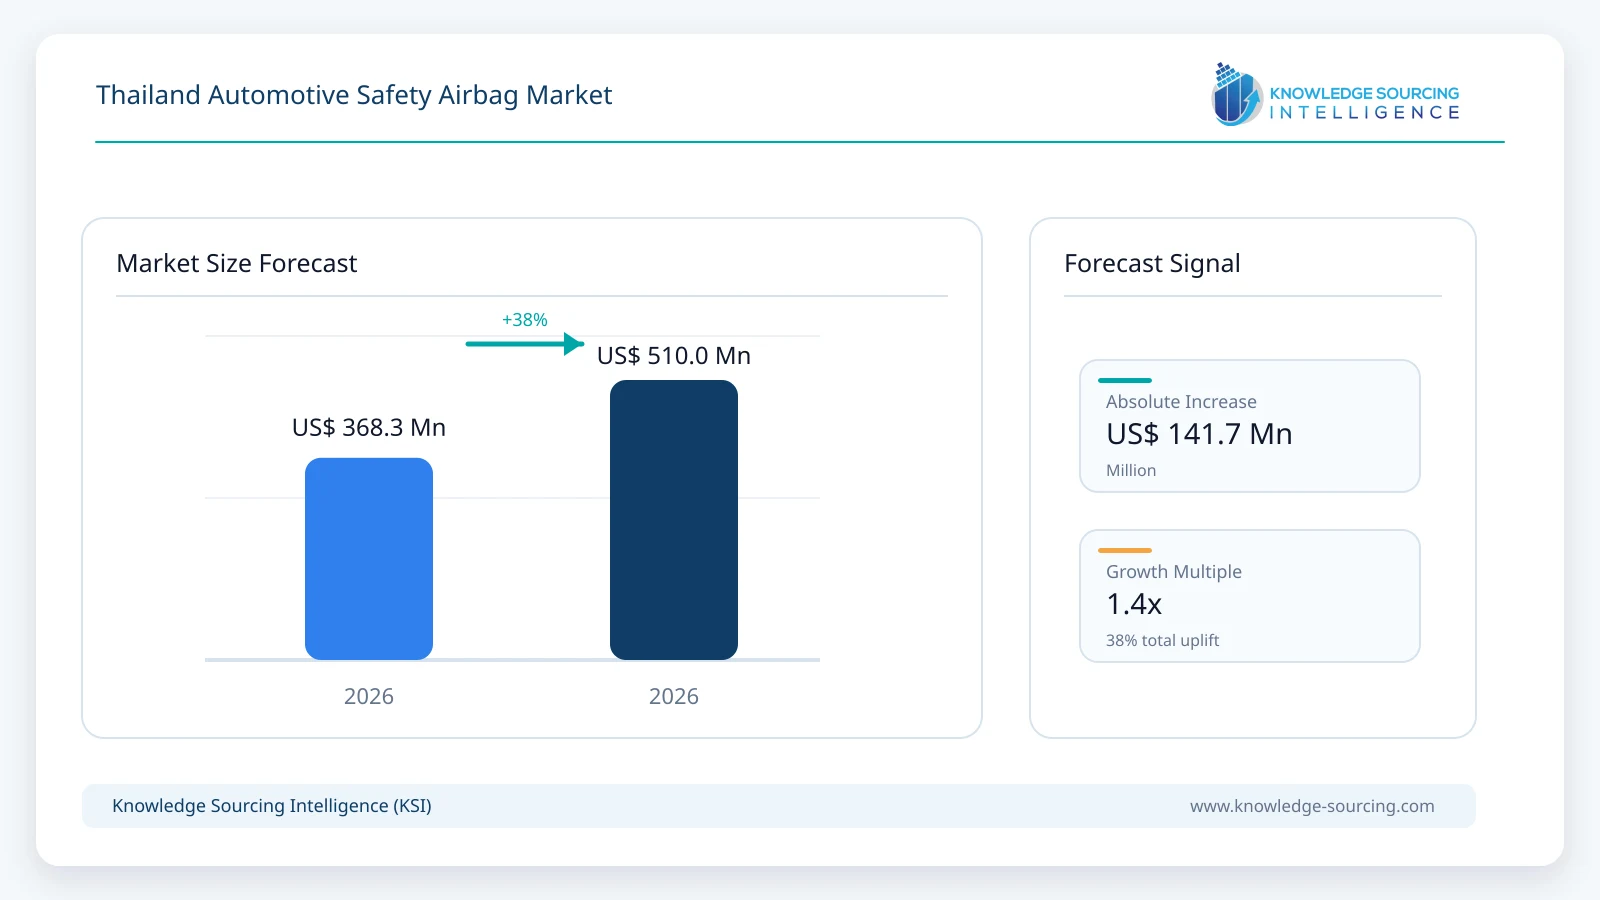
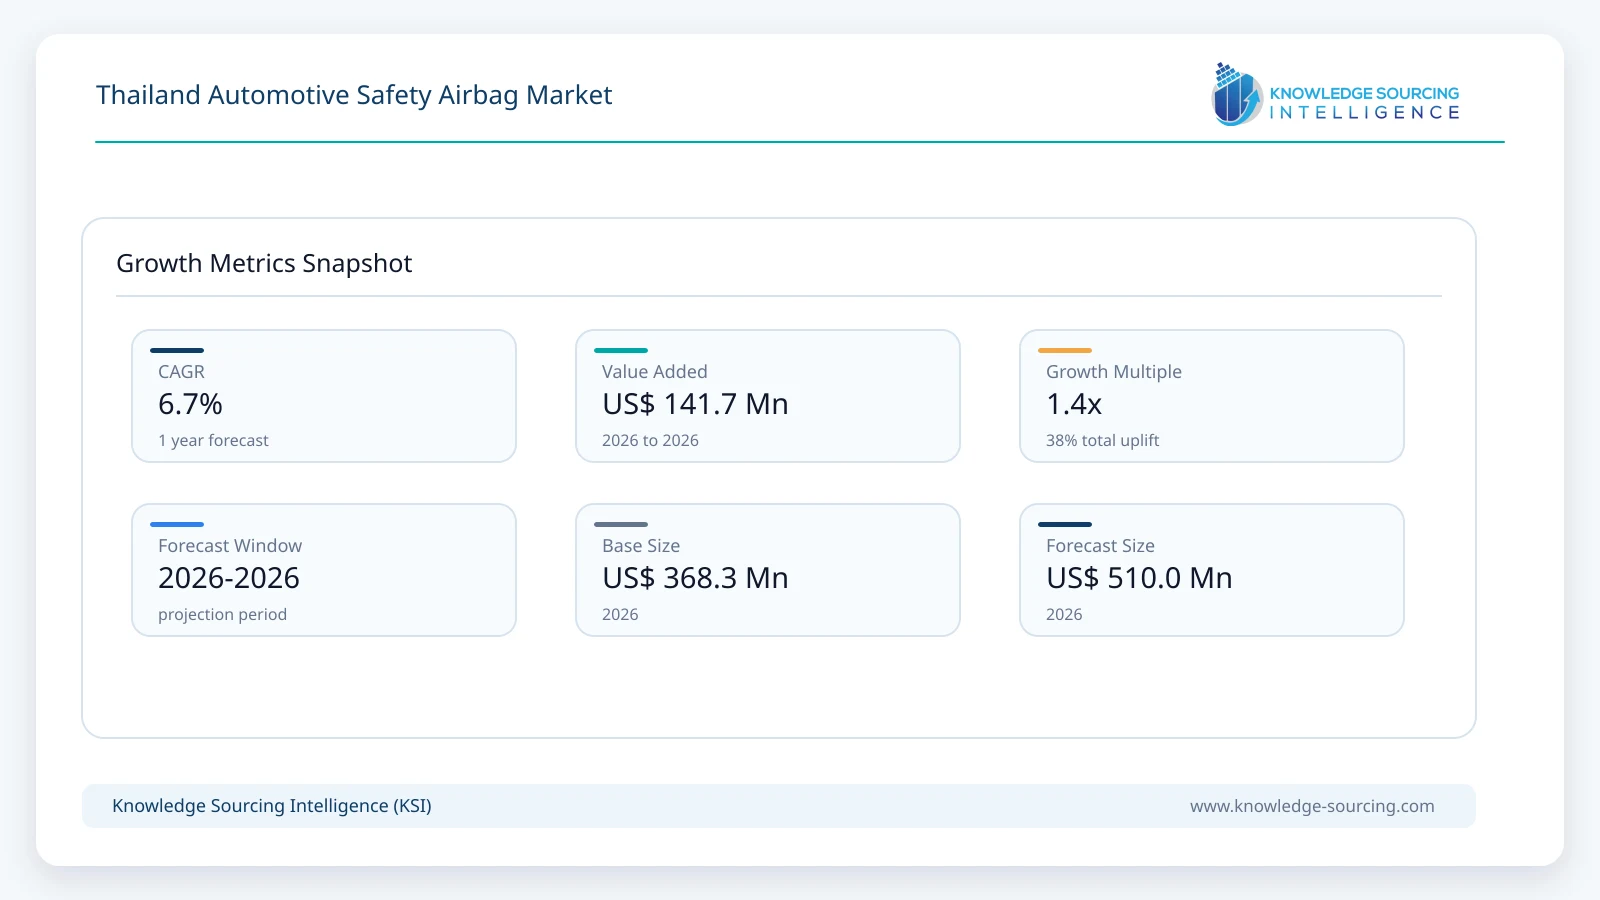
The Thailand automotive safety airbag market is forecast to grow at a CAGR of 6.7%, reaching USD 510.03 million in 2031 from USD 368.32 million in 2026.
Highlights:
- 1Front airbags hold a significant share in Thailand’s automotive safety airbag market by product type, driven by mandatory frontal-impact protection standards and rising passenger vehicle production.
- 2Nylon material segment is the fastest-growing, preferred for its durability, lightweight properties, and cost-effectiveness in airbag fabric manufacturing across vehicle categories.
- 3Commercial vehicles, including light and heavy commercial vehicles, are projected to capture a substantial market share due to expanding logistics fleets and safety compliance requirements.
- 4OEMs dominate the end-user segment with a major share, as vehicle manufacturers integrate advanced airbag systems during production to meet stringent Thai and international safety regulations.
- 5Expanding EV manufacturing, supported by over US$4.1 billion in investment pledges, is accelerating demand for specialized airbag designs tailored to electric and hybrid vehicle architectures.
- 6Strengthening road-safety regulations and occupant-protection standards continue to boost overall airbag adoption, reinforcing Thailand’s position as a key ASEAN automotive safety-component hub.
The growth of the market for safety airbags in Thailand is supported by dynamic competition between foreign OEMs, in addition to having an immense network of supporting industries. The country is continuing to expand its manufacturing base, and the auto part suppliers are growing by increasing their presence here. Thailand provides lucrative investment potential as the leading automotive production base in the ASEAN region, which is considered a fast-developing region for automotive manufacturing, and is expected to positively impact market growth.
Market Overview & Scope:
The Thailand automotive safety airbag market is segmented by:
Product Type: By product type, the automotive safety airbag market in Thailand is segmented into front airbag, side airbag, and others. The front airbag segment is expected to have a significant market share in this segment.
Material: By material, the Thailand automotive safety airbag market is divided into nylon, polyester, and others. The nylon segment is the fastest-growing segment.
Vehicle Type: By vehicle type, the Thailand automotive safety airbag market is categorized into passenger vehicles and commercial vehicles. The commercial vehicles segment is further segmented into light commercial vehicles and heavy commercial vehicles. The commercial vehicles segment is expected to have a significant market share in this segment.
End User: By end user, the market is segmented into OEMs and the aftermarket. The OEMs segment in the end user is predicted to hold a major share of the market during the projected period.
Market Trends:
Rise in Adoption of Electric Vehicles (EVs)
Thailand is a major automotive manufacturing hub in ASEAN, with a mature supply chain and growing foreign direct investment (FDI) in the automotive industry, including EVs. The emergence of EVs and autonomous vehicles is giving new opportunities for airbag manufacturers in the country to develop specialized and niche systems, such as external airbags for pedestrian protection.
Growth Drivers vs. Challenges:
Drivers:
Growing Automotive Production: Thailand’s automotive manufacturing sector continues to support demand for vehicle safety systems, including airbags, as the country strengthens its position as a regional production base and transitions toward next-generation vehicles. According to the Thailand Board of Investment (BOI), Thailand has secured more than US$4.1 billion in investment pledges across 198 EV supply-chain projects, covering battery electric vehicles, hybrid systems, batteries, critical components, and charging infrastructure. The investment pipeline includes more than 370,000 units of annual domestic BEV production capacity, reinforcing the country’s expanding vehicle manufacturing ecosystem.
Additionally, the International Organization of Motor Vehicle Manufacturers (OICA) reported that Thailand produced approximately 1.46 million motor vehicles in 2025, compared with about 1.47 million units in 2024. Although overall production was broadly stable, Thailand remained a significant vehicle manufacturing center in Southeast Asia, supported by established assembly facilities and an extensive automotive supplier base.
The transition toward electrified mobility is further strengthening Thailand’s automotive production infrastructure. The BOI reported that electrified vehicles represented more than 40% of new vehicle registrations in Thailand in 2025, comprising 21.8% hybrid vehicles and 19.6% battery electric vehicles. Major manufacturers, including Changan Auto, EV Primus, Hyundai Mobility, and Omoda & Jaecoo, have also expanded or initiated local manufacturing operations, with these investments contributing to more than 16,000 local jobs.
Furthermore, Thailand’s Ministry of Industry continues to promote the country as an automotive and parts manufacturing hub, including the development of testing and standards infrastructure for electric vehicles and components. The government has established 128 standards covering EVs, batteries, and charging stations, supporting the development of a broader and increasingly localized automotive supply chain. These manufacturing investments, expanding vehicle production capabilities, and stronger regulatory focus on vehicle safety are expected to sustain requirements for airbags and other occupant-protection systems across passenger and commercial vehicle applications.
Rise in Demand for Passenger Vehicles: Thailand’s automotive industry is undergoing a significant transition toward electric, connected, and safer vehicles, supported by government investment incentives and industry-development policies. In May 2026, Thailand’s Ministry of Industry reported that Changan’s Rayong facility was preparing to produce its new NEVO Q05 electric vehicle, with a target of 5,000 vehicles in June, highlighting continued expansion of modern vehicle manufacturing capacity. The government is also targeting Thailand as a major production base for electric vehicles and components, while encouraging manufacturers to strengthen domestic supply chains and advanced automotive technologies.
Airbags remain an important passive-safety component within passenger vehicles, protecting occupants during collisions and complementing increasingly advanced active-safety systems. Thailand’s Industrial Standards Institute has strengthened vehicle safety requirements, including updated standards for frontal and lateral occupant protection that took effect in September 2024. Thailand also introduced a standard for advanced emergency braking systems covering M1 and N1 vehicles, addressing collision risks involving vehicles, pedestrians, and motorcycles. These developments, together with the expansion of modern and electric vehicles, are supporting greater emphasis on integrated occupant-protection technologies and vehicle safety equipment in Thailand.
Growing emphasis on Passengers’ Safety in Road Accidents: The persistent burden of road crashes and associated fatalities is strengthening the emphasis on vehicle safety technologies, including airbags, seatbelts, and advanced occupant-protection systems. Thailand recorded 17,477 road traffic deaths in 2024, according to the Department of Disease Control under the Ministry of Public Health, with 14,144 fatalities involving motorcycles. The scale of road injuries continues to reinforce the importance of improving vehicle and occupant safety across the country.
Thailand is also strengthening its institutional response to road safety. The National Road Safety Master Plan 2022–2027 targets a 50% reduction in road traffic deaths by 2027, while the country established a Parliamentary Advisory Committee on Road Safety to support stronger legislation, enforcement, coordination, and safety standards. WHO reported 11,996 road traffic fatalities in Thailand during 2024 and highlighted road safety as a continuing national priority.
Further, Thailand’s Department of Disease Control reported that 87,142 people died in road crashes during 2020–2024, averaging 17,428 deaths annually. Its 2025 road-safety data initiatives, including integrated mortality datasets and improved accident-fatality reporting, are supporting more evidence-based safety policies. These developments are expected to sustain attention toward occupant-protection technologies and vehicle safety equipment, including airbags, as Thailand works to reduce the human and economic consequences of road crashes.
Stringent Government Safety Regulations: Continued road-safety concerns in Thailand are strengthening government efforts to reduce traffic fatalities and improve vehicle safety, supporting demand for occupant-protection systems such as airbags. Thailand’s Ministry of Transport has maintained a national objective of reducing road-traffic fatalities to 12 deaths per 100,000 population, while the Office of Transport and Traffic Policy and Planning reported that the country recorded 1,511 road accidents, 1,464 injuries, and 272 fatalities during the intensive New Year 2026 safety-control period, with fatalities down 10.23% from the corresponding period a year earlier. These continued safety initiatives are expected to reinforce requirements for passive safety technologies, including airbags and seatbelts.
Thailand is also strengthening vehicle occupant-protection requirements through regulatory alignment with international safety standards. In June 2025, the Department of Land Transport opened consultation on a draft regulation concerning UN Regulation No. 94 for occupant protection in frontal collisions, while the regulatory framework also references UN Regulation No. 137 concerning passenger-car frontal crash protection and restraint systems. Such regulatory developments encourage vehicle manufacturers and suppliers to integrate compliant restraint and crash-protection technologies, supporting continued demand for automotive airbags.
Industry participation further contributes to Thailand’s automotive safety ecosystem. Autoliv Thailand, which operates manufacturing facilities in Chonburi producing airbags, seatbelts, and other safety components, currently employs more than 4,000 people, according to the company’s Thailand operations. The company’s continued local manufacturing presence and focus on advanced occupant-protection systems reinforce Thailand’s role as an automotive safety-component production base and support the adoption of increasingly sophisticated airbag technologies.
Challenges:
High Costs and Price Sensitivity: The increase in innovation and advancement in the airbag system increases vehicle production costs, and the country being a price-sensitive market can deter consumer demand for this, which limits market growth.
Competitive Landscape:
The market is fragmented, with many notable players, including Continental AG, Robert Bosch GmbH, Autoliv Inc., Denso Corporation, ZF Friedrichshafen AG, Toyoda Gosei Co., Ltd., Nihon Plast Co., Ltd., and Daicel Corporation, among others.
Continental AG: Established in 1871, Continental AG is one of the world's prominent automotive components and tire manufacturers. The portfolio consists of technologies for safe, efficient, and connected mobility; the company operates in 56 countries, with an estimated revenue of approximately €39.4 billion in 2024. The company has three major sectors: Automotive, Tires, and ContiTech, focusing primarily on innovations for vehicle safety, autonomous driving, and sustainable tire manufacturing. The company focuses on the pursuit of Vision Zero, where it aims to decrease road deaths, road injuries, and road crashes via advanced safety systems such as ACUs. Continental has a strong footing in Asia-Pacific, including Thailand. Continental's operations in Thailand focus on tire manufacturing as well as automotive components, including airbag systems.
Key Developments:
September 2026: ZF LIFETEC unveiled production-ready integrated occupant sensing and adaptive restraint technology, using cameras and seat sensors to tailor airbag and seat-belt deployment strategies to individual occupants.
March 2026: Autoliv announced the launch of its first fully engineered wearable airbag system, the RS Taichi Airbag Vest T-SABE, alongside its integrated airbag system for commuter scooters like the Yamaha Tricity 300. These milestones officially expand its safety portfolio beyond traditional passenger vehicles to reinforce two-wheeler occupant protection technologies.
March 2026: Autoliv and Yamaha Motor introduced an airbag-equipped Tricity 300 commuter scooter, with Autoliv supplying the module and Yamaha targeting market availability during the first half of 2026. December 2025: Toyoda Gosei developed a self-supporting front center airbag that operates without a center console, enabling flexible installation across evolving vehicle interiors and autonomous-driving layouts.
Thailand Automotive Safety Airbag Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 368.32 million |
| Total Market Size in 2026 | USD 510.03 million |
| Forecast Unit | Million |
| Growth Rate | 6.7% |
| Study Period | 2021 to 2026 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2026 |
| Segmentation | Product Type, Material, Vehicle Type, End User |
| Companies |
|
Market Segmentation
By Product Type
Front Airbag
Side Airbag
Others
By Material
Nylon
Polyester
Others
By Vehicle Type
Passenger Vehicles
Commercial Vehicles
Light Commercial Vehicles
Heavy Commercial Vehicles
By End User
OEMs
Aftermarket
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. THAILAND AUTOMOTIVE SAFETY AIRBAG MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Front Airbag
5.3. Side Airbag
5.4. Others
6. THAILAND AUTOMOTIVE SAFETY AIRBAG MARKET BY MATERIAL
6.1. Introduction
6.2. Nylon
6.3. Polyester
6.4. Others
7. THAILAND AUTOMOTIVE SAFETY AIRBAG MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Passenger Vehicles
7.3. Commercial Vehicles
7.3.1. Light Commercial Vehicles
7.3.2. Heavy Commercial Vehicles
8. THAILAND AUTOMOTIVE SAFETY AIRBAG MARKET BY END USER
8.1. Introduction
8.2. OEMs
8.3. Aftermarket
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Continental AG
10.2. Robert Bosch GmbH
10.3. Autoliv Inc.
10.4. Denso Corporation
10.5. ZF Friedrichshafen AG
10.6. Toyoda Gosei Co., Ltd.
10.7. Nihon Plast Co., Ltd.
10.8. Daicel Corporation
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











