
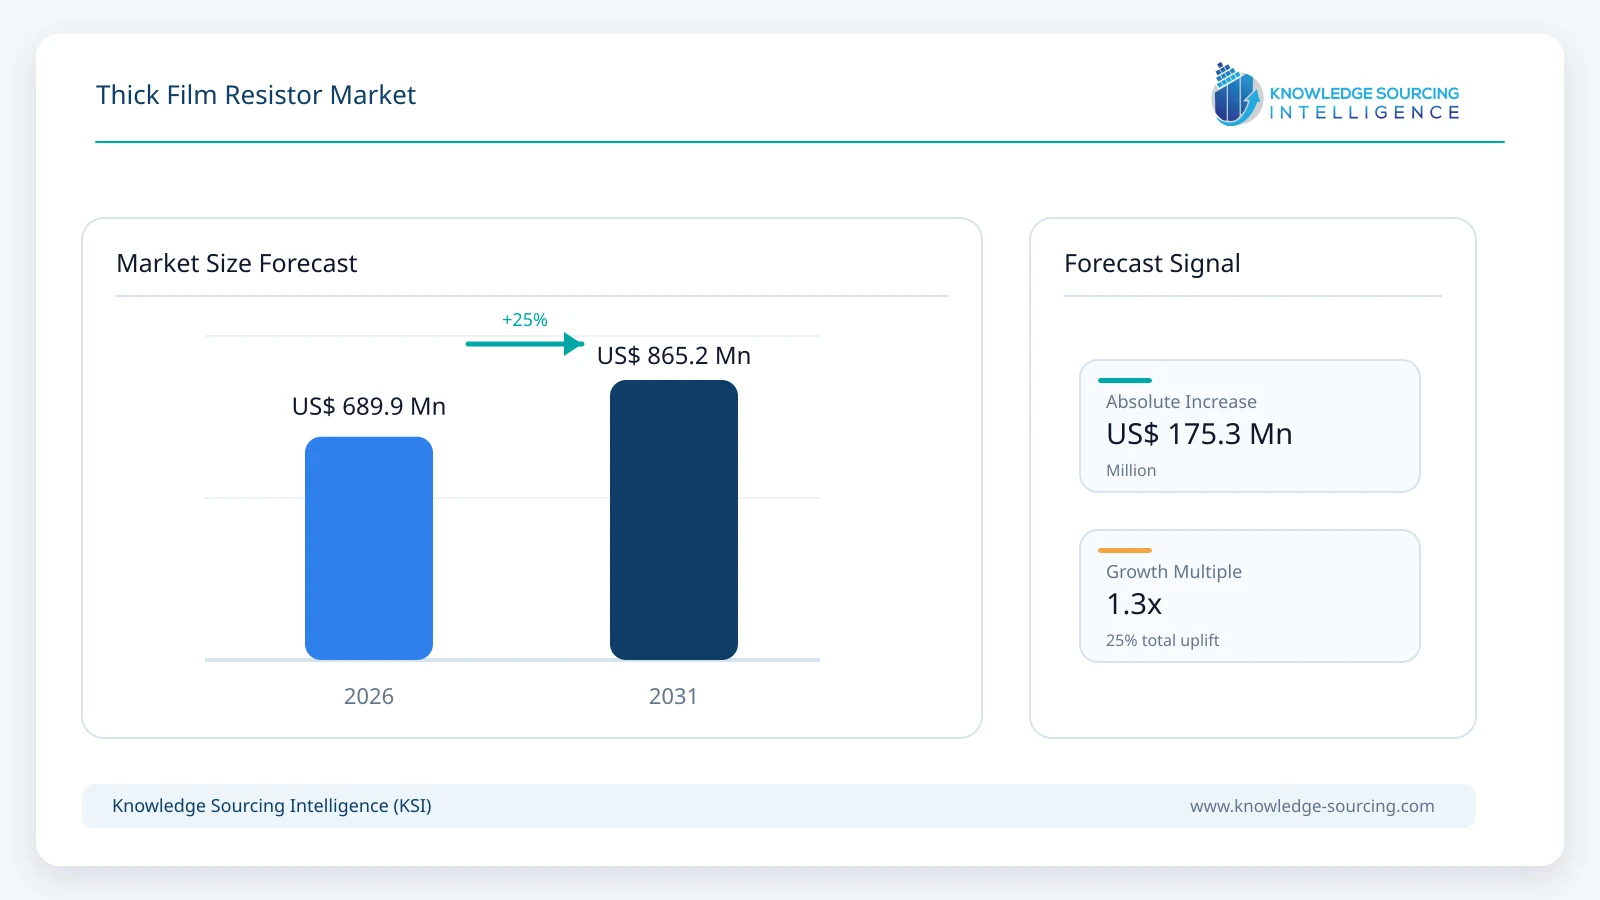
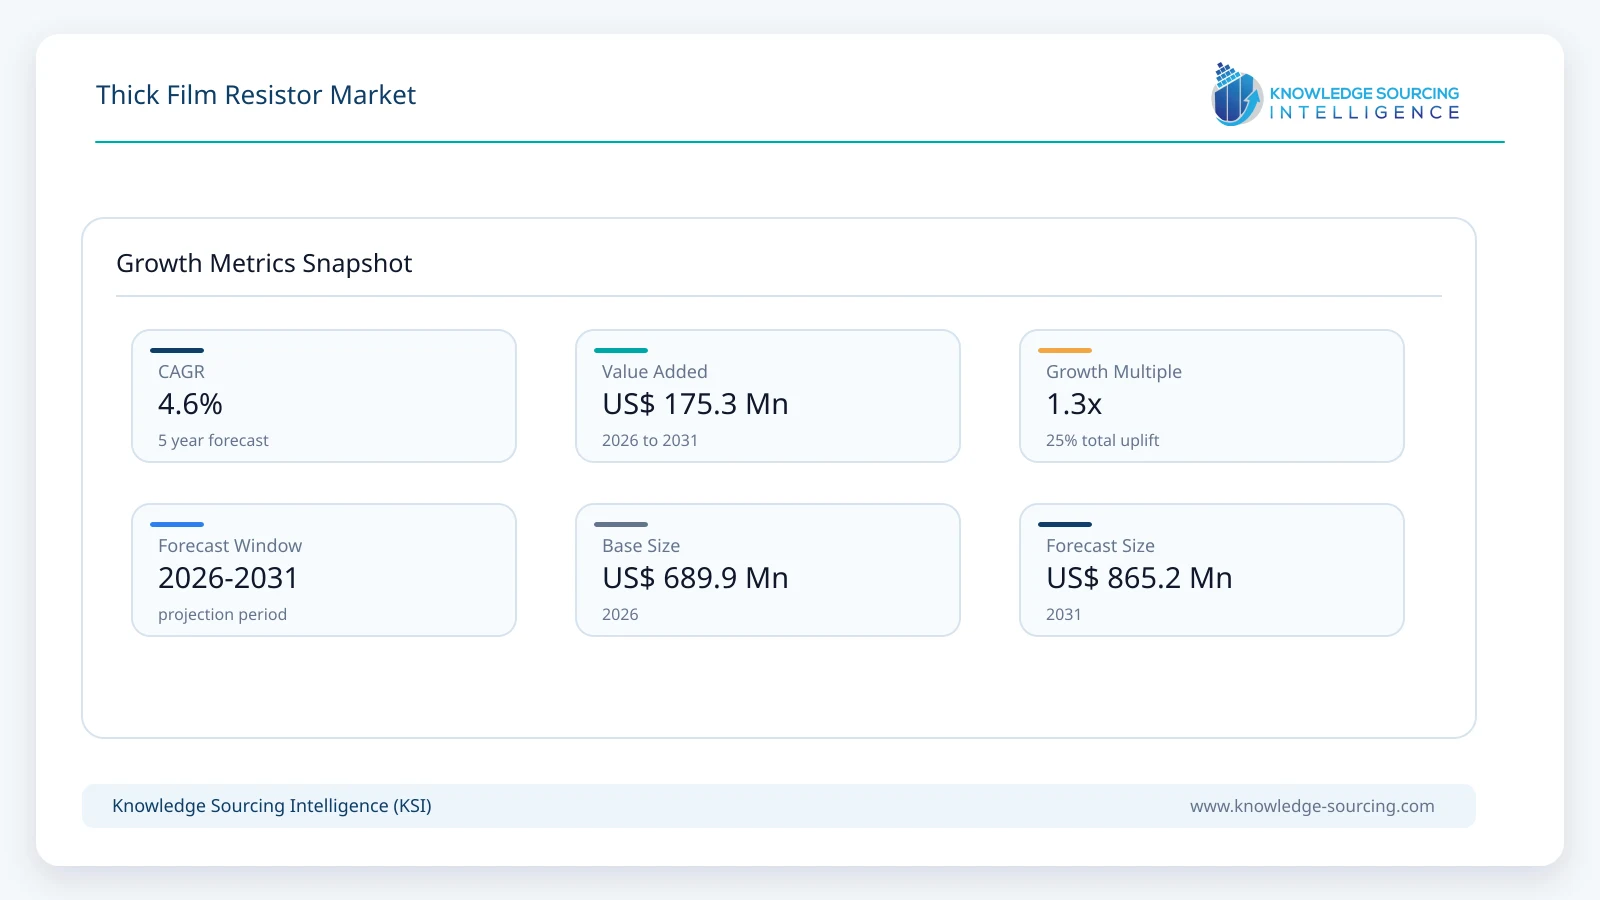
The Thick Film Resistor Market is forecast to grow at a CAGR of 4.6%, reaching USD 865.2 million in 2031 from USD 689.9 million in 2026.
Highlights:
- 1Automotive electrification and high-voltage power electronics continue to reshape demand for thick film resistors.
- 2Current sensing, power management, and circuit protection remain the principal application areas across industries.
- 3Automotive qualification standards and reliability requirements increasingly influence product design and supplier selection.
- 4Asia Pacific remains the primary manufacturing hub, while North America and Europe emphasize high-value industrial and automotive applications.
- 5Suppliers are expanding portfolios with higher-power, compact, and AEC-Q200-qualified products to address evolving customer specifications.
Market Overview
Demand is increasingly linked to the rising electronic content of vehicles, industrial automation equipment, renewable energy systems, electric power conversion, and communications infrastructure. Battery management systems, onboard chargers, traction inverters, advanced driver assistance systems, and industrial motor drives require resistors capable of operating under elevated temperatures, higher voltages, and continuous electrical loading. These requirements have encouraged manufacturers to expand portfolios toward higher-power thick film products, precision current sensing devices, and automotive-qualified resistor families. Company disclosures from passive component suppliers indicate continuing investment in products designed for electric vehicles, industrial automation, and power electronics applications.
Purchasing decisions increasingly extend beyond unit price. Original equipment manufacturers (OEMs) and electronic manufacturing service providers evaluate suppliers based on qualification history, manufacturing consistency, long-term supply assurance, compliance with automotive and industrial standards, and engineering support. Long product qualification cycles also strengthen customer relationships because once a component is validated within an electronic platform, switching suppliers generally requires additional testing, certification, and reliability verification.
Value creation across the market therefore depends less on simple production volume than on the ability to manufacture reliable passive components that satisfy increasingly demanding electrical, thermal, and regulatory specifications. Suppliers capable of supporting long product life cycles, global manufacturing footprints, and consistent quality control remain better positioned to secure business from automotive and industrial customers.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Automotive-qualified resistor development | 2025: New AEC-Q200-qualified 30 W thick film power resistor introduced | Reflects growing demand for high-reliability automotive passive components. |
Vishay resistor business revenue | US$759.3 million (2025) | Indicates continuing commercial importance of resistor products despite pricing pressure. |
Vishay resistor revenue change | +4.6% year-on-year (2025) | Recovery was primarily supported by higher shipment volumes rather than pricing improvements. |
Product development focus | High-voltage, high-power, precision thick film resistors | Product specifications increasingly align with electric vehicles, AI hardware, and industrial electronics. |
Principal demand industries | Automotive, industrial electronics, telecommunications, computing | Revenue diversity reduces dependence on a single downstream industry. |
Manufacturers continue to benefit from recovering demand, although pricing competition remains a structural characteristic of the passive component industry.
Market Drivers
Expansion of electric vehicle power electronics and battery management systems.
Electric vehicles require substantially higher numbers of precision and power resistors than conventional internal combustion vehicles because battery management systems, onboard chargers, DC-DC converters, traction inverters, and charging infrastructure depend on accurate current measurement and thermal stability. Automotive manufacturers increasingly specify AEC-Q200-qualified passive components that maintain electrical performance under vibration, humidity, and temperature extremes. Component suppliers have responded by introducing higher-power thick film resistors with improved overload capability and higher operating voltage ratings specifically for automotive applications.
Higher current sensing requirements across industrial power conversion equipment.
Industrial automation systems, renewable energy converters, factory motor drives, robotics, and energy storage installations increasingly require accurate current measurement to improve efficiency, equipment protection, and predictive maintenance. Shunt resistors and thick film power resistors have become important circuit elements because they support stable operation under continuous electrical loading while remaining compatible with automated surface-mount manufacturing. Equipment manufacturers increasingly prioritize long operating life, thermal management, and measurement accuracy, encouraging suppliers to expand high-power resistor portfolios for industrial customers.
Growing demand for compact high-power passive components.
Electronics manufacturers continue reducing board space while increasing power density across automotive electronics, telecommunications equipment, AI servers, industrial controllers, and power supplies. This trend increases demand for thick film resistor technologies capable of delivering higher power ratings within smaller package dimensions. YAGEO has reported development of high-voltage and high-power thick film resistor products designed to reduce component size while maintaining electrical performance and environmental resistance, reflecting broader customer demand for higher component integration and improved thermal efficiency.
Market Restraints and Challenges
Raw material cost volatility and pricing pressure constrain margin expansion.
Thick film resistors rely on conductive pastes containing precious metals such as ruthenium and silver, ceramic substrates, and specialty materials whose costs fluctuate with commodity markets and global supply conditions. At the same time, electronic manufacturing service providers and high-volume OEMs continue to negotiate aggressive pricing, particularly for standardized resistor products. Vishay's 2025 annual report shows that resistor revenue growth was supported by higher shipment volumes while average selling prices declined, illustrating the continuing balance between volume expansion and pricing pressure. Manufacturers increasingly respond through process automation, portfolio optimization, and higher-value automotive and industrial products rather than competing solely on price.
Lengthy qualification cycles increase market entry barriers.
Automotive, industrial automation, aerospace, and telecommunications customers require extensive qualification before approving passive electronic components for commercial production. Standards such as AEC-Q200 require testing for thermal cycling, vibration, humidity resistance, mechanical shock, and electrical overload. Product validation can extend over several months because electronic assemblies often undergo system-level reliability testing before production approval. These qualification requirements improve long-term reliability but also raise development costs, extend commercialization timelines, and make it difficult for smaller suppliers to enter high-value applications without established quality systems and engineering resources.
Geopolitical concentration within the electronic component supply chain.
Production of passive electronic components remains concentrated across East Asia, where manufacturers benefit from integrated supply chains, specialized materials suppliers, and established electronics manufacturing ecosystems. Regional trade restrictions, logistics disruptions, export controls, and geopolitical uncertainty therefore continue to influence procurement decisions among OEMs seeking supply resilience. Several multinational component manufacturers have responded by diversifying manufacturing locations, expanding regional inventories, and strengthening relationships with distribution partners to reduce delivery risks for automotive and industrial customers. While these measures improve resilience, they also increase operating costs and capital investment requirements across the value chain.
Major Segment Analysis
Automotive
The Automotive end-user segment represents the most commercially important application area because vehicle electrification continues to increase the number and performance requirements of passive electronic components. Thick film power resistors and shunt resistors support battery management systems, onboard chargers, electric power steering, traction inverters, regenerative braking systems, and advanced driver assistance systems. Purchasing decisions prioritize long-term reliability, overload capability, thermal stability, and compliance with AEC-Q200 qualification standards rather than component price alone.
Suppliers compete by developing compact, high-power resistor platforms capable of operating under elevated temperatures, vibration, humidity, and high-voltage conditions. Vishay's recent introduction of automotive-grade thick film power resistors with improved transient overload capability reflects customer demand for components that simplify thermal management while maintaining operational reliability in electric vehicles and high-voltage power electronics. Although industrial electronics remains another important revenue source, automotive programs generally involve longer qualification cycles and product life spans, providing suppliers with more stable revenue once components are designed into production platforms.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Automotive electrification, aerospace, industrial automation, and data center infrastructure | Higher manufacturing costs and dependence on global passive component supply chains |
Europe | Electric vehicle production, renewable energy systems, and industrial automation | Strict regulatory compliance and prolonged product qualification cycles |
Asia Pacific | Electronics manufacturing, automotive production, and semiconductor ecosystem | Pricing pressure resulting from intense supplier competition |
South America and Middle East and Africa | Industrial modernization, telecommunications expansion, and power infrastructure | Heavy reliance on imported electronic components |
North America continues to represent an important market for thick film resistors because of sustained investment in automotive electronics, industrial automation, aerospace, defense systems, and high-performance computing infrastructure. The United States remains the largest regional consumer, supported by vehicle electrification, data center expansion, and industrial equipment manufacturing. Buyers generally prioritize product reliability, engineering support, and long-term supply continuity over lowest-cost sourcing, creating opportunities for suppliers with qualified automotive and industrial portfolios. Although most passive components are sourced through global manufacturing networks, regional distributors and technical support capabilities remain important differentiators for multinational suppliers.
Europe maintains strong demand through its established automotive supply chain, industrial automation sector, and renewable energy equipment manufacturing. Germany, France, and the United Kingdom account for much of the region's commercial activity because vehicle manufacturers and industrial equipment producers increasingly require precision current sensing and power management components for electric mobility and factory automation. European customers also operate within demanding environmental and product safety frameworks, encouraging procurement from suppliers capable of demonstrating long-term product reliability, regulatory compliance, and stable quality management systems.
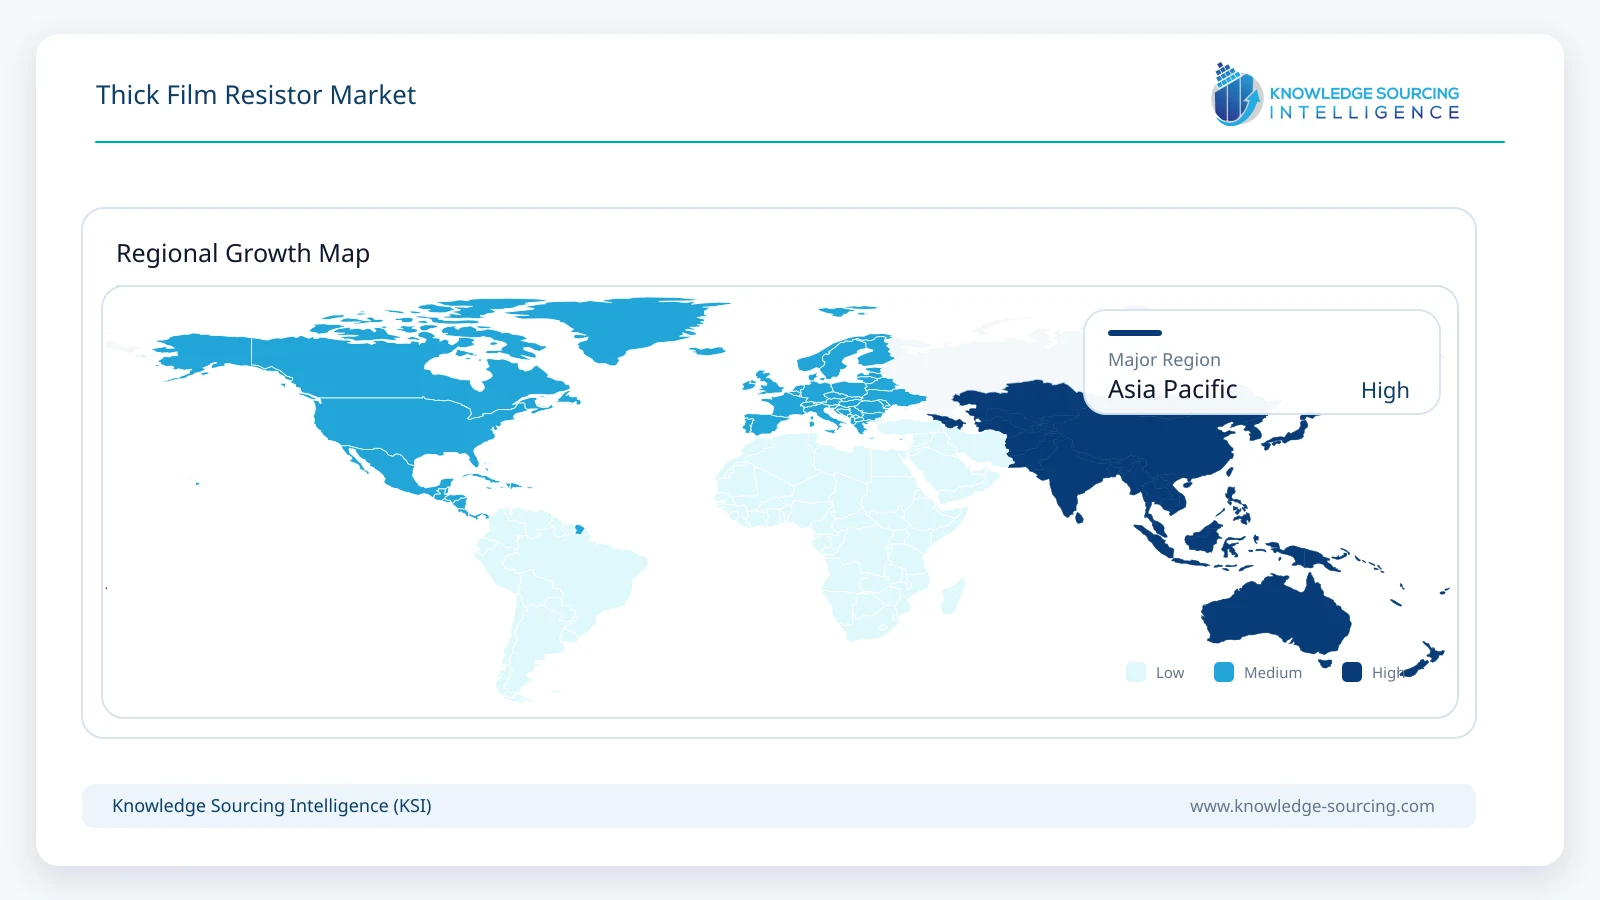
Asia Pacific remains the manufacturing center of the global thick film resistor industry. China, Japan, South Korea, Taiwan, and increasingly India support extensive electronics production ecosystems that integrate component manufacturing with semiconductor fabrication, printed circuit board assembly, and final equipment manufacturing. Companies including YAGEO, ROHM, KOA, Viking Tech, and numerous regional manufacturers benefit from proximity to consumer electronics, telecommunications equipment, industrial electronics, and automotive production. The concentration of manufacturing capacity creates cost advantages but also intensifies price competition, encouraging suppliers to differentiate through higher-power products, automotive-qualified components, and specialized resistor technologies rather than standard commodity offerings.
South America and the Middle East and Africa represent comparatively smaller demand centers but continue to benefit from gradual investment in telecommunications infrastructure, industrial modernization, renewable energy projects, and automotive assembly operations. Brazil remains the principal South American market because of its established automotive manufacturing base, while Saudi Arabia and the United Arab Emirates continue expanding industrial and energy infrastructure requiring reliable electronic power management components. Market development across these regions remains constrained by dependence on imported passive electronic components and relatively limited domestic manufacturing capacity.
Competitive Landscape
The thick film resistor market exhibits a moderately consolidated competitive structure, with established multinational manufacturers competing through manufacturing scale, product breadth, application-specific engineering, and long-term customer relationships rather than price alone. YAGEO Group, Vishay Intertechnology, Inc., KOA Corporation, ROHM Co., Ltd., TE Connectivity, TT Electronics, Viking Tech Corporation, Bourns, Inc., and Ohmite Mfg Co. continue expanding portfolios toward automotive, industrial automation, telecommunications, and power electronics applications where qualification requirements create higher barriers to entry.
Competition increasingly centers on AEC-Q200-qualified products, higher power density, improved thermal performance, precision current sensing, and compact package designs that support electric vehicles and industrial power conversion. Several suppliers have also expanded regional manufacturing capacity, diversified production locations, and strengthened distributor networks to improve supply resilience following recent supply-chain disruptions. While standardized resistor categories remain highly price competitive, higher-value automotive and industrial applications increasingly reward suppliers capable of combining product reliability, engineering support, global manufacturing capability, and long-term supply assurance.
Recent Developments
September 29, 2026: Vishay Intertechnology introduced its D2TO35S automotive-grade thick film power resistor in a compact TO-263 package, delivering 35 W power dissipation with top-side cooling to improve thermal management and reduce board space.
September 24, 2026: Vishay Intertechnology introduced four thick film resistor sample kits featuring 20 W and 35 W devices, automotive-grade qualification, multiple resistance values, and optional PCB test boards for electrical and thermal evaluation.
August 20, 2026: Vishay Intertechnology launched its MCB RPWA 650 thick film power resistor series, providing 650 W continuous power, customizable cabling, optional temperature sensing, and a low-profile design for space-constrained power applications.
February 18, 2026: Vishay Intertechnology launched the CRCW0201-AT e3 series of AEC-Q200-qualified thick film chip resistors in an ultra-compact 0201 package, reducing PCB footprint by 50% versus 0402 devices.
February 11, 2026: Vishay Intertechnology introduced its RCA-SR e3 series of AEC-Q200-qualified thick film chip resistors, combining sulfur resistance and long-term stability across five case sizes for automotive, industrial, and telecommunications applications.
Regulatory and Policy Environment
The thick film resistor market operates within a regulatory framework that emphasizes product reliability, electrical safety, environmental compliance, and quality assurance rather than direct product-specific legislation. Automotive applications remain subject to the most demanding qualification requirements, with AEC-Q200 serving as the industry benchmark for passive electronic component reliability. Compliance requires extensive testing for thermal shock, vibration, humidity resistance, mechanical durability, solderability, and electrical overload before components can be incorporated into vehicle platforms. These qualification requirements increase development costs but also create high barriers to entry and strengthen long-term supplier relationships.
Environmental regulations continue to influence material selection and manufacturing processes. Manufacturers supplying global markets must comply with the Restriction of Hazardous Substances (RoHS) Directive and the Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) Regulation within Europe, while many international customers also require declarations covering conflict minerals, responsible sourcing, and product traceability. Major suppliers, including YAGEO, Vishay, ROHM, and TE Connectivity, maintain dedicated compliance programs to satisfy customer documentation and regulatory reporting requirements.
Quality management standards also play an important commercial role. Automotive customers increasingly require manufacturing facilities certified to IATF 16949, while industrial and telecommunications customers commonly specify ISO 9001-based quality systems and rigorous supplier auditing. Compliance with these standards has become an important competitive differentiator because purchasing decisions increasingly consider manufacturing consistency, traceability, and long-term supply reliability alongside technical product performance.
Outlook and Strategic Implications
Demand for thick film resistors during the 2026–2031 forecast period is expected to remain closely aligned with the expansion of electric mobility, industrial automation, renewable energy systems, telecommunications infrastructure, and intelligent power management equipment. Higher power density, greater thermal performance, and more accurate current sensing will continue to shape product development priorities as electronic systems operate under increasingly demanding electrical conditions.
Competitive positioning will increasingly depend on engineering capability rather than manufacturing scale alone. Suppliers capable of delivering automotive-qualified products, supporting extended product life cycles, maintaining geographically diversified manufacturing networks, and providing technical design assistance are likely to strengthen relationships with OEMs and electronic manufacturing service providers. Continued investment in compact high-power resistor technologies, localized production capacity, and resilient supply chains should help manufacturers address customer requirements for quality, supply continuity, and faster product qualification.
For buyers, procurement strategies are expected to place greater emphasis on lifecycle reliability, dual-source availability, and regulatory compliance rather than lowest acquisition cost. Manufacturers, distributors, and technology providers that align product development with these procurement priorities will be better positioned to participate in higher-value automotive and industrial applications, where qualification requirements and long production programs support more stable long-term revenue streams.
Thick Film Resistor Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 689.9 million |
| Total Market Size in 2031 | USD 865.2 million |
| Forecast Unit | Million |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Thick Film Power Resistor
Shunt Resistor
By End-User
Automotive
Electrical and Electronics
Telecommunication
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. THICK FILM RESISTOR MARKET BY TYPE
5.1. Introduction
5.2. Thick Film Power Resistor
5.3. Shunt Resistor
6. THICK FILM RESISTOR MARKET BY END-USER
6.1. Introduction
6.2. Automotive
6.3. Electrical and Electronics
6.4. Telecommunication
6.5. Others
7. THICK FILM RESISTOR MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. YAGEO Group
9.2. TE Connectivity
9.3. Vishay Intertechnology, Inc.
9.4. KOA Corporation
9.5. ROHM CO., LTD.
9.6. Viking Tech Corporation
9.7. TT Electronics
9.8. Bourns, Inc.
9.9. Ohmite Mfg Co
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key benefits for the stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the Thick Film Resistor Market forecast by 2031?
Market is forecast to reach USD 865.2 million by 2031.
What is the projected CAGR for the Thick Film Resistor Market?
The Thick Film Resistor Market is forecast to grow at a 4.6% CAGR.
What key applications drive Thick Film Resistor Market growth?
Automotive electrification, industrial automation, and renewable energy drive growth.
Which region is the primary manufacturing hub for thick film resistors?
Asia Pacific remains the primary manufacturing hub.
How are thick film resistor suppliers adapting to demand?
Suppliers offer higher-power, compact, AEC-Q200-qualified products.
What are the principal application areas for thick film resistors?
Current sensing, power management, and circuit protection are key areas.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Thick Film Resistor Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/thick-film-resistor-market