
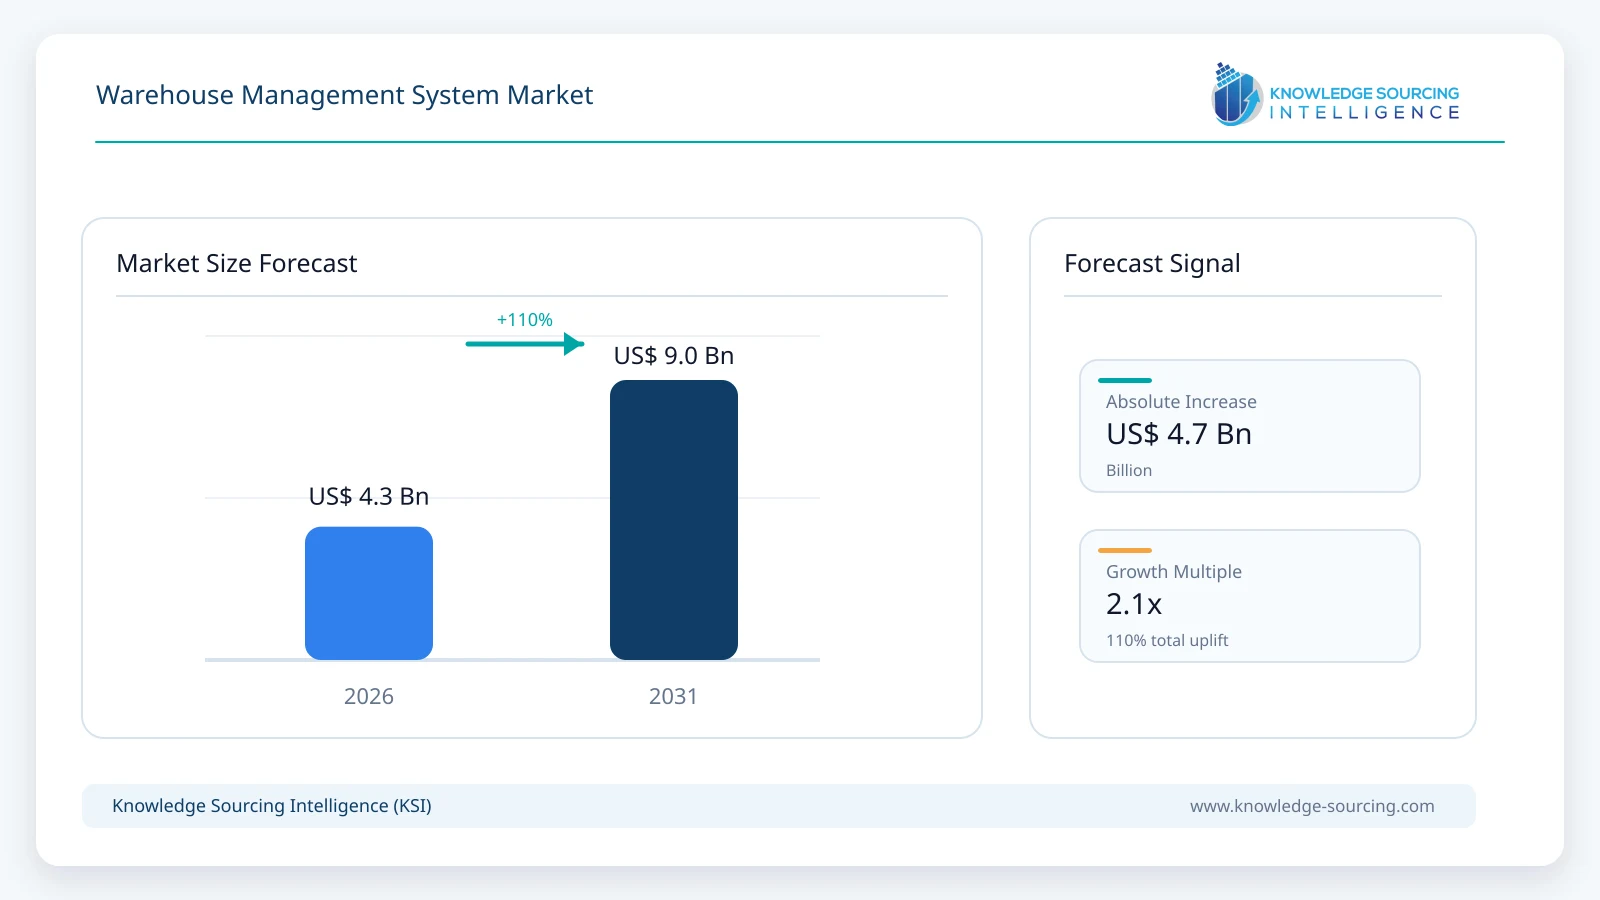
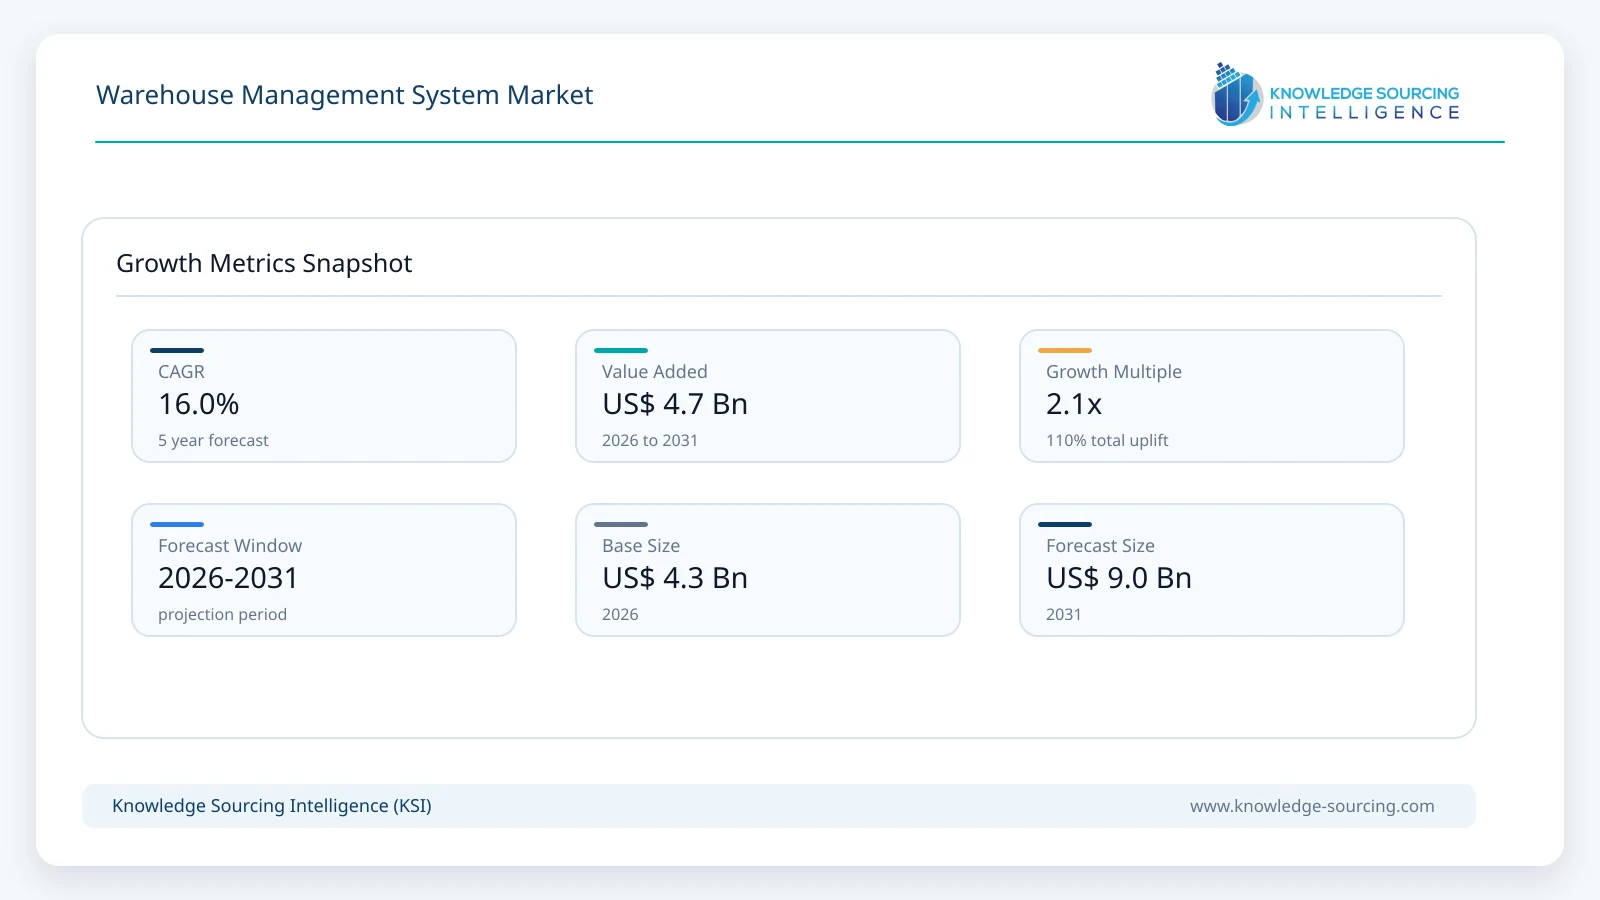
The warehouse management system market is anticipated to grow at a CAGR of 16.0%, from USD 4.28 billion in 2026 to USD 8.99 billion by 2031.
Highlights:
- 1Cloud deployment accounts for approximately 64% of global WMS revenue in 2026.
- 2Third-party logistics and transportation represent approximately 29% of 2026 WMS demand.
- 3North America contributes approximately 38% of global market revenue in 2026.
- 4Asia Pacific is projected to grow at approximately 18.5% annually through 2031.
- 5AI and automation orchestration are becoming core areas of WMS product differentiation.
Warehouse management software is becoming a more strategic layer of supply-chain execution as fulfillment operations combine warehouse workers, material-handling systems, autonomous mobile robots, sortation equipment and increasingly sophisticated inventory flows. The commercial market extends beyond new greenfield installations, and a significant share of spending is coming from replacement of legacy applications, migration from perpetual software to subscription models, and the addition of modules covering labor, yard operations, and analytics among others.
Cloud adoption is changing both the economics and purchasing cycle of WMS. Manhattan Associates reported a 26% year-on-year increase in cloud subscription revenue in the second quarter of 2026, while noting continued migration by existing customers from on-premises products to cloud solutions. Microsoft also provides warehouse-management-only deployment that can connect with external ERP environments, illustrating how WMS functionality is becoming less dependent on full-suite ERP replacement.
Market Trends
Cloud-Native WMS Replacement Cycle
Cloud migration is shifting from a deployment preference to a central part of the WMS replacement cycle. Mature warehouse operators frequently have deeply embedded applications connected with ERP, transportation, automation, parcel, carrier and customer systems, making complete replacement disruptive. Modern cloud platforms are addressing this through APIs, modular architecture, staged deployment and continuous product releases that allow companies to modernize warehouse execution without replacing every adjacent system simultaneously.
Supplier performance provides evidence of this transition. Manhattan Associates continues to report considerably faster growth in cloud subscriptions than in legacy maintenance revenue, while Tecsys positions its current WMS around secure SaaS execution and a common platform supporting configurable warehouse processes. Microsoft’s warehouse-management-only architecture enables advanced warehouse functionality to operate alongside external ERP and order-management systems, further reducing the requirement for a single-vendor enterprise stack. The commercial effect is a larger recurring-revenue component for suppliers and a broader addressable customer base for advanced WMS functionality.
WMS and Warehouse Automation Orchestration Convergence
Warehouse automation is increasing the operational importance of the software layer that coordinates inventory, people and machines. Large distribution centers may operate combinations of AS/RS systems, conveyors, sorters, autonomous mobile robots, automated guided vehicles and conventional manual processes. WMS suppliers are consequently extending their platforms beyond inventory and workflow control toward real-time resource orchestration and integration with multiple automation providers.
Blue Yonder now combines WMS functionality with a vendor-agnostic Robotics Hub and warehouse execution capabilities, while SAP EWM provides direct warehouse-automation control and integration with robotics. Mecalux separates WMS, WES and WCS functions within a connected software portfolio, and Made4net integrates WMS with warehouse control, yard, labor and routing capabilities. These architectures indicate that WMS purchasing decisions are becoming closely tied to an operator's automation roadmap. Customers increasingly need software that can accommodate changing equipment mixes without forcing a redesign of core warehouse processes each time a new robotics or material-handling system is introduced.
Embedded AI Moves Into Warehouse Execution
AI functionality within warehouse systems is progressing from reporting and forecasting toward operational recommendations and execution assistance. Current applications include dynamic slotting, labor forecasting, anomaly identification, pick-path optimization, resource allocation and exception management. This changes how suppliers compete because the value of AI depends on access to live warehouse data and the ability to translate recommendations into executable workflows.
Blue Yonder's 2026 releases introduced advanced slotting, warehouse-manager agentic AI experiences, predictive labor intelligence and operational heatmaps. Infios expanded warehouse AI capabilities during 2026 around real-time operational decision-making, while Infor is applying AI to pick-path optimization. SAP EWM now incorporates AI-assisted slotting and labor-demand planning alongside integrated warehouse automation. The commercial distinction is shifting from whether a WMS includes AI functionality to how effectively intelligence is embedded into daily receiving, picking, replenishment, labor and exception-management processes.
Market Drivers
Omnichannel Fulfillment and Order Complexity
The continued fragmentation of fulfillment demand is a significant driver of WMS investment. A single distribution facility may now replenish stores, process wholesale orders, fulfill direct-to-consumer shipments, manage marketplace orders and handle returns from the same inventory pool. These flows have different picking profiles, packaging requirements, service-level commitments and carrier cut-off times, creating complexity that cannot be managed efficiently through basic inventory applications.
Modern WMS deployments provide a common execution layer for managing those competing flows while retaining inventory visibility across locations and ownership structures. Retail and e-commerce operations require wave, batch, cluster and discrete picking strategies to coexist, while manufacturers and distributors must coordinate production supply, pallet movements and customer orders. The operational requirement is particularly strong where facilities have expanded organically and rely on several disconnected systems. As order profiles become less predictable, WMS investment is increasingly tied to improving warehouse responsiveness rather than simply expanding physical storage capacity.
Labor Productivity and Automation Investment
Warehouses continue to face pressure to increase throughput without proportional growth in labor and floor space. WMS software directly influences this equation through task sequencing, travel reduction, replenishment timing, workload balancing, labor standards and integration with automated equipment. This makes software modernization relevant even where companies are not building new warehouses.
Automation investment strengthens the driver because robotic systems require accurate inventory information, task priorities and coordination with manual operations. A warehouse can contain sophisticated hardware while still suffering from congestion, poorly sequenced replenishment or idle resources if the execution layer does not coordinate activity effectively. Current WMS products are addressing this through resource forecasting, dynamic orchestration, optimized picking paths and vendor-independent robotics integration. As more operators adopt a mixture of human and automated workflows, the commercial case for WMS shifts toward extracting higher utilization from the complete warehouse asset base rather than reducing headcount alone.
Multi-Client Operations and Traceability Requirements
Third-party logistics, food and beverage, healthcare, pharmaceuticals and other regulated or multi-owner warehouse environments require detailed inventory status, ownership, batch, lot, expiry and transaction records. In 3PL operations, the same physical facility may serve multiple customers with different workflows, billing rules, service levels and reporting requirements. This creates a strong need for configurable warehouse processes rather than standardized inventory functionality.
Current WMS platforms increasingly combine multi-owner inventory, customer-specific workflows, automated billing and detailed traceability. Infor, for example, provides multi-site and owner inventory capabilities alongside 3PL billing, while Generix and Mecalux provide WMS functionality specifically addressing 3PL operations. These requirements create durable demand because warehouse operators must maintain execution accuracy while onboarding new customers and product categories without substantially increasing administrative complexity.
Market Restraints
Integration Complexity and Operational Migration Risk
WMS replacement can affect almost every physical transaction within a distribution center, which makes implementation risk materially different from many other enterprise software projects. A new platform must integrate with ERP, order management, transportation, parcel systems, customer interfaces, automation equipment and warehouse devices while preserving inventory accuracy during migration. Large facilities also have limited tolerance for downtime because system interruption can stop receiving and shipping activity.
Legacy customization adds further difficulty. Processes developed over many years may contain customer-specific rules or interfaces that cannot simply be reproduced within a standardized cloud configuration. Operators must determine whether to redesign these workflows, recreate them or retire them. The availability of APIs, modular architectures and external-ERP deployment models is reducing some of this burden, but complex brownfield projects still require process mapping, testing, data migration and staged cutovers. Integration risk can therefore extend procurement cycles and delay replacement even where the operational case for modernization is clear.
Total Cost, Process Readiness and Implementation Resources
Subscription delivery reduces infrastructure requirements but does not eliminate the wider cost of WMS transformation. Implementation, integration, warehouse-device changes, automation interfaces, training, process redesign and parallel operations can materially increase total project expenditure. This particularly affects mid-sized companies where warehouse complexity may justify a sophisticated WMS but the internal IT and process teams required for implementation are limited.
Modern systems are also capable of exposing inefficient operating practices that must be standardized before automation or AI can produce meaningful benefits. Companies with inconsistent master data, poorly defined slotting rules or site-specific processes may need substantial operational work before deployment. Cybersecurity, system availability and recovery requirements become more significant as warehouse execution moves toward cloud-connected platforms controlling time-sensitive physical operations. These factors do not remove the need for WMS investment, but they can lengthen implementation schedules and favor phased deployments over large enterprise-wide replacements.
Segment Analysis
By Deployment Type: Cloud
Cloud is the principal growth component of the warehouse management system market and is projected to generate approximately USD 7.0 billion in revenue by 2031. Adoption is being driven by recurring software delivery, continuous upgrades, easier multi-site scaling and improved ability to integrate external applications and automation through standardized interfaces. Large enterprises are using cloud migration to replace heavily customized legacy WMS estates, while smaller operators can access advanced functionality without maintaining equivalent internal infrastructure.
The distinction between cloud and on-premises deployment is also becoming commercially important for suppliers. Subscription models generate recurring revenue and create more frequent product-release cycles, while legacy maintenance and perpetual-license streams gradually decline as customers migrate. Cloud adoption does not remove implementation complexity, particularly in highly automated warehouses, but modular architectures and integration layers make staged modernization more practical. Manhattan Associates' 2026 results provide a clear example of this transition, with cloud subscription revenue expanding while maintenance associated with perpetual software declined.
By End User: Third-Party Logistics and Transportation
Third-party logistics and transportation is projected to generate approximately USD 2.5 billion in WMS revenue by 2031, retaining its position as one of the largest commercial demand pools. A 3PL warehouse must frequently manage multiple inventory owners, client-specific workflows, billing arrangements, reporting formats and service-level requirements from the same physical infrastructure. Rapid customer onboarding and the ability to configure processes without extensive custom development are therefore major purchasing criteria.
The segment also has a strong incentive to invest in automation orchestration and labor optimization because warehouse operating costs directly influence contract margins. Multi-client facilities can experience rapid changes in volumes and order profiles as customers are added or contracts expand, making scalable cloud deployments commercially attractive. WMS platforms are responding with multi-owner inventory control, automated 3PL billing, customer portals, configurable workflows and integrated transportation capabilities. The expansion of dedicated 3PL functionality across Infor, Generix, Mecalux and Logistics Reply demonstrates the strategic importance of this customer group to WMS suppliers.
By Geography: North America
North America is projected to generate approximately USD 3.2 billion in WMS revenue by 2031, supported by a large installed base of distribution infrastructure, significant 3PL activity, omnichannel retail operations and continued warehouse automation investment. The United States accounts for most regional demand and combines mature enterprise WMS installations with a substantial replacement opportunity as older on-premises environments migrate toward cloud-based execution platforms.
The region also contains several major WMS software suppliers and a large concentration of customers deploying robotics, high-throughput fulfillment systems and multi-node distribution strategies. This creates demand for software capable of integrating heterogeneous automation while coordinating warehouse, transportation and order workflows. Asia Pacific is expected to expand faster from a lower base as modern distribution infrastructure grows across China, India, Southeast Asia and Australia, while Europe continues to generate significant replacement and automation-related demand. The geographic opportunity is consequently broadening even as North America retains the largest revenue base through the forecast period.
Competitive Environment
The competitive environment combines specialist WMS companies, broad supply-chain execution providers and enterprise software vendors. Manhattan Associates, Blue Yonder, Infios and Tecsys compete strongly around sophisticated warehouse execution and large-scale distribution requirements. SAP, Oracle, Microsoft and Infor link warehouse management with wider ERP and supply-chain ecosystems, while IFS Softeon, Made4net, Generix, Logistics Reply, Mecalux and Synergy Logistics provide differentiated combinations of WMS, warehouse execution, automation integration and vertical functionality.
Product differentiation is shifting toward cloud architecture, implementation flexibility, AI-enabled execution, robotics orchestration and the ability to integrate WMS with adjacent transportation, order and yard-management processes. Consolidation is also changing supplier positioning. IFS completed its acquisition of Softeon in March 2026, combining industrial software and AI capabilities with an established WMS platform. At the same time, specialist suppliers are expanding through product development rather than relying solely on consolidation, particularly in agentic AI, slotting, labor planning and multi-agent automation orchestration.
Recent Developments
July 2026: Manhattan Associates reported that second-quarter cloud subscription revenue increased 26% year on year to USD 126.7 million, illustrating continued customer migration toward cloud-based supply-chain execution products.
June 2026: Infios introduced expanded AI capabilities within its warehouse-management portfolio to improve operational decision-making and automate warehouse execution use cases.
May 2026: Exol selected Manhattan Active Warehouse Management and Transportation Management as core execution platforms for its expanding automated fulfillment-center network.
March 2026: IFS completed its acquisition of Softeon, establishing IFS Softeon and combining warehouse-management and robotics-orchestration capabilities with IFS's industrial software portfolio.
2026: Blue Yonder's warehouse-management releases added advanced slotting, agentic AI tools for warehouse managers, automation extensions, labor intelligence and predictive warehouse analytics.
Warehouse Management System Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.28 billion |
| Total Market Size in 2031 | USD 8.99 billion |
| Forecast Unit | Billion |
| Growth Rate | 16.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Deployment Type, End User, Geography |
| Companies |
|
Market Segmentation
By Deployment Type
On-Premises
Cloud
By End User
Third-Party Logistics and Transportation
Retail and E-Commerce
Manufacturing
Food and Beverage
Healthcare and Pharmaceuticals
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Singapore
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Omnichannel Fulfillment and Increasing Order Complexity
3.1.2. Labor Productivity and Warehouse Automation Investment
3.1.3. Multi-Client Operations and Traceability Requirements
3.2. Market Restraints
3.2.1. Integration Complexity and Operational Migration Risk
3.2.2. Total Cost, Process Readiness and Implementation Resources
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Cloud-Native and Composable WMS Architecture
4.2. AI-Enabled Warehouse Execution
4.3. Robotics and Automation Integration
5. WAREHOUSE MANAGEMENT SYSTEM MARKET BY DEPLOYMENT TYPE
5.1. Introduction
5.2. On-Premises
5.3. Cloud
6. WAREHOUSE MANAGEMENT SYSTEM MARKET BY END USER
6.1. Introduction
6.2. Third-Party Logistics and Transportation
6.3. Retail and E-Commerce
6.4. Manufacturing
6.5. Food and Beverage
6.6. Healthcare and Pharmaceuticals
6.7. Others
7. WAREHOUSE MANAGEMENT SYSTEM MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Italy
7.4.5. Spain
7.4.6. Netherlands
7.4.7. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Australia
7.6.6. Singapore
7.6.7. Indonesia
7.6.8. Thailand
7.6.9. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Manhattan Associates, Inc.
9.2. Blue Yonder
9.3. SAP SE
9.4. Oracle Corporation
9.5. Infor
9.6. Infios
9.7. Microsoft Corporation
9.8. Tecsys Inc.
9.9. IFS Softeon
9.10. Made4net
9.11. Generix Group
9.12. Logistics Reply
9.13. Mecalux
9.14. Synergy Logistics
9.15. Aptean
9.16. Epicor Software Corporation
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











