
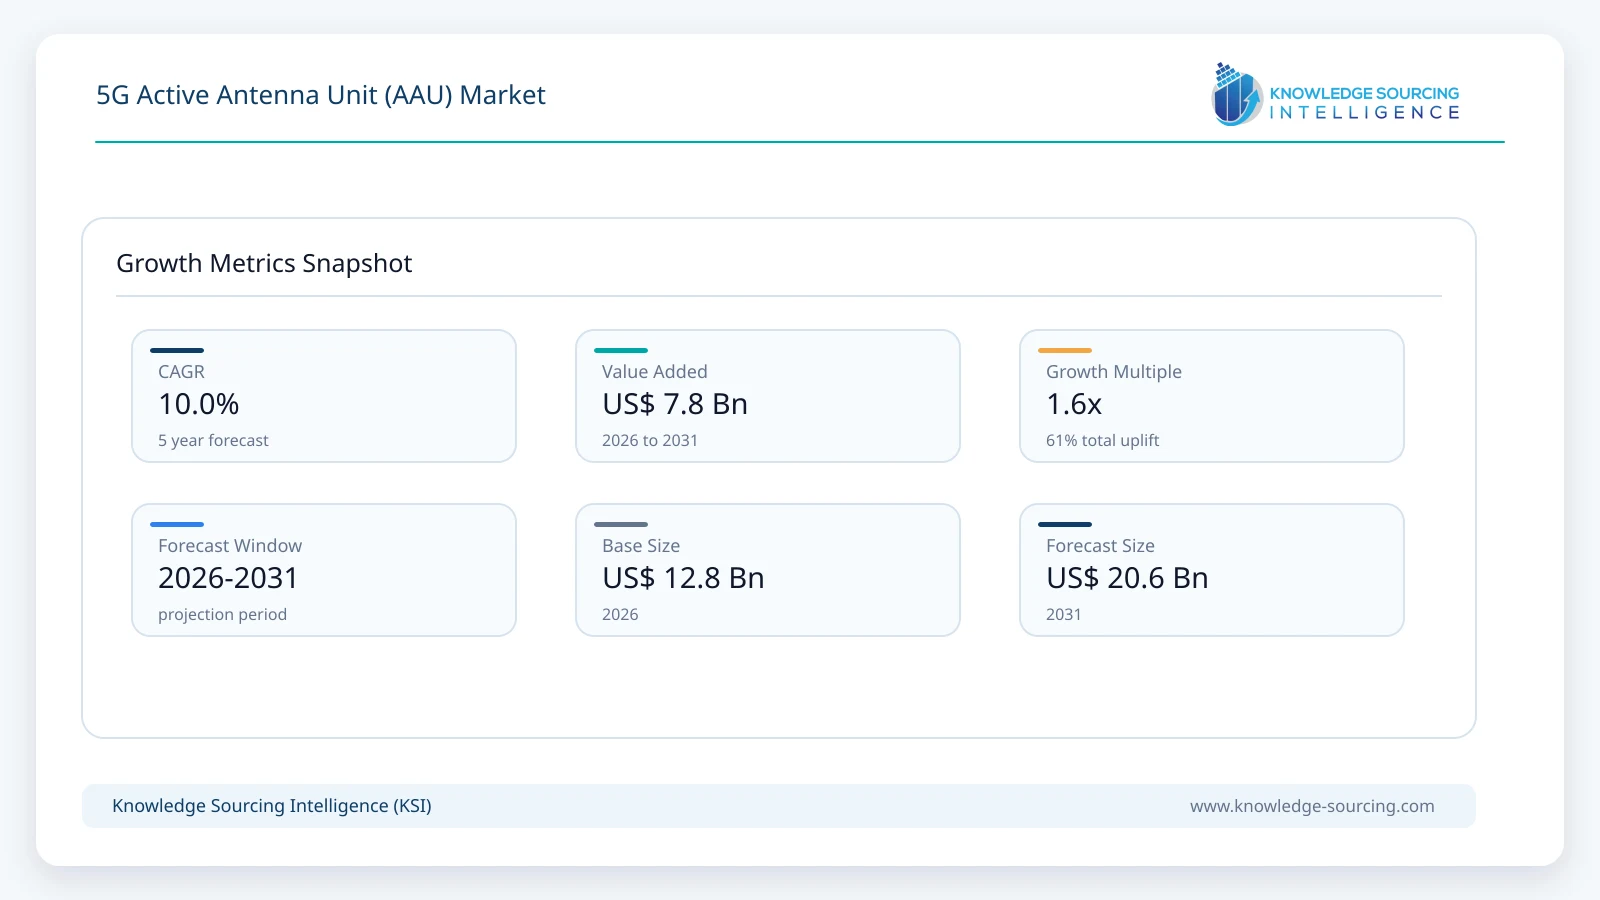
The Global 5G Active Antenna Unit (AAU) market is forecast to grow at a CAGR of 10.0%, reaching USD 20.6 billion in 2031 from USD 12.8 billion in 2026.
Highlights:
- 164T64R systems account for an estimated 43.0% of global AAU market revenue in 2026, retaining a strong position in high-capacity urban TDD deployments.
- 2TDD Sub-6 GHz represents approximately 80.0% of market revenue in 2026, reflecting the established role of Massive MIMO across C-band and comparable mid-band spectrum.
- 3Asia Pacific accounts for an estimated 57.1% of global AAU revenue in 2026, supported by China’s installed 5G network and continued infrastructure expansion in India.
- 4Mobile network operators remain the principal buyers of AAUs, while private and shared-network applications represent smaller but faster-growing opportunities.
- 55.15 million 5G base stations by July 2026China had approximately , while India had 562,971 5G BTSs by June 2026, demonstrating both the maturity of China’s deployment and continued physical network expansion in India.
- 66.4 billion by 2031Global 5G subscriptions are expected to increase from approximately 3.3 billion in mid-2026 to , sustaining radio-capacity requirements even where population coverage is already high.
- 7FDD Massive MIMO, lighter 32T32R radios, low-band active antennas and AI-assisted beamforming represent the principal technology transitions shaping the market through 2031.
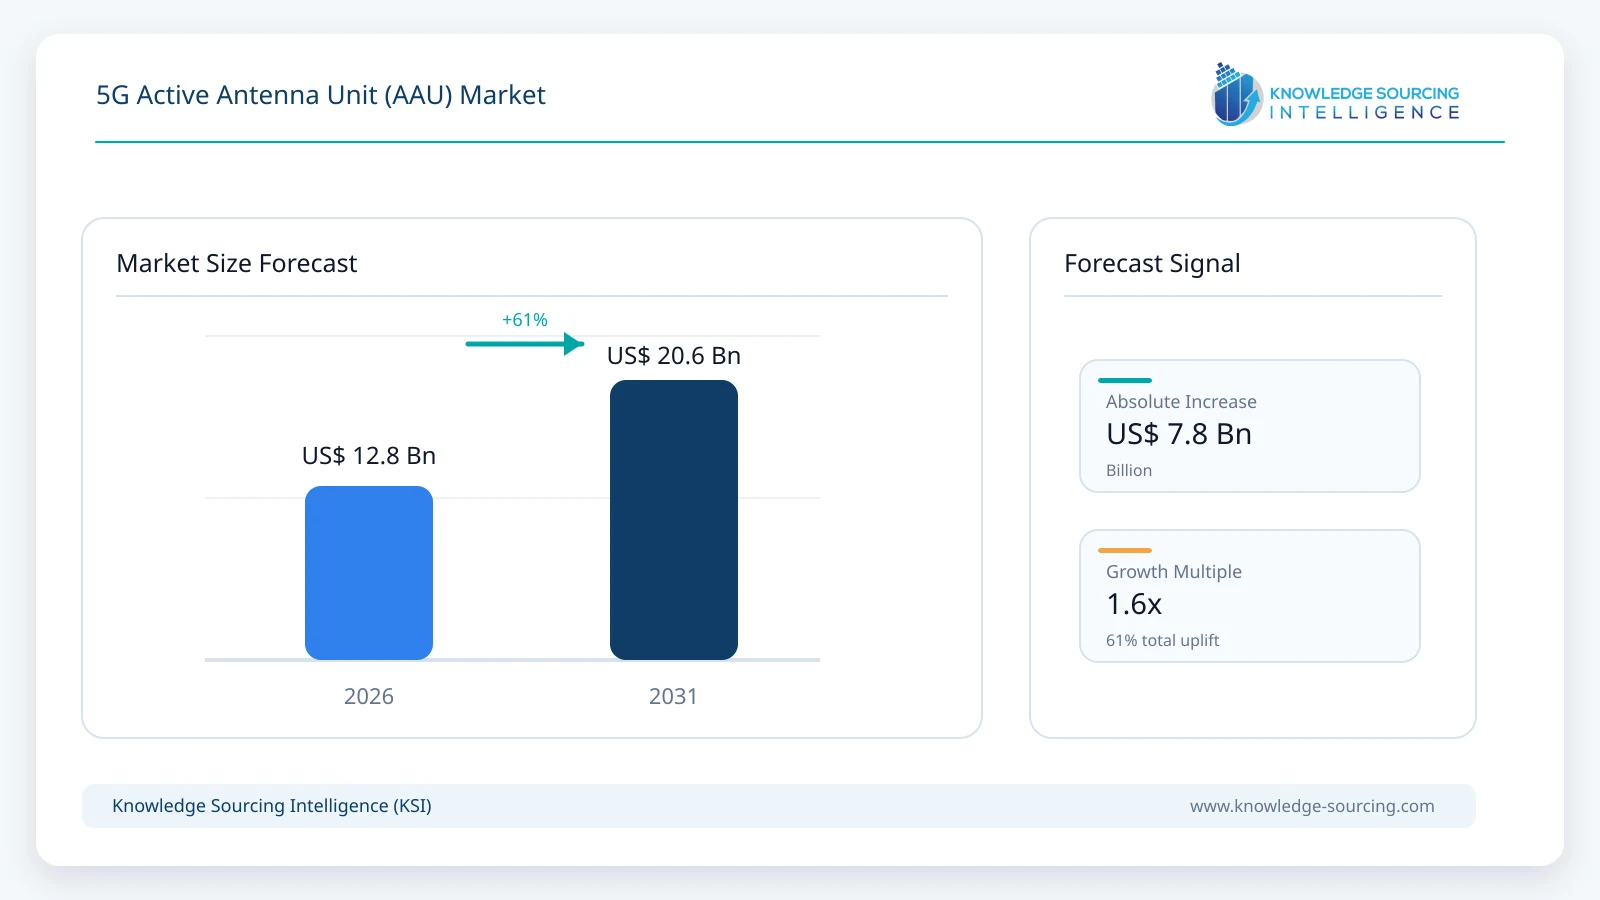
Market growth is supported by continued 5G capacity expansion, broader commercialization of FDD Massive MIMO, additional mid-band spectrum deployment, increasing uplink requirements and the transition toward 5G-Advanced radio networks. Demand is increasingly shifting from first-time 5G coverage deployment toward radio modernization, additional capacity, lower-band Massive MIMO and lighter multiband radio systems.
An Active Antenna Unit integrates radio-frequency electronics with an antenna array, enabling the radio and antenna functions to operate as a coordinated system. Commercial AAUs commonly support 16T16R, 32T32R or 64T64R architectures and use digital beamforming and Massive MIMO to increase spectral efficiency, capacity and cell-edge performance. Ericsson’s commercial portfolio identifies its Massive MIMO products as antenna-integrated radios, while CommScope describes AAUs as systems in which the radio and antenna are integrated into configurations such as 64T64R, 32T32R and 16T16R.
The market covers antenna-integrated Massive MIMO radio systems used across TDD Sub-6 GHz, FDD Sub-6 GHz and selected mmWave networks. It excludes standalone passive antennas, separate remote radio units, baseband equipment, RAN software and passive antenna systems where the radio electronics are not integrated with the antenna system.
Market Overview
Massive MIMO AAUs have become a core element of high-capacity 5G radio networks because they allow operators to generate additional capacity from existing spectrum without proportionally increasing the number of cell sites. Multiple transmit and receive chains operate with large antenna arrays to form beams toward individual users, improve spatial reuse and increase signal quality at the cell edge. This makes AAUs particularly valuable where traffic demand is concentrated and spectrum availability is constrained.
The first major commercial wave centered on 64T64R and 32T32R TDD systems operating primarily in mid-band frequencies. These deployments remain the largest revenue pool, but the technology mix is becoming more diverse. Ericsson’s current portfolio includes 32T32R TDD equipment such as AIR 3267, 64T64R equipment such as AIR 6492 and newer FDD products including AIR 3284 and AIR 3286. Nokia similarly offers Habrok Massive MIMO radios in both 32TRX and 64TRX formats, including FDD and dual-band variants.
This product evolution changes the commercial structure of the market. Operators are no longer maximizing the number of antenna elements at every site. Dense urban cells can justify high-output 64T64R radios, while lighter 32T32R architectures provide attractive capacity, weight and power trade-offs across suburban networks and increasingly across FDD deployments. Wider-band radios can also consolidate several frequency layers into fewer physical units, reducing installation complexity and tower loading.
The geographic profile is changing at the same time. China’s 5G base-station count reached 5.154 million by July 2026, up by 316,000 from the end of 2025. This remains a substantial equipment market, but growth is increasingly associated with network optimization, 5G-Advanced and radio replacement rather than another early-stage nationwide rollout. India remains in a stronger physical expansion cycle, having increased its 5G BTS count from 140,623 in March 2023 to 562,971 in June 2026.
Market Drivers
FDD Massive MIMO is expanding the addressable AAU market
The most important structural expansion opportunity is the movement of Massive MIMO from predominantly TDD mid-band networks into FDD spectrum. Operators have extensive low- and mid-band FDD holdings that historically relied on conventional 2T2R, 4T4R or 8T8R radios. New dual-band and triple-band AAUs allow operators to apply advanced beamforming, improved receive diversity and multi-user MIMO across these frequencies without acquiring additional spectrum.
Commercial deployments demonstrate that FDD Massive MIMO has moved beyond technical trials. Chunghwa Telecom and Ericsson commercially deployed the AIR 3284 triple-band 32T32R FDD Massive MIMO radio in Taiwan, where network capacity increased threefold during the Taipei New Year’s Eve traffic peak. Ericsson also deployed the dual-band AIR 3285 with Yas Tanzania, reporting up to four times the uplink capacity and twice the downlink capacity of traditional 4T4R equipment.
The KSI model therefore projects FDD Sub-6 GHz AAUs to grow at approximately 20.6% annually between 2026 and 2031, substantially faster than the overall AAU market.
Uplink traffic is increasing the commercial value of advanced antenna reception
Mobile networks have historically been engineered around downlink-intensive applications such as video streaming. AI-assisted applications, live video, cloud services, extended reality and increasingly interactive mobile applications are creating stronger uplink requirements. Ericsson’s June 2026 Mobility Report notes that uplink traffic is already growing faster than downlink for many operators, increasing the importance of radio architectures capable of improving uplink capacity and cell-edge reception.
Vendors are responding through additional receive paths, higher output power, AI-assisted beam management and more advanced FDD architectures. Ericsson’s February 2026 portfolio introduced high-power FDD Massive MIMO, new TDD radios, additional eight-receiver products and AI-managed beamforming. AIR 3286, for example, provides up to 640 W across two FDD bands while maintaining the mechanical form factor of the previous generation.
Uplink performance therefore becomes an increasingly important purchasing criterion through 2031 rather than AAU procurement being determined primarily by theoretical peak downlink capacity.
5G-Advanced is extending the radio modernization cycle
The transition toward 5G-Advanced supports continued radio investment in countries that have already achieved broad 5G coverage. 5G-Advanced enhances carrier aggregation, uplink performance, positioning, energy efficiency, network intelligence and differentiated connectivity, increasing the value of newer radios with greater processing capability and wider bandwidth.
China illustrates this transition. More than 5.1 million 5G base stations were operational by July 2026, while 5G-Advanced commercial networks had already expanded across more than 330 cities by mid-year. Infrastructure requirements therefore increasingly center on improving network performance and preparing the radio layer for more advanced functionality rather than simply achieving basic coverage.
Newer AAUs are also designed with wider instantaneous bandwidth and more powerful onboard processing. Ericsson’s AIR 3267 supports 600 MHz instantaneous bandwidth in a 13 kg 32T32R unit, illustrating how manufacturers are increasing capability without proportionally increasing site footprint.
Low-band Massive MIMO broadens the technology beyond urban capacity sites
AAUs have traditionally been associated with dense urban mid-band networks because lower-frequency antennas require larger physical elements, making high-order integrated arrays more difficult to design. Commercial low-band Massive MIMO deployments during 2026 demonstrate that this limitation is weakening.
MTN Nigeria and Huawei deployed the first commercial sub-1 GHz Massive MIMO site in April 2026, integrating extremely large antenna arrays with low-band spectrum and supporting future evolution from LTE toward NR. Huawei and rain subsequently announced a multi-thousand-site deployment in South Africa. Operational results from rain’s existing installations indicated 5 dB improvement in uplink coverage, 3 dB improvement in downlink coverage and capacity of up to three times that of conventional 4T4R equipment.
The ability to apply Massive MIMO to low-frequency spectrum widens AAU demand into suburban and rural coverage networks where operators previously relied predominantly on conventional radio architectures.
Lighter 32T32R systems are improving deployment economics
Tower loading, equipment weight, wind resistance, energy consumption and installation complexity have become important limits on radio modernization. Operators frequently have several generations and frequency layers mounted on the same physical site, making it difficult to keep adding large radio and antenna systems.
This supports increasing adoption of lighter 32T32R products. Ericsson’s AIR 3267 weighs approximately 13 kg while supporting 32T32R Massive MIMO and 600 MHz instantaneous bandwidth. Nokia’s Habrok portfolio similarly includes both 32TRX and 64TRX configurations, with compact form factors and dual-band options.
Under the KSI model, 32T32R AAUs increase from approximately USD 5.25 billion in 2026 to USD 9.89 billion in 2031. Their rising share does not imply that 64T64R systems become obsolete; instead, operators increasingly select radio configuration according to site economics and traffic requirements rather than maximizing the number of RF chains universally.
Market Restraints and Challenges
Initial 5G deployment is maturing in the largest installed market
China remains the largest individual source of global Massive MIMO demand, but its infrastructure profile is materially different from the initial 5G rollout period. With more than five million 5G base stations already installed, incremental requirements increasingly consist of replacements, 5G-Advanced upgrades, spectrum modernization and targeted capacity expansion.
This creates substantial recurring demand but does not support indefinite continuation of early deployment growth rates. Global AAU value growth consequently becomes more dependent on FDD adoption, India and emerging-market deployments, and radio modernization in developed markets.
Equipment efficiency and price reductions moderate revenue growth
Each new radio generation typically provides greater bandwidth, lower power consumption and more processing capability per unit. Semiconductor integration and competition among Huawei, Ericsson, Nokia, ZTE, Samsung and Open RAN suppliers place additional pressure on equipment pricing.
Improving price-performance supports adoption, but it also means growth in installed capacity does not translate directly into equivalent market-value growth. Radio equipment capable of replacing several legacy units can increase operator network capacity while simultaneously reducing the number of physical products required at a site.
High-capacity AAUs remain constrained by power and tower loading
64T64R systems deliver substantial capacity but place greater demands on site power and structural loading than compact radios. Operators need to evaluate mounting space, wind loading, cabling, power availability and structural reinforcement alongside radio performance.
The issue becomes increasingly important in mature networks with several existing frequency bands. Newer 32T32R systems, multiband AAUs and interleaved passive-active architectures can offer a better total-cost solution where sites cannot accommodate additional large arrays.
Operators require measurable returns from further radio upgrades
Mobile operators have already invested heavily in 5G spectrum and radio infrastructure. Further AAU upgrades increasingly need to demonstrate measurable gains in capacity, coverage, energy use or cost per bit rather than being justified primarily by technology generation.
FDD Massive MIMO has a comparatively strong business case because it can increase the productivity of existing spectrum. Equipment consolidation also provides measurable savings where newer radios replace several older units or avoid structural modifications to a tower.
Major Segment Analysis
By Transceiver Configuration
64T64R remains a major commercial configuration, particularly across high-capacity TDD networks. It accounts for an estimated 43.0% of market revenue in 2026 but gradually loses share as the AAU market expands into deployment scenarios where lower weight, lower power consumption and FDD support are more important. The segment is projected to reach approximately USD 7.42 billion in 2031, representing growth of around 6.1% annually.
32T32R records stronger growth and becomes the largest configuration during the forecast period. The segment benefits from lighter TDD radios as well as expanding FDD Massive MIMO adoption. Ericsson’s AIR 3267 is a 32T32R TDD radio, while AIR 3284 and related FDD products also use 32T32R architectures. Nokia’s Habrok portfolio similarly supports both 32TRX and 64TRX products across multiple deployment requirements.
KSI estimates 32T32R revenue at approximately USD 9.89 billion by 2031, equivalent to about 48% of the market.
16T16R and other configurations remain relevant in applications where operators require additional beamforming and diversity but do not need the capacity or site complexity of higher-order arrays. This category retains an estimated 16% market share through the forecast period.
By Spectrum and Duplexing
TDD Sub-6 GHz remains the largest market category because C-band, 2.5 GHz and comparable mid-band frequencies form the principal capacity layers for many 5G networks. The category grows from approximately USD 10.24 billion in 2026 to USD 14.21 billion in 2031, but its market share declines as FDD systems expand.
FDD Sub-6 GHz is the fastest-growing major spectrum category. The segment increases from approximately 17% of market revenue in 2026 to 27% by 2031, supported by dual-band, triple-band and low-band Massive MIMO deployments. Commercial examples across Taiwan, Tanzania, Nigeria and South Africa demonstrate applicability across both high-capacity and coverage-oriented networks.
mmWave remains a specialized segment rather than becoming a major global AAU architecture. KSI estimates mmWave AAU revenue at approximately USD 824 million by 2031, with applications concentrated in dense capacity hotspots, selected FWA deployments, venues and other environments where short propagation distances are commercially acceptable.
By Deployment Environment
Dense urban and high-capacity networks remain the largest AAU deployment environment through 2031. These locations typically have the highest traffic loads and provide the strongest economic justification for large antenna arrays and spatial multiplexing.
Suburban and general macro networks account for a substantial second category and increasingly use lighter 32T32R systems where network capacity needs to increase without imposing excessive site weight and energy requirements.
Rural and coverage-oriented AAUs represent the smallest 2026 category but are projected to grow at approximately 17.4% annually through 2031. Low-band Massive MIMO, expanding FDD systems and greater focus on uplink performance are allowing active antenna technology to address network requirements beyond conventional metropolitan capacity hotspots.
By End User
Mobile network operators remain overwhelmingly responsible for AAU expenditure because nationwide radio networks account for the majority of high-capacity Massive MIMO deployment. Their demand encompasses new site installation, spectrum modernization, capacity expansion and replacement of earlier-generation radio systems.
Private and enterprise networks remain smaller because most installations use fewer radio sectors and frequently rely on small cells. However, high-capacity industrial sites, ports, transportation facilities and large campuses can justify Massive MIMO where dedicated spectrum and intensive device connectivity create greater capacity requirements.
Neutral-host and shared-infrastructure models provide another smaller growth opportunity, particularly in dense venues and shared networks where one active infrastructure layer can support several service providers.
Regional Analysis
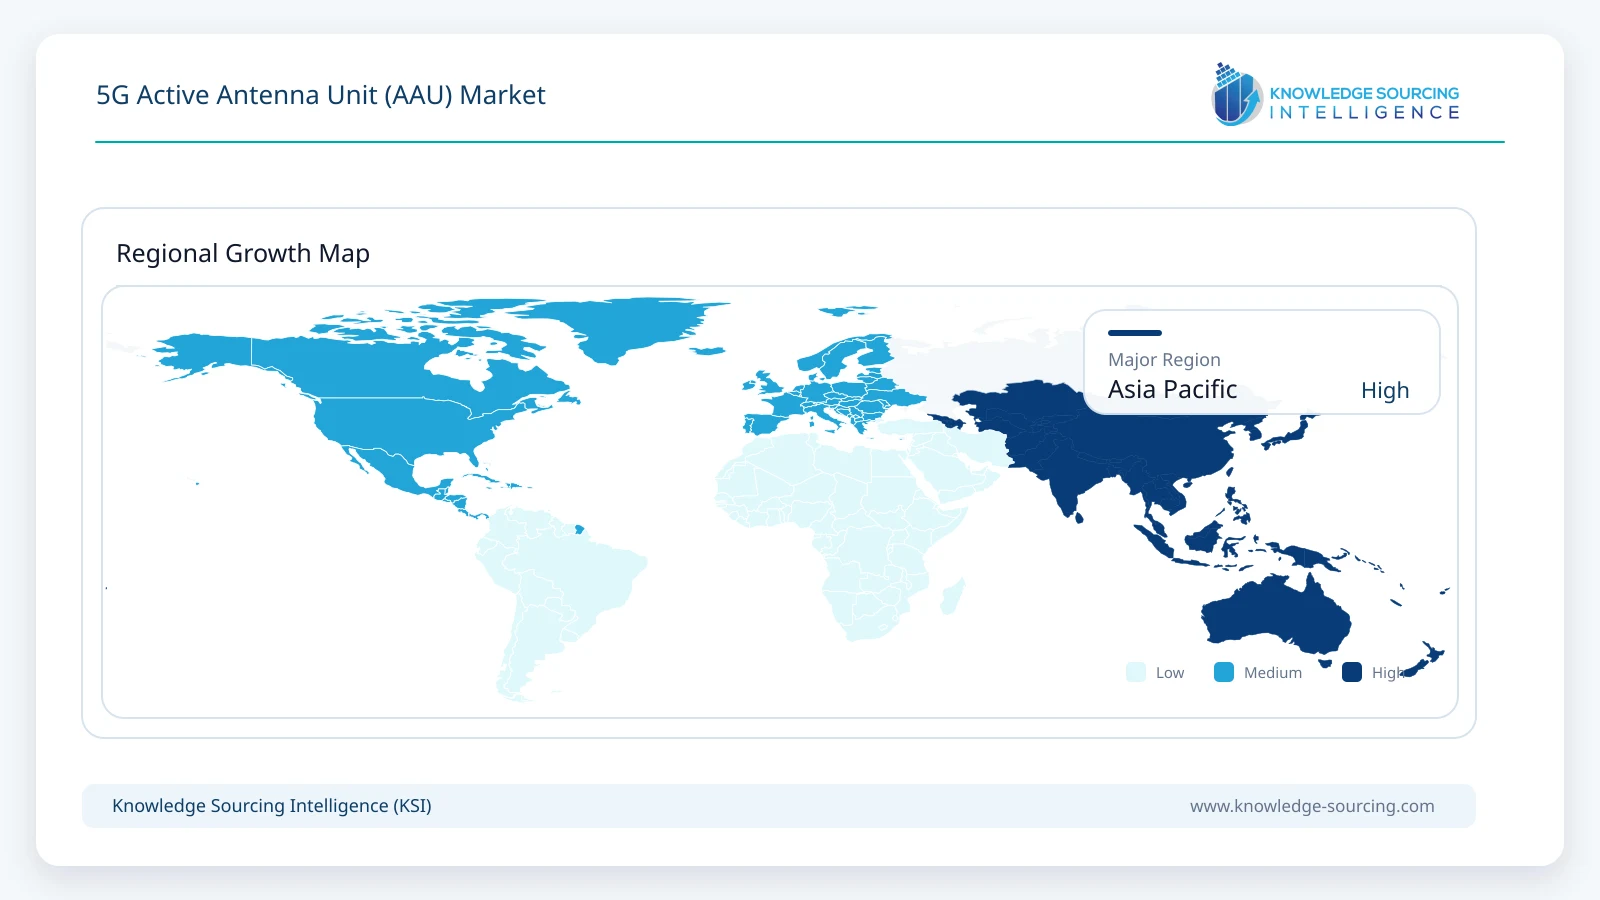
Asia Pacific remains the largest market and is projected to reach approximately USD 11.33 billion by 2031. China continues to dominate the installed base, but India contributes an increasing share of incremental demand. India’s 5G network expanded to 562,971 BTSs by June 2026 and Ericsson expects the country’s 5G subscriptions to exceed 1.1 billion by 2031.
Japan and South Korea increasingly emphasize radio modernization and 5G-Advanced, while Southeast Asian markets continue expanding physical 5G infrastructure. The regional mix therefore shifts gradually away from China even though Asia Pacific remains the largest global AAU market.
North America remains an important high-value market because of extensive mid-band spectrum deployment and continuing radio modernization. Operators increasingly focus on capacity, uplink performance and radio replacement rather than national first-time coverage. FDD Massive MIMO is particularly relevant because operators hold substantial low- and mid-band FDD spectrum that can be modernized without acquiring additional spectrum.
Europe follows a similar modernization trajectory. Nokia’s March 2026 Virgin Media O2 agreement includes its latest Massive MIMO radio portfolio as part of a multi-year UK network transformation program, demonstrating continued AAU investment in markets where basic 5G coverage is already extensive.
The Middle East and Africa record some of the strongest percentage growth through 2031. The region benefits from both conventional 5G expansion and newer FDD and low-band Massive MIMO applications. Commercial deployments in Tanzania, Nigeria and South Africa during 2026 demonstrate that the technology is increasingly relevant to coverage improvement as well as high-density urban networks.
Technology Outlook
FDD and Low-Band Massive MIMO
FDD Massive MIMO represents the most important expansion of the AAU addressable market. Operators can apply active antenna capabilities to substantial spectrum holdings that have historically been served by conventional radios. Dual- and triple-band systems additionally allow several frequency layers to be consolidated into one integrated unit.
Low-band deployments extend this opportunity further. Successful sub-1 GHz commercial implementations demonstrate that active antenna systems can improve spectral efficiency and coverage across frequencies historically considered difficult for large arrays.
AI-Managed Beamforming
AI is becoming part of radio operation rather than remaining solely a network-planning function. Ericsson’s February 2026 RAN portfolio includes AI-managed beamforming and neural-network accelerators in Massive MIMO radios, enabling more radio optimization to occur directly within the network.
ZTE’s commercial deployment with Zong in Pakistan demonstrates a second approach. AI-based automatic beam adaptation adjusted the number and direction of FDD Massive MIMO beams according to traffic conditions and increased busy-hour user downlink throughput by up to 39.4%.
Lightweight and Multiband AAUs
Future radio modernization depends on increasing capacity without continuously increasing site footprint. This is accelerating development of lighter AAUs, greater instantaneous bandwidth and multiband architectures.
Ericsson’s AIR 3267 combines 32T32R Massive MIMO with 600 MHz instantaneous bandwidth at approximately 13 kg, while Nokia’s Habrok portfolio includes compact 32TRX and 64TRX radios together with dual-band and FDD configurations.
The competitive advantage increasingly comes from capacity delivered per kilogram, watt and unit of tower space rather than antenna-element count alone.
Recent Developments
July 2026: rain South Africa and Huawei announced the commercial expansion of a multi-thousand-site sub-1 GHz Massive MIMO 5G network. Existing commercial installations showed 5 dB improvement in uplink coverage, 3 dB improvement in downlink coverage and up to three times the capacity of conventional 4T4R equipment. The announcement is directly relevant to AAUs because it demonstrates large-scale commercialization of integrated Massive MIMO radio technology in low-band spectrum.
June 2026: Ericsson and Yas Tanzania announced Africa’s first AIR 3285 deployment. AIR 3285 is a dual-band FDD Massive MIMO radio weighing approximately 31 kg and is designed for sites requiring greater uplink capacity. Ericsson states that it can provide up to four times the uplink capacity and twice the downlink capacity of conventional 4T4R systems.
March 2026: Nokia expanded its agreement with TIM Brasil to modernize the operator’s 5G infrastructure across a further 14 states. The equipment package specifically includes Habrok Massive MIMO radios, AirScale baseband and related AI-enabled network-management technologies, making the development directly relevant to the AAU market.
February 2026: Zong and ZTE announced the commercial launch of AI-based multibeam FDD Massive MIMO in Pakistan. The initial deployment increased busy-hour user downlink throughput by up to 39.4% and demonstrates how software-controlled beam adaptation is increasingly being combined with active antenna hardware.
February 2026: Tejas Networks signed an agreement with NEC Corporation to manufacture and supply 5G Massive MIMO radios for global customers. Tejas states that its mobility portfolio includes both 32TR and 64TR Massive MIMO radios compliant with 3GPP and O-RAN standards, adding another manufacturing participant to the international AAU supply base.
February 2026: Ericsson introduced a new range of AI-ready Massive MIMO radios, including AIR 3286, AIR 3211, AIR 3267 and AIR 6492. The portfolio extends FDD Massive MIMO, introduces broader bandwidth and higher output-power options and embeds neural-network acceleration for radio-level AI processing.
February 2026: Chunghwa Telecom and Ericsson announced the first commercial deployment of triple-band FDD Massive MIMO on a live network in Northeast Asia. The AIR 3284 deployment delivered three times higher network capacity during the 2026 Taipei 101 New Year’s Eve event, providing commercial validation of FDD Massive MIMO under extreme traffic conditions.
Competitive Landscape
Huawei, Ericsson, Nokia, ZTE and Samsung remain the principal global AAU suppliers because successful Massive MIMO equipment requires tightly integrated RF electronics, antenna design, baseband compatibility, proprietary silicon and beamforming software. The major vendors also benefit from existing operator relationships and the ability to integrate AAUs into nationwide RAN architectures.
Ericsson’s portfolio spans 32T32R and 64T64R TDD systems together with dual- and triple-band FDD Massive MIMO radios. Nokia similarly offers 32TRX and 64TRX Habrok systems, while Huawei has expanded Massive MIMO from conventional mid-band configurations into tri-band FDD and sub-1 GHz architectures. ZTE increasingly differentiates through AI-controlled beamforming and wider Massive MIMO deployment across FDD networks.
The competitive field is broadening through Open RAN and regional manufacturing. Mavenir maintains a Massive MIMO OpenBeam portfolio, NEC and Fujitsu participate in Open RAN radio systems, while Tejas Networks manufactures 32TR and 64TR Massive MIMO products and secured a supply agreement with NEC in February 2026. VVDN also offers both 32T32R and 64T64R n78 Massive MIMO radio units.
Comba Telecom, Airspan, JMA Wireless, Baicells and Parallel Wireless address additional operator, private-network and open-radio requirements. Competitive differentiation increasingly centers on equipment weight, supported spectrum combinations, output power, instantaneous bandwidth, energy efficiency, Open RAN compatibility and AI-enabled radio optimization rather than simply maximizing the number of antenna elements.
Analyst View
The AAU market is shifting from a first-generation 5G deployment story toward a broader radio-modernization market. TDD Massive MIMO remains the commercial foundation, but its growth is increasingly supplemented by FDD systems, low-band active antennas and replacement of early 5G radios with lighter and more capable equipment. This produces a more sustainable market trajectory than assuming that the rapid physical rollout rates recorded during the first half of the decade continue unchanged.
The most important change in the segment structure is the increasing role of 32T32R. 64T64R remains valuable where operators require maximum capacity and spatial multiplexing, particularly in dense TDD networks, but newer 32T32R products provide increasingly attractive capacity-to-weight and capacity-to-power economics. As FDD Massive MIMO expands, 32T32R consequently becomes the largest configuration by 2031.
Spectrum diversification represents the second major shift. TDD Sub-6 GHz still accounts for the majority of AAU revenue, but FDD Sub-6 GHz grows considerably faster as operators modernize long-held low- and mid-band spectrum. Commercial deployments in Taiwan, Tanzania, Nigeria and South Africa indicate that FDD and low-band Massive MIMO are progressing from isolated trials into repeatable operator deployments.
mmWave remains commercially relevant but considerably smaller than Sub-6 GHz AAUs. Short propagation distances and more limited nationwide deployment constrain its share even though specialized capacity and FWA applications support strong percentage growth from a low base.
Geographically, China remains the largest installed ecosystem but contributes a progressively smaller share of incremental growth as its national rollout matures. India continues adding physical network capacity, while Europe and North America create replacement and modernization opportunities. Middle Eastern and African operators increasingly provide a third source of growth through new 5G networks and the emerging use of FDD Massive MIMO for wide-area coverage.
5G Active Antenna Unit (AAU) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 12.8 billion |
| Total Market Size in 2031 | USD 20.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | By Transceiver Configuration, By Spectrum and Duplexing, By Deployment Environment, End User |
| Companies |
|
Market Segmentation
By Transceiver Configuration
· 64T64R
· 32T32R
· 16T16R & Other Configurations
By Spectrum and Duplexing
· TDD Sub-6 GHz
· FDD Sub-6 GHz
· mmWave
By Deployment Environment
· Dense Urban & High-Capacity Networks
· Suburban & General Macro Networks
· Rural & Coverage-Oriented Networks
By End User
· Mobile Network Operators
· Private & Enterprise Network Operators
· Neutral Host & Shared Infrastructure Providers
By Geography
North America
· United States
· Canada
· Mexico
South America
· Brazil
· Argentina
· Others
Europe
· United Kingdom
· Germany
· France
· Italy
· Spain
· Others
Middle East and Africa
· Saudi Arabia
· UAE
· South Africa
· Nigeria
· Others
Asia Pacific
· China
· India
· Japan
· South Korea
· Indonesia
· Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Market Segmentation
2.4. Key Market Indicators
2.5. Market Estimation and Forecast Assumptions
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. 5G Subscription and Mobile Traffic Outlook
3.5. Radio Modernization and Replacement Analysis
3.6. Site Power, Weight and Deployment Economics
3.7. Massive MIMO Pricing and Technology Evolution
3.8. Porter’s Five Forces Analysis
3.9. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. FDD and Low-Band Massive MIMO
4.2. AI-Managed Beamforming
4.3. Lightweight and Multiband AAUs
5. 5G ACTIVE ANTENNA UNIT MARKET BY TRANSCEIVER CONFIGURATION
5.1. Introduction
5.2. 64T64R
5.3. 32T32R
5.4. 16T16R & Other Configurations
6. 5G ACTIVE ANTENNA UNIT MARKET BY SPECTRUM AND DUPLEXING
6.1. Introduction
6.2. TDD Sub-6 GHz
6.3. FDD Sub-6 GHz
6.4. mmWave
7. 5G ACTIVE ANTENNA UNIT MARKET BY DEPLOYMENT ENVIRONMENT
7.1. Introduction
7.2. Dense Urban & High-Capacity Networks
7.3. Suburban & General Macro Networks
7.4. Rural & Coverage-Oriented Networks
8. 5G ACTIVE ANTENNA UNIT MARKET BY END USER
8.1. Introduction
8.2. Mobile Network Operators
8.3. Private & Enterprise Network Operators
8.4. Neutral Host & Shared Infrastructure Providers
9. 5G ACTIVE ANTENNA UNIT MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Nigeria
9.5.5. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Competitive Positioning
10.2. 32T32R and 64T64R Portfolio Benchmarking
10.3. TDD and FDD Massive MIMO Capability Analysis
10.4. Radio Weight, Bandwidth and Power Benchmarking
10.5. AI-Enabled Radio Capability Analysis
10.6. Open RAN and Multivendor AAU Landscape
10.7. Strategic Developments
10.8. Competitive Dashboard
11. COMPANY PROFILES
11.1. Huawei Technologies Co., Ltd.
11.2. Telefonaktiebolaget LM Ericsson
11.3. Nokia Corporation
11.4. ZTE Corporation
11.5. Samsung Electronics Co., Ltd.
11.6. Mavenir Systems, Inc.
11.7. NEC Corporation
11.8. Fujitsu Limited
11.9. Tejas Networks Limited
11.10. Airspan Networks Holdings Inc.
11.11. JMA Wireless
11.12. Comba Telecom Systems Holdings Limited
11.13. Baicells Technologies Co., Ltd.
11.14. Parallel Wireless, Inc.
11.15. VVDN Technologies
11.16. CommScope Inc.
12. ANALYST VIEW
13. APPENDIX
13.1. Research Methodology
13.2. Market Estimation and Assumptions
13.3. Scope and Double-Counting Controls
13.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











