
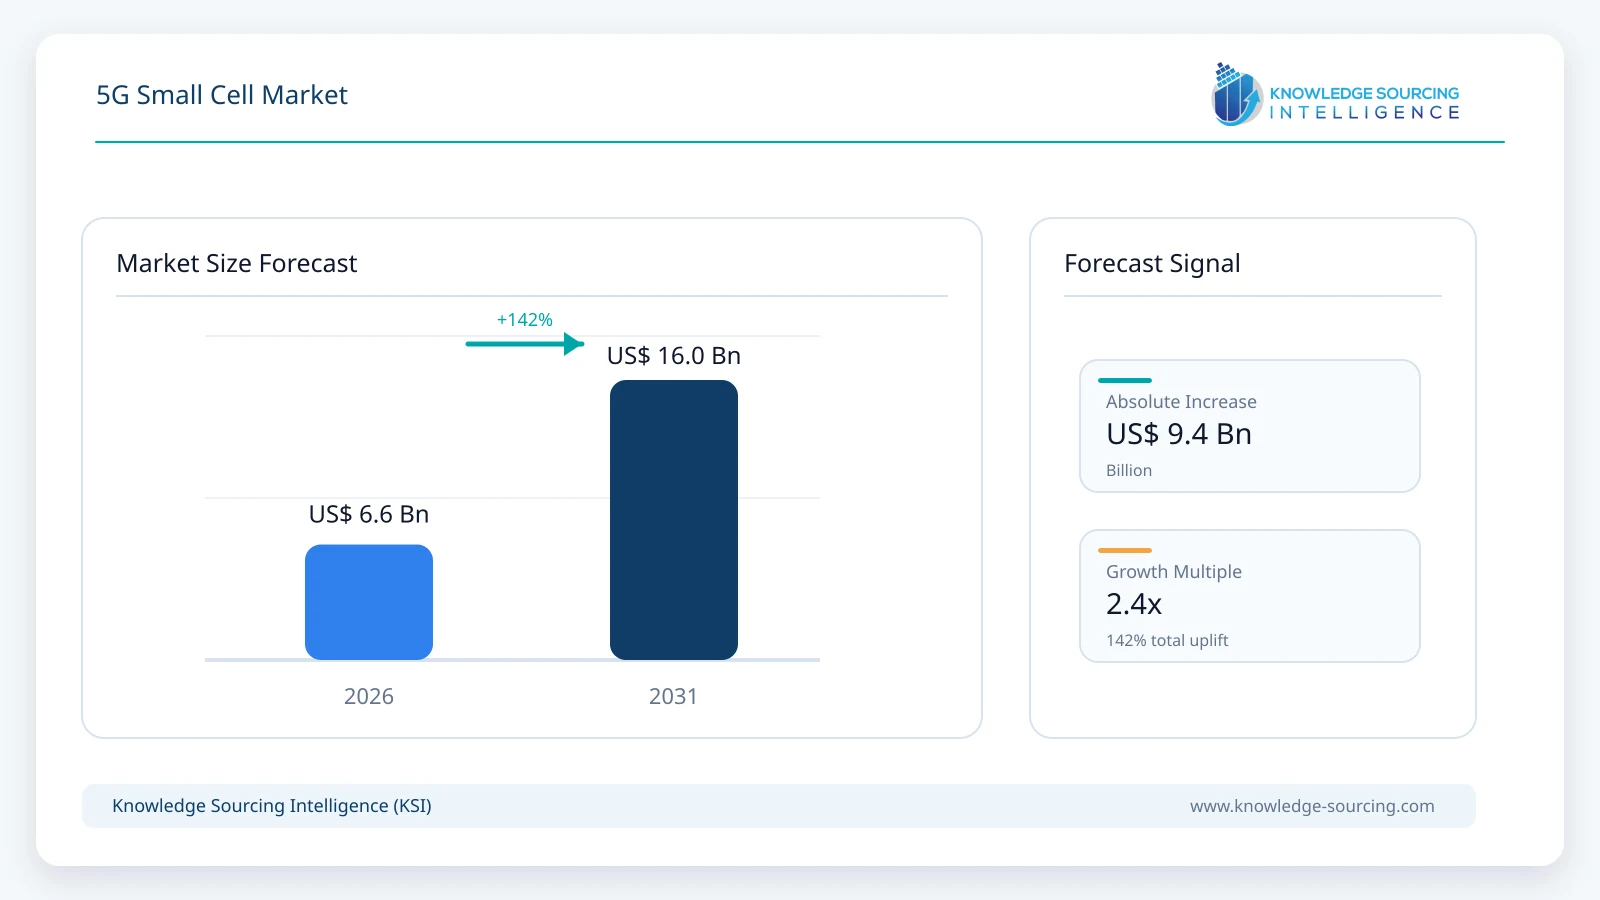
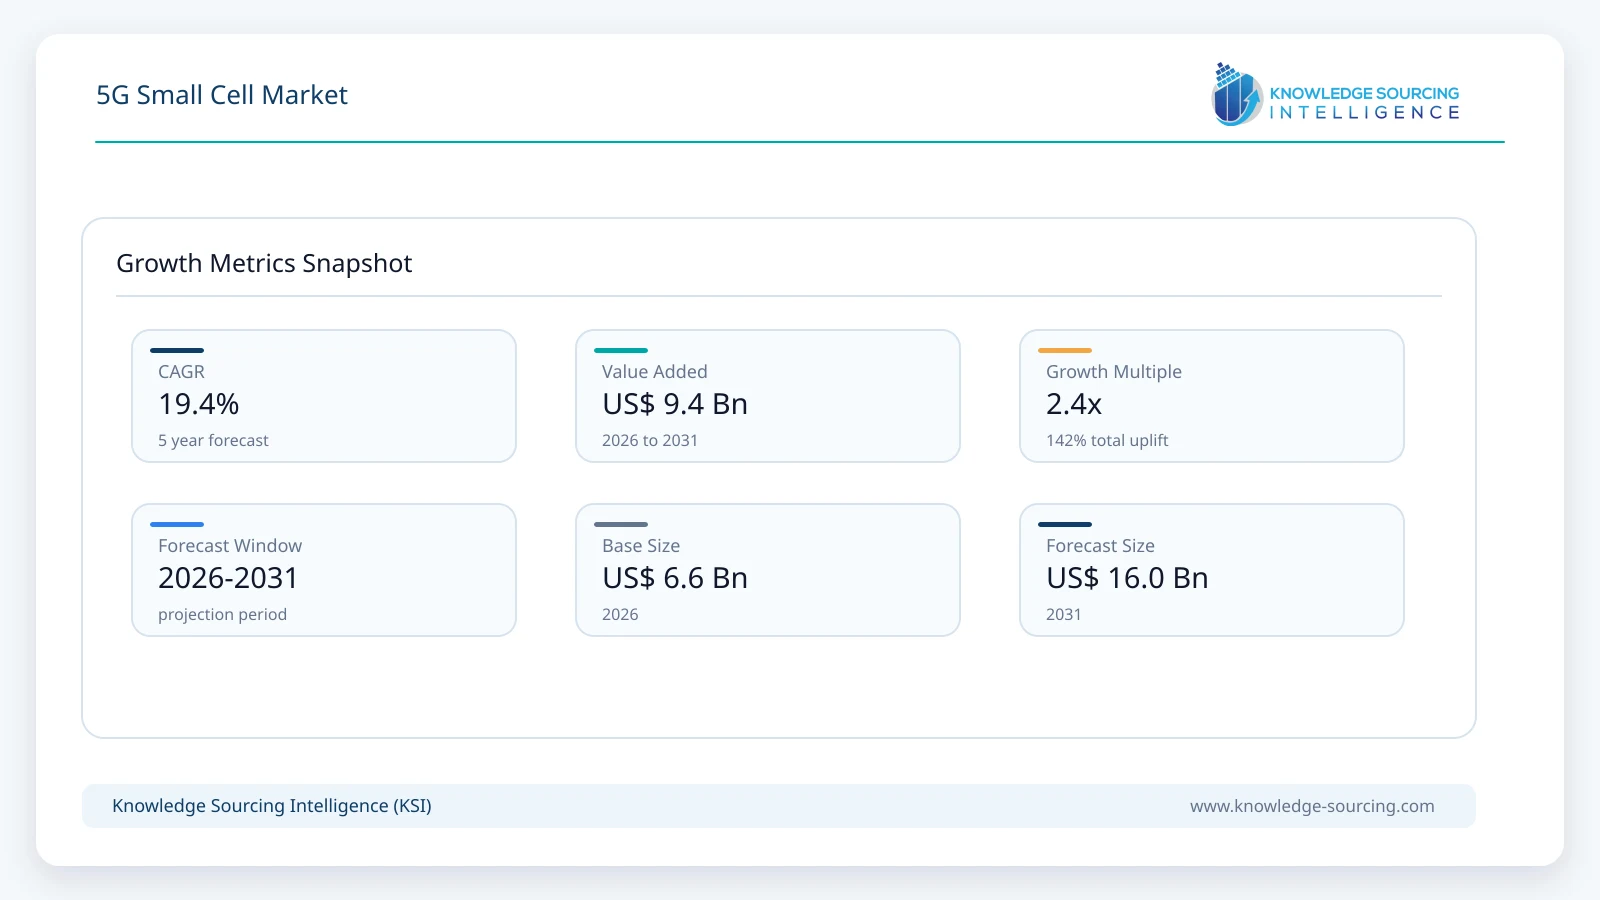
The 5G Small Cell Market is anticipated to grow at a CAGR of 19.4%, from USD 6.6 billion in 2026 to USD 16.0 billion by 2031.
Highlights:
- 1Indoor small cells account for approximately 64% of market revenue in 2026, supported by enterprise buildings, venues, campuses and neutral-host deployments.
- 2Sub-6 GHz remains the dominant spectrum category, while mmWave small cells are projected to grow at approximately 26.4% annually through 2031 as localized high-capacity deployments increase.
- 3Private and enterprise deployments are the fastest-growing major customer segment at approximately 26.8% annually, supported by factories, logistics facilities, campuses and other dedicated-network environments.
- 4Open and virtualized small-cell architectures are expanding considerably faster than conventional integrated systems as operators and enterprises seek greater software flexibility and vendor choice.
- 5Asia Pacific remains the largest regional opportunity, supported by dense urban networks, continued 5G expansion and growing enterprise/private-network adoption.
Growth is supported by the need to improve indoor 5G coverage, densify capacity in high-traffic urban locations, extend private 5G into enterprises and industrial facilities, support neutral-host infrastructure and provide more targeted radio capacity without relying entirely on additional macro sites.
5G small cells are compact, lower-power radio access nodes designed to provide localized cellular coverage and capacity. They include indoor enterprise small cells, outdoor micro and pico cells, neutral-host radio systems and private-network small cells operating across Sub-6 GHz and mmWave spectrum. The market covers small-cell radio hardware, integrated baseband functionality and embedded software directly associated with operating the small-cell RAN. Macro base stations, conventional distributed antenna systems, Wi-Fi access points, standalone mobile-core platforms and passive site infrastructure are excluded.
Small cells are becoming increasingly important as 5G shifts from broad population coverage toward the quality of connectivity available inside buildings and at specific traffic hotspots. Ericsson states that more than 80% of mobile data is consumed indoors, while Nokia similarly identifies indoor mobile traffic as a major coverage and capacity challenge. Small-cell systems allow radio processing to be positioned substantially closer to users than an outdoor macro network, reducing building penetration losses while adding dedicated capacity.
The first phase of 5G network construction relied primarily on upgrading macro sites with new spectrum and Massive MIMO radios. This model efficiently created national population coverage, but macro networks cannot solve every capacity and coverage problem. Modern building materials can attenuate outdoor cellular signals, high-rise offices can create complex indoor radio conditions and dense urban locations may require more capacity than additional macro spectrum alone can efficiently provide. Small cells address these gaps by moving the radio closer to the user and creating dedicated localized capacity.
Indoor deployment represents the largest commercial opportunity. Ericsson’s Radio Dot System, Nokia’s indoor small-cell portfolio, Airspan’s AirUnity and SpiderCloud platforms, Comba’s enterprise picocells and products from Mavenir, Samsung and other suppliers illustrate the breadth of radio architectures now available for offices, shopping centers, hospitals, airports, factories and venues. The market is also expanding beyond traditional single-operator deployments. Neutral-host systems allow one physical indoor network to serve subscribers from several mobile operators, spreading infrastructure cost across multiple users of the facility.
Ericsson and Freshwave’s UK deployment provides a current example. Their 5G on Omni service uses Ericsson Radio Dot small cells to provide indoor 4G and 5G connectivity from all UK mobile operators through common infrastructure. Ericsson states that the system requires less space and can use up to 50% less energy than a traditional DAS configuration.
The second major opportunity is private cellular. Manufacturing facilities, warehouses, ports, energy sites and campuses increasingly deploy private 5G where predictable latency, mobility, security or device density makes cellular connectivity preferable to relying exclusively on Wi-Fi. Small cells are well suited to these installations because enterprises generally need targeted coverage across defined facilities rather than a nationwide macro network.
Market Drivers
Indoor 5G coverage is becoming a dedicated infrastructure requirement
A strong outdoor 5G signal does not guarantee satisfactory indoor performance. Modern energy-efficient glass, concrete and metallic building materials can substantially attenuate cellular signals, while high concentrations of users can create capacity constraints even where coverage technically exists.
Ericsson reports that more than 80% of mobile data is consumed indoors, while Nokia states that approximately 80% of mobile traffic originates indoors. Nokia also indicates that only a small proportion of buildings currently use dedicated indoor mobile infrastructure, leaving a substantial addressable deployment base.
Small cells provide dedicated indoor radio capacity without requiring the extensive RF distribution architecture associated with conventional DAS. Digital architectures can also make multi-band and multi-operator deployments easier to scale.
The commercial proposition is increasingly tied to building productivity and tenant experience rather than only operator network engineering. Property owners, enterprise IT teams and neutral-host providers therefore become relevant purchasing stakeholders alongside mobile operators.
Neutral-host architecture improves the economics of indoor deployment
Installing separate indoor networks for every mobile operator can be difficult to justify in many commercial buildings. Neutral-host architecture changes this model by allowing multiple operators to use common indoor radio infrastructure.
Freshwave’s 5G on Omni service demonstrates this approach in the United Kingdom. Ericsson Radio Dot technology provides common infrastructure for multiple national operators, while Freshwave manages the indoor system centrally. The architecture allows building owners to provide operator-independent mobile connectivity without installing a completely separate system for every carrier.
A similar approach is developing in the Middle East. ACES deployed an O-RAN-based neutral-host indoor 4G/5G small-cell network at King Abdullah Financial District in Riyadh in May 2026. The deployment uses common indoor infrastructure while maintaining separation between participating operators.
Neutral-host deployments are particularly attractive in offices, airports, hospitals, retail developments and large mixed-use properties where users expect connectivity across several mobile networks.
Private 5G broadens small-cell demand beyond mobile operators
Private networks are creating a second substantial buyer group for small-cell infrastructure. Enterprises can deploy dedicated radio networks using licensed, shared or locally available spectrum and connect industrial devices without relying entirely on national public networks.
Factories can use private 5G for mobile robots, machine connectivity and video analytics; logistics facilities can connect scanners, vehicles and inventory systems; and energy or mining operations can use private cellular where Wi-Fi coverage or mobility performance is insufficient.
Small cells fit these environments because they can be deployed according to the physical layout and capacity requirements of one site. Airspan’s AirUnity portfolio supports both public-operator and enterprise deployments, while Nokia positions small cells as an important component of private 5G infrastructure. BLiNQ, Baicells, Mavenir, JMA Wireless and several other suppliers similarly address enterprise and industrial networks.
Private-network small-cell revenue is projected to reach approximately USD 3.7 billion by 2031, as enterprise deployments become a materially larger part of total demand.
Operators require targeted densification rather than additional macro sites everywhere
Mobile traffic growth does not occur uniformly across a network. Stadiums, transport hubs, shopping districts and city centers can experience much higher traffic density than surrounding areas. Adding another high-power macro site may be difficult because of site availability, planning restrictions and interference considerations.
Outdoor small cells allow operators to place radio capacity closer to these demand concentrations. Ericsson offers street-level radios that can be mounted on existing infrastructure such as street furniture and lighting poles, reducing the physical footprint compared with conventional macro construction.
Vodafone Idea’s network expansion in India provides another example of targeted densification. Ericsson has deployed new 4G and 5G sites, additional radio layers and High-Performance Small Cell infrastructure across several telecom circles as part of the operator’s network expansion.
The economics become increasingly attractive as national coverage matures and operators need to improve network quality in specific locations rather than simply add geographic coverage.
Open and virtualized architectures expand deployment flexibility
Small cells are becoming more software defined. Conventional systems typically combine radio and baseband functionality within a tightly integrated vendor architecture, while newer platforms support virtualized baseband functions, standardized interfaces and Open RAN configurations.
Airspan’s AirUnity supports both integrated all-in-one and Split 2 architectures, allowing operators to choose between embedded processing and more distributed deployment models. The same platform supports LTE, 5G NSA and 5G SA, reducing the requirement for separate hardware during network migration.
The ACES deployment in Saudi Arabia demonstrates a different architecture using an O-RAN Split 7.2 small-cell design. Such deployments allow radio and baseband elements to be separated and potentially sourced or managed more flexibly.
Open and virtualized small-cell systems are projected to become a much larger part of the market through 2031 as enterprise networks, neutral hosts and operators seek more flexible network economics.
Small cells can improve energy and space efficiency indoors
Large indoor DAS installations require head-end equipment, RF distribution and significant cabling across a building. Digital small-cell architectures can reduce some of this infrastructure by placing compact radios nearer to users.
Ericsson states that Freshwave’s 5G on Omni deployment can consume up to 50% less energy than a DAS solution while requiring less communications-room space and cabling. Its wider neutral-host analysis also highlights meaningful space and power reductions compared with conventional indoor architectures.
Energy efficiency becomes increasingly relevant because building owners and operators need to evaluate the total operating cost of indoor networks rather than only the initial equipment price.
Market Restraints and Challenges
Site acquisition remains a constraint for outdoor densification
Small cells reduce the physical footprint of a radio site, but they do not eliminate the requirement for a suitable mounting point, power, backhaul and local approval. Dense urban deployments can involve negotiations with municipalities, utilities, building owners and street-furniture operators.
The economics of individual outdoor small cells can also deteriorate when each site requires customized civil work. Standardized mounting, shared infrastructure and access to existing street furniture therefore remain important to achieving deployment scale.
This makes outdoor densification structurally slower than simply shipping additional radios. Airspan has described dense urban small-cell deployment as a sustained optimization cycle where individual build programs can extend over several years rather than a one-time network expansion event.
Fiber and power availability can determine deployment economics
A compact radio still needs connectivity to the wider network. Buildings without suitable fiber, Ethernet or existing structured cabling can require additional infrastructure before small cells can be activated.
Outdoor deployment faces similar constraints. A streetlight may provide an ideal radio location but require changes to electrical supply or backhaul before it can host a small cell.
Wireless backhaul and integrated power architectures can reduce these limitations, but site economics continue to vary materially by location. The market therefore favors solutions capable of operating across several backhaul and power configurations.
Wi-Fi remains a strong alternative inside enterprises
Private cellular does not replace Wi-Fi across every enterprise environment. Wi-Fi equipment is widely available, familiar to IT departments and economically effective for many office applications.
The small-cell business case is strongest where mobility, deterministic performance, security, wide-area coverage or operational technology requirements justify cellular infrastructure. Warehouses, manufacturing plants, healthcare facilities and other environments with mobile industrial assets therefore present stronger opportunities than a conventional office seeking only general internet access.
The market expands alongside Wi-Fi rather than through wholesale replacement of enterprise wireless LAN infrastructure.
Multi-operator indoor systems require commercial coordination
Neutral-host technology can allow several carriers to use common infrastructure, but the technical solution does not eliminate commercial complexity. Operators need to agree on spectrum, connection arrangements, service levels and operating responsibilities.
Building owners may also be reluctant to fund infrastructure unless enough operator participation is secured. Neutral hosts increasingly solve this problem by managing the commercial relationship between property owners and carriers, but rollout can still take longer than a single-operator installation.
Major Segment Analysis
Indoor Small Cells: Largest Deployment Segment
Indoor small cells remain the largest deployment segment as enterprises, venues and neutral hosts seek dedicated coverage that cannot be consistently delivered from outdoor macro networks.
The segment is projected to reach approximately USD 10.6 billion by 2031. Growth is supported by office buildings, airports, hospitals, stadiums, factories and mixed-use developments, with neutral-host architecture expanding the addressable market for buildings where separate infrastructure for each operator would be uneconomic.
Ericsson’s Radio Dot installed base spans operators and venues across numerous countries, while Nokia, Airspan, Samsung, Mavenir, Comba and other vendors provide competing indoor architectures.
The competitive emphasis is increasingly shifting toward installation simplicity, multi-operator capability, energy efficiency and centralized management rather than raw radio output alone.
mmWave Small Cells: Fastest-Growing Frequency Segment
Sub-6 GHz remains dominant because mid-band spectrum provides a strong balance of capacity and propagation for both indoor and outdoor systems. mmWave, however, has the strongest growth profile because its short range and very high available bandwidth make localized small-cell deployment a natural network architecture.
The segment is projected to reach approximately USD 5.1 billion by 2031. The largest opportunities are concentrated in high-density venues, FWA hotspots, transport environments, industrial sites and locations where very high capacity is required across a limited area.
mmWave does not replace Sub-6 GHz small cells. The technologies increasingly operate as complementary layers, with lower frequencies providing broader coverage and mmWave adding localized capacity.
Private & Enterprise Networks: Fastest-Growing Customer Segment
Private and enterprise deployments expand faster than the overall market as 5G moves beyond public mobile broadband. The segment grows from a comparatively small installed base but becomes an increasingly important source of incremental small-cell demand.
Revenue is projected to approach USD 3.7 billion by 2031. Industrial automation, logistics, healthcare, mining, utilities and campus environments provide the strongest commercial opportunities because cellular mobility, device identity and predictable quality of service offer clear operational benefits.
Small-cell suppliers increasingly design enterprise products around easier installation and centralized management rather than assuming that customers possess telecom-network engineering teams.
Open & Virtualized Small Cells: Fastest-Growing Architecture
Open and virtualized small-cell architectures are projected to reach approximately USD 7.2 billion by 2031. Their growth is supported by private 5G, neutral host and operator initiatives seeking greater flexibility in how radio and baseband functionality are deployed.
Integrated systems continue to represent a substantial market because they simplify installation and lifecycle management. The two architectures therefore serve different operational priorities rather than one completely replacing the other.
The strongest solutions increasingly support both models, allowing an operator to deploy an all-in-one radio in one environment and a split or virtualized architecture elsewhere while retaining a common software platform.
Regional Analysis
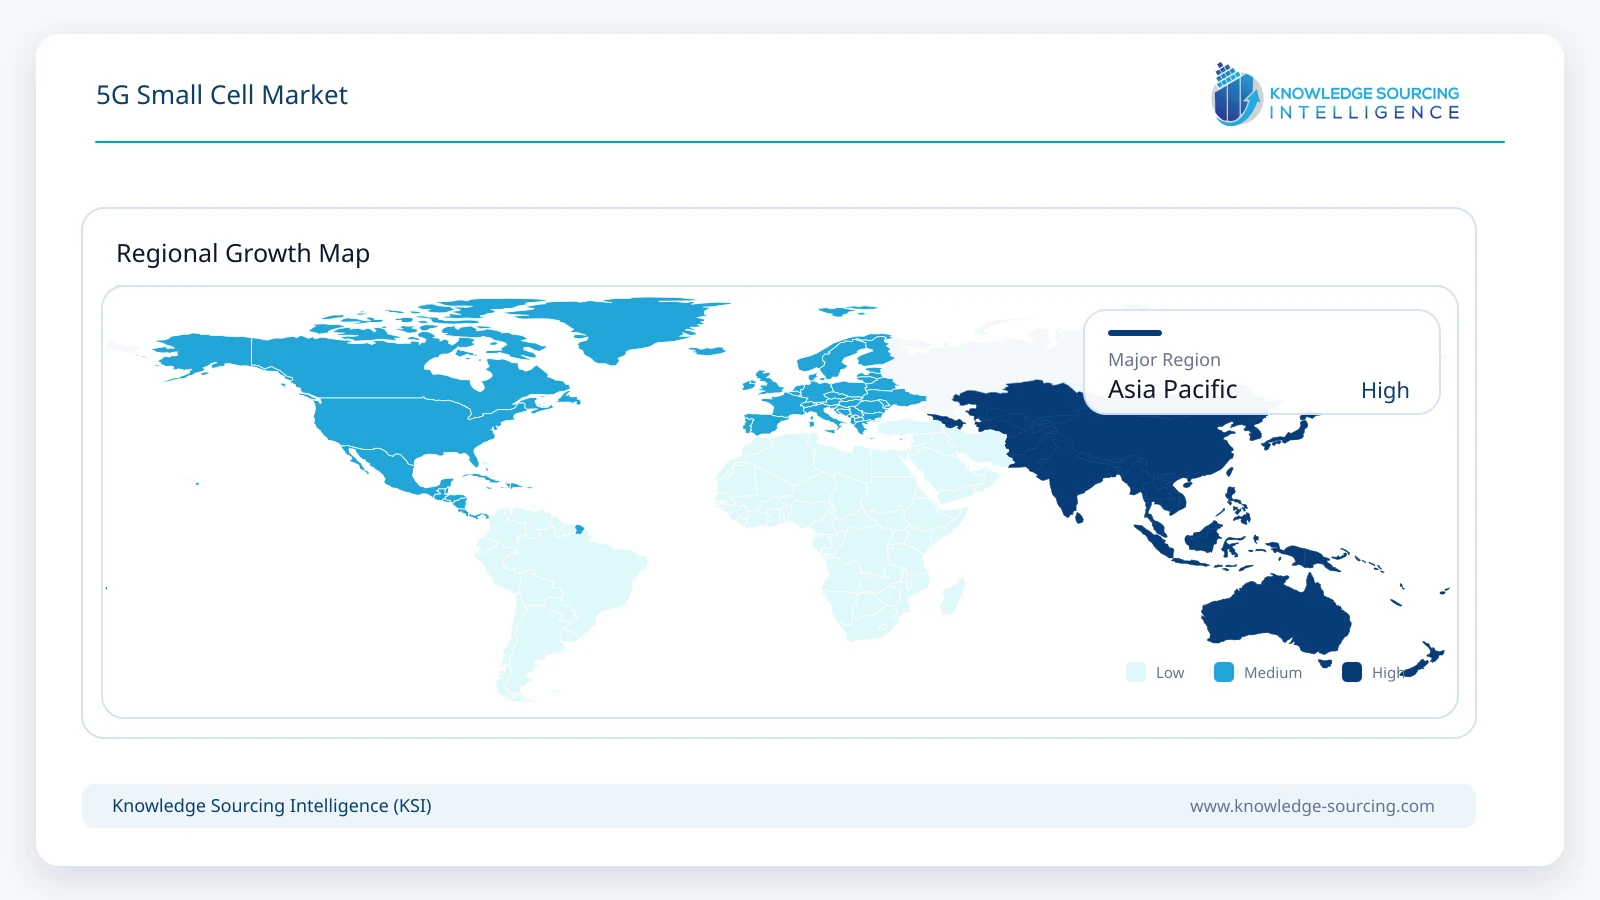
Asia Pacific remains the largest regional market and is projected to reach approximately USD 6.6 billion by 2031. Large 5G subscriber bases, dense cities, continued network expansion and manufacturing-sector private-network adoption support demand across China, India, Japan, South Korea and Southeast Asia.
China has one of the world’s largest 5G infrastructure footprints, while India’s continuing radio-network expansion creates opportunities for targeted capacity additions as national coverage improves. Japan and South Korea are comparatively mature 5G markets where enterprise, indoor and high-density network requirements become increasingly important.
North America remains a substantial market because of private 5G, CBRS-based enterprise deployments, sports and venue connectivity and operator network densification. Europe has a strong neutral-host and indoor connectivity opportunity, as demonstrated by the Freshwave deployment in the United Kingdom.
Middle East and Africa grow faster from a smaller base. Saudi Arabia’s May 2026 O-RAN neutral-host deployment demonstrates increasing interest in multi-operator indoor 5G across major commercial developments.
Technology Outlook
Multi-Operator Neutral-Host Small Cells
Neutral-host architecture is moving from proprietary indoor solutions toward more standardized and software-defined systems capable of serving several operators.
Shared radio infrastructure can improve building economics and reduce duplicated equipment while maintaining separate service relationships for each carrier.
The strongest commercial opportunity is in large office portfolios, airports, healthcare facilities, retail developments and other properties where reliable coverage across several national operators is essential.
Open and Virtualized Small-Cell RAN
Disaggregation allows radio equipment and processing software to evolve independently and creates greater deployment flexibility for private and shared networks.
Open RAN interfaces are particularly relevant where neutral hosts or enterprises want to avoid a single vertically integrated architecture. Virtualization also allows processing resources to be consolidated across several radio nodes rather than embedded independently at every location.
Integrated small cells remain important for simplicity, but software-defined platforms increasingly allow suppliers to support both integrated and distributed deployment models.
AI-Assisted Small-Cell Planning and Operations
Large small-cell networks create operational challenges because thousands of low-power nodes need to be configured, optimized and monitored.
Self-organizing network functions and AI-assisted planning can automate power settings, interference management and capacity optimization. These capabilities become increasingly important as indoor enterprise and outdoor densification networks scale beyond isolated individual sites.
The value of software consequently increases alongside radio hardware, particularly for neutral-host providers managing many buildings and enterprises operating multi-site private networks.
Recent Developments
May 2026: ACES deployed the Middle East’s first fully operational O-RAN neutral-host indoor 4G/5G small-cell site at King Abdullah Financial District in Riyadh in collaboration with Mavenir, Saudi Arabia’s Ministry of Communications and Information Technology and participating mobile operators. The deployment uses Split 7.2 architecture and supports multi-operator services through shared indoor infrastructure.
April 2026: Ericsson and Freshwave launched 5G on Omni in the United Kingdom, using Ericsson’s Radio Dot System to deliver indoor 4G and 5G connectivity from all UK mobile operators through a shared neutral-host small-cell architecture. The service was already live at Workspace’s Record Hall in London, with additional deployments underway.
February 2026: Airspan launched AirUnity Small Cells, a software-defined portfolio supporting LTE, 5G NSA and 5G SA across TDD and FDD spectrum. The platform supports both integrated all-in-one and Split 2 architectures for indoor, outdoor, public-network and enterprise deployments.
Competitive Landscape
Ericsson maintains a strong position through the Radio Dot System, indoor radio units and outdoor street-level small cells. The company’s strategy increasingly emphasizes multi-operator neutral-host deployments and integration between indoor and macro networks. Its Radio Dot platform has been deployed by more than 120 operators across over 70 countries, providing a large installed base for continued 5G upgrades.
Nokia competes through its indoor and outdoor small-cell portfolio and positions the technology for public networks, enterprise connectivity and private 5G. Its products address both coverage and capacity in locations where macro infrastructure cannot economically deliver the required indoor performance.
Airspan has one of the broadest independent small-cell portfolios across public, private and neutral-host deployments. Its AirUnity portfolio introduced in 2026 supports both integrated and split architectures, while its in-building portfolio includes SpiderCloud small-cell technology alongside digital DAS products. Airspan states that it has shipped more than one million radios globally.
Samsung combines compact radio systems with virtualized RAN and private-network capabilities, while Mavenir competes through Open RAN and cloud-native architectures suited to enterprise and neutral-host deployments. Mavenir technology is used in the ACES Saudi Arabian O-RAN indoor network.
Comba Telecom addresses enterprise indoor connectivity through 5G picocells alongside its wider in-building wireless portfolio. Baicells and BLiNQ focus strongly on private and enterprise small cells, while Sercomm supplies compact cellular equipment for operator and enterprise deployments.
JMA Wireless combines software-defined RAN with indoor and outdoor radio products and has a strong focus on U.S.-manufactured private and government 5G infrastructure. NEC and Fujitsu remain relevant through Open RAN, enterprise and operator radio portfolios, while Parallel Wireless targets open and virtualized networks. Huawei and ZTE maintain substantial small-cell portfolios across public-network and enterprise deployments in markets where their equipment is commercially available.
Competition increasingly centers on deployment simplicity, multi-operator support, software flexibility, spectrum coverage, energy consumption and the ability to operate indoor, private and neutral-host networks from a common management architecture.
Analyst View
The 5G small-cell market is moving from a long-discussed network-densification opportunity into a more clearly segmented commercial market. The strongest use cases are not based on operators installing small cells uniformly across entire cities. They occur where macro networks have a specific limitation that localized radio infrastructure can solve more economically.
Indoor coverage is the clearest example. Most mobile traffic is generated inside buildings, yet outdoor macro signals face physical penetration losses and cannot always provide the required capacity. Small cells therefore have a direct technical role in offices, airports, hospitals, factories and venues rather than serving only as supplementary outdoor capacity.
Neutral-host architecture materially improves this opportunity because one indoor network can support several mobile operators. The model brings property owners and specialist infrastructure providers into the value chain and reduces the requirement for each operator to justify an independent deployment.
Private 5G creates another high-growth channel. Enterprises increasingly purchase cellular infrastructure directly, particularly where mobility, reliability or operational technology requirements exceed what conventional enterprise Wi-Fi can provide. Small cells are the natural RAN architecture for most of these networks because deployment areas are geographically contained.
Outdoor densification remains relevant but is more dependent on local economics. Site access, power and backhaul can determine whether a compact radio is genuinely cheaper than expanding an existing macro location.
The strongest incremental opportunities through 2031 are therefore concentrated in indoor enterprise coverage, multi-operator neutral host, private 5G, mmWave hotspots and open or virtualized small-cell architectures, while conventional operator-owned integrated systems remain a large but slower-growing installed base.
5G Small Cell Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 6.6 billion |
| Total Market Size in 2031 | USD 16.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 19.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Deployment, Frequency Range, RAN Architecture, Customer, Geography |
| Companies |
|
Market Segmentation
By Deployment
Indoor
Outdoor
By Frequency Range
Sub-6 GHz
mmWave
By RAN Architecture
Integrated Small Cells
Open & Virtualized Small Cells
By Customer
Mobile Network Operators
Neutral Host & Shared Infrastructure Providers
Private Enterprise & Government Networks
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Indoor Mobile Coverage Gap
3.5. Neutral-Host Deployment Economics
3.6. Private 5G and Enterprise Demand
3.7. Outdoor Network Densification
3.8. Backhaul, Power and Site Economics
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. Multi-Operator Neutral-Host Small Cells
4.2. Open and Virtualized Small-Cell RAN
4.3. AI-Assisted Small-Cell Planning and Operations
5. 5G SMALL CELL MARKET BY DEPLOYMENT
5.1. Introduction
5.2. Indoor
5.3. Outdoor
6. 5G SMALL CELL MARKET BY FREQUENCY RANGE
6.1. Introduction
6.2. Sub-6 GHz
6.3. mmWave
7. 5G SMALL CELL MARKET BY RAN ARCHITECTURE
7.1. Introduction
7.2. Integrated Small Cells
7.3. Open & Virtualized Small Cells
8. 5G SMALL CELL MARKET BY CUSTOMER
8.1. Introduction
8.2. Mobile Network Operators
8.3. Neutral Host & Shared Infrastructure Providers
8.4. Private Enterprise & Government Networks
9. 5G SMALL CELL MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Australia
9.5.6. Indonesia
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Competitive Positioning
10.2. Indoor Small-Cell Capability
10.3. Outdoor Densification Capability
10.4. Neutral-Host & Multi-Operator Support
10.5. Private 5G Capability
10.6. Open & Virtualized RAN Architecture
10.7. Energy Efficiency & Deployment Economics
10.8. Strategic Developments
10.9. Competitive Dashboard
11. COMPANY PROFILES
11.1. Ericsson
11.2. Nokia Corporation
11.3. Airspan Networks
11.4. Samsung Electronics Co., Ltd.
11.5. Huawei Technologies Co., Ltd.
11.6. ZTE Corporation
11.7. Mavenir Systems, Inc.
11.8. NEC Corporation
11.9. Fujitsu Limited
11.10. Comba Telecom Systems Holdings Limited
11.11. Baicells Technologies Co., Ltd.
11.12. JMA Wireless
11.13. BLiNQ Networks
11.14. Sercomm Corporation
11.15. Parallel Wireless, Inc.
12. ANALYST VIEW
13. APPENDIX
13.1. Research Methodology
13.2. Market Estimation and Assumptions
13.3. Scope and Double-Counting Controls
13.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











