
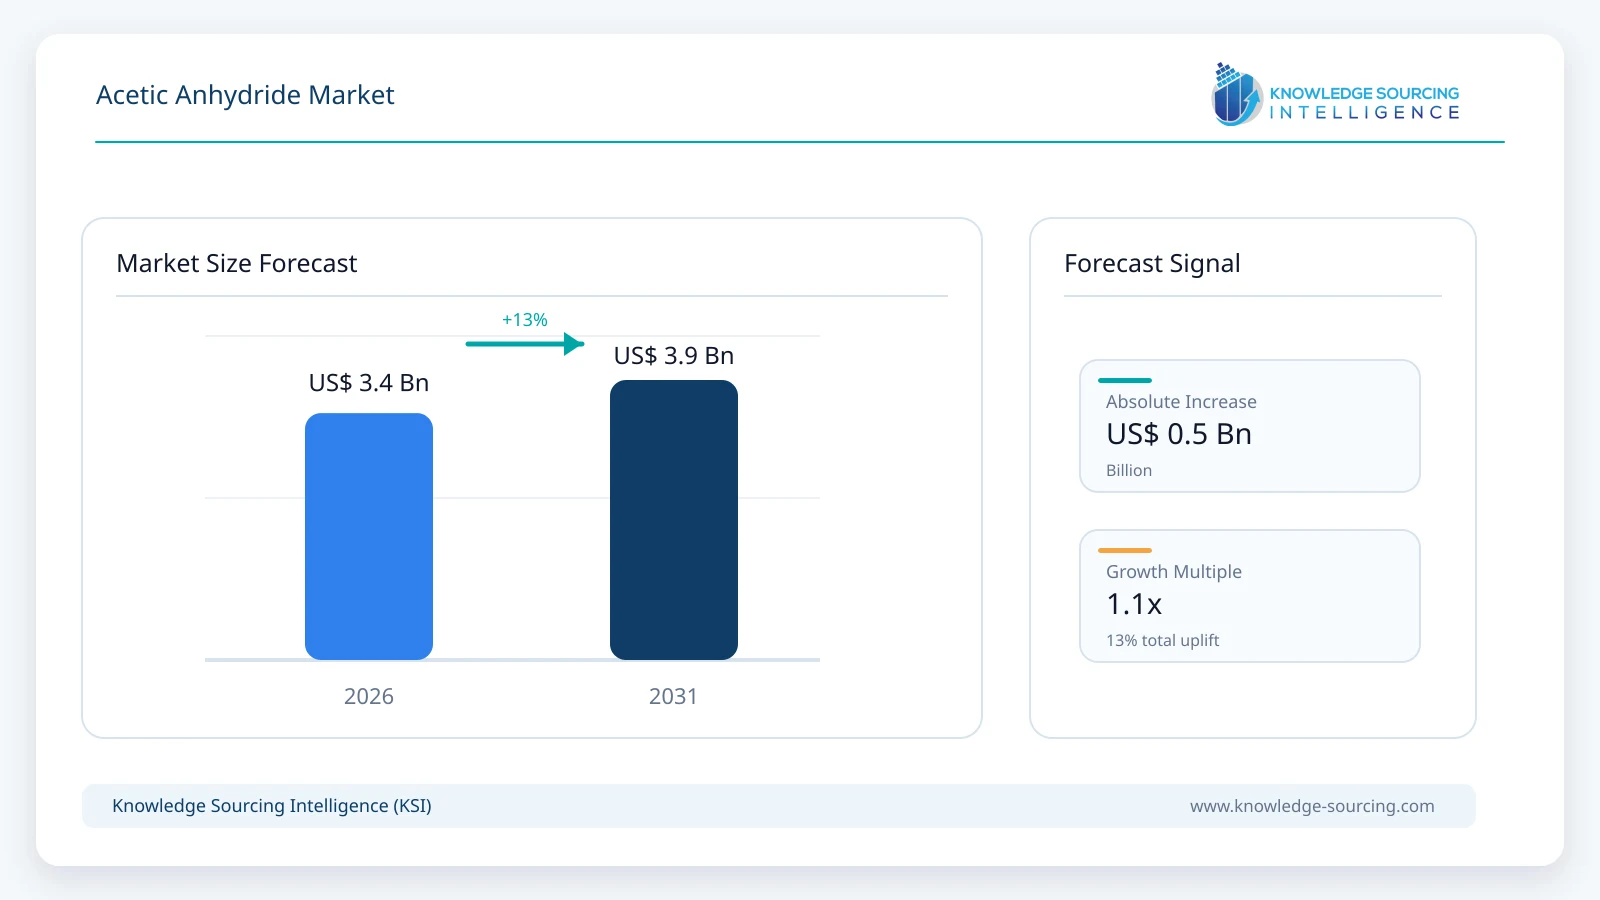
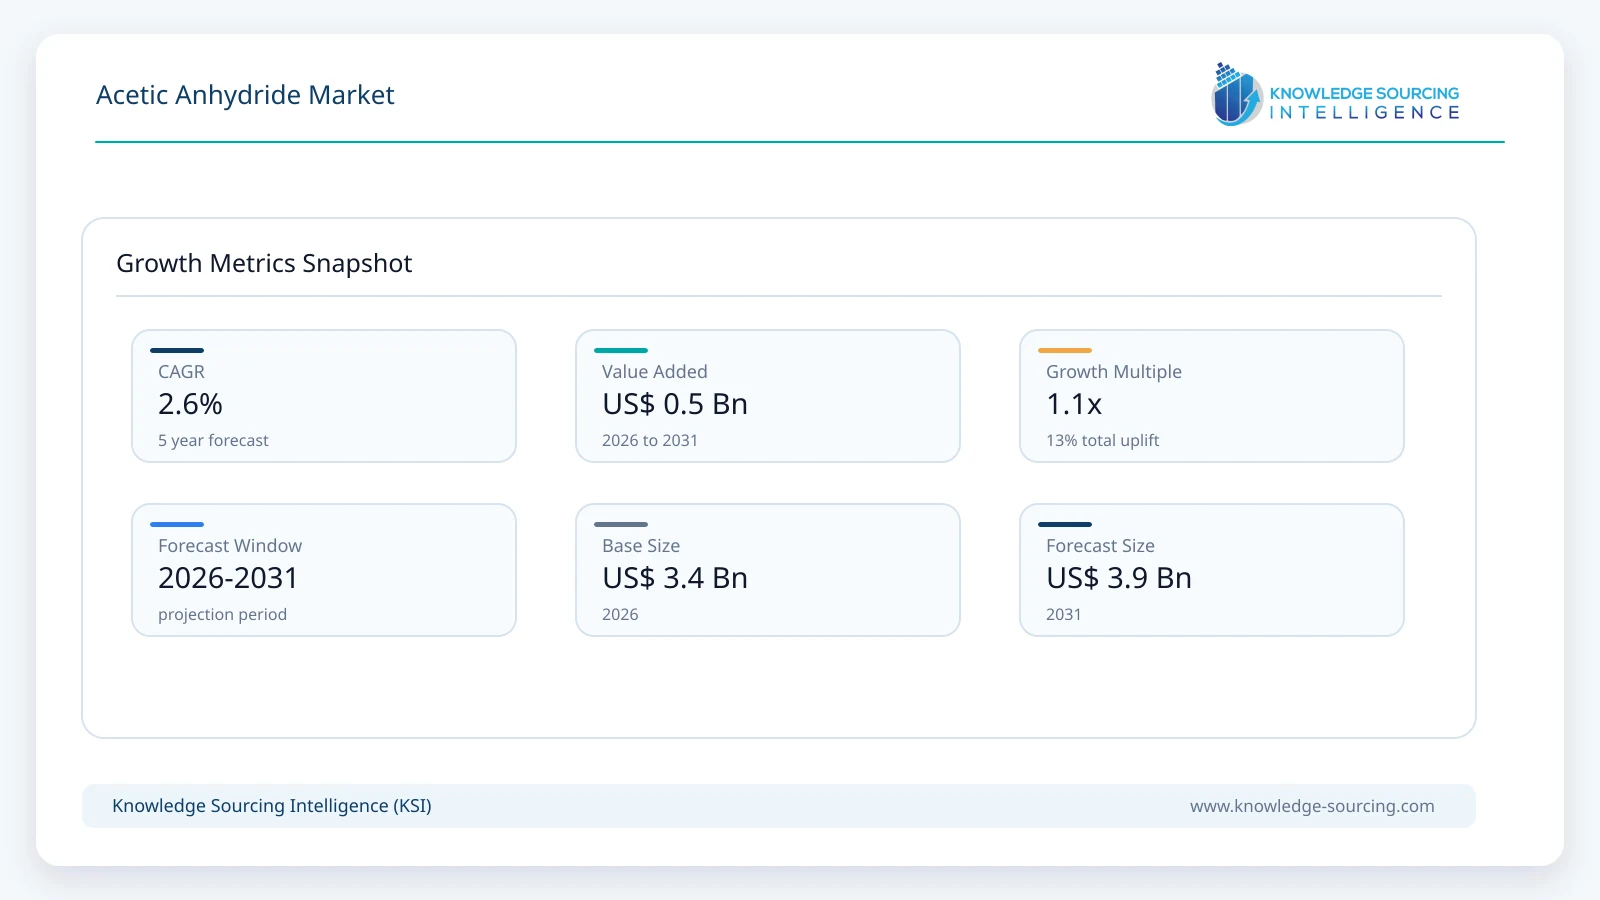
The acetic anhydride market is projected to expand at a CAGR of 2.6%, increasing from USD 3.43 billion in 2026 to USD 3.89 billion by 2031.
Highlights:
- 1Chemical manufacturers are increasing acetic anhydride production to support growing demand across industrial applications.
- 2Pharmaceutical companies are utilizing acetic anhydride for synthesizing active ingredients and essential chemical intermediates.
- 3Textile producers are expanding cellulose acetate applications, strengthening demand for acetic anhydride in fiber manufacturing.
- 4Specialty chemical companies are improving production efficiency while addressing safety and environmental compliance requirements.
Demand drivers of this market tie directly to the substance's role as a primary acetylating agent. Downstream manufacturers depend heavily on acetic anhydride for the production of cellulose acetate, modified starches, and essential active pharmaceutical ingredients like paracetamol and aspirin. This operational dependency forces major purchasers to establish long-term supply contracts with primary chemical producers to insulate themselves from spot-market volatility.
Regulatory factors introduce significant compliance requirements into the supply ecosystem, given that acetic anhydride serves as a critical precursor in narcotics processing. Chemical manufacturers must adhere to international diversion-control rules, including United Nations conventions and domestic regulations such as the United States Controlled Substances Act or European Union Precursor Regulations. These frameworks impose rigorous monitoring, licensing, and reporting burdens on transit operations, which limit spontaneous merchant trading and elevate the strategic importance of localized production nodes.
Establishing secure, regionalized acetyl supply chains remains vital for domestic industries looking to mitigate cross-border infrastructure disruptions and transport bottlenecks.
Market Dynamics
Drivers
Rising Cellulose Acetate Flake Demand: The expanding industrial requirement for high-durability coatings, specialty plastics, and tow filtration media continuously drives large-scale consumption of liquid acetic anhydride raw materials.
Evolving Technical Textile Processing: Downstream fabric manufacturers are increasing their utilization of advanced acetylation techniques to produce premium triacetate fibers, which permanently alter chemical intake patterns in industrial textile hubs.
Escalating Pharmaceutical Volume Requirements: Evolving global consumer demographics require a steady expansion in analgesic and anti-inflammatory drug production lines, which amplifies the ongoing need for consistent batch-chemical supplies.
Expanding Clean Ingredients In Laundry Applications: Industrial cleaner formulations are incorporating higher volumes of tetraacetylethylenediamine (TAED), which structurally increases the direct demand for upstream acetic anhydride precursors in bleaching applications.
Restraints and Opportunities
Severe Feedstock Cost Exposure: Upstream price fluctuations in glacial acetic acid and methanol directly squeeze manufacturer margins, which limit short-term supply flexibility during periods of geopolitical instability.
Strict Transport Infrastructure Constraints: Specialized corridor requirements for corrosive hazardous materials introduce structural logistics challenges, which frequently disrupt cross-border deliveries to remote downstream facilities.
Sustainable Biomass-Based Acetyl Sourcing: Evolving consumer environmental preferences create a structural opportunity for green acetic anhydride derived from bio-based ethanol, which attracts high-premium buyers in eco-conscious regions.
Advanced Multi-Product Chemical Complex Integration: Upstream producers are developing integrated manufacturing facilities that co-produce acetic acid, vinyl acetate monomer, and acetic anhydride, which improves cost efficiency and broadens market reach.
Supply Chain Analysis
The supply chain of the market operates as a highly integrated industrial sequence requiring synchronized raw material logistics and strict distribution controls. Upstream operations depend entirely on the continuous availability of primary petrochemical feedstocks, specifically methanol, carbon monoxide, and glacial acetic acid. Primary chemical synthesis proceeds through either the carbonylation of methyl acetate or the thermal cracking of acetic acid via the ketene pathway.
The production stage requires significant capital investment in specialized, corrosion-resistant chemical infrastructure. Once generated, the liquid chemical enters a highly consolidated distribution network managed under global hazardous material protocols.
The midstream segment involves strict regulatory monitoring, where chemical distributors must verify end-user certificates to prevent the diversion of regulated precursors. Storage operations demand dedicated stainless steel containment systems equipped with specialized moisture-exclusion setups to prevent premature hydrolysis into acetic acid.
Finally, downstream consumption is anchored by high-volume industrial processors, including cellulose acetate manufacturers, pharmaceutical formulation plants, and specialized coating producers. These end-users typically maintain direct pipeline connections or dedicated railcar routes with nearby chemical producers to ensure continuous operational access.
Government Regulations
Regulatory Body | Region | Policy | Operational Impact on Market Demand |
United Nations Office on Drugs and Crime (UNODC) | International | Convention Against Illicit Traffic in Narcotic Drugs (Table I Precursor) | Mandates universal import-export authorizations, which restrict informal cross-border merchant trading. |
Drug Enforcement Administration (DEA) | United States | Controlled Substances Act (List I Chemical) | Imposes strict recordkeeping and customer verification rules, which increase compliance overhead for local distributors. |
European Chemicals Agency (ECHA) | European Union | REACH Regulation (EC No 1907/2006) | Requires formal substance registration and safety documentation, which limits uncertified imports into Western Europe. |
Narcotics Control Bureau (NCB) | India | Controlled Substances Order | Controls domestic inventory distribution tracking, which forces buyers to secure long-term authorized licenses. |
Key Developments
October 2026: Eastman Announces Acetic Anhydride Price Increases. Eastman Chemical Company announced that, effective October 1, 2026, it would increase acetic anhydride prices by USD 0.05 per pound in North America and Latin America.
September 2026: INEOS Idles Hull Acetyls Plants. On September 22, 2026, INEOS announced the mothballing of its three Hull chemical plants due to high European energy costs, affecting regional acetyl-chain production and supply.
September 2026: Celanese Announces Global Acetyl-Chain Price Increases. On September 21, 2026, Celanese announced acetic anhydride price increases of USD 0.045 per pound in the United States and Canada, USD 100 per metric ton in Mexico and South America, and EUR 100 per metric ton in EMEA.
May 2026: Celanese Announces Acetic Anhydride Price Increases. On May 11, 2026, Celanese announced higher acetic anhydride prices, including USD 0.05 per pound in the Americas and Canada, USD 150 per metric ton in Mexico and South America, and EUR 150 per metric ton in EMEA.
March 2026: IOL Chemicals Expands Acetic Anhydride Capacity. On March 2, 2026, IOL Chemicals and Pharmaceuticals increased its annual acetic anhydride manufacturing capacity from 25,000 to 32,000 metric tons, investing approximately INR 5.71 crore.
Market Segmentation
By Form
The industrial consumption of acetic anhydride is concentrated primarily in specific physical formats that dictate handling infrastructure and process compatibility. Liquid form dominates large-scale manufacturing applications because automated industrial pumping systems require fluid media for continuous chemical feeding. Chemical plants utilize liquid delivery infrastructure to maintain steady-state reactions in downstream cellulose flake processing lines. This operational preference for bulk liquid transport requires specialized tank cars and dedicated climate-controlled storage arrays to prevent freezing.
Powder form, which often exists as a component in solid masterbatches or stabilized matrix formulations, addresses localized niche applications where fluid storage is impractical. Small-scale manufacturing operations utilize solid-state formulations to eliminate the need for corrosive liquid pumping systems. This choice restricts processing speed but provides safety benefits in small-scale laboratory environments.
As a result, chemical demand is shifting toward bulk liquid delivery as manufacturers phase out manual batch processing in favor of automated continuous production lines.
By Application
The functional role of acetic anhydride varies across distinct industrial applications that shape overall volume procurement strategies. Synthesizer applications dominate bulk volume procurement because chemical synthesis loops require high-purity inputs to generate downstream acetylated compounds. Pharmaceutical compounding lines depend directly on these inputs to maintain accurate stoichiometric balances during mass-volume medicine manufacturing.
Coating materials represent a rapidly evolving segment as eco-friendly formulations require modified wood and synthetic resins to enhance weather resistance. Surface treatment plants are increasing their consumption of acetylated intermediates to satisfy stricter regional durability mandates.
Dyes and inks processing requires high-purity acetyl derivatives to stabilize complex organic pigments against UV degradation. Textile dye factories utilize these specialized chemicals to improve coloration binding efficiency on synthetic fibers.
Plasticizers manufacturing requires steady volumes of acetic anhydride to modify polymer flexibility parameters for heavy industrial cables. Processing facilities depend on these regular chemical shipments to prevent production halts in plastic extrusion lines.
Other applications include the production of localized agricultural chemical intermediates and specialized flavors, which follow separate demand cycles.
By End-User
The purchasing landscape for acetic anhydride is shaped by distinct end-user industries that possess unique operational constraints and volume requirements. Pharmaceuticals represent a non-cyclical demand anchor because medicine manufacturing facilities require constant raw material volumes to satisfy global therapeutic demands. Healthcare manufacturing complexes maintain rigid quality specifications, which isolates this segment from low-grade merchant trading.
Textiles display high volume sensitivity because apparel production centers scale their chemical procurement directly alongside seasonal consumer retail trends. Weaver networks are shifting toward triacetate synthetic fabric varieties, which alters regional chemical allocation strategies.
Laundry and cleaning applications utilize steady volumes of acetyl derivatives to formulate low-temperature bleach activators for consumer detergents. Soap manufacturers are expanding their use of these compounds to comply with energy-efficiency mandates that prioritize cold-water washing cycles.
Building and construction firms consume acetic anhydride indirectly through architectural resins, wood preservation treatments, and modern structural adhesives. Construction projects require enhanced chemical resistance in building materials, which increases industrial usage of modified wood products.
Other end-users encompass specialized academic research labs and minor food manufacturing units, which exhibit highly fragmented buying behavior.
Regional Analysis
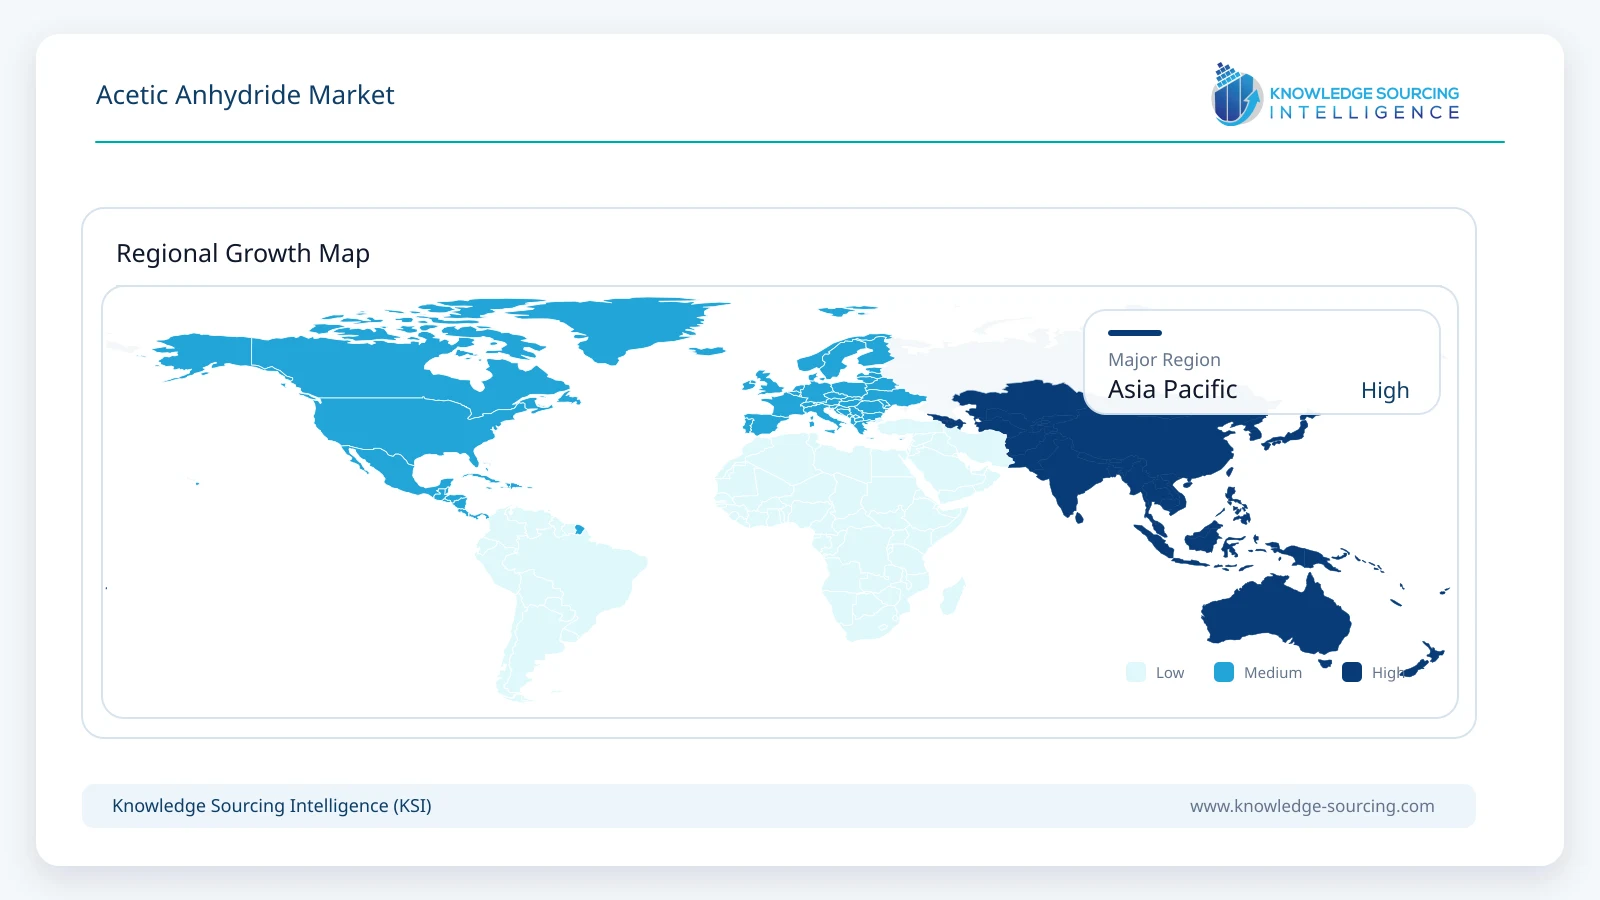
The regional consumption patterns of acetic anhydride are determined by the location of major downstream manufacturing clusters and available petrochemical raw material networks. North America represents a structurally advanced market anchored by extensive chemical manufacturing facilities located throughout the Gulf Coast region of the USA. American processing networks maintain high consumption volumes due to the presence of large-scale pharmaceutical synthesis facilities and automated cellulose acetate production hubs. Canadian industrial centers depend on regular cross-border rail shipments of liquid acetyl products to sustain their domestic specialty plastic manufacturing lines. Mexican manufacturing centers are expanding their localized automotive coatings production, which alters regional merchant distribution flows.
Europe maintains a highly regulated consumption profile dominated by strict environmental mandates and comprehensive chemical precursor diversion tracking frameworks. German chemical hubs utilize integrated production setups to feed downstream polymer processing plants directly via pipeline networks. French pharmaceutical manufacturing plants require high-purity liquid inputs to maintain continuous production of basic analgesic medications. The United Kingdom chemical sector depends heavily on specialized acetyl processing operations located near major deepwater shipping terminals. Spanish and Italian manufacturing plants are increasing their utilization of advanced intermediates to supply local architectural coatings and textile processing facilities.
The Asia Pacific region stands as the largest volume consumer due to the concentration of global textile hubs, pharmaceutical chemical suppliers, and plasticizers production facilities. China operates massive chemical manufacturing clusters that consume high volumes of feedstock to supply downstream export industries. Indian manufacturing plants are experiencing significant growth in chemical demand as domestic pharmaceutical companies expand active ingredient synthesis lines. Japanese processing complexes focus primarily on high-value, ultra-pure electronics-grade acetyl derivatives. South Korean, Indonesian, and Thai manufacturing hubs are scaling up their production infrastructure, which shifts global merchant shipping routes toward regional container terminals.
Competitive Landscape
Celanese Corporation
Jubilant Ingrevia Limited
Sigma Aldrich (Merck KGaA)
Eastman Chemical Company
Daicel Corporation
INEOS Group Limited
BASF SE
China National Petroleum Corporation (CNPC)
IOL Chemicals and Pharmaceuticals Limited (IOLCP)
Atom Scientific Ltd
Company Profiles
Celanese Corporation
Celanese Corporation operates as a strategically distinct acetyl chain leader by utilizing a deeply integrated global production asset network. The company maintains highly optimized manufacturing facilities in both North America and Asia, which minimizes localized raw material supply disruptions. This extensive network enables the company to adjust merchant volumes dynamically across international distribution channels.
Jubilant Ingrevia Limited
Jubilant Ingrevia Limited positions itself as a low-cost merchant supplier by operating integrated manufacturing complexes within the Indian domestic market. The company commands a dominant share of regional merchant sales by linking upstream acetyl production directly with downstream specialty chemical outputs. This localized integration secures consistent product purity for global pharmaceutical buyers.
Eastman Chemical Company
Eastman Chemical Company focuses on premium specialty derivatives by aligning its large-scale acetyl production directly with downstream cellulose copolymer manufacturing. The company maintains high-capacity production nodes in North America, which provides significant structural advantages in servicing the regional coatings market. This focused layout insulates the company from generic merchant spot-price volatility.
Analyst View
The global acetic anhydride market is entering a phase of structural consolidation as supply chains adapt to tightening chemical precursor regulations. Upstream integration and secure feedstock contracts are becoming essential requirements for maintaining profit margins amidst volatile energy and petrochemical input costs.
Acetic Anhydride Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.43 billion |
| Total Market Size in 2031 | USD 3.89 billion |
| Forecast Unit | Billion |
| Growth Rate | 2.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Form, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Form
Powder
Liquid
By Application
Synthesizer
Coating Material
Dyes and Inks
Plasticizers
Others
By End-User
Agriculture
Textiles
Laundry and Cleaning
Pharmaceuticals
Building and Construction
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ACETIC ANHYDRIDE MARKET BY FORM
5.1. Introduction
5.2. Powder
5.3. Liquid
6. ACETIC ANHYDRIDE MARKET BY APPLICATION
6.1. Introduction
6.2. Synthesizer
6.3. Coating Material
6.4. Dyes and Inks
6.5. Plasticizers
6.6. Others
7. ACETIC ANHYDRIDE MARKET BY END-USER
7.1. Introduction
7.2. Agriculture
7.3. Textiles
7.4. Laundry and Cleaning
7.5. Pharmaceuticals
7.6. Building and Construction
7.7. Others
8. ACETIC ANHYDRIDE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Celanese Corporation
10.2. Jubilant Ingrevia Limited
10.3. Sigma-Aldrich (Merck KGaA)
10.4. Eastman Chemical Company
10.5. Daicel Corporation
10.6. INEOS Group Limited
10.7. BASF SE
10.8. China National Petroleum Corporation (CNPC)
10.9. IOL Chemicals and Pharmaceuticals Limited (IOLCP)
10.10. Atom Scientific Ltd
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth of the Acetic Anhydride Market?
Market grows at 2.6% CAGR, reaching USD 3.89 billion by 2031.
What are the primary demand drivers for acetic anhydride?
Cellulose acetate, modified starches, and pharmaceutical APIs drive demand.
What key dynamics are boosting acetic anhydride consumption?
Cellulose acetate, advanced textiles, pharma, and TAED laundry applications drive demand.
What are the main restraints impacting the Acetic Anhydride Market?
Feedstock cost fluctuations and strict transport infrastructure are key restraints.
What emerging opportunities exist in this market?
Sustainable biomass-based acetyl sourcing presents a key market opportunity.
How do regulations affect the acetic Anhydride market?
Strict precursor regulations impose rigorous monitoring and limit merchant trading.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Acetic Anhydride Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/acetic-anhydride-market