
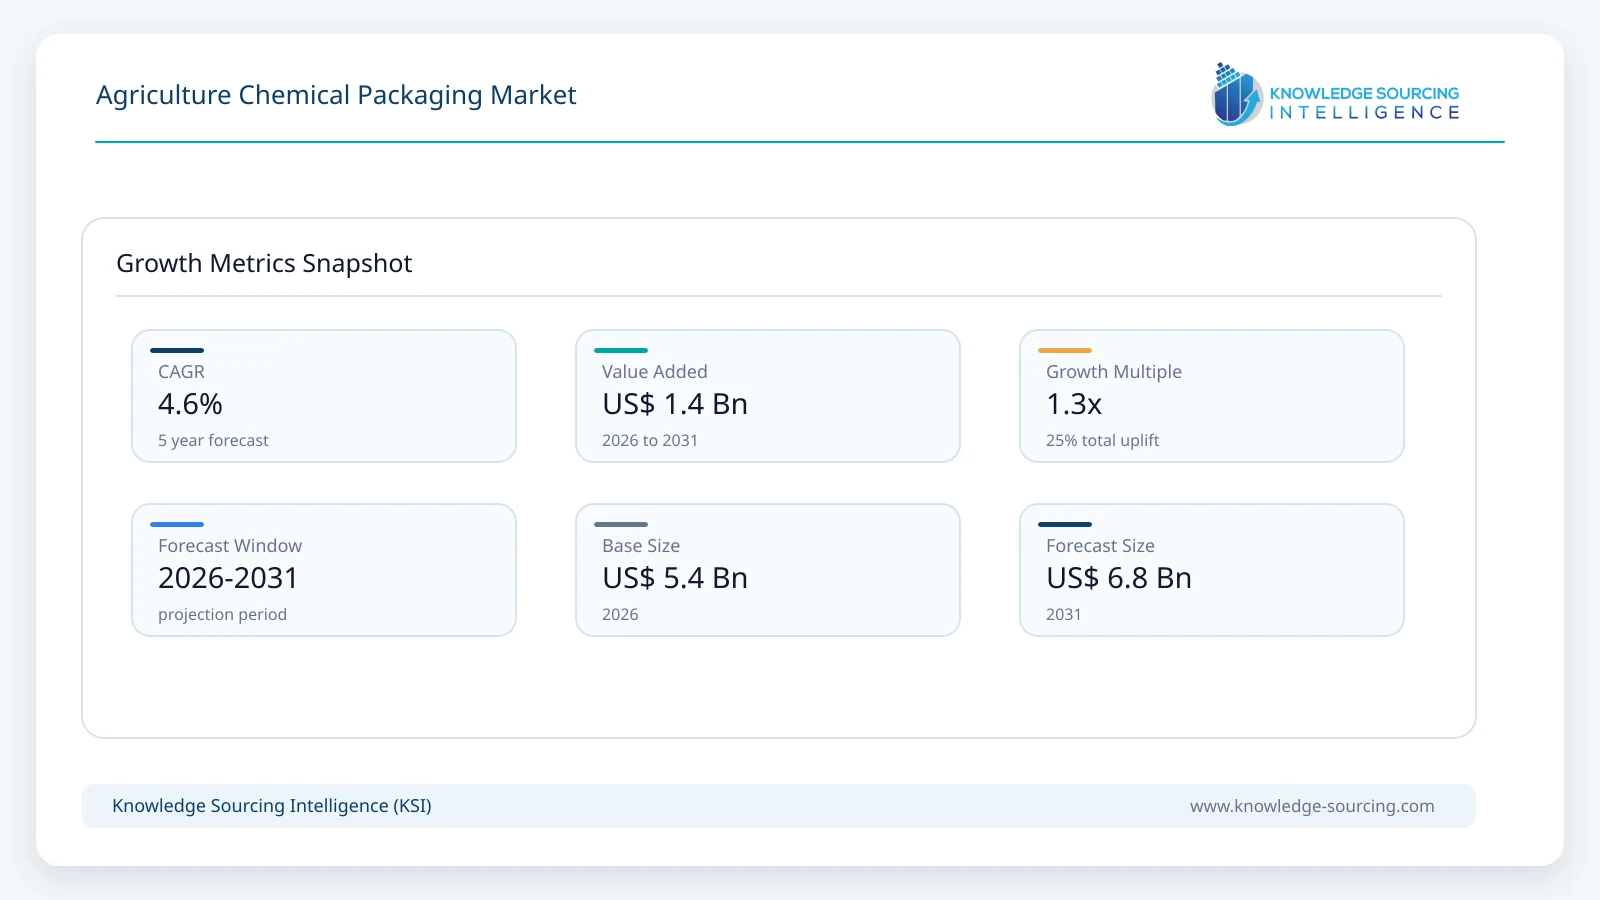
The Agriculture Chemical Packaging Market, growing at a 4.6% CAGR, is projected to achieve USD 6.81 billion in 2031 from USD 5.43 billion in 2026.
Highlights:
- 1Demand for safer handling of fertilizers and pesticides is reshaping packaging specifications.
- 2Plastic-based packaging remains the preferred material due to chemical resistance and cost efficiency.
- 3Refillable containers and intermediate bulk containers are gaining traction in commercial agriculture.
- 4Regulatory pressure on recycling, labeling, and containment is influencing packaging design decisions.
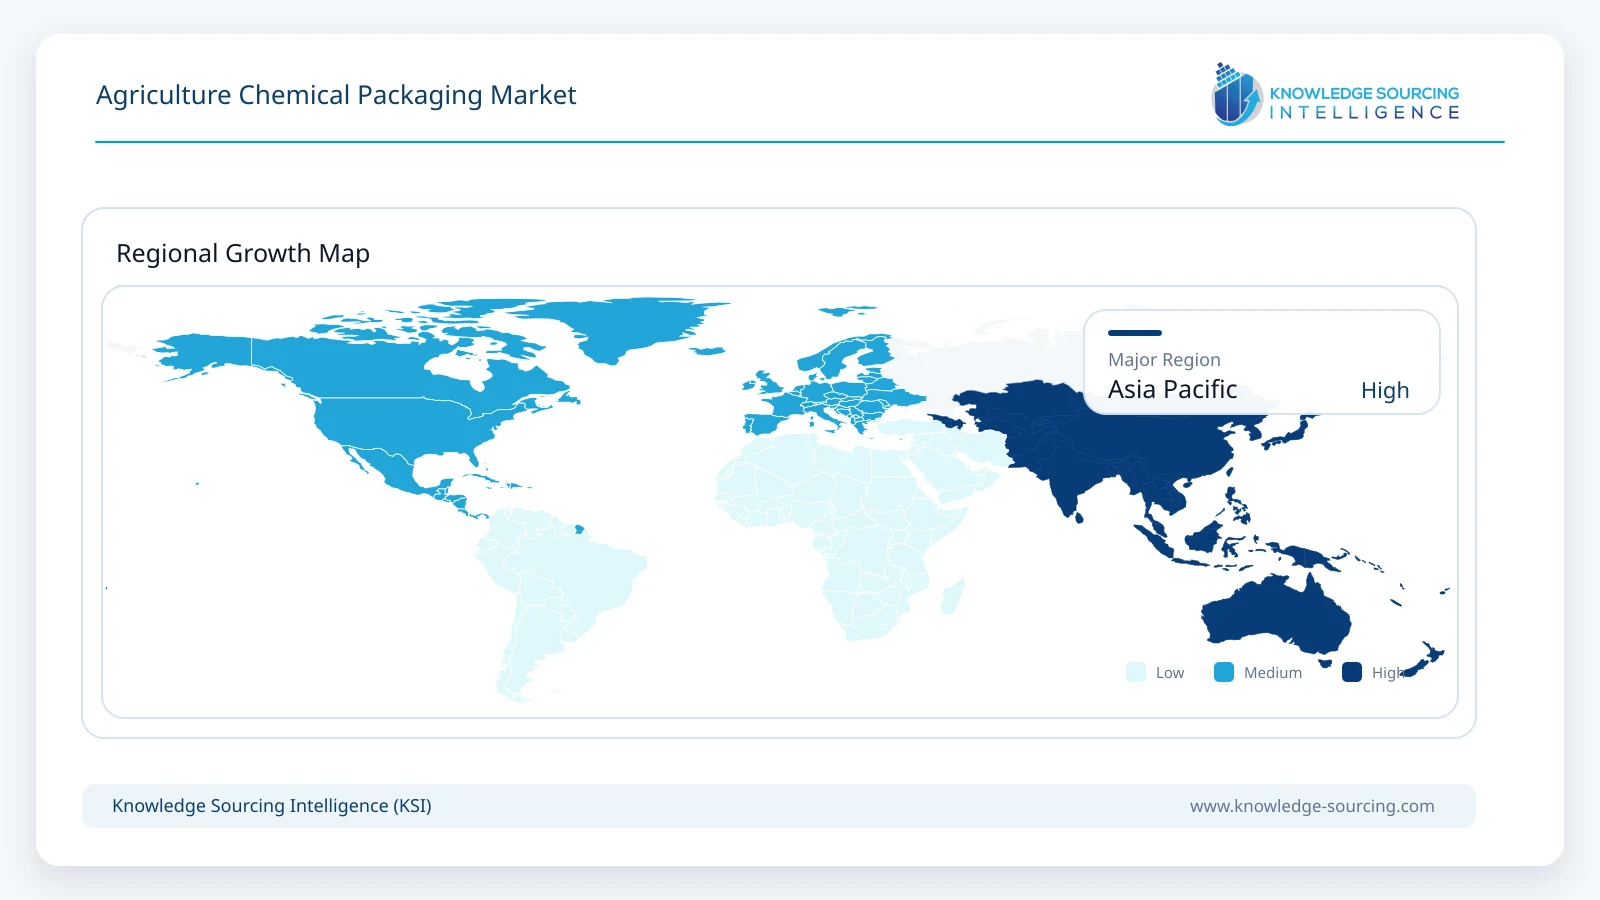
- 5Asia Pacific accounts for a substantial share of agricultural chemical consumption and packaging demand.
- 6Sustainability requirements are accelerating investment in recyclable and circular packaging formats.
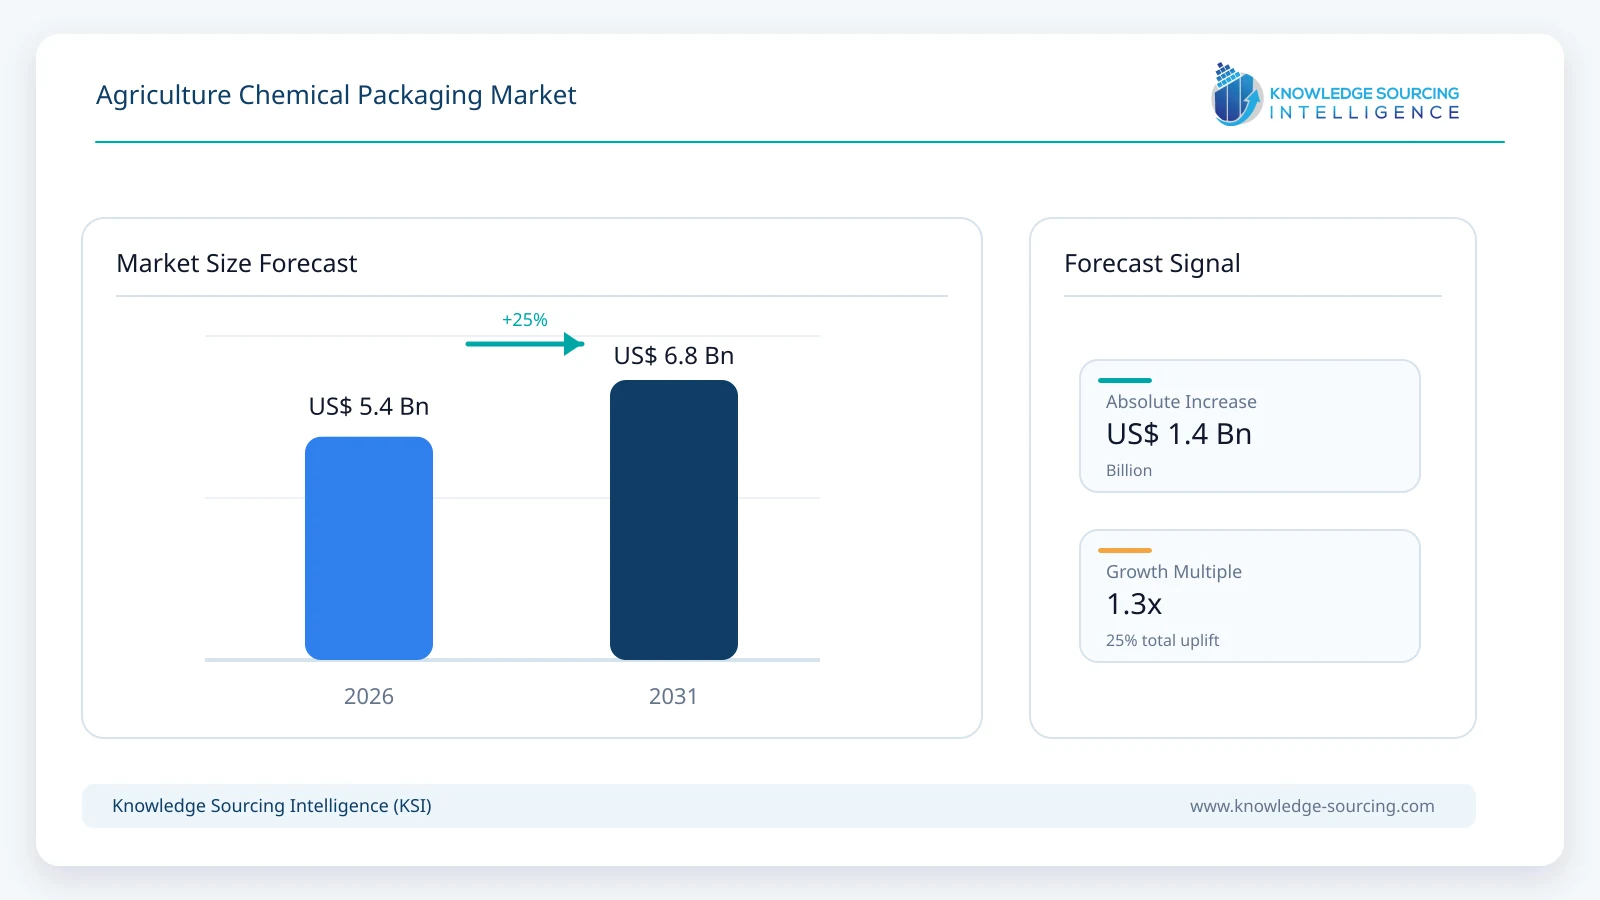
Agricultural chemical manufacturers operate in an environment where packaging performance directly affects product safety, transportation costs, regulatory compliance, and brand liability. Buyers increasingly evaluate packaging on chemical compatibility, durability, handling efficiency, recyclability, and compliance with hazardous-material regulations. This has increased demand for high-density polyethylene (HDPE) containers, multi-layer plastic packaging, industrial drums, and intermediate bulk containers (IBCs) capable of handling concentrated agrochemical formulations.
Value creation within the market is distributed across resin suppliers, packaging converters, industrial container manufacturers, closure-system suppliers, distributors, and agricultural chemical producers. Packaging suppliers that can provide certified, chemically resistant, and increasingly recyclable solutions are strengthening their position within procurement cycles. Regulatory requirements surrounding pesticide containment, labeling, recycling, and transportation are also raising technical barriers to entry for smaller packaging suppliers.
Demand patterns differ by product category. Fertilizers generate large-volume requirements for bags, pouches, and bulk packaging systems, while pesticides and crop-protection chemicals often require higher-specification containers because of toxicity, chemical stability requirements, and regulatory obligations. As agricultural chemical formulations become more concentrated, buyers are placing greater emphasis on leak prevention, tamper evidence, dispensing accuracy, and container reusability.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Global population | 8+ billion people (2025) | Sustains long-term demand for agricultural productivity and crop inputs. |
Global fertilizer demand | Continued growth in nutrient consumption across major agricultural economies | Supports recurring demand for fertilizer packaging formats. |
Hazardous goods regulations | Mandatory compliance across most developed agricultural markets | Raises packaging performance and certification requirements. |
Expansion of specialty agrochemicals | Growing adoption in high-value crop production | Increases demand for high-barrier and chemically resistant packaging. |
Circular economy regulations | Growing implementation across Europe and other regions | Encourages recyclable and reduced-plastic packaging designs. |
Agricultural trade flows | Large-scale international movement of crop inputs | Increases demand for durable transport packaging and bulk containers. |
Key Indicator: Growth in global agricultural input consumption remains closely tied to crop-yield improvement strategies and food security objectives.
Commercial Meaning: Packaging demand benefits from recurring replenishment cycles rather than one-time equipment purchases.
Market Drivers
Expansion of crop-protection chemical distribution networks.
Global food production systems continue to depend on pesticides, herbicides, fungicides, and specialty crop-protection products to improve yields and reduce crop losses. Distribution of these products requires packaging capable of maintaining chemical stability while meeting transportation and safety requirements. Packaging suppliers benefit when agrochemical producers expand product portfolios, enter new geographic markets, or increase distribution coverage through dealer networks and agricultural cooperatives.
Stricter pesticide handling and containment requirements.
The U.S. Environmental Protection Agency requires specific standards for pesticide containers, repackaging systems, refillable containers, labeling, cleaning instructions, and containment structures. These requirements have increased the importance of certified packaging solutions that reduce leakage, contamination, and worker exposure risks. Similar regulatory frameworks in other jurisdictions are encouraging investment in higher-performance containers, closures, and dispensing systems.
Growth in bulk agricultural chemical transportation.
Commercial farming operations increasingly purchase crop inputs in larger volumes to improve procurement efficiency and reduce logistics costs. This trend supports demand for industrial drums and IBCs capable of transporting concentrated formulations. Refillable packaging systems also improve asset utilization and reduce per-unit transportation costs, making them attractive to distributors serving large-scale agricultural producers.
Increasing adoption of recyclable and circular packaging solutions.
European packaging regulations are pushing packaging manufacturers toward designs that support recyclability, reuse, and reduced material consumption. The Packaging and Packaging Waste Regulation (PPWR), which entered into force in 2025, establishes requirements affecting packaging composition, recoverability, and waste management. Agricultural chemical suppliers selling into regulated markets are increasingly incorporating sustainability criteria into packaging procurement decisions.
Investment by industrial packaging manufacturers in agrochemical end markets.
Packaging companies continue to identify agricultural chemicals as a strategically attractive industrial end market. Industry participants are investing in drums, IBC systems, closure technologies, and specialty containers designed for hazardous and sensitive chemical products. Recent corporate disclosures indicate continued interest in expanding exposure to agricultural chemical customers because demand tends to be supported by recurring seasonal input purchases.
Market Restraints and Challenges
Regulatory complexity across multiple jurisdictions.
Agricultural chemicals frequently cross national and regional borders before reaching end users. Packaging suppliers must comply with differing transportation, hazardous-material, recycling, labeling, and disposal requirements. Compliance costs increase when manufacturers must certify packaging for multiple regulatory regimes, particularly in North America and Europe.
Pressure to reduce plastic use without compromising performance.
Plastic remains the preferred packaging material because of its chemical resistance, low weight, and cost advantages. However, regulators and large buyers are increasing pressure to reduce virgin plastic consumption and improve recyclability. Packaging suppliers face the challenge of meeting sustainability objectives while preserving barrier properties, durability, and chemical compatibility.
Volatility in polymer and metal input costs.
HDPE, polypropylene, steel, and other packaging inputs remain exposed to fluctuations in energy prices, petrochemical feedstock costs, and industrial demand cycles. Packaging manufacturers often face delays in passing higher material costs through to customers, creating margin pressure during periods of rapid commodity-price movement.
Hazardous-product liability exposure.
Failures in agricultural chemical packaging can result in environmental contamination, product loss, regulatory penalties, and reputational damage. As a result, agricultural chemical producers impose stringent qualification and testing requirements on packaging suppliers. These qualification cycles can extend product development timelines and increase compliance costs.
Recycling infrastructure limitations.
Although regulators increasingly encourage circular packaging systems, collection and recycling infrastructure for contaminated agricultural chemical packaging remains inconsistent across many markets. Container recovery programs vary substantially by country, limiting the pace at which recyclable packaging designs can translate into closed-loop material systems.
Major Segment Analysis
Plastic Packaging
Plastic represents the most commercially important material segment within the agricultural chemical packaging market. High-density polyethylene and related polymer materials provide chemical resistance, impact strength, moisture protection, lightweight transportation characteristics, and design flexibility. These attributes make plastic suitable for bottles, containers, drums, caps, pouches, and IBC components used across fertilizer and pesticide applications.
Purchasing decisions within this segment are influenced by compatibility with chemical formulations, transportation efficiency, regulatory certification, and total cost of ownership. Agricultural chemical manufacturers prioritize packaging that minimizes leakage risks while maintaining product stability throughout storage and distribution. Plastic packaging also supports customized dispensing systems and tamper-evident closures that improve operational safety.
Despite its commercial advantages, the segment faces increasing scrutiny from regulators and sustainability-focused buyers. Packaging suppliers are responding through lightweighting initiatives, increased recycled-content incorporation where technically feasible, and development of reusable container systems. Competitive differentiation is increasingly shifting from simple container production toward lifecycle performance, compliance documentation, and circular-economy capabilities.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Large-scale pesticide and fertilizer distribution networks | Regulatory compliance costs |
Europe | Sustainability and packaging regulations | Circular-economy compliance requirements |
Asia Pacific | High agricultural input consumption and crop intensity | Diverse regulatory frameworks |
South America | Export-oriented agriculture and large farming operations | Logistics and infrastructure constraints |
Middle East and Africa | Expanding agricultural productivity initiatives | Limited recycling infrastructure |
North America
The United States remains a major market for agricultural chemical packaging because of its large crop-production sector and extensive distribution infrastructure. EPA requirements governing pesticide containers, labeling, containment systems, and recycling procedures influence packaging specifications across the value chain. Demand is particularly strong for certified containers, drums, and refillable systems used in commercial agriculture.
Europe
European demand is increasingly shaped by sustainability regulation. The PPWR introduces requirements covering packaging design, recyclability, recoverability, and waste management. Agricultural chemical suppliers operating in Europe are evaluating packaging formats that support compliance while maintaining chemical performance standards. This is creating opportunities for recyclable plastics, reusable industrial containers, and circular packaging systems.
Asia Pacific
China, India, Japan, Indonesia, and other regional agricultural economies account for a substantial share of global crop-input consumption. Rising agricultural productivity requirements and continued use of fertilizers and crop-protection products support demand for packaging across both retail and commercial distribution channels. Cost competitiveness remains important, although regulatory compliance standards are gradually becoming more stringent in several markets.
South America
Brazil and Argentina represent important agricultural exporters with extensive use of crop-protection chemicals and fertilizers. Large farm sizes support demand for industrial-scale packaging formats, including drums and IBCs. Distribution efficiency and transportation durability remain critical purchasing considerations because chemicals often travel long distances between production facilities and farming regions.
Middle East and Africa
Agricultural modernization programs, water-efficiency initiatives, and efforts to improve food security are supporting demand for agricultural inputs across selected markets. Packaging suppliers frequently compete on product durability, climatic resistance, and distribution capability due to challenging logistics environments.
Competitive Landscape
The market exhibits characteristics of a moderately fragmented industrial packaging sector in which scale, regulatory compliance, chemical compatibility expertise, and distribution reach influence competitive positioning. Packaging suppliers compete through product performance, manufacturing footprint, sustainability capabilities, and long-term relationships with agricultural chemical producers.
Mauser Packaging Solutions and Greif, Inc. maintain strong positions in industrial containers, drums, and IBC systems serving hazardous and specialty chemical applications. Their competitive advantage is linked to manufacturing scale, global distribution networks, and experience in regulated packaging markets.
Silgan Holdings, Inc. and United Caps compete through packaging component innovation, closure technologies, and product safety features that support regulatory compliance.
ProAmpac and NNZ Group participate in flexible packaging applications, where lightweight designs and material efficiency remain important procurement considerations.
Competition increasingly extends beyond container manufacturing. Buyers are evaluating suppliers based on recyclability documentation, sustainability reporting, regulatory expertise, supply-chain resilience, and the ability to support circular packaging initiatives.
Recent Developments
March 2026: Gravis Global acquired Procon Pacific, expanding its flexible intermediate bulk container and woven-bag packaging portfolio. The transaction strengthened bulk-packaging capabilities serving agricultural chemicals, fertilizers, and other industrial end markets.
March 2026: ProAmpac completed its acquisition of TC Transcontinental Packaging, adding extensive extrusion, printing, lamination, and converting capabilities. The deal enhances flexible-packaging supply for agriculture, chemicals, and other industrial markets.
June 2025: ProAmpac and ScottsMiracle-Gro introduced a spouted pouch for Ortho Home Defense Max. The flexible package reduces plastic usage by approximately 90% while maintaining chemical resistance and dispensing convenience.
February 2025: The European Union's Packaging and Packaging Waste Regulation entered into force. The regulation increases focus on recyclable and recoverable packaging materials across industrial end markets, including agricultural chemicals.
Regulatory and Policy Environment
Packaging regulation is becoming a more influential market variable. In North America, EPA rules establish requirements governing pesticide containers, repackaging activities, refillable systems, containment structures, and labeling. Compliance affects packaging design, testing procedures, and documentation requirements across the supply chain.
European policy is increasingly focused on circular-economy outcomes. The PPWR extends beyond waste management and addresses packaging design, material composition, recyclability, and reuse. Agricultural chemical packaging suppliers serving European markets will need to align product development and material selection with evolving compliance requirements.
Environmental stewardship programs and container-recovery initiatives are also influencing procurement decisions. Agricultural chemical producers increasingly assess end-of-life management, recycled-content potential, and packaging sustainability performance alongside traditional cost and functionality criteria.
Outlook and Strategic Implications
Market performance through 2031 will be influenced by three interconnected factors: agricultural input demand, packaging regulation, and sustainability requirements. Growth is expected to remain linked to global crop-production needs and continued use of fertilizers and crop-protection products. However, value creation is likely to shift toward packaging systems that combine regulatory compliance, operational safety, and circular-economy characteristics.
Several strategic implications emerge:
Packaging suppliers will continue investing in recyclable, reusable, and refillable packaging formats.
Regulatory expertise will become a stronger competitive differentiator in pesticide packaging markets.
Large agricultural chemical manufacturers are likely to consolidate supplier relationships around companies with proven compliance and sustainability capabilities.
Industrial drums and IBC systems should benefit from continued growth in bulk chemical transportation.
Plastic packaging will remain commercially important, although material innovation and recycled-content integration will become increasingly important procurement criteria.
The market remains fundamentally tied to global agricultural productivity requirements. Companies capable of balancing chemical performance, regulatory compliance, operational efficiency, and sustainability objectives are expected to capture a larger share of future packaging spending across the agricultural chemicals value chain.
Agriculture Chemical Packaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.43 billion |
| Total Market Size in 2031 | USD 6.81 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Material Type, Chemical, Geography |
| Companies |
|
Market Segmentation
By Product Type
By Material Type
By Chemical
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. AGRICULTURE CHEMICAL PACKAGING MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Bags and Pouches
5.3. Bottles and Containers
5.4. Drums and Intermediate Bulk (IBC’s)
5.5. Others
6. AGRICULTURE CHEMICAL PACKAGING MARKET BY MATERIAL TYPE
6.1. Introduction
6.2. Plastic
6.3. Metal
6.4. Others
7. AGRICULTURE CHEMICAL PACKAGING MARKET BY CHEMICAL
7.1. Introduction
7.2. Fertilizer
7.3. Pesticide
7.4. Others
8. AGRICULTURE CHEMICAL PACKAGING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. United Caps
10.2. Mauser Packaging Solutions
10.3. Greif, Inc
10.4. NNZ Group
10.5. ProAmpac
10.6. Silgan Holdings, Inc.
10.7. LC Packaging International BV
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











