
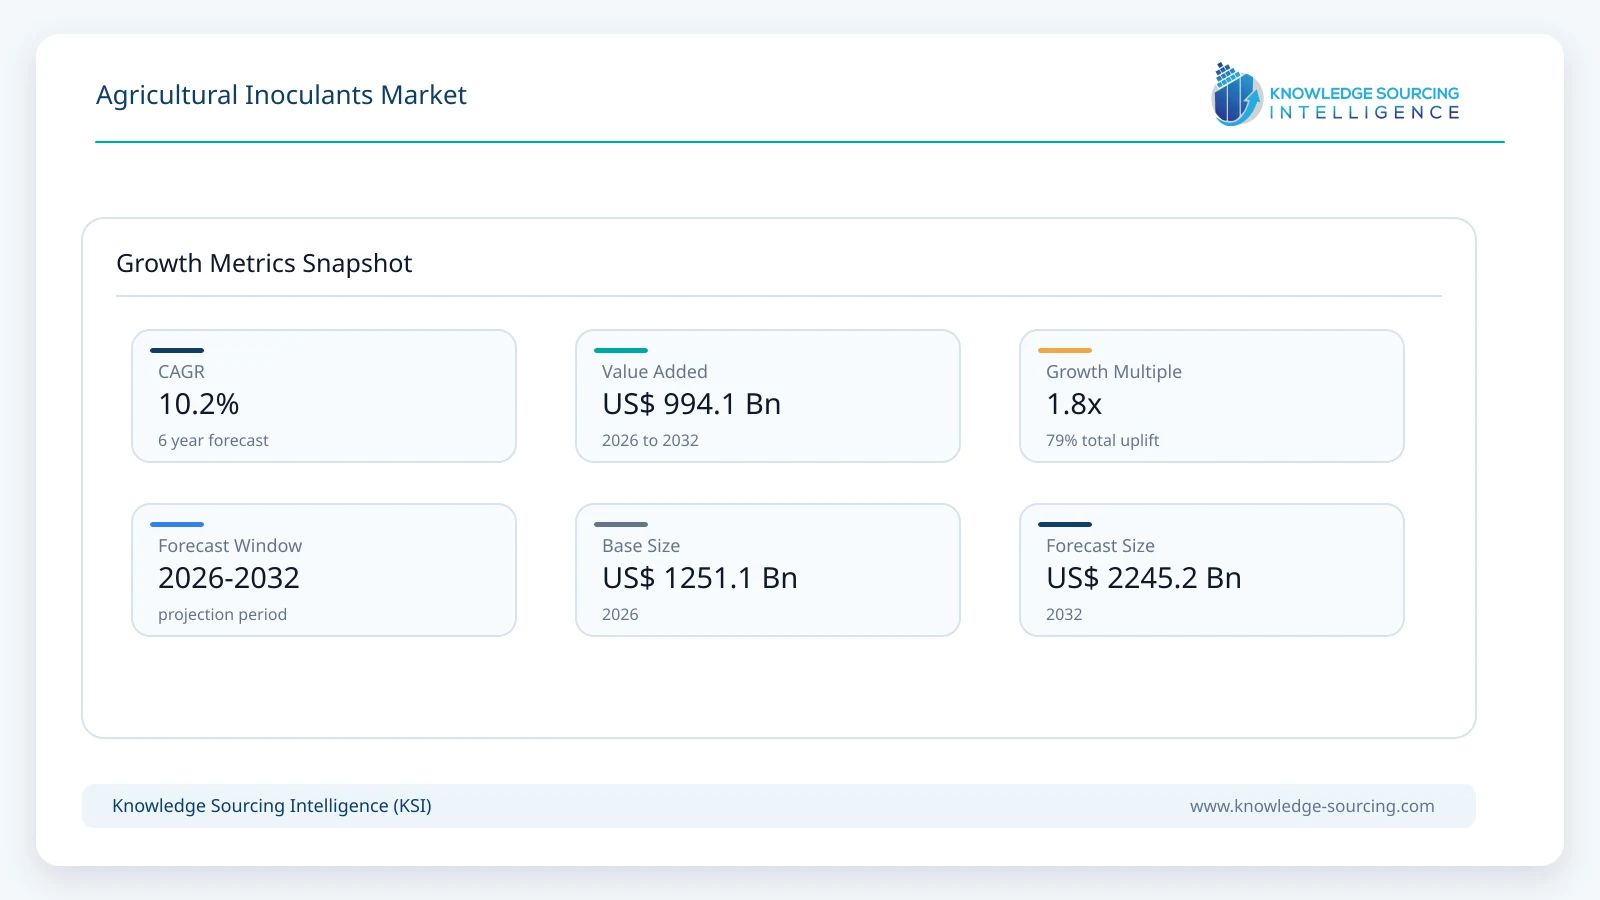
The global agricultural inoculants market is estimated at USD 1,251.1 million in 2026 and is projected to reach USD 2,245.2 million by 2032, representing a compound annual growth rate of 10.2% during the forecast period.
Highlights:
- 1Soybean applications represent a modeled 26.8% share of global agricultural inoculant revenue in 2026, reflecting extensive rhizobial use in Brazil and demand for repeat treatment in North American and South American cropping systems.
- 2Market growth is being supported by the expansion of microbial inoculants beyond legume nitrogen fixation into nutrient-solubilisation and root-development applications for cereals, oilseeds and higher-value crops.
- 3Inoculant efficacy depends on viable organism delivery, temperature exposure, storage conditions and seed-treatment compatibility; these constraints increasingly determine manufacturer differentiation and channel profitability.
- 4Brazil's 48.72 million hectares of soybean area in the 2025/26 season provide a significant recurring inoculation opportunity, while ANPII Bio reported approximately R$527 million of inoculant deliveries in its 2024 member survey.
- 5Competition is increasingly driven by formulation stability, microbial strain performance, retailer treatment-line integration and the documentation required for nutrient-use and plant-growth claims.
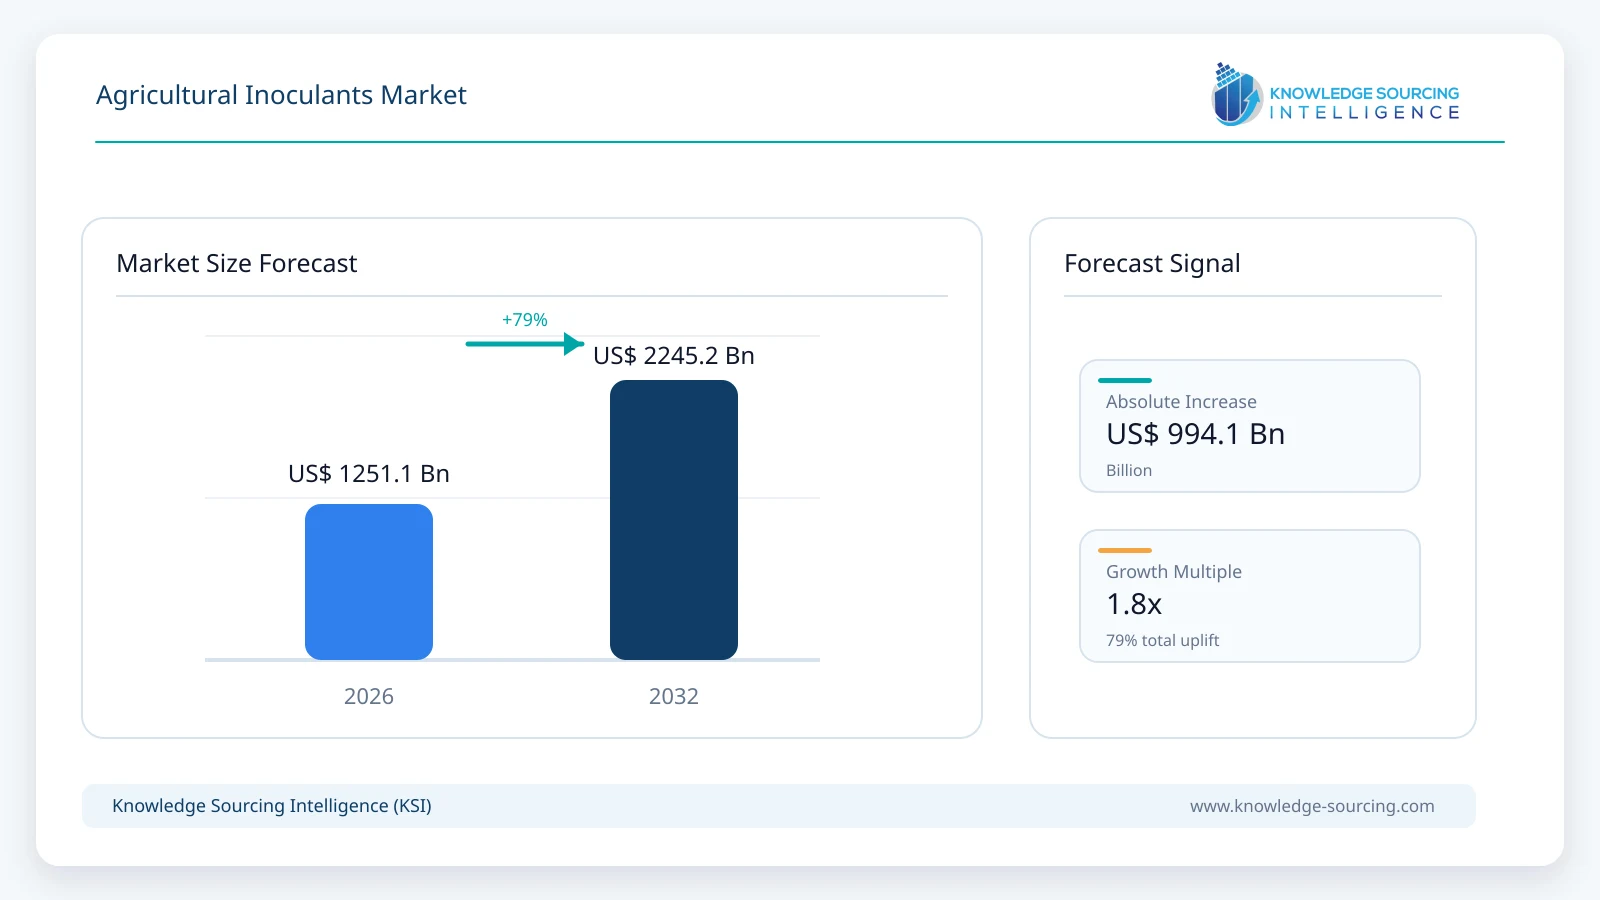
Demand comprises commercially purchased live-microbial preparations used to support nutrient fixation, nutrient mobilisation, root colonisation and other specified plant-growth functions. It is distinct from the larger markets for agricultural biologicals, conventional fertilizers and crop-protection chemicals. The forecast reflects treated crop area, use frequency and realized spending per treated hectare across soybean, other oilseed, pulse, cereal and other agricultural applications.
The commercial opportunity increasingly depends on the performance and economics of individual crop-management systems. A soybean farmer buying Bradyrhizobium to support biological nitrogen fixation faces a different purchasing decision from a maize grower trialling a phosphorus-solubilising organism or a horticultural producer applying mycorrhizal inoculants. Market growth therefore depends not merely on expanding planted acreage but also on improvements in survival during seed treatment, compatibility with crop-protection products, predictable field response and cost-effective distribution.
Agricultural Inoculants Market Trends
Commercial adoption is shifting from organism availability to reliable field delivery
The principal operational bottleneck in the inoculants industry is maintaining a viable microbial dose between manufacturing and root colonisation. A product may meet its declared colony-forming-unit concentration at packaging but deliver less biological activity following prolonged warehouse exposure, incompatible fungicide contact or delayed planting. For professional seed treaters, this translates into inventory holding limits, more demanding mixing protocols and narrower application windows. Suppliers that extend on-seed survival can reduce batch scheduling restrictions and allow inoculants to enter established commercial seed-treatment operations rather than relying exclusively on last-minute farm application.
Novonesis' Cell-Tech XC soybean inoculant is promoted with a 30-day on-seed survival period, illustrating the importance of formulation compatibility as a procurement specification. Lallemand's LALFIX PRO DOSE platform and Rizobacter's concentrated Rizoliq products likewise focus on viable microbial concentration and treatment flexibility. These features can reduce handling costs and improve distribution reach, but the margin benefit depends on whether higher-value formulations replace conventional products or are offered as add-ons to existing biological treatments.
Microbial products are moving beyond traditional nitrogen-fixing legumes
Growth in non-legume uses is closely tied to the difficulty of obtaining consistently positive agronomic responses under diverse soil conditions. Phosphorus-solubilising bacteria and mycorrhizal fungi operate through different mechanisms and do not have uniform performance across fields. Their commercial opportunity is therefore more dependent on soil tests, targeted agronomic positioning and credible multi-location trial evidence than on generalized claims that microbial products replace conventional fertilizer. The most viable supplier strategies involve crop-specific evidence packages and integration into existing nutrient-management practices rather than indiscriminate substitution.
This distinction also shapes pricing. Products that create measurable value in premium horticulture or specialized soil systems can sustain higher per-hectare spending than commodity rhizobial treatments. By contrast, broadacre cereals offer substantial addressable hectares but lower initial inoculant penetration and considerable variability in response. The result is a market in which revenue can expand through treatment intensity and product mix even when cultivated acreage changes only modestly.
Agricultural Inoculants Market Growth Drivers
Nitrogen-fixation economics underpin recurring demand in soybean production
Soybean cultivation provides the clearest established commercial case for microbial inoculation. Bradyrhizobium forms root nodules that fix atmospheric nitrogen, reducing dependence on an equivalent quantity of synthetic nitrogen fertilizer. The economic value is particularly meaningful in expanding soybean regions or fields with an insufficient population of effective bacteria. It is less straightforward in fields with an established rhizobial population, where expected incremental yields may be lower. As a result, suppliers increasingly compete on strain selection, microbial survival, ease of application and the evidence supporting incremental treatment.
The United States planted approximately 85.4 million acres of soybean in 2026 according to USDA NASS, while Brazil's soybean area reached 48.72 million hectares in 2025/26 according to Embrapa's CONAB-based reporting. These crop areas create sizable repeat sales opportunities, but only the inoculated share of hectares contributes to realized product revenue. Overestimating treatment penetration or allocating the entire price of a fungicide-and-inoculant seed package to inoculants can materially inflate market size.
Regulatory qualification influences access to premium European channels
Regulation (EU) 2019/1009 provides a harmonised route for qualifying microbial plant biostimulants and specifies microorganism categories under CMC 7. It does not confer automatic coverage on all beneficial agricultural microbes, nor does it erase differences between plant-growth claims and pesticidal claims. For innovators, the regulatory constraint affects strain selection, documentation, registration cost and launch geography. Companies able to build compliant evidence for a specific organism and target crop may gain earlier access to seed partners and established agricultural distribution systems.
Protealis' March 2026 announcement concerning its MagNfix soybean inoculant and the start of commercial deployment in Poland demonstrates how regulatory progress can translate into an identifiable product launch. The implication is commercial rather than merely administrative: suppliers seeking premium pricing must convert laboratory performance into repeatable field claims, meet the relevant product-classification requirements and establish a dependable channel before scaled revenue becomes feasible.
Agricultural Inoculants Market Restraints
Field response variability and difficult attribution constrain farm-level ROI
Microbial efficacy depends on temperature, moisture, soil chemistry, resident microbial communities and crop-management practices. This creates a different commercial risk profile from standardized chemical nutrient inputs. A product that improves root development at one trial site may provide limited incremental benefit under another soil condition, weakening the economics of universal treatment. Retailers and larger growers are consequently more likely to demand replicated performance data and recommendations tied to identifiable agronomic conditions.
Product economics are also obscured when an inoculant is bundled with fungicides, biological crop-protection products, nutrient enhancers or proprietary seed-treatment services. The full invoice price is not equivalent to inoculant revenue. Manufacturers that can quantify the separate contribution of the viable microbial component will be better positioned to communicate value and protect pricing during farmer input-budget scrutiny.
Storage life, logistics and product compatibility affect channel profitability
Inoculants contain live organisms and often require more careful inventory management than conventional dry fertilizers. Heat exposure, extended storage and poor handling can reduce microbial viability before application. For agricultural retailers, these risks create write-offs, handling expenses and claims exposure. Liquid, peat, powder and granular formulations compete partly on how well they preserve viable organisms under local logistics conditions; selection therefore depends on treatment equipment, crop type and distribution distance, not simply manufacturing cost.
Agricultural Inoculants Market Segmentation Analysis
By Crop Type: Soybeans
Soybean inoculants account for an estimated US$334.81 million in global 2026 revenue, reaching US$467.31 million by 2032. Although this is one of the most commercially mature crop applications, its forecast expansion is slower than that of some emerging non-legume uses because inoculation already has a substantial presence in Brazil and other major producing regions. The principal revenue opportunities in established soybean markets are therefore improvements in formulation value, compatible treatment platforms, repeat inoculation, and targeted use on farms where inoculation practices remain inconsistent.
Brazil is the central high-volume market. Embrapa records 48.72 million hectares of planted soybean area for the 2025/26 season. In the leading production states, biological nitrogen fixation is built into established soybean management, creating large annual demand for Bradyrhizobium formulations. However, the commercial relationship between crop area and product sales is not one-to-one. Multiple doses, different delivery methods and the presence of farm-produced or non-purchased biological preparations all affect purchased-market revenue. The 2024 ANPII Bio survey of member companies recorded approximately R$527 million in inoculant deliveries across Brazil, providing a useful industry-scale check but not an exact census of full-market 2026 sales.
The economic bottleneck for soybean inoculants is the viability of organisms delivered to seed before planting. Treatment operations increasingly combine rhizobia with fungicides, insecticides, polymers and additional biologicals. These components can interact, creating practical restrictions on how far in advance a seed lot can be treated. Manufacturers with longer on-seed survival and well-documented compatibility gain an advantage where large seed treaters need to prepare inventory ahead of planting windows. Higher concentration and lower liquid loading can also free treatment-line capacity for other approved components.
Novonesis' Cell-Tech and Optimize portfolio, BASF's Vault formulations, Rizobacter's Rizoliq products and Lallemand's LALFIX line demonstrate different commercial approaches to the same challenge. Competing technologies differ in rhizobial strains, application rates, carriers, compatibility conditions and support for early or pretreated seed. For buyers, the most relevant specifications are the viable organism count at use, permitted seed-treatment combinations, agronomic performance and delivered cost per hectare. Headline claims of biological activity alone are insufficient for comparing systems.
North American purchasing economics differ from those in Brazil. Soybean growers in the United States and Canada use inoculants in environments with varying histories of soybean cultivation and resident rhizobial populations. Application is therefore more selective, with a stronger emphasis on the incremental benefit of repeat treatment. University extension budgets provide useful price references: Mississippi State University's 2025 soybean planning budget included an inoculant line of US$1.55 per acre, while other extension examples of combined biological seed treatments show considerably higher costs because multiple products are included. These observations support a broad pricing range but should not be mistaken for a single universal inoculant ASP.
Soybean inoculant suppliers face additional pressure to avoid confusing crop-protection revenue with microbial nutrient revenue. BASF's Vault HP plus Integral illustrates a mixed inoculant-and-biofungicide approach: both components may have commercial value, but their combined seed-treatment selling price should not automatically be classified entirely as inoculant sales. This distinction affects competitive revenue estimates, product-margin analysis and comparisons with stand-alone rhizobial offerings.
The longer-term soybean opportunity remains attractive because large planted areas require treatment decisions each season, but manufacturers cannot rely solely on an expanding addressable acreage narrative. Mature markets will increasingly reward better formulation performance, treatment flexibility and channel execution. Higher-growth opportunities may arise in improved inoculant access for underserved soybean-growing areas and in microbe combinations that demonstrate measurable benefits beyond baseline nitrogen fixation. These must be substantiated by field evidence rather than assumed from the biological complexity of the products.
Other Segment Outlook
By microorganism, bacterial inoculants generate an estimated US$816.30 million in 2026, reflecting the commercial importance of rhizobial and nutrient-mobilising organisms. Fungal inoculants are projected to expand at an estimated 12.95% CAGR through 2032 as mycorrhizal products gain wider use in higher-value and non-legume applications. Microbial consortia are evaluated separately where the finished commercial product combines different organism groups and is not simply a relabelled bacterial inoculant.
By application method, seed treatment accounts for approximately US$717.82 million of the 2026 market, while soil and in-furrow applications provide an alternative when direct root-zone placement, seed-treatment compatibility or granular handling is required. Foliar application remains a smaller category and should only include qualifying live-microbial products, not nonmicrobial foliar biostimulants.
By formulation, liquid products represent an estimated 52.0% of 2026 revenue. Peat-based powder, granular and other dry products remain relevant in markets where viable organism survival, application equipment and field placement favor different carriers. Commercial classification should follow the sold formulation, with peat-based granules assigned once to the granular category.
By function, nitrogen fixation remains the leading identifiable use case; phosphorus mobilisation and mycorrhizal root enhancement offer avenues for diversification. Each product is assigned to its dominant marketed function for revenue estimation, avoiding double-counting multifunctional products.
Agricultural Inoculants Market Geographical Outlook
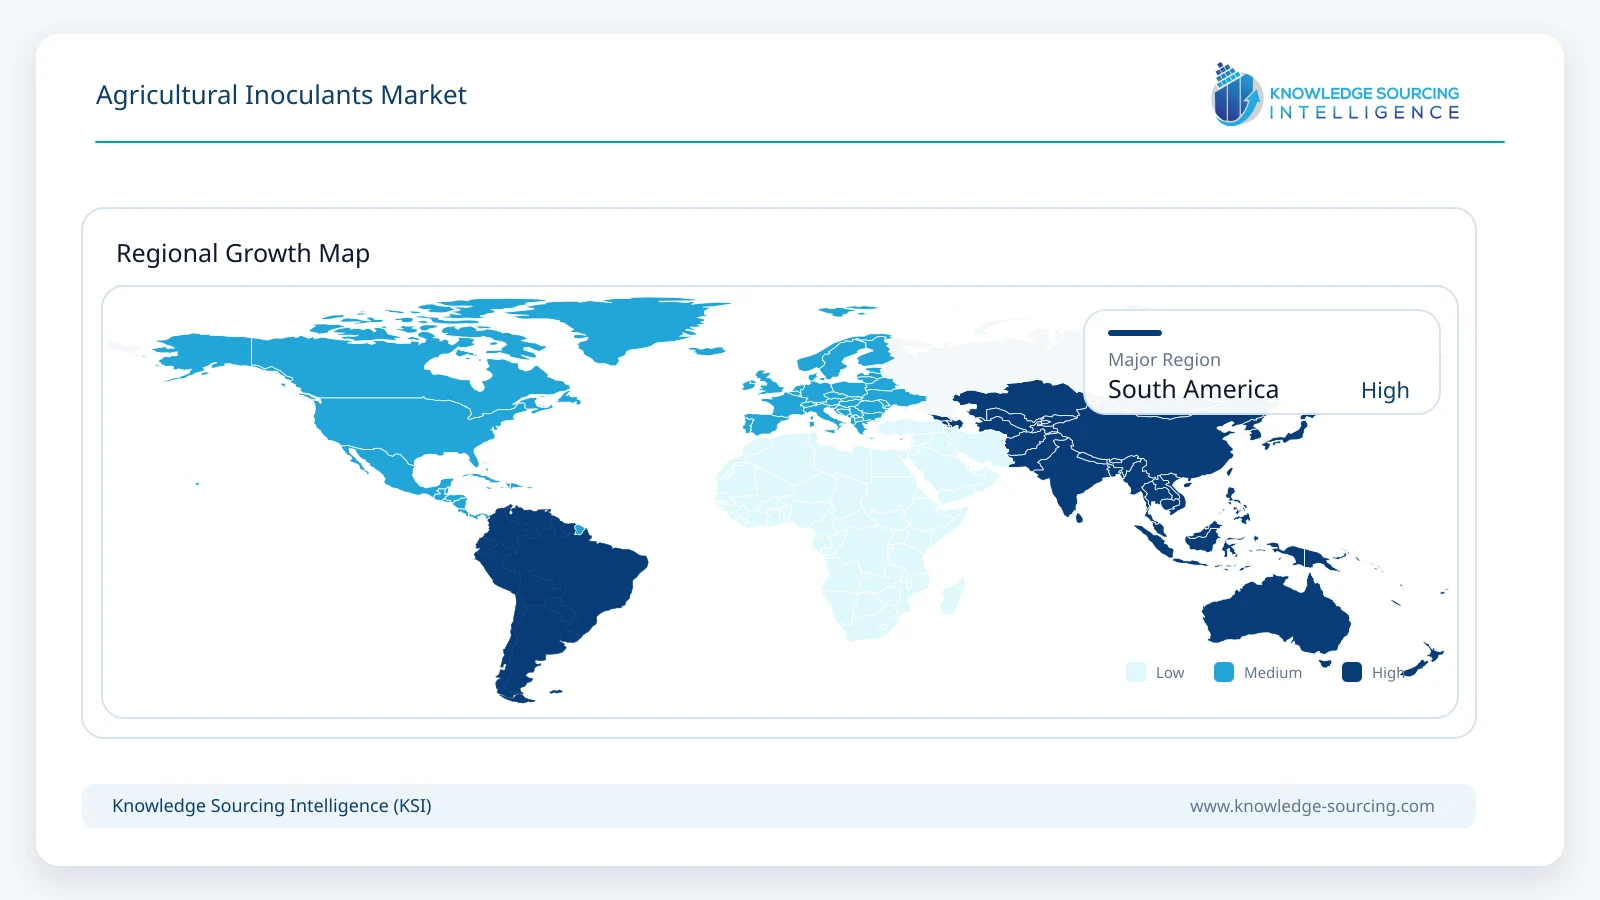
South America: Brazil's inoculant value chain is supported by soybean scale
Brazil combines unusually large soybean planting area with established awareness of biological nitrogen fixation and an industrial inoculant supplier ecosystem. The modeled Brazilian inoculant market is approximately US$135.91 million in 2026, including soybean and other qualifying crop applications. Growth is influenced by the treated share of planted area, repeat applications, increased use of Azospirillum and phosphorus-related organisms, and commercialization of more stable high-concentration formulations.
The association-reported 2024 inoculant sales figure of R$527 million offers more tangible triangulation than a generic sustainability narrative. It provides a reference for the revenue scale of the country but is not directly identical to the 2026 estimate because it covers a surveyed supplier panel, predates the forecast base by two years and is denominated in reais. Manufacturers entering the market therefore need to understand actual farmer acquisition costs, local distributor margins, registration claims and which biological products growers purchase rather than assuming that all soybean hectares generate the same average spend.
Elsewhere, North America combines relatively high spending per treated hectare with differentiated inoculation practices in soybeans and pulses. Europe is shaped by organism eligibility and commercial proof requirements, while Asia Pacific has the largest untapped treatment opportunity in modelled cereal and pulse areas. The region's agricultural inoculant market is projected to reach US$601.90 million by 2032, although uptake and realized pricing remain highly heterogeneous between countries.
Competitive Environment and Analysis
Competition spans specialist microbial producers, global crop-input companies and firms integrating inoculants into seed-treatment channels. Novonesis, BASF, Syngenta, Rizobacter, Lallemand Plant Care and Premier Tech Agriculture compete through rhizobial technology, formulation design and application compatibility. Groundwork BioAg and other mycorrhizal specialists focus on root-zone biology and product evidence, while newer entrants target crop-specific niches and innovative carriers. Company comparisons must be tied to qualifying inoculant products rather than consolidated biologicals or crop-protection revenue.
The principal distinction is between an established, repeat-purchase inoculant supporting nitrogen fixation and a broader microbial product whose agronomic claim and price still need validation. Suppliers able to combine dependable microbial viability, multi-season field data and channel distribution should be in a stronger position to sustain repeat sales and improve margins than companies relying on undifferentiated sustainability positioning.
Recent Developments
14 October 2026: Groundwork BioAg rootella Carbon received a BBB rating from BeZero Carbon.
11 September 2026: Syngenta Canada added Atuva Chickpea liquid rhizobial inoculant to the Atuva line.
24 July 2026: Syngenta Brazil announced Avakitt Neo mycorrhizal-based biological input for soybean and other crops.
20 January 2026: ProGro BIO introduced Rhizol JumpStart, a dry Bradyrhizobium peanut inoculant.
Agricultural Inoculants Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,251.1 million |
| Total Market Size in 2032 | USD 2,245.2 million |
| Forecast Unit | Billion |
| Growth Rate | 10.2% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Microorganism, Application, Formulation, Function, Crop Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Microorganism
Bacterial
Fungal
Microbial Consortia
By Application
Seed Treatment
Soil and In-Furrow
Foliar
By Formulation
Liquid
Peat-Based Powder
Granular
Other Dry Formulations
By Function
Nitrogen Fixation
Nutrient Mobilisation
Mycorrhizal Root Enhancement
Other Plant-Growth Functions
By Crop Type
Soybeans
Other Oilseeds
Pulses
Cereals and Grains
Other Crops
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
South Africa
Saudi Arabia
Others
Asia Pacific
China
India
Japan
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Revenue Boundary and Exclusions
2.4. Research Methodology
2.5. Study Period and Currency
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Value Chain and Distribution Economics
3.5. Pricing and Product Viability
3.6. Regulatory and Commercial Qualification
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Rhizobial and Nitrogen-Fixing Microorganisms
4.2. Phosphorus Mobilisation and Plant-Growth Microbes
4.3. Mycorrhizal Inoculants
4.4. Microbial Consortia and Formulation Stability
5. AGRICULTURAL INOCULANTS MARKET BY MICROORGANISM
5.1. Bacterial
5.2. Fungal
5.3. Microbial Consortia
6. AGRICULTURAL INOCULANTS MARKET BY APPLICATION
6.1. Seed Treatment
6.2. Soil and In-Furrow
6.3. Foliar
7. AGRICULTURAL INOCULANTS MARKET BY FORMULATION
7.1. Liquid
7.2. Peat-Based Powder
7.3. Granular
7.4. Other Dry Formulations
8. AGRICULTURAL INOCULANTS MARKET BY FUNCTION
8.1. Nitrogen Fixation
8.2. Nutrient Mobilisation
8.3. Mycorrhizal Root Enhancement
8.4. Other Plant-Growth Functions
9. AGRICULTURAL INOCULANTS MARKET BY CROP TYPE
9.1. Soybeans
9.2. Other Oilseeds
9.3. Pulses
9.4. Cereals and Grains
9.5. Other Crops
10. AGRICULTURAL INOCULANTS MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. Germany
10.3.2. France
10.3.3. United Kingdom
10.3.4. Spain
10.3.5. Others
10.4. Middle East and Africa
10.4.1. South Africa
10.4.2. Saudi Arabia
10.4.3. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. Australia
10.5.5. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Player Strategies
11.2. Product-Level Competitive Positioning
11.3. Partnerships and Product Launches
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Novonesis
12.2. BASF SE
12.3. Syngenta Group
12.4. Rizobacter
12.5. Groundwork BioAg
12.6. FMC Corporation
12.7. Lallemand Plant Care
12.8. Verdesian Life Sciences
12.9. Premier Tech Agriculture (AGTIV)
12.10. Protealis
12.11. ProGro BIO
12.12. BioConsortia
13. APPENDIX
13.1. Currency and Definitions
13.2. Forecast Assumptions
13.3. Base and Forecast Year Timeline
13.4. Research Methodology
13.5. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size for agricultural inoculants?
Market projected to reach $2,245.2 million by 2032.
What is the estimated CAGR for the Agricultural Inoculants Market?
Market is projected to grow at a 10.2% CAGR (2026-2032).
Which application segment holds the largest market share?
Soybean applications held a 26.8% share of revenue in 2026.
What key factors are driving market growth?
Growth driven by new applications, improved efficacy, and reliable delivery.
Which country represents a significant opportunity for inoculants?
Brazil's vast soybean area provides a significant recurring opportunity.
What are the primary operational challenges in the inoculants industry?
Maintaining viable microbial dose from manufacturing to root colonisation.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Agricultural Inoculants Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/agricultural-inoculants-market