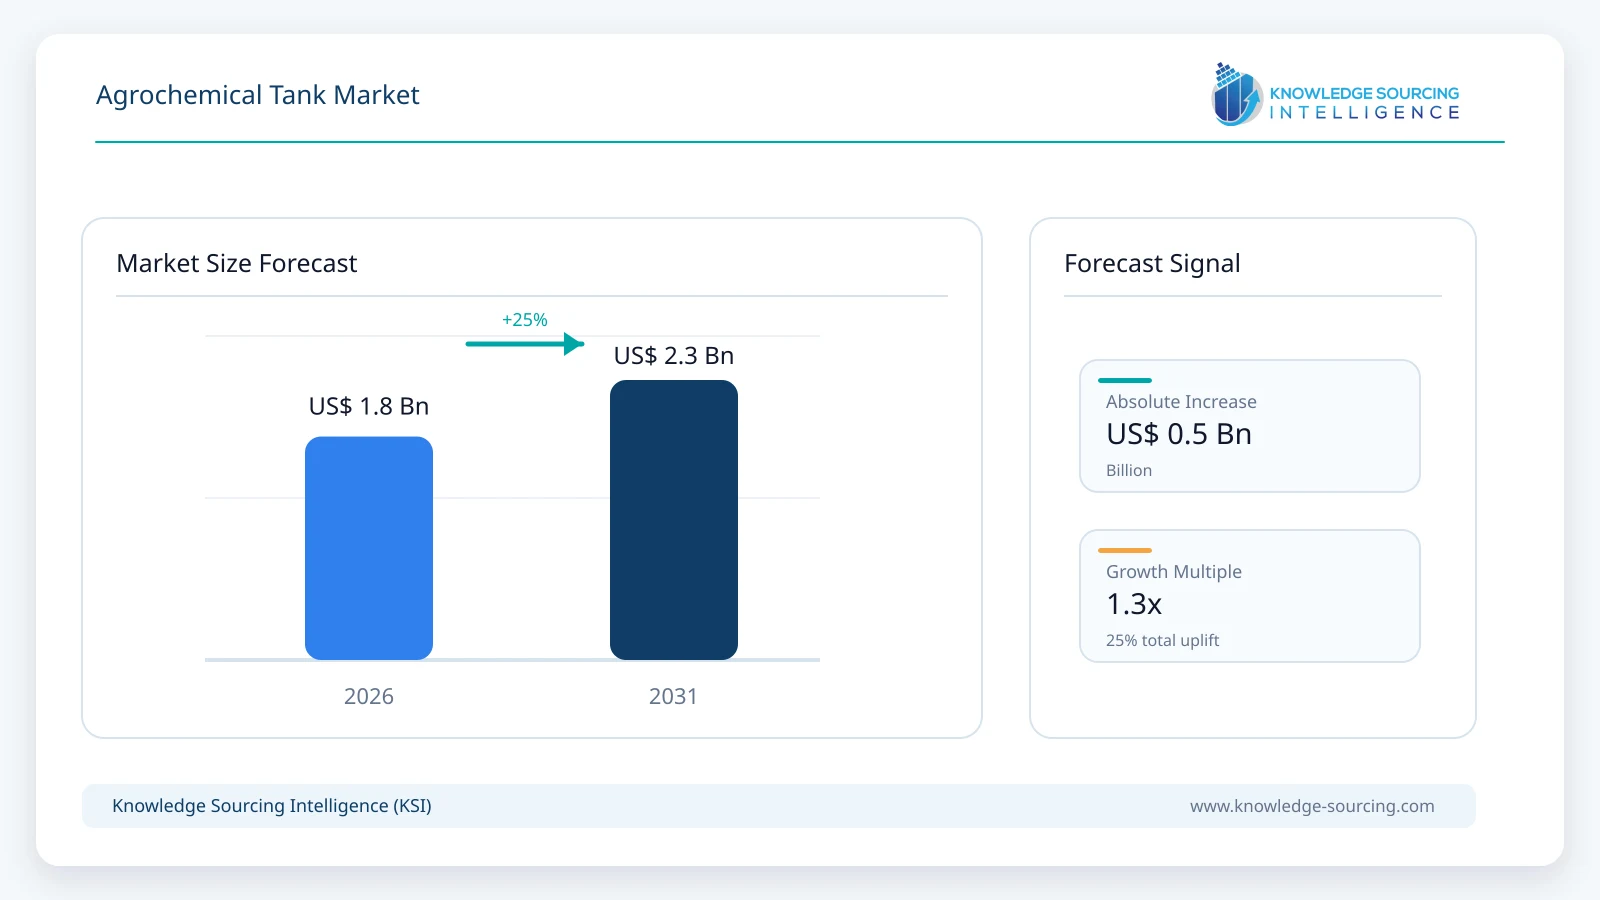
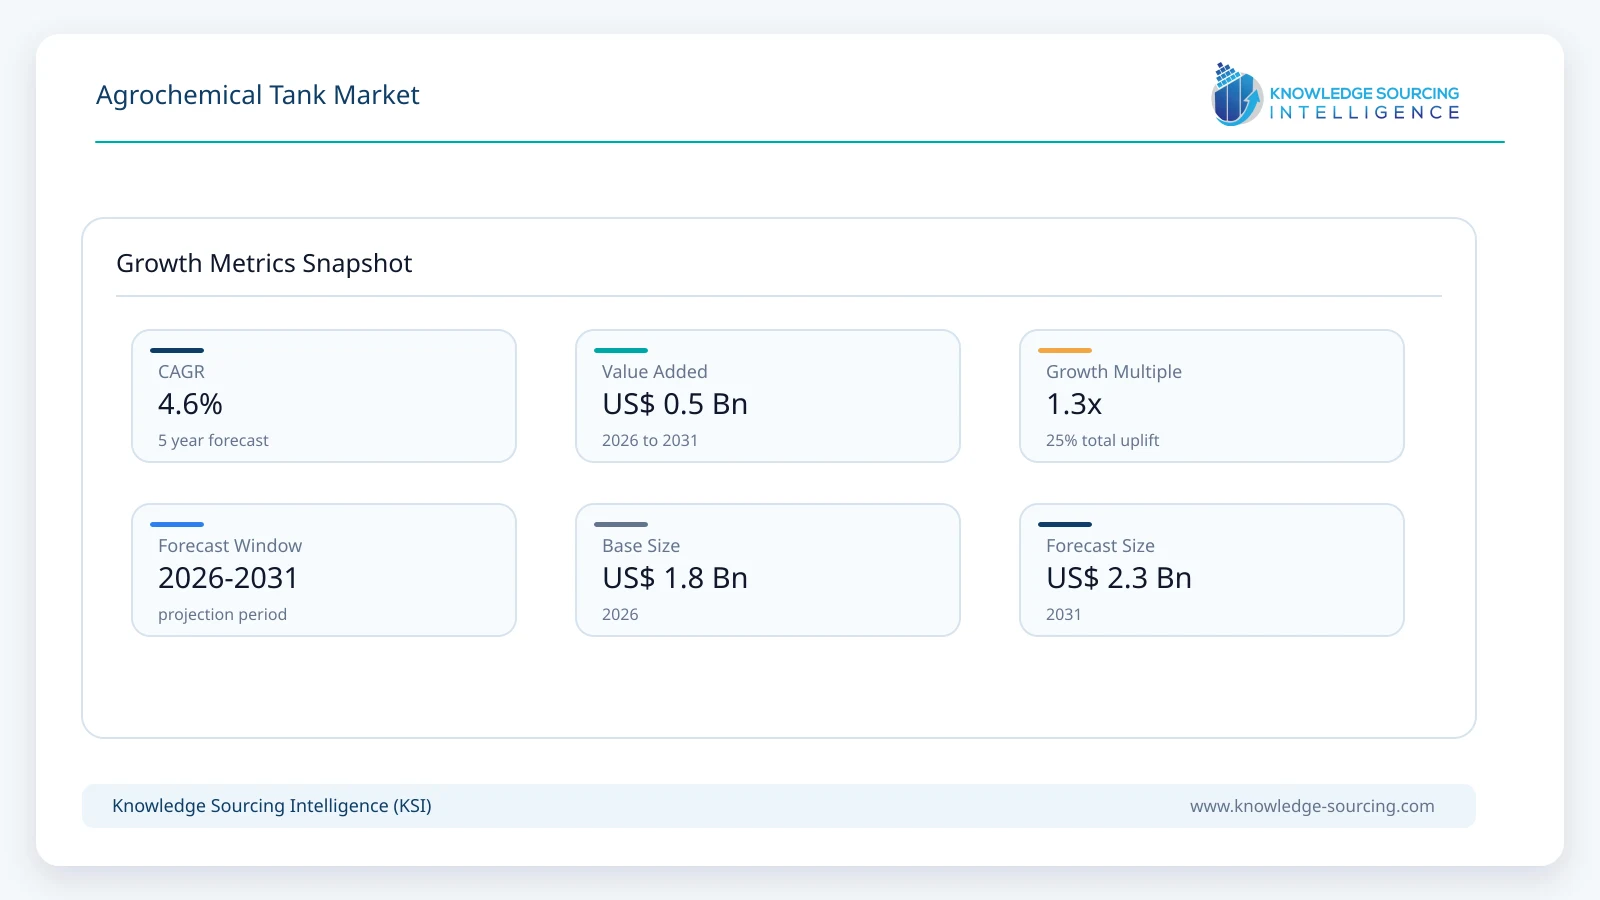
The Agrochemical Tank Market is projected to grow from an estimated USD 1.825 billion in 2026 to USD 2.287 billion by 2031, at a CAGR of approximately 4.61% during the forecast period.
Highlights:
1
Liquid-fertiliser customers buying in bulk increasingly select tank ratings, fill configurations and practical usable capacity together rather than treating volume as the only specification.
2
Purpose-built chemical storage is differentiated by compatibility testing, containment arrangements and fittings suited to the formulation; ordinary farm-water products cannot be presumed equivalent.
3
Polyethylene retains an established role in outdoor farm storage, while fibreglass and stainless-steel or engineered steel vessels address selected fertiliser and chemical applications.
4
The 15,000–30,000-litre segment represents an estimated 35% of 2026 market value, supported by bulk-delivery and agricultural distribution requirements.
5
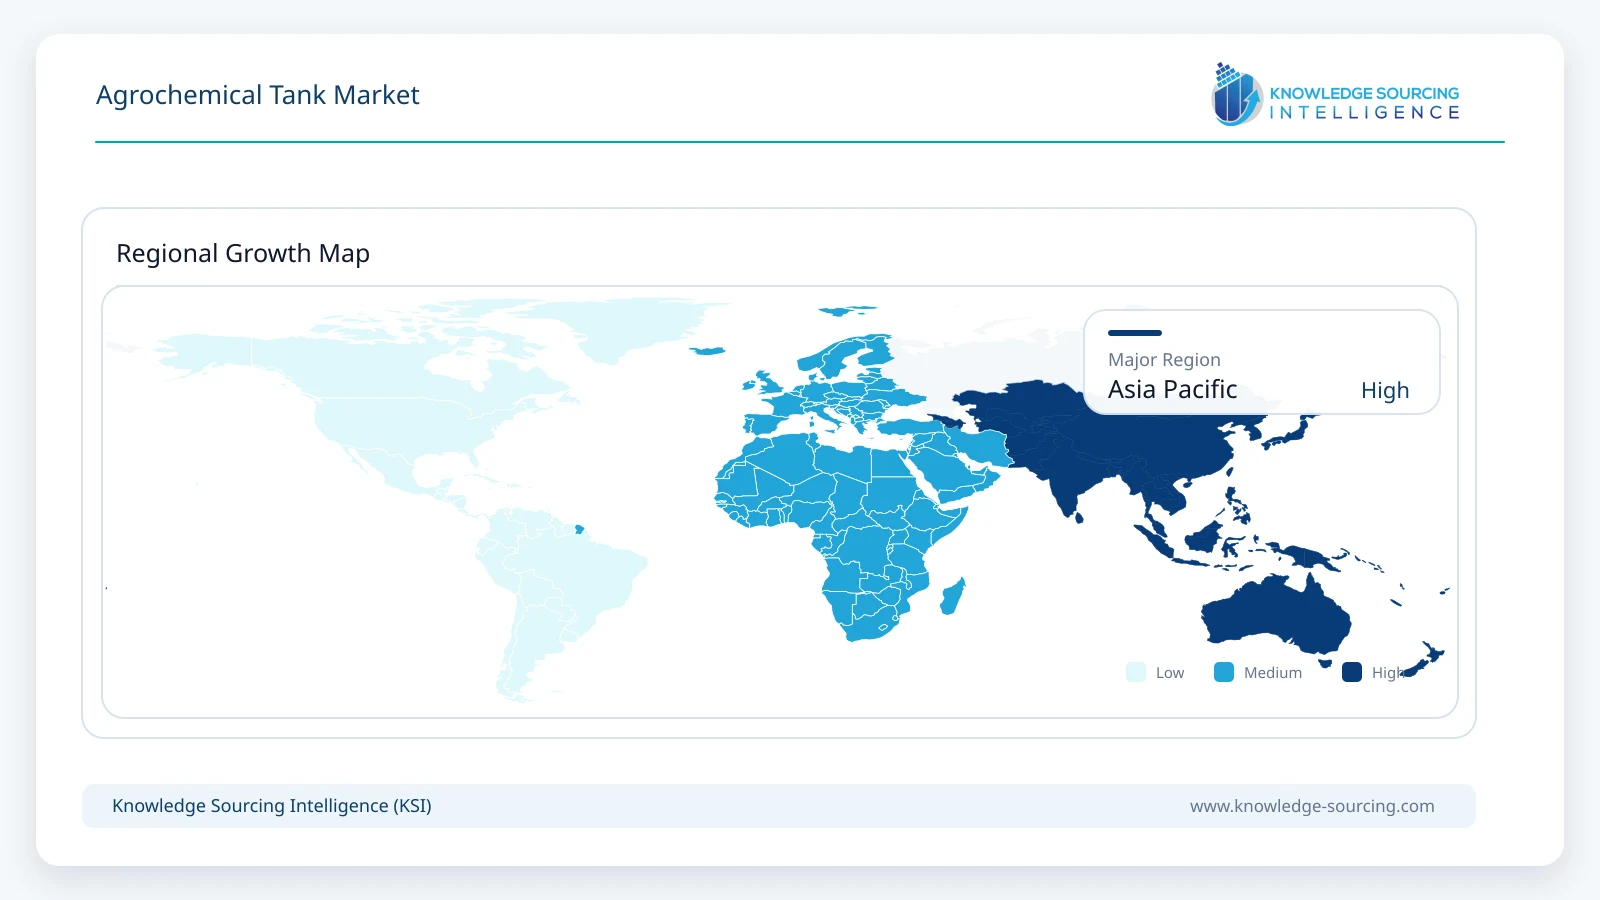
Asia Pacific remains the largest regional market, and irrigation-related investment provides a distinct growth channel for purpose-built storage in Middle East and Africa.
6
Tank suppliers offering documented chemical compatibility, suitable fittings and installation support are better positioned for regulated or high-density liquid duties.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Key Highlights:
Agrochemical storage tanks are manufactured for agricultural liquids, including crop-input mixing water, liquid fertilisers and pesticides. The product range extends from small batch and day tanks to stationary bulk vessels and transfer-compatible systems installed at farms and rural depots. Purchasers often order compatible valves, venting, filling equipment and containment with the vessel. Tank construction and the specifications of the stored liquid determine which products can be used safely, independently of nominal capacity.
An orchard feeding nutrients into irrigation lines may need a vessel that drains completely between blends, while a distributor receiving chemical tankers must consider unloading layout, backflow protection and the conditions of refillable-container storage. Manufacturer qualifications therefore depend on construction materials, density ratings, chemical resistance and installation documentation. The purchase also reflects local service capability: a large vessel with an attractive factory price can be costly if transport, site access or foundations are difficult.
Polymaster's liquid-fertiliser range illustrates the gap between buying a storage volume and specifying a working installation. Its flat-bottom tanks cover 9,000–50,000 litres, while self-draining vessels are offered at 23,000, 28,000 and 33,000 litres. The first configuration supports storage between bulk deliveries; the second is designed to reduce retained liquid when fertiliser blends change. An operator comparing them must consider the specific-gravity rating, discharge arrangement and cleaning requirements alongside capacity.
Agricultural pesticide storage imposes different conditions from storing water for application. U.S. Environmental Protection Agency rules apply containment requirements to specified pesticide retailers, commercial applicators and custom blenders with covered stationary containers or dispensing areas. Double-wall products, appropriate venting and compatible connections can therefore form part of the investment decision. Coverage depends on the actual chemical, site and jurisdiction, so a blanket claim that every agricultural tank requires identical containment would be misleading.
Direct manufacturing participation spans both agricultural tank producers and specialised chemical-storage suppliers. Tank Holding's Norwesco brand manufactures agricultural liquid-storage products, while Snyder Industries offers bulk chemical and agricultural tanks under the same corporate parent. Enduramaxx supplies fertiliser and bunded chemical vessels in the United Kingdom; KBK Industries builds fibreglass tanks for agricultural pesticides, fertilisers and water. Manufacturing proximity matters for bulky products, but an engineered vessel may compete across longer distances when chemical-duty specifications cannot be met locally.
Market Trends
Density-Rated Fertiliser Storage Becomes a More Visible Purchasing Requirement
Polymaster’s May 2026 farm-tank guidance distinguishes water storage from liquid fertiliser and molasses duty. Concentrated liquid products place greater hydrostatic loads on the vessel wall, requiring heavier construction and fittings appropriate to the stored material. The manufacturer identifies ratings of up to 1.5 specific gravity for selected fertiliser vessels. For a farm accepting full tanker deliveries, such specifications affect both the initial order and the likelihood of costly tank replacement later.
This raises the commercial value of written compatibility schedules and installation drawings. Dealers are better positioned to quote a complete, suitable unit when they know the mixture concentration, required turnover and likely temperature range. Simple capacity comparisons remain useful for purchasing, but they do not resolve the engineering questions that determine which suppliers can compete for a particular contract.
Self-Draining Bases Reduce Contamination between Fertiliser Blends
Liquid fertiliser tanks are increasingly sold with fittings that help an operator empty, clean and return the vessel to service. Polymaster’s self-draining configuration uses a sloped base, stainless-steel outlets and a tanker-fill connection; its published range covers 23,000, 28,000 and 33,000 litres. This design matters most where one site changes blends during the growing season and residual liquid could alter the next batch.
The premium for complete drainage must still be justified by operational savings. A dedicated tank storing one stable product can be less demanding, whereas contract blenders and intensive horticultural operations may value cleaning time, residue reduction and more precise stock accounting. The result is a wider price range within a single capacity category.
Secondary Containment Changes the Design of Bulk Chemical Storage
Enduramaxx lists double-skinned fertiliser tanks of 2,500 to 10,000 litres with integral containment of at least 110% of the primary vessel volume. Poly Processing also markets a tank-within-a-tank design, while its September 2026 catalog revision added a 407-gallon SAFE-Tank configuration. These products address facilities for which a spill has consequences beyond the cost of lost chemical.
Where bunding, level detection or compatible venting is required, the tank sale can include a larger engineered system. Such orders offer suppliers a different commercial position from the sale of plain water-storage vessels. Chemical-specific installation remains essential, because containment capacity alone does not establish suitability for every pesticide, acid or liquid fertiliser.
Chemical Storage Documentation Becomes Part of Supplier Differentiation
Assmann provides dimensional and capacity drawings across its vertical, conical and double-wall polyethylene tanks. Polymaster publishes installation manuals and compatibility resources, and Poly Processing maintains a chemical-by-chemical selection guide. These materials can reduce uncertainty during site design and shorten the effort required by an engineer or distributor to assemble a compliant specification.
An identifiable technical service proposition is particularly valuable in a fragmented manufacturing market. Buyers may accept a premium for traceable materials, suitable vents, correct nozzles and clear operating limits. Delivery lead times and after-sales support remain regional, so a supplier’s documentation and local fabrication capability can be more decisive than brand visibility alone.
Fibreglass and Steel Retain Roles in Large Chemical Installations
KBK Industries manufactures fibreglass agricultural tanks with resin selections matched to the corrosiveness of fertilisers and crop chemicals. L.F. Manufacturing supplies agricultural fertiliser and water-storage products in fibre-reinforced polymer, while Meridian's stainless-steel tanks serve specified liquid-fertiliser duties. These alternatives matter when a purchaser needs larger capacities, different corrosion performance or site arrangements not addressed by a standard polyethylene moulding.
None of these materials removes the need for chemical-by-chemical verification. Meridian, for example, identifies compatibility limits for grades of stainless steel used with fertiliser formulations. The manufacturer's engineering record, lining or resin selection, and installation requirements therefore influence the competitive field more than a general claim that one vessel material lasts longer.
Agrochemical Tank Market Segment Analysis
By Size
15,000–30,000 Litres
The 15,000–30,000-litre segment is projected to reach approximately USD 846 million in 2031. Farms and rural supply depots use these capacities for bulk liquid-fertiliser inventories without the full access and installation needs of the largest stationary tank installations. Polymaster's 22,500-litre flat-bottom design and its 23,000- and 28,000-litre self-draining models show how product configuration varies within a similar volume bracket. Buyers choose between cost-efficient holding capacity and easier changeover between crop-input blends.
The estimated growth rate of around 5.8% annually reflects a larger share of bulk deliveries and replacement of multiple smaller containers, rather than a uniform increase in vessel prices. Transport clearances, foundations and unloading plans become more relevant as capacity increases. Very large units above 30,000 litres serve a different procurement profile, often involving more specialised sites, while smaller tanks remain useful for rapid dispensing, temporary holding and portable applications.
By Application
Chemical Storage
Agricultural chemical storage is a more specialised purchasing category than general on-farm water storage. Crop-input distributors and commercial blenders increasingly require purpose-built containment and handling systems rather than standard low-density water vessels. Assmann and Poly Processing supply engineered polyethylene chemical-storage products; Enduramaxx offers bunded configurations. The suitability of each system depends on formulation, concentration, fittings, venting and applicable facility requirements.
By 2031, agricultural chemical storage is projected to reach approximately USD 617 million, expanding by about 6.2% annually as buyers place greater value on specified fittings and containment. A leak can interrupt crop-input distribution, damage stock and generate costs well beyond replacement of the vessel. Water remains the broadest storage application, while chemical tanks offer manufacturers more scope for engineering differentiation and higher-value installed configurations.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Drivers
Bulk Liquid-Fertiliser Handling at Larger Farms
Road-tanker deliveries increasingly determine the storage plan at commercial farms. Tank volume must fit delivery schedules and field application windows, while the fluid density and outlet package must match the actual fertiliser blend. Polymaster's flat-bottom and self-draining products show that similar capacities can serve different replenishment and cleaning requirements.
Bulk purchasing can reduce handling time and improve stock visibility, especially where several applications are made during the growing season. Replacement orders will nevertheless depend on whether existing tanks remain suitable and whether new fertiliser formulations, crop expansion or more frequent deliveries justify investment.
Water Availability and Farm Storage Investment
Irrigated production often requires a reserve of water for agrochemical dilution or nutrient dosing even where the farm is connected to a larger distribution network. Drought exposure and variable delivery schedules make the location and working capacity of that reserve important; crops with narrow timing windows are particularly sensitive to interruptions.
A tank manufacturer benefits when farms add discrete mixing or fertigation storage to an improved irrigation installation. Such spending should not be confused with the entire cost of reservoirs or pipelines. The commercial case improves when a standard capacity can be connected to existing pumps and controls without extensive civil work.
Safer Bulk Pesticide Dispensing
Pesticide distributors and custom blenders handling covered stationary containers face duties concerning containment and safe dispensing. The EPA's U.S. rules distinguish these facilities from ordinary small-container users, making the precise operating arrangement important when equipment is specified.
A compliant installation can require more than a vessel: containment, transfer connections and inspection provisions may all be material. For tank manufacturers, sales depend on proving chemical suitability and supplying reliable drawings and component specifications rather than promising that a generic polymer tank meets every regulation.
Expansion of Agricultural Distribution Infrastructure
Crop-input dealers operating away from major production centres need holding capacity between upstream tanker deliveries and smaller farm orders. Storage at the regional depot can reduce repeated unloading of small packages and help distributors service farms during peak fertiliser and spraying periods.
Locally made polyethylene tanks may gain an advantage where haulage distance dominates delivered cost, while larger fibreglass or steel vessels compete on duty rating and lifetime service. Dealer consolidation and the seasonal cost of financing inventories mean such installations are often approved in discrete steps rather than as a continuous national rollout.
Replacement of Unsuitable Multi-Purpose Tanks
Farms sometimes repurpose clean-water tanks for liquid fertilisers or concentrated formulations after the original equipment was installed. Manufacturers' published specific-gravity limits and chemical-resistance schedules show why visual similarity between two tanks does not guarantee safe interchangeability.
Investment can be triggered by an inspection finding, changed crop-input formulation or a new contract requiring certified storage. This is a replacement market grounded in avoided failures and appropriate equipment selection, rather than one that necessarily follows expanding planted acreage.
Market Restraints
Farm Capital Budgets and Seasonal Purchasing
The acquisition cost of bulk tanks frequently understates the installed project expense. Foundations, unloading access, transfer pumps, containment and delivery equipment can change the financial assessment, especially where the tank is remote from the manufacturer's plant.
Growers also balance storage against seasonal purchases of seed, machinery and other inputs. Standardised configurations and local dealer stock may shorten delivery, but high-capacity installations remain vulnerable to delayed farm capital spending when operating margins or available credit weaken.
Chemical Compatibility and Liability Exposure
Chemical compatibility is a product-level constraint. Specific gravity, liquid temperature, concentration, seals and resin formulation all affect the suitable tank design; a rating for one fertiliser mixture does not establish suitability for another.
Buyers without complete formulation and installation information may need technical review before placing an order. The consequences of unsuitable specification include leakage, warranty disputes and environmental liability, putting greater weight on manufacturer documentation and trained distribution partners.
Bulky Freight and Site Preparation
The freight cost of a large tank is driven by its diameter and height as well as its mass. Oversized loads, narrow farm access roads and available cranes can determine whether a vessel is practical at a proposed site.
This gives nearby moulders an advantage in standard-capacity categories. Suppliers of larger engineered vessels can still compete across borders, but freight, customs and installation schedules must be considered alongside the factory quotation, sometimes favouring alternative configurations or modular storage.
Regulatory Variation across Stored Products
Storage regulations apply to specific products, facilities and handling activities rather than an undifferentiated class of all agricultural tanks. Pesticide containment rules, local construction provisions and environmental obligations can differ substantially across jurisdictions.
The same product range therefore needs different application guidance and site documentation in different markets. A manufacturer that cannot establish the customer's duties may lose a sale to a local specialist; an operator may defer a purchase while compatibility or containment requirements are resolved.
Price Competition from Standard Water Tanks
General-purpose water tanks can be visually indistinguishable from higher-duty chemical and fertiliser vessels in an online catalogue. Where a buyer compares only nominal litres and price, the additional wall strength, fittings and specification work of a purpose-built product may be undervalued.
Suppliers need to show why their ratings fit the stored liquid rather than relying on broad durability claims. The competitive pressure is particularly strong in small sizes and in price-sensitive rural channels, while larger facilities more often require documentation before approving a purchase.
Regional Outlook
Asia Pacific
Asia Pacific accounts for an estimated 35% of agrochemical tank revenue in 2026, equivalent to approximately USD 639 million. KSI identifies the region as the principal market, and the breadth of farming in China, India and Southeast Asia supports demand for both general agricultural-water vessels and storage for fertiliser and crop-protection inputs. Manufacturers must serve large-scale commercial users alongside smaller holdings that buy standard tanks through rural distributors.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
The regional market is forecast to reach approximately USD 800 million in 2031, retaining a share of around 35% and expanding by approximately 4.6% annually. Growth in fertigation, larger farming operations and rural input distribution favours high-density liquid service and reliable bulk delivery. At the same time, differences in farm size, industrial standards and access to installation services prevent premium chemical-storage specifications from becoming uniform across the region.
Middle East and Africa
Middle East and Africa is expected to be the fastest-growing regional market, at approximately 9.4% annually from 2026 to 2031, compared with its smaller initial revenue base. Agricultural projects confronting water scarcity require local storage alongside irrigation and nutrient-handling systems. Financing programmes for water-efficient agriculture, including EBRD-supported irrigation modernisation in Morocco, illustrate the infrastructure backdrop, although not every such project purchases an agrochemical tank.
The region's estimated market share rises from 8% in 2026 to 10% in 2031, or approximately USD 229 million by the end of the period. That acceleration depends on execution of farm and input-distribution projects and the availability of suitable local installation support. High temperatures, chemical suitability, transport distances and uneven financing still influence procurement, favouring suppliers able to provide appropriate product data and practical delivery plans.
Competitive Landscape
Tank Holding’s Norwesco and Snyder operations illustrate the range within a single manufacturing group: agricultural liquid storage on one side and specialised bulk chemical containers on the other. Polymaster combines farm-fertiliser products with heavier-duty engineered chemical tanks; Enduramaxx covers conventional and bunded options in the UK. Assmann and Poly Processing place greater emphasis on chemical storage engineering and compatible accessories. The competitive boundary follows the installation requirement more closely than a simple ranking of manufacturers by vessel output.
Transport economics favour regional manufacturers, while specialised chemical-storage suppliers can justify longer delivery routes where ratings and engineering services are decisive. KBK Industries offers fibreglass agricultural tanks for pesticides, herbicides and fertilisers; L.F. Manufacturing supplies agricultural fertiliser vessels, and Meridian manufactures compatible stainless-steel tanks for selected fertiliser duties. These firms compete in identifiable products rather than acting simply as resin suppliers, advisers or farming customers.
Recent Developments
August 2026: Polymaster published a Wilmar AgServices project case study describing engineered liquid storage supplied for an agricultural sugarcane-related operation. The published installation illustrates specialist tank demand within agribusiness supply chains.
August 2026: Polymaster documented a Brookeshill Orchards project involving bulk liquid-storage systems to support orchard water management. This is a disclosed customer installation, not a new product introduction.
July 2026: Polymaster released its hazardous-IBC chemical-storage guidance, detailing issues of chemical compatibility, containment and transfers relevant to agricultural input depots.
January 2026: The U.S. Environmental Protection Agency updated its pesticide-storage guidance, reiterating the containment conditions for covered stationary agricultural pesticide containers of 500 gallons or more; it was guidance maintenance, not a new rule.
Market Outlook
Expansion will depend on investment in productive farm storage, not simply the volume of agrochemicals sold. The main replacement opportunity is to fit existing sites with equipment suited to the liquid handled, including specific-gravity ratings, outlets, venting and containment where necessary. The market will continue to serve low-cost standard tanks and specialised engineered systems simultaneously, with different suppliers winning each type of order.
A reliable commercial proposition will increasingly include more than the molded shell. Installers and distributors need product-specific drawings, chemical compatibility guidance and access to replacement parts. The most resilient manufacturers are likely to combine repeatable fabrication with application knowledge and local delivery networks. Spending on water infrastructure and agricultural input distribution can support market growth, while farm capital constraints and transport costs should temper expectations of uniform regional expansion.
Agrochemical Tank Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 1.825 billion
Total Market Size in 2031
USD 2.287 billion
Forecast Unit
USD Billion
Growth Rate
4.61%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Size, Application, Geography
Companies
Tank Holding Corp. (Norwesco and Snyder Industries)