AI in Epigenetics Market - Strategic Insights and Forecasts (2026-2031)
AI in the Epigenetics Market Size, Growth, Forecasts and Trends Analysis By Technology (DNA Methylation, Histone Modification, Non-Coding RNA Analysis, Chromatin Accessibility, Others), Application (Oncology, Non-Oncology), End User (Academic & Research Institutions, Pharmaceutical & Biotechnology Companies, Clinical Laboratories, Hospitals & Clinics), and Geography
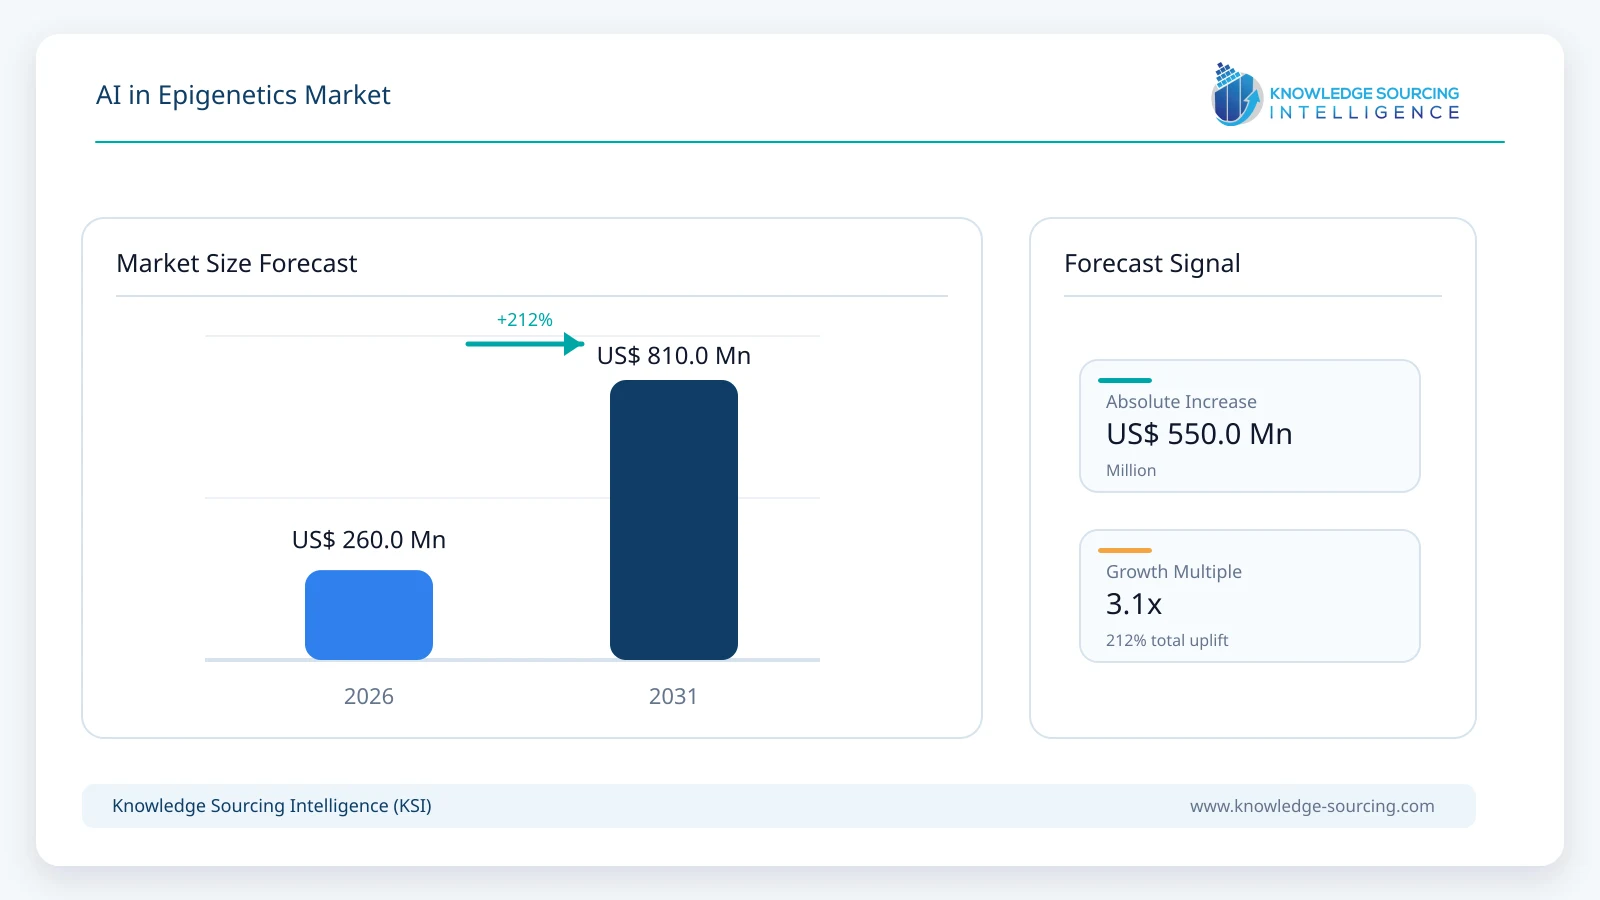
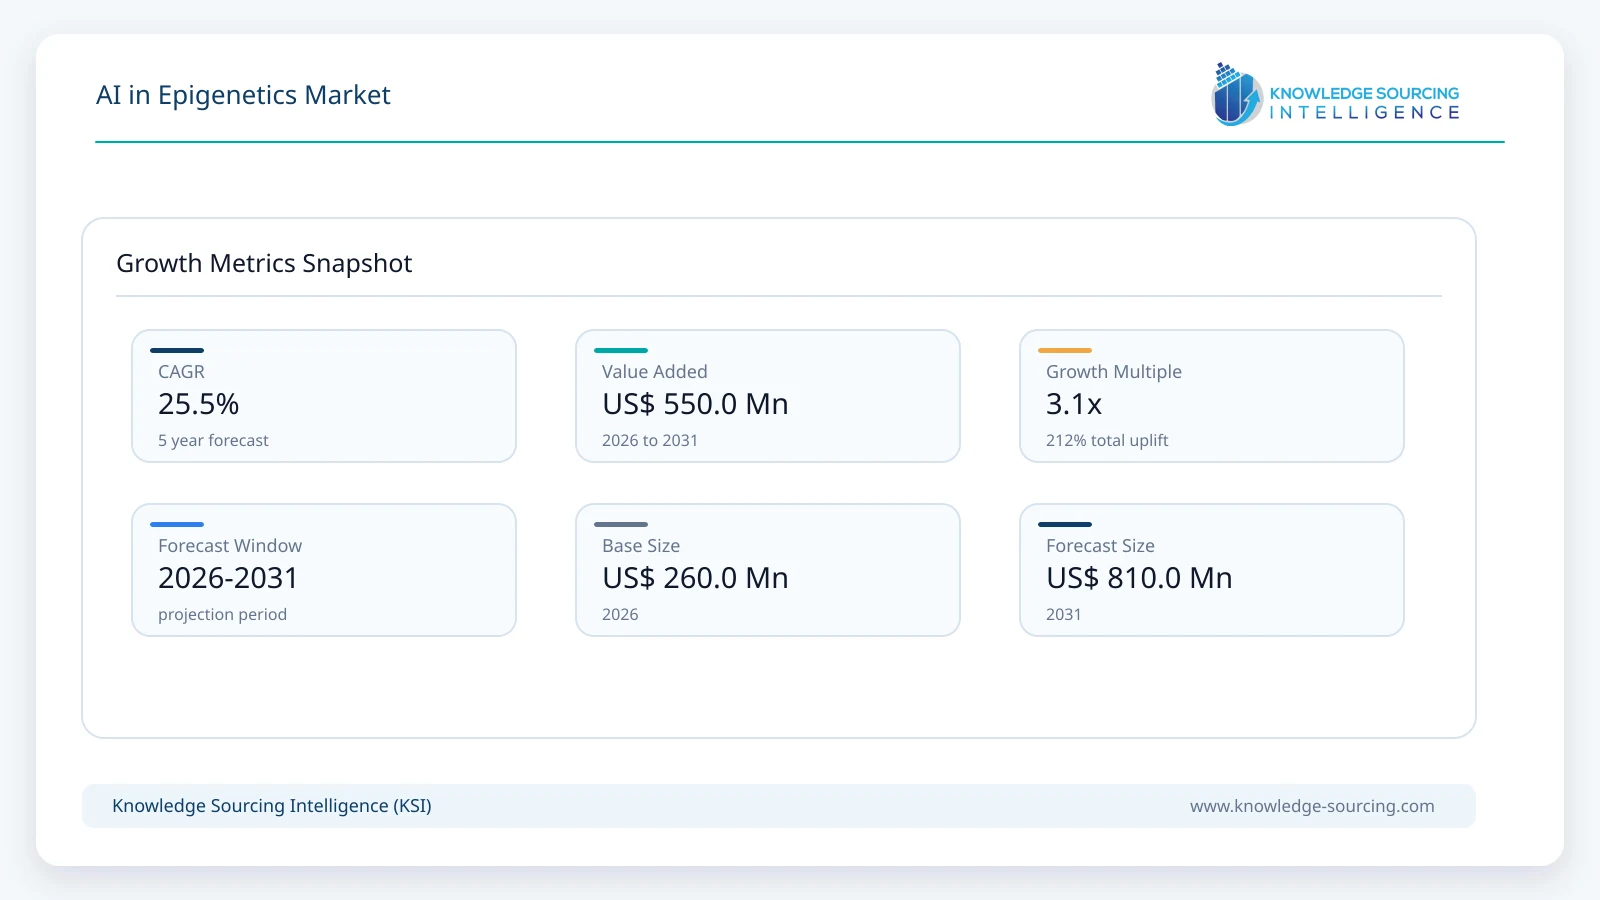
The AI in Epigenetics Market is projected to grow from USD 260 million in 2026 to USD 810 million by 2031, at a CAGR of 25.5% during the forecast period.
Highlights:
1
DNA methylation is the principal technology segment because disease-linked episignatures and tumor methylation classifications have established analytical pathways.
2
Oncology remains the largest modeled application, while rare-disease and developmental-disorder testing support a distinct non-oncology opportunity.
3
Academic and research institutions provide the broadest installed user base; clinical laboratories offer a more specialized route to recurring interpretation services.
4
Sequencing-derived methylation analysis is reducing dependence on separate array-only workflows, although specimen and platform validation remain necessary.
5
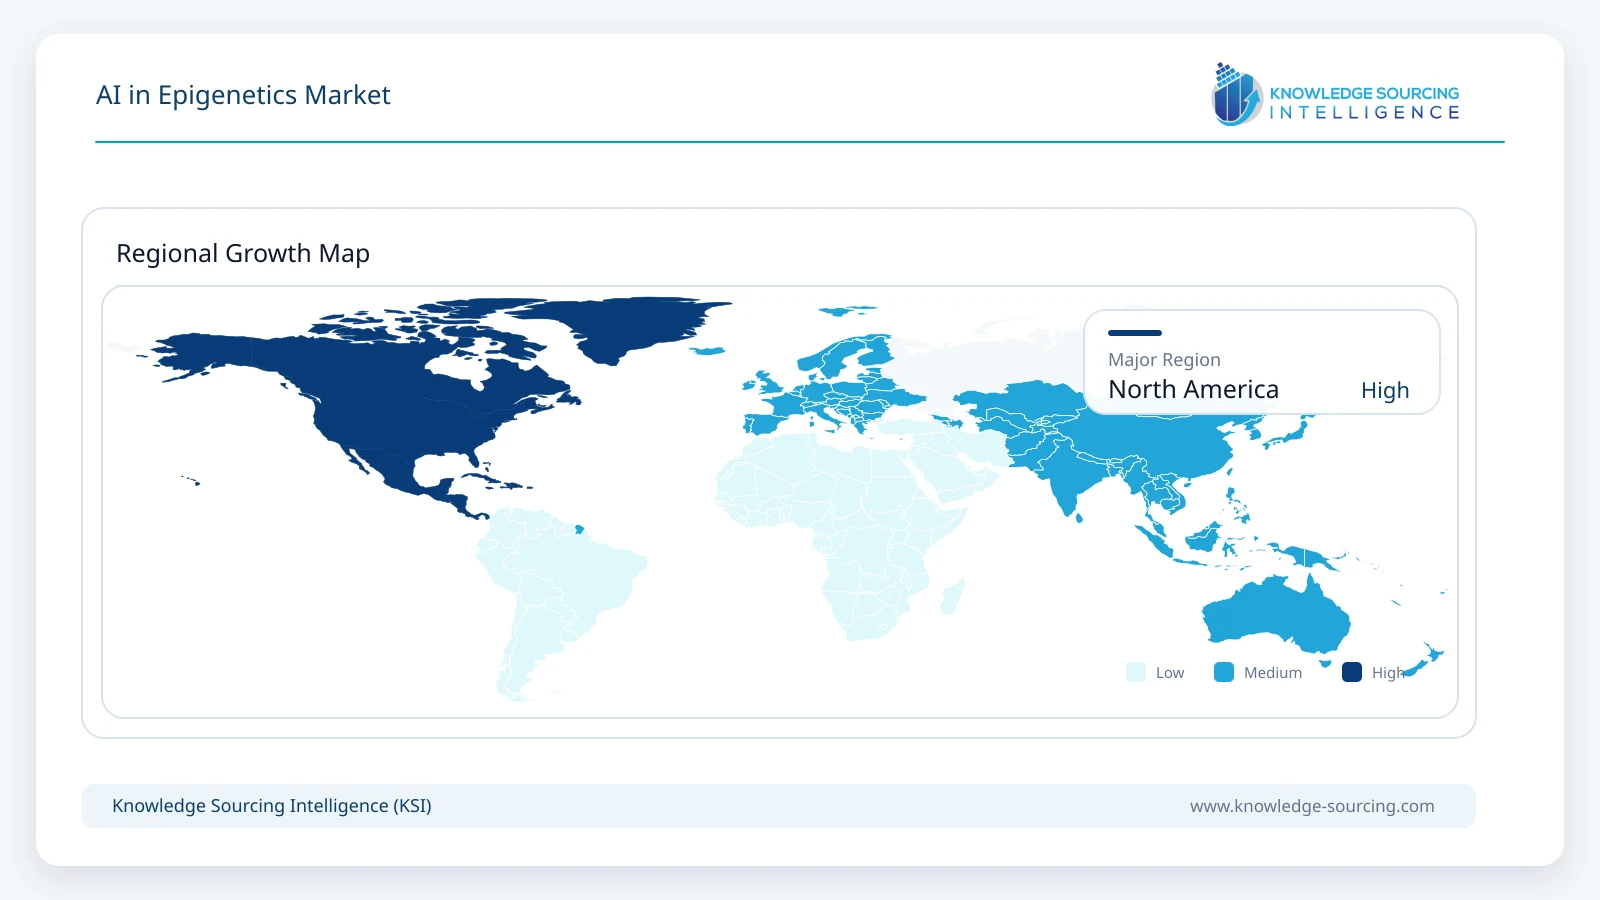
North America represents the largest modeled market in 2026; Asia Pacific is expected to expand faster as regional sequencing capacity and translational research increase.
6
Product positioning increasingly depends on the breadth of reference databases, external reproducibility and clear differentiation between research and clinical indications.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Key Highlights:
AI in epigenetics encompasses specialized computational software and analytical services used to interpret DNA methylation, histone marks, non-coding RNA and chromatin accessibility data. Buyers use these capabilities to identify disease-associated regulatory patterns, classify samples, prioritize research hypotheses and compare molecular evidence across assays. The commercial scope includes identifiable classifier access, research analytics and specialist integration. The full price of a sequencing system, laboratory reagent or epigenetic therapy should not be equated with the value of AI-enabled interpretation.
The laboratory workflow determines the product’s usefulness. Long-read sequencing and 5-base chemistry are generating richer methylation measurements, but classifier performance still depends on tissue type, specimen handling, reference-cohort design and controls for batch effects. A tool calibrated with blood-based rare-disease samples cannot automatically serve as an oncology classifier. These differences constrain cross-selling, yet they also support specialized products with curated training data and documented performance across compatible assays.
Procurement is distributed across universities, pharmaceutical developers, diagnostic laboratories and precision-medicine programs. Academic groups may purchase software under research grants; commercial laboratories want reliable turnaround and documented validation; pharmaceutical companies seek reproducible evidence of a useful biomarker or regulatory target. Market participation consequently ranges from EpiSign and Cyclomics to measurement platform providers such as Illumina, PacBio and Oxford Nanopore. The ability to connect computational outputs with existing laboratory records remains central to sustained adoption.
PacBio began worldwide shipment of SPRQ-Nx chemistry in May 2026, combining expanded modified-base calling with improvements to its AI-powered DeepConsensus analysis. Illumina has also described workflows that bring 5-base methylation measurements into Connected Multiomics for joint review with variant and pathway evidence. These developments increase the quantity of epigenetic information a laboratory can recover from an established sequencing program. The resulting opportunity for software suppliers lies in calibrated biological interpretation, not merely in processing more sequence reads.
Rare-disease diagnostics already provide evidence of a maintainable classification business. EpiSign version 6 expanded coverage to more than 310 episignature conditions in June 2026, and its subsequent METRIC 5-base offering extends that classifier framework to supported sequencing outputs. The new 5-base workflow was launched for research use and requires site-level validation before routine implementation. Customers therefore compare not only the number of disorders represented but also the quality of external reference data, cross-platform concordance and the rules governing a reportable result.
Oncology presents a related but technically different market. Cyclomics secured rights to the Sturgeon classifier in May 2026 to develop rapid tumor identification with its Epinn software. Its value proposition is strongest where obtaining a molecular classification during a clinical decision window could change how specimens are handled or interpreted. Commercial progress depends on defined tumor indications, assay readiness and clinical evidence, while research teams studying chromatin or RNA regulation may continue to prefer adaptable open analysis pipelines over fixed diagnostic products.
Market Trends
Methylation interpretation is following sequencing into the laboratory
The September 2026 METRIC 5-base release illustrates a change in how epigenetic software is distributed. Laboratories producing methylation signals through Illumina 5-base, PacBio HiFi or Oxford Nanopore workflows can evaluate a common reference classifier without developing hundreds of disease-specific models. That reduces the technical burden of first adoption, but it does not eliminate the need to check data processing, classification confidence and compatibility with local sample types.
Platform-neutral interpretation creates opportunities for subscription and per-analysis services, particularly among laboratories that already own the required sequencers. Supplier differentiation is shifting toward the maintained reference database, quality assurance and integration with clinical review. An algorithm that accepts more data formats will only win durable business if its outputs remain consistent and explainable across sites.
Rapid tumor classification is testing the limits of clinical turnaround
Cyclomics’ Sturgeon licensing agreement puts methylation-based tumor classification into a workflow designed for decisions made under considerable time pressure. The underlying model uses nanopore data and deep learning to identify central nervous system tumor classes during surgery. Its commercial promise is tied to time-sensitive pathology decisions rather than the general availability of AI computation.
Hospitals assessing such products must establish what happens when a specimen generates insufficient coverage or low-confidence output. Training, sample logistics, pathologist oversight and documentation add cost to the software. Reliable deployment could nonetheless support specialist service fees where a result arrives early enough to alter a defined decision and where the alternative diagnostic sequence takes substantially longer.
Multi-omics platforms are treating epigenetic marks as connected evidence
Epigenetic findings become more informative when researchers can compare them with sequence variation, RNA expression and clinical phenotype. Illumina’s Connected Multiomics workflows are designed to keep methylation, quality-control and pathway evidence within a traceable analytical environment. The adoption driver is not the novelty of combining data types; it is the ability to revisit a conclusion when an assay or reference model changes.
Cross-omics integration increases demand for consistent identifiers, specimen metadata and versioned pipelines. Products built around one assay type may face pressure from broader research informatics platforms, yet specialist classifiers retain value when they offer validated knowledge that a general platform cannot supply. Data-governance provisions for multi-institutional research are becoming a material part of the purchase decision.
Rare-disease reference networks are becoming commercial assets
A methylation classifier is only as useful as its disease reference set and the samples against which it has been tested. EpiSign’s expanded episignature catalogue and research partnerships show how a maintained reference library can accumulate value over time. The company’s March 2026 participation in a secure synthetic-reference initiative also reflects the difficulty of pooling sensitive patient-level methylation data across institutions.
For customers, shared networks can broaden access to uncommon syndromes and improve the chance that an unusual finding is interpreted against a relevant comparison group. For suppliers, the operational work involves permissioned data access, cohort documentation and ongoing model assessment. Funding a one-off research classifier is comparatively easy; maintaining an internationally usable reference service requires recurring technical and clinical support.
Computational research is expanding beyond DNA methylation
Histone modifications, chromatin accessibility and non-coding RNA measurements help researchers examine regulatory effects that methylation alone cannot explain. Epigenica’s 2026 EpiFinder cNUC release, for example, combines circulating-nucleosome histone-mark profiling and DNA methylation within a research-oriented assay. Analytical software has to preserve distinctions among these measurements rather than collapse them into an undifferentiated risk score.
Pharmaceutical programs may pay for integrated methods when they identify an experimentally actionable regulatory target. Moonwalk Biosciences and nChroma Bio illustrate adjacent therapeutic interest, but their research spending is not equivalent to diagnostic classifier revenue. The next competitive opportunity is likely to sit with software and service teams that connect epigenomic predictions to confirmatory experiments and document what remains uncertain.
AI in Epigenetics Market Segment Analysis
By Technology
DNA Methylation
DNA methylation accounts for an indicative USD 156 million, or 60% of the 2026 market model. Its commercial lead reflects a relatively established measurement infrastructure, disease-specific episignature libraries and recognizable use cases in tumor classification and rare-disease interpretation. EpiSign’s software and Cyclomics’ tumor-oriented tools provide a clearer purchasing rationale than open-ended epigenomic exploration, because the output can be tested against a named classification problem.
The segment is modeled to reach USD 445.5 million by 2031 as methylation analysis spreads across sequencing workflows, although faster growth in chromatin and multimodal research gradually broadens the market mix. Histone modification and accessibility analysis are technically significant but remain more dependent on customized pipelines and research expertise. Commercial software must preserve the relationship between a signal, its assay conditions and an independently reviewed biological interpretation.
By Application
Oncology
Cancer-related epigenomic analysis represents approximately USD 169 million in the 2026 working estimate, reflecting the use of methylation and chromatin information in tumor subtyping, biomarker research and therapeutic target investigation. The June 2026 Hetairos publication, which assessed prediction of central nervous system tumor methylation subtypes from histology, demonstrates how AI is extending the range of evidence available to pathologists. Such research is promising but should not be mistaken for an automatically deployable clinical product.
Oncology revenue is indicatively projected to reach USD 486 million by 2031. Practical adoption will depend on specimen compatibility, the probability of indeterminate results and whether an algorithm changes diagnosis, treatment selection or trial enrollment. Non-oncology programs will continue growing around rare genetic conditions and biological aging research, although claims in those areas require equally careful control of indications and clinical evidence.
By End-User
Academic & Research Institutions
Academic and research institutions are modeled as the largest end-user category at about USD 91 million in 2026, or 35% of the total. Their laboratories generate reference datasets, investigate uncommon regulatory effects and evaluate new assay combinations before a commercial diagnostic pathway is established. Such activity supports purchases of specialist software, analytical services and selected platform extensions, but grant awards and full laboratory equipment budgets are not direct measures of AI epigenetics spending.
By 2031, academic and research demand is modeled near USD 243 million as more institutions adopt analysis support across shared sequencing and bioinformatics facilities. Pharmaceutical developers and clinical laboratories may gain share as validated workflows become repeatable and budgeted operational services. For research suppliers, interoperability, reproducible file formats, institutional licensing and technical support will remain as important as model sophistication.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Drivers
Sequencing workflows are capturing more epigenetic information
Modified-base information is becoming available through technologies that laboratories also use for conventional genomic analysis. PacBio’s expanded methylation callers and Illumina’s 5-base workflow mean that a single specimen can provide more regulatory information without always requiring a separate epigenetic assay. This increases the opportunity for interpretation platforms tied to existing sequencing throughput.
The commercial conversion is not automatic. A laboratory must decide whether the additional data answers a funded research or clinical question, and the associated analysis must be supported across instruments and sample conditions. Vendors that maintain reproducible pipelines and integrate findings into current reporting software are more likely to earn repeat purchases.
Precision oncology requires more informative molecular classification
Tumors with similar appearances can differ in regulatory state, progression and response to treatment. Methylation-based classifiers and related machine-learning tools offer additional information when routine pathology or limited sequencing is insufficient. The Sturgeon development is relevant because it focuses on identifying a classification within a meaningful decision window, not merely producing an academic probability score.
Adoption depends on evidence for the specific tumor group and the consequences of an uncertain prediction. Research groups and molecular laboratories will pay for better interpretation where it improves case resolution or stratification. However, classifiers that require costly manual preprocessing or extensive confirmatory work may struggle to demonstrate a net operational benefit.
Curated rare-disease references support specialized services
Many patients with suspected genetic conditions remain unresolved after standard sequence interpretation. DNA methylation signatures can provide an additional functional layer, particularly for disorders that affect transcriptional regulation. EpiSign’s 2026 catalogue expansion increases the range of reference conditions available to participating laboratories.
Commercial demand follows from maintaining that reference environment and supporting laboratories that cannot develop a robust classifier independently. Broader reach also raises expectations for population representation, technical validation and reporting limits. New records are valuable only when the reference labels and analytical process remain reliable.
Pharmaceutical research is linking epigenomics with functional experiments
Drug-discovery programs use epigenetic measurements to identify regulatory vulnerabilities, assess target engagement and understand cellular responses. AI can prioritize experiments across high-dimensional measurements, particularly when DNA methylation is integrated with gene expression or chromatin state. Research groups are interested in approaches that explain why a target matters, not just that two features are correlated.
The commercial opportunity favors specialist partnerships able to move from computation to laboratory evidence. Pharmaceutical budgets can support high-value analytical contracts, but they also carry significant project risk: negative validation can end a program quickly. Suppliers therefore need pricing and service arrangements that separate recognized analysis revenue from speculative therapeutic milestones.
Cloud collaboration is broadening access to specialized interpretation
Few research institutions can independently maintain a comprehensive set of disease-specific methylation models and supporting reference data. Secure platform delivery allows groups to access maintained analysis methods while retaining oversight of sample provenance and result review. EpiSign’s synthetic-reference project addresses the additional challenge of sharing useful statistical information without unrestricted movement of patient-level records.
Cross-border deployment will remain selective, especially where genomic and health-data rules constrain transfer. The strongest commercial offers combine permission controls, transparent output records and local validation support. A cloud-hosted service without those features may be easy to demonstrate but difficult for a clinical or pharmaceutical customer to approve.
Market Restraints
Assay differences and biological variability undermine transferability
Methylation and chromatin patterns change with cell mixture, tissue sampling, age, treatment and experimental conditions. Two laboratories can process biologically similar samples and obtain different feature distributions because their preparation or sequencing protocols differ. A classifier trained on one cohort may consequently fail even when its internal validation appears strong.
Routine use requires external cohorts, batch controls and transparent handling of low-confidence cases. These are resource-intensive tasks for small software suppliers, and they reduce the speed at which a promising published method becomes a validated product. Multi-platform support must be established experimentally rather than inferred from a common model architecture.
Research-use tools face a demanding clinical translation pathway
A software launch does not establish authorization for every possible diagnostic application. EpiSign’s METRIC 5-base was made available for research use while participating laboratories continued local evaluation. Similarly, an intraoperative tumor classifier must be assessed within the conditions and time pressures of its intended surgical workflow before being represented as routine care.
Hospitals evaluate reportability, interpretability, quality systems and professional accountability alongside analytical performance. Vendors must maintain documentation as classifiers and reference sets evolve. The associated evidence burden can slow commercialization even when research institutions are eager to test a new approach.
Sensitive molecular records restrict pooling and model training
Epigenomic data may reveal disease associations, age-related patterns and other personal biological information, especially when linked with genomic variants and clinical history. Cross-institutional models require data permissions, transparent consent and safeguards against unintended re-identification. Simple removal of names does not automatically eliminate these risks.
Federated learning or carefully governed synthetic references can help, but they require additional security and statistical evaluation. Smaller laboratories may lack the resources to prepare datasets for such arrangements. Contracting around training rights, retention and derivative models can therefore delay projects that are technically ready.
AI value is difficult to separate from bundled laboratory purchases
Sequencing systems, reagents, data-processing software and specialized analysis are frequently purchased together. Some methylation calling is integrated into a vendor’s sequencing workflow rather than billed as a distinct service. General cloud analytics and proprietary research agreements add further complexity to software procurement and supplier comparisons.
Independent classifier businesses must demonstrate a benefit that is not already available in the base instrument package. At the same time, the price of a complete sequencing system cannot be attributed to epigenetic AI merely because it includes modified-base calling. This commercial boundary limits the transparency of competitor sales and complicates consistent market measurement.
Reimbursement and research funding do not always support scale
Research grants can fund exploratory analytics without creating a long-term departmental software budget. Clinical laboratories face different constraints: reimbursement may apply to a particular testing service, not to every computational component used during interpretation. Rare-disease volumes are also fragmented across conditions and institutions.
Product vendors consequently need sustainable pricing across low-volume indications, training programs and complex technical support. Broader adoption is most credible where interpretive value reduces unresolved cases, improves laboratory throughput or enables a funded pharmaceutical research decision. Unsupported claims of broad clinical benefit may instead delay institutional purchasing.
Regional Outlook
North America: Established analytical and translational infrastructure
North America accounts for an indicative USD 111.8 million in 2026, approximately 43% of the modeled global market, supported by biotechnology investment, sequencing-platform suppliers and a substantial academic research base. US instrumentation and software businesses operate alongside Canadian research and testing networks. EpiSign’s Canadian program illustrates how specialized classifiers can be distributed through partner laboratories rather than through a single centralized laboratory service.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
The region is modeled to reach USD 299.7 million in 2031, equivalent to annual growth of approximately 21.8%. Its position reflects strong access to clinical research cohorts and established regulatory and genomic-testing infrastructure. Commercial competition should increasingly center on externally validated indications, local laboratory integration and the right to use reference data, rather than headline machine-learning performance.
Asia Pacific: Accelerating sequencing and precision-medicine research
Asia Pacific is indicatively valued at USD 62.4 million in 2026, representing 24% of the global model. China, Japan, South Korea and India have active sequencing and multi-omics research communities, but they differ in funding, patient-data governance and local bioinformatics capacity. Growing availability of methylation-capable sequencing provides an entry point for algorithmic interpretation, especially for institutions already working on cancer or developmental disorders.
The regional model reaches USD 259.2 million in 2031, implying approximately 33.0% annual growth, the fastest among the five geographic areas. Suppliers will require locally relevant reference cohorts, flexible deployment arrangements and robust technical training. Research collaborations are likely to precede large-scale clinical purchases where validation standards, reimbursement and digital laboratory infrastructure are still evolving.
Competitive Landscape
EpiSign and Cyclomics compete on maintained, indication-linked methylation classification, while PacBio, Illumina and Oxford Nanopore influence upstream data quality and workflow integration. Epigenica offers analytical inputs through multiplex epigenomic research assays; QIAGEN and Thermo Fisher Scientific provide instruments, sample preparation and laboratory informatics that enable epigenetic studies. These groups are not economically interchangeable: proprietary classification fees, assay receipts and instrument revenue address different parts of a customer program.
Research-oriented platforms and therapeutic developers also shape the market. DNAstack supports genomics data management and analysis infrastructure, while Moonwalk Biosciences applies epigenomic methods to therapeutic target investigation. Chroma Medicine now forms part of nChroma Bio after the December 2024 merger with Nvelop Therapeutics, and its research pipeline should not be presented as a standalone classifier business. Buyers will increasingly compare vendors on supported assay types, reproducibility, clinically meaningful evidence and continued access to software updates.
Recent Developments
September 2026: EpiSign Inc.
EpiSign launched METRIC 5-base to interpret sequencing-derived methylation data using its existing episignature reference framework. The product supports several sequencing platforms, but this new workflow is available for research use and requires site-level evaluation before clinical adoption.
September 2026: Illumina
Illumina outlined use of Connected Multiomics to combine quality control, methylation-region assessment, pathway interpretation and variant evidence from 5-base sequencing. The development addresses interpretation and provenance rather than the sale of a separately approved diagnostic algorithm.
June 2026: EpiSign Inc.
The company released EpiSign version 6, increasing coverage to more than 310 rare-disease episignature conditions. The expanded reference library may reduce the need for laboratories to maintain individual disease classifiers, subject to validation of supported specimens and conditions.
May 2026: PacBio
PacBio commenced worldwide shipment of SPRQ-Nx chemistry for Revio, including expanded methylation calling and updates to the AI-powered DeepConsensus method. The release improves upstream data generation and analysis capacity, but it does not separately establish AI epigenetics software revenue.
May 2026: Cyclomics and Oncode Institute
Cyclomics obtained exclusive worldwide rights to Sturgeon software, technology and intellectual property for rapid CNS tumor classification. Integration with Epinn advances a defined translation pathway, with broader clinical deployment dependent on validation and local requirements.
March 2026: EpiSign Inc.
EpiSign confirmed its involvement in an Ontario Genomics initiative to create privacy-preserving, synthetic-reference epigenomics infrastructure. The project addresses secure cross-institutional analytical collaboration; participation is not equivalent to a booked commercial software contract.
Market Outlook
Commercial growth in AI epigenetics will depend on how effectively advanced assays can be translated into maintainable biological interpretation. Rare-disease signatures and specific tumor-classification workflows offer relatively visible procurement routes because customers can test results against existing clinical questions. Broader chromatin, histone and RNA applications should generate research software and integration demand, but they may require more bespoke analytical support before they become standardized products.
The most durable supplier advantage is likely to come from access to trusted reference cohorts, documented cross-platform performance and predictable deployment within laboratory systems. As sequencing increasingly produces both genetic and epigenetic information, interpretation software can occupy a greater share of the research workflow. The pace of adoption will nevertheless be shaped by clinical evidence, data-governance rules and budgets that distinguish ongoing analysis value from hardware, assays and therapeutic research.