
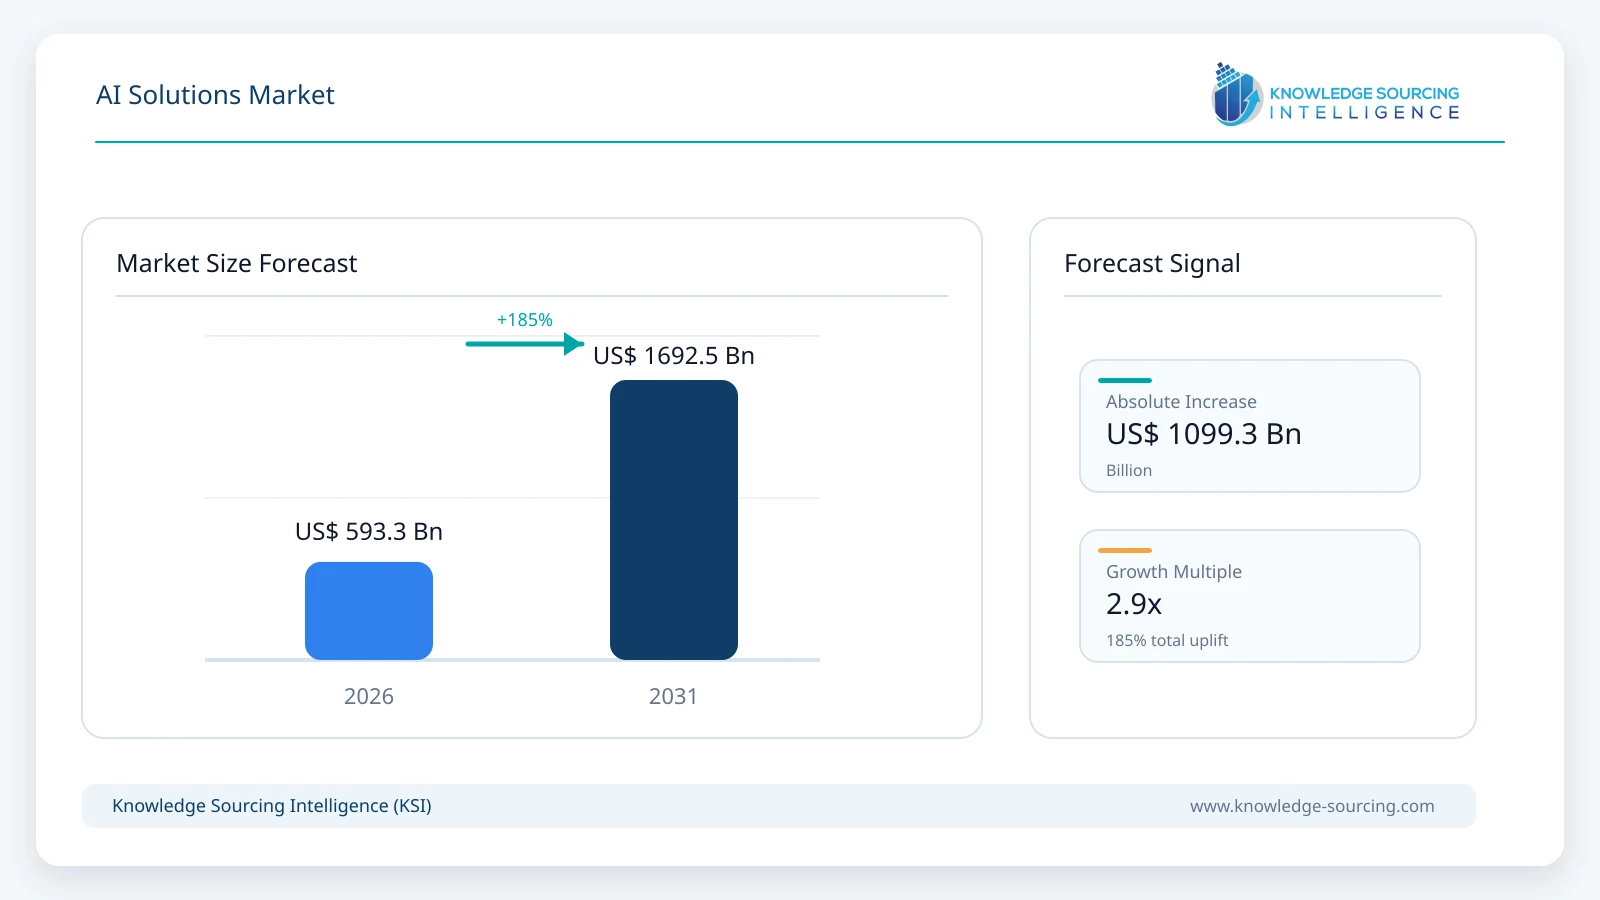
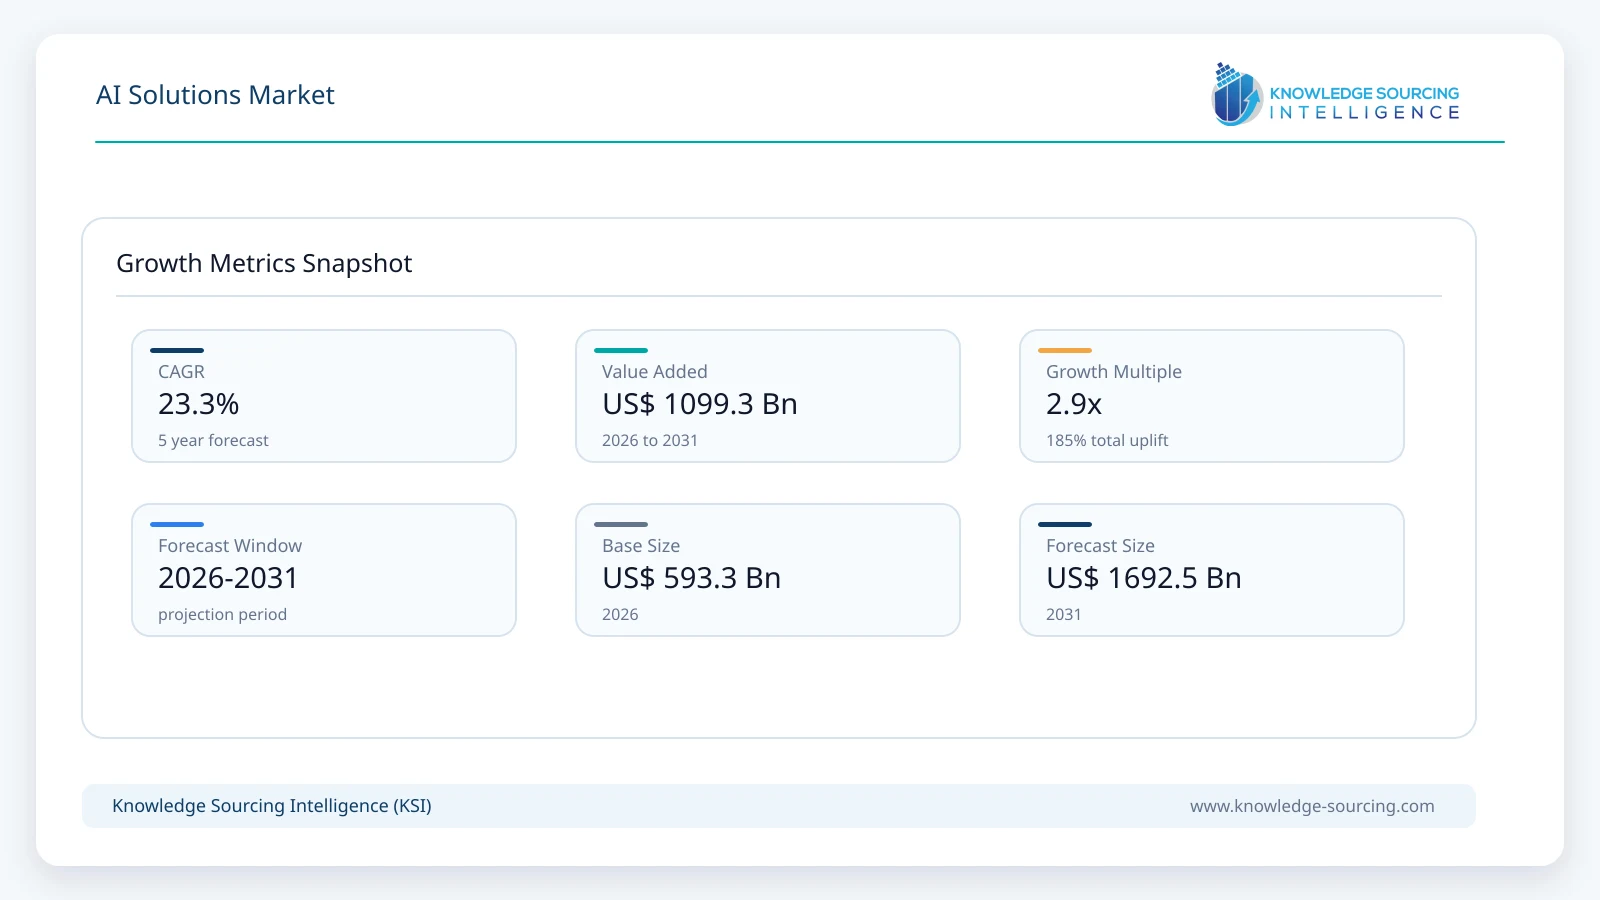
The global AI solutions market is forecast to grow from USD 593.28 billion in 2026 to USD 1,692.55 billion by 2031, representing a CAGR of approximately 23.3% during the forecast period.
Highlights:
- 1Cloud deployment accounts for approximately 78% of global AI solutions market value in 2026, supported by hyperscale computing, managed model access and subscription-based enterprise applications.
- 2AI infrastructure and model services account for approximately 39% of market value in 2026, reflecting high spending on training, inference and managed foundation-model services.
- 3BFSI accounts for approximately 18% of global AI solutions spending in 2026, led by fraud detection, risk analytics, customer service, document processing and software modernization.
- 4North America accounts for approximately 42% of global market value in 2026, supported by large enterprise technology budgets and a dense supplier ecosystem.
- 5The United States accounts for approximately 35% of global market value in 2026, with strong demand across cloud platforms, financial services, technology, healthcare and professional services.
Enterprise AI spending is spreading across both horizontal and industry-specific workloads. Financial institutions are using AI in service operations, fraud detection, document processing and software development; healthcare organizations are deploying it in administrative workflows and clinical support; manufacturers are applying AI to engineering, inspection and maintenance; and technology companies are embedding models throughout software-development and customer-support processes. Large-scale adoption is increasingly tied to existing business systems rather than standalone AI interfaces.
The supplier landscape is also broadening. Microsoft Cloud revenue reached USD 214.4 billion in FY2026, with Azure and other cloud services growing 41% for the year, while Oracle's cloud infrastructure revenue grew sharply as AI training and inference contracts expanded. Salesforce's Agentforce and Data 360 annual recurring revenue reached nearly USD 3.9 billion in Q2 FY2027, and ServiceNow AI crossed USD 1 billion in annual contract value during Q2 2026. OpenAI reports more than two million business customers globally, indicating that enterprise AI adoption is extending well beyond the first group of technology-led adopters.
Market Trends
Agentic AI Moves Into Production
Enterprise deployments are moving toward agents that can complete multi-step work across business applications, internal data and external tools. Google has reorganized its enterprise offering around the Gemini Enterprise Agent Platform, AWS has expanded AgentCore and Bedrock around managed agents, and OpenAI launched Presence for production voice and chat agents. Salesforce and ServiceNow are also adding agent-management layers across their software portfolios. Commercial value is shifting toward orchestration, tool access, identity, memory, monitoring and policy controls that allow agents to operate across existing enterprise systems.
Governance Becomes Part of the Core Platform
As AI gains permission to act across business systems, enterprises need stronger controls over identity, data access, cost, model choice and agent behavior. Salesforce introduced its Enterprise AI Harness and AI Control Plane in September 2026, while ServiceNow has positioned AI Control Tower as a governance layer across enterprise AI deployments. Google and AWS are also adding agent registries, identity controls and observability into their platforms. Governance is becoming a purchasing requirement rather than a separate compliance project, particularly in financial services, healthcare, government and other regulated industries.
Model Choice Expands
Enterprises are increasingly adopting platforms that support several frontier and specialized models rather than committing all workloads to a single provider. AWS added OpenAI models and Codex to Amazon Bedrock in 2026, while Anthropic makes Claude available through multiple major cloud environments. Application vendors are also exposing several model options behind common enterprise controls. This shifts differentiation toward orchestration, data integration, security and workflow performance, while model providers compete on capability, price, latency and specialization.
Usage Economics Gain Importance
AI consumption is becoming a larger operating expense as enterprises deploy agents continuously across customer service, software development, research and internal operations. Buyers are paying more attention to token consumption, model routing, inference cost and the number of agent actions required to complete a workflow. Vendors are responding with spend controls, usage analytics, smaller models and more flexible pricing structures. Cost management will have greater influence on platform selection as AI moves from centrally funded experimentation into departmental budgets.
Market Drivers
Productivity Gains Support Larger Enterprise Deployments
Large organizations are expanding AI where it can reduce processing time or increase employee throughput. BBVA has deployed ChatGPT Enterprise at large scale, while OpenAI reports substantial adoption across major financial, technology and industrial companies. Coding assistants are also moving into standard engineering workflows, where time savings can be measured through software delivery, incident resolution and development throughput. These use cases give buyers clearer economic justification than general-purpose experimentation and are helping AI budgets move into recurring operating expenditure.
Cloud Providers Are Expanding AI Capacity
Microsoft, AWS, Google Cloud and Oracle continue to add infrastructure for model training and inference as enterprise consumption rises. Microsoft added 31 data centers in its latest reported quarter and said Azure demand continued to exceed available capacity, while Oracle reported more than USD 30 billion of additional AI cloud contracts in Q1 FY2027. Greater infrastructure availability allows enterprises to scale AI without owning dedicated hardware and gives software vendors a distribution layer for advanced models, managed agents and enterprise data services.
Enterprise Applications Are Becoming AI-Native
AI is being embedded directly into established business software, reducing the need for customers to build separate interfaces and integrations. Salesforce Agentforce, ServiceNow AI, Microsoft 365 Copilot, SAP Joule and Oracle's AI-enabled applications bring model capabilities into CRM, IT service management, productivity, ERP and industry workflows. This distribution advantage is commercially important because enterprise software already contains user permissions, business processes and operational data, allowing AI functionality to be introduced within systems employees use every day.
Implementation Services Expand Alongside Software
Moving AI into production requires process redesign, data integration, evaluation, governance and user adoption. Anthropic launched a USD 100 million partner programme in 2026 and subsequently expanded its services track, while global consulting firms continue to build AI practices around multiple cloud and model ecosystems. The services opportunity is strongest where customers need to connect models to legacy systems, establish controls and redesign workflows rather than simply purchase model access.
Market Restraints and Challenges
Compute Costs Pressure Deployment Economics
High-volume inference and long-running agent workloads can generate substantial recurring costs, particularly where enterprises rely on frontier models for every task. Buyers are responding with model routing, smaller models, caching and tighter usage controls, while vendors are optimizing infrastructure to reduce cost per inference. Pricing pressure is likely to intensify as customers compare the operating economics of competing model and cloud combinations.
Security and Data Requirements Slow Production Rollouts
Enterprise AI often requires access to customer, financial, healthcare or operational information, making identity, permissions, data residency and auditability central to deployment decisions. Regulated organizations frequently need additional controls before moving from pilot to production, particularly where agents can take actions rather than simply provide recommendations. Vendors with strong governance, private connectivity and enterprise security controls are better positioned in these environments.
Legacy Integration Adds Cost
Large organizations operate across ERP systems, databases, custom applications and workflows built over many years. AI agents cannot deliver broad operational value without secure access to these systems and consistent enterprise data. APIs, connectors, data fabrics and Model Context Protocol support are improving interoperability, but integration remains a significant part of project cost and continues to support demand for consulting and managed AI services.
AI Solutions Market Segment Analysis
By Deployment
Cloud
Cloud-based AI solutions are expected to generate approximately USD 1.42 trillion by 2031, retaining the dominant deployment position. Hyperscale platforms give enterprises access to frontier models, accelerated computing, data services, orchestration and monitoring without building dedicated infrastructure, while subscription-based AI applications are also delivered primarily through cloud environments. Private and on-premise deployments remain important where data residency, latency or regulatory requirements justify dedicated infrastructure, but most enterprises are adopting hybrid architectures rather than replacing cloud services entirely.
By Solution Type
AI Infrastructure and Model Services
AI infrastructure and model services are forecast to generate approximately USD 575 billion by 2031. Growth is being driven by rising inference volumes, model training, fine-tuning and agent workloads that run for longer periods and interact with multiple systems. Microsoft, AWS, Google Cloud and Oracle are expanding capacity, while model providers increasingly distribute through more than one cloud environment. Falling cost per unit of compute should gradually moderate infrastructure growth, but the absolute volume of AI consumption is expected to increase substantially.
By Industry Vertical
BFSI
BFSI is expected to account for approximately USD 280 billion of AI solutions spending by 2031. Banks, insurers and capital-markets firms are deploying AI across customer service, fraud detection, anti-money-laundering review, risk analytics, document processing and software engineering. The sector's large employee base and information-intensive workflows create multiple opportunities for measurable automation, while stringent governance requirements raise demand for secure deployment, monitoring and human oversight. Large financial institutions are now moving beyond narrow experiments and deploying enterprise AI across tens of thousands of employees.
Major Region
North America
North America is forecast to generate approximately USD 660 billion in AI solutions revenue by 2031. The region combines large enterprise technology budgets with most of the world's leading cloud providers, frontier-model companies and enterprise software vendors.
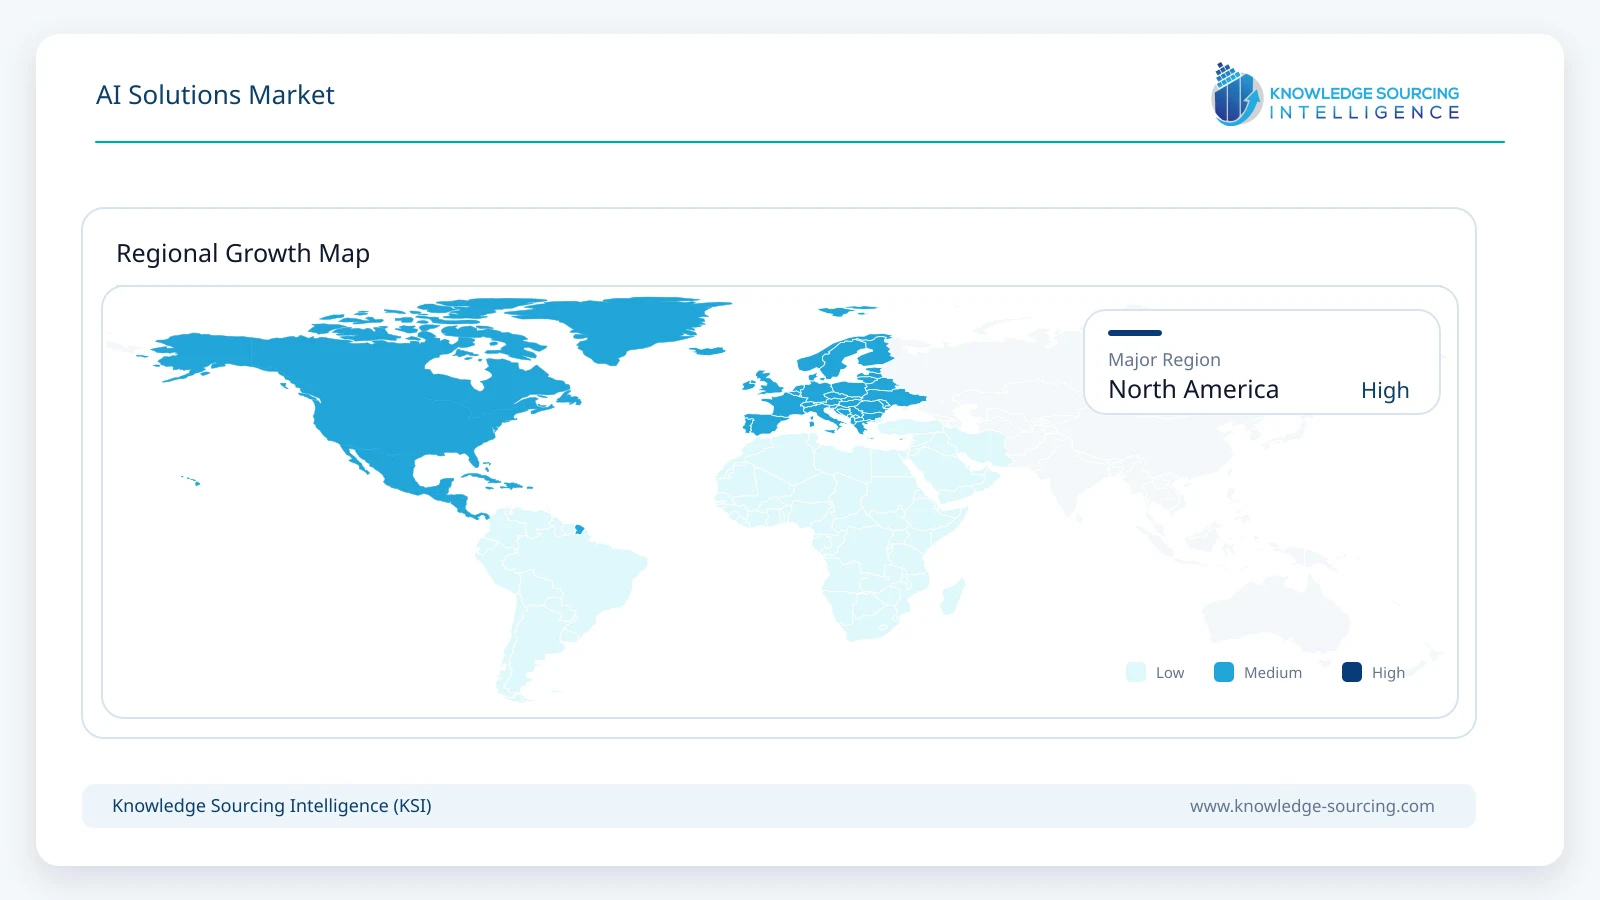
Microsoft, AWS, Google, OpenAI, Anthropic, Salesforce, ServiceNow, Oracle, IBM and NVIDIA have substantial commercial operations in the region, supported by a broad consulting and systems-integration ecosystem. North America's global share is expected to decline modestly as Asia Pacific and the Middle East expand faster from smaller bases, even as absolute regional spending continues to rise.
Major Country
United States
The United States is expected to account for approximately USD 525 billion in AI solutions spending by 2031, led by cloud services, financial services, technology, healthcare, retail, professional services and industrial adoption. The country's supplier base captures revenue both domestically and internationally, while major enterprises are among the earliest adopters of agentic workflows and coding automation. OpenAI now reports more than two million business customers globally, and US-headquartered software companies such as Salesforce and ServiceNow are generating material recurring revenue from enterprise AI products.
Competitive Environment and Analysis
The AI solutions market spans infrastructure, models, development platforms, business applications and implementation services, creating competition across several layers rather than one consolidated product category. Microsoft, AWS, Google and Oracle combine cloud infrastructure with development platforms and enterprise services, while OpenAI and Anthropic compete more directly in frontier models, APIs and enterprise AI products. NVIDIA participates through enterprise AI software and optimized infrastructure services, while Salesforce, ServiceNow, SAP, IBM and Palantir compete through workflow, application and data integration.
Distribution is becoming as important as model capability. Enterprise software vendors can place AI directly inside established workflows, cloud providers can bundle model usage into existing infrastructure commitments, and model companies are expanding partnerships with systems integrators and hyperscalers. AWS added OpenAI models and Codex to Bedrock in 2026, while Anthropic expanded its partner network after more than 40,000 firms applied to participate. These arrangements allow customers to buy model access through existing security, billing and procurement environments.
The competitive set has also changed through consolidation. Siemens completed its acquisition of Altair Engineering in March 2025, adding simulation, data science and AI capabilities to Siemens Xcelerator, so Altair is no longer treated as an independent participant. Newer enterprise-AI suppliers such as OpenAI and Anthropic now warrant direct inclusion alongside established software companies because their products are increasingly deployed as enterprise platforms rather than only as underlying models.
Recent Developments
September 2026: Salesforce introduced its Enterprise AI Harness and AI Control Plane to manage context, governance, identity, performance and cost across enterprise agents.
September 2026: Oracle reported more than USD 30 billion of additional AI cloud contracts booked during Q1 FY2027 as training and inference demand continued to exceed available capacity.
July 2026: OpenAI launched Presence, a managed enterprise platform for deploying and improving governed voice and chat agents in production workflows.
April 2026: Google expanded Gemini Enterprise into an end-to-end platform for agent development, orchestration, governance and long-running enterprise workflows.
April 2026: AWS added OpenAI frontier models, Codex and Managed Agents to Amazon Bedrock, expanding model and agent choice within existing AWS enterprise controls.
Market Outlook
AI spending through 2031 will shift progressively from initial infrastructure build-out toward recurring model consumption, agent execution and embedded enterprise applications. Infrastructure will remain a large revenue pool because inference volumes are increasing quickly, but workflow-level software and orchestration should capture a greater share of incremental spending as organizations deploy AI deeper into daily operations.
Agent platforms are likely to become a standard layer across enterprise software stacks, connecting models with business data, identity, permissions and applications. This will increase demand for governance, observability and cost-management tools around AI rather than only for the models themselves. Enterprise buyers will place greater emphasis on completed work, reliability and measurable business outcomes as the number of available models expands.
Competition should remain fluid as model providers move further into applications and established software companies build more of their own AI functionality. Partnerships between hyperscalers, frontier-model vendors and business-software companies will continue because customers want model choice without rebuilding security and integration around every provider.
AI Solutions Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 593.28 billion |
| Total Market Size in 2031 | USD 1,692.55 billion |
| Forecast Unit | Billion |
| Growth Rate | 23.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Deployment, Solution Type, Industry Vertical, Geography |
| Companies |
|
Market Segmentation
By Deployment
Cloud
On-Premise and Private AI
By Solution Type
AI Infrastructure and Model Services
AI Platforms and Development Tools
Enterprise AI Applications
Implementation and Managed AI Services
By Industry Vertical
BFSI
Healthcare and Life Sciences
Retail and E-commerce
Manufacturing
IT and Telecommunications
Automotive and Transportation
Government and Public Sector
Energy and Utilities
Media and Professional Services
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
United Arab Emirates
Saudi Arabia
South Africa
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Singapore
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.4.1. Bargaining Power of Suppliers
4.4.2. Bargaining Power of Buyers
4.4.3. Threat of New Entrants
4.4.4. Threat of Substitutes
4.4.5. Competitive Rivalry in the Industry
4.5. Industry Value Chain Analysis
4.6. Regulatory and AI Governance Landscape
4.7. Analyst View
5. AI SOLUTIONS MARKET BY DEPLOYMENT
5.1. Introduction
5.2. Cloud
5.3. On-Premise and Private AI
6. AI SOLUTIONS MARKET BY SOLUTION TYPE
6.1. Introduction
6.2. AI Infrastructure and Model Services
6.3. AI Platforms and Development Tools
6.4. Enterprise AI Applications
6.5. Implementation and Managed AI Services
7. AI SOLUTIONS MARKET BY INDUSTRY VERTICAL
7.1. Introduction
7.2. BFSI
7.3. Healthcare and Life Sciences
7.4. Retail and E-commerce
7.5. Manufacturing
7.6. IT and Telecommunications
7.7. Automotive and Transportation
7.8. Government and Public Sector
7.9. Energy and Utilities
7.10. Media and Professional Services
7.11. Others
8. AI SOLUTIONS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. United Arab Emirates
8.5.2. Saudi Arabia
8.5.3. South Africa
8.5.4. Israel
8.5.5. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Australia
8.6.6. Singapore
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Microsoft Corporation
10.2. Alphabet Inc. / Google Cloud
10.3. Amazon Web Services, Inc.
10.4. OpenAI
10.5. Anthropic PBC
10.6. NVIDIA Corporation
10.7. IBM Corporation
10.8. Oracle Corporation
10.9. Salesforce, Inc.
10.10. ServiceNow, Inc.
10.11. SAP SE
10.12. Accenture plc
10.13. Palantir Technologies Inc.
10.14. C3.ai, Inc.
10.15. SAS Institute Inc.
10.16. Siemens AG
10.17. Databricks, Inc.
10.18. Adobe Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Research Methodology
11.5. Abbreviations
Navigate
Trusted by the world's leading organizations











