
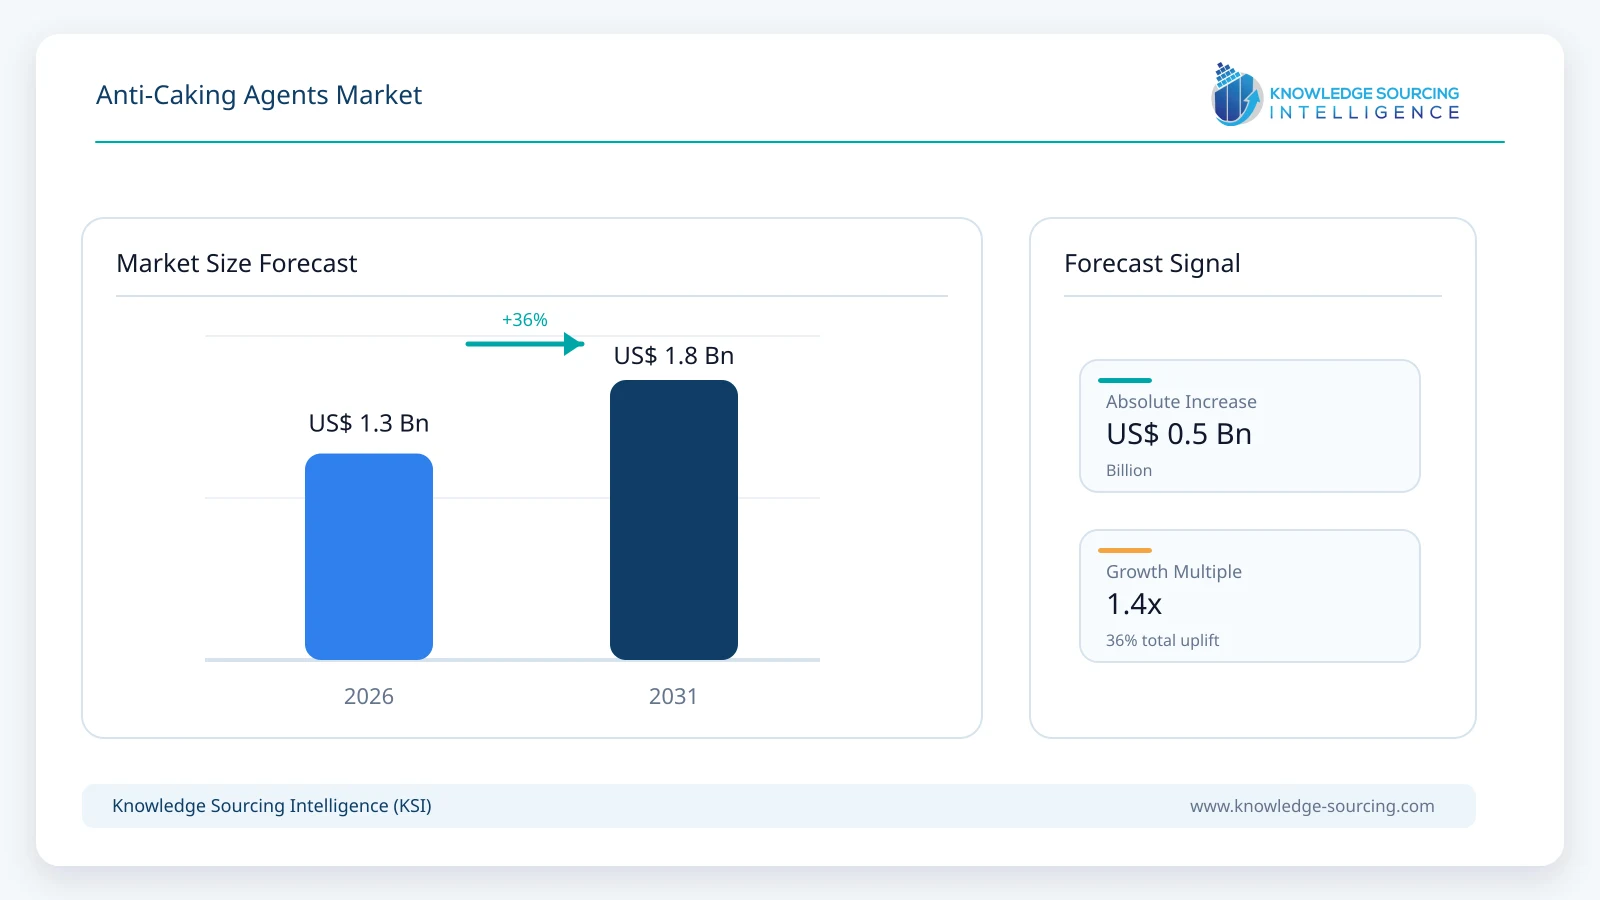
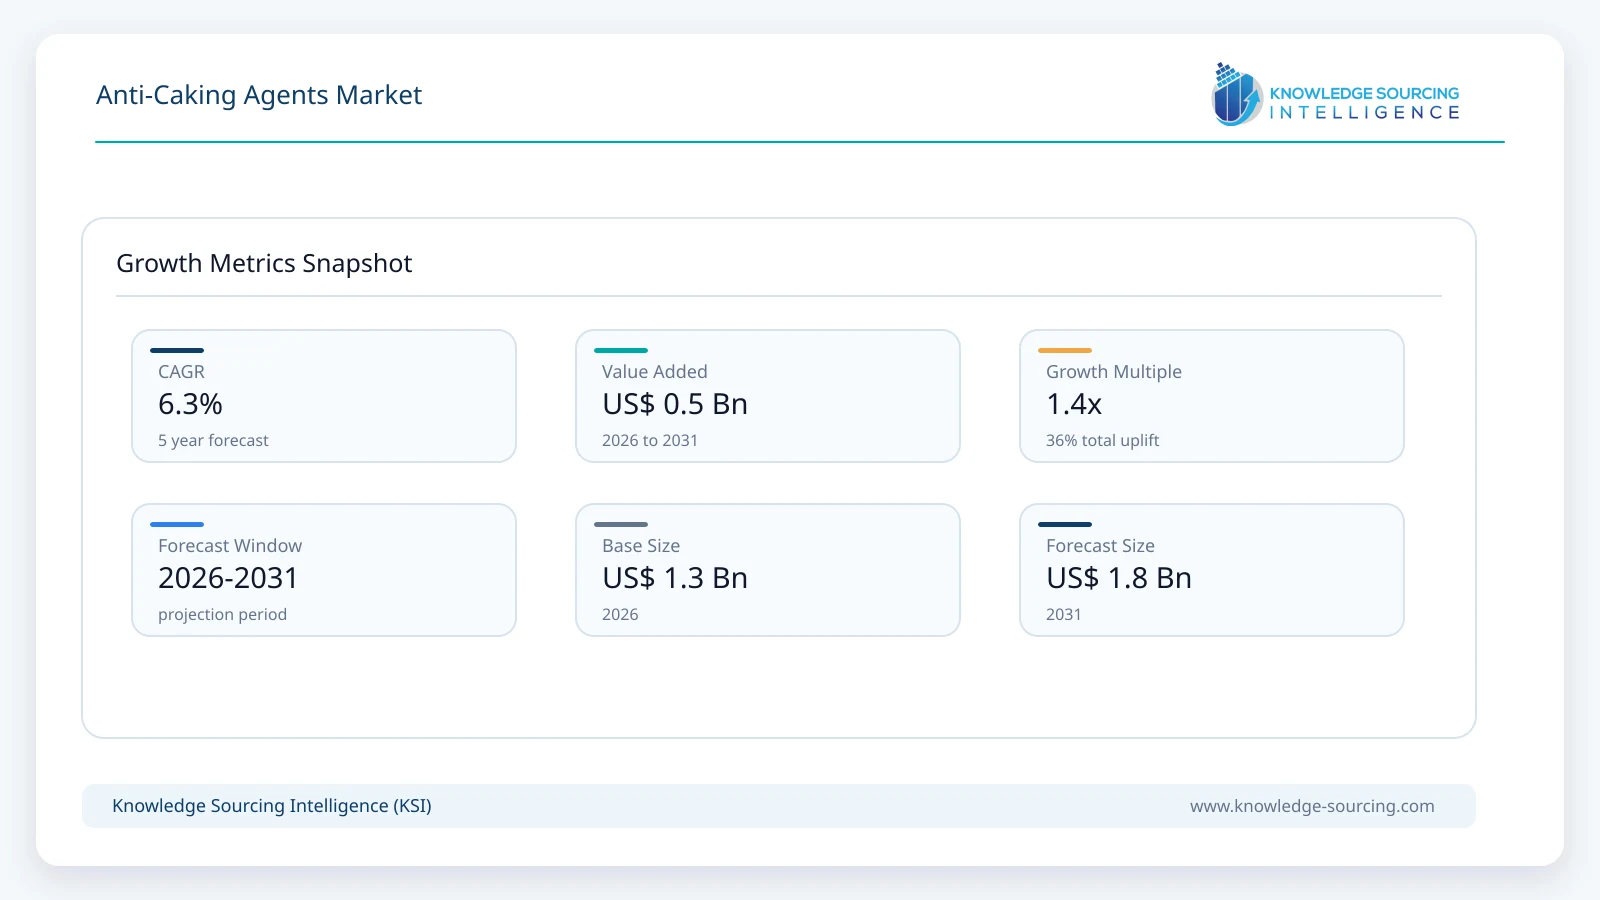
The global Anti-Caking Agents Market is projected to expand at a CAGR of 6.3%, increasing from USD 1.32 billion in 2026 to USD 1.79 billion by 2031.
Highlights:
- 1Calcium-based additives support moisture control in widely distributed powdered foods and nutritional blends.
- 2Food processors increasingly assess caking under actual humidity, shipping pressure and storage conditions.
- 3Fine silica grades retain importance where liquid uptake and stable powder flow are critical.
- 4Asia Pacific offers substantial growth through packaged foods, nutrition, feed and industrial powders.
- 5Supplier differentiation depends on approved grades, controlled dusting and credible application testing.
Anti-caking agents are functional additives used to maintain particle separation and powder flow during processing, transport, and storage. Common chemistry includes calcium silicates and phosphates, sodium compounds, magnesium compounds and engineered silica, alongside certain mineral and starch-based alternatives. The mechanism depends on the material: porous particles absorb or redistribute moisture, while fine coatings and spacers reduce adhesive contact between the particles that form a bulk powder. For industrial buyers, the relevant specifications include flow under consolidation, caking resistance, regulatory acceptability, and performance at a practical dose.
Food and beverage is the principal purchasing environment, but even this market is not homogeneous. Seasoning blends are exposed to kitchen and tropical humidity; infant and dairy powders face strict ingredient and microbiological requirements; beverage premixes may contain hygroscopic acids or sweeteners; and salt presents a distinctive crystallization problem. Feed, cosmetics and personal-care powders introduce further differences in particle geometry, handling conditions and approved chemistry. A carrier that works with a vitamin premix may be unsuitable for a consumer product whose sensory or labeling requirements are more restrictive.
Commercial sales are made by mineral processors and specialty chemical producers through direct industrial accounts, ingredient distributors and formulation partners. Competitive advantage arises from reproducible particle properties, application-specific technical data and delivery reliability across countries. Growing use of high-performance powder lines increases opportunities for engineered grades, although procurement teams continue to evaluate the lowest effective inclusion level, product losses, and compliance rather than the additive price alone.
Market Overview
A powder can be free-flowing when packed and still become difficult to dispense after several weeks. Moisture moves through packaging, changes surface energy, and can create liquid bridges between particles. Temperature fluctuations and mechanical compression during transport intensify these effects. The manufacturer consequently faces more than an appearance defect: line stoppages, inconsistent dosing, rejected cartons, incomplete dissolution, and cleaning losses can all raise the cost of a product that otherwise meets its chemical specification.
Omya has commercialized porous mineral grades including Omyafood 120 and Omyanutra 300, connecting reduced caking with low-dusting handling and reproducible powder tests. Its disclosed approach simulates stress from humidity, temperature, and mechanical loading, allowing formulators to screen materials against conditions resembling distribution. In silica, Evonik’s SIPERNAT and AEROSIL products perform as carriers and free-flow aids for selected food, feed and technical applications; Qemetica’s FLO-GARD precipitated silica is marketed for food and feed flow conditioning. These are not direct substitutes at a universal addition rate: oil content, bulk density, particle size, intended consumer and permitted use determine the optimum choice.
Equipment and packaging are part of the solution. Dehumidified production rooms and better moisture barriers may be necessary when a formulation is highly hygroscopic, while stronger filler controls can prevent compaction before palletizing. Buyers increasingly want test results after aging and transport simulation rather than a short funnel-flow demonstration. Because agents are used in relatively small amounts, a successful formulation can sustain technical-margin products, but claims of greater shelf life must be demonstrated for each powder matrix.
Market Trends
Mineral grades are being evaluated as alternatives to conventional silica
Food and nutraceutical formulators are paying closer attention to the combined effect of flowability, dust, consumer perception and micronutrient contribution. Omyafood 120 is positioned as a porous, low-dusting mineral solution for dry blends; Calcipur and Omyanutra cover additional calcium-based functions. This has opened a formulation pathway where the customer seeks moisture management without relying exclusively on a synthetic, high-surface-area silica grade.
Performance still needs a matrix-specific trial. Omya reports reductions in caking in tested bread and spice mixes, but the magnitude depends on test conditions and cannot be transferred mechanically to salt or dairy powders. Calcium-based products also contribute mineral content, which affects nutritional declarations and can matter for sensory properties. Suppliers selling to multinational food groups therefore need consistent technical dossiers, not a single promotional claim.
Shelf-life testing is becoming more predictive and commercially relevant
Rather than judge an ingredient only by the angle of repose immediately after blending, manufacturers are exposing candidate formulations to humidity cycling and pressure to understand degradation during warehousing. Omya described rheometer-based testing in April 2026, connecting flow deterioration with the environmental history of a powder. This approach is especially useful for e-commerce, export shipments, and premixes stored in humid markets.
Adoption changes how additives are specified. A grade that is slightly more expensive per kilogram can reduce line cleaning, consumer complaints, or discarded product if the improvement is maintained at the end of shelf life. Formulators nevertheless have to establish whether the change arises from the additive, a modified package, or the total moisture balance; laboratory acceleration is a decision aid rather than a substitute for a real-time stability program.
High-absorption silicas are supporting complex powdered ingredients
Liquid flavors, fats, oleoresins and oils are increasingly introduced into dry formulations, creating a flow challenge that is different from ordinary moisture absorption. Evonik positions porous SIPERNAT precipitated silica as a carrier that can convert selected liquid ingredients into more manageable powders, while its AEROSIL grades can reduce particle-to-particle stickiness. Qemetica’s FLO-GARD family addresses related flow-conditioning and carrier requirements for feed and food manufacturing.
The opportunity is greatest where liquid loading can be increased without oily agglomerates or erratic feeding. The economic calculation includes carrier demand, active concentration, total bulk density, and the performance of a finished beverage or seasoning. An additive that improves bulk flow may alter dispersibility or mouthfeel, so specifications increasingly cover multiple stages of processing rather than only the blending hopper.
Manufacturing footprints are being reconfigured around competitive silica supply
Evonik announced in September 2026 a shift in German precipitated silica output toward a proposed Marl facility, following its earlier North American asset-network changes. Such decisions affect a broad silica portfolio rather than anti-caking products alone, but they underscore the importance of efficient production and reliable transfer of approved grades. Manufacturers supplying multinational food or feed companies must manage alternate sites and product equivalency carefully.
Technical specifications may remain nominally unchanged while process-scale changes influence particle distribution or bulk behavior. Purchasing teams are likely to request continuity studies, comparative certificates, and contingency inventory during transfers. New producers face a demanding qualification process even if their chemical identity is identical to an established material.
Regulatory fitness and lower-dust handling are gaining procurement weight
Mineral and silica additives sit under food additive rules that vary by substance, product category and market. The European Union uses a positive-list system and requires safety justification and approved conditions of use. For multinational products, a supplier must reconcile a grade’s declared function, particle properties, purity, and local documentation with the actual finished-food application.
Dust containment also influences the total cost of handling fine particles. A free-flow aid that is effective at a low dose but creates difficult charging or cleanup conditions may require enclosed feeders and ventilation. Alternatives with more favorable handling can win individual applications even if a conventional silica provides stronger adsorption in laboratory screening.
Segment Analysis
By Type: Calcium Compounds
Calcium compounds are estimated to represent about 36% of 2026 market value, making them the largest single class within this classification. Calcium silicate, calcium phosphate, and specially engineered calcium carbonate-based aids have commercially distinct properties, but all can help maintain free-flow behavior where the powder and local regulations permit their use. Demand is broad across bakery and dairy powders, nutritional products and mixes exposed to moisture during transport.
Omya’s mineral powders illustrate how the segment is moving toward application-specific particle architecture rather than indiscriminate use of common calcium salts. For a beverage powder, dissolution and flavor delivery may limit the permitted inclusion; in a dry food premix, mineral contribution and process handling may matter more. Relative growth can be restrained as engineered silicas and specialized carrier materials gain share in more complex powdered formulations. Buyers will continue to compare performance at equal effective dose, not simply the nominal chemistry family.
By Application: Food and Beverage
Milk and whey powders, baking premixes, instant soups, spices, drink powders and seasoning products create a wide market for additives that preserve packing consistency and consumer convenience. Producers operate at volumes where a brief stoppage in pneumatic conveying or a rise in rejected packs can materially affect profitability. Their requirements vary significantly: dairy plants prioritize hygienic handling, seasoning companies manage oily flavors, and powdered beverages must remain dispersible after storage.
Food and beverage applications are projected to account for approximately USD 1.254 billion by 2031. Growth reflects industrial processing of powdered ingredients as well as higher product variety in retail and food service. The opportunity is not a uniform increase in dosing; reformulation teams often seek to keep use rates low, reduce additive declarations or replace an existing grade with one that performs more reliably under humidity stress. Suppliers with appropriate food-grade documentation and pilot-processing support are better placed to capture these conversions.
Market Drivers
Greater use of shelf-stable convenience foods
Ready-to-prepare soups, spice mixes, instant drinks and bakery blends require a predictable shelf life under varied retail conditions. Agglomeration can prevent consistent dispensing, produce unattractive lumps or interrupt high-speed filling. Anti-caking chemistry is selected to reduce these losses as manufacturers broaden ranges and pursue distant export markets.
The commercial driver is strongest where ingredient failure has a measurable consequence, such as out-of-spec fill weights or consumer complaints. Suppliers able to validate performance after storage and shipment can defend their role even when food producers seek fewer additives overall.
Higher throughput in automated powder lines
Dosing systems, screw feeders and pneumatic handling lines are designed around a defined range of powder flow properties. Small changes in moisture or particle cohesion can interrupt output, requiring intervention and cleaning. Conditioned powders can reduce those disruptions when the root cause is particle adhesion rather than defective equipment.
For industrial buyers, the return is measured in line availability and stable batch composition. Ingredient manufacturers offering both formulation trials and process support can compete against lower-priced commodity additives.
Expansion of functional nutrition and premix formulations
Protein, vitamin, mineral, and powdered supplement products can contain hygroscopic or oily components that are difficult to blend homogeneously. Engineered carriers and mineral flow aids help formulators maintain a suitable powder texture through manufacturing and use.
Development teams must balance flow with dose density, consumer taste, and permitted additive declarations. New recipes therefore create technical screening work and potential demand for specialized grades rather than simply higher consumption of one conventional agent.
Commercialization of low-dusting mineral and silica variants
Fine additives can be difficult to meter cleanly and may raise workplace dust-control costs. Mineral producers are developing or positioning grades that address both caking and handling. Omyafood is a direct example; high-absorption precipitated silica families provide a different solution where liquid carrying capacity dominates.
Greater choice supports application-led substitution. Buyers can select a grade appropriate to packaging, hygiene and process conditions, potentially opening higher-value uses where older powder aids created too much dust or compromised final-product appearance.
Broader industrial and agricultural powder use
Feed premixes, dry agricultural products and personal-care powders experience many of the same distribution stresses as foods. Moisture-sensitive components, long transit routes and inconsistent warehouse climates create demand for controlled particulate flow beyond the consumer-food category.
Selling successfully into these markets requires grade-specific assessment: feed regulations, cosmetic performance and agrochemical compatibility are not interchangeable. Suppliers with several qualified product lines can reduce reliance on a single food-processing channel.
Market Restraints
Approval conditions narrow the addressable formulation range
Permitted anti-caking substances and maximum levels vary by jurisdiction and food category. An additive accepted in one dry premix cannot automatically be used in every dairy or infant product, while a cosmetic or feed formulation operates under a different regulatory regime. Requalification can require significant documentation and finished-product testing.
This protects established approved suppliers but slows product substitution and entry into new regions. Smaller innovators may struggle to justify the cost of simultaneous food-grade approvals and technical validation.
Clean-label policies can displace conventional additives
Food brands increasingly examine whether ingredient lists align with product positioning. Some prefer to reduce silicon-based names or substitute a functional mineral ingredient; others first invest in better moisture-barrier packaging or process humidity control. Consumer perceptions do not always match technical or regulatory assessments.
Anti-caking suppliers cannot rely on a claim that the additive is essential. They must demonstrate why a specific concentration is needed and whether a lower dose or a different particle structure offers equivalent protection.
Powder chemistry limits universal performance
Fatty or sticky seasoning powders behave differently from crystalline salt, cocoa, high-protein dairy mixtures and acidic beverage premixes. Particle morphology, electrostatic charging and moisture sorption determine whether a silica, calcium or magnesium grade improves flow. A wrong additive may even worsen dusting or dissolve poorly.
That diversity increases laboratory expense and slows standardization across multinational portfolios. Vendors with extensive technical data can use it as a competitive advantage, but customer qualification remains costly.
Upstream energy and mineral costs pressure pricing
Precipitated and fumed silica manufacturing depends on energy, industrial inputs and tightly controlled processes. Calcium and magnesium mineral grades also incur mining, processing and freight costs. Changes in these costs affect the economics of high-purity and specialty grades more than customers may anticipate from their low dosing level.
Even when the additive represents a small fraction of the finished-food bill, large buyers negotiate rigorously and may qualify substitutes in response to sustained price increases. Supplier plant consolidation can improve cost positions but introduce transition risks.
Dust exposure and handling requirements increase integration effort
Fine powders can become airborne during bag unloading, weighing and dosing. Facilities may require enclosed equipment, appropriate housekeeping and operator protection even when the additive is permitted in the finished product. These measures are particularly material for high-frequency batch manufacturing.
Lower-dusting products can mitigate the problem but may have different bulk densities or feeding behavior. Customers must validate the entire process, and some plants may favor packaging improvements or changes to the base powder instead of another additive.
Regional Outlook
North America: Established Formulation and Ingredient Supply
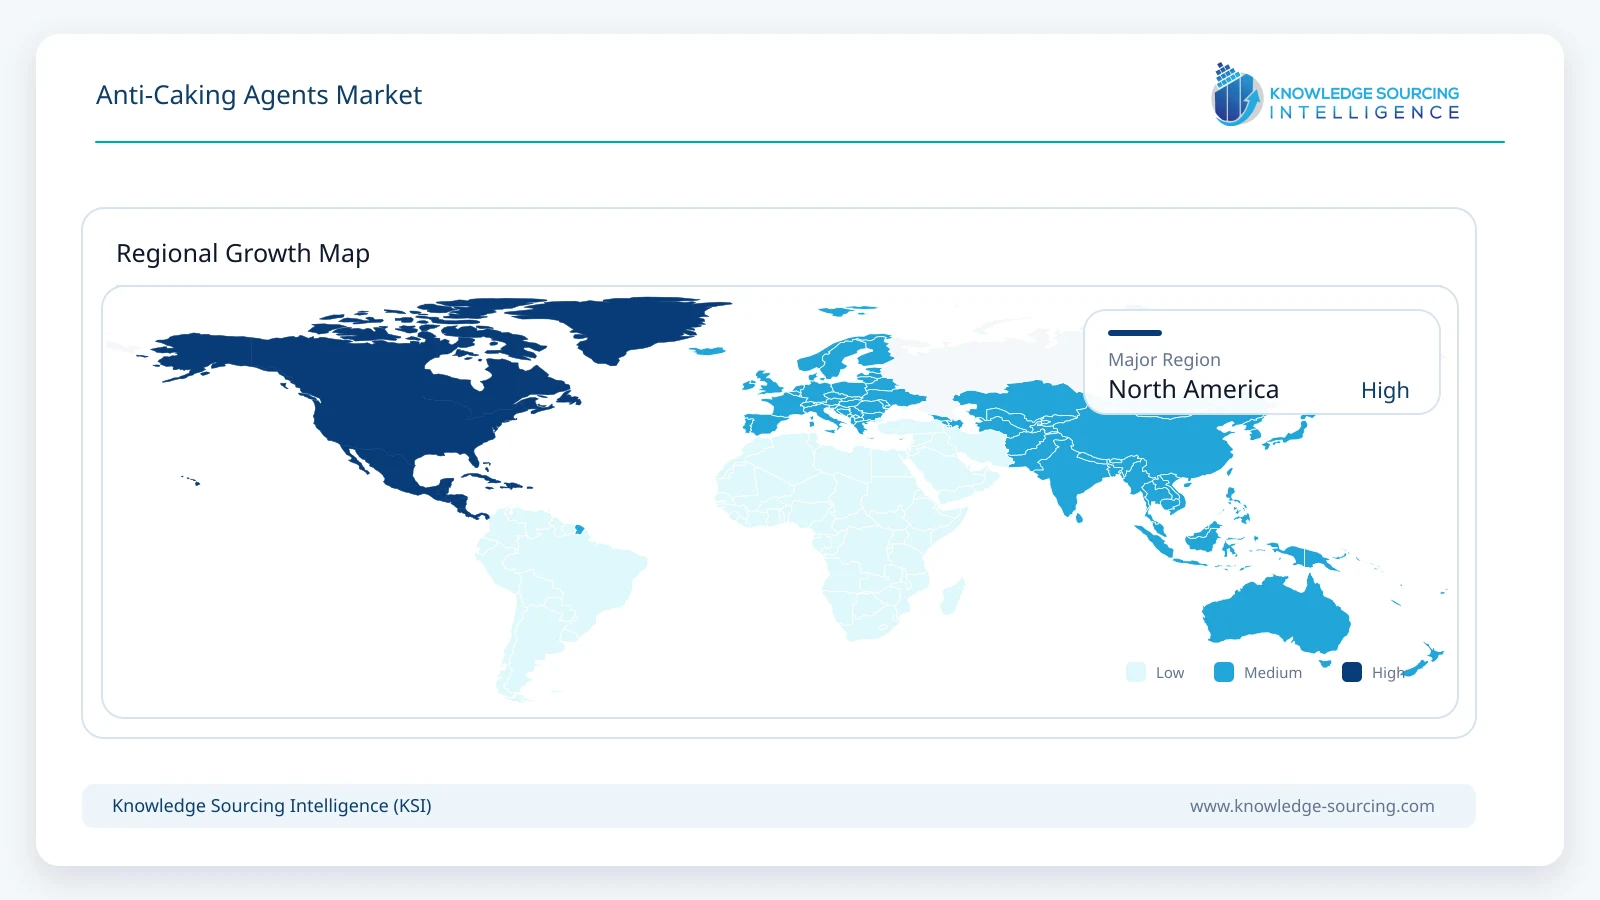
North America combines large-scale food and beverage manufacturing, specialty feed blending and a substantial installed base of powdered-product handling equipment. United States suppliers such as Qemetica Silica and Grace sell application-specific precipitated silica and pharmaceutical or nutrition processing aids, while food groups and private-label manufacturers maintain established ingredient-qualification processes. Demand is shaped by dry seasoning, bakery, dairy, and nutritional-premix operations in which small changes in flow have an immediate impact on production yield.
The region is estimated to represent approximately 33% of global market value in 2026. Mature consumption limits the scope for rapid volume expansion relative to developing Asian markets, but formulation upgrades can favor higher-performance grades and technical services. Evonik’s North American silica capacity realignment also highlights the importance of continuity planning for customers dependent on approved sources. Mexico and Canada contribute different food-processing and distribution requirements; treating them as equivalent to the United States would obscure local regulatory and manufacturing conditions.
Asia Pacific: Accelerating Consumption across Multiple Powder Markets
Asia Pacific is expected to grow at an estimated 10.1% CAGR between 2026 and 2031, supported by its expanding packaged-food, nutrition, feed and specialty-chemical production. The purchasing base is varied: China combines industrial-scale food and feed processing with chemical-material capacity, Japan and South Korea demand well-controlled ingredient specifications, and India and Southeast Asia offer volume growth in food manufacturing and modern retail distribution. Export-oriented producers also face longer storage and more variable humidity exposure.
The region is becoming more attractive for both established engineered-silica suppliers and local mineral companies able to offer technically reliable alternatives. However, country-level approval regimes, product-price sensitivity and differences in technical support can constrain the adoption of higher-value grades. Companies that document powder performance under tropical transport conditions and establish reliable local distribution may gain more durable customer relationships than those competing primarily on spot mineral prices.
Competitive Landscape
The competitive field is divided between specialty silica manufacturers, mineral processors and ingredient or excipient companies. Evonik competes through SIPERNAT, AEROSIL and ZEOFREE applications; Qemetica Silica owns FLO-GARD and related silica technologies acquired from PPG; Omya offers calcium-based powder-flow systems; and Grace provides SYLOID silica for specialized pharmaceutical and food-processing functions. Product prices and performance cannot be compared across all these suppliers without accounting for the target matrix and intended use.
Ownership and market boundaries warrant particular care. Qemetica, not PPG, controls the divested precipitated-silica business, while Sigma-Aldrich is part of Merck KGaA rather than an additional independent producer. Roquette supplies functional plant-based ingredients and excipients, but its entire starch or pharmaceutical portfolio should not be categorized as anti-caking revenue. Procurement teams increasingly value verified regional supply, documentation and performance after warehouse aging alongside the headline cost per kilogram.
Recent Developments
11 October 2026: Omya expands technical guidance on liquid-to-powder conversion. Omya detailed carrier-technology considerations for protecting flavors as liquids are converted into stable powder ingredients. The disclosure illustrates the growing intersection between carrier selection, flow management and retention of sensitive actives; it is technical guidance, not an announced capacity addition.
11 September 2026: Evonik announces further restructuring of precipitated-silica manufacturing. Evonik outlined the transfer of German precipitated-silica production toward a planned large-scale Marl plant, targeting operation at the end of 2028. The broader silica portfolio includes material used for powder conditioning, although the announcement did not disclose anti-caking-specific capacity.
13 April 2026: Omya details mineral anti-caking selection and accelerated performance testing. Omya published its approach to moisture and mechanical-stress evaluation, highlighting Omyafood, Calcipur and Omyanutra mineral products for food and nutraceutical powders. The application work illustrates a shift toward measured performance after realistic storage stresses.
10 November 2025: Omya addresses dusting costs in food manufacturing. The supplier published technical analysis connecting powder dust control with processing efficiency and formulation decisions. For anti-caking grades, it reinforces the value of handling performance alongside moisture control.
17 January 2025: Evonik announces North American silica plant rationalization. The company detailed planned closure of its Waterford fumed-silica facility and Havre de Grace precipitated-silica and calcium-silicate production, with supply to be transferred elsewhere. The announcement is directly relevant to capacity continuity for selected conditioning grades.
25 November 2024: Qemetica acquires the PPG precipitated-silica business. The transaction transferred US and Dutch manufacturing assets and established brands used in food and feed flow conditioning, including FLO-GARD. It changed ownership of directly relevant product lines rather than adding the entire acquired silica portfolio to anti-caking market value.
Market Outlook
The market should continue to expand through broader use of powdered foods and complex dry ingredients, though growth will not be captured evenly by all chemistry classes. Demand for more stable feeding, lower dust, and application-specific caking resistance can support premium grades, while calcium-based and silica solutions will continue to compete on an effective-dose basis. The most defensible opportunity lies in measurable improvement to a customer’s processing or shelf-life outcome rather than in promoting a single substance as a universal fix.
Supplier strategy will increasingly combine formulation support, regulatory documentation and production-network resilience. North American and European customers may focus on continuity and specialist performance, while Asian food, feed and nutrition production supports faster volume development. Standards, local approvals and customer testing will remain practical barriers to substitution, reinforcing the value of established technical relationships.
Anti-Caking Agents Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.32 billion |
| Total Market Size in 2031 | USD 1.79 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
Calcium Compounds
Sodium Compounds
Magnesium Compounds
Other Types
By Application
Food and Beverage
Bakery Products
Dairy Products
Soups and Sauces
Beverages
Others
Cosmetic and Personal Care
Feed
Other Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
2.3. Estimation Methods
2.4. Validation and Triangulation
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry
4.4. Industry Value Chain Analysis
5. ANTI-CAKING AGENTS MARKET, BY TYPE
5.1. Introduction
5.2. Calcium Compounds
5.3. Sodium Compounds
5.4. Magnesium Compounds
5.5. Other Types
6. ANTI-CAKING AGENTS MARKET, BY APPLICATION
6.1. Introduction
6.2. Food and Beverage
6.2.1. Bakery Products
6.2.2. Dairy Products
6.2.3. Soups and Sauces
6.2.4. Beverages
6.2.5. Others
6.3. Cosmetic and Personal Care
6.4. Feed
6.5. Other Applications
7. ANTI-CAKING AGENTS MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. United Kingdom
7.4.2. Germany
7.4.3. France
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. United Arab Emirates
7.5.3. Israel
7.5.4. Others
7.6. Asia Pacific
7.6.1. Japan
7.6.2. China
7.6.3. India
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Taiwan
7.6.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategies
8.2. Emerging Players
8.3. Mergers, Acquisitions and Collaborations
8.4. Vendor Competitiveness Matrix
9. COMPANY PROFILES
9.1. Evonik Industries AG
9.2. Qemetica Silica
9.3. Omya International AG
9.4. W. R. Grace & Co.
9.5. Huber Engineered Materials
9.6. Roquette Frères
9.7. Merck KGaA
9.8. BASF SE
9.9. Kao Corporation
9.10. PQ Corporation
9.11. Solvay SA
9.12. Imerys SA
Navigate
Trusted by the world's leading organizations











