
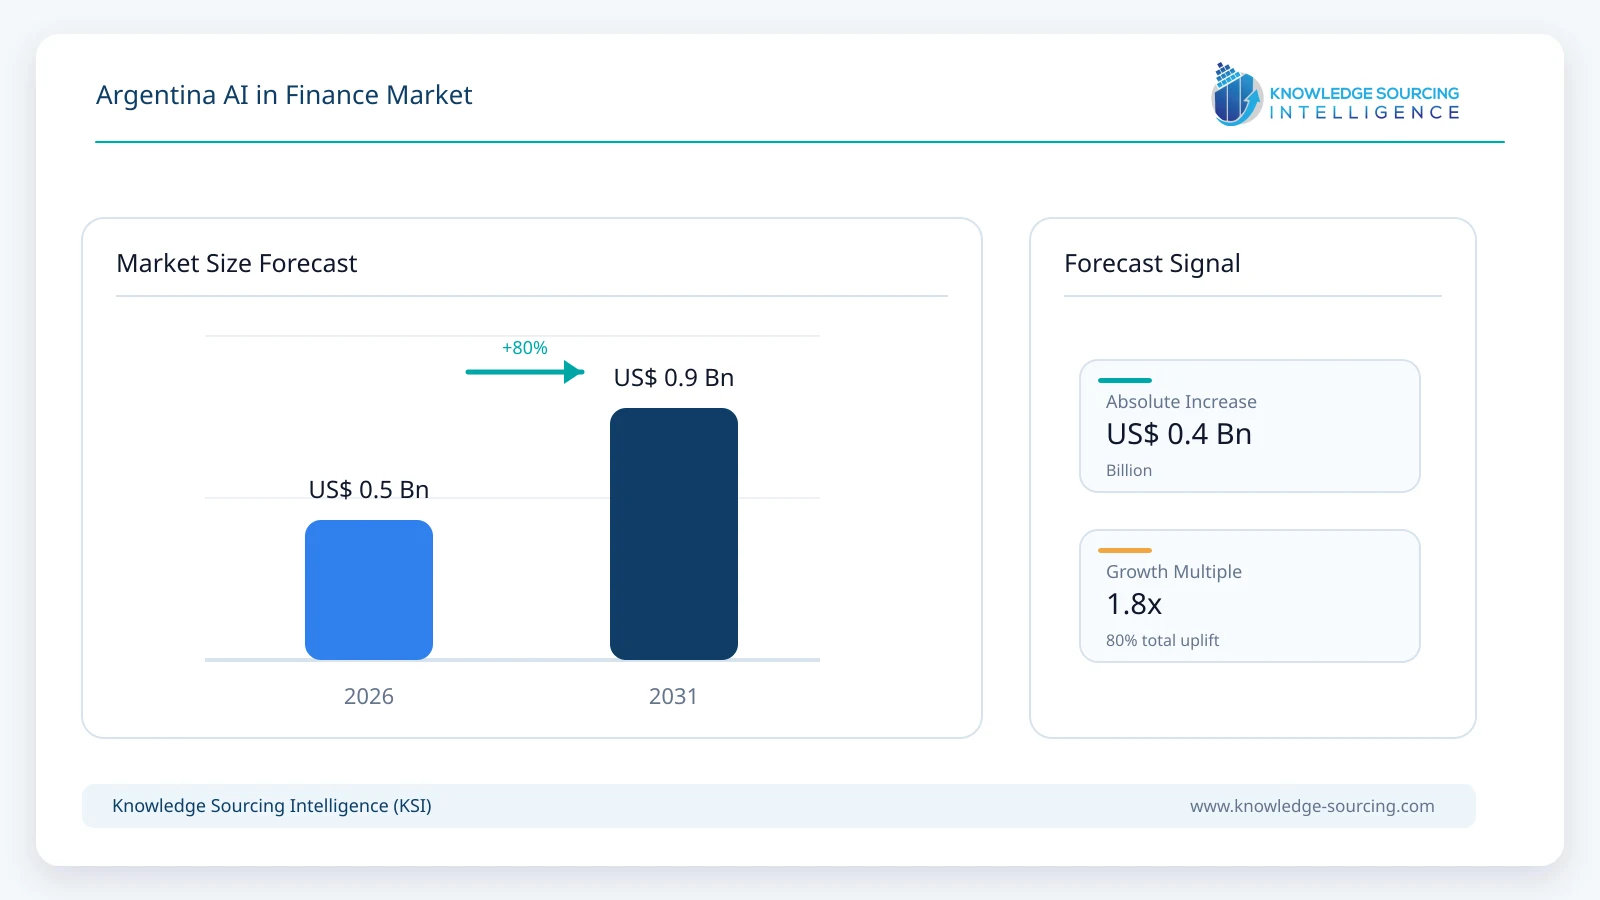
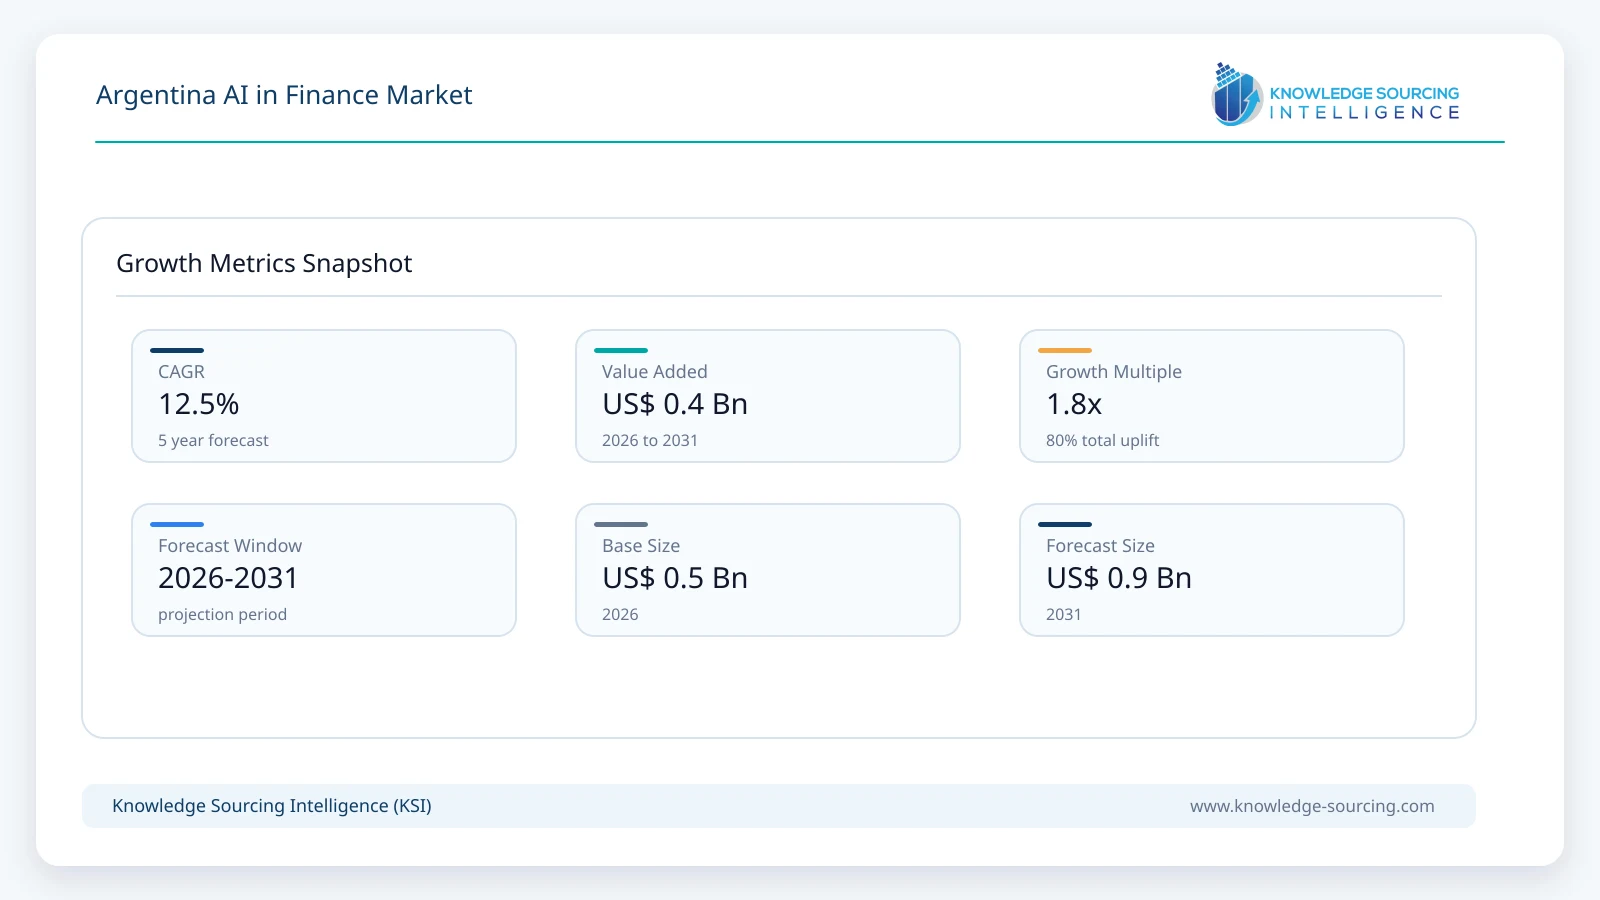
The Argentina AI in Finance Market is projected to expand at a CAGR of approximately 12.5%, reaching USD 0.90 billion in 2031 from USD 0.50 billion in 2026.
Highlights:
- 1AI-enabled payment screening is moving closer to real-time transfer authorization and intervention.
- 2Cloud delivery represents an estimated 56% of 2026 market spending, reflecting managed deployment preferences.
- 3Back-office applications remain important because onboarding, fraud review and compliance require auditable workflows.
- 4Large language models are gaining share, although credit and payment decisions still need controlled validation.
- 5Regulatory guidance prioritizes model inventories, testing, human oversight and third-party risk governance.
The Argentine AI in finance market comprises identifiable spending on AI-capable software, financial risk analytics, model-serving infrastructure and implementation or managed services for banks, payment-service providers, credit firms and regulated financial operations. Machine-learning fraud scoring, intelligent document processing, conversational assistants and credit underwriting are included when their incremental financial-sector value can be attributed. Ordinary core-banking licences, payment value, customer deposits and non-AI cybersecurity spending are excluded from the market definition.
BCRA payment statistics point to a larger pool of transactions requiring continuous screening: instant transfers and interoperable payments have increased markedly, including activity involving virtual payment accounts. Technology suppliers such as Visa, Mastercard, Red Hat and Globant operate at different layers of the stack, from payment decisioning to enterprise deployment. Banks and fintechs may also build and own models internally; their total operating expenditure is not automatically third-party AI supplier revenue.
Market Overview
The BCRA’s 2025 annual payments review records a 13.3% increase in the number of national payment-system transactions and a 25.6% rise in immediate push transfers. As these streams move through banking applications, interoperable wallets and account-to-account channels, the number of events available for screening increases without a corresponding tolerance for slow or unnecessary intervention. Machine-learning systems can combine transaction patterns, device signals and behavioural anomalies, but the commercial value comes from reducing actual fraud and avoidable friction rather than from classifying more payments as suspicious.
For bank operations, document handling and account opening are established use cases. Red Hat’s description of Banco Galicia’s intelligent corporate-document workflow records a reduction from an approximately 20-day manual process to near-real-time review; the bank reported lower operating costs associated with that workflow. This example concerns a specific production process, not proof that all bank documentation is automatically evaluated or that compliance decisions can be delegated without human accountability.
The BCRA published initial guidance on responsible and secure AI use in June 2026. It addresses model governance, traceability, bias monitoring, operational continuity and third-party risk as part of financial supervision. These considerations alter procurement: technology teams need access to documentation and testing interfaces as well as model performance, and financial institutions remain responsible for decisions implemented through external software.
Market Trends
Real-Time Transfer Fraud Scoring Is Becoming More Important
Argentina’s increased use of interoperable transfers changes fraud detection from a largely card-network exercise into a multi-rail operating requirement. The BCRA reported 779 million peso-denominated push transfers in August 2026, up 20.3% year over year. Banks and payment providers need models that can combine account history, beneficiary relationships and behavioural signals while producing a decision quickly enough for an immediate transfer.
Visa introduced an enhanced A2A Protect offering in September 2026, bringing Featurespace-derived intelligence into its transfer-risk capabilities. The announcement describes a global product, not a confirmed Argentine deployment; nevertheless, it illustrates the external products available as institutions modernize payment protection. Training on local fraud patterns and suppressing false positives will determine whether similar tools justify their operating cost.
Document Intelligence Is Moving Into Account Operations
Banco Galicia’s corporate onboarding example demonstrates a distinct workflow for natural-language processing: machine extraction and classification of documents before specialist risk and legal review. Staff time, customer waiting periods and incomplete-document requests can fall when information is interpreted reliably, particularly where legal instruments vary across customers.
Financial institutions must still test extraction accuracy on Argentine documentation, validate changes to templates and preserve traceable reasons for accepting or rejecting a customer. The most economical systems combine reusable document models with configurable review rules; unverified generative summaries are unsuitable as substitutes for authoritative client files.
Generative AI Purchasing Is Moving Toward Controlled Enterprise Use
Language models can assist relationship managers, contact centres and compliance teams with document summarization and retrieval from approved knowledge bases. Their economic benefit is more conditional than in conventional transaction scoring: answer quality varies with the underlying records, and financial communications often require precise product terms, correct interest calculations and consistent escalation routes.
Vendor selection is increasingly shaped by access permissions, audit logs, retrieval architecture and the possibility of restricting sensitive records from external training environments. For many banks, the first commercially sustainable use may be a staff-facing assistant rather than an autonomous consumer financial adviser.
Agentic Payments Are Advancing Through Controlled Trials
Mastercard reported completed agentic payment transactions across Latin America in March 2026 and named Banco de la Nación Argentina, Banco Galicia and payment technology provider Pomelo among participants. The announcement identifies participating organisations but does not show that every bank customer has access to autonomous payments. Cardholder consent, verification of agent identity and an authorized transaction record were central features of the demonstration.
These early applications could eventually add orchestration and verification revenue to financial AI platforms. Immediate deployment will depend on whether banks can place spending limits, dispute processes and fraud screening around automated agents without compromising obligations to cardholders.
Model Governance Is Becoming a Product Requirement
The BCRA’s June 2026 supervisory guidance calls attention to a documented inventory of models, evaluation of bias, monitoring for model drift and suitable human review. These are not simply data-science procedures: they affect vendor support contracts, deployment options, record retention and the ability of auditors to reconstruct high-impact decisions.
Specialist suppliers able to offer model documentation, controllable updates and evidence for third-party risk reviews can compete against less governed point solutions. Institutions with extensive legacy architectures may pay more for integration and validation than for the original model licence.
Segment Analysis
By Type: Natural Language Processing
Natural language processing accounts for an estimated 30% of Argentine financial AI spending in 2026. The category includes dedicated classification, extraction and financial-language interpretation functions, not generative models already allocated to the separate Large Language Models category. Banks use these tools for corporate records, customer correspondence, claims and compliance documents where a predictable structure is valuable.
Demand is sustained by the need to turn unstructured information into system records with auditable provenance. Banco Galicia’s document-processing workflow provides a domestic implementation example, while standalone NLP products compete with newer general-purpose models for the same tasks. By 2031, NLP remains significant even as some budgets migrate to specialized language-model deployments; accuracy on Spanish financial text and regulatory forms remains a differentiator.
By Deployment Model: Cloud
Financial AI delivered through cloud infrastructure can support short development cycles, elastic processing and access to specialized model services without the purchase of dedicated accelerators. The segment is estimated at USD 280 million in 2026, reflecting a wide range of hosted analytics, payment-security services and managed model endpoints. Its growth does not imply that institutions can place all regulated data into an uncontrolled external service.
Financial institutions are increasingly concerned with cloud-region selection, encryption, outsourcing responsibilities, operational recovery and portability. Contracts often combine hosted model execution with customer-controlled data stores; payments and identity data can remain subject to strict access restrictions. Continued growth will depend on controlled integration rather than an uncomplicated shift away from on-premise infrastructure.
By User: Consumer Finance
Consumer-finance operations offer substantial scope for behaviour-based credit analysis, loan monitoring and digitally assisted servicing. More payment history and wallet interaction can improve affordability assessments when used lawfully and interpreted alongside formal financial information. The commercial buyer is typically the lending institution or financial platform, even when the model is embedded in a consumer-facing application.
The segment is projected to reach approximately USD 396 million by 2031. Expansion depends on calibration through Argentina’s changing credit conditions and on suitable treatment of customers with incomplete histories. Strong risk management can make credit products available to more borrowers, but models must be tested for performance drift and unfair exclusion rather than relying solely on alternative-data availability.
By Application: Back Office
An estimated 42% of spending in 2026 is associated with back-office processes, including suspicious-activity screening, document processing, operational reconciliation and review of exceptions. These systems can reduce manual queues while improving the consistency of evidence presented to compliance and operations staff. The required data quality and review rules vary considerably between fraud scoring and customer onboarding.
Implementation economics depend on whether a model connects to an existing case-management platform and yields measurable reductions in manual review or losses. A bank may purchase analytics components separately or obtain them within a wider vendor service; the associated AI content should be counted once. Back-office software remains a central source of value as financial institutions maintain increasingly detailed model-governance requirements.
Market Drivers
Growing Immediate-Payment Activity
BCRA retail-payment records show increased instant transfers and QR-linked payments, including operations routed through virtual payment accounts. The larger real-time flow gives banks and payment providers more transactions to authenticate, monitor and investigate, with limited time for staff intervention. Machine-learning scoring can prioritize anomalies at the moment a transaction is requested rather than after funds have moved.
This demand is not proportional to payment value. More efficient models and bundled provider contracts can lower the cost per screened transfer, while additional risk controls create spending on data features, model operation and investigation workflow. Providers compete on measurable false-positive reduction and the speed of risk decisions.
Pressure to Improve Lending Decisions
Consumer lenders operating through mobile channels need to make credit decisions without traditional branch-based file review. Machine-learning tools may combine repayment records and permitted behavioural indicators to improve default prediction, especially for customers with limited conventional history. Higher digital service use expands the information available, though access and suitability vary by borrower.
A lending model needs robust testing through changing interest-rate and income conditions. Financial institutions are more likely to renew high-value software where it improves portfolio outcomes than where it merely automates approval. Vendor requirements therefore include monitoring, score explanations and the ability to update variables in a controlled way.
Corporate Onboarding and Operating Efficiency
Corporate account opening involves company registrations, authorization documents and other records that require scrutiny by legal and compliance staff. The documented Banco Galicia implementation shows why financial firms invest in extraction and classification models: substantial preparation work can be automated while the institution retains responsibility for the approval decision.
The same architecture can serve account maintenance and periodic customer review. Commercial returns depend on document volumes, accuracy, staff workload and successful integration with bank records, not simply on the number of users accessing a chatbot. Repeatable workflows can justify enterprise contracts over isolated proof-of-concept budgets.
Competitive Pressure from Digital Financial Platforms
Digital wallets and app-based banking make service speed, fraud handling and customer support visible points of competition. Established banks must provide responsive digital operations, while fintechs need automated controls to handle large user populations without equivalent branch infrastructure. AI-based service routing and suspicious-activity detection can help both groups manage growing interaction volumes.
Because consumers can use several financial applications, personalized interaction alone may not produce durable revenue. Vendors have a stronger case when systems also improve approval rates, dispute resolution or cost-to-serve. Competition therefore favours integrated financial AI tools rather than generic conversation interfaces.
Formalization of AI Oversight and Risk Management
The BCRA’s supervisory guidance describes expectations for controlled AI-model inventories, auditability, monitoring, fairness and third-party oversight. Financial institutions already using models may need more rigorous documentation and testing as their deployment broadens. These activities create service demand around validation, model management and secure integration.
The guidance should not be read as a legal requirement to buy AI or to use a particular vendor. It raises the operational standard for institutions choosing to deploy AI, encouraging procurement that includes governance functions and qualified support rather than only model access.
Market Restraints
Legacy Core Systems and Fragmented Data
Established banks operate systems built for account processing, payments and compliance at different points in time. Adding model-based risk decisions requires interfaces that reliably join customer identity, transaction context and prior outcomes across those systems. Historical records may use inconsistent identifiers, and real-time screening is sensitive to delays and missing data.
Integration programmes can involve extensive testing without immediately generating new revenue. Technology buyers may extend existing vendor relationships rather than authorize entirely new AI platforms if the transition threatens payment continuity or increases the number of system dependencies.
Model Drift Under Changing Economic Conditions
Argentine credit and payments behaviour can change materially as inflation, borrowing costs and consumer demand shift. A model trained during one set of economic conditions may misclassify risk in another, even when underlying software remains operational. False alarms increase customer friction, while undetected risk can damage a lending portfolio.
Institutions need periodic recalibration, independent validation and controlled release procedures. For smaller financial providers these costs can narrow the business case for a model that performs well in a limited test but lacks durable operational support.
Sensitive Financial Data and Third-Party Exposure
Credit files, identity documents and transaction histories contain personal and commercially sensitive information. Argentina’s data-protection requirements, contractual confidentiality and BCRA technology-risk practices constrain where those records may be processed and who may access them. Vendor claims about model capability do not replace an institution’s obligation to govern the data.
When financial models depend on an outside cloud or analytics provider, purchasing teams must examine information security, subcontractors, incident response, audit rights and the practical ability to switch suppliers. These costs can slow deployment where an application lacks clear operational benefit.
Explainability and Fair-Lending Concerns
Machine-learning credit decisions may incorporate variables that are difficult to interpret or that correlate with protected characteristics. Banks and lenders need to understand why a customer receives a particular outcome, particularly if a decision affects access to essential financial services. A highly accurate aggregate model can still perform unevenly for borrowers with limited histories.
Model-governance obligations therefore influence algorithm choice and feature selection. More transparent models may be preferable to complex alternatives in high-impact workflows, limiting the immediate addressable spending for some advanced architectures.
High Cost of Specialized Integration and Oversight
Financial AI development requires expertise in data engineering, security, financial regulation and operational risk in addition to model training. Qualified specialists must work with bank compliance and business teams to translate algorithms into controlled decisions. Small institutions often lack sufficient volumes or in-house teams to justify dedicated deployments.
Managed services can reduce the need for internal infrastructure, but recurring fees, testing and vendor concentration remain material. Institutions may prioritize a small number of high-impact deployments rather than fund parallel pilots across every department.
Regional Outlook
Buenos Aires Metropolitan Area
The Buenos Aires Metropolitan Area is estimated to account for approximately 71% of Argentina’s financial AI expenditure in 2026, reflecting the concentration of leading banks, major fintech headquarters, payment-system operators and enterprise technology procurement. This spending allocation concerns the location of purchasing institutions and project ownership, rather than the residence of every consumer whose transactions are screened. National mobile banking transactions generate AI workloads that may be contracted centrally.
Financial institutions in the capital region are early purchasers of enterprise fraud scoring, customer analytics and compliance automation because they operate across large volumes and maintain technical procurement teams. By 2031, the area's projected market share eases to 67% as technology access broadens beyond the capital. The region nevertheless remains the country's largest concentration of complex banking integrations and model-governance work.
Central Argentina: Córdoba, Santa Fe and Entre Ríos
Central Argentina is the fastest-growing domestic market grouping in the regional model, with spending forecast to rise from about USD 70 million in 2026 to USD 153 million in 2031. Its financial-services customer base combines regional banks, insurance operations, agricultural business finance and expanding digital-payment activity. Cloud-delivered applications allow institutions outside Buenos Aires to procure specialised risk and service functions without establishing a large, independent model-engineering department.
The implied CAGR is approximately 17.0%, though the region begins from a considerably smaller spending base. The forecast assumes additional adoption by regional financial institutions and financial-service technology teams; comparable published provincial AI-revenue statistics are not available. Opportunities depend on local integration capacity, lending demand and the usefulness of centrally hosted models for regional customers.
Competitive Landscape
Visa and Mastercard compete in payment decisioning and financial-risk software as well as network services. Visa's Advanced Authorization, Decision Manager and enhanced A2A Protect illustrate transaction-scoring products, while Mastercard's agentic payment infrastructure and associated verification methods address authorization, trust and orchestration. Their Argentine payment relationships create channels to institutions, although global platform announcements should not be mistaken for disclosed Argentina-only AI sales.
Red Hat provides an enterprise platform and documented workflow technology used by Banco Galicia; Globant offers financial-services AI engineering and implementation. Cloud and analytics suppliers including Microsoft, IBM, Google Cloud and Amazon Web Services provide directly usable financial AI software and model infrastructure, but only finance-attributable spending belongs within this market. Companies competing in the same account may earn revenue at different layers, making bundled services a material consideration for any supplier comparison.
Payment infrastructure specialists such as Pomelo participate in AI-enabled financial workflows alongside banks and issuers. Mercado Pago and Ualá are important integrated financial-service operators that may develop or deploy their own models, but their gross payment volume and total finance revenue are not AI vendor revenue. Similarly, Banco Galicia, Banco de la Nación Argentina and BBVA Argentina are demand-side examples rather than standalone vendors of AI software simply because they use such systems. Market-share rankings cannot responsibly be derived from these institutions' headline financial results.
Recent Developments
21 October 2026: Visa announced SESA 2.0, using AI-driven supplier-spend assessment for commercial payments, alongside fraud controls and an agent-initiated invoice-payment pilot. The offerings were announced internationally; no Argentina-specific customer rollout was claimed.
2 September 2026: Visa introduced an enhanced A2A Protect fraud-scoring service using integrated Featurespace capabilities for account-to-account payments. Its relevance to Argentine transfer screening is technical; the announcement did not identify an Argentine installation.
24 March 2026: Mastercard reported completed live agentic-payment transactions across Latin America and identified Banco de la Nación Argentina, Banco Galicia and Pomelo among participating organisations. The release described tested payment flows, not a nationwide consumer rollout.
27 February 2026: Visa completed its acquisition of Argentine payment processors Prisma and Newpay, with plans to bring additional intelligent-risk, biometric and digital-payment services to their infrastructure.
28 January 2026: Mastercard announced Agent Suite, a set of services for enterprise adoption of agentic AI in commerce and payments. The original launch did not establish an Argentina-only deployment.
Market Outlook
Through 2031, AI spending in Argentine financial services will increasingly follow production-critical processes rather than general experimentation. Transaction fraud controls, credit risk modelling and document intelligence have identifiable outcomes that banks can measure in losses avoided, case-processing time and the cost of serving customers. Language models will gain a larger role in customer and staff support, but deployment into regulated decisions will remain dependent on validation and supervisory controls.
Cloud infrastructure should gain share as managed financial AI services become more capable, while domestic banks continue to keep sensitive data and high-impact decision controls under explicit governance. Buenos Aires will remain the principal purchasing centre, with faster growth possible in regional financial institutions as services become easier to deploy. Competition will favour suppliers combining finance-specific models with system integration, evidence of performance and the ability to support audits over several years.
Argentina AI in Finance Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.50 billion |
| Total Market Size in 2031 | USD 0.90 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Deployment Model, User, Application |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Natural Language Processing
Large Language Models
Sentiment Analysis
Image Recognition
Others
By Deployment Model
On-Premise
Cloud
By User
Personal Finance
Consumer Finance
Corporate Finance
By Application
Back Office
Middle Office
Front Office
By Domestic Geography
Buenos Aires Metropolitan Area
Central Argentina (Córdoba, Santa Fe and Entre Ríos)
Other Argentine Provinces
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Growing Immediate-Payment Activity
3.1.2. Pressure to Improve Lending Decisions
3.1.3. Corporate Onboarding and Operating Efficiency
3.1.4. Competitive Pressure from Digital Financial Platforms
3.1.5. Formalization of AI Oversight and Risk Management
3.2. Market Restraints
3.2.1. Legacy Core Systems and Fragmented Data
3.2.2. Model Drift Under Changing Economic Conditions
3.2.3. Sensitive Financial Data and Third-Party Exposure
3.2.4. Explainability and Fair-Lending Concerns
3.2.5. High Cost of Specialized Integration and Oversight
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ARGENTINA AI IN FINANCE MARKET BY TYPE
5.1. Introduction
5.2. Natural Language Processing
5.3. Large Language Models
5.4. Sentiment Analysis
5.5. Image Recognition
5.6. Others
6. ARGENTINA AI IN FINANCE MARKET BY DEPLOYMENT MODEL
6.1. Introduction
6.2. On-Premise
6.3. Cloud
7. ARGENTINA AI IN FINANCE MARKET BY USER
7.1. Introduction
7.2. Personal Finance
7.3. Consumer Finance
7.4. Corporate Finance
8. ARGENTINA AI IN FINANCE MARKET BY APPLICATION
8.1. Introduction
8.2. Back Office
8.3. Middle Office
8.4. Front Office
9. ARGENTINA AI IN FINANCE MARKET BY DOMESTIC GEOGRAPHY
9.1. Introduction
9.2. Buenos Aires Metropolitan Area
9.3. Central Argentina (Córdoba, Santa Fe and Entre Ríos)
9.4. Other Argentine provinces
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Visa Inc.
11.2. Mastercard Incorporated
11.3. Red Hat, Inc.
11.4. Globant S.A.
11.5. Microsoft Corporation
11.6. IBM Corporation
11.7. Google LLC (Google Cloud)
11.8. Amazon Web Services, Inc.
11.9. Oracle Corporation
11.10. SAS Institute Inc.
11.11. Fiserv, Inc.
11.12. Veritran S.A.
11.13. Pomelo Fintech Services
11.14. Feedzai
11.15. Temenos AG
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size of Argentina AI in Finance by 2031?
The Argentina AI in Finance Market is projected to reach USD 0.90 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for this market?
The Argentina AI in Finance Market is projected to expand at approximately 12.5% CAGR.
Which delivery model holds significant market spending?
Cloud delivery represents an estimated 56% of 2026 market spending.
What are key applications within Argentina's AI in Finance market?
Payment screening, fraud scoring, document processing, and credit underwriting are included.
What are the key regulatory considerations for AI in finance?
Regulatory guidance prioritizes model inventories, testing, human oversight, and third-party risk.
What drives the need for AI in Argentina's finance market?
Increased instant transfers and interoperable payments are driving market expansion.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Argentina AI in Finance Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/argentina-ai-in-finance-market