
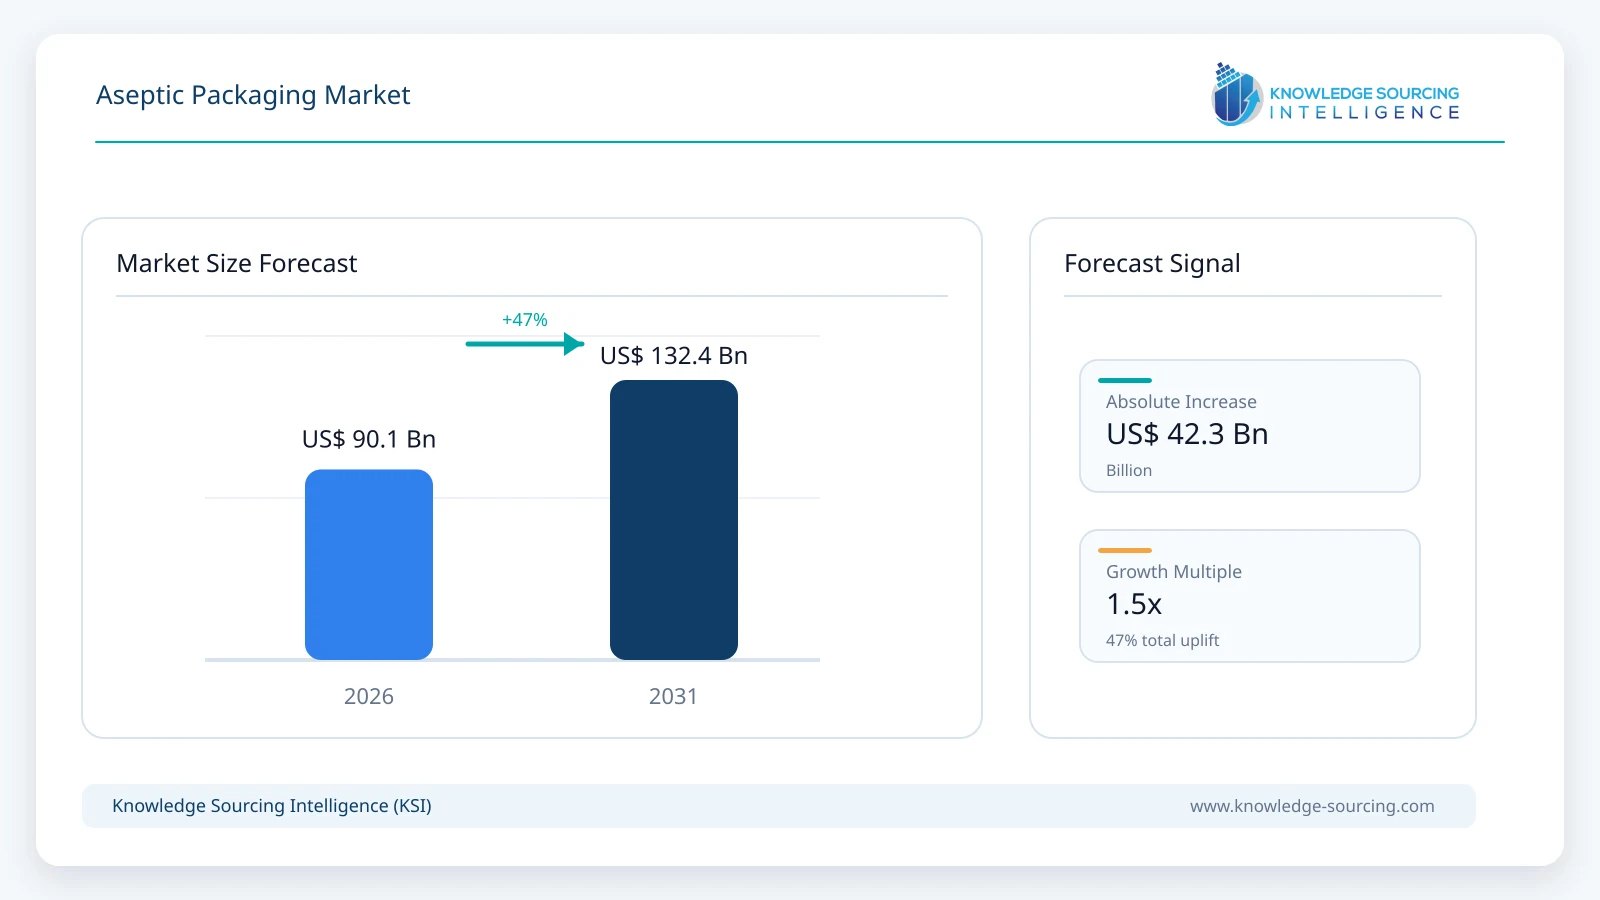
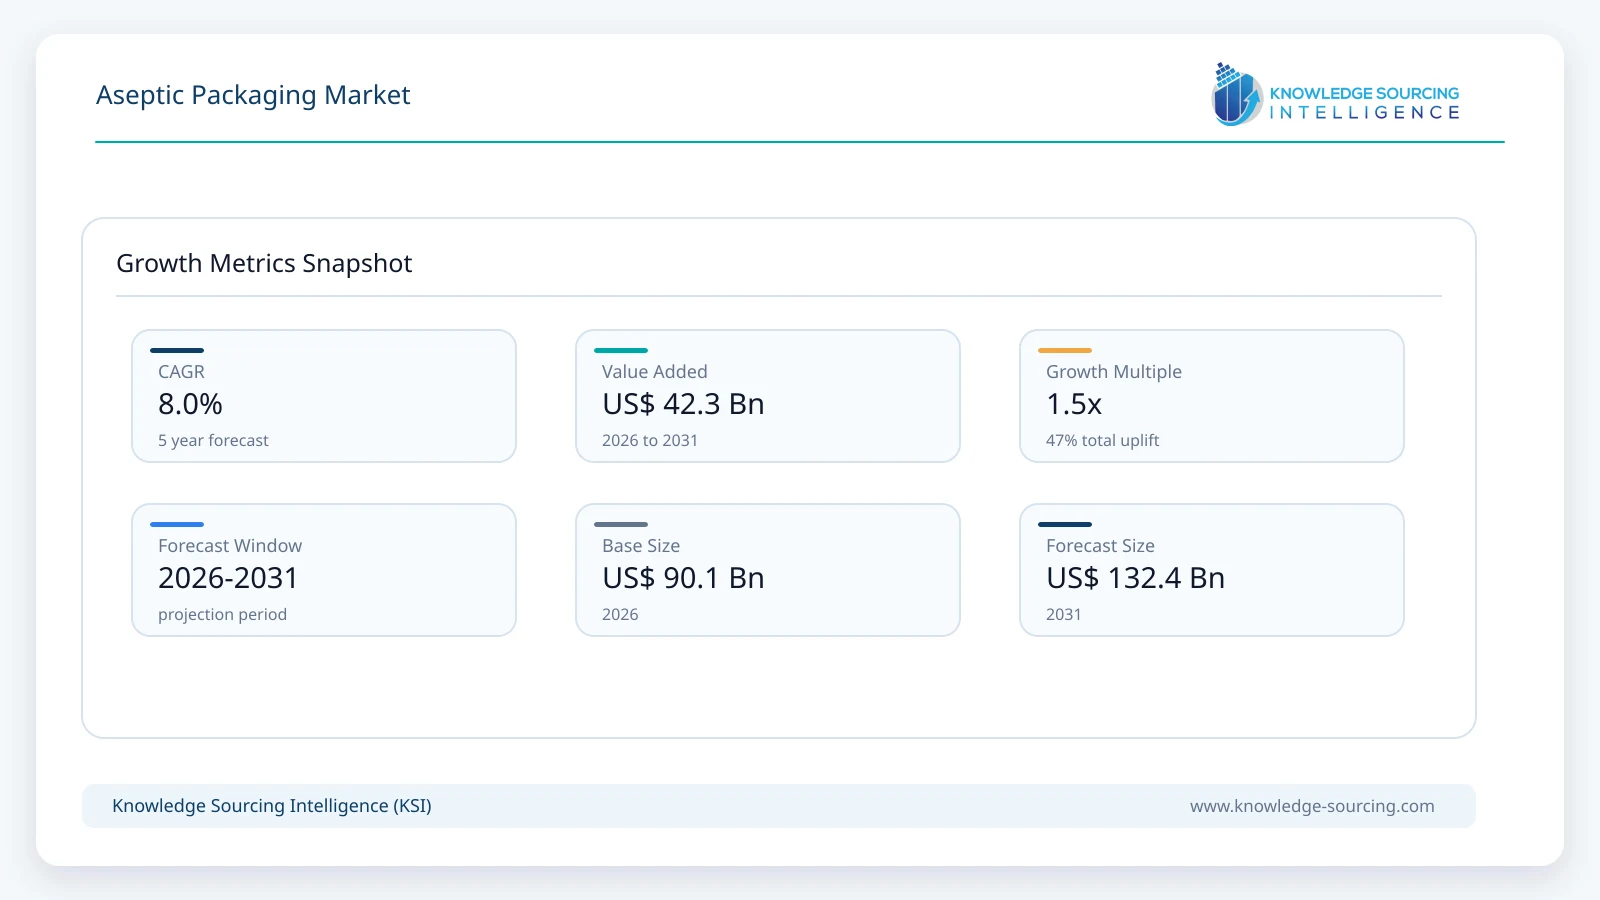
The Aseptic Packaging Market is forecast to grow at a CAGR of 8.0%, reaching USD 132.4 billion in 2031 from USD 90.1 billion in 2026.
Highlights:
- 1Rising Demand for Shelf-Stable Food and BeveragesGrowing dairy, beverage, and processed-food consumption is supporting aseptic packaging because it enables commercially sterile products to be distributed without continuous refrigeration.
- 2Strong Dairy Production BaseGovernment data indicate continued large-scale milk production in major consuming markets. USDA projections for 2026 place India’s cow milk production at 105.4 million metric tons, China at 40.6 million metric tons, and Brazil at 26.2 million metric tons, supporting demand for shelf-stable dairy formats.
- 3Sustainability Is Reshaping Aseptic CartonsRegulatory requirements and customer sustainability targets are accelerating the development of paper-based barriers, aluminum-free structures, lower-carbon materials, and packaging designed for improved recycling.
- 4Pharmaceutical Packaging Is Increasingly SpecializedGrowth in biologics, vaccines, complex injectables, and self-administered therapies is supporting demand for sterile vials, prefilled syringes, cartridges, and other high-performance primary packaging formats.
- 5Asia Pacific Remains a Strategic Expansion RegionPopulation growth, urbanization, dairy consumption, food-processing investment, and increasing local manufacturing capacity are strengthening the region’s role in aseptic packaging demand and production.
Aseptic packaging is a packaging and processing system in which the product, packaging material, and relevant processing and filling equipment are treated to achieve commercial sterility before filling and sealing under controlled conditions. The objective is to protect the packaged product from microbiological contamination while maintaining the required quality throughout its intended shelf life. The U.S. Food and Drug Administration identifies aseptic processing as requiring commercial sterility of the product, packaging system, and associated equipment, with documented scheduled processes and controls.
The market serves food, beverage, and pharmaceutical applications through formats including cartons, bottles and cans, bags and pouches, prefilled syringes, and vials and ampoules. Aseptic cartons are particularly important for liquid dairy products, juices, plant-based beverages, sauces, and other shelf-stable products, while pharmaceutical applications rely on sterile primary packaging capable of protecting sensitive injectable formulations.
Demand is being influenced by the interaction of food distribution requirements, changing consumer purchasing patterns, pharmaceutical innovation, and packaging regulation. The United Nations estimates that the global population reached 8.2 billion in 2024 and is projected to reach approximately 8.5 billion by 2030. Population growth, particularly in developing economies, increases the underlying requirement for efficient food and beverage distribution systems.
Urbanization is another structural factor. The World Bank's urban population dataset, based on United Nations Population Division data, provides annual urbanization data through 2025 and highlights the continuing importance of urban population growth in shaping food, beverage, infrastructure, and distribution requirements.
Dairy represents a particularly important demand base for aseptic packaging. USDA Foreign Agricultural Service projections published in December 2025 estimate 2026 cow milk production of 105.4 million metric tons in India, 40.6 million metric tons in China, 26.2 million metric tons in Brazil, 14.1 million metric tons in Mexico, and 106.2 million metric tons in the United States. These large production bases support continued demand for packaging systems that can facilitate safe processing, storage, and distribution of liquid dairy products.
Food security and supply-chain resilience also reinforce the value proposition of ambient-stable products. Aseptic packaging can reduce dependence on refrigerated distribution for suitable products and enables manufacturers to reach geographically dispersed markets. This is particularly relevant in countries with large geographic territories, developing cold-chain infrastructure, or significant distances between production and consumption centers.
Technological development is simultaneously changing the competitive basis of the industry. Packaging manufacturers are working on paper-based barriers, aluminum-free structures, lower-carbon inputs, improved filling-line efficiency, and digitally enabled production systems. In April 2026, Tetra Pak and Sterilgarda Alimenti introduced a 1-litre aseptic carton using a paper-based barrier, with the company reporting renewable content of up to 90% when combined with plant-based polymers and a carbon-footprint reduction of up to 50% compared with the referenced conventional solution.
Aseptic Packaging Market Analysis
Growth Drivers
One of the principal growth drivers is the continued requirement for safe, shelf-stable food and beverage products. Aseptic packaging allows appropriately processed products to be stored and transported under ambient conditions, reducing reliance on uninterrupted refrigeration during distribution. This characteristic is particularly valuable for milk, flavored milk, juices, plant-based beverages, liquid foods, sauces, and other products for which extended shelf life is commercially important.
The scale of global dairy production reinforces this demand. USDA projections indicate that global cow milk production among the selected countries and regions in its December 2025 outlook is expected to remain substantial in 2026, with India, the European Union, the United States, China, Brazil, New Zealand, and other major producers contributing to a large international dairy supply base.
India is particularly important because of its very large dairy production and consumption base. USDA projects Indian cow milk production at 105.4 million metric tons in 2026, compared with 103.2 million metric tons in 2025. China is projected at 40.6 million metric tons in 2026, while Brazil is projected at 26.2 million metric tons. These figures do not represent aseptic packaging consumption directly, but they provide an important official indicator of the underlying dairy-processing opportunity relevant to aseptic packaging suppliers.
Plant-based beverages, ready-to-drink products, and functional beverages are also expanding the range of products that can use aseptic formats. Manufacturers increasingly require packaging that supports long shelf life, convenient portion sizes, efficient transportation, and product differentiation. Aseptic cartons and flexible formats can address these requirements while providing opportunities for lightweighting and material optimization.
Pharmaceutical demand provides another structural growth driver. Injectable medicines, vaccines, biologics, and other sensitive therapies require primary containers that maintain product quality and container-closure integrity. WHO's vaccine and biological-product activities continue to emphasize quality, safety, manufacturing, and regulatory control for biological medicines. Its 2026 Expert Committee on Biological Standardization agenda includes standards and guidance related to vaccines and biotherapeutics.
WHO's current prequalification database also demonstrates the continued use of vial-based presentations for vaccines, including products manufactured in India and other countries. This reinforces the importance of sterile vial systems within the pharmaceutical packaging ecosystem.
Challenges and Opportunities
The market faces several operational and economic challenges. Aseptic filling systems require specialized equipment, validated processes, controlled environments, and trained personnel. Capital expenditure can therefore be significant for manufacturers that need to establish new filling capacity. Process validation and quality-control requirements can also increase the time and resources required to commission new production lines.
The U.S. FDA illustrates the complexity of aseptic food processing. Its inspection guidance requires controls covering product sterilization, downstream processing equipment, packaging equipment, and packaging materials. Commercial processors of relevant low-acid and acidified foods must also meet registration and scheduled-process filing requirements under applicable regulations.
Packaging recyclability is another challenge. Conventional aseptic cartons can combine paperboard, polymer layers, and barrier materials, creating technical and collection challenges for recycling systems. The industry's response is increasingly focused on simplifying structures, reducing the use of difficult-to-recycle components, and increasing the proportion of renewable or lower-carbon materials.
These constraints create opportunities for packaging manufacturers with advanced material and filling technologies. Paper-based barriers, aluminum-free high-barrier structures, low-carbon aluminum, improved polymer systems, and higher-fiber packaging can help suppliers respond to regulatory and customer requirements without compromising product protection.
Another opportunity is the growth of contract manufacturing and co-packing. Smaller food and beverage brands can use external filling infrastructure rather than investing immediately in dedicated aseptic lines. This can broaden the addressable customer base and encourage new products to enter the shelf-stable beverage and food categories.
Raw Material and Pricing Analysis
The principal raw materials used across aseptic packaging formats include paper and paperboard, polymers, aluminum and other barrier materials, and pharmaceutical-grade glass and polymers. The relative importance of each material depends on the product format and application.
Carton-based aseptic packaging generally uses paperboard as its structural component together with polymer layers and barrier technologies. Flexible aseptic packaging relies more heavily on polymer films and barrier structures, while pharmaceutical packaging uses specialized glass and polymer materials designed for direct contact with sensitive drug products.
Raw-material economics are affected by pulp and paper prices, polymer feedstock costs, energy prices, aluminum markets, transportation costs, and regional supply conditions. Packaging manufacturers can reduce exposure to individual inputs through supplier diversification, material optimization, lightweighting, and the development of alternative barrier systems.
The sustainability transition is also changing the definition of material cost. A material with a lower direct purchase price may become less attractive if it creates higher compliance, recycling, carbon, or extended-producer-responsibility costs. Consequently, packaging companies are increasingly evaluating materials through a broader total-cost and lifecycle perspective.
Supply Chain Analysis
The aseptic packaging supply chain combines raw-material suppliers, packaging-material converters, filling-equipment manufacturers, sterilization technologies, food and beverage processors, pharmaceutical manufacturers, logistics providers, and recycling systems. The integration between packaging materials and filling equipment is particularly important for aseptic cartons because package specifications and filling-machine compatibility are closely connected.
Regional manufacturing is becoming increasingly important. Packaging producers are adding or expanding facilities in major consumption markets to reduce transportation distances, strengthen customer service, and improve supply-chain resilience. The trend is visible in India, North America, Southeast Asia, and other growth markets where local food and beverage processing capacity is expanding.
For example, SIG's Ahmedabad aseptic carton facility became fully operational in December 2025. The company stated that the plant was completed in 20 months and was designed to supply its growing filler base in India while also serving neighboring Asian markets.
In April 2026, SIG also announced plans to expand its Querétaro plant in Mexico in phases, with the objective of increasing annual production capacity from 1.5 billion to 3 billion packages by 2028. The investment supports the company's nearshoring strategy and is intended to strengthen the North American regional supply chain.
The supply chain nevertheless remains dependent on specialized machinery, technical materials, sterilization systems, and validated processes. Equipment downtime, raw-material shortages, logistics disruptions, and qualification requirements can therefore affect the speed at which new capacity is brought online.
Government Regulations
Aseptic packaging is governed by different regulatory frameworks depending on the application. Food packaging is primarily subject to food-contact and food-processing requirements, while pharmaceutical packaging is subject to stringent requirements governing container closure, sterility, extractables and leachables, quality systems, and product protection.
Jurisdiction | Regulation / Authority | Market Implications |
|---|---|---|
European Union | Regulation (EU) 2025/40 on Packaging and Packaging Waste (PPWR) | The PPWR entered into force on 11 February 2025 and generally applies from 12 August 2026. It establishes requirements covering packaging manufacturing, composition, recyclability, waste management, and prevention, increasing pressure on suppliers to redesign packaging structures and improve circularity. |
United States | FDA requirements for aseptic processing and low-acid foods | FDA requirements include establishment registration and scheduled-process filings for applicable low-acid and acidified foods. Aseptic operations require documented controls for commercial sterility across product, equipment, packaging systems, and packaging materials. |
India | Food Safety and Standards (Packaging) Regulations, 2018 and amendments | India's packaging regulations establish requirements for food-grade materials, migration limits, multilayer packaging, and materials used in direct contact with food. FSSAI also issued draft packaging amendments in 2025 and 2026, indicating continuing regulatory development for food-contact materials. |
China | GB 4806 series of food-contact material standards | The standards establish safety and compliance requirements for food-contact materials, influencing the selection and formulation of polymers, coatings, adhesives, and other packaging components. |
The EU regulatory environment is particularly significant in 2026 because the PPWR generally begins applying from 12 August 2026. The European Commission issued implementation guidance in June 2026 to provide greater clarity to economic operators and Member State authorities.
India is also strengthening its food-contact regulatory framework. FSSAI's current regulatory material defines multilayer or composite food packaging and establishes requirements for materials including cardboard, paper, glass, metal, plastic, and multilayer packaging. FSSAI also published a draft Packaging Amendment Regulation in March 2026 concerning additional definitions, following earlier draft provisions concerning PFAS and BPA in food-contact materials.
Aseptic Packaging Market Segment Analysis
By Product: Cartons
Cartons represent a core product segment within the aseptic packaging market because they combine relatively low packaging weight with efficient product protection, storage, transport, and shelf presentation. Aseptic cartons are extensively used for liquid dairy products, juices, plant-based beverages, nutritional drinks, sauces, and other products requiring ambient stability.
The structural design of an aseptic carton typically combines paperboard with polymer and barrier layers. This construction provides the mechanical strength required for transportation while protecting the packaged product from external factors such as light and oxygen. The combination also supports efficient palletization and storage compared with many rigid formats.
Product innovation is increasingly focused on reducing the environmental impact of cartons without compromising barrier performance. In April 2026, Tetra Pak and Sterilgarda Alimenti introduced a 1-litre Tetra Brik Aseptic 1000 Edge carton incorporating a paper-based barrier. Tetra Pak stated that the package can achieve 90% renewable content when combined with plant-based polymers and can reduce carbon footprint by up to 50% against the referenced conventional packaging solution.
Tetra Pak also announced in February 2026 that its paper-based barrier packaging was being extended to high-speed A3/Speed filling lines in Asia, with Maeil Dairies identified as the first adopter for soy milk. The development is significant because adoption on high-speed lines can support broader commercialization of alternative barrier structures.
Carton innovation is also expanding beyond conventional liquid dairy and juice applications. In June 2026, Tetra Pak introduced a new Tetra Recart solution for shelf-stable tuna, positioning carton packaging as a paper-based alternative to traditional cans for a specific shelf-stable food application.
SIG is pursuing a similar direction through differentiated aseptic carton technologies. In June 2026, SIG and Seoul Dairy Cooperative received recognition for Seoul Dairy White Milk packaged in SIG Terra Alu-free + Full barrier, which SIG described as the world's first full-barrier aseptic carton packaging material without an aluminum layer.
These developments indicate that future competition within the carton segment will increasingly depend on barrier performance, recyclability, renewable content, carbon footprint, filling-line compatibility, package convenience, and total system economics rather than packaging volume alone.
By Application: Pharmaceuticals
The pharmaceutical application segment requires specialized packaging systems because injectable medicines, vaccines, biologics, and other sensitive products must remain protected from contamination and interaction with the container throughout their intended shelf life. The segment includes vials and ampoules as well as prefilled syringes and other specialized primary-container systems.
Demand is supported by the continued development of biologics and complex injectable therapies. Pharmaceutical manufacturers increasingly require packaging with controlled dimensional characteristics, high chemical resistance, low extractables and leachables, and strong container-closure performance. These requirements create higher technical barriers than many conventional food and beverage packaging applications.
SCHOTT Pharma provides a current illustration of this trend. In February 2026, the company reported first-quarter fiscal 2026 revenue of EUR 240.2 million, up 4.8% at constant currencies. Its Drug Containment Solutions segment, which includes glass vials, ampoules, and cartridges for injectable drugs, generated EUR 137.2 million, increasing 9.4% at constant currencies. The company also reported continued demand for sterile cartridges and specialty vials.
In January 2026, SCHOTT Pharma launched EVERIC lyo & amber vials for light-sensitive antibody-drug conjugates. The company stated that the vial is designed for lyophilized, light-sensitive medicines and provides primary-packaging-level light protection.
In April 2026, SCHOTT Pharma announced cartriQ BioPure, a sterile glass cartridge designed for sensitive biologics. The product complements the company's EVERIC pure vials and syriQ BioPure syringes and is intended for complex biologics including monoclonal antibodies and fusion proteins.
In June 2026, SCHOTT Pharma inaugurated expanded vial production capacity at its Lebanon, Pennsylvania facility. The company reported an investment exceeding USD 60 million, supported by the Biomedical Advanced Research and Development Authority, to expand production of standard and sterile ready-to-use glass vials for biologics, vaccines, and other injectable medicines.
These developments demonstrate that pharmaceutical aseptic packaging is increasingly moving toward application-specific container systems rather than standardized packaging alone. The growing complexity of drug formulations is increasing the importance of material compatibility, sterilization, container-closure integrity, and specialized drug-delivery systems.
Aseptic Packaging Market Geographical Analysis
United States Market Analysis
The United States represents a mature but technologically important aseptic packaging market. Demand comes from shelf-stable dairy and beverage products, nutritional products, food applications, and pharmaceutical packaging. The country's large pharmaceutical manufacturing base creates demand for high-value sterile vials, syringes, and other primary packaging formats.
FDA requirements are particularly relevant to food processors using aseptic systems. Commercial processors of applicable low-acid and acidified foods must meet registration and scheduled-process filing requirements, while aseptic operations must maintain commercial sterility across relevant processing and packaging systems.
The United States is also attracting pharmaceutical packaging capacity. SCHOTT Pharma's June 2026 expansion of vial production in Pennsylvania demonstrates continuing investment in domestic sterile-packaging capabilities.
Brazil Market Analysis
Brazil is an important South American market because of its large dairy and food-processing industries and extensive geographic distribution requirements. USDA projects Brazilian cow milk production at 26.2 million metric tons in 2026, up from 25.6 million metric tons in 2025. This production base supports demand for packaging solutions capable of maintaining product quality through long distribution routes.
The Brazilian market is also affected by sustainability and recycling policy. Packaging producers are increasingly required to consider collection, recycling, material recovery, and the broader environmental performance of packaging structures. These factors support development of packaging formats with improved material recovery characteristics.
Germany Market Analysis
Germany is an important European market for aseptic packaging technology because of its large food-processing industry, advanced manufacturing capabilities, and strong sustainability requirements. The country's regulatory environment is increasingly influenced by European packaging and circular-economy policy.
The EU PPWR generally applies from August 2026, increasing the importance of recyclability, packaging composition, waste prevention, and recovery characteristics. For aseptic packaging suppliers, this creates incentives to improve material compatibility with existing and emerging recycling systems.
Saudi Arabia Market Analysis
Saudi Arabia represents an important Middle Eastern market for shelf-stable food and beverage packaging. Food-security priorities, local food-processing investment, climatic conditions, and the need to distribute products across a large territory support demand for packaging that can provide extended shelf life without depending entirely on refrigerated distribution.
The development of local food manufacturing capacity also increases the importance of regional packaging and filling infrastructure. Suppliers with local technical support, filling-equipment expertise, and reliable material supply can therefore gain an advantage in the market.
China Market Analysis
China is a major aseptic packaging market supported by its large food-processing and beverage industries. USDA projects China's cow milk production at 40.6 million metric tons in 2026, maintaining a substantial domestic dairy-processing base.
The Chinese market is also characterized by strong local manufacturing capabilities and high demand for packaged dairy, beverages, and convenient food products. Packaging suppliers are increasingly balancing cost efficiency with recyclability, lightweighting, barrier performance, and automated filling technologies.
India Market Analysis
India has become an increasingly important market for aseptic packaging because of its large dairy industry, expanding beverage sector, growing food-processing capacity, and increasing urban consumption. USDA projects India's cow milk production at 105.4 million metric tons in 2026, making it one of the largest milk-producing markets globally.
Packaging capacity is also expanding. SIG's Ahmedabad aseptic carton plant became fully operational in December 2025 following a reported EUR 90 million investment, strengthening local supply for dairy and non-carbonated soft drinks and creating an export-oriented production base for neighboring Asian markets.
India's regulatory environment is also becoming more important for packaging manufacturers. FSSAI's Packaging Regulations cover food-contact materials including paper, cardboard, plastic, glass, metal, and multilayer structures, while amendments and draft amendments indicate continuing regulatory attention to food-contact substances and packaging definitions.
Aseptic Packaging Market Competitive Environment and Analysis
The aseptic packaging market combines packaging materials, filling equipment, processing technology, technical services, and specialized pharmaceutical containers. Competitive positioning therefore depends on more than packaging-material production. Companies with established filling-machine platforms, large installed bases, material expertise, technical service networks, and strong customer relationships can benefit from higher switching barriers.
Competition is also increasingly influenced by sustainability performance. Packaging companies are developing paper-based barriers, aluminum-free structures, lower-carbon raw materials, renewable polymers, and improved recycling systems. The commercial success of these solutions depends on whether they can provide equivalent or sufficiently comparable barrier performance while maintaining filling-line efficiency and product shelf life.
Tetra Pak (Tetra Laval Group)
Tetra Pak remains a major integrated supplier of processing, filling, and packaging solutions for food and beverage manufacturers. Its 2026 product developments demonstrate a strong focus on carton innovation. In April 2026, the company introduced a 1-litre aseptic carton with a paper-based barrier, while in June 2026 it introduced a new 48-ounce Tetra Brik Aseptic Edge size for the United States and Canada, targeting dairy, juice, plant-based, and ready-to-drink coffee applications.
SIG Group AG
SIG competes through aseptic carton systems, filling equipment, bag-in-box systems, spouted pouches, and differentiated packaging formats. Its 2026 announcements show continued emphasis on aseptic systems and regional manufacturing. In April 2026, SIG announced plans to double production capacity at its Querétaro facility to 3 billion packages annually by 2028. In June, the company highlighted its aluminum-free full-barrier carton technology, while in July and August it announced new aseptic filling applications in Indonesia, Europe, and Slovakia.
Elopak ASA
Elopak competes primarily through paper-based liquid packaging solutions for dairy and beverage applications. Its sustainability strategy is increasingly focused on reducing the carbon footprint of carton materials. In June 2026, Elopak announced that it had started sourcing low-carbon aluminum produced using renewable electricity for European carton production. The company reported an 8% reduction in the carbon footprint of its standard aluminum ambient cartons and a reduction from 53 to 49 grams of CO2e per standard aseptic Pure-Pak carton under its stated cradle-to-gate calculation.
Amcor plc
Amcor participates across rigid and flexible packaging and can address aseptic applications through specialized packaging structures and formats. Its competitive relevance is supported by broad material expertise, multinational manufacturing capabilities, and relationships with food, beverage, healthcare, and pharmaceutical customers. Its competitive position is increasingly linked to material efficiency, recyclability, lightweighting, and compliance with evolving packaging regulations.
SCHOTT AG / SCHOTT Pharma
SCHOTT is particularly relevant to the pharmaceutical side of the aseptic packaging ecosystem through specialized glass containers, vials, ampoules, cartridges, and syringes. Its 2026 product and capacity developments show continued investment in high-value drug-containment systems. The company reported strong demand for sterile cartridges and specialty vials in its first fiscal quarter of 2026 and subsequently expanded U.S. vial capacity.
Other relevant participants include Greatview Aseptic Packaging/NewJF Group, Ecolean AB, Jet Technologies, and International Paper, with competitive relevance varying by product format, geography, technology, and customer segment. The market-share analysis should distinguish between companies with direct aseptic packaging exposure and diversified packaging groups whose total corporate revenues include substantial non-aseptic activities.
Aseptic Packaging Market Developments:
August 2026: SIG announced that its H1 2026 adjusted EBIT margin increased to 15.6% from 14.8% in the prior-year period and stated that the company continued sharpening its focus on aseptic system solutions. SIG also confirmed its full-year 2026 guidance.
June 2026: Elopak began sourcing low-carbon aluminum produced with renewable electricity for European carton production. The company reported an 8% reduction in the carbon footprint of its standard aluminum ambient cartons and a reduction to 49 grams of CO2e per standard aseptic Pure-Pak carton under its stated methodology.
June 2026: SCHOTT Pharma inaugurated expanded vial production capacity at its Lebanon, Pennsylvania facility following an investment exceeding USD 60 million, supported by BARDA. The new lines produce standard and sterile ready-to-use glass vials for biologics, vaccines, and injectable medicines.
April 2026: Tetra Pak and Sterilgarda Alimenti launched a 1-litre aseptic carton using a paper-based barrier. Tetra Pak stated that the package can reach 90% renewable content when combined with plant-based polymers and can reduce carbon footprint by up to 50% against the referenced conventional packaging solution.
Aseptic Packaging Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 90.1 billion |
| Total Market Size in 2031 | USD 132.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Packaging Material, Product, Application, Geography |
| Companies |
|
Market Segmentation
By Packaging Material
- Paper & Paperboard
- Plastic
- Glass
- Metal
- Others
By Product
- Cartons
- Bottles & Cans
- Bags & Pouches
- Prefilled Syringes
- Vials & Ampoules
- Others
By Application
- Food
- Beverages
- Pharmaceuticals
- Others
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Others
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Others
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base Year and Forecast Period
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Data Collection and Analysis
2.3. Data Validation and Triangulation
2.4. Market Size Estimation and Forecasting
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. ASEPTIC PACKAGING MARKET BY PACKAGING MATERIAL
5.1. Introduction
5.2. Paper & Paperboard
5.3. Plastic
5.4. Glass
5.5. Metal
5.6. Others
6. ASEPTIC PACKAGING MARKET BY PRODUCT
6.1. Introduction
6.2. Cartons
6.3. Bottles & Cans
6.4. Bags & Pouches
6.5. Prefilled Syringes
6.6. Vials & Ampoules
6.7. Others
7. ASEPTIC PACKAGING MARKET BY APPLICATION
7.1. Introduction
7.2. Food
7.3. Beverages
7.4. Pharmaceuticals
7.5. Others
8. ASEPTIC PACKAGING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Packaging Material
8.2.2. By Product
8.2.3. By Application
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Packaging Material
8.3.2. By Product
8.3.3. By Application
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Packaging Material
8.4.2. By Product
8.4.3. By Application
8.4.4. By Country
8.4.4.1. United Kingdom
8.4.4.2. Germany
8.4.4.3. France
8.4.4.4. Spain
8.4.4.5. Italy
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Packaging Material
8.5.2. By Product
8.5.3. By Application
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. South Africa
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Packaging Material
8.6.2. By Product
8.6.3. By Application
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. India
8.6.4.4. South Korea
8.6.4.5. Australia
8.6.4.6. Indonesia
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Greatview Aseptic Packaging Company Limited / NewJF Group
10.2. Tetra Pak (Tetra Laval Group)
10.3. Amcor plc
10.4. Ecolean AB
10.5. Sealed Air Corporation
10.6. Jet Technologies
10.7. SIG Group AG
10.8. International Paper
10.9. SCHOTT AG
10.10. Elopak ASA
LIST OF TABLES
LIST OF FIGURES
Navigate
Trusted by the world's leading organizations











