
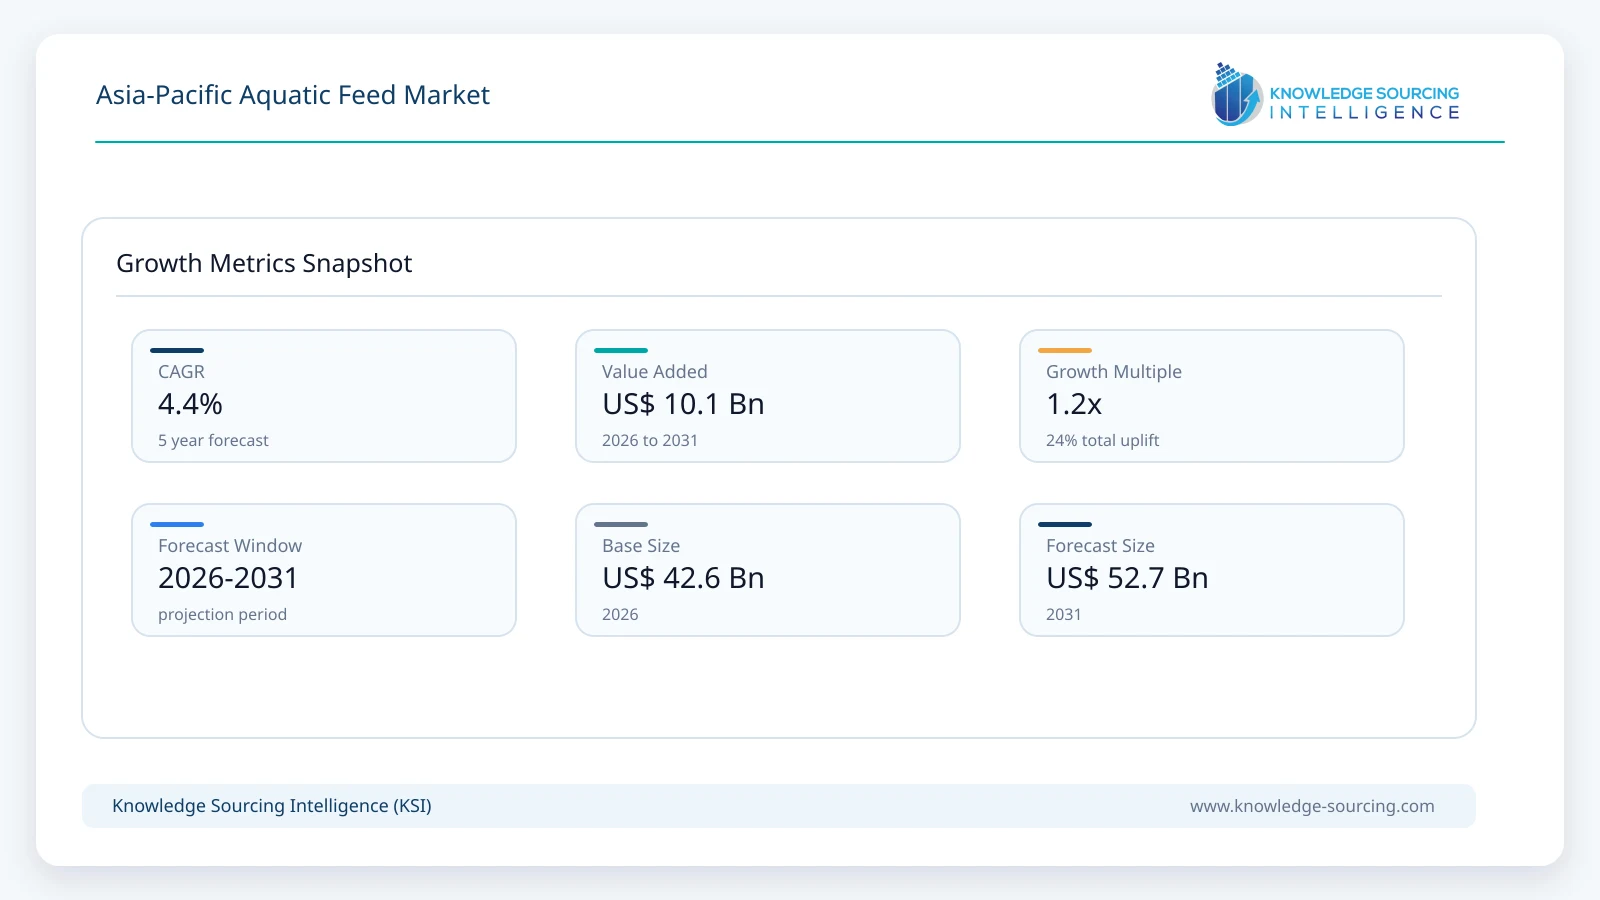
The Asia Pacific (APAC) Aquatic Feed Market is expected to expand at a CAGR of 4.4%, reaching USD 52.7 billion in 2031 from USD 42.6 billion in 2026.
Highlights:
- 1Carp feed represents approximately 29% of regional market value in 2026.
- 2Amino-acid-led diets account for around 26% of the attributed 2026 feed mix.
- 3Shrimp diets remain commercially important as export farms seek reliable survival and feed conversion.
- 4China anchors regional demand through extensive freshwater farming and domestic feed capacity.
- 5India offers faster growth through shrimp nutrition and increasing freshwater feed commercialization.
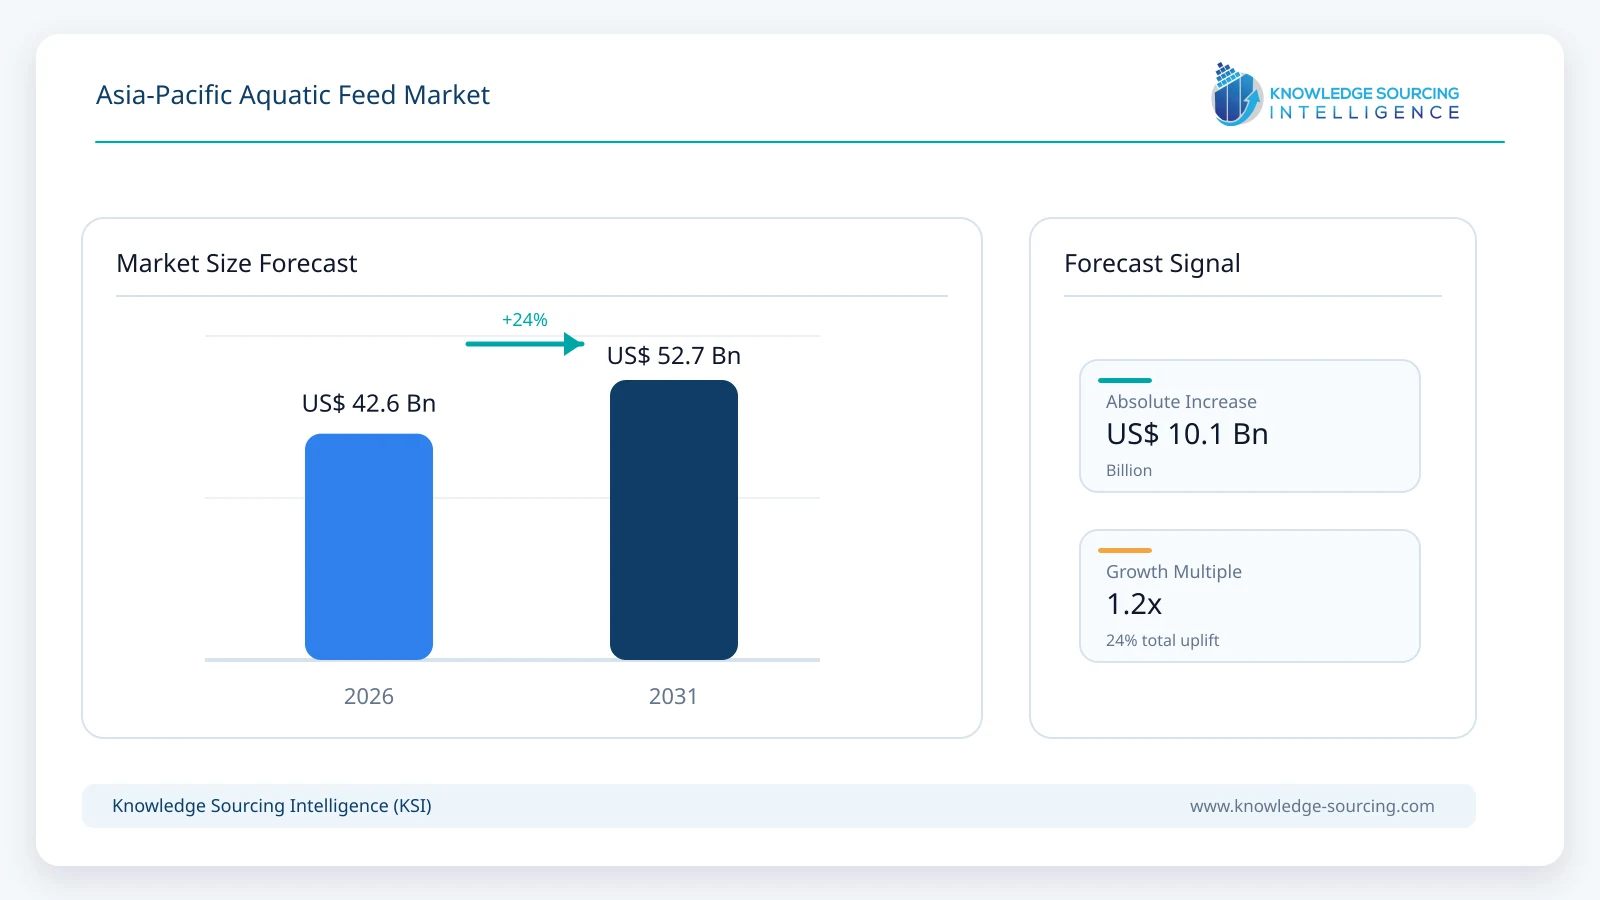
The Asia-Pacific aquatic feed market comprises commercially manufactured feeds sold for farmed aquatic animals, including grow-out rations, nursery and hatchery diets, and specialty formulations for freshwater fish, crustaceans and marine species. Demand is measured at the sale of feed, rather than at the value of harvested seafood or the separate cost of nutrients already incorporated into a finished ration.
Competitive conditions vary by species and country. Bulk carp diets are sensitive to price and local grain supply, whereas shrimp hatcheries and high-value marine farms buy diets on a broader assessment of growth, feed conversion, survival and traceability. Producers such as Avanti Feeds, Thai Union Feedmill, C.P. Vietnam, Skretting and BioMar illustrate the combination of domestic manufacturing scale and research-intensive nutrition that shapes supplier differentiation.
Market Overview
Aquafeed manufacturers convert cereals, oilseed proteins, marine meals, oils, minerals, and functional ingredients into stable pellets or starter diets designed for particular species and feeding conditions. Ingredient selection affects digestibility, water stability and the amount of nitrogen and phosphorus released into ponds. In China's extensive freshwater-fish industry, feed economics are especially exposed to the delivered cost of plant proteins. Shrimp producers in India, Vietnam and Thailand face a different purchasing equation, where inadequate nutrition during stressful growing periods can reduce harvest output and export-grade quality.
FAO's 2026 assessment places Asian farmed aquatic-animal production at 91.5 million tonnes in 2024, including 57.6 million tonnes in China. This is a large production base but not a direct measure of manufactured-feed demand: shellfish and other species may derive much of their nutrition from the water, and some smaller farms continue using supplementary materials. Alltech recorded 37.074 million tonnes of aquaculture feed production in Asia-Pacific in 2024, down 1.7% from the previous year. The difference between rising biological production and temporarily weaker commercial feed tonnage underscores the effect of stocking decisions, weather, fish prices and farmer cash flow on supplier revenue.
Manufacturers are investing in more differentiated feed categories despite these cyclical pressures. Skretting inaugurated a dedicated hatchery-feed line in Zhuhai in April 2025, while BioMar's Wuxi project addresses higher-value fish and nursery diets. In Vietnam, De Heus opened a specialized marine and cold-water fish feed facility in July 2026 and C.P. Vietnam inaugurated another aquaculture feed mill in August. Commercial advantage increasingly depends on how reliably a manufacturer turns formulation expertise and regional factory capacity into lower feed cost per kilogram of saleable fish or shrimp.
Market Trends
Specialty Diets Are Becoming More Important Alongside Bulk Grow-Out Feed
In April 2025 Skretting opened its LifeStart line in Zhuhai, introducing hatchery feeds for salmon, tilapia, golden pompano, snakehead and catfish. That investment addresses a stage at which ration particle size, nutrient availability and water quality can influence later farm performance. BioMar likewise planned a Wuxi line for nursery feeds and high-value species, extending the range available to Chinese growers beyond conventional grow-out pellets.
Specialty feed typically requires tighter process control and stronger technical assistance than commodity rations. Expansion of hatchery and nursery offerings can improve value per tonne even where overall feed tonnage grows more slowly. Adoption nevertheless depends on farmers recognizing sufficient survival and growth benefits to justify higher unit prices.
Marine Protein Substitution Is Being Evaluated Through Feed Performance
Feed manufacturers are reformulating diets as fishmeal and fish-oil availability, plant-protein prices and customer sustainability requirements change. Soy ingredients, novel proteins and improved amino-acid balancing can reduce reliance on scarce marine inputs, but individual species differ in tolerance to alternative raw materials. Shrimp and carnivorous fish present more demanding digestibility and palatability constraints than several freshwater species.
The procurement advantage of an alternative ingredient is not simply a lower purchase price per tonne. Producers must account for inclusion rate, feed-conversion outcomes, pellet behavior and processing yield. Companies with repeatable feeding trials and flexible raw-material purchasing can respond to ingredient-price swings without shifting all formulation risk to the farmer.
Feed Certification Is Becoming Part of Export-Farm Supplier Selection
BioMar Viet-Uc achieved ASC Feed certification in July 2026, linking a Vietnamese fish and shrimp feed factory to an established responsible-sourcing standard. Thai Union Feedmill obtained halal certification for 48 fish and shrimp feed products in August 2026. Although the two schemes serve different commercial requirements, both indicate that feed buyers increasingly examine what lies behind the printed nutrient specification.
Traceability of marine ingredients, social and environmental controls, and reliable batch documentation can influence the supplier shortlist for export-oriented producers. Certification does not automatically create a price premium: commercial advantage arises when it helps farmers meet purchaser specifications while maintaining competitive feed conversion and supply reliability.
Regional Manufacturing Capacity Is Moving Closer to Specialized Demand
C.P. Vietnam inaugurated its fourth aquaculture feed mill in the country in August 2026, bringing reported Vietnamese aquafeed capacity within the group to more than 650,000 tonnes annually. De Heus separately opened a 168,000-tonne-per-year facility in Vinh Long for marine and cold-water fish feed. These investments highlight the importance of distribution distance, freshness and production-line suitability to different feed types.
New capacity can strengthen competition where farmers previously relied on a small supplier base. It also raises the risk of underutilized mills during disease outbreaks or weak farm-gate prices. Operators with several species and customer channels are better placed to balance seasonal feed demand than manufacturers dependent on one shrimp crop or one export market.
Segment Analysis
By End-User: Carps
Carp farming represents the largest volume-oriented feed demand group in the regional market. Commercial feeds for common, grass and other cultured carp varieties are manufactured close to major freshwater farming districts, particularly in China and parts of South Asia. The segment is shaped by broad consumption demand, established pond-farming systems and a strong requirement for affordable protein and energy inputs rather than the extreme nutritional density needed in marine hatcheries.
Carp feed revenue is projected to reach approximately USD 14.23 billion in 2031. Its relative weight moderates as formulated whiteleg-shrimp and tilapia feeds gain ground, particularly where farmers intensify feeding and move away from traditional supplementary ingredients. Suppliers must maintain pellet quality and stable production costs while demonstrating that feed efficiency offsets changes in grain and oilseed meal prices.
By Additives: Amino Acids
Amino-acid-oriented feed formulations are projected to account for approximately USD 14.76 billion of regional finished-feed revenue by 2031. Methionine, lysine and other essential amino acids are incorporated to balance available proteins, particularly when manufacturers substitute some marine meals with terrestrial or alternative protein sources. Their commercial relevance is tied to the finished diet's digestible nutrient profile and fish or shrimp performance, not to an independent sale of the additive on top of feed revenue.
Avanti Feeds and multinational aquafeed formulators adjust feed specifications against growth stage, feed conversion and ingredient availability. Amino-acid balance can become more valuable as customers seek lower crude-protein formulations without sacrificing harvest output or increasing nitrogen discharge. Formulators still need species-specific validation because a nominally complete amino-acid profile does not by itself establish digestibility or performance in pond conditions.
Market Drivers
Growth in Commercially Fed Freshwater Aquaculture
China's freshwater-fish production base supports large recurring purchases of compound feed, while expansion of structured tilapia, catfish and carp farms in Southeast and South Asia increases the addressable supply chain. The 2026 FAO assessment confirms that Asia accounts for the overwhelming majority of global farmed aquatic-animal output. Commercial feed demand benefits most where farms replace inconsistent on-farm mixes with purchased diets and adopt more measured feeding schedules. The shift is gradual because the economics of individual species and regions differ substantially.
Export-Oriented Shrimp Production and Harvest Quality
India exported 741,529 tonnes of frozen shrimp during FY2024–25 according to MPEDA, illustrating the scale of export-linked farming activity behind specialist feed purchases. Whiteleg-shrimp producers in India and Vietnam evaluate diets through growth, survival, water stability and consistency of harvested size. Feed manufacturers therefore compete on field support and performance as well as factory output. Export pricing and trade restrictions can rapidly alter pond stocking, making the sector attractive over the medium term but volatile from season to season.
Investments in Local Mills and Feed Distribution
The July and August 2026 plant inaugurations by De Heus and C.P. Vietnam expand access to specialized rations near Vietnamese aquaculture clusters. Shorter delivery routes can improve inventory management and reduce dependence on imported finished pellets, while regional mills can tailor product lines to local species and pond conditions. Capacity utilization remains critical to returns, but facilities built around several fish and shrimp categories create opportunities for broader dealer coverage and technical-service relationships with farm operators.
Higher Value of Hatchery and Nursery Nutrition
Early-life feeds serve smaller production volumes but carry demanding quality specifications. Skretting's LifeStart line in China and BioMar's planned advanced Wuxi production illustrate the supplier focus on particle sizing, nutrient stability and stage-specific products. If hatchery survival and juvenile growth improve, growers may accept higher feed prices because later farming economics are affected. The opportunity favors manufacturers that can document repeatable outcomes and provide field support rather than relying solely on premium nutrient claims.
Improving Traceability and Formulation Discipline
Export aquaculture increasingly requires batch records and documentation of ingredient sourcing and production controls. BioMar Viet-Uc's ASC Feed certification and Thai Union Feedmill's product certification show manufacturers investing in compliance capabilities beyond minimum nutrient specifications. Better traceability can reduce buyer qualification friction and support sales to farms serving demanding retail and foodservice customers. Adoption may also raise testing and documentation costs, but established manufacturers can spread these costs across larger feed volumes.
Market Restraints
Volatile Fishmeal, Fish-Oil and Oilseed Ingredient Costs
Fishmeal, fish oil, soy protein and energy inputs can change sharply in delivered price. Aquafeed producers cannot always pass these movements to farms immediately, particularly when fish or shrimp prices weaken. Lower-cost substitutes require feeding trials and sometimes changes to binding or palatability systems. Margin risk is therefore tied to formulation capability and working capital, not simply to the headline cost of imported ingredients. Smaller manufacturers may be less equipped to absorb sudden procurement shocks.
Disease Outbreaks and Unpredictable Farm Stocking
Shrimp diseases and adverse water conditions can cause producers to harvest early or postpone restocking, immediately reducing feed demand. Alltech reported a 1.7% decline in Asia-Pacific aquafeed production during 2024 despite the region's strong underlying aquaculture position. Feed factories then face lower throughput and greater inventory pressure. Suppliers heavily exposed to a single shrimp-growing district may experience sharper sales swings than manufacturers serving multiple freshwater and marine species.
Feed Affordability in Low-Value Freshwater Species
Commercially prepared diets compete with on-farm ingredients and other supplementary feeding approaches in some low-margin freshwater operations. A higher-priced pellet must deliver sufficiently better harvest efficiency to win repeat purchases, and farmers may reduce feeding intensity when pond-gate prices fall. High-quality product formulations alone do not eliminate these constraints. Distribution economics and access to technical guidance matter, especially across fragmented rural districts with small order sizes.
Environmental Limits and Responsible Sourcing Requirements
Nutrient-rich discharges and sediment loading can restrict intensification in sensitive inland and coastal farming areas. Feed manufacturers face additional scrutiny over traceability of marine ingredients and labor or environmental conditions in supply chains. These requirements encourage more precise formulations but also increase laboratory analysis, documentation and supplier-qualification expenditure. Where farms cannot invest in better water management, feed productivity benefits may be limited even when a higher-specification ration is available.
Excess Mill Capacity and Price Competition
The addition of sophisticated production lines in Vietnam and China creates more feed options for commercial farmers, but equipment returns depend on sustained utilization. A poor production season can leave mills competing for the same available tonnage, compressing realization per tonne and encouraging generous dealer credit. Production advantages are most durable when manufacturers pair scale with proven feed performance and diversified species exposure. A simple increase in installed capacity is not sufficient evidence of proportional market revenue growth.
Geographical Outlook
China accounts for approximately 49% of the region's aquatic feed market in 2026, supported by large freshwater aquaculture production, integrated feed manufacturing and growing demand for specialty diets for marine and high-value freshwater species. FAO records 57.6 million tonnes of farmed aquatic animals in China in 2024, although a material share of that output does not translate proportionately into purchased feed. Feed mills compete across commodity carp rations, marine finfish products and hatchery nutrition, with different realized prices and technical-service demands.
BioMar's Wuxi expansion and Skretting's Zhuhai LifeStart investment demonstrate how suppliers seek higher-value opportunities within an already extensive feed industry. Local mills benefit from proximity to growers but face competition on formulation costs and feeding outcomes. A broader product mix should support value growth, while the sheer scale and mature character of the market temper its expected pace relative to smaller, more rapidly commercializing countries.
India is the fastest-growing large country market in the regional forecast, with modeled annual growth of approximately 9.96% between 2026 and 2031. Its shrimp farms purchase specialized grow-out feed, while cultured freshwater fish represent a longer-term avenue for greater use of factory-made rations. Avanti Feeds recorded around 550,000 tonnes of shrimp feed sales in FY2024–25, demonstrating the presence of an established domestic manufacturing base rather than a market dependent entirely on imports.
Shrimp-export exposure makes farmer stocking sensitive to prices in major overseas markets. At the same time, better hatchery practices, dealer reach and formulation support can expand commercially fed production. The country's growth case rests on increasing participation by domestic freshwater farms and more demanding shrimp nutrition, rather than assuming that export volumes or feed utilization improve every year without interruption.
Competitive Landscape
Competition is split between national high-volume mills and multinational suppliers with established specialty-feed formulation and production networks. China's Tongwei operates within a large freshwater-fish ecosystem; Indian producers such as Avanti Feeds, Growel Feeds, Godrej Agrovet and The Waterbase address shrimp and fish farmers through domestic manufacturing and technical support. In Thailand and Vietnam, Thai Union Feedmill, Charoen Pokphand Foods, Grobest and other regional manufacturers combine feed processing with extensive aquaculture customer relationships.
Skretting, BioMar, De Heus and Cargill compete on nutrition programs, hatchery products, quality systems and sourcing. BioMar's collaboration with Tongwei in China illustrates joint-venture access to regional manufacturing, while its ASC-certified Vietnamese facility strengthens traceability credentials. De Heus' new Vietnamese mill targets higher-value marine and cold-water fish categories rather than merely adding generic pellet capacity. The competitive comparison therefore involves species expertise, cost per kilogram of fish produced, distribution coverage and qualifying documentation, not an unsupported ranking of company market shares.
Feed manufacturers increasingly compete through farmer services as well as the sale of rations. Trial support, water-quality advice and feeding schedules can help demonstrate the value of a formulation. Producers with weak access to farms may lose volume to established local distributors even with competitive product specifications. Conversely, premium feed providers can face resistance when cash-constrained growers prioritize lower upfront spending.
Recent Developments
11 August 2026: Thai Union Feedmill announced halal certification for 48 shrimp and fish feed SKUs, widening the qualifications of its commercial aquafeed portfolio for regional customers.
7 August 2026: C.P. Vietnam inaugurated its Ca Mau Aquaculture Feed Mill, its fourth in Vietnam, bringing the group's reported local aquafeed capacity above 650,000 tonnes per year.
22 July 2026: De Heus inaugurated a marine and cold-water fish feed mill in Vinh Long, Vietnam, designed for 168,000 tonnes of annual production capacity.
22 July 2026: BioMar reported that its Viet-Uc aquafeed facility had achieved ASC Feed certification, extending certified production within its Asian network.
11 February 2026: BioMar announced a Wuxi expansion intended to add 50,000 tonnes of annual capacity, with commissioning expected in the first quarter of 2027.
17 April 2025: Skretting opened a dedicated LifeStart feed production line in Zhuhai, China, and introduced five new hatchery-feed products for farmed fish species.
Market Outlook
Asia-Pacific aquatic feed revenue through 2031 will depend on a combination of commercially fed fish and shrimp volumes, product mix and feed prices. China's established freshwater market will remain the largest source of regional demand, while India and selected Southeast Asian countries offer greater scope for growth through farm intensification and wider use of formulated feeds. Disease conditions and seafood prices will continue to influence annual purchases more immediately than general population or seafood-consumption trends.
Manufacturers positioned to supply both affordable grow-out diets and reliable specialized nutrition are better placed to protect sales across market cycles. Investment in hatchery feeds, species-specific mills and traceable sourcing can increase technical differentiation, but sustained returns will still depend on proven farm performance and disciplined plant utilization. Competition is likely to strengthen around consistent feed conversion, effective ingredient substitution and access to farmers rather than capacity additions alone.
Asia-Pacific (APAC) Aquatic Feed Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 42.6 billion |
| Total Market Size in 2031 | USD 52.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | End-user, Additives, Country |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By End-user
Litopenaeus vannamei
Carps
Shrimp (other than L. vannamei)
Tilapia
Mollusks
Catfish
Salmon
Lobsters
Others
By Additives
Antibiotics
Vitamins
Antioxidants
Amino Acids
Feed Enzymes
Feed Acidifiers
By Country
China
Japan
India
South Korea
Indonesia
Vietnam
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Asia Pacific (APAC) Aquatic Feed Market Size, 2026–2031
1.3. End-User Outlook
1.4. Additives Outlook
1.5. Country Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Growth in Commercially Fed Freshwater Aquaculture
3.1.2. Export-Oriented Shrimp Production and Harvest Quality
3.1.3. Investments in Local Mills and Feed Distribution
3.1.4. Higher Value of Hatchery and Nursery Nutrition
3.1.5. Improving Traceability and Formulation Discipline
3.2. Market Restraints
3.2.1. Volatile Fishmeal, Fish-Oil and Oilseed Ingredient Costs
3.2.2. Disease Outbreaks and Unpredictable Farm Stocking
3.2.3. Feed Affordability in Low-Value Freshwater Species
3.2.4. Environmental Limits and Responsible Sourcing Requirements
3.2.5. Excess Mill Capacity and Price Competition
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Species-Specific Pellet and Hatchery-Feed Technology
4.2. Functional Ingredients and Digestible Amino-Acid Profiles
4.3. Alternative Protein and Oil Formulation
4.4. Feed Performance Monitoring and Quality Assurance
5. ASIA PACIFIC (APAC) AQUATIC FEED MARKET BY END-USER
5.1. Introduction
5.2. Litopenaeus vannamei
5.3. Carps
5.4. Shrimp (other than L. vannamei)
5.5. Tilapia
5.6. Mollusks
5.7. Catfish
5.8. Salmon
5.9. Lobsters
5.10. Others
6. ASIA PACIFIC (APAC) AQUATIC FEED MARKET BY ADDITIVES
6.1. Introduction
6.2. Antibiotics
6.3. Vitamins
6.4. Antioxidants
6.5. Amino Acids
6.6. Feed Enzymes
6.7. Feed Acidifiers
7. ASIA PACIFIC (APAC) AQUATIC FEED MARKET BY COUNTRY
7.1. Introduction
7.2. China
7.3. Japan
7.4. India
7.5. South Korea
7.6. Indonesia
7.7. Vietnam
7.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Avanti Feeds Limited
9.2. Godrej Agrovet Limited
9.3. Growel Feeds Private Limited
9.4. The Waterbase Limited
9.5. Grobest Group
9.6. Thai Union Feedmill Public Company Limited
9.7. Charoen Pokphand Foods Public Company Limited
9.8. PT Japfa Comfeed Indonesia Tbk
9.9. Greenfeed Vietnam Corporation
9.10. Cargill, Incorporated
9.11. Nutreco N.V. (Skretting)
9.12. BioMar Group
9.13. De Heus Animal Nutrition
9.14. Tongwei Co., Ltd.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits to Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size of the Asia-Pacific aquatic feed market by 2031?
The Asia-Pacific Aquatic Feed Market is projected to reach USD 52.7 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for APAC aquatic feed (2026-2031)?
The Asia-Pacific Aquatic Feed Market is expected to expand at a 4.4% CAGR.
Which aquatic species feed segment holds the largest share in the APAC market?
Carp feed represents approximately 29% of the regional market value in 2026.
Which country is a primary demand anchor in the Asia-Pacific aquatic feed market?
China anchors regional demand through extensive freshwater farming capacity.
What key ingredient segment comprises a significant portion of the 2026 feed mix?
Amino-acid-led diets account for around 26% of the 2026 feed mix.
Which country offers faster growth opportunities in the APAC aquatic feed market?
India offers faster growth through shrimp nutrition and freshwater feed commercialization.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia-Pacific Aquatic Feed Market Size, Share & Forecast (2026–2031). https://www.knowledge-sourcing.com/report/asia-pacific-apac-aquatic-feed-market