
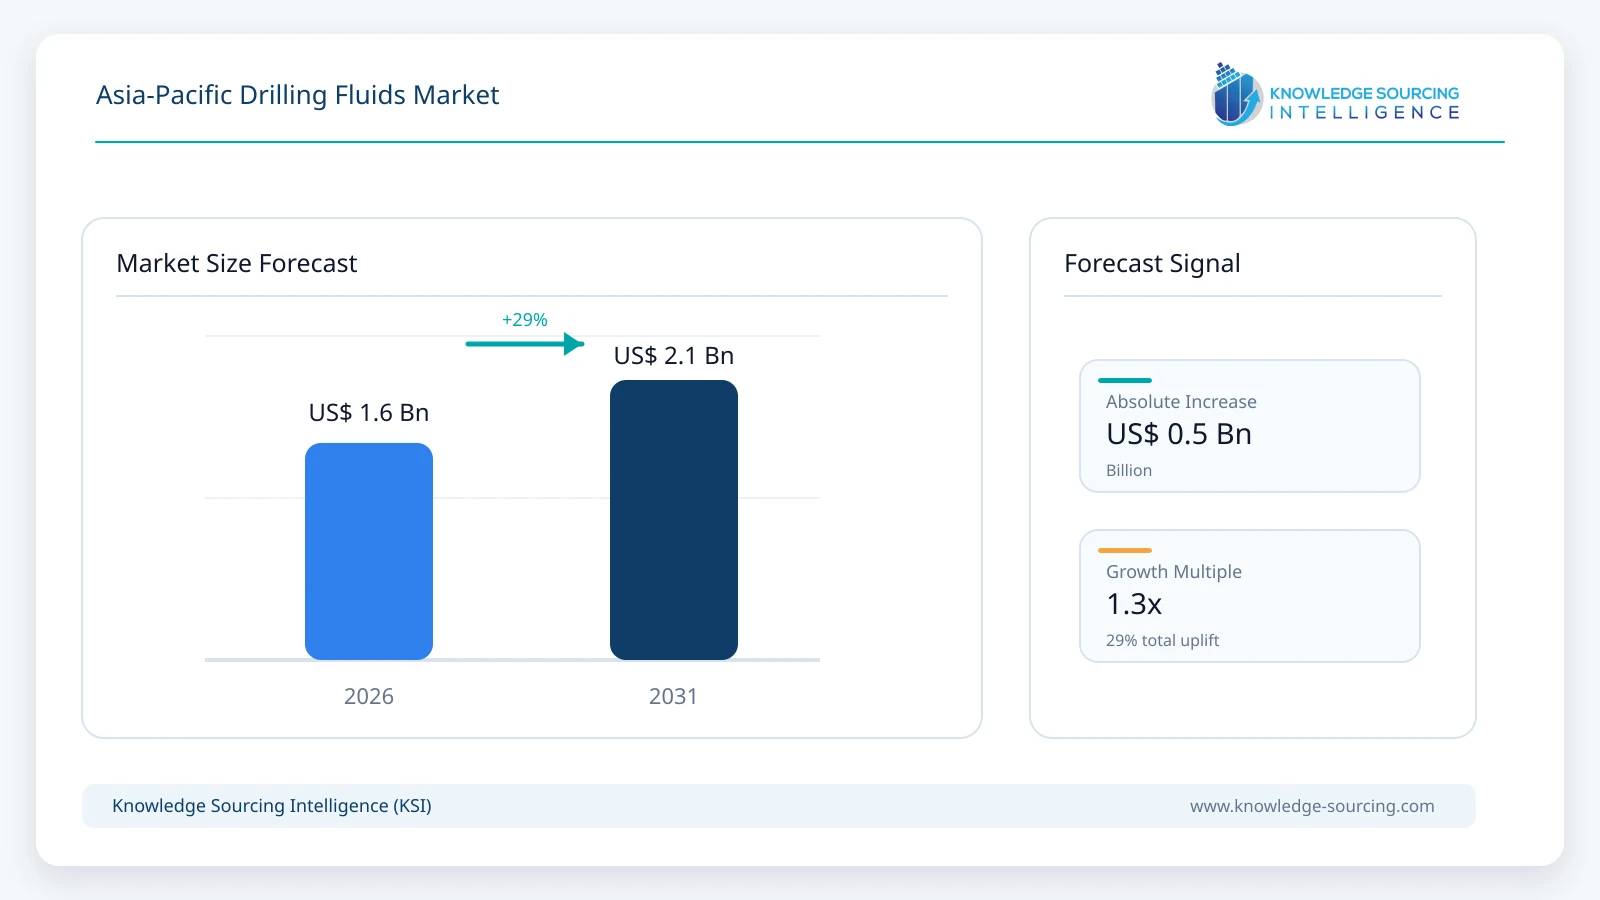
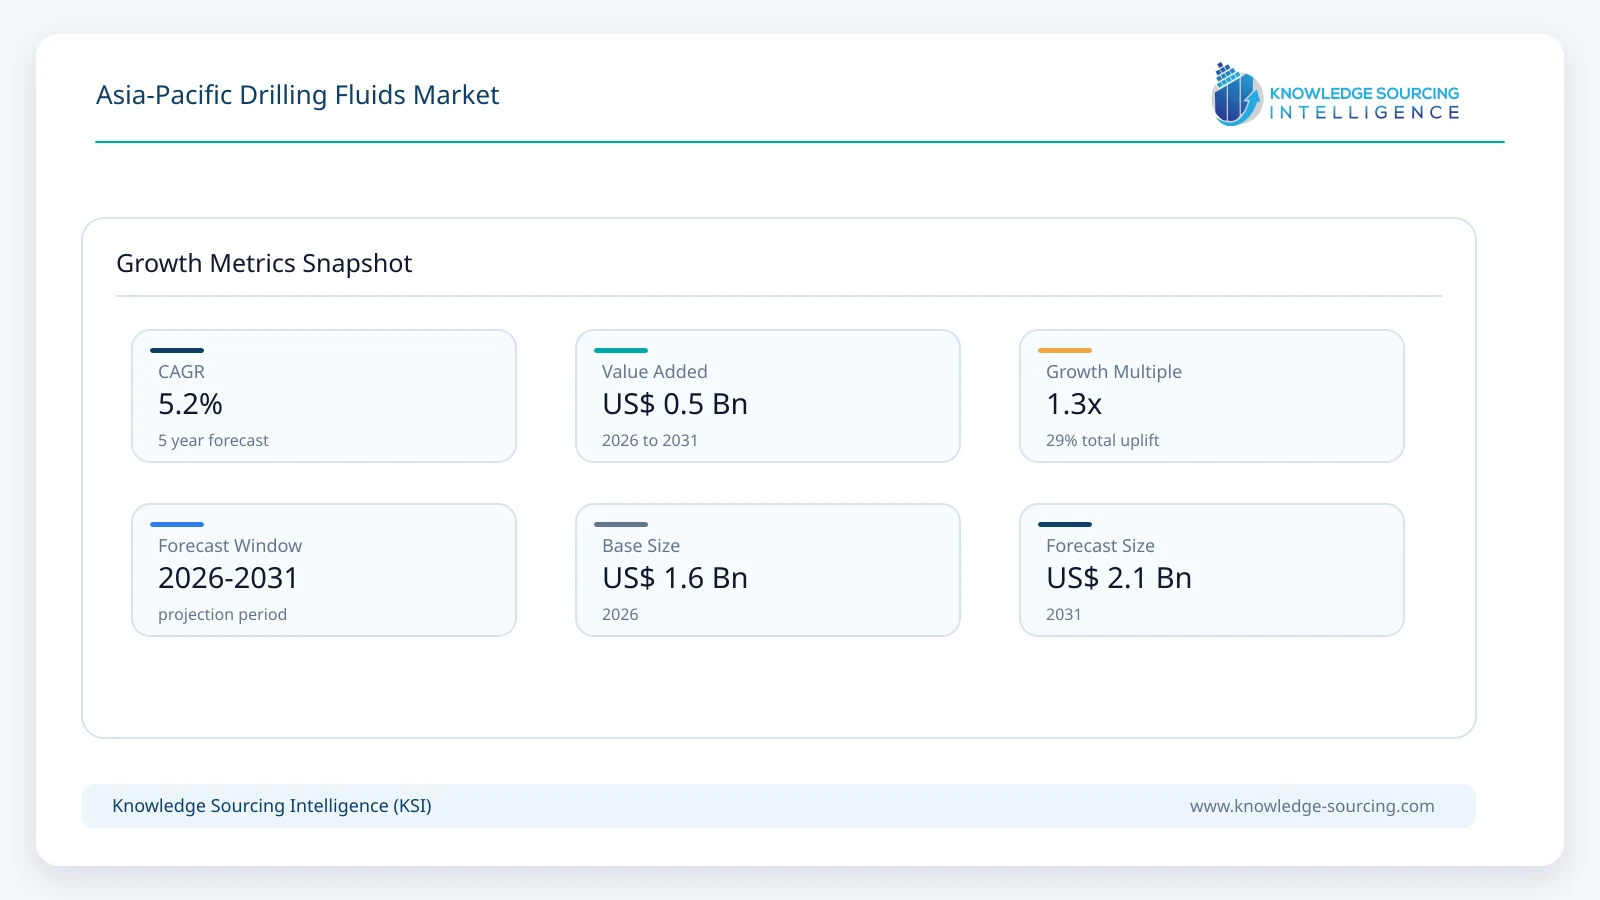
The Asia-Pacific Drilling Fluids market is growing at a CAGR of 5.2%, from USD 1.62 billion in 2026 to USD 2.09 billion by 2031.
Highlights:
- 1Asia Pacific drilling fluids revenue is projected to reach USD 2.09 billion by 2031.
- 2Water-based fluids account for approximately 56% of regional drilling-fluid revenue in 2026.
- 3Offshore drilling applications are projected to grow at approximately 6.3% annually through 2031.
- 4Oil and gas contributes approximately 81% of Asia Pacific drilling-fluids revenue in 2026.
- 5China accounts for approximately 29% of Asia Pacific drilling-fluids revenue in 2026.
- 6Digital fluid monitoring and real-time rheology management are becoming more important in complex wells.
Drilling fluid demand in Asia Pacific is closely linked to the number and complexity of wells drilled, but market value does not move in direct proportion to rig count. Offshore, high-pressure/high-temperature, extended-reach and depleted-reservoir wells require more sophisticated fluid formulations, higher service intensity and tighter real-time control than conventional land wells. This raises revenue per well even when the active rig base is broadly stable. In 2025, CNOOC drilled 202 exploration wells offshore China and another 123 exploration wells onshore, illustrating the scale of ongoing Chinese exploration activity. Halliburton also reported higher drilling-related services in Indonesia during 2025, while SLB noted stronger drilling activity in China during the second quarter of 2026.
Regional demand differs materially by application. Oil and gas customers purchase complete water-based, oil-based and synthetic-based systems together with engineering support, solids control and waste-management services. Mining customers in Australia, Indonesia and other mineral-producing markets use lower-viscosity polymer systems, lubricants, shale-control products and other additives to improve core recovery, hole stability and drilling productivity. IMDEX, through its AMC product portfolio, reported an uplift in fluids activity across Asia during FY2026, while Australian suppliers such as Mudex and Tiger Fluids continue to target mining, geothermal, HDD and other drilling applications. The result is a market with large integrated oilfield service companies at the high-specification end and a broad regional supplier base competing in additives, packaged fluid systems and specialized mining formulations.
Market Trends
High-performance water-based systems are displacing conventional non-aqueous fluids in selected wells
Environmental constraints and waste-handling costs are increasing the commercial appeal of advanced water-based drilling fluids where these systems can deliver sufficient shale inhibition, lubricity and thermal stability. The shift is not uniform because deepwater and narrow-margin wells may still require non-aqueous systems, but suppliers are increasingly designing water-based formulations for applications that historically relied on oil- or synthetic-based mud. Baker Hughes markets high-performance water-based systems for deepwater, extended-reach and HPHT applications, while Halliburton Baroid and SLB's M-I SWACO maintain comparable technology platforms. This product transition is particularly relevant in Australia and offshore Asia, where operators place a high value on fluid performance, waste minimization and environmental-plan compliance.
Digital fluid monitoring is moving from reporting toward active drilling optimization
Fluid management is becoming more data-driven as operators use real-time measurements of density, rheology, temperature and flow behavior to reduce manual testing delays and improve wellbore control. Baker Hughes' current fluids portfolio includes real-time monitoring and reporting through its Kantori fluid-management service, while major service providers increasingly combine hydraulics software, digital modeling and field chemistry. In complex wells, the commercial value is tied to reducing non-productive time, minimizing unnecessary dilution and maintaining equivalent circulating density within narrow operating windows. This favors suppliers that can integrate chemistry, field engineering and digital monitoring rather than compete only on the price of bulk additives.
Market Drivers
Offshore and technically complex drilling programs increase fluid value per well
The strongest driver is the increasing technical intensity of drilling programs rather than a broad rise in rig count. Offshore China, India's western offshore basins, Indonesian fields and Australian gas developments include extended-reach, HPHT, depleted and deepwater wells that require stable rheology, strong shale inhibition, controlled equivalent circulating density and effective lost-circulation management. These conditions increase the quantity and specification of emulsifiers, polymers, weighting agents, lubricants and fluid-loss-control products used per well. Halliburton has documented HPHT fluid applications in India's western offshore basin, while CNOOC's 2025 exploration program included more than 200 offshore exploration wells. As operators prioritize drilling efficiency and lower non-productive time, higher-performance formulations can gain revenue even when the regional rig count remains relatively flat.
Mining and geothermal drilling broaden demand beyond conventional oil and gas
Asia Pacific contains some of the world's largest mineral exploration and mining markets, led by Australia and supported by copper, nickel, lithium, gold and other exploration programs across Southeast Asia. Core drilling uses specialized fluids to stabilize formations, improve cuttings transport, reduce torque and protect sample quality, creating a distinct demand pool from conventional oilfield mud systems. IMDEX reported that fluid activity improved in Asia during FY2026, with signs of recovery in Indonesia, and its AMC portfolio continues to target mineral drilling and drilling optimization. Geothermal development in Indonesia, the Philippines, Japan and other markets creates an additional niche for high-temperature fluid systems. These applications are smaller than oil and gas in value but provide faster-growing opportunities for specialized regional suppliers.
Market Restraint
Dependence on drilling activity and project timing limits volume growth
Drilling fluids are consumed directly with drilling activity, making the market sensitive to rig utilization, operator capital budgets and the timing of exploration campaigns. Baker Hughes data show that the Asia Pacific rig count averaged about 207 rigs in 2025 compared with roughly 223 in 2024, and the August 2026 count stood at 201. Lower rig activity can quickly reduce demand for commodity fluid volumes, especially in conventional land drilling. Offshore project delays can have a similar effect because a small number of high-value programs account for meaningful service revenue. Suppliers therefore face uneven utilization of blending facilities and field personnel, while regional manufacturers must also manage volatility in barite, bentonite, base oils, polymers and specialty chemical costs when customer activity slows.
Segment Analysis
By Fluid Type - Water-Based Fluids
Water-based fluids remain the largest product category, accounting for approximately 56% of Asia Pacific drilling fluids revenue in 2026 and projected to reach about USD 1.20 billion by 2031. Their position is supported by broad use in conventional onshore wells, top-hole offshore sections, mining, geothermal and other drilling applications, together with lower disposal complexity than oil-based systems. Product development is moving toward high-performance water-based formulations that provide stronger inhibition, lubricity and thermal stability in formations where conventional water-based muds previously underperformed. This allows operators to retain the cost and environmental advantages of water-based systems across a wider operating envelope. Oil- and synthetic-based fluids remain important in highly reactive shales, deepwater and other technically difficult wells where wellbore stability and lubricity justify their higher cost.
By Application - Offshore Drilling
Offshore drilling is projected to expand at approximately 6.3% annually between 2026 and 2031, reaching about USD 0.88 billion in regional drilling-fluids revenue by 2031. Offshore wells generate higher fluid revenue per well because of deeper sections, longer drilling durations, more demanding pressure-temperature conditions and stricter requirements for solids control, fluid recovery and waste management. China contributes substantial activity through the Bohai Sea, South China Sea and other offshore basins, while India, Indonesia, Malaysia, Thailand, Vietnam and Australia support additional demand. Offshore projects also create stronger opportunities for synthetic-based systems, high-density fluids, specialized lost-circulation materials and real-time fluid engineering, making this segment disproportionately important to the major international oilfield service companies.
By End User - Oil and Gas
Oil and gas remains the principal end-user, accounting for approximately 81% of Asia Pacific drilling-fluids revenue in 2026 and projected to generate about USD 1.71 billion by 2031. Demand is distributed across national oil companies, international operators and independent producers, with China and India providing large domestic drilling programs and Southeast Asia contributing a mixture of mature-field redevelopment and offshore exploration. The segment increasingly rewards technology capable of reducing non-productive time rather than simply lowering fluid cost per barrel. Wellbore-strengthening materials, high-temperature polymers, shale inhibitors, advanced non-aqueous systems and digital fluid monitoring are therefore capturing a larger portion of spending in complex wells. Mining remains the smaller end-user segment but grows faster from a lower base as mineral exploration and production drilling expand.
By Country - China
China accounts for approximately 29% of Asia Pacific drilling fluids revenue in 2026 and is projected to generate about USD 0.64 billion by 2031, making it the largest country market. The scale reflects domestic onshore drilling that is not fully captured in international rig-count statistics, a substantial offshore program and a large local oilfield-services and chemical-manufacturing base. CNOOC reported 202 offshore exploration wells and 123 onshore exploration wells in 2025, while COSL provides drilling and completion fluids services in China and international Asia Pacific markets. Continued development of offshore oil, deep gas and unconventional resources supports demand for high-performance water-based, oil-based and completion-compatible fluid systems. India follows as another major market, while Australia, Indonesia and Malaysia remain important because of offshore, mining and technically challenging drilling activity.
Competitive Environment
The market combines global integrated oilfield service companies, large regional service providers and specialized chemical manufacturers. SLB's M-I SWACO, Halliburton Baroid and Baker Hughes compete in high-specification oil and gas wells through integrated fluid engineering, field services, digital tools and extensive additive portfolios. China Oilfield Services Limited has a strong domestic and regional position, while Newpark Fluids Systems continues as a dedicated drilling-fluids business under SCF Partners following its 2024 divestiture from Newpark Resources.
Regional competition is broader in India and Australia. IMDEX's AMC portfolio is strongly positioned in mining and exploration drilling, while Gumpro Drilling Fluids, Global Drilling Fluids & Chemicals and Universal Drilling Fluids manufacture specialty products and complete fluid systems in India. Mudex and Tiger Fluids serve mining, geothermal, HDD and other drilling applications from Australia and Singapore. Competitive advantage differs by customer type: offshore operators prioritize field engineering, technical qualification and reliability, while mining and land-drilling customers place greater weight on product availability, logistics, technical support and delivered cost.
Recent Developments
August 2026: IMDEX reported record FY2026 revenue and highlighted an uplift in fluids activity across Asia, with signs of recovery in Indonesia and continued growth in its drilling-optimization portfolio.
January 2026: Halliburton reported improved drilling-related services activity in Indonesia during 2025, alongside higher stimulation activity in India, supporting demand for well-construction chemicals and services.
Asia-Pacific Drilling Fluids Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.62 billion |
| Total Market Size in 2031 | USD 2.09 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Fluid Type, Application, End-User, Country |
| Companies |
|
Market Segmentation
By Fluid Type
Water-Based Fluids
Oil-Based Fluids
Synthetic-Based Fluids
Others
By Application
Onshore Drilling
Offshore Drilling
By End User
Oil and Gas
Mining
By Country
China
India
Australia
Indonesia
Malaysia
Thailand
Vietnam
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Offshore and Technically Complex Drilling Programs Increase Fluid Value per Well
3.1.2. Mining and Geothermal Drilling Broaden Demand Beyond Conventional Oil and Gas
3.2. Market Restraint
3.2.1. Dependence on Drilling Activity and Project Timing Limits Volume Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. High-Performance Water-Based Fluid Systems
4.2. Digital Fluid Monitoring and Real-Time Rheology
4.3. HPHT and Deepwater Fluid Technologies
5. ASIA PACIFIC DRILLING FLUIDS MARKET BY FLUID TYPE
5.1. Introduction
5.2. Water-Based Fluids
5.3. Oil-Based Fluids
5.4. Synthetic-Based Fluids
5.5. Others
6. ASIA PACIFIC DRILLING FLUIDS MARKET BY APPLICATION
6.1. Introduction
6.2. Onshore Drilling
6.3. Offshore Drilling
7. ASIA PACIFIC DRILLING FLUIDS MARKET BY END USER
7.1. Introduction
7.2. Oil and Gas
7.3. Mining
8. ASIA PACIFIC DRILLING FLUIDS MARKET BY COUNTRY
8.1. Introduction
8.2. China
8.3. India
8.4. Australia
8.5. Indonesia
8.6. Malaysia
8.7. Thailand
8.8. Vietnam
8.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. SLB Limited (M-I SWACO)
10.2. Halliburton Company (Baroid)
10.3. Baker Hughes Company
10.4. Newpark Fluids Systems
10.5. China Oilfield Services Limited (COSL)
10.6. IMDEX Limited (AMC Drilling Optimisation)
10.7. Gumpro Drilling Fluids Pvt. Ltd.
10.8. Global Drilling Fluids & Chemicals Limited
10.9. Universal Drilling Fluids
10.10. Mudex
10.11. Tiger Fluids
10.12. Innova Corporate (India)
10.13. Coho Resources
10.14. Sinopec Oilfield Service Corporation
10.15. PetroChina / CNPC Oilfield Services
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











