
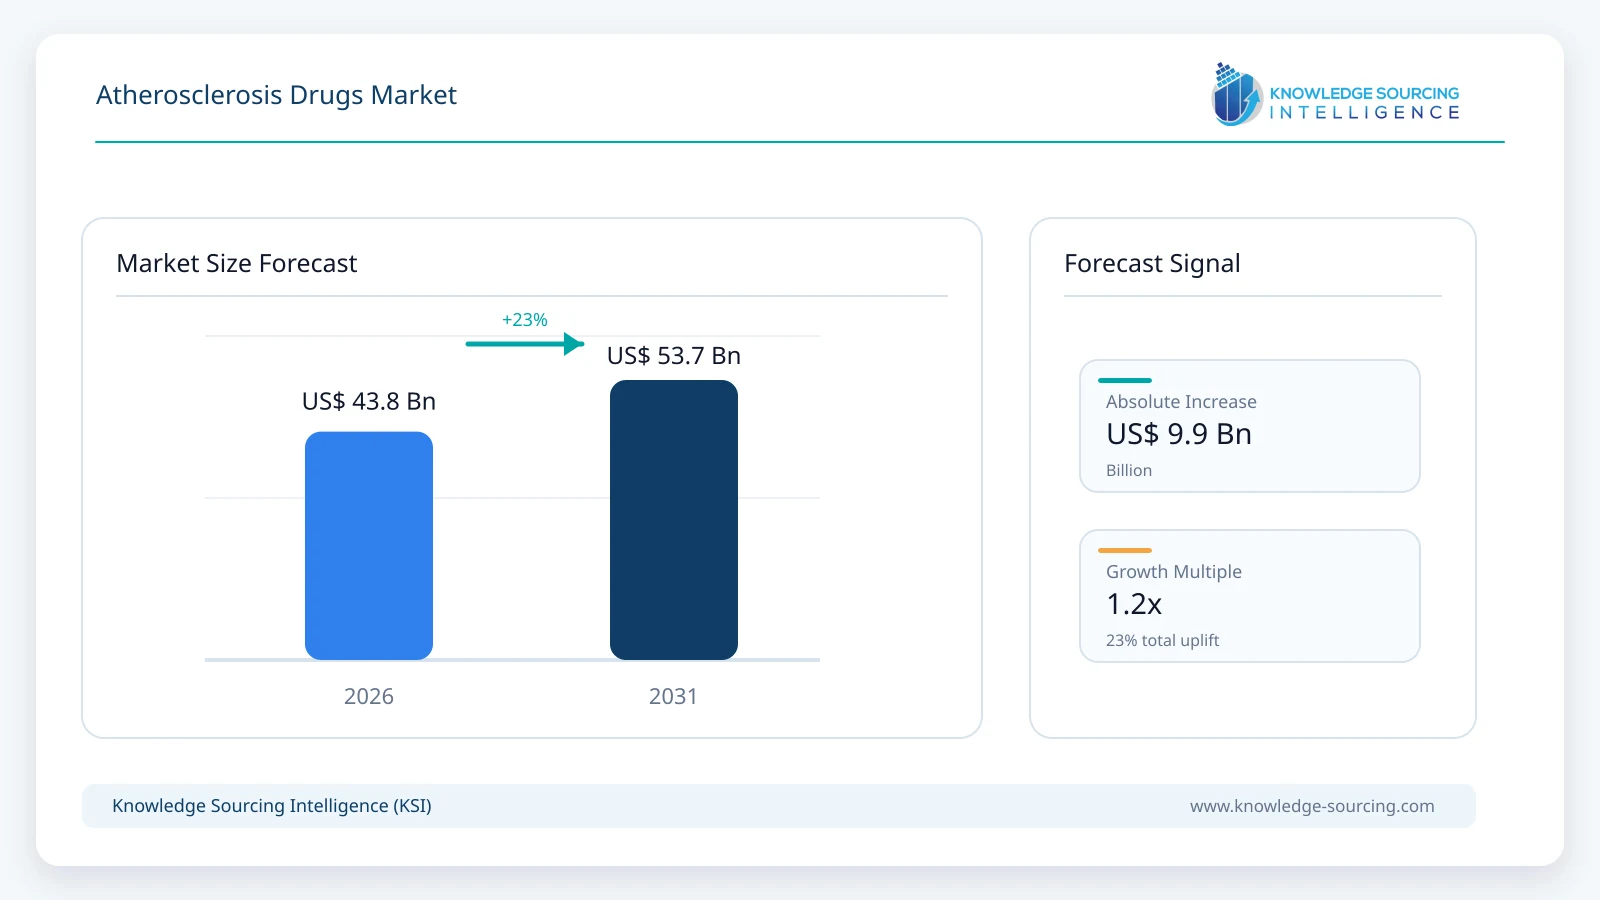
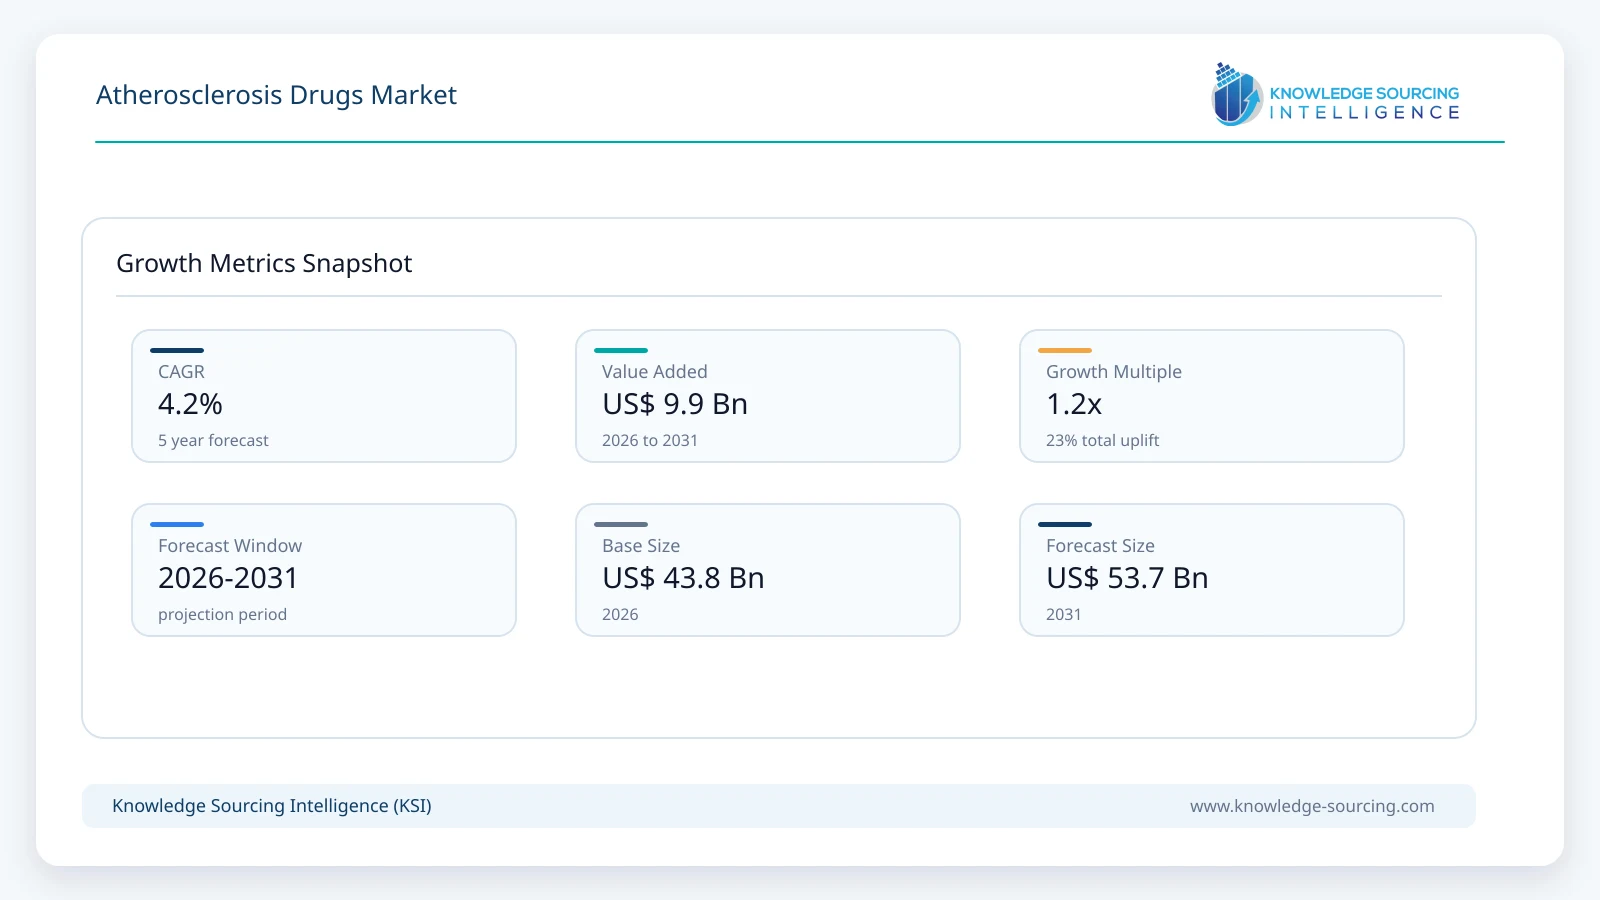
The Atherosclerosis Drugs Market is forecast to grow at a CAGR of 4.2%, reaching USD 53.7 billion in 2031 from USD 43.8 billion in 2026.
Highlights:
- 1Cholesterol-lowering therapies account for approximately USD 34.6 billion of 2026 market value.
- 2Oral therapies represent approximately USD 36.8 billion of the global market in 2026.
- 3Established ASCVD and secondary-prevention treatment contributes about USD 27.2 billion in 2026.
- 4Retail pharmacies account for approximately USD 25.4 billion of 2026 distribution-channel revenue.
- 5North America represents approximately USD 18.0 billion of the global market in 2026.
The market covers prescription pharmacotherapies used to slow atherosclerotic disease progression, reduce atherogenic lipid exposure, prevent thrombotic events, and lower recurrent cardiovascular risk in patients with established or elevated atherosclerotic cardiovascular disease (ASCVD) risk.
The scope includes statins and other lipid-lowering therapies, PCSK9-targeting medicines, cholesterol absorption and ATP-citrate lyase inhibitors, antiplatelet therapies, selected triglyceride-lowering drugs used for cardiovascular risk reduction, and other pharmacotherapies with a direct role in ASCVD prevention. Interventional devices, angioplasty and stenting, imaging equipment, stand-alone antihypertensive therapy, and anticoagulants used primarily for atrial fibrillation or venous thromboembolism are excluded.
Commercial value is increasingly separating from prescription volume. Generic statins remain the treatment foundation and account for very high patient volumes at low unit prices, while PCSK9 monoclonal antibodies, siRNA therapies, bempedoic acid combinations, and the first oral PCSK9 inhibitor are expanding the premium revenue pool. This creates a market in which modest top-line growth masks a faster shift in value toward specialty and differentiated non-statin therapies.
Growth remains moderate because mature statins, ezetimibe, clopidogrel, and other established agents are heavily genericized. Revenue expansion is increasingly driven by higher-value non-statin therapies, broader treatment intensity in high-risk patients, better reimbursement, and lower LDL-C targets that move more patients into combination therapy.
Atherosclerosis Drugs Market Trends
Lower LDL-C Targets Expand the Addressable Combination-Therapy Pool
The 2026 ACC/AHA multisociety dyslipidemia guideline re-establishes LDL-C treatment goals and recommends more intensive lowering in higher-risk patients, including a target below 55 mg/dL for many very-high-risk secondary-prevention patients. The commercial consequence is a larger population that will not reach the target on statin monotherapy. This increases the practical addressable market for ezetimibe, bempedoic acid, PCSK9 monoclonal antibodies, inclisiran, and combination regimens rather than simply increasing statin volume.
Premium Non-Statin Therapies are Capturing Disproportionate Revenue Growth
The specialty segment is already large enough to materially reshape market value. Amgen reported Repatha sales of USD 3.02 billion in 2025, up 36% year over year, while Novartis reported Leqvio sales of USD 1.20 billion, up 59%. Combined, these two products generated more than USD 4.2 billion in 2025 sales despite serving a much smaller patient base than generic statins. This illustrates why prescription counts alone understate where value is moving within atherosclerosis pharmacotherapy.
Oral PCSK9 Therapy Changes the Access and Adherence Trade-Off
In July 2026, the U.S. FDA approved Merck's Lipfendra (enlicitide), the first oral PCSK9 inhibitor. The approval removes injection as a barrier to PCSK9-class adoption and could broaden use outside specialty injectable channels. Commercially, it creates a new trade-off: daily oral administration may improve route acceptance and pharmacy access, while long-interval injectable therapies such as inclisiran retain an adherence advantage for patients who struggle with daily chronic medication.
Generic Volume and Specialty Value are Pulling the Market in Different Directions
Atorvastatin, rosuvastatin, ezetimibe, aspirin and clopidogrel remain low-cost, high-volume therapies. Their broad generic availability suppresses revenue growth even as treated patient numbers increase. By contrast, newer agents compete on incremental LDL-C lowering, cardiovascular outcomes evidence, dosing convenience, statin-intolerance positioning, and payer access. The result is a two-speed market: high-volume mature oral therapy with limited pricing power and lower-volume specialty therapy with significantly higher revenue per treated patient.
Segment Analysis
By Drug Class - Cholesterol-Lowering Therapies
Cholesterol-lowering therapies are estimated at approximately USD 34.6 billion in 2026, representing the largest share of the atherosclerosis drugs market. Statins provide the volume base, while PCSK9 inhibitors, inclisiran, ezetimibe, and bempedoic acid increase value per treated patient when LDL-C goals are not achieved with statins alone. The segment is becoming more commercially differentiated as guideline-directed therapy moves from sequential escalation toward earlier use of combination treatment in very-high-risk patients.
By Route of Administration - Oral
Oral therapies account for approximately USD 36.8 billion in 2026. Statins, ezetimibe, bempedoic acid, antiplatelet medicines and the newly approved oral PCSK9 inhibitor support this dominance. Oral delivery benefits from primary-care familiarity, retail-pharmacy distribution and lower administration burden, while injectables retain an important role in patients requiring larger LDL-C reductions or infrequent dosing.
By Treatment Context - Established ASCVD and Secondary Prevention
Established ASCVD and secondary-prevention treatment is estimated at approximately USD 27.2 billion in 2026. Patients with prior myocardial infarction, ischemic stroke, symptomatic peripheral artery disease or other documented atherosclerotic disease typically require more intensive lipid-lowering and antithrombotic therapy than lower-risk primary-prevention populations. This concentration of combination therapy makes secondary prevention the largest value pool even though primary-prevention patient numbers are larger.
By Distribution Channel - Retail Pharmacies
Retail pharmacies account for approximately USD 25.4 billion of 2026 market value. Long-duration oral treatment for dyslipidemia and platelet inhibition is predominantly dispensed through retail channels, while specialty pharmacies and hospital-linked channels are more important for high-cost injectable biologics and complex reimbursement workflows. The arrival of oral PCSK9 therapy is likely to shift a portion of premium therapy value toward conventional pharmacy channels.
By Geography - North America
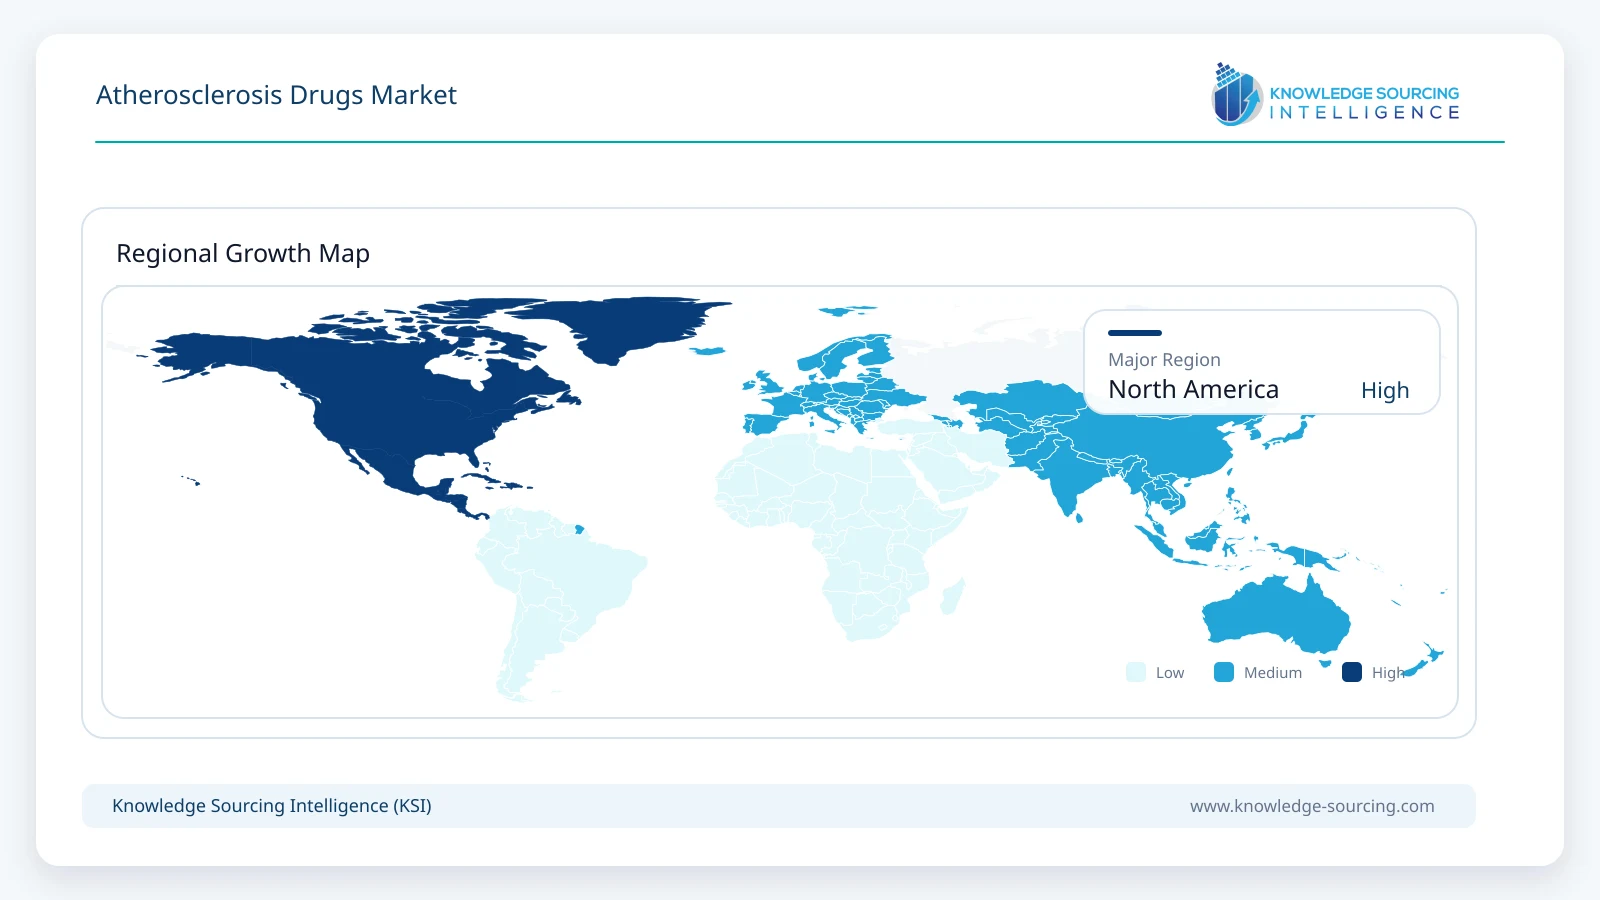
North America is estimated at approximately USD 18.0 billion in 2026. The region combines high ASCVD prevalence, broad lipid screening, aggressive guideline-directed LDL-C targets, strong access to specialty therapies and comparatively high pharmaceutical pricing. U.S. payer policy remains a critical commercial variable because formulary sequencing and prior authorization determine how quickly non-statin therapies move from guideline eligibility to actual prescription volume.
Market Drivers
More aggressive LDL-C treatment goals are expanding the number of patients requiring combination therapy.
Aging, diabetes, obesity and chronic kidney disease continue increasing the high-risk ASCVD treatment pool.
PCSK9, siRNA and ACL-inhibitor therapies are creating higher-value alternatives beyond generic statins.
Improving payer coverage for selected non-statin therapies is reducing a major barrier to treatment escalation.
Long-duration and oral innovations are widening treatment options for adherence- and injection-sensitive patients.
Market Restraints
Generic statins and antiplatelet medicines exert persistent price pressure on the largest prescription-volume segments.
Prior authorization and step-therapy rules can delay uptake of higher-cost non-statin treatments.
Long-term adherence remains difficult because treatment is preventive and often asymptomatic.
Clinical overlap with hypertension, diabetes and thrombosis complicates market attribution across cardiovascular drug categories.
Outcome evidence remains important for newer mechanisms before broad guideline and payer adoption.
Competitive Environment
Competition is split between high-volume generic manufacturers and innovation-led cardiovascular companies. Amgen, Novartis, Merck, Regeneron and Esperion compete in differentiated LDL-C reduction, while AstraZeneca, Bayer and multiple generic manufacturers retain participation in antiplatelet and established cardiovascular risk-reduction therapy. The strategic battleground is shifting from basic LDL-C lowering toward route, dosing frequency, outcomes evidence, access, fixed-dose combinations and the ability to move patients to target with fewer treatment steps.
Repatha and Leqvio demonstrate the revenue potential of specialty lipid lowering, while bempedoic acid has expanded as an oral non-statin alternative for patients who cannot take recommended statin therapy. Merck's 2026 entry with oral enlicitide increases competitive pressure on both injectable PCSK9 monoclonal antibodies and other oral add-on therapies.
Recent Developments
July 2026: The U.S. FDA approved Merck's Lipfendra (enlicitide), the first oral PCSK9 inhibitor for adults with hypercholesterolemia, including HeFH.
March 2026: ACC/AHA and partner societies issued an updated dyslipidemia guideline with renewed LDL-C and non-HDL-C targets and broader non-statin treatment options.
March 2026: Bempedoic acid received multiple Class 1 recommendations in the 2026 U.S. dyslipidemia guideline, strengthening its positioning in statin-intolerant and high-risk patients.
2025 full year: Amgen reported Repatha sales of USD 3.02 billion, up 36% year over year on volume growth.
2025 full year: Novartis reported Leqvio sales of USD 1.20 billion, up 59%, demonstrating rapid adoption of infrequent-dose siRNA lipid lowering.
Market Outlook
The atherosclerosis drugs market is expected to remain a moderate-growth but rapidly changing cardiovascular therapeutic market through 2031. Generic statins will continue dominating prescription volume, but incremental revenue will increasingly come from patients who remain above LDL-C targets despite standard treatment, patients with statin intolerance, and very-high-risk secondary-prevention populations requiring combination therapy. The commercial winners are likely to be therapies that combine large LDL-C reductions with simple dosing, strong cardiovascular outcomes evidence and payer-friendly access.
The 2026 approval of an oral PCSK9 inhibitor also creates a new competitive axis. Injectable therapies no longer have exclusive access to PCSK9 biology, while oral agents must still prove that convenience translates into durable adherence and broad outcomes-driven use. By 2031, the market is likely to contain a larger premium non-statin revenue pool even as the majority of treated patients continue receiving inexpensive generic therapy.
Atherosclerosis Drugs Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 43.8 billion |
| Total Market Size in 2031 | USD 53.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Drug Class, Route Of Administration, Treatment Context, Distribution Channel, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Drug Class
Statins
PCSK9 Inhibitors
Cholesterol Absorption Inhibitors
ATP Citrate Lyase Inhibitors
Antiplatelet Agents
Omega-3 and Fibrate Therapies
Anti-inflammatory and Other Therapies
By Route Of Administration
Oral
Subcutaneous Injection
By Treatment Context
Established ASCVD / Secondary Prevention
High-Risk Primary Prevention
Familial Hypercholesterolemia And Genetic Dyslipidemia
By Distribution Channel
Retail Pharmacies
Hospital Pharmacies
Specialty Pharmacies
Online Pharmacies
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East And Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Revenue Reference Point
1.4. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Clinical, Regulatory and Company Validation
2.3. Market Estimation and Forecasting
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Treatment Access and Reimbursement
4.4. Generic Erosion and Specialty-Therapy Economics
5. ATHEROSCLEROSIS DRUGS MARKET BY DRUG CLASS
5.1. Statins
5.2. PCSK9 Inhibitors
5.3. Cholesterol Absorption Inhibitors
5.4. ATP Citrate Lyase Inhibitors
5.5. Antiplatelet Agents
5.6. Omega-3 and Fibrate Therapies
5.7. Anti-inflammatory and Other Therapies
6. ATHEROSCLEROSIS DRUGS MARKET BY ROUTE OF ADMINISTRATION
6.1. Oral
6.2. Subcutaneous Injection
7. ATHEROSCLEROSIS DRUGS MARKET BY TREATMENT CONTEXT
7.1. Established ASCVD / Secondary Prevention
7.2. High-Risk Primary Prevention
7.3. Familial Hypercholesterolemia and Genetic Dyslipidemia
8. ATHEROSCLEROSIS DRUGS MARKET BY DISTRIBUTION CHANNEL
8.1. Retail Pharmacies
8.2. Hospital Pharmacies
8.3. Specialty Pharmacies
8.4. Online Pharmacies
9. ATHEROSCLEROSIS DRUGS MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Australia
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Branded vs Generic Market Structure
10.2. Product and Mechanism Positioning
10.3. Pricing, Access and Reimbursement
10.4. Strategic Developments
11. COMPANY PROFILES
11.1. Amgen Inc.
11.2. Novartis AG
11.3. Merck & Co., Inc.
11.4. Regeneron Pharmaceuticals, Inc.
11.5. Esperion Therapeutics, Inc.
11.6. Daiichi Sankyo Company, Limited
11.7. AstraZeneca PLC
11.8. Bayer AG
11.9. Agepha Pharma s.r.o.
11.10. Amarin Corporation plc
11.11. Viatris Inc.
11.12. Teva Pharmaceutical Industries Ltd.
11.13. Sun Pharmaceutical Industries Ltd.
11.14. Dr. Reddy's Laboratories Ltd.
11.15. Aurobindo Pharma Limited
11.16. Lupin Limited
11.17. Zydus Lifesciences Limited
12. APPENDIX
12.1. Market Definition and Exclusions
12.2. Assumptions





Frequently asked questions
What is the projected market size for atherosclerosis drugs in 2031?
The Atherosclerosis Drugs Market is forecast to reach USD 53.7 billion in 2031.
What is the projected CAGR for the Atherosclerosis Drugs Market?
The Atherosclerosis Drugs Market is forecast to grow at a 4.2% CAGR.
Which therapy type holds the largest market share in 2026?
Cholesterol-lowering therapies account for USD 34.6 billion in 2026.
Which region represents the largest market share in 2026?
North America represents USD 18.0 billion of the global market.
What drives revenue growth in the Atherosclerosis Drugs Market?
Higher-value non-statin therapies and lower LDL-C targets drive growth.
How do new LDL-C targets affect the market?
Lower LDL-C targets expand the addressable combination therapy pool.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Atherosclerosis Drugs Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/atherosclerosis-drugs-market