
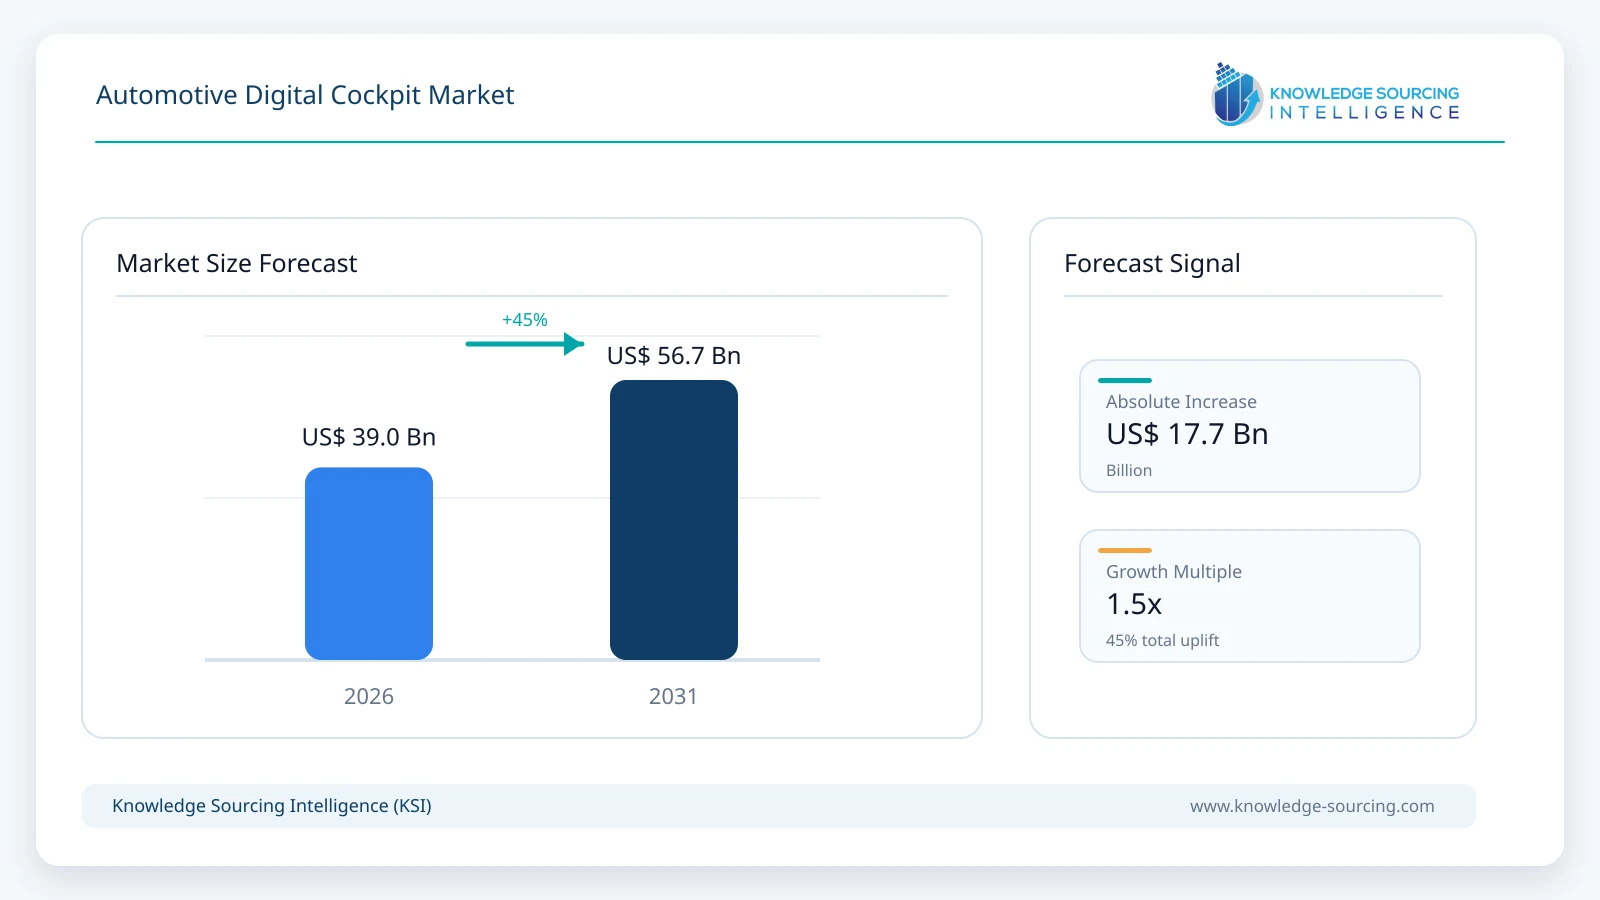
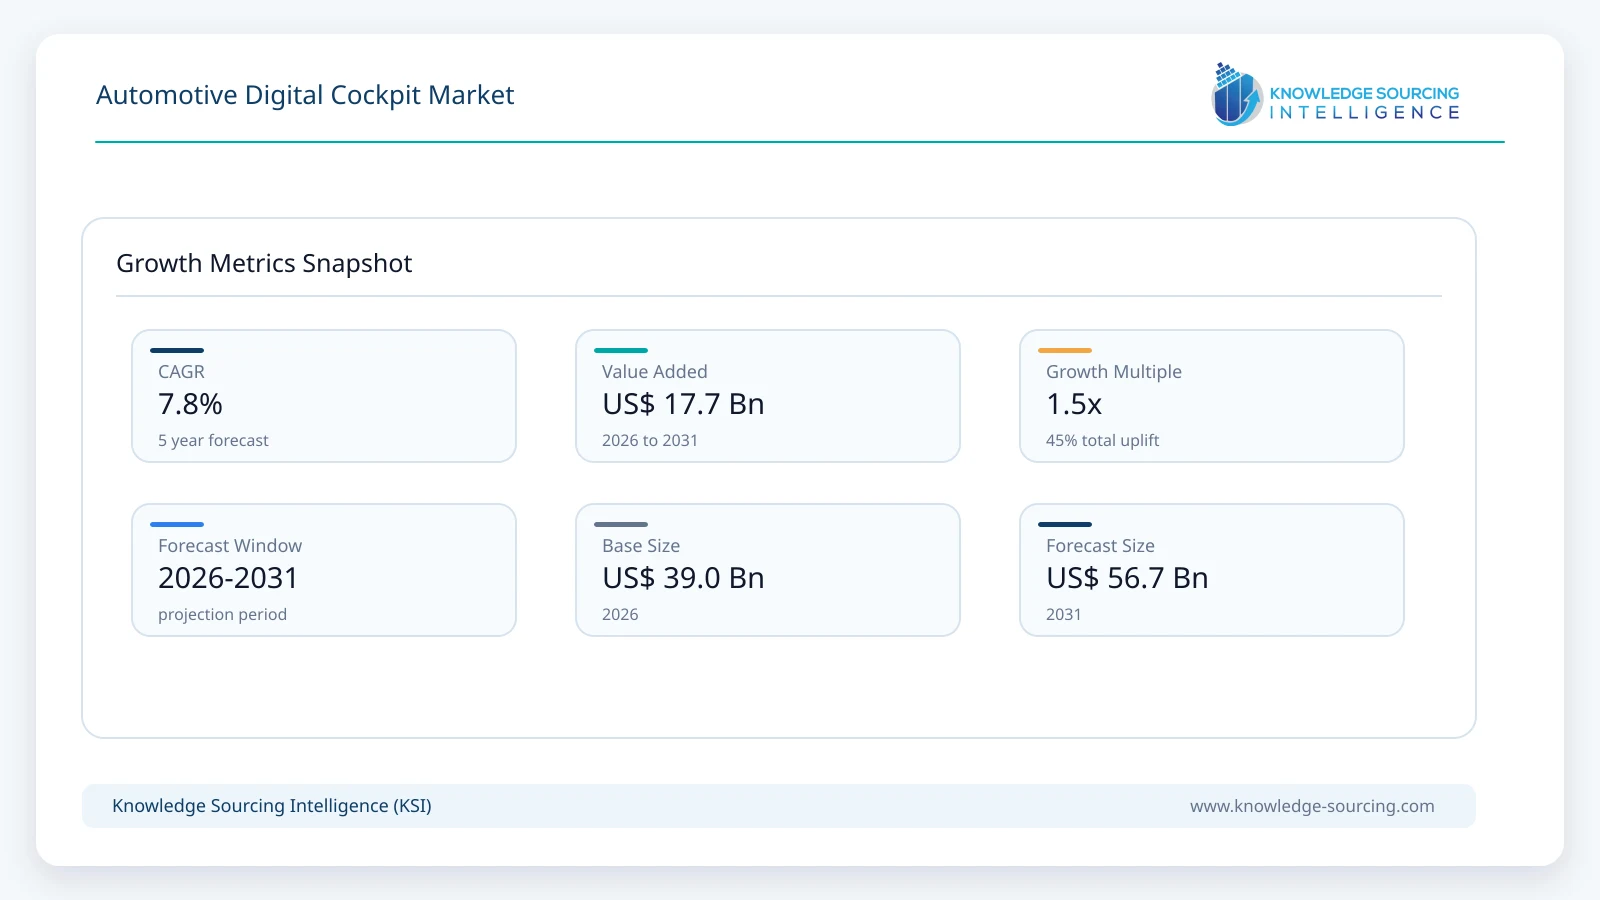
The Automotive Digital Cockpit Market is projected to expand at a CAGR of 7.8%, increasing from USD 39.0 billion in 2026 to USD 56.7 billion by 2031.
Highlights:
- 1Digital displays and instrument clusters account for approximately 39% of global market value in 2026, making visualization the largest system layer within the digital cockpit.
- 2Digital cockpit controllers and IVI systems represent approximately 36% of 2026 market value as high-performance compute consolidates infotainment, graphics and multiple display outputs.
- 3Cockpit domain-consolidated architecture accounts for approximately 49% of market value in 2026 and is modeled to reach 58% by 2031.
- 4Multi-display and panoramic cockpit configurations represent approximately 34% of 2026 value and are modeled to reach 45% by 2031 as passenger displays and pillar-to-pillar formats expand.
- 5Passenger vehicles account for approximately 93% of global market value in 2026 because fully digital cockpit adoption is concentrated in passenger cars, SUVs and MPVs.
- 6Asia Pacific represents approximately 45% of global market value in 2026 and is modeled to reach 48% by 2031, supported by smart-cockpit scale in China and strong display/electronics supply chains across East Asia.
Global vehicle production reached a base of 96.4 million units in 2025, while increasing cockpit content per vehicle is strengthening demand for advanced electronics. Visteon generated USD 3.768 billion in 2025 sales and secured USD 7.4 billion in new business, including USD 3.6 billion in displays, USD 2.1 billion in SmartCore and infotainment, and USD 1.4 billion in clusters. These figures highlight the growing importance of digital cockpit electronics, as automakers integrate advanced displays, connected infotainment, centralized computing, and instrument clusters to improve vehicle functionality and user experience.
Digital cockpit value is concentrated in integrated compute, visualization and HMI rather than the full cockpit-electronics stack, so standalone telematics, audio and sensing hardware are excluded unless they directly support the digital cockpit platform. Qualcomm states that Snapdragon digital cockpit platforms now power more than 75 million vehicles, Bosch has delivered more than ten million Snapdragon-based cockpit computers, and ECARX reports its technology solutions across more than eleven million vehicles. These production indicators support a market in which domain controllers, displays, and software increasingly replace separate cluster and infotainment modules.
Market Overview
Replacing analog gauges and independent infotainment hardware with coordinated displays and shared compute allows speed, navigation, ADAS status, entertainment, and connected functions to move dynamically across cluster, central display, passenger display, and HUD under one software framework. The architecture therefore links visualization and compute rather than treating each screen as an isolated product.
High-performance cockpit controllers are becoming the execution layer because modern SoCs can run Android infotainment, safety-relevant cluster software, 3D graphics and AI simultaneously. AUMOVIO positions cockpit HPC as a one-box solution for cluster and infotainment, while Visteon SmartCore HPC targets multi-display and AI-enabled cockpit architectures.
Display systems remain the largest system pool as clusters, center screens, passenger displays and HUDs increase in size and feature content. BOE Varitronix generated HKD 13.449 billion in 2024 revenue, while Visteon's 2025 new-business wins included USD 3.6 billion of display programs, supporting the continued scale of cockpit visualization.
OEM efforts to reuse applications across hardware generations and vehicle lines are increasing the value of cockpit software, middleware and hardware abstraction within the digital cockpit stack. HARMAN Ready Upgrade, Panasonic's VirtIO work and ECARX's Flyme Auto expansion all target this decoupling, allowing HMI and application layers to evolve without redesigning the full cockpit platform.
Market Trends
Domain-Consolidated Digital Cockpits Are Becoming the Mainstream Architecture
OEMs are replacing separate cluster and infotainment ECUs with shared cockpit domain controllers because one high-performance platform can drive several displays and software environments. Bosch's ten-million-unit cockpit-computer milestone, Panasonic's Mazda CDC program and Visteon's SmartCore portfolio show that consolidation is already at series-production scale. The internal model raises domain-consolidated architecture from 49% of value in 2026 to 58% by 2031.
Panoramic and Multi-Display Cockpits Are Replacing Conventional Dual-Screen Layouts
Digital cockpit design is moving beyond the traditional cluster-plus-center-screen format toward passenger displays, curved ultrawide surfaces and pillar-to-pillar assemblies. Visteon, AUMOVIO and BOE are all advancing multi-display architectures. The configuration raises both display area and graphics demand, supporting a modeled share increase from 34% in 2026 to 45% by 2031.
AI Processing Is Increasing the Performance Requirements of the Digital Cockpit
Adding voice assistants, personalization and visual recognition to platforms originally designed around infotainment and graphics is raising NPU, memory and thermal requirements across the digital cockpit. Snapdragon Cockpit Elite, Visteon SmartCore HPC and ECARX Zenith all target AI-capable architectures, increasing compute value per vehicle as OEMs provision headroom for future software.
Displays Are Becoming Integrated HMI Surfaces rather than Passive Output Devices
Combining touch, haptics, privacy control, hidden cameras and adaptive content within the display module is shifting cockpit visualization from a passive output layer toward an integrated HMI surface. AUMOVIO has secured an OLED program with an invisibly integrated camera, while HARMAN Ready Display combines premium visual processing with production-ready cockpit integration, moving supplier value away from commodity panels.
Cross-Domain Compute Is Beginning to Absorb Digital Cockpit Functions
Combining cockpit, ADAS, body, and gateway functions on broader centralized computers allows premium SDV platforms to reduce domain boundaries while sharing expensive compute resources. Leapmotor's dual Snapdragon Elite controller and ECARX Zenith illustrate this path, and the internal model raises cross-domain architecture from 10% of value in 2026 to 19% by 2031.
Segment Analysis
By System Type: Digital Displays and Instrument Clusters
Digital displays and instrument clusters account for approximately USD 15.21 billion in 2026 and are projected to reach about USD 22.68 billion by 2031. Share rises from 39% to 40% as screen area, premium panel technologies, and multi-display adoption grow slightly faster than the overall market. Visualization remains the largest system pool through 2031.
By System Type: Digital Cockpit Controllers and IVI Systems
Digital cockpit controllers and IVI systems account for approximately USD 14.04 billion in 2026 and are projected to reach about USD 18.14 billion by 2031. Share declines from 36% to 32% because displays, HUD, and software grow faster, while absolute controller value still increases through domain consolidation and higher compute content.
By Electronics Architecture: Cockpit Domain-Consolidated Architecture
Cockpit domain-consolidated systems account for approximately USD 19.11 billion in 2026 and are projected to reach about USD 32.89 billion by 2031, implying roughly 11.5% annual growth. Share rises from 49% to 58% as shared high-performance compute replaces distributed cluster and infotainment controllers across higher-volume vehicle segments.
By Cockpit Configuration: Multi-Display and Panoramic Cockpit
Multi-display and panoramic cockpits account for approximately USD 13.26 billion in 2026 and are projected to reach about USD 25.52 billion by 2031, equivalent to roughly 14.0% annual growth. Share rises from 34% to 45% as passenger displays, curved ultrawide panels and full-width cockpit surfaces spread beyond flagship vehicles.
By Vehicle Class: Premium and Upper-Mid-Range Vehicles
Premium and upper-mid-range vehicles account for approximately USD 19.50 billion in 2026 because they carry the highest display count, cockpit compute and advanced HMI content. Their share falls from 50% to 44% by 2031 as digital clusters, larger center displays and domain controllers become standard in broader vehicle segments.
By Vehicle Type: Passenger Vehicles
Passenger vehicles account for approximately USD 36.27 billion in 2026 and are projected to reach about USD 51.60 billion by 2031. Share eases from 93% to 91% as commercial vehicles add digital clusters and cockpit controllers faster from a smaller base, although passenger cars, SUVs and MPVs remain overwhelmingly dominant.
Market Drivers
Replacement of Analog and Hybrid Instrumentation Is Expanding the Digital Cockpit Base
Replacing analog or hybrid instrumentation with fully digital clusters and integrated infotainment is expanding cockpit electronics content across mainstream vehicle programs rather than only premium models. Visteon's 2025 launches included digital clusters across Toyota, Tata and Ford platforms, while BOE and AUMOVIO continue to scale automotive display portfolios.
Software-Defined Vehicle Architectures Are Increasing Cockpit Compute Content
Software-defined vehicle programs increase cockpit compute content because controllers must run several operating systems, support OTA updates and retain headroom for functions added after start of production. Qualcomm, Bosch, Panasonic, HARMAN and ECARX are all developing reusable compute and software platforms, raising processor, memory and middleware value even as ECU count falls.
Larger and More Numerous Displays Are Raising Value per Vehicle
Expanding center displays, passenger screens, clusters and HUDs raise value per vehicle because larger screen area also requires more optical bonding, touch electronics and graphics-controller capability. Visteon's USD 3.6 billion of 2025 display wins and BOE Varitronix's revenue scale demonstrate the commercial significance of this content expansion.
AI-Enabled HMI Is Driving Higher-Performance Cockpit Platforms
Generative voice, personalization and visual recognition are increasing local AI requirements beyond conventional infotainment workloads, pushing OEMs toward cockpit platforms with dedicated acceleration and future compute headroom. Snapdragon Cockpit Elite, Visteon SmartCore HPC and ECARX Zenith all target this architecture, raising silicon and memory content per vehicle.
EV and Smart-Cockpit Competition Is Accelerating Premiumization
Digital cockpit quality has become a visible competitive lever for electric and software-focused brands because displays, graphics and interaction are immediately apparent to customers. Chinese OEM competition has accelerated multi-display and AI-enabled cockpit adoption across a wider price range, pushing established automakers to move premium digital features into upper-mid-range and mainstream platforms.
Market Restraints
Domain Consolidation Reduces the Number of Separate Cockpit ECUs
A high-performance cockpit controller can replace separate cluster, infotainment, and display-control ECUs, reducing module count even as system capability increases. Market growth therefore depends on added compute, software and display value exceeding the hardware eliminated through consolidation, which keeps overall growth below some narrower child technologies.
Display and Compute Premiumization Raises Thermal and Power Requirements
Combining large high-brightness displays with powerful SoCs and AI accelerators raises dashboard power and heat enough to constrain sustained performance and packaging. Premium cockpit HPCs may require advanced cooling while displays face severe solar load, making system-level power optimization increasingly important.
Mixed-Criticality Software Increases Validation Complexity
Running safety-relevant cluster software beside Android infotainment, third-party apps and AI functions on one cockpit controller increases the need for hypervisors, fault isolation and mixed-criticality validation. Engineering effort rises as more displays and software environments share hardware, offsetting part of the cost benefit created by consolidation.
Fast Consumer-Electronics Cycles Can Make Cockpit Hardware Appear Outdated
Consumer-electronics expectations for display quality, UI responsiveness and AI capability evolve faster than automotive development cycles, creating a risk that cockpit hardware appears dated before vehicle production ends. OTA software and hardware abstraction improve longevity but cannot fully overcome fixed screen size or silicon capability, forcing OEMs to balance future-proofing against launch cost.
Driver-Distraction Concerns Limit Uncontrolled Screen and Feature Expansion
Expanding screen count and software functionality can increase driver visual demand when frequently used controls move into changing menus, limiting the benefit of additional digital content. Regulatory and NCAP pressure increasingly favors eyes-on-road interaction, stable controls, and effective voice or haptic alternatives, so OEMs need disciplined information architecture rather than maximum display area.
Regional Outlook
Asia Pacific
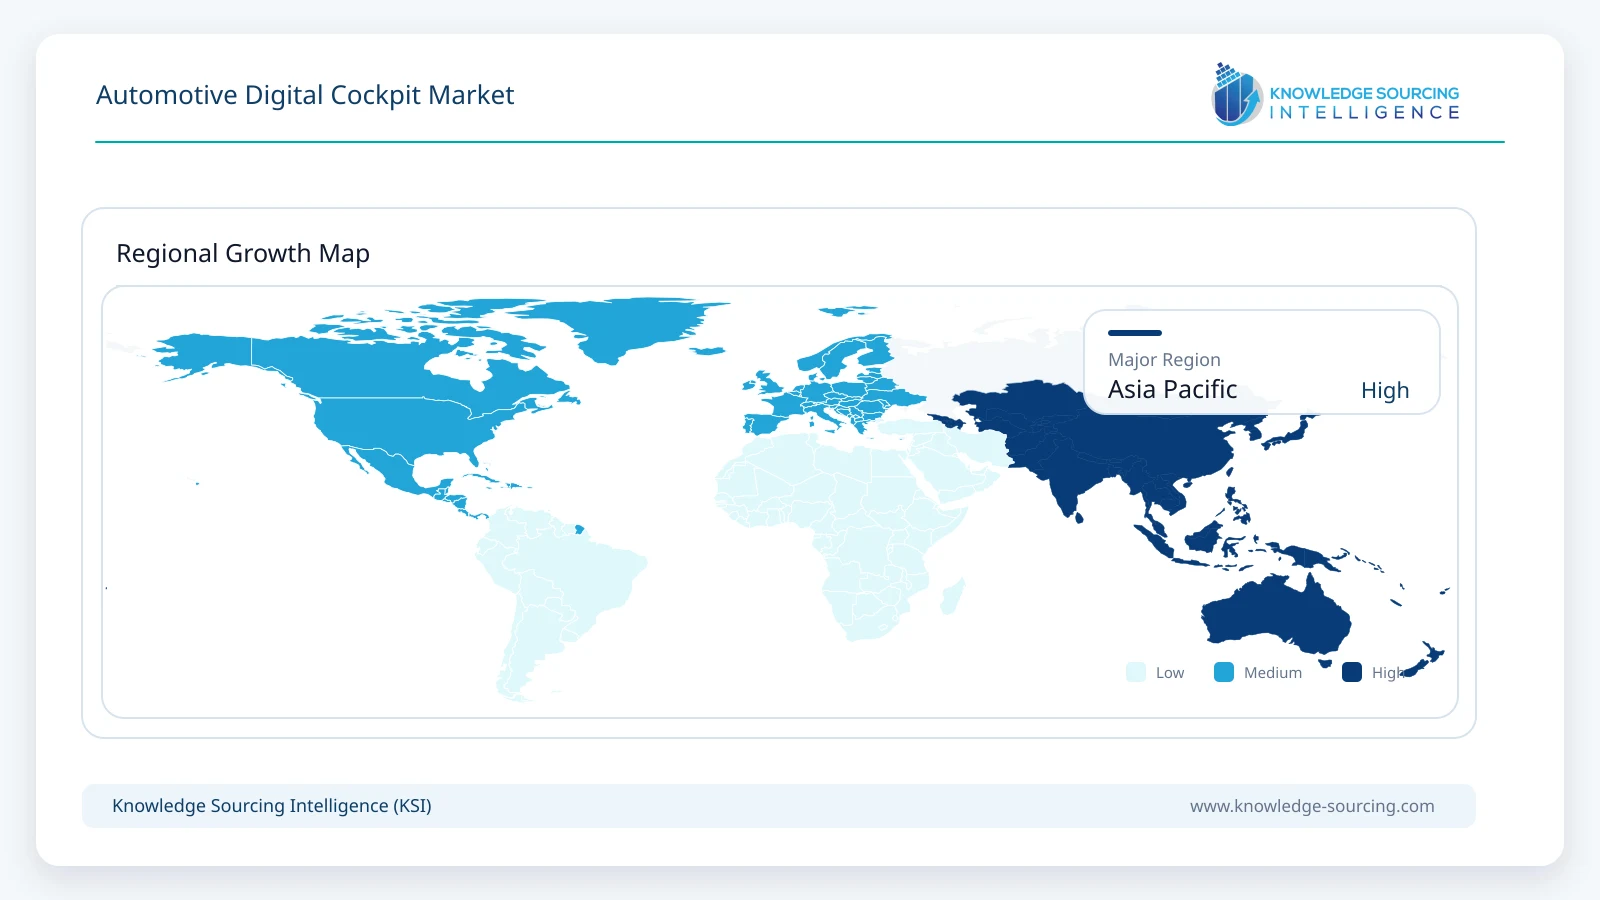
Asia Pacific accounts for approximately 45% of global market value in 2026 and is modeled to reach 48% by 2031. China combines high vehicle production with rapid smart-cockpit adoption, while Japan, South Korea and Taiwan contribute major electronics and display supply chains. Visteon, BOE and ECARX all show substantial regional scale, and faster replacement cycles support wider adoption of panoramic displays and domain controllers.
Europe
Europe is the second major high-value market because premium OEMs and SDV programs support high compute, display and HMI content per vehicle. Bosch, AUMOVIO, HARMAN and Marelli provide a strong regional supplier base. Europe's share eases from approximately 26% in 2026 to 24% in 2031 as Asia Pacific grows faster, although absolute value continues to rise.
Competitive Landscape
Digital-cockpit value is distributed across compute, visualization, and HMI software, creating competition among Tier 1 integrators, display specialists, software-platform companies, and semiconductor providers rather than one homogeneous supplier group. Visteon, HARMAN, Panasonic Automotive Systems, AUMOVIO, Bosch, LG Vehicle Solution, Marelli, Hyundai Mobis, BOE Varitronix, Desay SV, ECARX and Qualcomm are among the most relevant participants for deeper profiling.
Visteon is a strong pure-play benchmark with USD 3.768 billion of 2025 sales and program wins across displays, SmartCore and clusters. HARMAN, Panasonic, Bosch and AUMOVIO compete through scalable cockpit controllers and lifecycle software, while LG and Marelli combine infotainment, displays and integrated in-cabin electronics.
BOE remains strategically important because visualization is the largest system pool, while ECARX, Desay SV and Qualcomm strengthen competition around full-stack software and cockpit computing. Supplier advantage increasingly depends on platform reuse, display integration, AI capability, and software portability rather than a single hardware specification.
Competitive Company Universe
• Visteon Corporation
• HARMAN International
• Panasonic Automotive Systems Co., Ltd.
• AUMOVIO
• Robert Bosch GmbH
• LG Electronics Vehicle Solution Company
• Marelli
Recent Developments
8 October 2026: LG Electronics announced a suite of six in-cabin solutions for the Genesis GV90, including a 24.6-inch variable popup central display, integrated infotainment combining cluster, AVN and HUD, and connected vehicle-control electronics.
29 July 2026: Qualcomm and BMW Group announced a long-term agreement making Qualcomm a lead compute-silicon provider for BMW's next-generation digital cockpit and automated-driving platforms.
7 July 2026: Panasonic Automotive Systems announced that its cockpit domain controller was adopted in Mazda's all-new CX-5, centralizing infotainment, HUD and instrument-cluster functions on an OTA-updatable platform.
22 June 2026: ECARX agreed to acquire the full Flyme software business, including Flyme Auto, strengthening its end-to-end cockpit operating-system stack after Flyme Auto deployment in more than two million vehicles.
3 June 2026: Visteon announced its 12.3-inch narrow-border driver display in the all-new Lexus ES, expanding its premium digital-cockpit display footprint and in-house optical-bonding capability.
7 April 2026: AUMOVIO announced a major series-production order for an OLED driver display with an invisibly integrated camera, combining premium visualization with driver-monitoring functionality in one cockpit module.
Market Outlook
The automotive digital cockpit market is being shaped by increasing value per vehicle through domain controllers, larger displays, panoramic configurations, head-up displays (HUDs), and software integration rather than rapid expansion in vehicle production volumes. Automakers are increasingly adopting domain-consolidated cockpit architectures to simplify electronic systems, improve computing efficiency, and deliver connected user experiences. Cross-domain central computing is also gaining traction as manufacturers integrate cockpit, driver assistance, and vehicle control functions into unified computing platforms. These developments are strengthening demand for advanced hardware, software, and integrated digital cockpit solutions across passenger and commercial vehicles.
Asia Pacific should retain the largest regional value pool, while Europe remains important for premium display and SDV engineering. Supplier performance will depend on integrating compute, displays and software into reusable platforms without allowing thermal load, validation complexity or driver-distraction risk to offset the benefits of digitalization.
Automotive Digital Cockpit Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 39.0 billion |
| Total Market Size in 2031 | USD 56.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | System Type, Electronics Architecture, Cockpit Configuration, Vehicle Class |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By System Type
Digital Cockpit Controllers & IVI Systems
Digital Displays & Instrument Clusters
HUD & Projection Systems
HMI Software, Middleware & Interface Electronics
By Electronics Architecture
Distributed Digital Cockpit
Cockpit Domain-Consolidated Architecture
Cross-Domain / Centralized Cockpit Architecture
By Cockpit Configuration
Dual-Screen Cluster + Central Display
Multi-Display / Panoramic Cockpit
HUD-Centric / Minimal-Cluster Integrated Cockpit
By Vehicle Class
Premium & Upper-Mid-Range Vehicles
Mid-Range Vehicles
Mass-Market & Economy Vehicles
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicles
Medium & Heavy Commercial Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Replacement of Analog and Hybrid Instrumentation Is Expanding the Digital Cockpit Base
3.1.2. Software-Defined Vehicle Architectures Are Increasing Cockpit Compute Content
3.1.3. Larger and More Numerous Displays Are Raising Value per Vehicle
3.1.4. AI-Enabled HMI Is Driving Higher-Performance Cockpit Platforms
3.1.5. EV and Smart-Cockpit Competition Is Accelerating Premiumization
3.2. Market Restraints
3.2.1. Domain Consolidation Reduces the Number of Separate Cockpit ECUs
3.2.2. Display and Compute Premiumization Raises Thermal and Power Requirements
3.2.3. Mixed-Criticality Software Increases Validation Complexity
3.2.4. Fast Consumer-Electronics Cycles Can Make Cockpit Hardware Appear Outdated
3.2.5. Driver-Distraction Concerns Limit Uncontrolled Screen and Feature Expansion
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Cockpit Domain Controllers and Cockpit HPC
4.2. Digital Instrument Clusters
4.3. Central and Passenger Displays
4.4. Head-Up Displays and Windshield Projection
4.5. LCD, MiniLED, OLED and Emerging MicroLED Displays
4.6. Panoramic and Pillar-to-Pillar Display Architectures
4.7. Multi-Display Graphics and Rendering
4.8. HMI Middleware and Graphics Frameworks
4.9. Hypervisors, VirtIO and Multi-OS Architecture
4.10. AI Acceleration and Edge Inference
4.11. Touch, Haptic, Voice and Gesture Integration
4.12. Integrated Driver Monitoring and Display-Sensing Architecture
4.13. OTA Updates and Cockpit Software Lifecycle Management
4.14. Migration toward Cross-Domain and Central Compute
5. AUTOMOTIVE DIGITAL COCKPIT MARKET BY SYSTEM TYPE
5.1. Digital Cockpit Controllers & IVI Systems
5.2. Digital Displays & Instrument Clusters
5.3. HUD & Projection Systems
5.4. HMI Software, Middleware & Interface Electronics
6. AUTOMOTIVE DIGITAL COCKPIT MARKET BY ELECTRONICS ARCHITECTURE
6.1. Distributed Digital Cockpit
6.2. Cockpit Domain-Consolidated Architecture
6.3. Cross-Domain / Centralized Cockpit Architecture
7. AUTOMOTIVE DIGITAL COCKPIT MARKET BY COCKPIT CONFIGURATION
7.1. Dual-Screen Cluster + Central Display
7.2. Multi-Display / Panoramic Cockpit
7.3. HUD-Centric / Minimal-Cluster Integrated Cockpit
8. AUTOMOTIVE DIGITAL COCKPIT MARKET BY VEHICLE CLASS
8.1. Premium & Upper-Mid-Range Vehicles
8.2. Mid-Range Vehicles
8.3. Mass-Market & Economy Vehicles
9. AUTOMOTIVE DIGITAL COCKPIT MARKET BY VEHICLE TYPE
9.1. Passenger Vehicles
9.2. Light Commercial Vehicles
9.3. Medium & Heavy Commercial Vehicles
10. AUTOMOTIVE DIGITAL COCKPIT MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. United Kingdom
10.3.2. Germany
10.3.3. France
10.3.4. Italy
10.3.5. Spain
10.3.6. Others
10.4. Middle East & Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. Israel
10.4.4. South Africa
10.4.5. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. South Korea
10.5.5. Australia
10.5.6. Indonesia
10.5.7. Thailand
10.5.8. Taiwan
10.5.9. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Digital Cockpit Architecture Benchmarking
11.4. Distributed versus Domain-Consolidated versus Central Compute Comparison
11.5. Display and Cockpit Configuration Benchmarking
11.6. HMI Software and AI Capability Benchmarking
11.7. Agreements, Collaborations and Platform Partnerships
11.8. Competitive Dashboard
12. COMPANY PROFILES
12.1. Visteon Corporation
12.2. HARMAN International
12.3. Panasonic Automotive Systems Co., Ltd.
12.4. AUMOVIO
12.5. Robert Bosch GmbH
12.6. LG Electronics Vehicle Solution Company
12.7. Marelli
12.8. Hyundai Mobis
12.9. BOE Varitronix Limited
12.10. Desay SV
12.11. ECARX Holdings Inc.
12.12. Qualcomm Technologies, Inc.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
13.7. Data Sources





Frequently asked questions
What is the projected market size and CAGR for automotive digital cockpits?
Market projected to reach $56.7 billion by 2031, growing at 7.8% CAGR.
Which region holds the largest share in the Automotive Digital Cockpit Market?
Asia Pacific accounts for 45% in 2026, growing to 48% by 2031.
Which system layer represents the largest market value in digital cockpits?
Digital displays and instrument clusters comprise 39% of 2026 market value.
What is the dominant architectural trend in the digital cockpit market?
Cockpit domain-consolidated architecture dominates, reaching 58% by 2031.
What is driving demand for automotive digital cockpits?
Increasing cockpit content per vehicle and advanced electronics integration.
Which vehicle segment accounts for most of the digital cockpit market value?
Passenger vehicles represent approximately 93% of global market value.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Automotive Digital Cockpit Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-digital-cockpit-market