
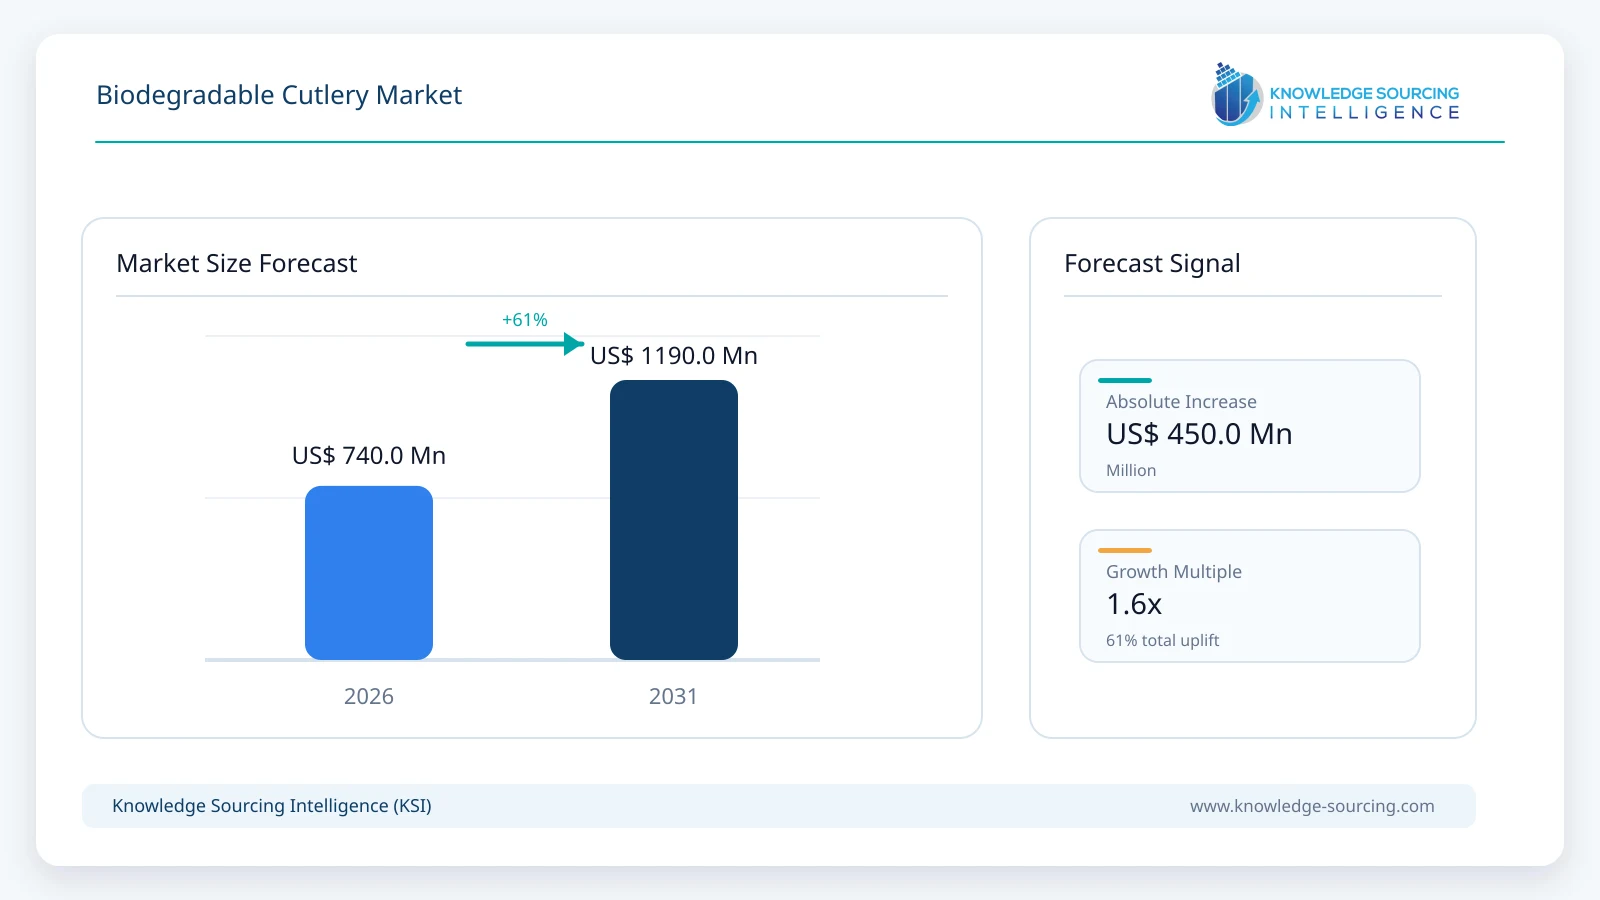
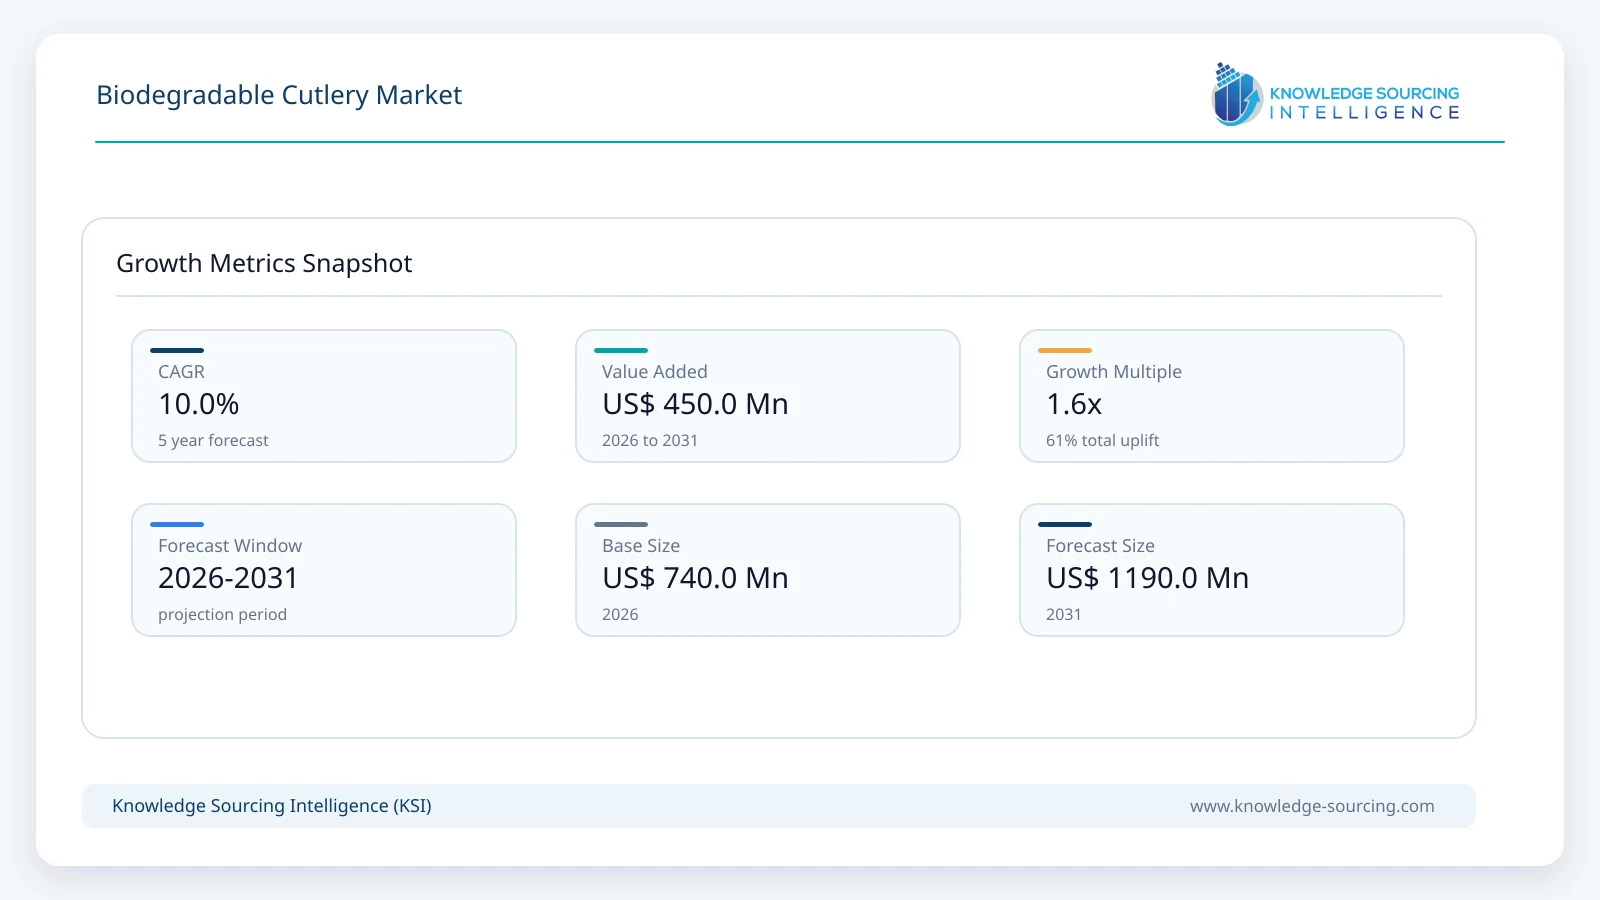
The Biodegradable Cutlery Market is projected to expand at a CAGR of 9.97%, reaching USD 1,190.0 million in 2031 from USD 740.0 million in 2026.
Highlights:
- 1Wood remains the largest material category, while engineered paper cutlery gains commercial traction.
- 2Commercial foodservice dominates demand through recurring restaurant, catering and institutional purchasing.
- 3Forks constitute the largest utensil category, alongside growing demand for specialty serving formats.
- 4Plastic restrictions encourage non-plastic alternatives, but compostability certification remains product- and jurisdiction-specific.
- 5Asia Pacific benefits from manufacturing scale; North America shows strong premium-format adoption.
Biodegradable cutlery comprises single-use forks, knives, spoons, sporks and related utensils made from materials capable of biological breakdown under defined conditions, including uncoated wood, suitable paper and molded plant fiber, and certified compostable polymers. Revenue arises from finished utensils sold into commercial foodservice and household channels; plates, food containers, straws, reusable metal utensils and upstream resin sales are distinct markets. Product performance and environmental claims are not interchangeable: certified industrial compostability, home compostability and simple biodegradability describe different outcomes.
Procurement is shaped by the interaction of food-contact compliance, hot-food durability, unit cost, and disposal options. Sabert sells pressed-paper EcoEdge cutlery, World Centric offers bamboo-paper NoTree utensils, and Fiberdom markets home-compostable plastic-free fiber alternatives. Compostable CPLA and PLA remain commercially available through companies such as Eco-Products and Eco Guardian, although legislation and local organics-collection rules determine where those products can be used and recovered. Foodservice distributors and brand owners must qualify the utensil and its packaging separately before writing customer sustainability specifications.
Market Overview
Restaurant operators are replacing conventional disposable plastic utensils with wooden, pressed-paper and molded-fiber designs where regulation or purchasing policy makes substitution necessary. Wood has a relatively direct processing chain but can create concerns about mouthfeel, splintering and moisture absorption. Pressed-paper utensils need sufficient lamination, shaping and coating control to preserve stiffness in soups, salads and other demanding foods. Their commercial success consequently depends as much on use performance as on the renewable content of the material.
Suppliers are increasingly selling purpose-built utensils rather than treating cutlery as an incidental addition to packaging contracts. World Centric's bamboo-paper NoTree range includes forks, knives, spoons and sporks intended for hot and cold foods; Sabert's EcoEdge uses pressed paperboard and emphasizes neck strength for heavier foods. Fiberdom's certified home-compostable cutlery addresses buyers who want to avoid plastic polymers entirely, while Vegware offers formed paper utensils with a sugar-based coating. These products illustrate different technical approaches to the same purchasing requirement and should not be assumed to have identical recovery characteristics.
The economics of the market are unusually sensitive to procurement format. Unwrapped bulk cases offer the lowest handling cost, while individually wrapped utensils, kits with napkins, and dispensing cartridges add converting, packaging and distribution expenses. A large caterer may require consistent case dimensions and traceable batch documentation; a household buyer often pays more per utensil for smaller packs. In both channels, a product promoted as compostable delivers its intended end-of-life benefit only when the corresponding collection and treatment route actually exists.
Market Trends
Paper and Molded Fiber Designs Are Improving in Mechanical Performance
Pressed paperboard cutlery has moved beyond thin, easily softened shapes through better forming pressure, multi-ply construction and surface finishes. Sabert's EcoEdge line is designed to preserve strength in hot and cold foods, while World Centric's NoTree products use certified bamboo paper and an oil- and grease-resistant coating. The relevant commercial test is whether a fork can hold a dense meal and a spoon can withstand prolonged wet contact without deforming; buyers compare those outcomes with wood and compostable polymers before changing specifications.
Premium paper construction can increase material and conversion cost, so these products are not necessarily a low-price replacement for plastic. Their strongest opportunity is in regulated markets and branded foodservice programs where a clearly non-plastic material is preferable to a polymer requiring industrial composting. Scale improvements will depend on consistent paper supply, efficient die-forming and reduced rejection rates.
Disposal Claims Are Becoming Part of Product Qualification
The EU Single-Use Plastics Directive restricts placing single-use plastic cutlery on the market, and its definition of plastic is broader than conventional fossil-based resins. A cutlery item made from PLA does not become exempt simply because a supplier describes it as biodegradable. Elsewhere, certification under applicable compostability standards and acceptance by local organics processors influence whether a foodservice customer can responsibly specify compostable polymer cutlery.
Manufacturers therefore face different material decisions across export markets. Fiber and wood products still require responsible sourcing and credible claims, while industrially compostable products require evidence for disintegration, biodegradation and food-contact safety. The ability to give buyers accurate disposal instructions is becoming a differentiator alongside product strength, especially for multinational restaurant and event contracts.
Case-Level Purchasing Is Increasingly Linked to Waste Prevention
Large hospitality buyers are increasingly concerned with how many utensils are dispensed, not only their material. Eco-Products' Cutlerease system uses individually issued certified-compostable PLA utensils to reduce contact and unnecessary take-up. That model adds equipment and refill logistics but may lower overall consumption where customers previously took multiple utensils from open bins.
Foodservice purchasing teams also compare wrapped and unwrapped kits, napkins, condiment packs, and different utensil lengths. A lighter tasting spoon sold in bulk has a different economic profile from a full-size knife individually wrapped for delivery. This pushes suppliers toward differentiated portfolios rather than a single material or form factor for every eating occasion.
Commercial Composting Programs Are Being Tested in Real Settings
Vegware reported a September 2025 partnership involving Forest Green Rovers and waste-management provider Grundon, with plant-based cutlery among the serviceware collected for composting. Such programs matter because contamination, collection systems and composting-facility acceptance can determine whether a certified product achieves its environmental objective. High-throughput venues provide a practical test of bin placement, staff training and product segregation.
The operational requirements are demanding: mixed packaging, food residue and non-compostable substitutes can disrupt collection. Suppliers offering technical specifications, matching serviceware and practical end-of-life guidance can earn repeat contracts, although conventional disposal is still common in regions without dedicated collection infrastructure.
Segment Analysis
By Type: Wood
Wooden utensils account for an estimated 40% of the biodegradable cutlery market in 2026, making wood the largest material group. Cut and formed wood requires no compostable-plastic certification to establish that it is not a conventional plastic product, and widely available supply supports large foodservice tenders. Restaurants favor the recognizable appearance and broad temperature tolerance, while manufacturers must control surface finish, splinter risk and food-contact suitability.
Wood's relative position is expected to moderate as better pressed-paper and molded-fiber products become available for uses requiring a smoother mouthfeel or more complex shaping. BioPak's offering illustrates the continuing range of wooden forks, knives, spoons and branded kits. Buyers will continue to favor wood when predictable performance and procurement cost matter more than premium tactile characteristics.
By Product Type: Fork
Single-use forks lead the product mix because they are used across salads, takeaway meals and general catering, and are frequently included in multi-piece kits. Their prong geometry requires strength without sharp edges or breakage, making the design challenge greater than that of many simple stirring implements. Paper and molded-fiber manufacturers have responded with reinforced necks and shaped tines intended for denser foods.
The fork segment is projected to reach approximately USD 440 million by 2031 as foodservice purchasing shifts toward alternatives designed for everyday meal use. Forks will remain a recurring-volume product, although specialty sporks, tasting utensils and dessert spoons grow faster in settings where one format can replace multiple pieces.
By End-User: Commercial
Restaurants, contract caterers, universities, hospitals, travel operators and event organizers generate recurring purchases of biodegradable cutlery in cartons and customized kits. The commercial channel places particular emphasis on volume availability, documented material claims, pricing stability and reliable delivery. Packaging often accounts for a meaningful part of the specification, especially in individually wrapped food-delivery formats.
Commercial consumption is expected to generate close to USD 1.00 billion by 2031, reflecting its continued central role in the market. Fiberdom's retail partnerships show that household distribution is expanding, but foodservice contracts remain the most important route to scale. Buyers increasingly evaluate functional testing and recovery logistics rather than selecting utensils solely on the basis of a sustainability claim.
Market Drivers
Restrictions on Disposable Plastic Cutlery
India's nationwide prohibition of specified single-use plastic cutlery has been effective since July 2022, while the EU Single-Use Plastics Directive restricts plastic forks, spoons and knives in its markets. These regulations shift demand toward commercially available wood, paper and other qualifying non-plastic alternatives. The scope of each law matters, since a biodegradable polymer is not automatically outside a plastic restriction.
For manufacturers, local compliance creates an incentive to offer multiple materials with documented composition. Export-oriented producers can win larger accounts when they supply appropriate products for several jurisdictions, but a one-material global strategy may create regulatory exposure.
Expansion of Food-to-Go and Institutional Dining
Quick-service chains, institutional kitchens and prepared-meal businesses use disposable utensils at high frequency, particularly where reusable-item collection is impractical. A small change in the number of utensils per order can affect annual procurement materially. The sector therefore rewards consistent supply, practical packaging formats and standardized specifications across many outlets.
Commercial buyers frequently award contracts on landed cost and performance rather than environmental claims alone. Suppliers that can deliver reliable bulk cartons and tailored kits are better positioned to convert pilot trials into regular purchasing programs.
Improved Fiber Forming and Surface Treatment
Wood-free pressed-paper designs increasingly compete with traditional wooden utensils by addressing stiffness, taste and wet-use performance. Sabert's formed paperboard products and World Centric's bamboo-paper line demonstrate that fiber engineering can extend the usable application range beyond dry snacks and simple spoons. Performance depends on the full utensil structure, not merely the renewable origin of the paper.
Better forming yields and low-defect conversion are essential to keeping prices within foodservice budgets. Suppliers able to make stronger fiber products at scale can reduce the need for separate polymer-based lines in jurisdictions that restrict disposable plastics.
Procurement Standards and Sustainability Audits
Multinational restaurant groups increasingly ask suppliers for traceable material sources, food-contact documentation, and evidence supporting environmental labeling. A compostability logo is not a substitute for an appropriate standard or waste-route qualification. These requirements favor manufacturers with consistent production controls and practical documentation of each specific item.
Certification and testing add upfront expense but can shorten qualification time for large contracts. They also make it easier for procurement teams to compare otherwise similar forks or spoons without relying on unverified environmental descriptions.
Higher-Value Formats and Consumption Control
Individually wrapped utensils, closed dispensing systems, and coordinated meal kits allow vendors to sell more than an undifferentiated loose fork. Eco-Products' dispensing concept illustrates how a branded product can combine certified cutlery with hygienic handling and potential waste reduction. Foodservice operators may accept a higher purchase price when it reduces unnecessary use or labor.
This opportunity is not universal; low-cost takeaway outlets may continue to purchase the simplest bulk alternative. Nevertheless, format innovation can support revenue per unit in institutional, travel and premium catering settings.
Market Restraints
Higher Cost than Conventional Disposable Plastics
Wood, multilayer paper and certified compostable materials typically face a tighter cost position than mass-produced fossil-based plastic utensils, particularly in smaller orders. Added pressing, finishing or wrapping steps can compound the premium. Catering businesses with high disposable-item volumes may respond by issuing cutlery only on request or shifting suitable meals toward reusable utensils.
The cost barrier is strongest where a plastic restriction is not in place and buyers have limited budget flexibility. Manufacturers must reduce conversion losses and optimize case logistics rather than assuming sustainable-material preference alone supports pricing.
Composting Infrastructure and Acceptance Gaps
A utensil certified for industrial composting may still enter landfill or residual waste when food-waste collection is unavailable. Facilities can also reject some compostable serviceware because of contamination risk or local processing constraints. Product claims must therefore specify the intended environment and cannot promise rapid breakdown under every disposal condition.
This limits the addressable demand for polymer cutlery in locations without reliable recovery routes. Manufacturers that make home-compostable or non-plastic alternatives may gain an advantage, though those formats also require accurate material claims and suitable conditions.
Performance Trade-Offs in Wet and Hot Foods
Paper cutlery can soften, wooden forks may splinter or feel rough, and some lower-temperature compostable polymers can deform in hot dishes. These failure modes are visible to consumers and can quickly disqualify a product from restaurant service. Customers commonly test utensils against realistic food loads instead of accepting laboratory compostability as evidence of use performance.
Meeting stronger performance requirements often increases material input or processing complexity. Design improvements must deliver a measurable benefit without pushing the unit price above a buyer's allowable cost.
Regulatory Differences Across Material Classes
A biodegradable or compostable polymer can remain legally defined as plastic, creating problems for suppliers that assume certification guarantees permission to sell. The EU's treatment of single-use plastic cutlery illustrates the importance of material definitions, while India has its own product restrictions. Export manufacturers must therefore maintain market-specific specifications and labels.
Regulatory divergence can complicate inventory management and supplier contracts. A paper or wooden utensil accepted in one market may also be subject to separate food-contact, sourcing or waste-labeling requirements in another.
Competition from Reusable and No-Cutlery Service Models
Biodegradable utensils are not the only response to disposable-plastic restrictions. Dine-in operators can use washable metal cutlery, while takeaway platforms can let customers opt out of disposable utensils altogether. Both approaches reduce the number of single-use pieces sold, even when environmental policy is becoming stricter.
For suppliers, this creates an incentive to target meals and venues where disposable serviceware remains necessary. An increase in sustainable packaging adoption should not be equated automatically with an increase in total disposable-cutlery unit demand.
Regional Outlook
Asia Pacific
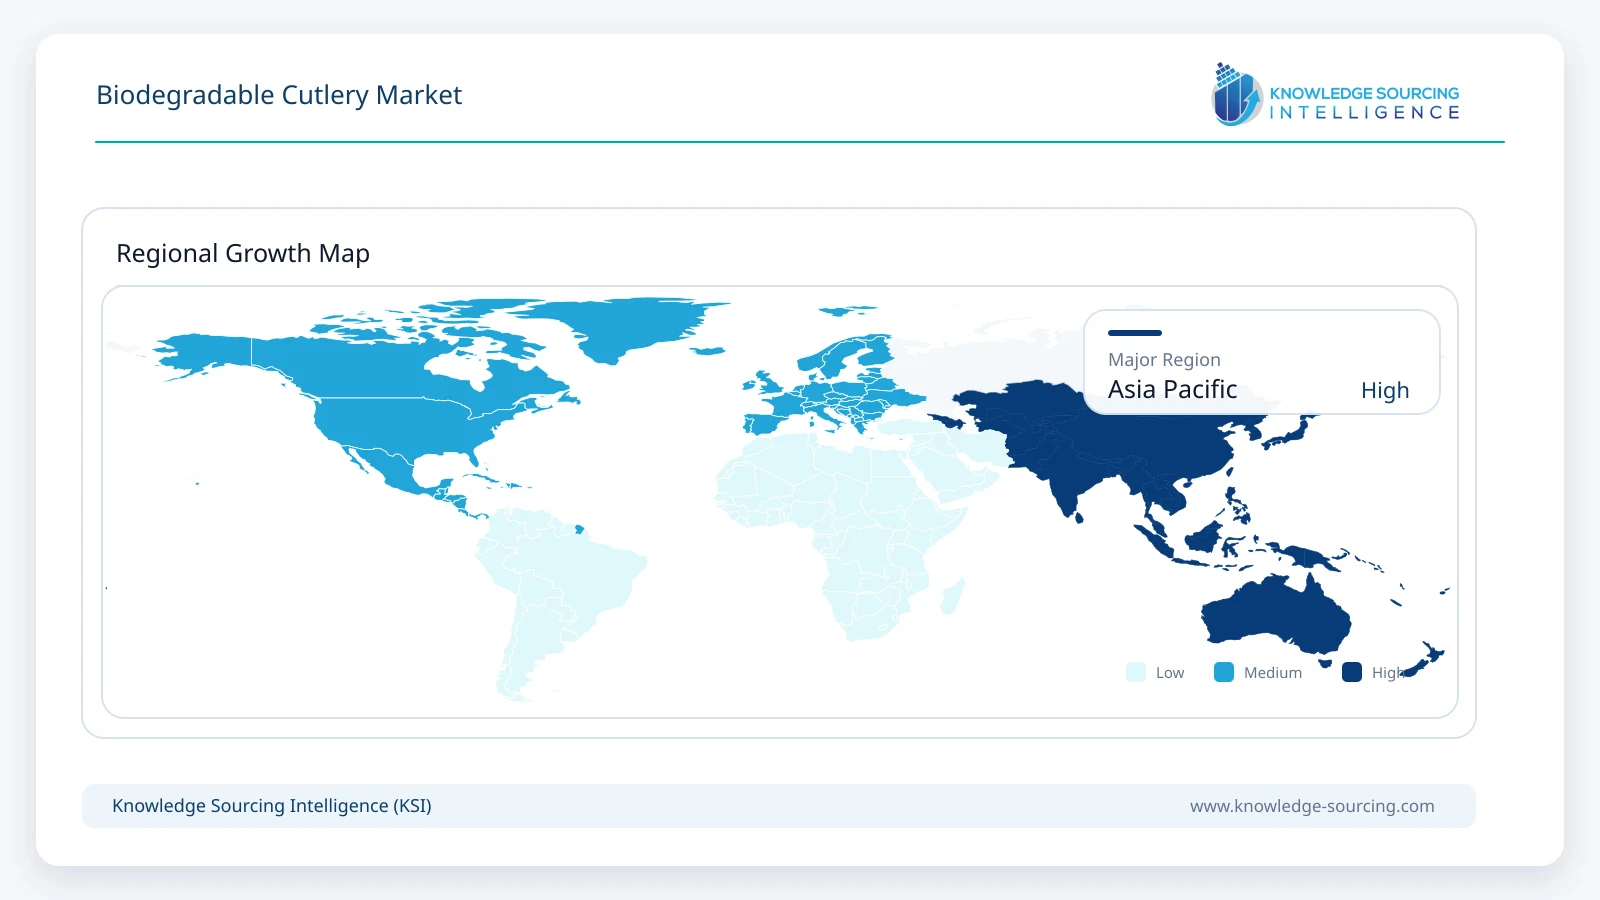
Asia Pacific accounts for an estimated 36% of 2026 global market value, supported by large foodservice markets, export-oriented utensil manufacturing and the substitution of disposable plastic in countries such as India. China provides substantial production capability across paper, wood and plant-based materials, while Japan and South Korea offer demand for standardized foodservice formats. The region's larger physical volumes do not necessarily translate into the highest realized price per utensil.
Growth remains dependent on the relative affordability of renewable materials and on local regulations, which differ considerably across countries. Producers able to meet export product standards while serving domestic restaurant chains are positioned to benefit from manufacturing scale. The outlook also allows for stronger paper and molded-fiber demand as buyers seek products that avoid restrictions applying to disposable plastic utensils.
North America
World Centric's expansion into bamboo-paper cutlery and Eco-Products' certified cutlery dispensing formats show how North American competition extends beyond basic material replacement. Institutional buyers value predictable performance, credible labeling, selective dispensing and product systems that can be incorporated into existing foodservice logistics. The United States represents the largest underlying national market, with Canadian and Mexican demand shaped by different regulatory and procurement conditions.
North America is modelled to expand at approximately 11.7% annually through 2031, faster than the other regions in the base case. Premium engineered-fiber products and foodservice programs account for much of the relative growth, although access to organics treatment remains uneven. Product certification and recovery-system compatibility will continue to influence how quickly new formats can scale.
Competitive Landscape
Huhtamaki participates in global foodservice packaging and utensils, supported by international manufacturing and procurement capabilities, while Sabert specializes in formed paperboard EcoEdge cutlery and other foodservice formats. World Centric has established bamboo-paper, molded-fiber and compostable-polymer ranges; Vegware markets paper and plant-based cutlery in institutional foodservice channels. Their product strategies differ in material technology, certification and the handling requirements of different food settings.
Specialist suppliers such as Fiberdom compete through distinctive fiber formulations and home-compostable plastic-free products, while deSter applies paper-cutlery engineering to travel catering and large events. BioPak and Eco Guardian supply commercial cutlery portfolios, and Eco-Products combines compostable utensils with dispensing systems. Bioleader and other Asian manufacturers contribute contract manufacturing and product diversity. Company size is not a reliable proxy for share within biodegradable cutlery because revenue is usually reported within broader foodservice packaging divisions.
Competition is likely to concentrate on functional quality and documentation rather than simply expanding the number of materials offered. Consistency in hot and wet food, sourcing traceability, customer-specific wrapping, and certification claims can determine contract outcomes. Suppliers able to produce a small range of dependable, economically viable formats may outperform portfolios that are broad but difficult for buyers to qualify.
Recent Developments
7 August 2026: deSter reported use of its KAMI compostable paper cutlery at Tomorrowland 2026 alongside reusable serviceware, demonstrating use of a direct manufacturer’s utensils in a high-throughput festival setting.
26 September 2025: Vegware announced a partnership with Forest Green Rovers and Grundon incorporating compostable cutlery and collection arrangements at matchday foodservice outlets.
26 June 2025: World Centric introduced its FSC-certified bamboo-paper NoTree cutlery range for hot and cold food, available as forks, knives, spoons and sporks.
6 March 2025: Fiberdom announced a distribution partnership with Finland’s S Group for its home-compostable, plastic-free cutlery, including a newly introduced small spoon.
Market Outlook
The fastest technical gains are likely to come from stronger pressed-paper and molded-fiber designs that can replace existing cutlery in a wider variety of food applications. Conventional wooden utensils will retain a large volume position because they are recognizable, relatively simple, and widely available. Certified compostable polymers remain relevant in markets with compatible regulation and waste treatment, but they are unlikely to be a universal solution.
Foodservice contracts will increasingly assess the total cost of the utensil in use, including packaging, breakage, dispensing and disposal logistics. Manufacturers that offer a predictable product, accurate certification claims and dependable supply will be better placed to capture long-term purchasing programs. Asia Pacific should continue to represent the largest regional market, while North America provides stronger scope for higher-value formats and market-share shifts toward engineered fiber.
Regulation and waste collection will not move together everywhere. The competitive advantage is therefore likely to come from material-specific product engineering and careful adaptation to the local end-of-life system, rather than from any blanket claim that a disposable product is environmentally harmless.
Biodegradable Cutlery Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 740.0 million |
| Total Market Size in 2031 | USD 1,190.0 million |
| Forecast Unit | Million |
| Growth Rate | 9.97% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Product Type, End-user, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Wood
Paper
Plastic
Others
By Product Type
Fork
Knife
Spoon
Others
By End-user
Commercial
Residential
By Geography
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
North America
United States
Canada
Mexico
Europe
United Kingdom
Germany
France
Italy
Spain
Others
South America
Brazil
Argentina
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Global Market Size and Forecast, 2026–2031
1.3. Segment and Regional Highlights
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Restrictions on Disposable Plastic Cutlery
3.1.2. Expansion of Food-to-Go and Institutional Dining
3.1.3. Improved Fiber Forming and Surface Treatment
3.1.4. Procurement Standards and Sustainability Audits
3.1.5. Higher-Value Formats and Consumption Control
3.2. Market Restraints
3.2.1. Higher Cost than Conventional Disposable Plastics
3.2.2. Composting Infrastructure and Acceptance Gaps
3.2.3. Performance Trade-Offs in Wet and Hot Foods
3.2.4. Regulatory Differences Across Material Classes
3.2.5. Competition from Reusable and No-Cutlery Service Models
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Pressed Paperboard and Fiber Forming
4.2. Wooden Cutlery Processing
4.3. Certified Compostable Biopolymers
4.4. Food-Contact and End-of-Life Qualification
5. BIODEGRADABLE CUTLERY MARKET BY TYPE
5.1. Introduction
5.2. Wood
5.3. Paper
5.4. Plastic
5.5. Others
6. BIODEGRADABLE CUTLERY MARKET BY PRODUCT TYPE
6.1. Introduction
6.2. Fork
6.3. Knife
6.4. Spoon
6.5. Others
7. BIODEGRADABLE CUTLERY MARKET BY END-USER
7.1. Introduction
7.2. Commercial
7.3. Residential
8. BIODEGRADABLE CUTLERY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. Asia Pacific
8.2.1. China
8.2.2. India
8.2.3. Japan
8.2.4. South Korea
8.2.5. Taiwan
8.2.6. Thailand
8.2.7. Indonesia
8.2.8. Others
8.3. North America
8.3.1. United States
8.3.2. Canada
8.3.3. Mexico
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. South America
8.5.1. Brazil
8.5.2. Argentina
8.5.3. Others
8.6. Middle East and Africa
8.6.1. Saudi Arabia
8.6.2. United Arab Emirates
8.6.3. South Africa
8.6.4. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Huhtamäki Oyj
10.2. Sabert Corporation
10.3. World Centric
10.4. Vegware Ltd.
10.5. Fiberdom Oy
10.6. deSter Holding B.V.
10.7. Eco-Products, PBC
10.8. BioPak
10.9. Eco Guardian Inc.
10.10. Bioleader (Xiamen)
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits to Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market value of biodegradable cutlery by 2031?
USD 1,190.0 million by 2031, growing at 9.97% CAGR.
Which materials dominate the Biodegradable Cutlery Market?
Wood remains largest; engineered paper cutlery gains commercial traction.
Which sector primarily drives biodegradable cutlery demand?
Commercial foodservice dominates demand through recurring restaurant and institutional purchasing.
What is the largest biodegradable utensil category?
Forks constitute the largest utensil category.
Which regions show key Biodegradable Cutlery Market dynamics?
Asia Pacific benefits from manufacturing scale; North America adopts premium formats.
What key factors shape biodegradable cutlery procurement?
Food-contact compliance, hot-food durability, unit cost, and disposal options.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Biodegradable Cutlery Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/biodegradable-cutlery-market