
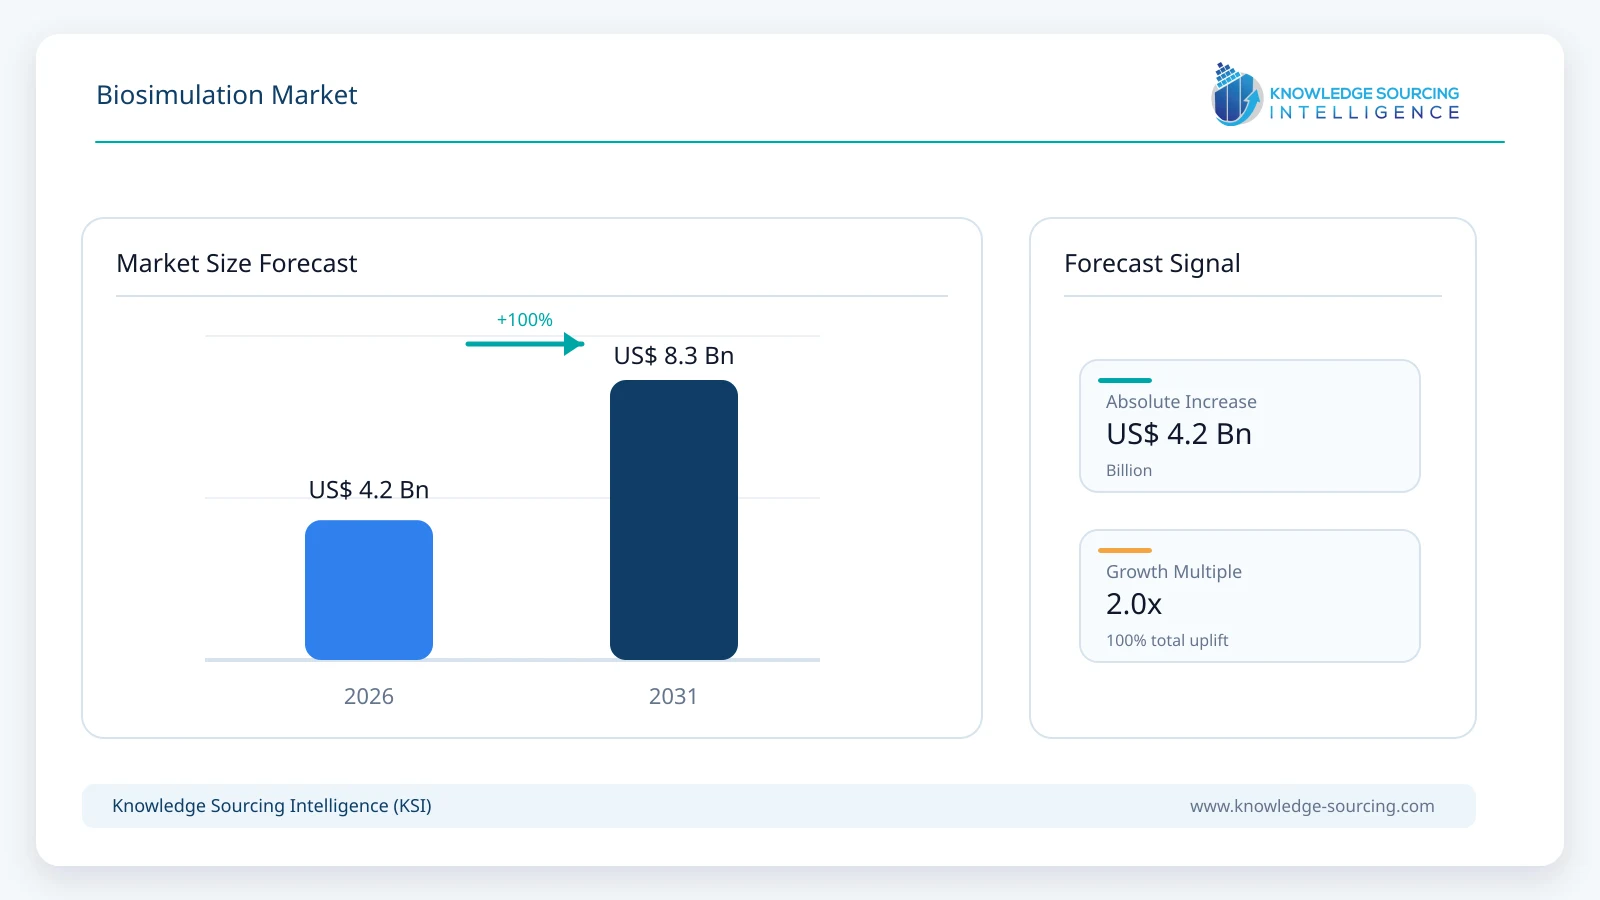
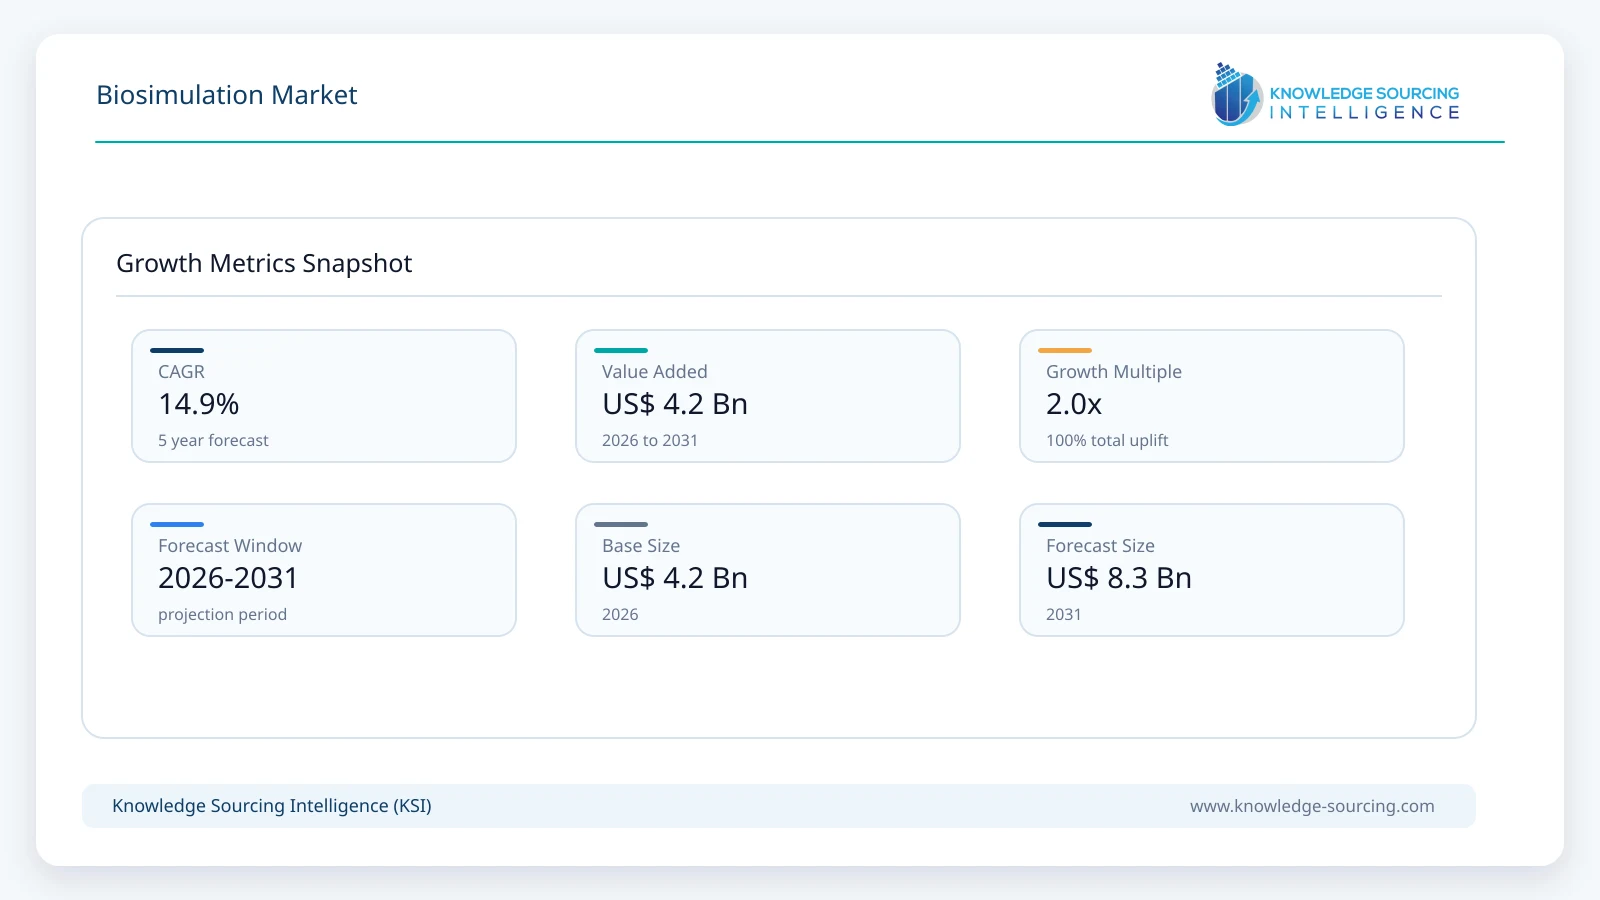
The global biosimulation market is forecast to grow at a CAGR of 14.9%, reaching USD 8.33 billion in 2031 from USD 4.16 billion in 2026.
Highlights:
- 1Software platforms account for approximately 61% of global biosimulation revenue in 2026.
- 2Services are projected to grow at approximately 16.4% annually through 2031.
- 3Drug development applications generate about USD 2.37 billion in 2026 market value.
- 4Pharmaceutical and biotechnology companies account for approximately 70% of 2026 spending.
- 5North America represents approximately 46% of global biosimulation revenue in 2026.
- 6Asia Pacific is projected to grow at approximately 17.4% annually through 2031.
Market Overview
Biosimulation is used to turn experimental, clinical, and biological knowledge into quantitative models that can be tested repeatedly without running a physical study for every scenario. PBPK models simulate drug absorption, distribution, metabolism, and elimination across organs and patient populations. Population PK/PD models quantify exposure-response relationships and variability. QSP models connect drug action with biological pathways and disease mechanisms, while molecular dynamics and physics-based simulations evaluate interactions at the molecular level. These approaches increasingly connect with clinical trial simulation, virtual populations, toxicology prediction, and digital-twin concepts as computing capacity and biological data improve.
The market is commercially diverse. Certara generated USD 418.8 million of revenue in 2025, including USD 183.3 million from software and USD 235.6 million from services, while Simulations Plus reported preliminary fiscal 2025 revenue of USD 79.1 million with software representing about 58% of its mix. Schrodinger generated USD 199.5 million of software revenue in 2025 from a broader computational platform spanning molecular discovery and simulation. These companies capture only part of the addressable market because internal pharmaceutical modeling teams, specialist consultancies, QSP providers, academic spinouts and broader life-sciences software groups also participate. The market estimate therefore includes both licensed software and externally purchased modeling, simulation and related scientific services, while excluding general-purpose laboratory informatics and unrelated CRO activity.
Market Trends
Regulatory acceptance is moving from case-by-case use toward a more standardized MIDD framework
Model-informed drug development has been used for years, but the regulatory environment is becoming more structured. FDA issued final ICH M15 guidance in June 2026 covering MIDD planning, model evaluation, documentation and regulatory interaction. EMA adopted the same guideline with a legal effective date of July 23, 2026. FDA's MIDD Paired Meeting Program also continues through fiscal 2027, giving sponsors a formal route to discuss dose selection, clinical trial simulation, mechanistic safety evaluation and other model-informed strategies. The effect on the commercial market is important because standardized expectations reduce uncertainty around how models should be planned, validated, and reported, increasing demand for software with traceable workflows and for specialists who can defend model assumptions in regulatory submissions.
AI is being layered onto mechanistic simulation rather than simply replacing physics-based models
Biosimulation vendors are increasingly combining mechanistic models with machine learning, agentic workflows and cloud computing. Schrodinger introduced Bunsen in July 2026 as an AI co-scientist designed to plan and execute workflows using its physics-based molecular discovery platform, and later announced a strategic deployment agreement with Bristol Myers Squibb. Simulations Plus has highlighted the integration of PBPK, QSP, predictive modeling and AI-augmented mechanistic approaches, while Certara is extending its biosimulation software around regulatory workflows and larger virtual populations. The commercial implication is a shift from single-purpose modeling tools toward connected environments where experimental data, mechanistic knowledge, predictive algorithms, and simulation outputs can be used within the same decision cycle.
Market Drivers
Validated simulation can reduce dedicated study burden and improve dose and trial-design decisions
The strongest economic driver is not the elimination of physical studies but the ability to answer some questions earlier, test more scenarios and avoid unnecessary development work. FDA states that MIDD can support dose selection, clinical trial simulation, and predictive or mechanistic safety evaluation. In March 2026, Certara reported that Simcyp PBPK modeling for asciminib was accepted by FDA in lieu of ten clinical pharmacology studies supporting the drug's application. Such cases demonstrate how a validated model can create direct value by reducing study burden, shortening decision cycles and allowing evidence to be reused across development questions. As development programs become more global and patient populations more segmented, sponsors also use virtual populations to investigate drug-interactions, organ impairment, age, ethnicity and other sources of variability before deciding which physical studies remain necessary.
New approach methodologies increase demand for human-relevant computational evidence
Regulatory and funding agencies are broadening the scientific toolkit beyond conventional animal models. In April 2025, FDA announced a roadmap to reduce, refine, or potentially replace some animal testing in monoclonal antibody and other drug development using approaches that include AI-based computational toxicity models, cell lines and organoids. NIH followed with initiatives to prioritize human-based research technologies and created the Office of Research Innovation, Validation, and Application in June 2026 to coordinate the development and validation of NAMs, including computational tools. These policies do not make biosimulation a standalone substitute for all preclinical testing, but they increase the value of models that can integrate in vitro, omics, clinical, and mechanistic data into human-relevant predictions.
Market Restraint
Model credibility depends on data quality, validation and specialist expertise, limiting routine use
Biosimulation can only influence high-stakes development decisions when the model is fit for its stated context of use. Sparse biological data, uncertain parameter values, inconsistent source datasets and poorly characterized disease mechanisms can produce precise-looking outputs that are not sufficiently reliable for decision-making. ICH M15 therefore places emphasis on model planning, risk assessment, evaluation and documentation rather than treating simulation output as evidence by default. The skills constraint is also material: sophisticated PBPK, QSP and population models require teams that understand biology, pharmacology, statistics, computation and regulatory science. Smaller biotechnology companies frequently rely on external specialists because maintaining all of this expertise internally is expensive. This supports services revenue but can slow adoption where budgets are limited or data are not mature enough to justify complex modeling.
Segment Analysis
By Type - Services
Biosimulation services are projected to reach approximately USD 3.47 billion in revenue by 2031. The segment includes model development, pharmacometric analysis, QSP and PBPK consulting, virtual trial design, regulatory strategy, model qualification support and outsourced simulation work. Its growth is faster than the broader software segment because many sponsors buy software and specialist expertise together, particularly when a model will support a regulatory interaction or when internal teams do not have enough capacity. Certara's 2025 results illustrate this mixed model: services remained larger than software in reported revenue, and fourth-quarter service bookings increased 17% year over year even as quarterly service revenue was slightly lower. Specialist firms such as Metrum Research Group, Rosa & Co., Physiomics and Pumas-AI also compete by combining modeling expertise with software or reusable scientific frameworks.
By Application - Drug Development
Drug development applications are projected to reach approximately USD 4.77 billion by 2031. Demand spans first-in-human planning, dose and regimen optimization, drug-drug interaction assessment, special-population analysis, formulation and bioequivalence questions, exposure-response modeling and clinical trial simulation. Regulatory acceptance gives this segment a stronger willingness to pay than exploratory modeling alone because the output can influence protocol design, study waivers, labeling and submission strategy. PBPK is particularly established for interaction and population questions, while population PK/PD and QSP are used to connect exposure, biomarkers, efficacy and safety. Drug discovery is growing faster from a smaller base as physics-based molecular simulation, predictive toxicology and AI-assisted workflows move earlier in candidate selection.
By End User - Pharmaceutical and Biotechnology Companies
Pharmaceutical and biotechnology companies are projected to generate approximately USD 5.73 billion of biosimulation spending by 2031. Large pharmaceutical companies maintain internal pharmacometrics and computational chemistry groups but continue to license external platforms and purchase specialized services for peak capacity, disease-specific modeling and regulatory support. Smaller biotechnology firms often depend more heavily on external providers because their development programs do not justify maintaining full-time PBPK, QSP and pharmacometric teams. Academic institutions remain important for method development and training, while CROs and specialist research organizations are growing as users and resellers of modeling capabilities embedded within wider development programs.
By Geography - Asia Pacific
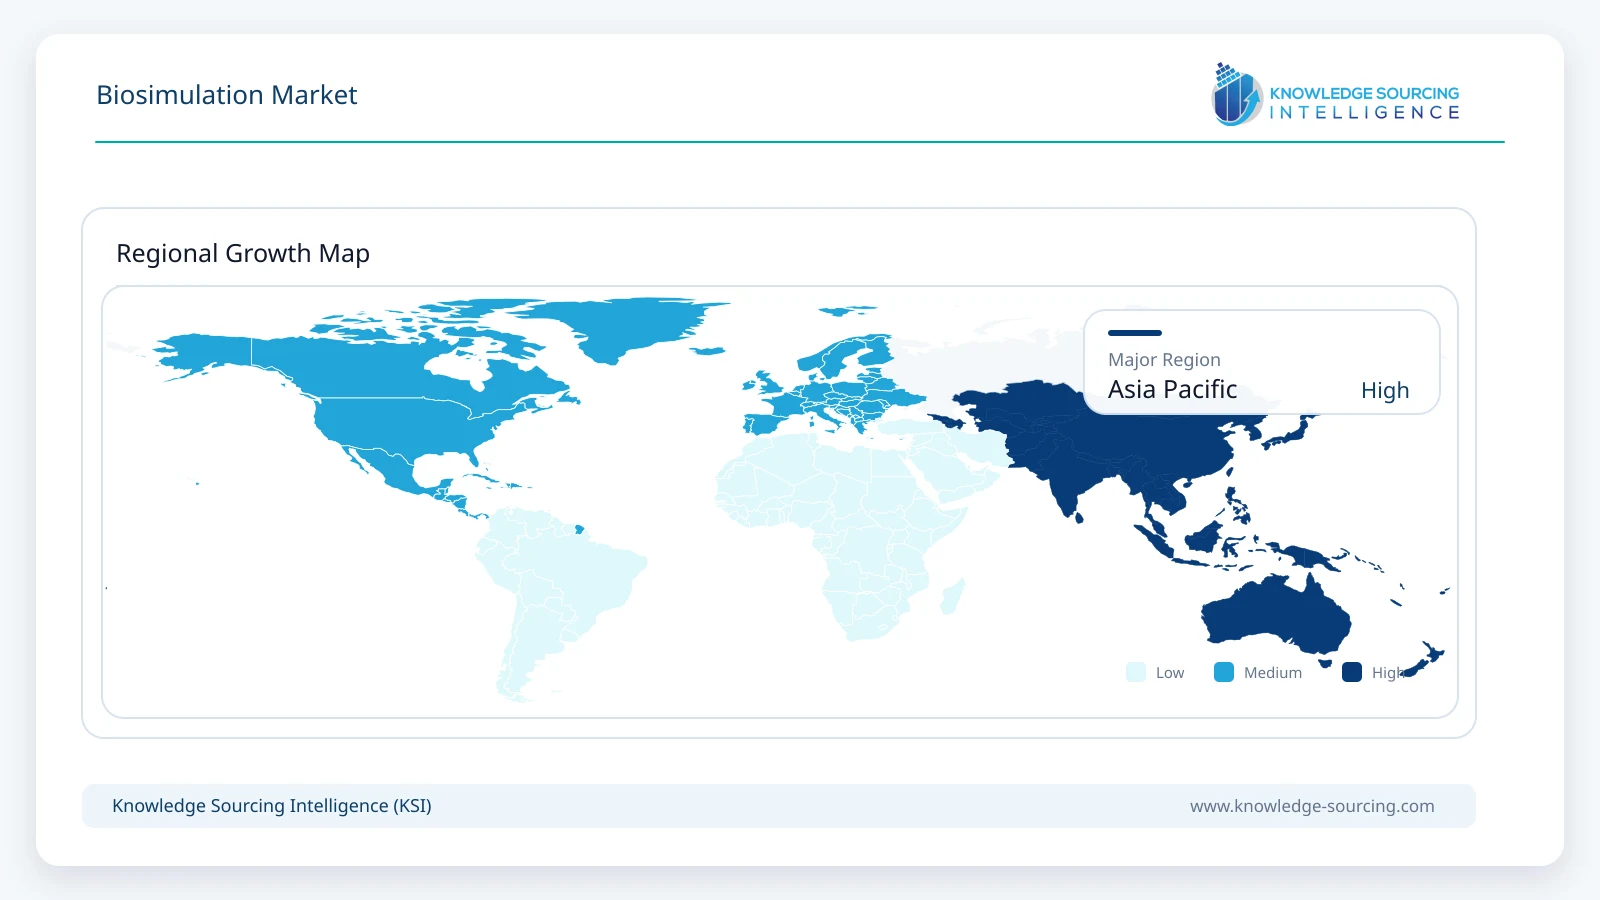
Asia Pacific is projected to approach USD 1.95 billion in biosimulation revenue by 2031. The region is expanding from a smaller installed base than North America but benefits from growth in biopharmaceutical research, clinical development, contract research and domestic drug innovation across China, Japan, South Korea, India, Singapore and Australia. Multinational software suppliers are increasing cloud delivery and regional technical support, while local pharmaceutical companies are building pharmacometrics and computational drug-development teams. North America remains the largest regional market because of its concentration of biopharma R&D, specialist vendors and FDA-linked MIDD activity. Europe retains a strong position through EMA regulatory science, academic modeling networks and pharmaceutical R&D centers.
Competitive Environment
Competition spans three overlapping groups: established biosimulation platforms, broader computational drug-discovery software companies and specialist modeling consultancies. Certara has one of the strongest positions in regulatory-facing biosimulation through Simcyp, Phoenix, QSP and related services. Simulations Plus competes through GastroPlus, MonolixSuite, DILIsym and complementary consulting, while Schrodinger is strongest in physics-based molecular simulation and increasingly combines that capability with AI and enterprise collaboration. Dassault Systemes, Genedata and Chemical Computing Group participate through broader discovery, modeling and scientific informatics portfolios, while smaller specialists compete in QSP, pharmacometrics, virtual patient modeling and regulatory consulting.
Competitive differentiation increasingly depends on regulatory credibility, validated model libraries, scientific support and integration rather than raw compute alone. EMA's 2025 qualification opinion for the Simcyp Simulator strengthened the importance of platform validation in PBPK, while hosted and cloud deployment is becoming a commercial requirement as users run larger virtual populations and connect models with enterprise data. Schrodinger is accelerating its transition toward hosted licensing, and Certara continues to expand Simcyp around regulatory submissions. Smaller providers can still compete where disease-specific expertise, faster customization, or high-touch consulting matters more than platform breadth.
Recent Developments
August 2026: Schrodinger announced a strategic Bunsen deployment agreement with Bristol Myers Squibb.
July 2026: Schrodinger introduced Bunsen, combining agentic AI with physics-based molecular simulation workflows.
July 2026: Physiomics secured multiple modeling and biometrics contracts valued above GBP 200,000 combined.
June 2026: FDA finalized ICH M15 guidance establishing harmonized principles for model-informed drug development.
March 2026: Certara released Simcyp Simulator Version 25 with expanded regulatory and modeling capabilities.
March 2026: Certara reported FDA acceptance of Simcyp analyses replacing ten asciminib clinical pharmacology studies.
Biosimulation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.16 billion |
| Total Market Size in 2031 | USD 8.33 billion |
| Forecast Unit | Billion |
| Growth Rate | 14.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, End-user, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Software
Services
By Application
Drug Development
Drug Discovery
Others
By End User
Pharmaceutical and Biotechnology Companies
Academic Institutions
CROs and Research Organizations
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Singapore
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Validated Simulation Can Reduce Dedicated Study Burden and Improve Dose and Trial-Design Decisions
3.1.2. New Approach Methodologies Increase Demand for Human-Relevant Computational Evidence
3.2. Market Restraint
3.2.1. Model Credibility Depends on Data Quality, Validation and Specialist Expertise
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Physiologically Based Pharmacokinetic Modeling
4.2. Quantitative Systems Pharmacology
4.3. Population PK/PD and Pharmacometrics
4.4. Molecular Dynamics and Physics-Based Simulation
4.5. AI-Augmented Biosimulation and Virtual Patients
5. BIOSIMULATION MARKET BY TYPE
5.1. Introduction
5.2. Software
5.3. Services
6. BIOSIMULATION MARKET BY APPLICATION
6.1. Introduction
6.2. Drug Development
6.3. Drug Discovery
6.4. Others
7. BIOSIMULATION MARKET BY END USER
7.1. Introduction
7.2. Pharmaceutical and Biotechnology Companies
7.3. Academic Institutions
7.4. CROs and Research Organizations
7.5. Others
8. BIOSIMULATION MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Australia
8.6.6. Singapore
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Certara, Inc.
10.2. Simulations Plus, Inc.
10.3. Schrodinger, Inc.
10.4. Dassault Systemes SE
10.5. Genedata AG (Danaher Corporation)
10.6. Chemical Computing Group ULC
10.7. Pumas-AI, Inc.
10.8. Metrum Research Group
10.9. Rosa & Co. LLC
10.10. Physiomics plc
10.11. Immunetrics, Inc.
10.12. InSilicoTrials Technologies S.p.A.
10.13. VeriSIM Life, Inc.
10.14. Insilico Medicine
10.15. Gubra A/S
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected Biosimulation Market size by 2031?
The Biosimulation Market is projected to reach USD 8.33 billion by 2031.
What is the projected CAGR for the Biosimulation Market (2026-2031)?
The Biosimulation Market is forecast to grow at a 14.9% CAGR.
Which application generates the most Biosimulation Market value in 2026?
Drug development applications generate about USD 2.37 billion in 2026.
Which segment accounts for the largest Biosimulation Market revenue in 2026?
Software platforms account for approximately 61% of global revenue in 2026.
Which industry accounts for the most biosimulation spending in 2026?
Pharmaceutical and biotechnology companies account for 70% of 2026 spending.
Which region is projected for the fastest growth in the Biosimulation Market?
Asia Pacific is projected to grow at approximately 17.4% annually through 2031.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Biosimulation Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/biosimulation-market