
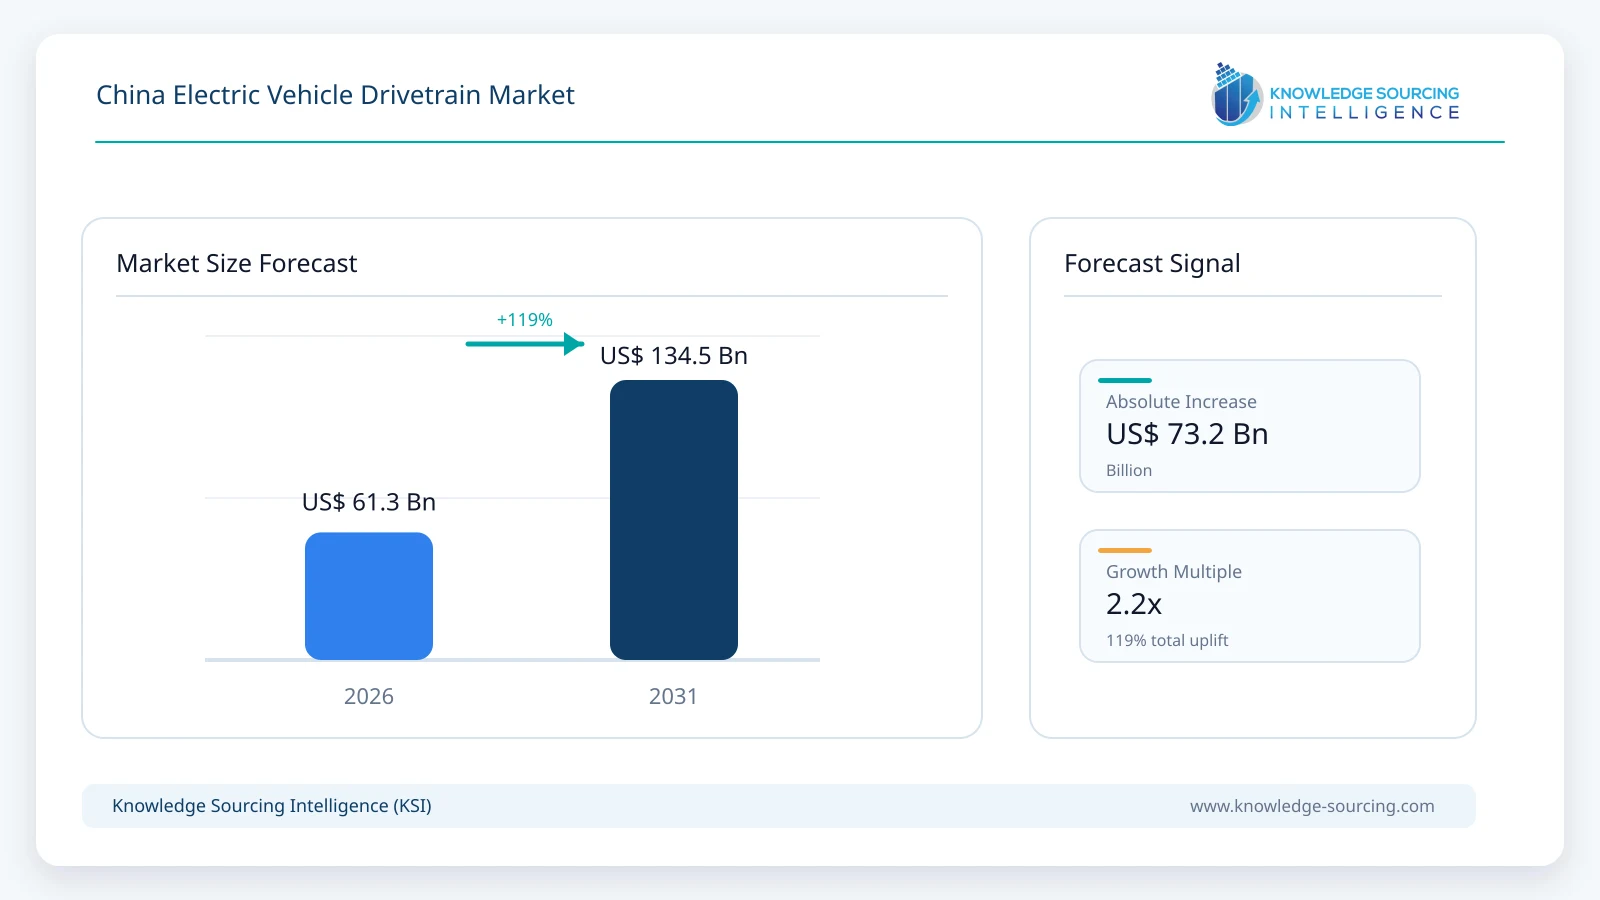
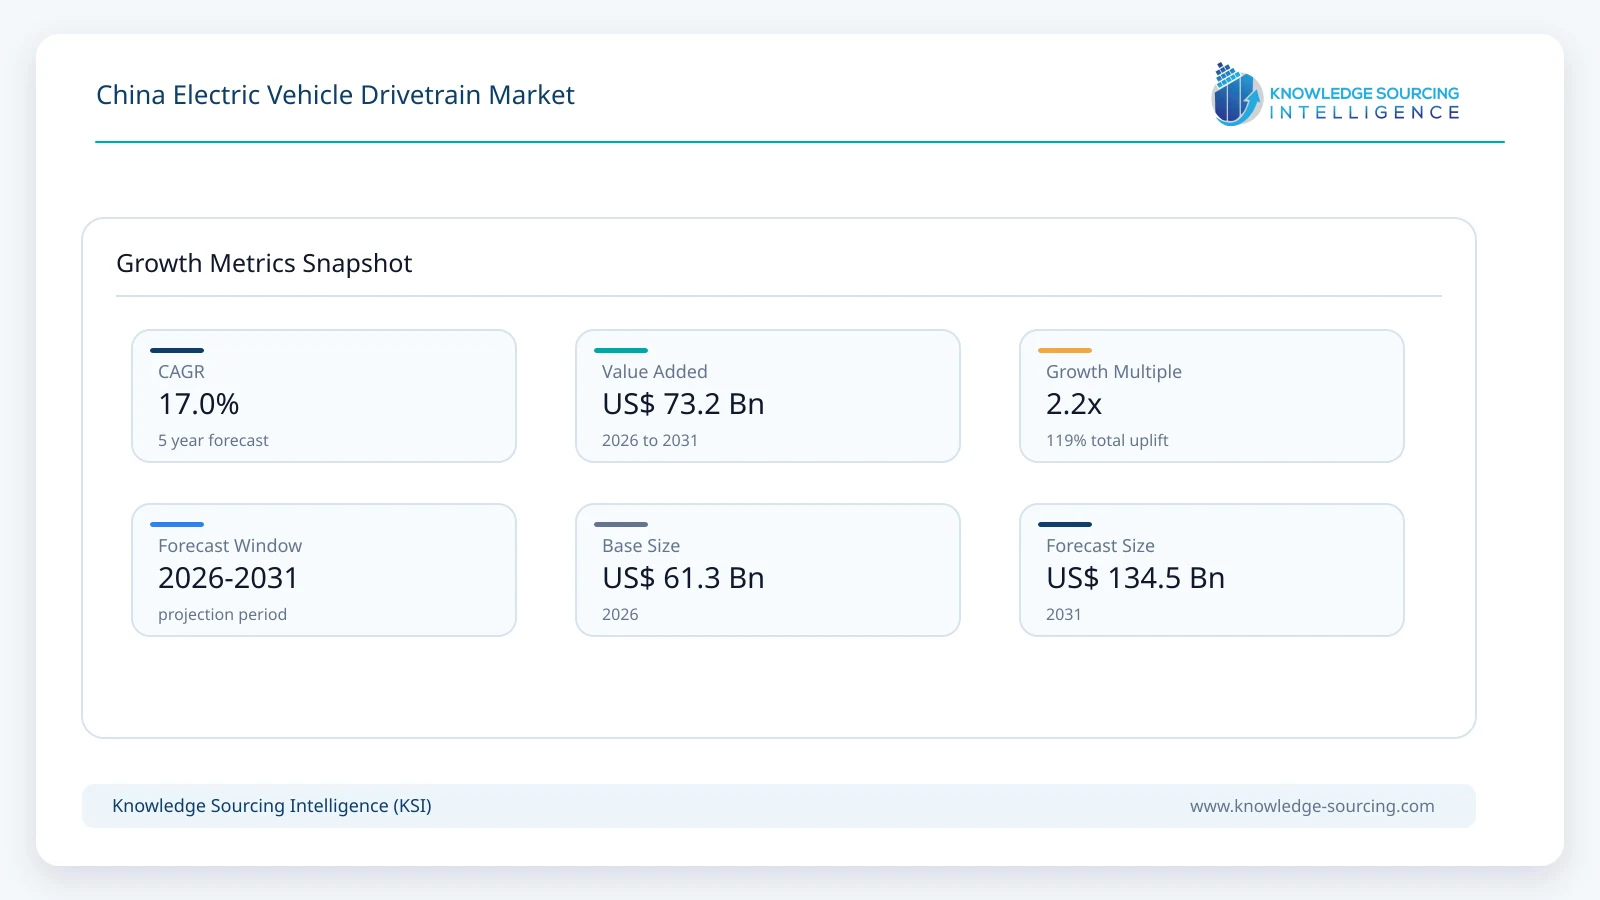
The China Electric Vehicle Drivetrain Market is forecast to grow at a CAGR of 17.0%, reaching USD 134.5 billion in 2031 from USD 61.3 billion in 2026.
Highlights:
- 1Vehicle electrification is the primary demand catalyst, with new-energy vehicles representing 47.9% of China's new-vehicle sales in 2025.
- 2Integrated electric-drive architectures are gaining commercial importance as automakers seek fewer interfaces, lower mass, simplified assembly, and improved drivetrain efficiency.
- 3BEVs represent the principal technology base, while PHEVs and REEVs create additional demand for compact, efficient electric propulsion systems.
- 4East and coastal China remain important production centers, supported by dense automotive supply chains, engineering capabilities, semiconductor activity, and vehicle manufacturing clusters.
- 5Power electronics and functional safety are becoming stronger purchasing criteria, alongside motor efficiency and mechanical durability.
- 6Government vehicle replacement incentives and charging infrastructure expansion are supporting vehicle electrification, indirectly increasing demand for electric drivetrain systems.
The China Electric Vehicle Drivetrain Market covers the electric propulsion systems that convert stored electrical energy into vehicle motion. The scope includes electric motors, motor controllers and inverters, transmission or reduction gears, e-axles, integrated e-drive systems, power semiconductors, and related drivetrain components. It covers front-wheel-drive, rear-wheel-drive, and all-wheel-drive configurations across battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), range-extended electric vehicles (REEVs), and fuel cell electric vehicles (FCEVs).
The market is commercially important because the drivetrain sits at the intersection of vehicle efficiency, driving performance, cost, thermal management, packaging, reliability, and software-controlled propulsion. Chinese automakers have moved from purchasing individual propulsion components toward integrated systems that combine the motor, inverter, reduction gear, thermal interfaces, controls, and increasingly power electronics within compact architectures. This shift changes supplier economics because purchasing decisions now depend on system efficiency and integration capability rather than motor output alone.
China provides an unusually large demand base for drivetrain suppliers. According to the Ministry of Industry and Information Technology, China produced 16.626 million new energy vehicles and sold 16.49 million in 2025. New energy vehicles accounted for 47.9% of total new-vehicle sales. This installed production base creates substantial recurring demand for traction motors, inverters, reduction systems, semiconductor modules, and integrated drive assemblies.
The demand environment is also becoming more technology-sensitive. Vehicle manufacturers are attempting to reduce drivetrain mass, improve energy conversion efficiency, increase peak power density, and simplify vehicle assembly. Suppliers therefore compete on several parameters simultaneously: electrical efficiency, torque density, thermal performance, NVH characteristics, functional safety, cost per vehicle, manufacturing yield, software compatibility, and ability to support different vehicle platforms.
Buyer behavior differs by vehicle program. Large automakers with high annual volumes generally seek platform-level supply agreements and increasingly evaluate complete electric-drive systems. Emerging EV manufacturers can place greater emphasis on development speed, modularity, engineering support, and rapid validation. Commercial vehicle manufacturers place stronger weight on continuous-load performance, durability, thermal stability, serviceability, and total operating cost.
The procurement model also reflects China's substantial domestic automotive manufacturing capacity. Chinese vehicle manufacturers can source motors, inverters, gears, semiconductors, and complete e-drive systems from domestic suppliers while retaining the option of vertically integrating selected components. This creates a market in which suppliers must demonstrate manufacturing scale while maintaining engineering differentiation.
Government policy continues to support the underlying vehicle demand environment. China's 2026 vehicle trade-in program provides a subsidy for qualifying consumers who scrap an eligible vehicle and purchase a new-energy passenger vehicle, while qualifying vehicle replacements receive an 8% subsidy capped at RMB 15,000. Separately, new-energy passenger vehicles purchased during 2026–2027 receive a 50% vehicle-purchase-tax reduction, subject to a maximum tax reduction of RMB 15,000 per vehicle.
These measures affect drivetrain demand indirectly but materially. When subsidies and tax treatment improve the economics of replacing an older vehicle with an electrified model, vehicle manufacturers receive greater incentive to secure drivetrain capacity and introduce new propulsion platforms. The commercial effect is strongest for high-volume passenger-vehicle programs, where even a small change in drivetrain cost or efficiency can materially affect vehicle-level margins.
China's charging infrastructure also supports drivetrain utilization. The National Energy Administration reported 20.092 million electric-vehicle charging facilities at the end of December 2025, including 4.717 million public facilities and 15.375 million private facilities. Public charging infrastructure averaged 46.5 kW per charging gun, while more than 98% of highway service areas had charging facilities. A denser charging network increases the practical usability of BEVs and supports higher utilization of electric propulsion systems.
The market therefore extends beyond component replacement demand. It represents a broader industrial shift toward integrated electrical propulsion, with purchasing decisions increasingly tied to vehicle architecture, semiconductor selection, thermal systems, software controls, and manufacturing integration.
Market Drivers
High New-Energy Vehicle Production Is Expanding the Addressable Drivetrain Base
The most direct market driver is the scale of China's new-energy vehicle production. China produced 16.626 million NEVs in 2025, with sales reaching 16.49 million units. Every vehicle using electric propulsion requires a drivetrain architecture capable of converting battery or fuel-cell energy into controlled wheel torque.
This creates demand across the entire component chain. A conventional BEV typically requires traction motors, inverters, reduction gearing, thermal management interfaces, sensors, controllers, and semiconductor devices. Dual-motor AWD vehicles increase the number and sophistication of electric-drive components. PHEVs and REEVs create another demand channel because their electric propulsion systems must operate alongside an internal combustion engine and related power-management systems.
Vehicle manufacturers therefore have a strong commercial incentive to standardize drivetrain modules across several models. A common motor or inverter family can reduce engineering expenditure, simplify procurement, and increase manufacturing utilization.
For suppliers, the implication is important: winning a platform contract can create demand across multiple vehicle models rather than a single product line. Suppliers with flexible manufacturing and modular architectures can therefore compete for larger vehicle-program volumes.
Pressure to Improve Vehicle Efficiency Is Raising the Value of Drivetrain Engineering
As electric vehicles become more price-sensitive, automakers cannot rely exclusively on larger batteries to improve driving range. Increasing drivetrain efficiency offers another route to reducing energy consumption without adding battery mass.
Motor efficiency, inverter switching performance, mechanical losses, thermal management, and reduction-gear efficiency all influence vehicle energy consumption. Improving one element can also reduce the required capacity of another system. For example, a more efficient drivetrain can reduce battery energy requirements for a given driving range, while better thermal control can preserve motor and inverter performance under sustained loads.
This relationship makes drivetrain procurement increasingly connected to vehicle-level economics. Buyers evaluate not only the purchase price of a drivetrain but also its contribution to range, acceleration, thermal stability, and battery utilization.
Chinese suppliers are consequently developing increasingly integrated propulsion systems. The national standard framework itself recognizes the importance of complete drive motor systems, with GB/T standards covering electric-vehicle drive motor systems and functional-safety requirements.
Vehicle Trade-In Policies Are Supporting New-Energy Vehicle Replacement Demand
Government-supported vehicle replacement provides another demand mechanism. China's 2026 policy allows qualifying consumers to receive subsidies when replacing eligible older vehicles with qualifying new-energy passenger vehicles. The scrappage incentive is 12% of the new vehicle's sales price, capped at RMB 20,000, while replacement through sale receives an 8% subsidy capped at RMB 15,000 for qualifying NEVs.
The drivetrain effect comes from the composition of replacement purchases. When a consumer changes from an internal combustion vehicle to a BEV, PHEV, or REEV, the vehicle's propulsion architecture changes completely. The replacement cycle therefore generates incremental drivetrain demand rather than merely substituting one conventional powertrain with another.
For automakers, policy-supported demand can also improve production planning. Higher volumes support longer production runs for motors, inverters, gears, and integrated e-drive systems, allowing suppliers to amortize tooling and engineering expenditure over larger volumes.
Charging Infrastructure Is Reducing Practical Barriers to Electric Propulsion
The growth of charging infrastructure strengthens the operating proposition for electric vehicles. China had more than 20 million charging facilities by the end of 2025, with private charging accounting for the majority of installations.
This matters for drivetrain suppliers because propulsion-system economics depend on vehicle utilization. A drivetrain that remains underutilized because of inadequate charging access has weaker commercial value to vehicle buyers. Conversely, widespread charging increases vehicle usability and supports continued electrification across passenger and commercial applications.
High-power charging also places additional requirements on the vehicle's electrical architecture. Greater charging power increases the importance of thermal management, electrical protection, power conversion efficiency, and coordination between battery and drivetrain controls.
The National Energy Administration reported that China's public charging infrastructure averaged 46.5 kW per charging gun in 2025, while highway service-area coverage exceeded 98%. This infrastructure development supports longer-distance EV operation and strengthens demand for drivetrains capable of maintaining stable performance during repeated high-load operation.
Higher System Integration Is Improving Vehicle Packaging and Manufacturing Economics
Automakers increasingly evaluate electric propulsion as a system rather than a collection of unrelated components. Integrated e-drive systems can combine the motor, inverter, reduction gear, and associated electronics into a smaller package.
Integration can reduce wiring, connectors, housing requirements, assembly steps, and vehicle packaging constraints. It can also allow manufacturers to optimize the complete propulsion system around a defined vehicle platform.
The commercial consequence is a change in supplier competition. A motor supplier competing only on electromagnetic performance may face pressure from a supplier that can provide a complete drive unit with validated controls, inverter electronics, mechanical reduction, and thermal interfaces.
This does not eliminate component-level opportunities. Power semiconductor suppliers, motor specialists, gear manufacturers, and controller developers remain important because system integrators still depend on component-level performance. However, procurement increasingly rewards suppliers capable of demonstrating system-level results.\
Market Restraints and Challenges
Price Competition Can Compress Drivetrain Supplier Margins
China's large EV production base creates substantial economies of scale but also strong pressure on component pricing. Automakers can compare multiple domestic and international suppliers and may seek annual cost reductions after production begins.
The root challenge is that drivetrain technology requires substantial engineering expenditure while the vehicle market remains price-sensitive. Suppliers must fund motor development, inverter software, validation, tooling, production automation, and functional-safety compliance before realizing sufficient production volumes.
Smaller suppliers can therefore face a margin disadvantage even when their technology is competitive. Larger suppliers can spread engineering expenditure across several vehicle programs and maintain greater negotiating flexibility.
Mitigation requires modular product families, manufacturing automation, common component platforms, and tighter supplier coordination. Suppliers that cannot reduce unit manufacturing cost without compromising reliability may struggle to retain high-volume contracts.
Power Semiconductor Supply and Technology Constraints Remain Important
Inverters depend on semiconductor devices that control the flow of electrical energy between the battery and motor. Silicon-based devices remain widely used, while silicon carbide is increasingly relevant for high-efficiency, high-voltage applications.
The challenge extends beyond semiconductor availability. Suppliers must manage device cost, thermal characteristics, switching losses, electromagnetic compatibility, reliability, and packaging. High-performance semiconductor adoption can improve efficiency but can also increase drivetrain cost.
Automakers therefore balance efficiency gains against vehicle price targets. Suppliers need to demonstrate measurable vehicle-level benefits rather than simply offering higher semiconductor specifications.
Functional-Safety and Reliability Requirements Increase Validation Costs
Electric drivetrains operate at high electrical voltages and combine mechanical, electrical, thermal, and software-controlled functions. Failures can affect propulsion, braking coordination, thermal safety, or vehicle control.
China's standards framework imposes specific safety and testing requirements. GB 18384-2025, published on December 31, 2025, replaced the earlier GB 18384-2020 standard and entered implementation on July 1, 2026.
For suppliers, new or revised requirements can increase testing, documentation, certification, engineering, and production-control costs. These costs are particularly relevant for companies supplying multiple vehicle platforms, because configuration changes may require additional validation.
The practical mitigation strategy is earlier compliance engineering. Suppliers that integrate safety requirements into product architecture during development can reduce late-stage redesign risk.
Integration Creates Greater Supplier Responsibility
Integrated e-drive systems can improve vehicle economics but also concentrate technical responsibility. A supplier providing motor, inverter, gear reduction, and controls becomes accountable for interactions among these subsystems.
A motor may meet its standalone efficiency target while the complete system performs below expectations because of thermal constraints, inverter calibration, gear losses, or control strategy. This raises the engineering burden for system suppliers.
Automakers must therefore evaluate supplier development capabilities, testing facilities, software competence, and warranty support in addition to hardware specifications. Smaller suppliers may find it difficult to provide the full engineering infrastructure demanded by integrated programs.
Demand Differences Across Powertrain Architectures Complicate Capacity Planning
BEV, PHEV, REEV, and FCEV applications require different drivetrain configurations. BEVs generally emphasize pure electric efficiency and regenerative operation. PHEVs and REEVs must coordinate electric propulsion with an engine-driven energy source. FCEVs introduce fuel-cell-specific electrical and thermal requirements.
This diversity makes capacity planning more difficult. A supplier optimized around a single high-volume architecture may face utilization pressure if automakers shift product mix.
Flexible manufacturing lines and modular components can reduce this exposure. Suppliers that can adapt common motor, inverter, and reduction architectures to different vehicle platforms have greater opportunity to maintain production utilization.
Major Segment Analysis
Battery Electric Vehicle (BEV)
The Battery Electric Vehicle segment represents the most commercially important vehicle architecture for China's electric drivetrain market because it requires a complete electric propulsion system as the primary means of vehicle movement.
The commercial distinction is important. In a BEV, drivetrain efficiency directly influences driving range, battery consumption, thermal behavior, acceleration, and charging requirements. Consequently, the drivetrain becomes a major engineering lever for vehicle differentiation.
BEV demand also benefits from China's large-scale production ecosystem. The country sold 16.49 million NEVs in 2025, representing 47.9% of total new-vehicle sales. Even without assuming that all NEVs use identical drivetrain architectures, this volume demonstrates the scale of the underlying electric-propulsion procurement environment.
Buyer requirements within BEVs are becoming more demanding. Entry-level vehicles prioritize low system cost, adequate efficiency, compact packaging, and reliability. Premium vehicles place greater emphasis on power density, acceleration, AWD capability, low NVH, high-voltage operation, and sustained performance.
The rise of integrated e-drive systems is especially relevant to BEVs. Combining motor, inverter, and reduction gear can reduce package size and simplify assembly. It also gives the supplier greater control over calibration and system optimization.
AWD BEVs create additional commercial opportunities for dual-motor architectures. These vehicles can independently control front and rear propulsion, enabling torque distribution for acceleration, traction, and efficiency. However, the additional motor and inverter increase cost, weight, thermal requirements, and control complexity.
For suppliers, BEV procurement is therefore shifting from a component-price discussion toward total system value. Suppliers that can reduce mass, improve efficiency, support multiple voltage architectures, and demonstrate reliable production quality can command stronger strategic relevance.
Competitive Landscape
The competitive structure includes vertically integrated Chinese automotive groups, specialized electric-drive suppliers, power-electronics companies, international automotive technology suppliers, and companies developing integrated propulsion architectures.
The provided competitive set comprises FinDreams Powertrain, Huawei Digital Power, Shanghai Electric Drive Co., Ltd., INOVANCE Automotive, InfiMotion, NIO Power Technology, Nidec Corporation, Dana Incorporated, Magna International Inc., and ZF Friedrichshafen AG.
Competition occurs across several layers. Domestic suppliers generally benefit from proximity to Chinese automakers, localized engineering teams, shorter development cycles, and established domestic sourcing networks. International suppliers can differentiate through global engineering platforms, specialized manufacturing capabilities, quality systems, and relationships with multinational vehicle manufacturers.
Integrated suppliers have an advantage when automakers seek to reduce the number of interfaces between motor, inverter, reduction gear, controls, and thermal systems. Component specialists remain relevant where automakers retain greater control over system architecture or seek second-source arrangements.
Technology differentiation increasingly centers on power density, high-voltage operation, semiconductor architecture, thermal management, software calibration, and functional safety. Huawei Digital Power, for example, reported that its DriveONE systems had shipped more than 3.5 million units by September 2025, supporting more than two million vehicles.
INOVANCE Automotive and Shanghai Electric Drive operate within China's established industrial automation and electric-drive ecosystem, while FinDreams Powertrain benefits from integration with a major domestic EV manufacturing group. InfiMotion represents the specialized electric-drive supplier model. NIO Power Technology introduces a different approach by connecting vehicle propulsion technology with a broader charging and battery-swapping ecosystem.
International companies such as Nidec, Dana, Magna, and ZF compete through engineering expertise, global customer relationships, and technology portfolios spanning electric motors, transmissions, e-drive systems, and vehicle systems.
Partnerships are also becoming more important. NIO's March 2025 strategic agreement with CATL included battery-swapping network development, technical-standard cooperation, and an investment framework involving NIO Power. Although battery swapping is not itself a drivetrain component, the development demonstrates how electric propulsion suppliers can compete through broader vehicle-energy ecosystems.
The competitive model is consequently shifting toward platform participation. Suppliers seek to secure long-term vehicle programs, expand component content per vehicle, and demonstrate system-level reliability. Automakers, meanwhile, have incentives to maintain multiple qualified suppliers for cost discipline, supply continuity, and technology benchmarking.
Recent Developments
May 2026: Li Auto officially launched the all-new Li L9 in China, expanding its electric-drive EREV lineup with deliveries beginning May 17 and reinforcing electric-motor-based propulsion.
February 2026: NIO announced completion of its 100 millionth battery swap. The company reported that its swap network had delivered 5.28 billion kWh through these transactions and performed battery and electric-drive health assessments during swaps. Commercial relevance: the milestone demonstrates the scale at which integrated vehicle propulsion, battery management, and energy-service infrastructure can operate as a connected commercial system.
December 2025: China's authorities issued the 2026 automobile trade-in subsidy rules, providing a 12% subsidy capped at RMB 20,000 for qualifying scrappage purchases of new-energy passenger vehicles and an 8% subsidy capped at RMB 15,000 for qualifying replacement purchases. Commercial relevance: continued replacement incentives support new-energy vehicle volumes and therefore sustain downstream demand for electric motors, inverters, reduction gears, and integrated e-drive systems.
December 2025: China published GB 18384-2025, Electric Vehicles Safety Requirements, replacing GB 18384-2020 and taking effect on July 1, 2026. Commercial relevance: drivetrain suppliers must align product validation, electrical safety, testing, documentation, and production controls with the updated safety framework.
Regulatory and Policy Environment
China's electric drivetrain industry operates within a broad regulatory framework covering vehicle safety, energy consumption, vehicle qualification, taxation, manufacturing, electrical systems, and charging infrastructure.
A central requirement is compliance with national vehicle safety standards. GB 18384-2025 became effective on July 1, 2026, replacing GB 18384-2020. The standard covers electric-vehicle safety requirements and is administered under the Ministry of Industry and Information Technology through China's automotive standardization system.
Drive motor systems also fall under dedicated national standards. China's standard system includes requirements covering electric-vehicle drive motor systems, with organizations including China Automotive Technology and Research Center, BYD, Huawei Digital Power, Shanghai Electric Drive, NIO, and other industry participants represented among relevant drafting organizations.
Functional safety is another important consideration. The national standard framework includes requirements and testing methods for the functional safety of electric-vehicle drive motor systems. This increases the importance of fault detection, redundant control strategies where applicable, validation procedures, and documented safety processes.
Tax policy also affects drivetrain demand indirectly. China's policy provides a 50% reduction in vehicle purchase tax for qualifying new-energy vehicles purchased during 2026 and 2027, subject to a maximum reduction of RMB 15,000 per passenger vehicle.
Vehicle replacement incentives provide another demand-support mechanism. The 2026 program links subsidy eligibility to qualifying vehicle categories and official documentation, including vehicle invoices and registration records. Suppliers should therefore expect vehicle manufacturers to monitor policy-driven demand changes when planning component procurement and capacity.
Charging infrastructure is also subject to government planning. China's three-year charging-infrastructure action plan for 2025–2027 targets continued expansion of charging capacity, while the National Energy Administration has emphasized appropriate advance deployment, scientific planning, intelligent operation, and higher charging efficiency.
For drivetrain suppliers, the regulatory environment has two commercial effects. First, compliance increases product-development expenditure and validation requirements. Second, common standards can reduce uncertainty for suppliers developing scalable platforms for multiple vehicle manufacturers.
Outlook and Strategic Implications
The 2026–2031 outlook for China's electric vehicle drivetrain market will be determined primarily by the scale of NEV production, drivetrain integration, vehicle price competition, semiconductor technology, vehicle architecture changes, and regulatory requirements.
The most important strategic shift will be from component supply toward system participation. Automakers will continue to evaluate individual motors, inverters, gears, and semiconductors, but integrated e-drive systems can offer advantages in packaging, assembly, calibration, and system responsibility. Suppliers that can combine these capabilities without materially increasing vehicle cost will have a stronger position in platform sourcing.
Investment priorities are likely to center on high-efficiency motors, high-voltage inverter systems, advanced semiconductor packaging, thermal management, functional-safety engineering, and automated manufacturing. Investment will increasingly be evaluated against production scale rather than laboratory performance alone.
Procurement strategies are also likely to become more modular. Automakers need the ability to use common drivetrain architectures across sedans, SUVs, commercial vehicles, and different performance grades. Suppliers that offer configurable systems can reduce engineering duplication for customers.
BEV propulsion will remain central, but PHEV and REEV platforms will remain relevant where buyers value electric driving with reduced dependence on charging availability. This creates demand for propulsion systems that can deliver efficient electric operation while fitting more constrained vehicle packaging requirements.
AWD systems will provide a higher-value opportunity because dual-motor architectures increase drivetrain content per vehicle. However, their commercial success depends on whether the additional performance and traction benefits justify higher cost, weight, and thermal complexity.
Power semiconductor selection will become more strategic. Silicon carbide can provide efficiency and high-voltage advantages, particularly in applications where energy losses materially affect range and charging performance. Yet cost remains a major purchasing constraint. Suppliers will therefore need to demonstrate vehicle-level economics rather than simply promote semiconductor specifications.
Charging infrastructure will continue influencing drivetrain design. China's charging network reached more than 20 million facilities by the end of 2025, and national policy is targeting further expansion through 2027. Higher charging availability supports larger EV fleets, while faster charging increases requirements for thermal and electrical system coordination.
The competitive environment will likely become more polarized. Large integrated suppliers can compete on scale, cost, validation capability, and platform coverage. Specialized suppliers can defend their position through superior motor design, inverter control, semiconductor expertise, software, or mechanical engineering. International suppliers will remain relevant where automakers require global technology platforms and diversified sourcing.
The principal risks include price erosion, overcapacity in selected drivetrain components, semiconductor cost volatility, rapid changes in vehicle electrical architecture, customer vertical integration, and regulatory revisions. Suppliers with high fixed-cost manufacturing structures face particular exposure if vehicle-program volumes change unexpectedly.
Strategically, suppliers should prioritize platform-level design wins, flexible manufacturing, common product architectures, functional-safety competence, and localized engineering support. The ability to reduce total vehicle cost while improving efficiency will be more commercially valuable than isolated performance improvements.
China's scale gives drivetrain manufacturers an opportunity to spread development expenditure over very large production volumes. However, scale alone will not guarantee supplier profitability. Procurement organizations increasingly have the ability to compare domestic and international technologies, negotiate annual cost reductions, and shift component sourcing when performance or pricing fails to meet vehicle-program targets.
The strongest long-term positions are therefore likely to belong to suppliers that combine manufacturing scale, engineering depth, system integration, quality consistency, and cost discipline. As electric propulsion becomes a larger share of China's vehicle production, drivetrain purchasing will increasingly influence vehicle economics rather than remain a conventional component procurement decision.
For 2026–2031, the central commercial question is not whether electric drivetrains will remain relevant in China. The more important question is which drivetrain architectures and supplier models can deliver the required efficiency, cost, reliability, and integration level at China's exceptionally large vehicle-production scale. That distinction will shape investment allocation, supplier selection, technology partnerships, and competitive positioning throughout the forecast period.
China Electric Vehicle Drivetrain Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 61.3 billion |
| Total Market Size in 2031 | USD 134.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 17.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Drive Type, Vehicle Type |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
By Drive Type
By Vehicle Type
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. CHINA ELECTRIC VEHICLE DRIVETRAIN MARKET BY COMPONENT
5.1. Introduction
5.2. Electric Motor
5.3. Motor Controller/Inverter
5.4. Transmission/Reduction Gear
5.5. E-Axle
5.6. Integrated E-Drive System
5.7. Power Semiconductor
5.8. Others
6. CHINA ELECTRIC VEHICLE DRIVETRAIN MARKET BY DRIVE TYPE
6.1. Introduction
6.2. Front-Wheel Drive (FWD)
6.3. Rear-Wheel Drive (RWD)
6.4. All-Wheel Drive (AWD)
7. CHINA ELECTRIC VEHICLE DRIVETRAIN MARKET BY VEHICLE TYPE
7.1. Introduction
7.2. Battery Electric Vehicle (BEV)
7.3. Plug-in Hybrid Electric Vehicle (PHEV)
7.4. Range-Extended Electric Vehicle (REEV)
7.5. Fuel Cell Electric Vehicle (FCEV)
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. FinDreams Powertrain
9.2. Huawei Digital Power
9.3. Shanghai Electric Drive Co., Ltd.
9.4. INOVANCE Automotive
9.5. InfiMotion
9.6. NIO Power Technology
9.7. Nidec Corporation
9.8. Dana Incorporated
9.9. Magna International Inc.
9.10. ZF Friedrichshafen AG
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the forecasted market size and growth rate for the China Electric Vehicle Drivetrain Market from 2026 to 2031?
The China Electric Vehicle Drivetrain Market is projected to grow at a robust CAGR of 17.0% between 2026 and 2031. This growth will see the market expand from an estimated USD 61.3 billion in 2026 to USD 134.5 billion by 2031.
What major technological shifts are driving innovation within the Chinese Electric Vehicle Drivetrain Market?
The China Electric Vehicle Drivetrain Market is rapidly migrating from multi-component systems to integrated "Three-in-One" or "e-Axle" designs, combining the electric motor, power electronics, and gearbox into a single unit. This is complemented by a widespread shift to 800V high-voltage architectures, necessitating SiC-based power electronics for faster charging and extended range.
How do national policies and government mandates influence demand in the China Electric Vehicle Drivetrain Market?
Government mandates, particularly the central government's New Energy Vehicle (NEV) credit system, constitute a foundational growth driver. These policies directly compel automakers to increase NEV production volumes, thereby creating scaled and non-discretionary demand for electric drivetrain assemblies.
Who are the key players shaping the competitive landscape of the China Electric Vehicle Drivetrain Market?
The competitive landscape is being reshaped with traditional Tier 1 suppliers competing against vertically integrated domestic OEMs and specialized Chinese electric drive manufacturers. This dynamic environment is leading to intense pricing pressure and accelerated product iteration across the market.
What strategic component localization efforts are critical for Chinese EV drivetrain manufacturers?
A strategic imperative for Chinese original equipment manufacturers (OEMs) is the domestic sourcing and development of high-voltage power electronics, particularly Silicon Carbide (SiC) inverters. This effort aims to enhance vehicle performance and secure the supply chain for critical drivetrain components.
Why is China considered the global epicenter for Electric Vehicle Drivetrain design, manufacturing, and deployment?
China's leading position is defined by a unique combination of proactive industrial policy, a vast domestic consumer base, and the world's most aggressive pace of technological integration. As the largest global market for New Energy Vehicles (NEVs), it fosters robust demand and rapid advancement in electric propulsion systems.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). China Electric Vehicle Drivetrain Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/china-electric-vehicle-drivetrain-market